
 Warehouse Automation Systems Market | 2026-2036
Warehouse Automation Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Warehouse Automation Systems Market Analytics
Market Context
Buyer concentration among third-party logistics providers is repositioning procurement leverage toward integrated platform vendors. Dematic leverages its end-to-end software-hardware stack to anchor multi-site contracts with consolidated e-commerce fulfillment networks. Daifuku competes through deep specialization in cleanroom and cold-chain automation for pharmaceutical distributors. Swisslog sustains technology leadership in cube-based robotic storage through its AutoStore partnership, while KNAPP differentiates via proprietary warehouse management software that controls heterogeneous robot fleets.
Technical Definition and Segment Structure
Warehouse automation systems encompass electromechanical equipment, control software, and sensor networks that execute material movement, storage retrieval, and order consolidation without continuous human intervention, typically operating at throughput rates exceeding 10,000 picks per hour in high-density configurations. Automated Guided Vehicles and sortation systems currently dominate capital expenditure allocations due to their proven return profiles in parcel and grocery fulfillment. AI Robotics within the technology dimension is expanding fastest as machine vision and reinforcement learning reduce pick-cycle variability for irregular-shaped inventory. RFID Systems and IoT Sensors capture disproportionate margin pools through recurring software subscriptions and predictive maintenance contracts rather than one-time hardware sales.
Regulatory Framework
OSHA in the United States and the EU machinery directives under CE marking enforce mandatory safety-rated monitored stops and collaborative robot speed limits for mixed human-automation zones. The EU AI Act introduces risk-classification requirements for autonomous decision-making systems in logistics, while ISO 3691-4 establishes international validation protocols for mobile robot navigation reliability. Stakeholders must monitor evolving liability frameworks for fully unmanned operations and pre-certify systems against anticipated amendments to occupational exposure limits for collaborative workspaces.
Market Dynamics
E-commerce fulfillment networks are compressing order cycle times below four hours, forcing warehouse operators to replace batch-based material handling with continuous-flow automation architectures that synchronize robotic sortation, autonomous mobile robots, and AI-driven orchestration layers.
Growth Catalysts
- EU AI Act risk-classification mandates:Logistics operators in Germany and France are pre-certifying autonomous decision-making systems to secure early-mover advantage in unmanned fulfillment zones.
- Automotive third-party logistics:Tier-1 suppliers in Stuttgart and Wolfsburg are retrofitting legacy distribution hubs with machine vision-guided robotic storage to support just-in-sequence battery module delivery.
- Reinforcement learning for irregular inventory:Grocery and apparel fulfillment centers are deploying AI robotics that reduce pick-cycle variability for non-uniform SKUs without pre-programmed grasp patterns.
Market Restraints
- Steel and rare-earth magnet costs:Permanent magnet motors in mobile robots face input price volatility from concentrated Chinese refining capacity.
- ISO 3691-4 validation timelines:International navigation reliability protocols extend deployment cycles for autonomous mobile robot vendors by eight to fourteen months.
- Collaborative robot speed limits:OSHA safety-rated monitored stops cap human-robot workcell throughput below theoretical maximums in mixed-zone configurations.
Strategic Opportunities
- India PLI scheme for logistics infrastructure:Domestic e-commerce platforms are qualifying for production-linked incentives on automated storage and retrieval system deployments in Mumbai and Bangalore fulfillment corridors.
- RFID-to-IoT sensor convergence:Predictive maintenance subscriptions are displacing one-time hardware margins with recurring software revenue pools in pharmaceutical cold-chain automation.
- Pharmaceutical cleanroom retrofit:European distributors are automating temperature-controlled handling for cell and gene therapy products under EMA good distribution practice guidelines.
Industry Challenges
- Mechatronics technician scarcity:Germany's dual vocational system is failing to produce sufficient maintenance specialists for heterogeneous robot fleet management.
- Legacy WMS integration:Proprietary warehouse management software from incumbent vendors creates API friction when orchestrating third-party autonomous mobile robots.
- CE marking amendment cycles:Evolving EU machinery directives force recertification of installed collaborative robot workcells every eighteen to twenty-four months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Warehouse Automation Systems Market |
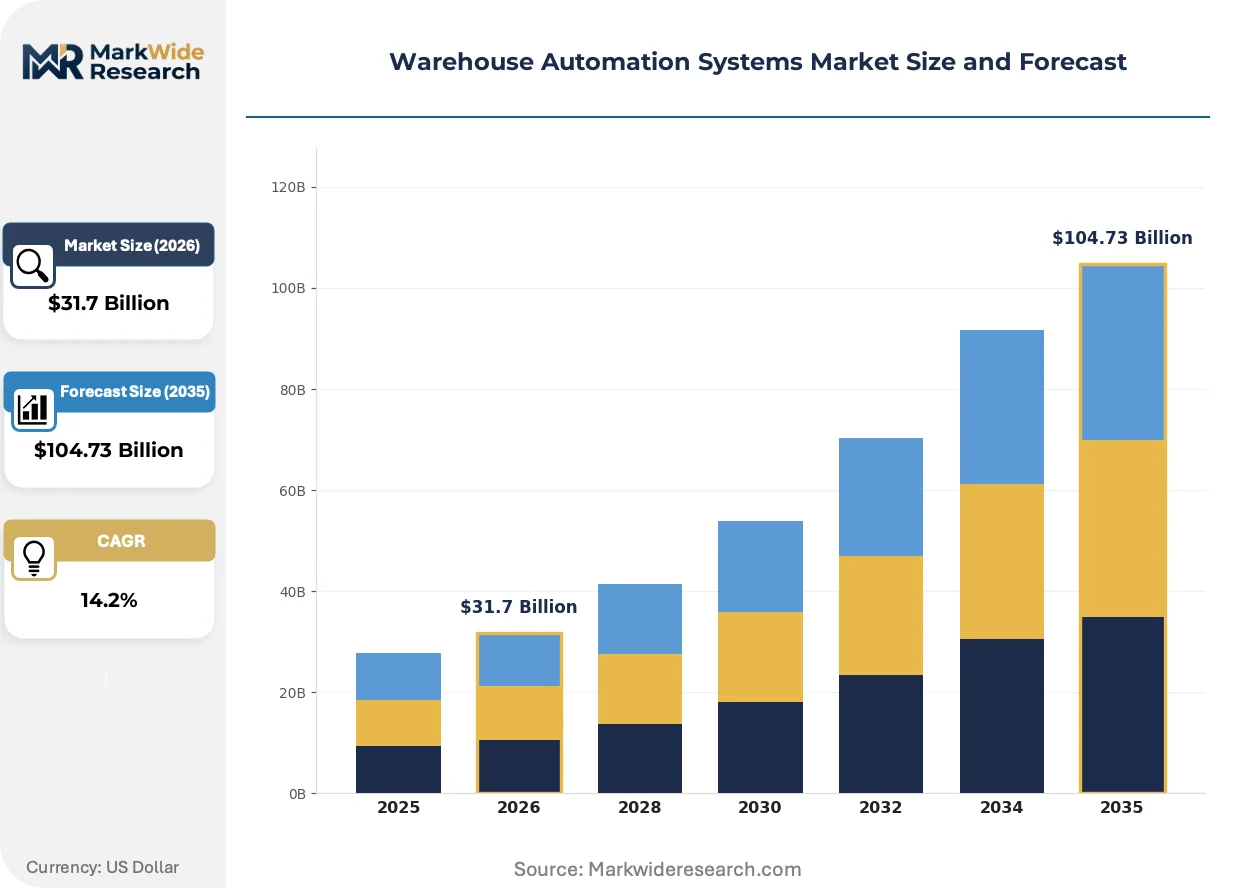
| Market Size in 2026 | $31.7 Billion |
| Market Size in 2035 | $104.73 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Guided Vehicles, Robotic Arms, Sortation Systems, Conveyor Systems Technology: Barcode Scanning, RFID Systems, AI Robotics, IoT Sensors End User: E-Commerce, Retail, Food & Beverage, Pharmaceuticals Application: Inventory Management, Order Fulfillment, Shipping & Receiving, Packaging |
| Companies Covered | Dematic, Daifuku, SSI Schaefer, Swisslog, Honeywell Intelligrated, KNAPP, AutoStore, Vanderlande, Bastian Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Warehouse Automation Systems Market Evolving Landscape
Machine vision and edge computing are collapsing the latency between perception and actuation in robotic systems, enabling real-time adaptation to unstructured warehouse environments without centralized cloud dependency.
Reinforcement learning-based grasp planning is electrifying fulfillment economics for non-conveyable inventory. Third-party logistics providers in the Netherlands and Belgium are deploying these systems across fashion and home goods verticals. The technology is compressing labor cost differentials between high-wage European markets and lower-cost manual alternatives.
The EU AI Act's risk-classification framework for autonomous logistics systems is forcing vendors to document decision audit trails and human oversight protocols. Pharmaceutical distributors operating under EMA guidelines face the strictest compliance burdens. German automation integrators are responding by embedding explainable AI modules into warehouse orchestration platforms.
Buyer concentration among consolidated e-commerce networks is shifting contract structures from capital purchase toward throughput-based service agreements. Third-party logistics providers now demand guaranteed picks-per-hour performance with penalty clauses. This model is most visible in the Benelux corridor, where DHL and Kuehne+Nagel are standardizing performance-contract templates across multi-site deployments.
Warehouse Automation Systems Market Segmentation
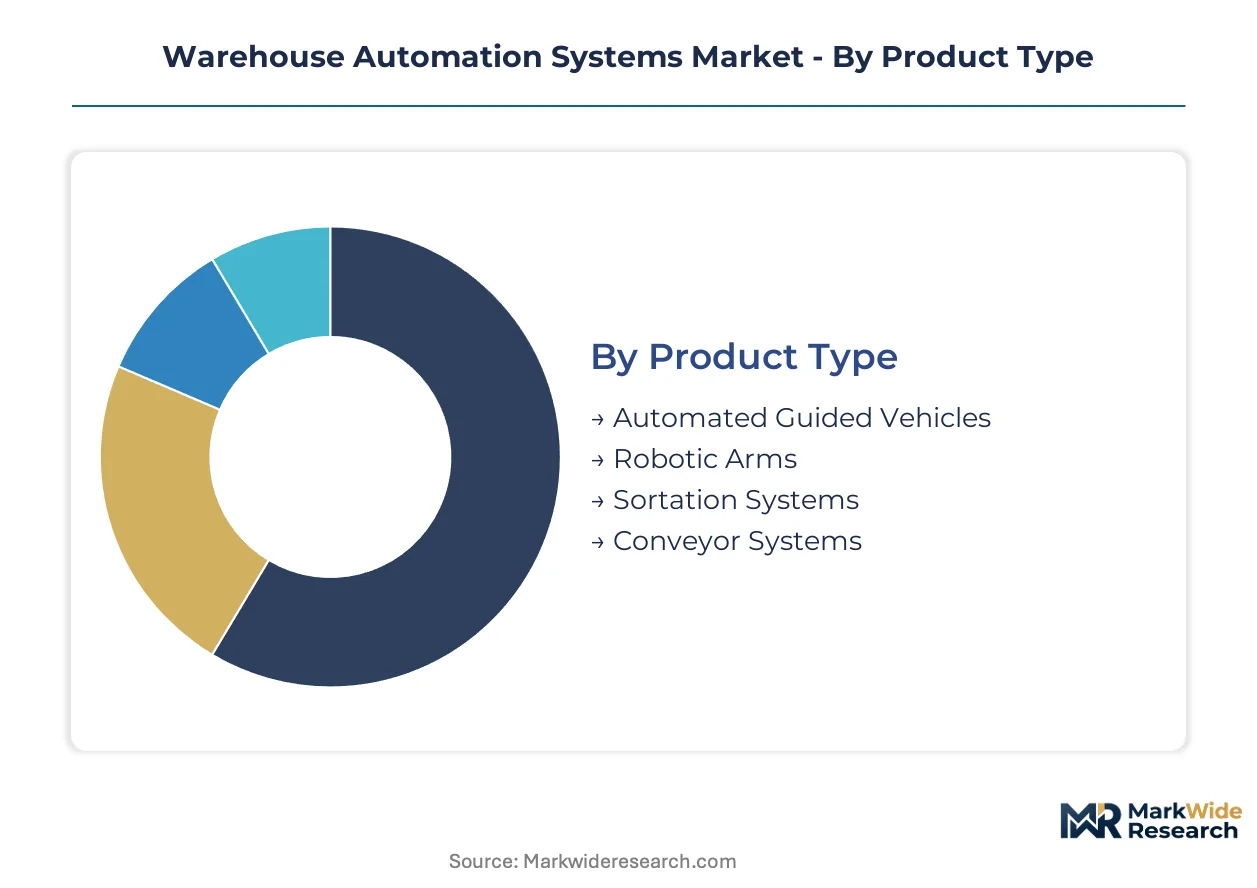
Warehouse automation procurement varies sharply by operational scale and inventory profile. Capital allocation patterns diverge between asset-heavy robotic infrastructure and sensor-overlay retrofits. Understanding these segment boundaries clarifies where integration complexity concentrates and where modular deployment accelerates payback cycles.
Product Type:
Capital intensity peaks with mobile robotics and high-throughput sortation, where electromechanical complexity and software orchestration layers compound upfront investment requirements.
- Automated Guided Vehicles:Magnetic tape, laser guidance, or vision-based navigation platforms execute pallet and tote transport across distribution hubs. German automotive third-party logistics providers in Stuttgart and Wolfsburg are retrofitting legacy distribution hubs with AGV fleets to support just-in-sequence battery module delivery under compressed cycle-time requirements.
- Sortation Systems:Tilt-tray, cross-belt, and sliding-shoe configurations process parcel streams exceeding 10,000 units per hour. E-commerce fulfillment centers in the Netherlands and Belgium are standardizing these systems across fashion and home goods verticals to compress labor cost differentials against manual alternatives.
- Robotic Arms:Articulated and delta configurations handle case picking, depalletizing, and mixed-SKU palletizing with machine vision guidance.
- Conveyor Systems:Belt, roller, and accumulation configurations form the backbone of continuous-flow architectures in grocery and parcel fulfillment.
Most installed capacity flows through Conveyor Systems. Expansion is steepest in Sortation Systems.
Technology:
Margin architecture separates hardware-centric deployments from recurring-revenue sensor networks that monetize predictive maintenance and software subscriptions.
- AI Robotics:Reinforcement learning and machine vision enable real-time grasp planning for irregular-shaped inventory without pre-programmed patterns. Grocery and apparel fulfillment centers are deploying these systems to reduce pick-cycle variability for non-uniform SKUs.
- RFID Systems:UHF and HF tag infrastructures enable item-level tracking without line-of-sight constraints. Pharmaceutical cold-chain automation in Europe is displacing one-time hardware margins with recurring software revenue pools through predictive maintenance subscriptions.
- IoT Sensors:Vibration, temperature, and proximity monitors feed edge-computing analytics for predictive maintenance and energy optimization.
- Barcode Scanning:Laser and imager-based systems remain the cost baseline for high-volume, low-complexity inventory tracking.
Barcode Scanning retains the largest installed base. AI Robotics is climbing the fastest as reinforcement learning compresses deployment timelines.
End User:
Operational velocity requirements and regulatory exposure create distinct procurement profiles across verticals.
- E-Commerce:Same-day and next-day fulfillment mandates drive continuous-flow automation with sub-four-hour order cycle targets. Buyer concentration among consolidated networks is shifting contract structures from capital purchase toward throughput-based service agreements with guaranteed picks-per-hour performance.
- Pharmaceuticals:Temperature-controlled handling and EMA good distribution practice guidelines enforce strict validation protocols. European distributors are automating cleanroom environments for cell and gene therapy products under risk-classification frameworks from the EU AI Act.
- Retail:Store replenishment and omnichannel fulfillment balance automation density with seasonal volume flexibility.
- Food & Beverage:Cold-chain integrity and batch traceability requirements favor sensor-overlay retrofits over full robotic replacement.
E-Commerce accounts for the dominant share of new capital deployment. Pharmaceuticals is gaining share fastest on regulatory tailwinds and biologics handling complexity.
Application:
Workflow integration depth varies from standalone point solutions to fully orchestrated end-to-end automation.
- Order Fulfillment:Pick, pack, and ship workflows represent the highest automation priority as e-commerce compresses delivery windows. Third-party logistics providers now demand penalty clauses for throughput shortfalls in multi-site contracts.
- Inventory Management:Cycle counting, put-away, and slotting optimization leverage AI-driven orchestration platforms to maximize storage density.
- Shipping & Receiving:Dock door automation and yard management systems synchronize inbound and outbound flows.
- Packaging:Void fill, cartonization, and label application integrate with upstream pick workflows for dimensional weight optimization.
Order Fulfillment captures the largest automation spend. Inventory Management is expanding most quickly as cube-based robotic storage penetrates high-density configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany outpaces France in warehouse automation capital deployment density, while the United States and China compete for absolute installed base leadership through divergent technology sourcing strategies.
Germany
Automotive third-party logistics providers in Stuttgart and Wolfsburg drive retrofit demand for AI-driven orchestration platforms supporting just-in-sequence battery module delivery. The EU AI Act risk-classification mandates require pre-certification of autonomous decision-making systems for unmanned fulfillment zones. Bavaria's distribution corridor concentrates multi-site contracts with consolidated e-commerce networks demanding throughput-based service agreements.
United States
E-commerce fulfillment networks compress order cycle times below four hours, forcing continuous-flow automation architectures across robotic sortation and autonomous mobile robot fleets. OSHA workplace safety standards enforce mandatory safety-rated monitored stops and collaborative robot speed limits for mixed human-automation zones. The Inland Empire logistics cluster in Southern California anchors capital deployment for same-day delivery infrastructure serving consolidated retail networks.
China
Domestic e-commerce platforms accelerate adoption of robotic sortation systems to manage parcel volumes exceeding 10,000 units per hour in high-density configurations. GB standards and MIIT regulations govern autonomous mobile robot navigation reliability in manufacturing-integrated distribution hubs. The Yangtze River Delta logistics corridor concentrates cleanroom automation deployments for pharmaceutical distributors under national good distribution practice guidelines.
Netherlands
Third-party logistics providers standardize performance-contract templates with guaranteed picks-per-hour clauses across multi-site deployments in fashion and home goods verticals. CE marking requirements under EU machinery directives enforce collaborative robot workcell recertification cycles every eighteen to twenty-four months. The Rotterdam-Antwerp corridor compresses labor cost differentials through reinforcement learning-based grasp planning for non-conveyable inventory.
India
Domestic e-commerce platforms qualify for production-linked incentives on automated storage and retrieval system deployments in Mumbai and Bangalore fulfillment corridors. The PLI scheme for logistics infrastructure subsidizes capital expenditure for cube-based robotic storage penetrating high-density configurations. Karnataka's technology manufacturing belt concentrates demand for sensor-overlay retrofits over full robotic replacement in food and beverage cold-chain applications.
Warehouse Automation Systems Market Competitive Landscape
German producers anchor one tier in integrated platform supply; Japanese specialists hold positions in cleanroom and high-throughput sortation configurations. The vendor base separates into consolidated multi-site contractors, component-focused technology licensors, and regional system integrators serving single-facility deployments. Three archetypes dominate: end-to-end stack vendors, robotic storage specialists, and software-centric orchestration providers. Competitive moves concentrate on strategic partnerships for AI module integration and geographic expansion through local integrator acquisition.
Among German-based fabricators, Dematic GmbH and SSI Schaefer occupy positions within the integrated platform tier, exemplifying multi-site contract anchoring through combined software-hardware stacks. KNAPP AG represents the software-centric archetype, with its proprietary warehouse management systems controlling heterogeneous robot fleets across European pharmaceutical and retail deployments. These three entities illustrate how geographic origin correlates with strategic positioning in high-regulation environments demanding CE marking compliance and EU AI Act risk-classification documentation.
| Leading Market Players |
|---|
| Dematic |
| Daifuku |
| SSI Schaefer |
| Swisslog |
| Honeywell Intelligrated |
| KNAPP |
| AutoStore |
| Vanderlande |
| Bastian Solutions |
| Others |
Value Network & Pricing Analysis
Consolidated e-commerce fulfillment networks in Germany and the Netherlands are shifting procurement toward throughput-based service agreements with penalty clauses, compressing vendor margins and favoring integrated platform providers over component specialists.
Pricing Analysis
Capacity additions in China are reshaping price floors for permanent magnet motors and mobile robot chassis, intensifying cost competition in mid-tier AGV segments. Three-tier pricing structure across premium CE-certified systems, standard ISO-compliant configurations, and economy-grade retrofit kits dominates contract structures. Price differentiation hinges on software orchestration depth and after-sales predictive maintenance bundling. Pricing pressure stems from steel and rare-earth magnet input volatility, with third-party logistics providers exhibiting highest price sensitivity due to thin fulfillment margins, while pharmaceutical distributors accept premium tiers for EMA-validated cleanroom automation.
Supply Chain Analysis
India's PLI scheme for logistics infrastructure is reshaping sourcing patterns, mandating domestic value-add for automated storage and retrieval system deployments. Component fabrication concentrates in China for rare-earth magnet refining, Germany for precision mechatronics, and Japan for cleanroom-grade servo motors. Permanent magnet motors, machine vision sensors, and edge-computing chipsets constitute critical input dependencies. Single-source vulnerability in Chinese rare-earth processing creates tariff-exposed chokepoints. Distribution runs through regional system integrators who bundle hardware installation with software commissioning and multi-year maintenance subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as buyer procurement shifts toward guaranteed picks-per-hour performance contracts that favor vendors with proven AI orchestration platforms over hardware-only suppliers.
For Market Incumbents: Acquire specialized machine vision software assets to close perception-to-actuation latency gaps in robotic grasp planning. Consolidate regional integrator networks in the Benelux corridor to defend multi-site contract anchoring against emerging AI-native entrants. CE marking recertification cycles every eighteen to twenty-four months favor incumbents with established compliance documentation over new market entrants facing extended ISO 3691-4 validation timelines. For New Entrants and Emerging Players: Reinforcement learning-based grasp planning for non-conveyable inventory offers a technology-first wedge into fashion and home goods verticals where labor cost differentials remain acute. Target India's PLI-subsidized fulfillment corridors in Mumbai and Bangalore where domestic-content rules disadvantage pure-import vendors. Lead with sensor-overlay retrofits for food and beverage cold-chain applications rather than full robotic replacement, reducing upfront capital friction and accelerating payback demonstration. For Investors and Strategic Acquirers: Third-party logistics providers with captive automation engineering capabilities are the most active acquirer in this space, seeking to internalize orchestration software rather than remain dependent on vendor platforms. Focus on mid-scale AI robotics specialists with validated pharmaceutical cleanroom deployments, as EMA guideline complexity creates durable competitive moats. Watch for inflection when EU AI Act enforcement triggers mandatory explainable AI module adoption, separating pre-certified vendors from compliance laggards.| Strategic Initiative | Industry Significance |
|---|---|
| AI Module Integration Partnership | Machine vision vendors embedding reinforcement learning reduce pick-cycle variability for irregular SKUs. |
| Regional Integrator Acquisition | Dematic and KNAPP consolidate Benelux service networks to anchor multi-site throughput contracts. |
| Pharmaceutical Cleanroom Certification | EMA good distribution practice compliance opens cell and gene therapy automation revenue pools. |
| Predictive Maintenance Subscription Pivot | RFID-to-IoT convergence displaces one-time hardware margins with recurring software revenue. |
| Domestic Content Manufacturing | India PLI scheme subsidies favor local assembly of cube-based robotic storage systems. |
Research Methodology
Bottom-up e-commerce fulfillment modeling reconciled against top-down mobile robot deployment tracking forms the analytical core of this study. Primary interviews with warehouse operations directors, mechatronics procurement leads at third-party logistics providers, automation integration engineers, and pharmaceutical distribution compliance officers were cross-validated against secondary sources including OSHA workplace safety filings, EU machinery directive amendment notices, SEC 10-K equipment vendor disclosures, and customs data for AGV and sortation system imports. Top-down trade flow analysis and bottom-up facility-level automation spend estimates were triangulated to reconcile volume and value figures.
Input-output matrices mapped technology adoption rates across product type, technology layer, end-user vertical, and application workflow dimensions over the projection horizon. Segmentation modeling incorporated deployment model, operational scale tier, inventory profile complexity, and regional regulatory cluster. CAGRs were derived from fitted adoption curves accounting for EU AI Act pre-certification timelines and ISO 3691-4 validation delays. Industry-specific forecast inputs included e-commerce order cycle compression targets and automotive just-in-sequence delivery requirements.
The model holds under stable rare-earth magnet supply and continued OSHA collaborative robot speed limit enforcement; deviation in Chinese export restrictions or CE marking amendment acceleration would shift deployment timelines. Forecasts reflect documented assumptions regarding reinforcement learning commercialization rates and PLI scheme subsidy continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Asia Pacific Industrial Communication Market
Industrial Automation
US Smart Manufacturing Market
Industrial Automation
Smart and Connected Elevators and Elevators Control Systems Market
Industrial Automation
UK Industrial Automation System Integrator Market
Industrial Automation
Smart Manufacturing Market
Industrial Automation
United States SCADA Market
Industrial Automation
Smart Elevator Automation System Market
Industrial Automation
Global PC Based Automation Market
Industrial Automation
United States Human Machine Interface Market
Industrial Automation
Europe SCADA Market
Industrial Automation
Operational Predictive Maintenance Market
Industrial Automation
Warehouse Automation Equipment Market
Industrial Automation
Machine Automation Controllers Market
Industrial Automation
Industrial Multiprotocol Gateways Market
Industrial Automation
Global Mining Automation Consumption Market
Industrial Automation
Europe ICS Market