
 Liquid Handling Technology Market | 2026-2036
Liquid Handling Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Handling Technology Market Analytics
ISO 8655 calibration standards for piston-operated pipettes is bifurcating the competitive landscape between certified precision suppliers and uncertified commodity vendors. Thermo Fisher Scientific leverages its global service network to anchor recurring calibration revenue streams. Danaher competes through integrated workflow automation spanning sample prep to analytics. Hamilton Company specializes in OEM liquid handling modules for embedded diagnostic instruments.
Liquid handling technology encompasses precision fluid transfer systems employing air displacement, positive displacement, acoustic, or microfluidic mechanisms to achieve volumetric accuracy from nanoliters to milliliters. These systems integrate programmable controllers, disposable tips, and sensor feedback to eliminate cross-contamination in life science workflows. Automated pipetting systems command the largest installed base due to throughput requirements in drug discovery, yet acoustic dispensing technology captures premium positioning in ultra-high-throughput screening where tip consumption costs dominate operational budgets. Microfluidics segments attract venture funding for point-of-care miniaturization, though clinical validation timelines constrain near-term revenue conversion.
FDA enforces current Good Manufacturing Practice quality system regulations for diagnostic liquid handlers used in clinical laboratories, while EPA oversees hazardous waste protocols for reagent disposal from high-throughput facilities. EU MDR and REACH compliance obligations extend to disposable tip biocompatibility and fluoropolymer trace element thresholds, respectively. Stakeholders must monitor evolving harmonization gaps between FDA predicate device pathways and EU notified body conformity assessments as dual-territory product registrations become standard practice.
Market Dynamics
Automated liquid handling systems face a structural inflection as FDA 21 CFR Part 11 compliance mandates and EU MDR traceability requirements force equipment qualification protocol overhauls, bifurcating vendor capabilities between certified precision suppliers and uncertified commodity producers.
Growth Catalysts
- High-throughput screening automation:Pharmaceutical companies deploy robotic pipetting workstations to compress compound screening cycles. Drug discovery pipelines in the United States, Germany, and China anchor this equipment demand.
- EU MDR traceability mandates:European diagnostic manufacturers must document liquid handler calibration chains and disposable tip biocompatibility. This regulatory pressure elevates certified service contracts over ad-hoc maintenance.
- Acoustic dispensing technology:Tipless liquid transfer eliminates consumable costs in ultra-high-throughput screening. Genomics and proteomics facilities adopt these systems for nanoliter-precision workflows.
Market Restraints
- Fluoropolymer supply concentration:Precision piston seals and chemically resistant components depend on concentrated PTFE and PFA resin suppliers. Price volatility in fluoropolymer feedstocks compresses margins for mid-tier instrument manufacturers.
- ISO 8655 calibration infrastructure gaps:Certified metrology laboratories remain scarce in emerging biopharma clusters. Equipment owners in India and Brazil face extended downtime waiting for qualified service technicians.
- Manual pipette substitution in low-throughput settings:Academic and clinical laboratories with modest sample volumes continue using handheld single-channel pipettes. This installed base resists capital conversion to automated workstations.
Strategic Opportunities
- Point-of-care microfluidics miniaturization:Venture funding flows toward cartridge-based diagnostic platforms requiring embedded liquid handling modules. Near-patient testing applications in decentralized healthcare settings represent unpenetrated volume.
- India's PLI scheme for medical devices:Production-linked incentives attract domestic manufacturing of diagnostic instruments. Local assembly of liquid handling components reduces import duties and service response times.
- Cloud-connected predictive maintenance:IoT sensor integration enables remote calibration monitoring and failure prediction. Service revenue models shift from reactive repairs to subscription-based uptime guarantees.
Industry Challenges
- Cross-platform software integration:Laboratory information management systems from multiple vendors communicate through incompatible protocols. Biopharma facilities struggle to orchestrate liquid handlers within unified workflow automation.
- EPA hazardous waste disposal compliance:High-throughput facilities generate substantial reagent and solvent waste. Stringent disposal documentation requirements extend operational overhead for contract research organizations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Handling Technology Market |
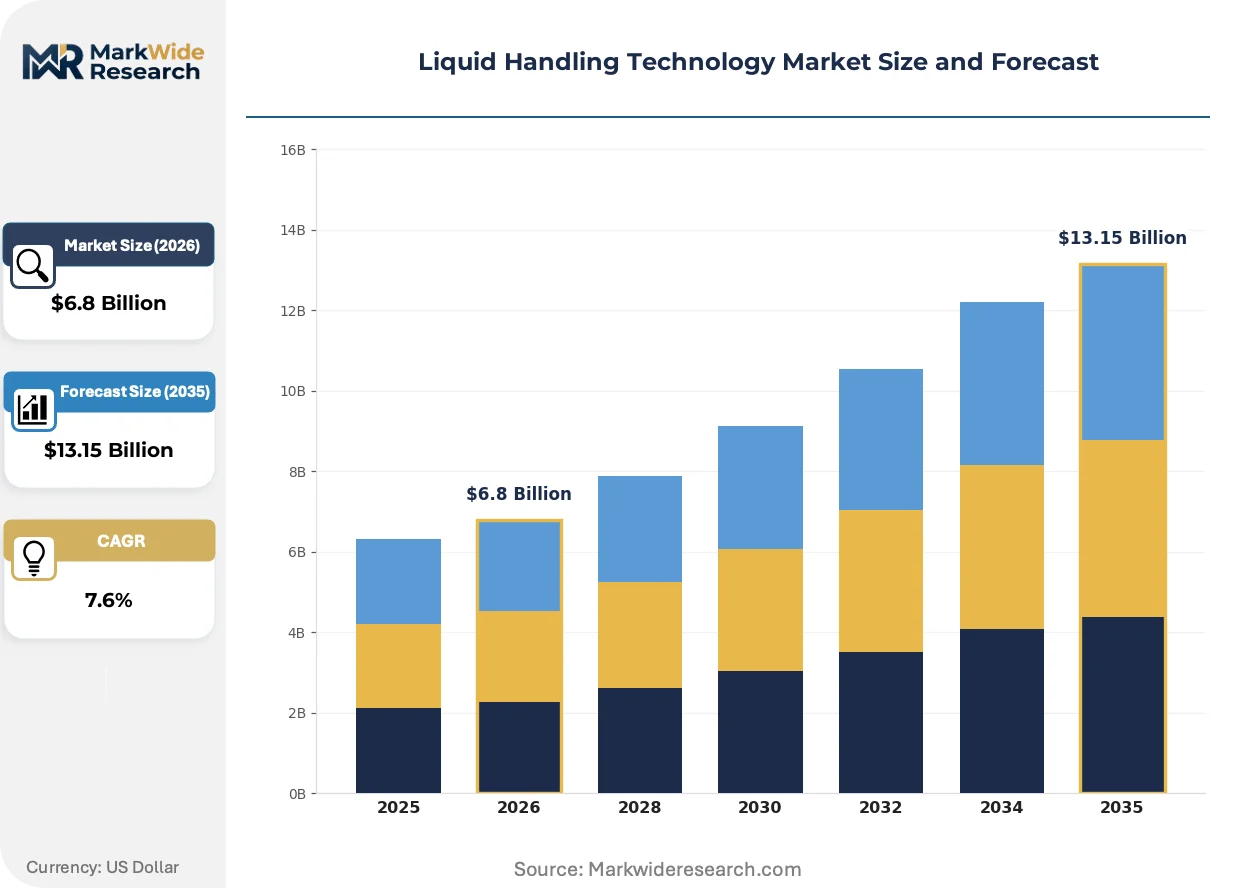
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Pipetting, Manual Pipettes, Multichannel Systems, Liquid Dispensers End User: Pharmaceutical Companies, Biotechnology Firms, Academic Institutes, Clinical Laboratories Technology: Microfluidics, Air Displacement, Positive Displacement, Acoustic Dispensing Application: Drug Discovery, Genomics, Proteomics, Cell Culture |
| Companies Covered | Thermo Fisher Scientific, Danaher, Agilent Technologies, Eppendorf, Tecan Trading AG, Hamilton Company, PerkinElmer, Sartorius AG, Mettler Toledo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Handling Technology Market Evolving Landscape
Digitalization of laboratory workflows is compressing equipment replacement cycles while elevating software and service components to parity with hardware in vendor revenue structures.
Acoustic droplet ejection technology is supplanting traditional tip-based dispensing in ultra-high-throughput screening applications. Genomics core facilities and contract research organizations adopt these systems to eliminate plastic tip consumption and cross-contamination risks. The technology is supplanting multi-channel pipetting workstations in compound library management, compressing per-sample processing costs below five cents.
EU MDR Annex XVI classification expansion now captures certain laboratory automation equipment previously exempt from conformity assessment. Diagnostic liquid handlers used in clinical settings must undergo notified body review for software validation and cybersecurity. German manufacturers accelerate ISO 13485 quality system adoption to maintain EU market access, while US-based exporters face divergent predicate device pathways at FDA.
Consolidated procurement through group purchasing organizations concentrates buyer power among the largest pharmaceutical and academic medical center networks. Independent laboratories and mid-tier biotech firms lose negotiating leverage as preferred vendor agreements lock in multi-year service contracts. This concentration is most visible in the United States, where three national GPOs control the majority of hospital system capital equipment spending.
Liquid Handling Technology Market Segmentation
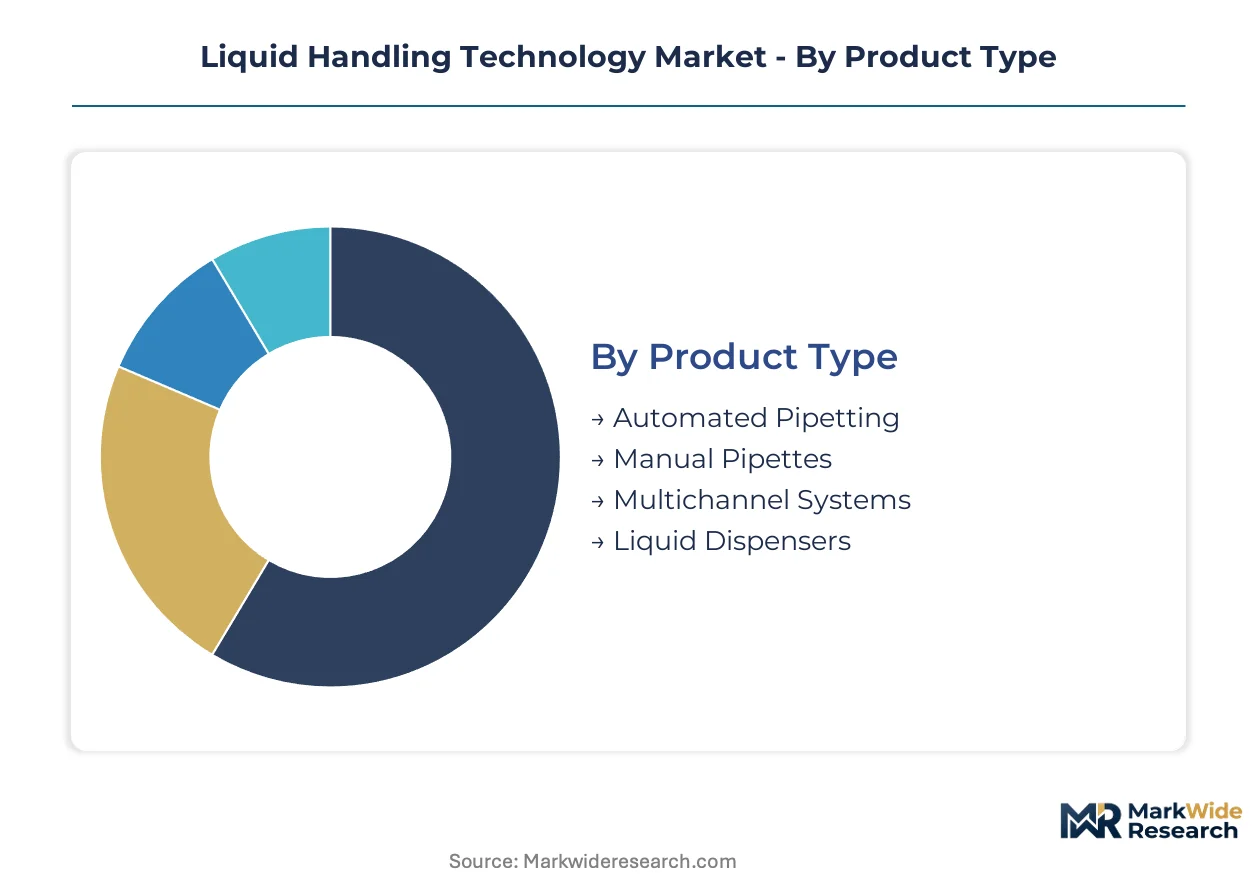
Segmentation in liquid handling technology reveals how precision requirements, throughput demands, and regulatory compliance reshape vendor priorities across equipment categories. Understanding these divisions exposes where capital investment concentrates and where service revenue pools deepen.
Product Type:
Margin pools concentrate in automated systems where recurring calibration contracts and disposable tip consumables generate annuity revenue streams.
- Automated Pipetting:Robotic workstations integrate programmable controllers with sensor feedback for nanoliter-to-milliliter precision. Pharmaceutical companies in the United States deploy these systems to compress compound screening cycles, with FDA 21 CFR Part 11 compliance mandates forcing equipment qualification protocol upgrades.
- Multichannel Systems:Parallel dispensing heads execute 96- and 384-well plate formats simultaneously. High-throughput screening facilities in Germany anchor demand as EU MDR traceability requirements elevate certified service contracts over ad-hoc maintenance.
- Manual Pipettes:Handheld single-channel instruments dominate academic laboratories with modest sample volumes. The installed base resists capital conversion to automated workstations.
- Liquid Dispensers:Bulk reagent distribution systems handle milliliter-scale transfers for cell culture media preparation. Bioproduction facilities favor peristaltic and syringe pump configurations.
Automated Pipetting holds installed capacity. Multichannel Systems is rotating up the share rankings.
End User:
Customer concentration patterns split between capital-rich pharmaceutical networks and price-sensitive academic procurement channels.
- Pharmaceutical Companies:Integrated drug discovery pipelines demand end-to-end workflow automation from sample prep to analytics. Consolidated procurement through group purchasing organizations concentrates buyer power among the largest networks.
- Biotechnology Firms:Mid-tier innovators balance throughput requirements against capital constraints. Contract research organizations in China expand automated liquid handling adoption to compete for international outsourcing contracts.
- Academic Institutes:Research funding cycles drive episodic equipment replacement. Manual pipette substitution persists in low-throughput settings.
- Clinical Laboratories:Diagnostic applications require FDA-enforced current Good Manufacturing Practice quality system compliance. EU MDR Annex XVI classification expansion now captures certain laboratory automation equipment previously exempt from conformity assessment.
Pharmaceutical Companies command the premium tier. Biotechnology Firms are expanding most quickly as venture funding flows toward platform therapeutics developers.
Technology:
Technology selection determines consumable economics, with tipless mechanisms capturing share in high-volume screening operations.
- Acoustic Dispensing:Tipless droplet ejection eliminates plastic consumption and cross-contamination risks through focused ultrasound energy. Genomics core facilities adopt these systems where per-sample processing costs must compress below five cents.
- Microfluidics:Cartridge-based miniaturization enables point-of-care diagnostic platforms requiring embedded liquid handling modules. Clinical validation timelines constrain near-term revenue conversion.
- Air Displacement:Piston-driven air cushion systems dominate general laboratory pipetting through cost-effective disposable tip architectures. ISO 8655 calibration standards bifurcate the competitive landscape between certified precision suppliers and uncertified commodity vendors.
- Positive Displacement:Direct piston-to-liquid contact handles viscous or volatile samples where air displacement fails. Specialized applications in proteomics sample prep sustain niche demand.
Air Displacement maintains broadest deployment. Acoustic Dispensing is climbing the fastest as sustainability pressures intensify.
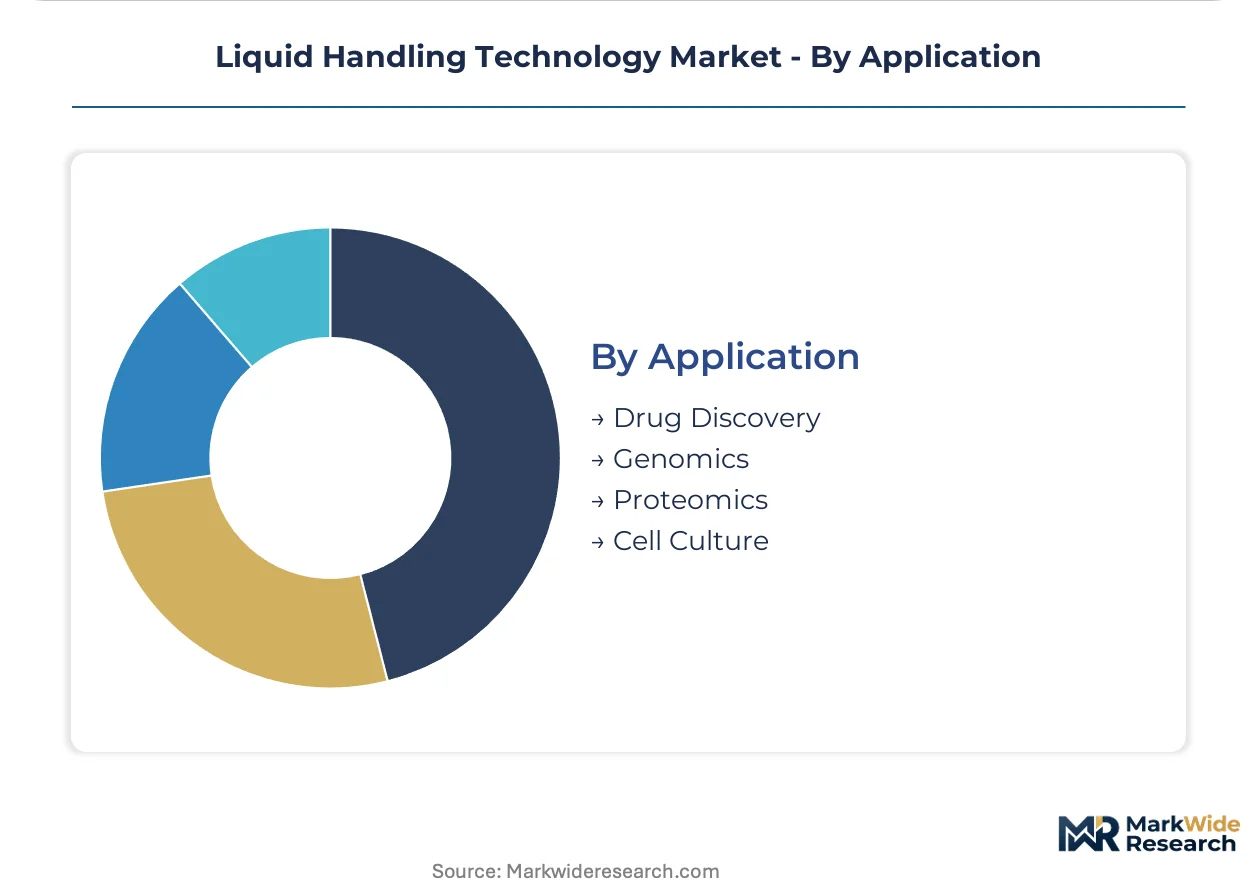
Application:
Application focus determines throughput specifications and integration complexity with upstream sample prep and downstream analytics.
- Drug Discovery:Compound library management and high-throughput screening anchor the largest equipment installations. Robotic workstations process millions of samples annually.
- Genomics:Next-generation sequencing library preparation demands nanoliter-precision normalization and pooling. Core facilities upgrade acoustic dispensing to eliminate tip waste.
- Proteomics:Mass spectrometry sample prep requires precise reagent addition and digestion timing. Positive displacement technology addresses detergent-containing lysis buffers.
- Cell Culture:Sterile media exchange and passaging operations favor peristaltic dispensers with enclosed fluid paths. Bioproduction scale-up drives demand for larger-volume systems.
Drug Discovery retains the deepest installed base. Genomics is gaining share fastest as sequencing throughput expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical networks in the United States, Germany, and China concentrate procurement authority for automated liquid handling systems, while emerging biopharma clusters in India and Brazil struggle with calibration infrastructure gaps.
United States
FDA 21 CFR Part 11 compliance mandates force equipment qualification protocol overhauls among diagnostic manufacturers and contract research organizations. The Boston-Cambridge biotech corridor anchors demand for high-throughput screening automation, with venture-backed platform therapeutics companies driving workstation installations.
Germany
EU MDR traceability requirements elevate certified service contracts over ad-hoc maintenance for diagnostic liquid handlers. The Rhine-Main biopharma cluster, encompassing Frankfurt and Darmstadt, deepens automation investments as notified body conformity assessments tighten equipment validation standards.
China
Domestic biopharma contract research organizations expand automated pipetting adoption to compete for international outsourcing contracts. Shanghai and Suzhou industrial parks concentrate genomics core facility buildouts, though NMPA quality system regulations lag FDA predicate device pathways in harmonization.
India
Production-linked incentives under the PLI scheme attract domestic manufacturing of diagnostic instruments to reduce import duties. Hyderabad and Bengaluru biotech clusters face extended equipment downtime due to scarce ISO 8655 certified metrology laboratories.
Brazil
Academic and clinical laboratories with modest sample volumes resist capital conversion from manual pipettes to automated workstations. São Paulo's research medical centers anchor the limited installed base of multichannel systems, constrained by ANVISA import registration timelines.
Liquid Handling Technology Market Competitive Landscape
Player mix skews toward diversified life science conglomerates with recurring calibration revenue streams. Market structure concentrates around three tiers: premium precision suppliers with global service networks, mid-tier workflow integrators, and specialized OEM module fabricators. Dominant competitive moves include strategic partnerships for software integration and geographic expansion through local assembly partnerships.
Within the diversified conglomerate tier, Thermo Fisher Scientific and Danaher occupy anchor positions through global service infrastructure and integrated workflow portfolios. Hamilton Company exemplifies the specialized OEM archetype, embedding liquid handling modules into diagnostic instruments. These three entities represent distinct strategic vectors: service-network scale, workflow integration breadth, and embedded component specialization.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Danaher |
| Agilent Technologies |
| Eppendorf |
| Tecan Trading AG |
| Hamilton Company |
| PerkinElmer |
| Sartorius AG |
| Mettler Toledo |
| Others |
Value Network & Pricing Analysis
ISO 8655 calibration certification gates both supplier qualification and price differentiation simultaneously, separating certified precision vendors who command service contract premiums from uncertified commodity producers competing on hardware margins alone. Pharmaceutical procurement teams in the United States and Germany now require documented metrology chains, compressing pricing power for vendors lacking accredited laboratory networks.
Pricing Analysis
Cost-plus service contracts with fluoropolymer resin indexation dominate mid-tier automated workstation procurement, protecting instrument manufacturers from PTFE and PFA feedstock volatility. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated systems with 21 CFR Part 11 software compliance from basic laboratory pipettes without calibration documentation. Pricing pressure stems from consolidated group purchasing organization buying power in United States hospital networks. Academic laboratories in Brazil and India exhibit highest price sensitivity, while pharmaceutical companies in Germany prioritize certified service uptime over capital expenditure minimization.
Supply Chain Analysis
Extended lead times for precision piston seals and sensor modules stretch 16-24 weeks, forcing equipment manufacturers to hold strategic inventory buffers against fluoropolymer supply disruptions. Component manufacturing concentrates in Germany, Switzerland, and Japan for high-precision metrology-grade instruments, while plastic consumable molding feeds from China and Malaysia. Supply chains draw from concentrated PTFE resin suppliers in the United States and Japan, creating single-source vulnerability for chemically resistant seals. Distribution runs through authorized service dealer networks with regional calibration capabilities, bypassing traditional industrial distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face acute substitution pressure from acoustic dispensing technology eliminating consumable revenue streams in ultra-high-throughput screening facilities, requiring defensive repositioning around integrated workflow software and predictive maintenance subscriptions.
For Market Incumbents: Shield recurring revenue streams by embedding IoT-enabled remote calibration monitoring into installed base contracts, countering acoustic tipless systems that erode disposable tip annuity income. Deepen backward integration into fluoropolymer component manufacturing to insulate margins from resin price volatility. Prioritize ISO 13485 quality system certification for diagnostic liquid handlers ahead of EU MDR Annex XVI enforcement expansion.
For New Entrants and Emerging Players: Lead with cloud-native laboratory information management system integration targeting mid-tier biotechnology firms struggling with cross-platform orchestration gaps. India's PLI scheme for medical devices manufacturing offers white-space entry with reduced import duty exposure and faster service response times. Position around subscription-based predictive maintenance models rather than capital equipment sales to bypass entrenched vendor service relationships.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified life science conglomerates liquidating non-core liquid handling divisions amid portfolio consolidation pressures. Long-term viability hinges on software and service revenue exceeding hardware sales ratios, with acoustic dispensing technology penetration serving as the critical inflection signal for traditional tip-based equipment obsolescence risk.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Quality System Adoption | EU MDR Annex XVI compliance secures notified body certification for diagnostic liquid handler market access. |
| Cloud-Connected Predictive Maintenance | IoT sensor integration shifts revenue from reactive repairs to subscription-based uptime guarantees. |
| Acoustic Dispensing Technology Licensing | Tipless droplet ejection eliminates consumable costs in genomics core facility screening workflows. |
| Point-of-Care Microfluidics Partnership | Cartridge-based diagnostic platforms open decentralized healthcare settings previously inaccessible to laboratory equipment. |
| Fluoropolymer Backward Integration | In-house PTFE seal production insulates margins from concentrated resin supplier price volatility. |
Research Methodology
A standing panel of drug discovery executives, regulatory affairs leads at diagnostic manufacturers, biomedical engineers at genomics core facilities, and group purchasing organization contracts managers provided ongoing calibration against market dynamics. Primary interview insights combined with secondary validation from FDA 510(k) filings, EU MDR notified body conformity assessment databases, and NMPA quality system registration records. Bottom-up equipment installation tracking and top-down pharmaceutical R&D expenditure analysis enabled triangulation across independent analytical paths.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including technology mechanism, end-user procurement channel, application throughput requirements, and regional regulatory compliance cluster. CAGRs derived from equipment replacement cycle analysis, biopharma automation capital expenditure trends, and acoustic dispensing adoption curve parameters calibrated against genomics facility buildout rates.
The analysis sits within stated boundaries; outcomes outside sustained pharmaceutical R&D investment levels or accelerated EU MDR enforcement timelines would require recalibration. Forecasts reflect assumptions regarding fluoropolymer supply stability and harmonization progress between FDA predicate device pathways and EU notified body assessments. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Linear Motion System Market
Industrial Automation
Warehouse Automation Equipment Market
Industrial Automation
Middle East and Africa Machine Control System Market
Industrial Automation
UV Curing System Market
Industrial Automation
Connected Worker Market
Industrial Automation
Hardware in the Loop Market
Industrial Automation
Cross-Belt Sorters Market
Industrial Automation
Europe Factory Automation and Industrial Controls Market
Industrial Automation
Brazil Factory Automation and Industrial Controls Market
Industrial Automation
Programmable Logic Controller Market
Industrial Automation
Global Operational Technology Market
Industrial Automation
Motion Control Centers Market
Industrial Automation
US and Europe Warehouse Automation Market
Industrial Automation
Smart and Connected Elevators and Elevators Control Systems Market
Industrial Automation
Latin America HMI Market
Industrial Automation
Europe Water Automation and Instrumentation Market