
 Enterprise Network Equipment Market | 2026-2036
Enterprise Network Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Enterprise Network Equipment Market Analysis
Indirect distribution through value-added resellers and systems integrators is reshaping how enterprise network equipment reaches end customers. Cisco Systems leverages its global partner program to sustain deep channel control across enterprise accounts. Huawei Technologies anchors its position through integrated silicon-to-system capabilities in select regional markets. Arista Networks specializes in high-throughput data center switching, competing aggressively for cloud provider contracts.
Enterprise network equipment encompasses routers, switches, access points, firewalls, and associated management systems engineered to process traffic at speeds from 1 Gbps to 400 Gbps with sub-microsecond latency for mission-critical workloads. These systems form the backbone of organizational connectivity, enabling secure data transport across campus, branch, and cloud environments. Ethernet switching dominates product-level revenue due to refresh cycles in hyperscale facilities, while SD-WAN technology represents the fastest-expanding segment as enterprises disaggregate hardware from control planes. Government end users present concentrated procurement volumes through classified network modernization programs.
The FCC governs spectrum allocation and equipment authorization for wireless network gear in the United States, directly shaping vendor product roadmaps for Wi-Fi and cellular backhaul. ETSI and the EU AI Act impose emerging compliance obligations on network equipment with embedded intelligence, affecting how vendors architect edge analytics capabilities. Procurement teams must evaluate supplier exposure to semiconductor export controls and dual-use technology classifications when qualifying vendors for multi-year infrastructure commitments.
Market Dynamics
Hyperscale data center operators are compressing refresh cycles from five years to three years, forcing vendors to accelerate 400 Gbps and 800 Gbps port development timelines while managing semiconductor supply constraints.
Growth Catalysts
- FCC Broadband Equity Access and Deployment (BEAD) Program:The $42.45 billion infrastructure initiative mandates fiber-to-the-premises deployments across underserved counties, driving router and optical transport procurement for last-mile backhaul.
- AI/ML training cluster expansion:Cloud providers are building dedicated GPU fabrics requiring ultra-low-latency Ethernet fabrics with RDMA over Converged Ethernet (RoCE) support.
- 5G standalone core migration:Mobile network operators are replacing virtualized packet core appliances with cloud-native user plane functions, generating fresh demand for high-density switching platforms.
Market Restraints
- Advanced networking silicon concentration:Merchant switch silicon fabrication depends on a single foundry geography for 7nm and below process nodes, creating allocation risk during geopolitical disruptions.
- EU AI Act compliance burden:Network equipment with embedded machine learning for traffic optimization now faces conformity assessment procedures, extending product launch timelines by 8-14 months.
- White-box switch substitution:Disaggregated hardware-software procurement models allow cloud operators to source commodity switching hardware directly from ODMs, compressing branded equipment margins.
Strategic Opportunities
- India data center buildout:The country's national electronics regulator and state-level data localization mandates are accelerating hyperscale facility construction in Mumbai, Chennai, and Hyderabad.
- Private 5G industrial networks:Manufacturing campuses and port authorities are deploying localized cellular infrastructure, creating demand for integrated small cell and edge routing platforms.
- Energy-efficiency certification differentiation:The EU Green Deal's embodied carbon reporting requirements for ICT equipment enable vendors with verified low-carbon supply chains to capture premium positioning.
Industry Challenges
- Specialized silicon design talent scarcity:Vendors compete for limited pools of engineers capable of architecting 112 Gbps SerDes and co-packaged optics, inflating R&D compensation costs.
- Multi-vendor interoperability certification:Enterprise buyers mandate proof of seamless operation across three or more equipment vendors, forcing suppliers into costly third-party test lab engagements.
- Legacy MPLS-to-SD-WAN migration complexity:Financial services and healthcare organizations with decade-old WAN architectures face 18-24 month transition timelines, delaying new equipment procurement decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enterprise Network Equipment Market |
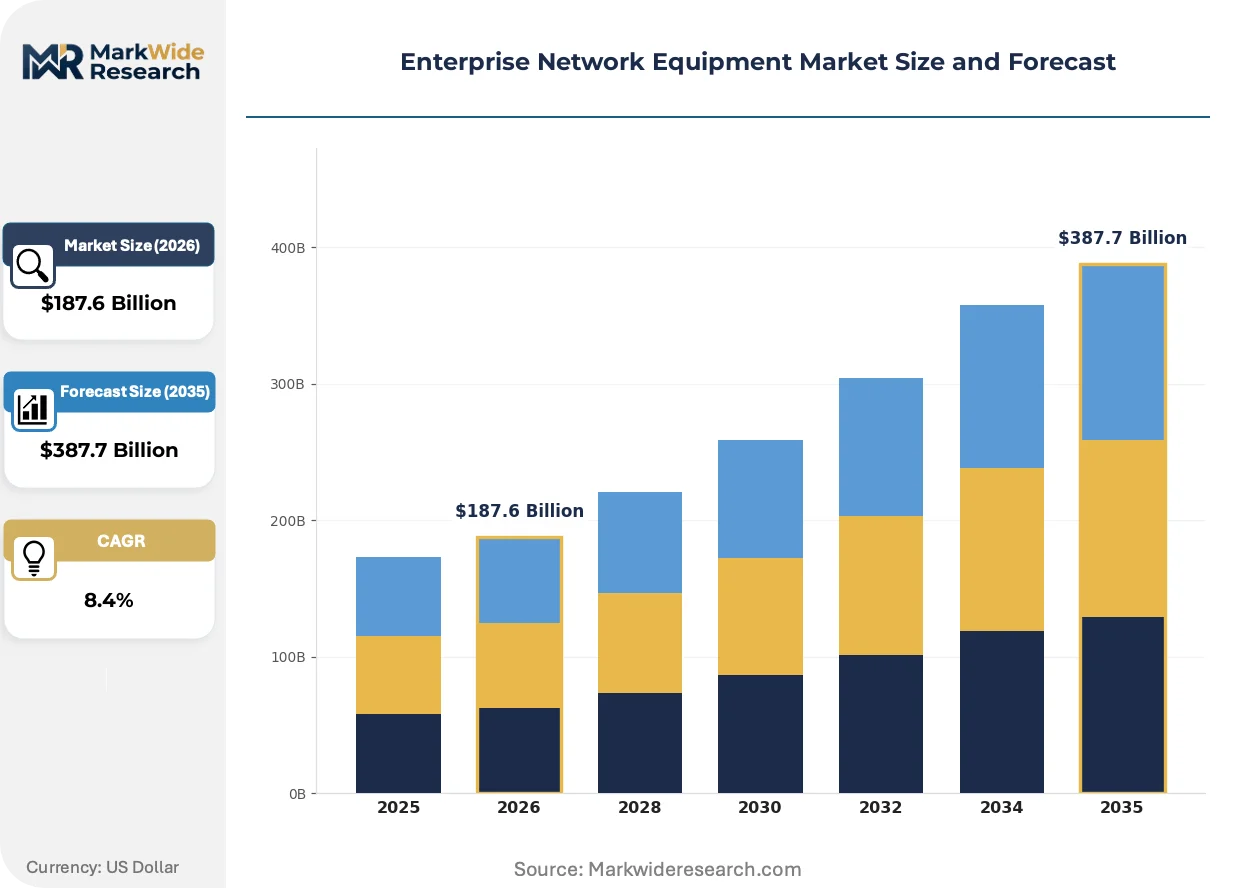
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $387.7 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Routers, Switches, Access Points, Firewalls Technology: Ethernet, Wi-Fi, MPLS, SD-WAN End User: SMBs, Enterprises, Government, Educational Institutions Application: Data Center Connectivity, Network Security, Cloud Connectivity, VoIP |
| Companies Covered | Cisco Systems, Huawei Technologies, Hewlett Packard Enterprise, Juniper Networks, Arista Networks, Broadcom, Dell Technologies, Fortinet, Palo Alto Networks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enterprise Network Equipment Market Emerging Trajectories
Silicon photonics and co-packaged optics are collapsing power-per-bit metrics, while regulatory pressure on supply chain transparency is rewiring vendor qualification processes across enterprise procurement teams.
Co-packaged optics (CPO) technology replaces pluggable transceivers with optical engines mounted directly on switch ASIC substrates. Hyperscale operators at facilities in Northern Virginia and Dallas-Fort Worth are piloting 51.2 Tbps CPO-based switches for 2025 deployment. This architecture is digitizing data center fabric economics by cutting optical interconnect power consumption by 30 percent and eliminating retimer components from the bill of materials.
The EU AI Act's risk-based classification system now captures network equipment with autonomous traffic engineering capabilities. Vendors must document training data provenance and algorithmic decision logic for products deployed in EU member states. European enterprise and telecom procurement teams are inserting AI Act conformity clauses into RFP requirements, favoring suppliers with pre-positioned technical documentation packages.
Enterprise buyers are unbundling hardware acquisition from software licensing and support contracts, treating network infrastructure as a consumable operating expense. Value-added resellers and systems integrators are responding with as-a-service financing structures that wrap equipment, installation, and lifecycle management into per-port monthly fees. This model is gaining strongest traction among mid-market healthcare and retail organizations in the United States seeking to preserve balance sheet capacity.
Enterprise Network Equipment Market Segmentation
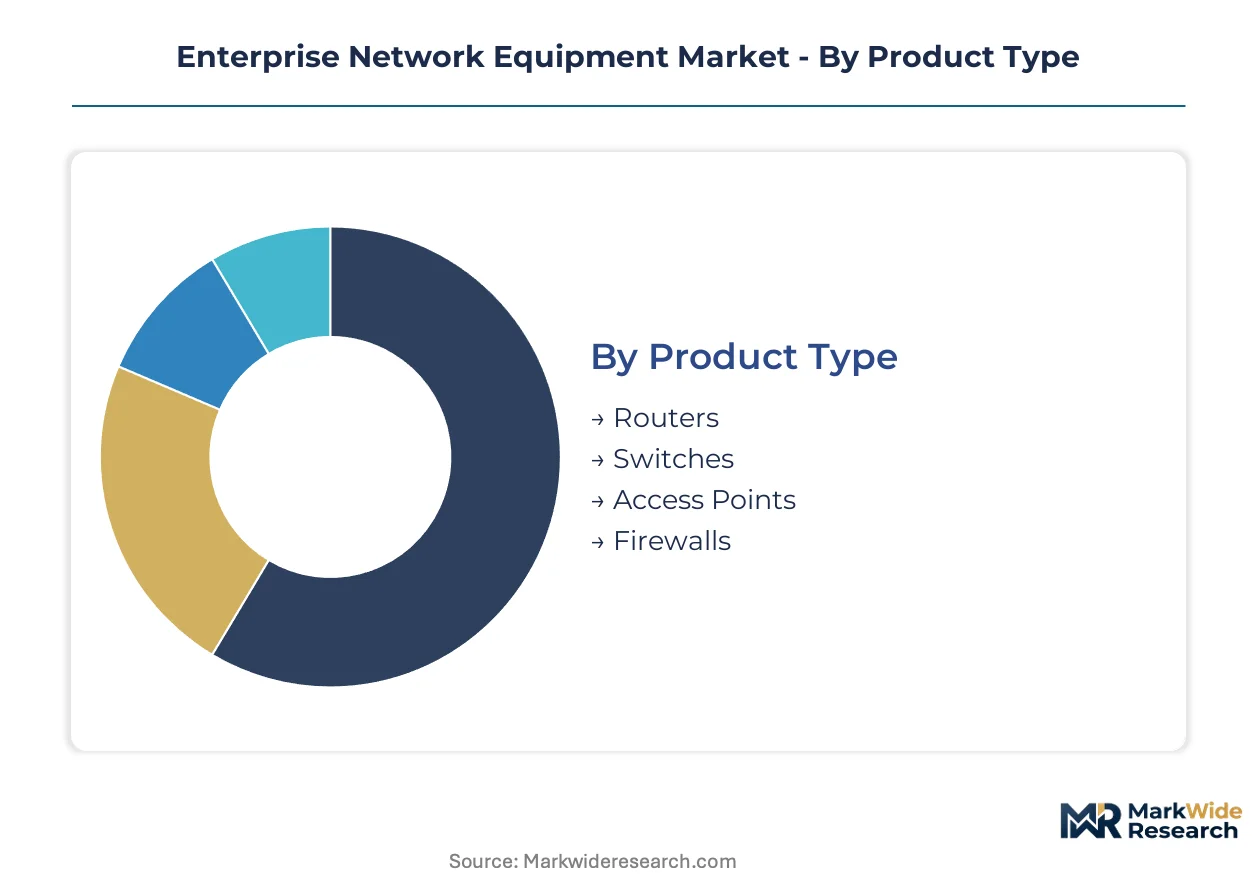
Equipment segmentation in this market determines procurement complexity, lifecycle support obligations, and margin structures for vendors. Distinct technical requirements across product categories and deployment contexts create specialized service ecosystems that reshape competitive positioning.
Product Type:
After-sales service intensity varies sharply across hardware categories, with some segments demanding continuous firmware management and others operating on extended replacement cycles.
- Switches:High-density Ethernet switches process traffic at 400 Gbps in hyperscale facilities, requiring thermal management and optics cleaning protocols. Demand concentrates in Northern Virginia and Dallas-Fort Worth data center clusters, driven by compressed three-year refresh cycles forcing accelerated port density roadmaps.
- Routers:Core and edge routing platforms handle BGP table growth and segment routing policies for WAN aggregation. Government end users present concentrated procurement volumes through classified network modernization programs, creating multi-year support contract requirements.
- Access Points:Wi-Fi 6E and Wi-Fi 7 radios deliver 6 GHz spectrum utilization for high-density campus environments.
- Firewalls:Next-generation appliances integrate deep packet inspection with threat intelligence feeds for perimeter and east-west segmentation.
Switches hold the largest share; momentum sits with firewalls as zero-trust architectures expand.
Technology:
Cost tier differentiation separates capital-intensive hardware refreshes from software-overlay deployments that preserve existing infrastructure investments.
- Ethernet:Layer 2 and Layer 3 switching fabrics dominate data center capital expenditure, with 800 Gbps port development timelines accelerating. Cloud providers in the United States are building dedicated GPU fabrics requiring ultra-low-latency fabrics with RDMA over Converged Ethernet support.
- SD-WAN:Software-defined overlays disaggregate control planes from hardware, enabling policy-based path selection across multiple transport types. Mid-market healthcare and retail organizations in the United States are adopting as-a-service financing structures for this technology.
- Wi-Fi:Wireless LAN infrastructure supports mobility and IoT density requirements across enterprise campuses.
- MPLS:Legacy private WAN technology faces displacement as enterprises migrate to internet-based transport with encrypted overlays.
Ethernet holds the largest share; SD-WAN is climbing the fastest as enterprises disaggregate hardware from control planes.
End User:
Volume concentration and procurement sophistication create distinct margin profiles across customer categories, with some segments demanding extensive pre-sales engineering support.
- Enterprises:Large organizations operate multi-site networks with dedicated operations teams and formal vendor qualification processes. Financial services and healthcare organizations face 18-24 month MPLS-to-SD-WAN migration timelines, delaying new equipment procurement decisions.
- Government:Federal and classified network operators mandate supply chain provenance documentation and domestic manufacturing requirements. The FCC's broadband infrastructure programs are accelerating fiber and wireless backhaul deployments for civilian agency connectivity.
- SMBs:Small and medium businesses prioritize simplified management interfaces and bundled support contracts over feature depth.
- Educational Institutions:Universities and K-12 districts balance budget constraints with high-density wireless requirements for student device populations.
Enterprises hold the largest share; momentum sits with government as classified network modernization programs expand.
Application:
Customer type and deployment maturity shape how application requirements translate into equipment specifications and vendor selection criteria.
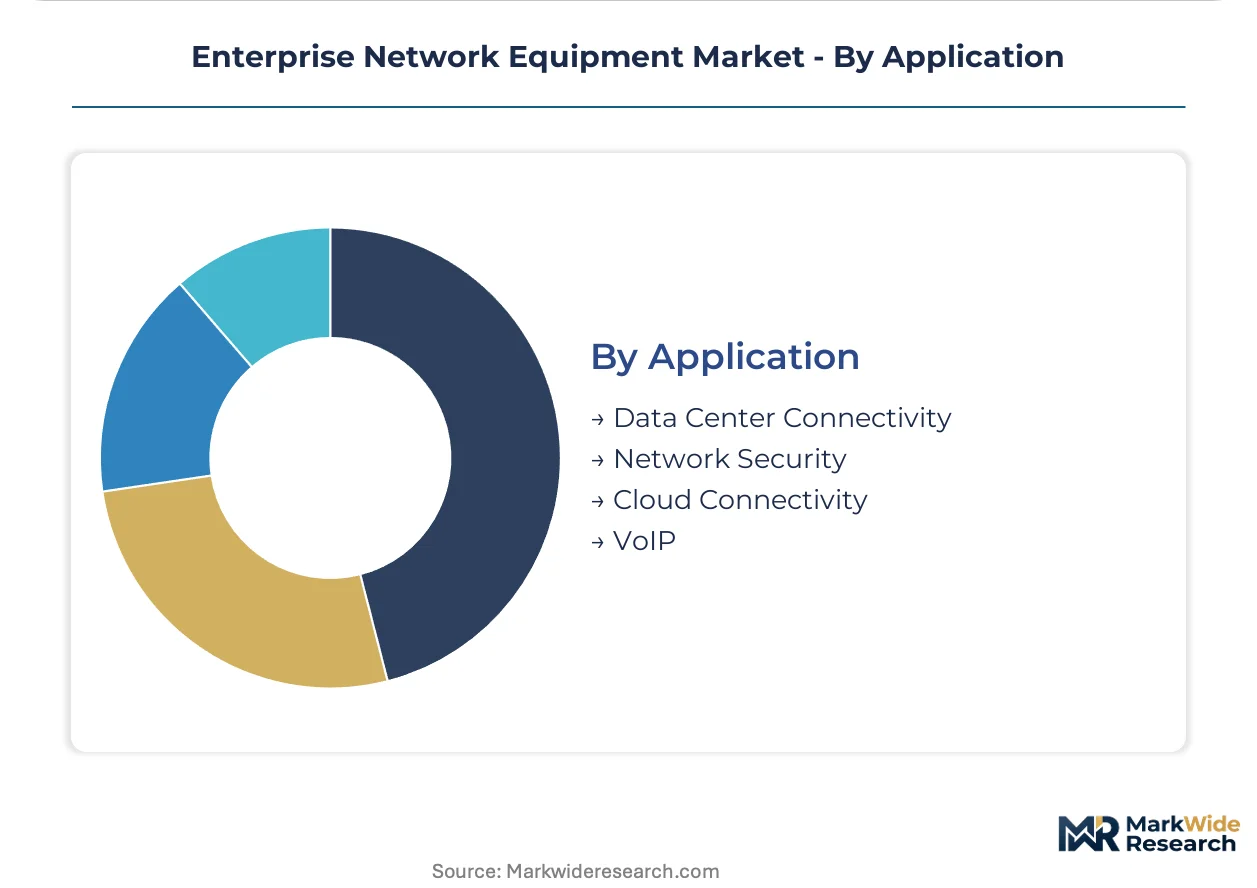
- Data Center Connectivity:Spine-leaf architectures and co-packaged optics integration dominate hyperscale facility design. Operators in Northern Virginia are piloting 51.2 Tbps CPO-based switches, cutting optical interconnect power consumption by 30 percent.
- Network Security:Segmentation and threat prevention capabilities increasingly influence switching and routing procurement decisions. The EU AI Act's risk-based classification system captures equipment with autonomous traffic engineering, extending product launch timelines.
- Cloud Connectivity:Direct cloud on-ramps and dedicated interconnects require consistent policy enforcement across hybrid environments.
- VoIP:Voice over IP infrastructure demands quality-of-service prioritization and power-over-Ethernet support for endpoint devices.
Data Center Connectivity holds the largest share; Network Security is gaining share fastest as regulatory compliance requirements harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in United States hyperscale clusters while procurement costs compress in European markets facing extended regulatory timelines. This asymmetry shapes vendor resource allocation and product launch sequencing across geographies.
United States
Hyperscale data center construction in Northern Virginia and Dallas-Fort Worth drives 400 Gbps and 800 Gbps switch procurement at compressed three-year refresh cycles. The FCC's BEAD program mandates fiber-to-the-premises deployments across underserved counties, accelerating router and optical transport procurement for last-mile backhaul. Cloud providers in these clusters are piloting co-packaged optics switches for 2025 deployment.
Germany
Industrial automation and automotive manufacturing campuses are deploying private 5G networks requiring integrated small cell and edge routing platforms. The EU AI Act imposes conformity assessment procedures on network equipment with embedded machine learning, extending product launch timelines by 8-14 months. Frankfurt's data center hub faces procurement delays as enterprises await regulatory clarity on autonomous traffic engineering systems.
China
Domestic cloud providers are expanding physical infrastructure footprints with state-backed financing for hyperscale facilities in Beijing-Tianjin-Hebei and Yangtze River Delta clusters. MIIT spectrum allocation policies shape vendor roadmaps for Wi-Fi and cellular backhaul equipment. Shanghai-based operators are sourcing commodity switching hardware through disaggregated procurement models, compressing branded equipment margins.
India
National data localization mandates and state-level electronics policies are accelerating hyperscale facility construction in Mumbai, Chennai, and Hyderabad. TRAI regulations govern spectrum allocation for wireless network gear, directly influencing vendor product specifications. Mumbai's emerging data center cluster is attracting 400 Gbps switch deployments from cloud providers building dedicated GPU fabrics for AI training.
United Kingdom
Financial services organizations in London face 18-24 month MPLS-to-SD-WAN migration timelines, delaying new equipment procurement decisions. The UK national cybersecurity regulator imposes supply chain provenance documentation requirements for critical network infrastructure. London's financial district is seeing concentrated demand for next-generation firewalls with deep packet inspection capabilities.
Enterprise Network Equipment Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in the silicon and optics layers. The vendor base separates into three tiers: full-stack platform providers, merchant silicon suppliers, and disaggregated hardware-software specialists. Two dominant competitive moves are reshaping positioning: strategic partnerships between cloud operators and merchant silicon vendors, and vertical integration into co-packaged optics design.
Within the full-stack platform tier, Cisco Systems and Arista Networks exemplify divergent approaches to cloud provider engagement. Cisco leverages its global partner program to sustain deep channel control across enterprise accounts, while Arista occupies a position concentrated on high-throughput data center switching for hyperscale contracts. Huawei Technologies anchors the integrated silicon-to-system capability archetype in select regional markets where supply chain constraints permit continued presence.
| Leading Market Players |
|---|
| Cisco Systems |
| Huawei Technologies |
| Hewlett Packard Enterprise |
| Juniper Networks |
| Arista Networks |
| Broadcom |
| Dell Technologies |
| Fortinet |
| Palo Alto Networks |
| Others |
Supply Flow & Price Mechanics
Northern Virginia's hyperscale data center cluster concentrates procurement volumes for 400 Gbps and 800 Gbps switches, compressing refresh cycles and amplifying buyer leverage over vendor pricing schedules. Cloud operators in this corridor negotiate multi-year volume commitments that reset benchmark pricing tiers across the enterprise equipment sector.
Pricing Analysis
The customization-premium spread separates standard catalog pricing from engineered-to-order configurations for classified government networks. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales bundling intensity. Cost compression in the standard tier is intensifying because white-box switch substitution allows cloud operators to bypass branded equipment entirely. Mid-market healthcare and retail organizations in the United States exhibit highest price sensitivity, while government end users with multi-year modernization mandates show lowest sensitivity.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from merchant silicon vendors have become critical liquidity tools for switch manufacturers managing 7nm and below wafer allocation. Fabrication capacity concentrates in Taiwan, South Korea, and the United States, drawing from advanced CMOS process nodes, co-packaged optics substrates, and specialized SerDes IP. Single-source vulnerability around leading-edge foundry geography creates allocation risk during geopolitical disruptions. Distribution runs through value-added resellers and systems integrators for enterprise accounts, while hyperscale operators procure directly from original design manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as SD-WAN disaggregation and AI-driven traffic engineering create specialized vendor niches outside incumbent full-stack dominance. The shift from hardware-centric to software-overlay procurement splits purchasing authority between infrastructure and application teams.
For Market Incumbents: Build switching fabric moats through captive co-packaged optics design to defend against merchant silicon commoditization. Deepen channel control by embedding lifecycle management services into per-port subscription offerings. Secure 800 Gbps port development timelines against emerging entrants with foundry allocation guarantees. Counter white-box substitution threat with verified interoperability certification across three or more vendor environments.
For New Entrants and Emerging Players: Build out private 5G industrial network integration capabilities targeting manufacturing campuses and port authorities in Germany and the United States. Private cellular infrastructure remains underpenetrated relative to Wi-Fi densification, offering white-space entry with integrated small cell and edge routing platforms. Pursue as-a-service financing structures for mid-market healthcare verticals seeking operating expense treatment of network infrastructure.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors merchant silicon specialists with 112 Gbps SerDes and optical engine integration capabilities. Five-to-ten year viability hinges on backward integration into co-packaged optics design or strategic foundry partnerships. Acquisition target archetype: disaggregated hardware-software specialists with pre-positioned EU AI Act technical documentation. Signal to watch: hyperscale pilot deployments of 51.2 Tbps CPO-based switches validating power-per-bit economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Co-Packaged Optics Integration | Reduces optical interconnect power consumption by 30 percent in Northern Virginia facilities. |
| EU AI Act Compliance Pre-Positioning | Accelerates product launch timelines by 8-14 months versus reactive conformity assessment. |
| Private 5G Platform Development | Captures industrial automation demand from automotive manufacturing campuses in Germany. |
| Merchant Silicon Partnership | Secures allocation priority for 7nm process nodes during foundry capacity constraints. |
| As-a-Service Financing Structure | Preserves balance sheet capacity for mid-market healthcare organizations in the United States. |
Methodological Framework
Initial hypotheses were tested against primary input from data center infrastructure directors, network engineering leads at cloud providers, government procurement officers, and value-added reseller principals and refined through secondary validation against SEC filings, hyperscaler capital expenditure disclosures, FCC broadband program documentation, and ETSI technical specifications. Bottom-up equipment shipment modeling was cross-checked against top-down addressable market sizing across the analysis window.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology layer, end user category, and deployment application plus regional regulatory cluster. CAGRs were derived from fitted growth curves applied to base-year estimates. Industry-specific forecast inputs incorporated 400 Gbps and 800 Gbps port adoption trajectories and BEAD program disbursement schedules.
Stress conditions across semiconductor allocation disruptions, EU AI Act implementation delays, and hyperscale capital expenditure freezes were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about refresh cycle compression and white-box substitution rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Network Management Solutions Market
Network Technology
Global LWAN Market
Network Technology
Private LTE Market
Network Technology
GCC Set-Top Box Market
Network Technology
ISP Management Systems Market
Network Technology
Virtual Router Market
Network Technology
Network Devices Market
Network Technology
Mobile Backhaul Market
Network Technology
Internet Protocol Address Management (IPAM) Market
Network Technology
Fiber to the Home (FTTH) Market
Network Technology
Europe Self-Healing Networks Market
Network Technology
5G Enterprise Private Network Market
Network Technology
Session Border Controller (SBC) Market
Network Technology
Philippines Software-Defined Wide Area Network (SD-WAN) Market
Network Technology
Mobile Accelerator Market
Network Technology
Global Routing Market