
 Global Industrial Analytics Market | 2026-2036
Global Industrial Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Industrial Analytics Market Foresight
Power generation and chemical processing is broadening as the fastest-expanding end-use vertical mix for industrial analytics platforms. Siemens AG leverages deep automation heritage to dominate European deployment of edge analytics for turbine monitoring. Microsoft Corporation sustains cloud infrastructure leadership through Azure IoT integration with manufacturing execution systems. General Electric Company anchors its position in asset performance management through Predix platform specialization in aviation and energy verticals.
Industrial analytics encompasses software platforms, edge computing nodes, and machine learning models that process operational technology data streams from sensors, programmable logic controllers, and supervisory control systems to predict equipment failures, optimize throughput, and reduce unplanned downtime. Predictive maintenance solutions command the largest solution offering revenue pool due to quantifiable return on investment from avoided catastrophic failures. Cloud-based deployment is accelerating fastest as hyperscaler infrastructure meets latency requirements through regional edge nodes, while on-premise systems retain share in defense and classified chemical processing environments.
The EU AI Act imposes conformity assessments on high-risk industrial AI systems, compelling vendors to document training data provenance and model drift monitoring. The FDA's software-as-medical-device framework extends to pharmaceutical manufacturing analytics, requiring validation protocols for algorithms controlling batch release decisions. ISO 50001 energy management standards drive utility operators toward certified analytics platforms. Stakeholders must evaluate whether their current vendor roadmaps address emerging algorithmic audit requirements before procurement cycles close.
Market Dynamics
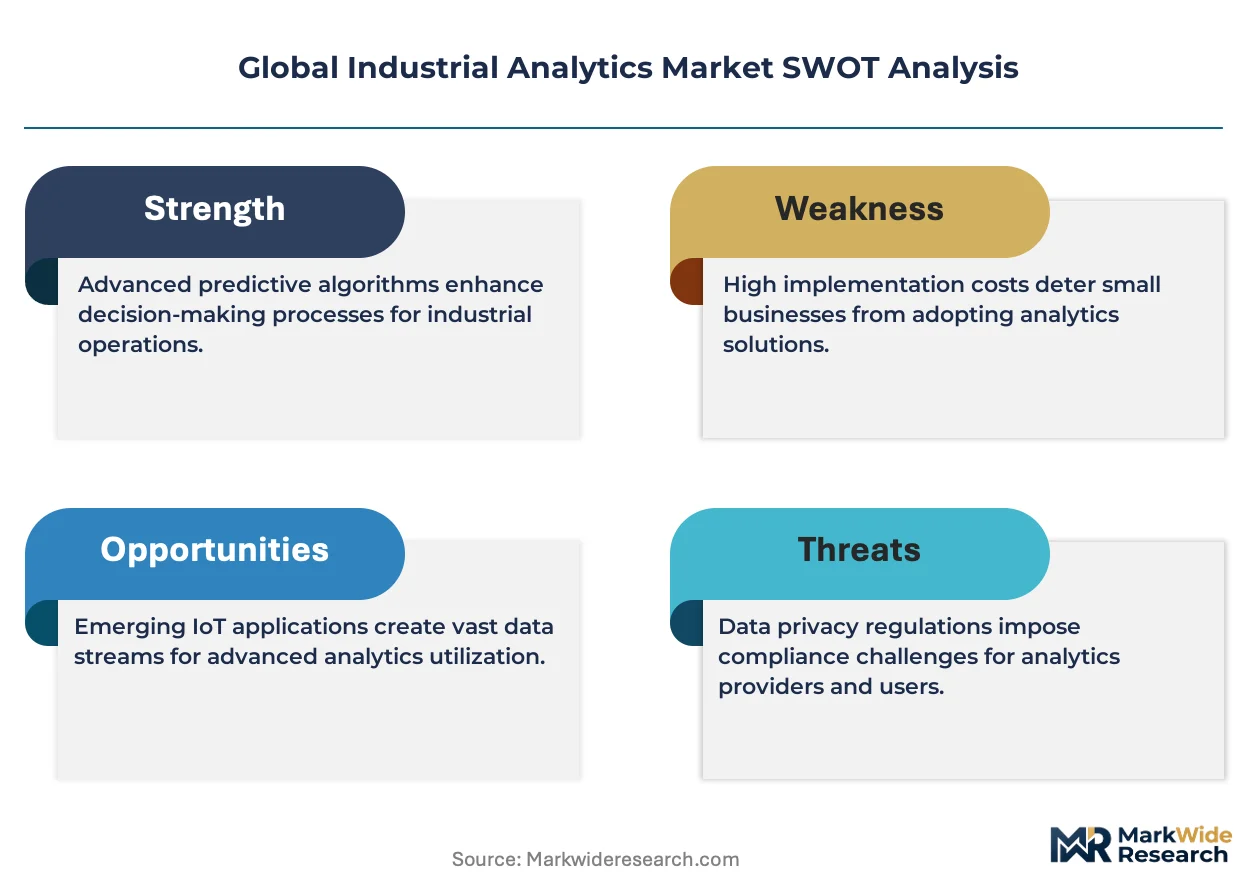
The industrial analytics sector faces a structural compression between algorithmic transparency mandates and the opacity of proprietary machine learning models, forcing vendors to rearchitect platforms for auditable decision trails without sacrificing predictive accuracy.
Growth Catalysts
- EU AI Act Conformity Assessments:High-risk system classifications create procurement pull for certified analytics platforms in German automotive and French pharmaceutical manufacturing clusters.
- Edge Computing Latency Reduction:Regional hyperscaler nodes now support sub-50 millisecond response times for turbine vibration analysis in North Sea offshore installations.
- Power Generation Asset Intensity:Utility operators deploy predictive maintenance to avoid single-point failures in combined-cycle gas turbine fleets where downtime costs exceed $1 million per day.
Market Restraints
- Semiconductor Supply Concentration:Edge analytics hardware depends on advanced node fabrication concentrated in Taiwan and South Korea, exposing deployment timelines to geopolitical friction.
- Specialized Talent Scarcity:Industrial data science roles require simultaneous fluency in operational technology protocols and machine learning operations, with qualified practitioners concentrated in Munich, Boston, and Shenzhen corridors.
- Legacy System Integration Friction:Brownfield manufacturing sites operate decades-old programmable logic controllers lacking standardized data interfaces, forcing expensive middleware development.
Strategic Opportunities
- India PLI Scheme for Manufacturing:Production-linked incentives for advanced chemical and electronics manufacturing create greenfield demand for integrated analytics platforms without legacy debt.
- Digital Twin Convergence:Physics-based simulation is converging with operational data streams to enable closed-loop optimization in semiconductor fabrication facilities.
- Outcome-Based Performance Contracts:Equipment vendors in aviation and energy verticals now guarantee availability metrics, transferring operational risk and embedding analytics as core service infrastructure.
Industry Challenges
- Model Drift Monitoring:Continuous validation requirements under FDA software-as-medical-device guidance demand dedicated machine learning operations teams that most industrial firms lack.
- Cross-Border Data Sovereignty:Analytics platforms processing sensor data across multiple jurisdictions face conflicting localization mandates from China's data security law and EU GDPR transfer mechanisms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Industrial Analytics Market |
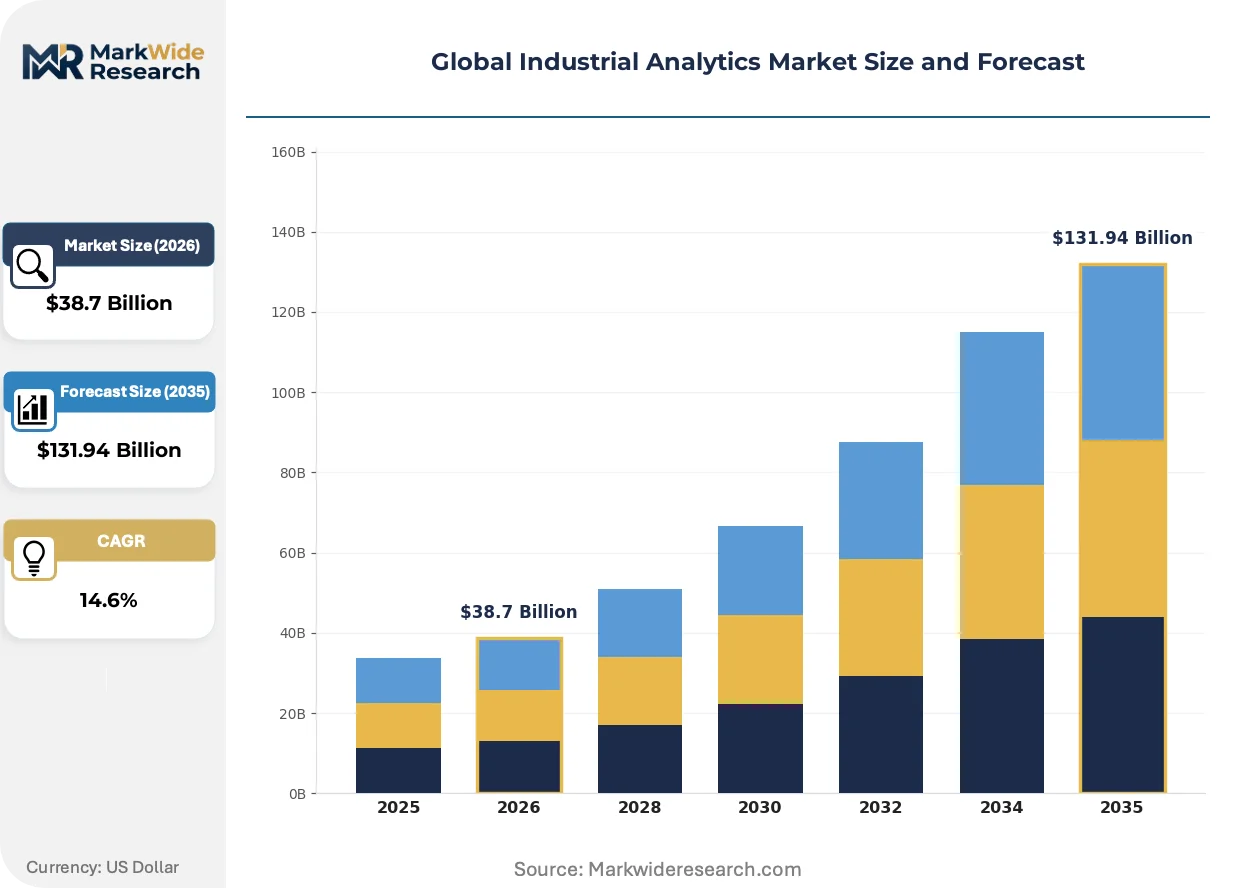
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $131.94 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Edge Computing Solution Offering: Predictive Maintenance, Process Optimization, Quality Management, Asset Performance Management, Energy Management Application: Manufacturing Optimization, Supply Chain Analysis, Equipment Monitoring, Safety Management, Production Scheduling End User: Manufacturers, Utilities Operators, Mining Companies, Oil & Gas Firms, Chemical Plants |
| Companies Covered | IBM Corporation, Microsoft Corporation, Siemens AG, General Electric Company, Cisco Systems, Robert Bosch GmbH, Oracle Corporation, Rockwell Automation, SAP SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Industrial Analytics Market Shifts & Advancements
Industrial analytics is undergoing platform architecture transformation as cloud-native deployment models absorb functions previously requiring on-premise infrastructure, while regulatory pressure forces visibility into algorithmic decision pathways that vendors historically treated as proprietary.
Digital twin technology is converging with real-time operational data streams to create persistent virtual replicas of physical assets. Chemical processing operators in the Netherlands and Belgium deploy these integrated systems to simulate catalyst degradation before physical inspection. The structural consequence is compressing maintenance windows from scheduled calendar intervals to condition-triggered interventions, eliminating unnecessary shutdowns.
The EU AI Act's high-risk system classification imposes mandatory conformity assessments on analytics platforms controlling batch release decisions in pharmaceutical manufacturing. Vendors must now document training data provenance and implement human oversight interfaces. German and Swiss contract manufacturers are responding by demanding ISO 27001-certified audit trails as standard procurement prerequisites.
Buyer organizations are consolidating vendor relationships around integrated platform ecosystems rather than point solutions for specific equipment types. This concentration favors hyperscaler-backed analytics suites over specialized industrial software in procurement evaluations. The shift is most visible in Japanese automotive supply chains, where tier-one suppliers now mandate Azure IoT or AWS IoT connectivity as a condition of supplier qualification.
Global Industrial Analytics Market Segmentation
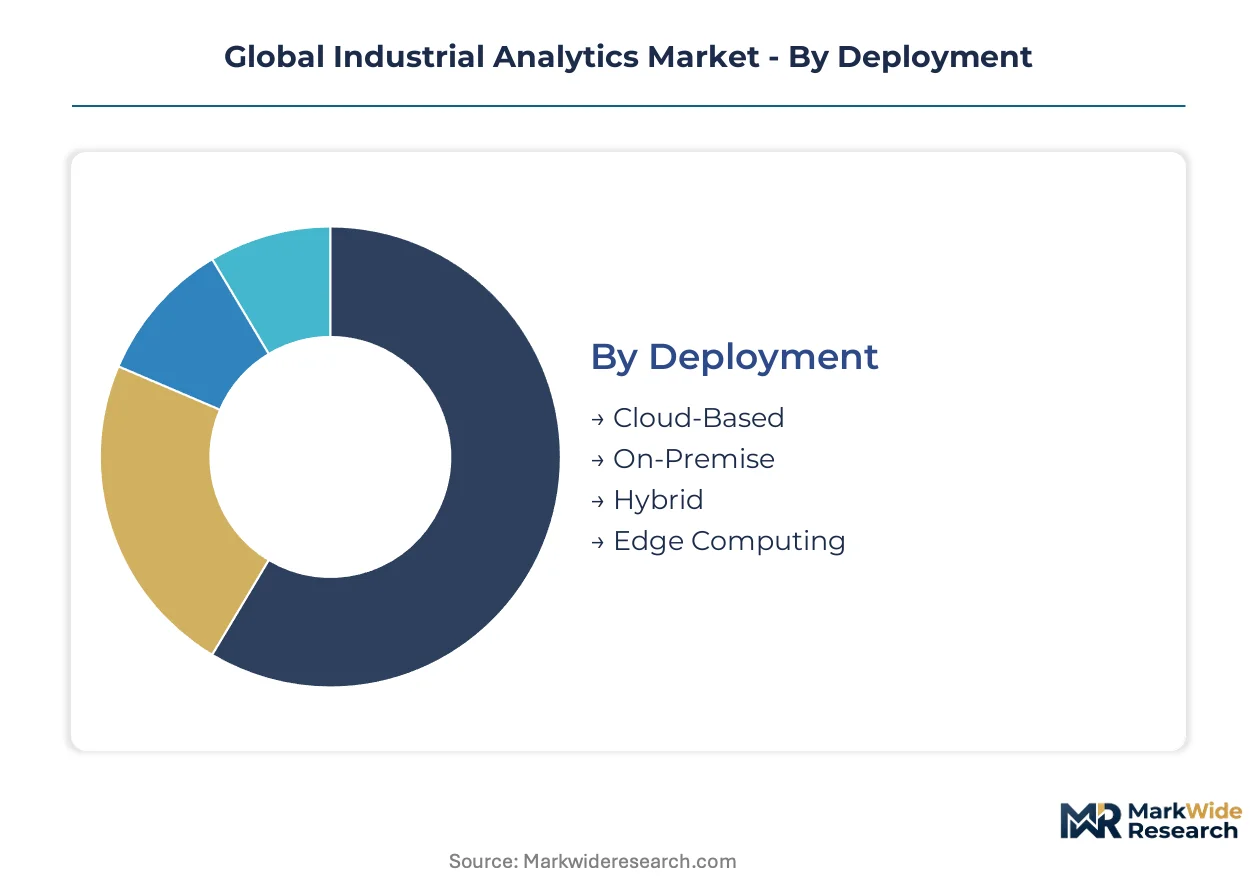
Industrial analytics platforms serve heterogeneous operational environments where deployment constraints, regulatory exposure, and asset criticality vary dramatically. Segmentation reveals how vendors architect pricing and capability tiers around these friction points.
Deployment:
Volume concentrates in cloud-native configurations while premium pricing attaches to latency-sensitive edge installations.
- Cloud-Based:Hyperscaler infrastructure delivers elastic compute for batch analytics and model training. Siemens AG and Microsoft Corporation anchor European manufacturing demand through Azure IoT integration with brownfield programmable logic controllers.
- Edge Computing:Sub-50 millisecond inference on vibration and thermal data streams requires localized GPU clusters. North Sea offshore turbine monitoring commands premium deployment economics due to satellite bandwidth constraints and failure cost exposure exceeding $1 million per day.
- On-Premise:Defense contractors and classified chemical processors retain air-gapped systems under ITAR and EU AI Act high-risk conformity protocols.
- Hybrid:Split architectures process sensitive telemetry locally while pushing aggregated insights to cloud training pipelines.
Today's leader: Cloud-Based. Tomorrow's challenger: Edge Computing.
Solution Offering:
Application maturity separates proven ROI categories from emerging capability investments.
- Predictive Maintenance:Algorithmic failure prediction for rotating equipment and electrical infrastructure commands the largest revenue pool. Oil and gas firms quantify returns through avoided catastrophic shutdowns in downstream refining and LNG liquefaction trains.
- Asset Performance Management:General Electric Company's Predix platform specializes in aviation engine and power generation fleet optimization, embedding physics-informed neural networks for remaining useful life estimation.
- Process Optimization:Real-time setpoint adjustment for throughput maximization in continuous chemical processing.
- Quality Management:Computer vision systems for defect detection in semiconductor wafer fabrication and automotive assembly.
- Energy Management:ISO 50001-certified platforms for utility demand response and industrial load balancing.
Predictive Maintenance captures current procurement budgets. Asset Performance Management is climbing the fastest as outcome-based contracting transfers operational risk to equipment vendors.
Application:
Functional scope determines integration complexity and incumbent vendor advantage.
- Equipment Monitoring:Sensor fusion for rotating machinery, transformers, and pressure vessels constitutes the foundational analytics use case with standardized data models.
- Manufacturing Optimization:Closed-loop control of throughput and yield in pharmaceutical batch processing requires FDA software-as-medical-device validation protocols.
- Supply Chain Analysis:Demand forecasting and inventory optimization extending beyond facility boundaries into supplier networks.
- Safety Management:Predictive models for process deviation and personnel hazard detection in high-consequence chemical and mining environments.
- Production Scheduling:Dynamic job shop optimization responding to real-time order mix changes and machine availability.
Equipment Monitoring dominates installed base. Manufacturing Optimization is expanding most quickly under EU AI Act pharmaceutical manufacturing compliance deadlines.
End User:
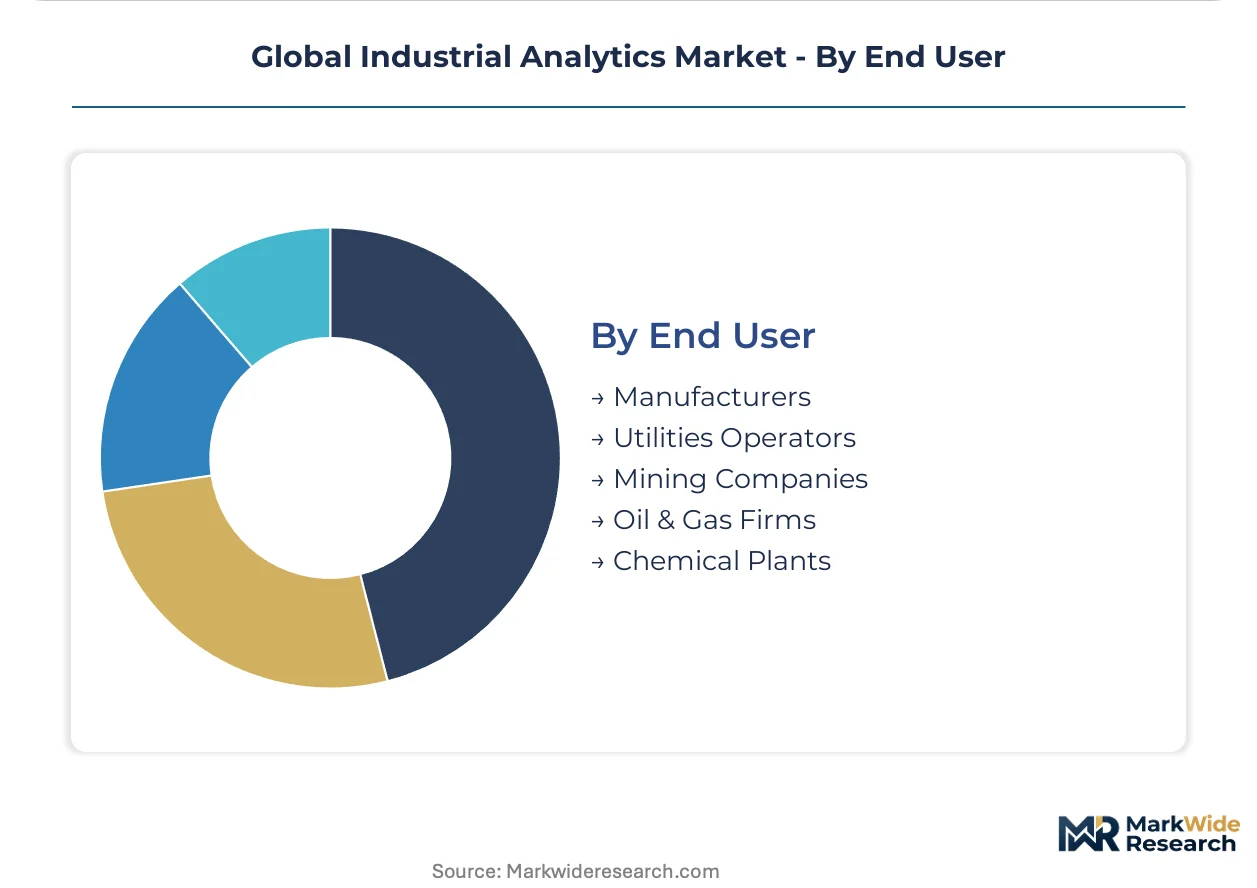
Asset intensity and downtime cost exposure stratify willingness-to-pay across verticals.
- Oil & Gas Firms:Upstream exploration and downstream refining operations deploy predictive maintenance for compressors, pumps, and heat exchangers where single-point failures cascade into multi-day outages.
- Utilities Operators:Combined-cycle gas turbine and renewable generation fleets require continuous analytics for grid stability compliance and renewable integration.
- Manufacturers:Automotive and electronics assembly lines prioritize quality management and production scheduling for just-in-time delivery commitments.
- Chemical Plants:Batch and continuous processing operators balance catalyst optimization against EU REACH and ECHA environmental reporting obligations.
- Mining Companies:Autonomous haul truck and processing plant analytics for remote operations with limited maintenance access.
Oil & Gas Firms anchor premium pricing. Utilities Operators represent the steepest expansion trajectory as renewable penetration destabilizes legacy dispatch economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping deployment patterns as pharmaceutical manufacturers migrate analytics infrastructure toward jurisdictions with clearer AI conformity pathways. The EU AI Act's high-risk system classification has compressed procurement timelines in Germany and Switzerland while creating compliance cost gaps with less regulated markets.
Germany
Automotive and chemical processing clusters in Bavaria and North Rhine-Westphalia drive demand for edge analytics platforms integrated with legacy programmable logic controllers. The EU AI Act mandates conformity assessments for batch release algorithms, compelling Siemens AG and Robert Bosch GmbH to certify audit trail capabilities. Munich anchors the deepest concentration of industrial data science talent, with Fraunhofer institutes bridging operational technology and machine learning operations gaps.
United States
Power generation utilities and oil and gas operators deploy predictive maintenance for combined-cycle gas turbines where unplanned downtime exceeds $1 million per day. The FDA's software-as-medical-device guidance extends validation requirements to pharmaceutical manufacturing analytics, creating procurement friction in New Jersey and Massachusetts biotech corridors. Houston's energy sector concentration commands premium pricing for offshore platform analytics subject to satellite bandwidth constraints.
China
Semiconductor fabrication facilities in the Yangtze River Delta integrate digital twin simulations with real-time operational data for closed-loop catalyst optimization. The country's data security law imposes localization mandates on cross-border sensor data flows, fragmenting analytics architectures for multinational chemical processors. Shenzhen's electronics manufacturing base concentrates demand for computer vision quality management systems in automotive supplier qualification programs.
India
Production-linked incentive schemes for advanced chemical and electronics manufacturing create greenfield demand without legacy programmable logic controller debt. The Bureau of Indian Standards is developing conformity frameworks for industrial AI systems, though implementation lags EU timelines by 18-24 months. Gujarat's petrochemical corridor and Karnataka's aerospace clusters represent the fastest-expanding deployment opportunities for integrated platform ecosystems.
Netherlands
Chemical processing operators in the Rotterdam-Antwerp port cluster deploy physics-informed neural networks for catalyst degradation prediction before physical inspection. REACH and ECHA environmental reporting obligations drive certified analytics platform procurement for emissions monitoring. The Randstad's concentration of contract research organizations accelerates FDA-aligned validation protocol development for pharmaceutical manufacturing analytics.
Global Industrial Analytics Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with hyperscaler-backed platform suites capturing procurement evaluations while industrial automation incumbents retain edge deployment advantages. The vendor base concentrates around three strategic archetypes: cloud-native analytics providers, operational technology heritage players with programmable logic controller integration depth, and equipment OEMs embedding analytics as outcome-based service infrastructure. Consolidation pressure is accelerating as buyer organizations mandate integrated platform ecosystems over point solutions. Technology licensing partnerships and regional edge node expansion constitute the dominant competitive moves.
Within the operational technology heritage tier, Siemens AG and Robert Bosch GmbH anchor European deployment of edge analytics for turbine monitoring and automotive manufacturing optimization. Microsoft Corporation exemplifies the cloud-native archetype through Azure IoT integration with manufacturing execution systems, while General Electric Company occupies a position in asset performance management specialization for aviation and energy verticals. These three companies represent the structural fault lines between automation heritage, hyperscaler infrastructure, and equipment OEM risk-transfer models.
| Leading Market Players |
|---|
| IBM Corporation |
| Microsoft Corporation |
| Siemens AG |
| General Electric Company |
| Cisco Systems |
| Robert Bosch GmbH |
| Oracle Corporation |
| Rockwell Automation |
| SAP SE |
| Others |
Supply & Pricing Matrix
Oil and gas supermajors concentrating procurement through outcome-based performance contracts anchor premium pricing for edge analytics platforms, while tier-two chemical processors drive subscription-tier compression through standardized cloud deployments.
Pricing Analysis
Distributor margins for industrial analytics platforms compress as hyperscalers Microsoft and AWS bypass channel partners for direct enterprise sales. Three-tier pricing structure across certified compliance-grade, standard enterprise, and basic monitoring tiers reflects EU AI Act conformity assessment costs. Pricing pressure stems from hyperscaler infrastructure commoditizing core compute layers. Tier-two automotive suppliers exhibit highest price sensitivity due to thin margins on supplier qualification programs.
Supply Chain Analysis
Dual-sourcing mandates from defense contractors and pharmaceutical manufacturers force edge hardware vendors to qualify secondary GPU suppliers beyond NVIDIA's dominant position. Advanced node semiconductor fabrication concentrates in Taiwan and South Korea, with memory components sourcing from Japan and USA. Supply chain risk centers on single-source vulnerability for AI accelerators subject to export control restrictions. Distribution runs through systems integrators with programmable logic controller integration expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial analytics vendors capture margin expansion through outcome-based contracting that transfers operational risk, while certification premiums for EU AI Act-compliant platforms widen pricing spreads.
For Market Incumbents: Anticipate hyperscaler encroachment by deepening programmable logic controller integration moats and pre-certifying edge analytics platforms for FDA software-as-medical-device pathways. Prioritize backward integration into sensor hardware to capture data-layer value. Defend against cloud-native entrants by embedding physics-informed models that require operational technology heritage to replicate. For New Entrants and Emerging Players: Enter via India's PLI-funded greenfield manufacturing corridors where legacy system integration debt is absent and procurement cycles remain open. Target pharmaceutical contract manufacturers in the Netherlands and Belgium facing compressed EU AI Act compliance deadlines. Lead with ISO 27001-certified audit trail capabilities as a differentiated procurement wedge. For Investors and Strategic Acquirers: Cloud hyperscalers are the most active acquirer in this space, seeking edge deployment capabilities to complete platform ecosystems. Long-term viability hinges on regulatory compliance automation rather than raw predictive accuracy. Monitor FDA software-as-medical-device enforcement intensity as the inflection signal for pharmaceutical manufacturing analytics valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Azure IoT connectivity mandates from Japanese automotive tier-one suppliers consolidate vendor relationships. |
| Acquisition of Specialist Firm | Hyperscalers acquire edge analytics hardware vendors to secure sub-50 millisecond inference capabilities. |
| Geographic Expansion | Regional edge node deployment in Germany's industrial corridor addresses EU data sovereignty requirements. |
| Strategic Partnership | Siemens partners with Fraunhofer institutes to bridge operational technology and machine learning operations gaps. |
| Product Launch | Physics-informed neural networks for remaining useful life estimation differentiate GE Predix in aviation verticals. |
Research Methodology
Coverage spans Germany, United States, China, India, and Netherlands, with primary inputs from each market. Primary interviews with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads combined with secondary validation from SEC filings, hyperscaler capex disclosures, and industrial automation trade data. Bottom-up deployment estimates triangulate against top-down vertical spending analysis.
Rate-of-change decomposition separates volume expansion from pricing tier shifts across the analysis window. Segmentation dimensions include deployment model, solution offering maturity, application functional scope, and end-user vertical intensity. CAGRs derive from regression against industrial capital expenditure cycles and regulatory compliance deadline clustering. Forecast inputs incorporate EU AI Act implementation timelines and FDA software-as-medical-device guidance enforcement patterns.
Inputs from hyperscaler infrastructure disclosures and industrial OEM earnings calls were available through the study window; gaps in private edge deployment metrics introduce uncertainty bands around installed base estimates. Deviation in EU AI Act conformity assessment timelines or export control restrictions on AI accelerators would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Retail Analytics Market
Analytics
United States Geospatial Analytics Market
Analytics
Europe HR Analytics Market
Analytics
Europe Speech Analytics Market
Analytics
Business Intelligence (BI) Market
Analytics
Asia-Pacific Mobile Analytics Market
Analytics
Extract, Transform, Load (ETL) Market
Analytics
Investigative Analytics Market
Analytics
Analytics Sandbox Market
Analytics
Patent Analytics Market
Analytics
Saudi Arabia Geospatial Analytics Market
Analytics
Cloud-Based Business Analytics Software Market
Analytics
Web Analytics Market
Analytics
Procurement Analytics Market
Analytics
Israel Geospatial Analytics Market
Analytics
Edge Analytics Market