
 MENA Wireless Routers Market | 2026-2036
MENA Wireless Routers Market Size, Share, and Industry Trends Forecast 2026-2036
MENA Wireless Routers Market Insights
Saudi Arabia's giga-project infrastructure rollout is reshaping enterprise router demand across the Gulf. Huawei Technologies Co., Ltd. anchors its position through deep integration with national broadband initiatives, while Cisco Systems, Inc. leverages channel partnerships with system integrators serving government verticals. TP-Link Technologies Co., Ltd. competes aggressively on price-performance ratios for residential and small enterprise segments across North African markets.
A wireless router functions as a network gateway device that forwards data packets between computer networks using radio frequency bands, typically operating at 2.4 GHz or 5 GHz with newer standards extending into 6 GHz spectrum. These devices execute network address translation, firewall functions, and quality-of-service prioritization to manage traffic across local area networks and wide area network uplinks. Mesh routers now command premium positioning as multi-node coverage solutions displace standalone units in large residential and commercial footprints across the MENA region. Wi-Fi 6 and Wi-Fi 6E connectivity standards are capturing replacement cycles as enterprise buyers prioritize orthogonal frequency-division multiple access for dense device environments. Gaming routers occupy a niche but defensible margin pool where specialized quality-of-service firmware attracts dedicated consumer segments in Gulf urban centers.
The UAE's Telecommunications and Digital Government Regulatory Authority and Saudi Arabia's Communications, Space and Technology Commission shape equipment certification timelines and spectrum allocation decisions that directly gate market entry. Egypt's National Telecom Regulatory Authority enforces type-approval protocols that filter non-compliant hardware from official distribution channels, reinforcing quality barriers. Stakeholders must monitor spectrum auction schedules and localization requirements as Gulf states tighten cybersecurity compliance for network infrastructure procurement.
Market Dynamics
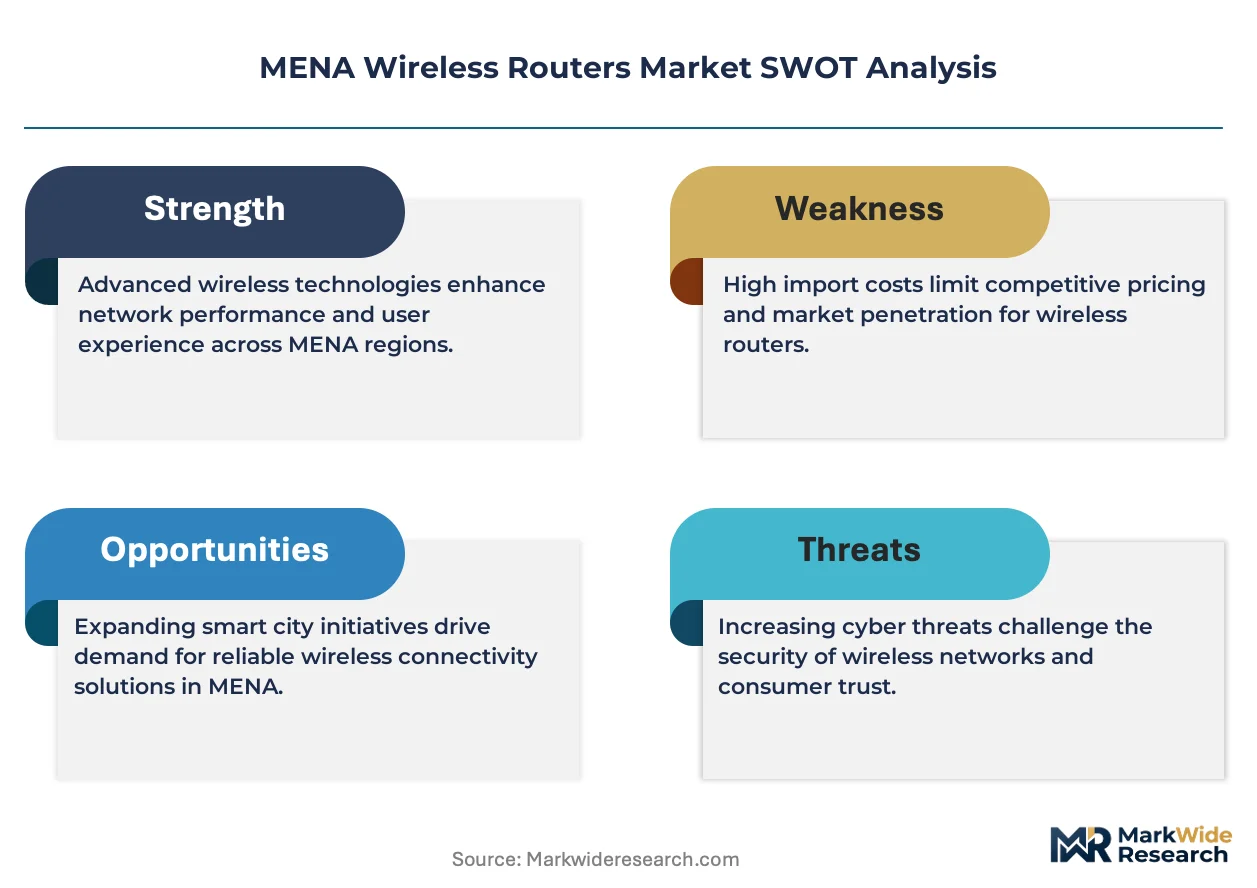
Wi-Fi 6E spectrum liberalization across Gulf Cooperation Council states is compressing hardware replacement cycles as enterprises race to deploy 6 GHz infrastructure before municipal smart city deadlines.
Growth Catalysts
- Saudi giga-project mandates:NEOM and Red Sea Project specifications require mesh-capable enterprise routers with sub-10 millisecond latency, pulling fiber-backhaul hardware into municipal procurement pipelines.
- TRAI-equivalent frameworks:UAE Telecommunications and Digital Government Regulatory Authority accelerated Wi-Fi 6E licensing in 2024, removing equipment certification bottlenecks that previously delayed enterprise deployments.
- Edge computing density:Data center corridors in Dubai's Jebel Ali Free Zone and Riyadh's King Salman Energy Park demand low-latency gateway hardware for distributed AI inference workloads.
Market Restraints
- Semiconductor input volatility:Router SoC and RF frontend component costs fluctuate with Taiwan foundry capacity allocation, compressing OEM margins on mid-tier enterprise units.
- Supply concentration risk:Sub-6 GHz power amplifier modules concentrate among three East Asian suppliers, exposing MENA distributors to allocation priority shifts during capacity crunches.
- Cybersecurity compliance friction:Saudi Arabia's Communications, Space and Technology Commission mandates hardware-level encryption certification that extends type-approval timelines by four to six months for non-domestic vendors.
Strategic Opportunities
- Egypt's underpenetrated SME segment:Cairo and Alexandria small enterprises still operate on 802.11n infrastructure, creating white space for Wi-Fi 6 migration programs bundled with ISP service contracts.
- Convergence of SD-WAN and wireless:Enterprise buyers in UAE logistics hubs seek unified appliances combining cellular failover, Wi-Fi 6E, and software-defined policy management in single hardware units.
- MOHAP healthcare digitization:UAE Ministry of Health and Prevention mandates for connected medical device networks create specialized demand for isolated guest-network routers in hospital campuses.
Industry Challenges
- Embedded systems firmware expertise gap:MENA system integrators lack sufficient OpenWrt and proprietary SDK engineers to customize QoS policies for vertical-specific deployments.
- Multi-standard certification complexity:Simultaneous Wi-Fi Alliance, GCC regulatory, and national cybersecurity approvals for a single SKU extend time-to-revenue by eight to twelve months.
- Legacy 2.4 GHz dependency:Industrial IoT sensor networks across Saudi Aramco facilities still require backward-compatible 802.11b/g support, fragmenting firmware development resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MENA Wireless Routers Market |
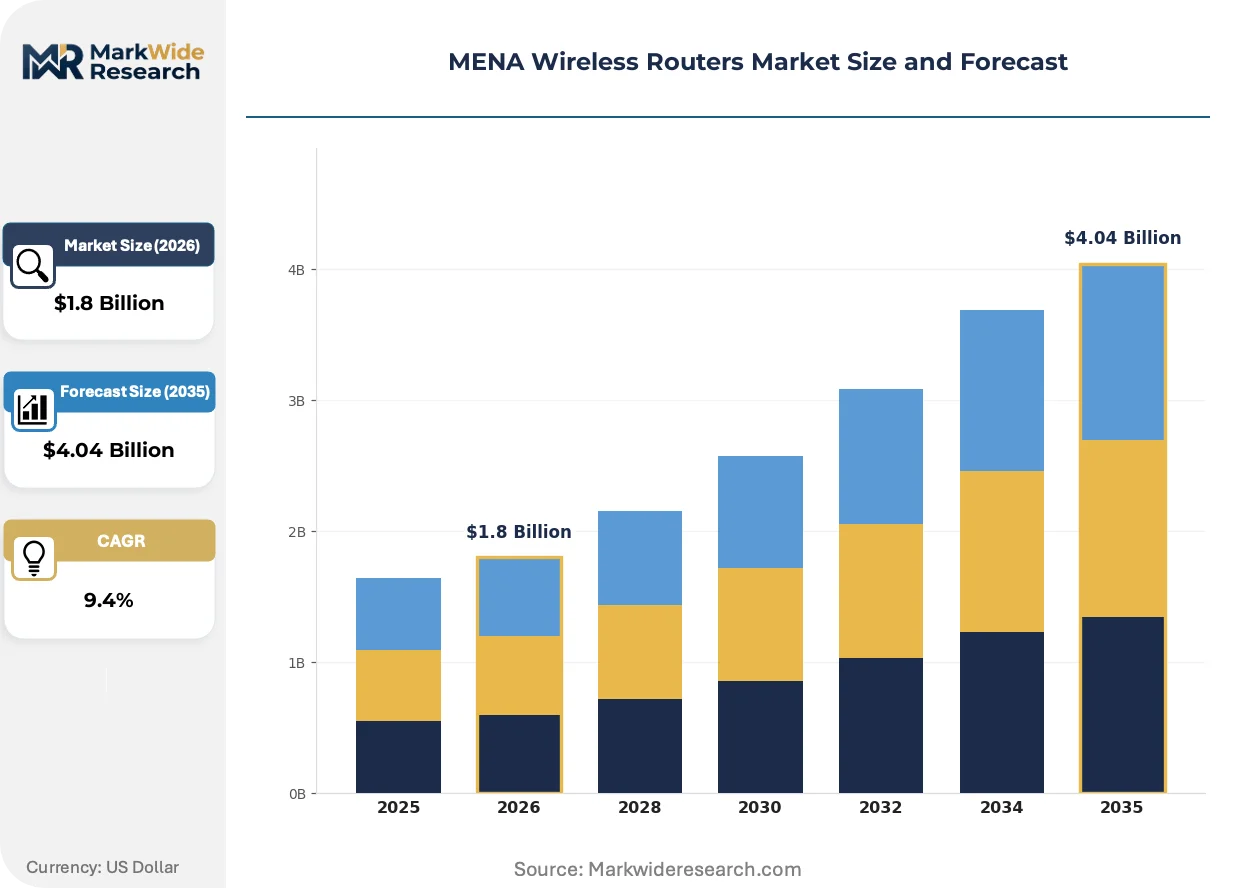
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Routers, Mesh Routers, Mobile Hotspots, Gaming Routers Connectivity Standard: Wi-Fi 5, Wi-Fi 6, Wi-Fi 6E, LTE End User: Residential Users, Small Enterprises, Large Corporations, Public Institutions Distribution Channel: Online Retail, Offline Retail, Direct Sales, System Integrators |
| Companies Covered | ASUSTeK Computer Inc., Huawei Technologies Co., Ltd., D-Link Systems, Nokia Corporation, Cisco Systems, Inc., TP-Link Technologies Co., Ltd., NETGEAR, Inc., Hewlett Packard Enterprise, Dell Technologies, Others |
| Regions Covered | MENA: Saudi Arabia, UAE, Qatar, Kuwait, Egypt, Morocco, Algeria, Tunisia, Rest of MENA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MENA Wireless Routers Market Trends and Innovations
Radio access network disaggregation is rewriting procurement specifications as enterprises seek software-programmable hardware that decouples physical layer functions from vendor-locked management platforms.
Network function virtualization is virtualizing router architectures across MENA enterprise deployments. Open RAN-inspired firmware stacks now run on commodity ARM-based hardware, allowing Saudi telecom operators to substitute proprietary control planes with containerized third-party software. Large hospitality chains in Dubai are virtualizing guest network management, collapsing CapEx per property by eliminating standalone controller appliances.
UAE Telecommunications and Digital Government Regulatory Authority spectrum harmonization with European Conference of Postal and Telecommunications Administrations frameworks is eliminating regional hardware SKU fragmentation. Equipment vendors now certify single 6 GHz SKUs for simultaneous UAE and EU deployment, compressing inventory carrying costs for distributors serving both markets. Enterprise buyers in Abu Dhabi free zones benefit from faster access to globally current chipsets previously gated by regional certification delays.
Hardware-as-a-service contracting is displacing outright purchase in Kuwaiti and Qatari government verticals. Ministries of education now lease router infrastructure with bundled lifecycle management, transferring firmware update liability to vendor operators. This procurement pivot favors vendors with local spare-part depots and 24-hour swap capabilities, penalizing direct-ship models from distant manufacturing bases.
MENA Wireless Routers Market Segmentation
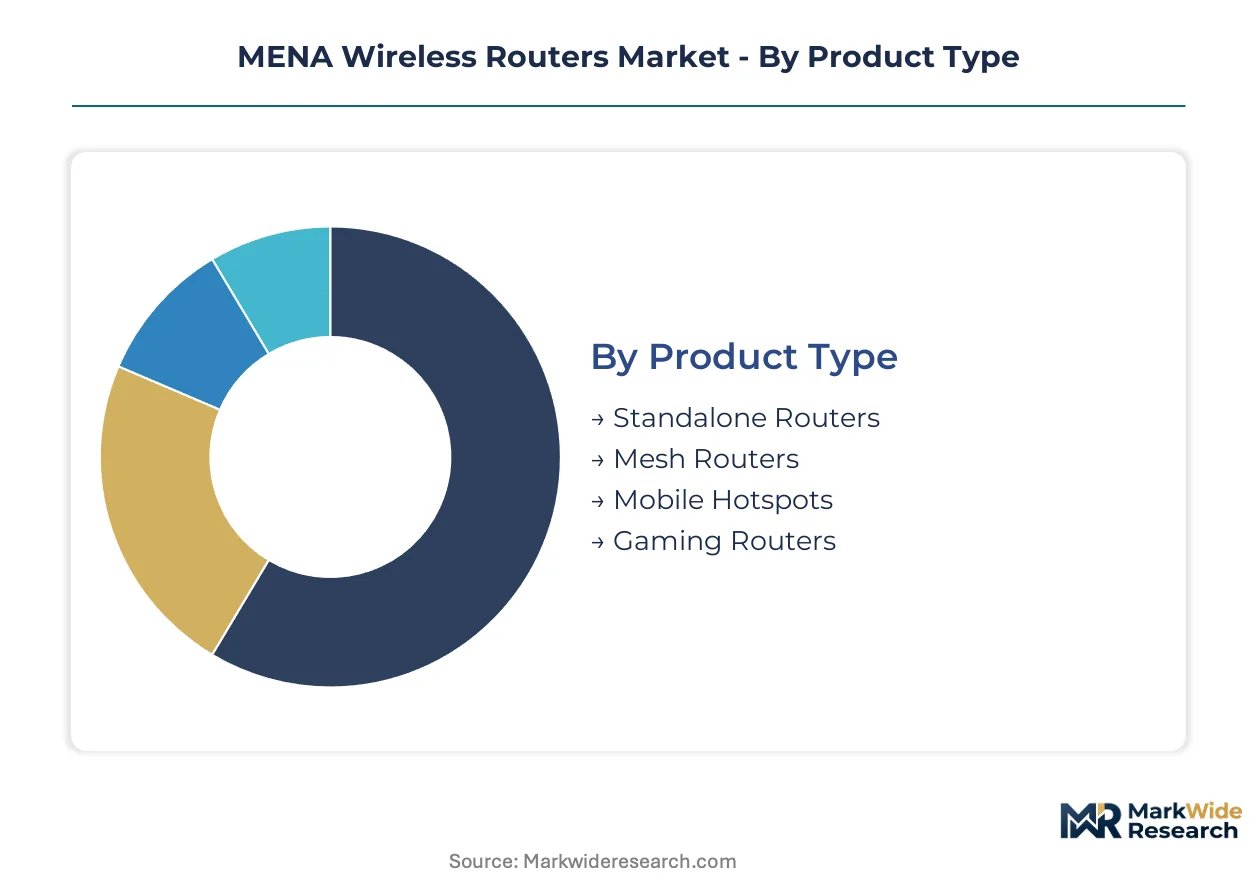
Wireless router procurement patterns across the MENA region diverge sharply by deployment scale, spectrum requirements, and buyer sophistication. Understanding these segment boundaries clarifies why enterprise buyers prioritize 6 GHz infrastructure while residential demand concentrates on price-optimized mesh systems.
Product Type:
The use-case spectrum spans single-unit residential coverage to campus-wide enterprise mesh architectures with centralized policy management.
- Standalone Routers:Single-unit devices with integrated antennas serving 50-100 concurrent connections through dual-band or tri-band configurations. Demand concentrates in Egypt's residential segment and Saudi Arabia's legacy small enterprise installations where fiber-to-the-home penetration remains uneven and cost sensitivity dominates procurement decisions.
- Mesh Routers:Multi-node systems with dedicated backhaul channels enabling seamless roaming across 10,000+ square meter footprints. NEOM and Red Sea Project specifications mandate sub-10 millisecond handoff latency, pulling premium mesh hardware into municipal procurement pipelines across Saudi Arabia's giga-project developments.
- Mobile Hotspots:Battery-powered cellular-to-WiFi gateways for field deployment and temporary connectivity.
- Gaming Routers:Specialized hardware with QoS firmware prioritizing UDP packet streams for competitive multiplayer environments.
The dominant share belongs to Standalone Routers, while Mesh Routers is closing the gap fastest.
Connectivity Standard:
Cost tier stratification separates premium 6 GHz deployments from legacy infrastructure serving price-sensitive segments.
- Wi-Fi 5:802.11ac standard operating exclusively on 5 GHz with 80 MHz channel bonding and MU-MIMO support. Cairo and Alexandria small enterprises still rely on this infrastructure, creating replacement white space as ISPs bundle Wi-Fi 6 migration with service contract renewals.
- Wi-Fi 6:802.11ax with OFDMA scheduling and 1024-QAM modulation for dense device environments. UAE logistics free zones in Jebel Ali prioritize this standard for warehouse IoT sensor networks where 2.4 GHz backward compatibility remains mandatory.
- Wi-Fi 6E:Extended 6 GHz spectrum access with 160 MHz contiguous channels and reduced interference profiles.
- LTE:Cellular fallback connectivity for remote sites lacking fiber backhaul.
Wi-Fi 5 retains installed-base dominance, though Wi-Fi 6E is climbing the fastest as Gulf Cooperation Council spectrum liberalization accelerates hardware refresh cycles.
End User:
Application intensity varies from consumer streaming bandwidth to industrial IoT latency requirements and healthcare network isolation mandates.
- Residential Users:Households with 15-50 connected devices requiring parental controls and guest network segmentation. Demand clusters in Saudi Arabia's urban centers and UAE expatriate communities where multi-device streaming and smart home integration drive replacement cycles.
- Small Enterprises:Businesses with 10-100 employees needing VPN termination and basic traffic prioritization. Egypt's underpenetrated SME segment presents expansion opportunity as bundled ISP offerings displace unmanaged consumer hardware.
- Large Corporations:Multi-site enterprises with SD-WAN integration requirements and centralized policy orchestration.
- Public Institutions:Government and education networks with cybersecurity certification mandates and lifecycle management contracts.
Residential Users command volume leadership, while Large Corporations is gaining share fastest through smart city infrastructure build-outs.
Distribution Channel:
Customer type and procurement sophistication determine whether buyers self-serve through retail or engage specialized integration partners.
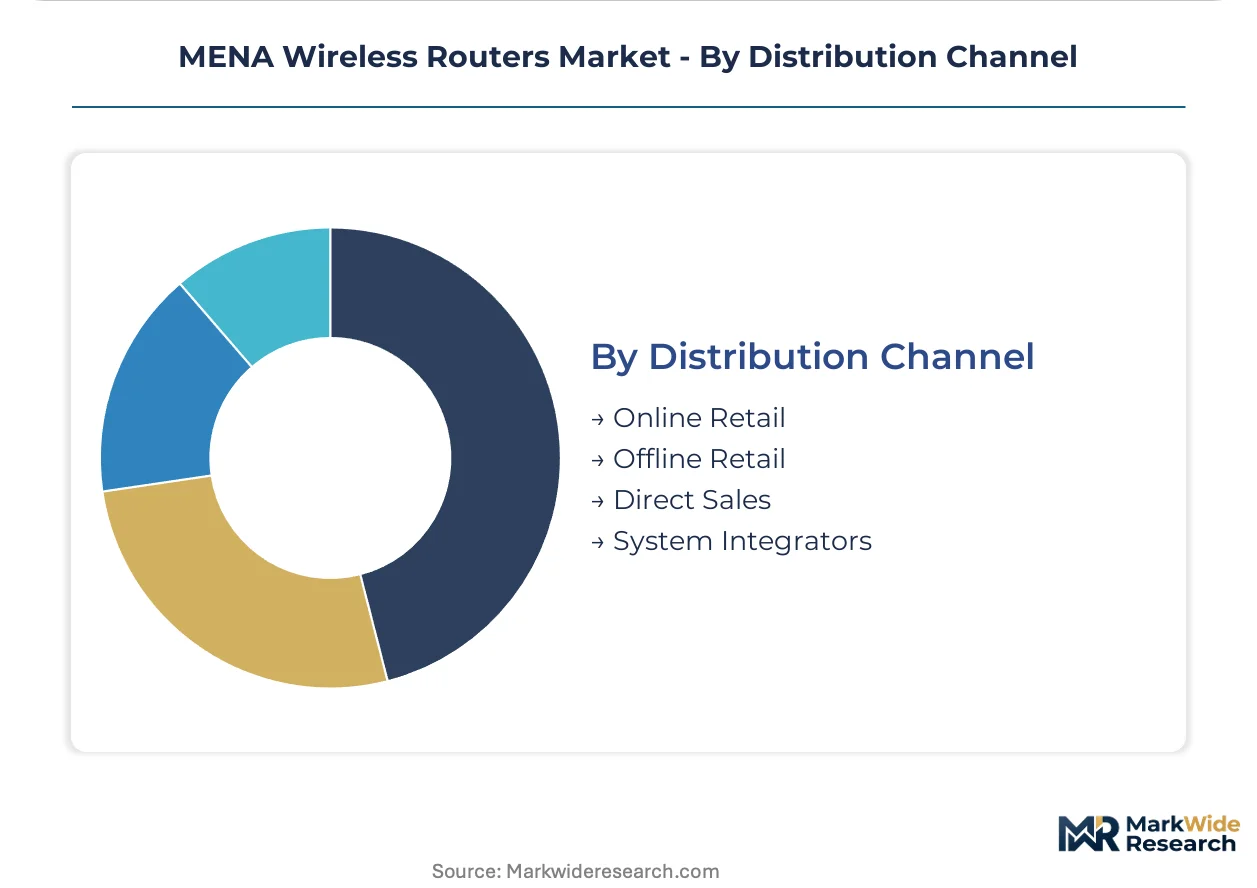
- Online Retail:E-commerce platforms serving tech-savvy consumers and price-comparison buyers. North African markets show channel concentration here as traditional electronics retail infrastructure remains fragmented.
- Offline Retail:Brick-and-mortar electronics chains with immediate fulfillment and installation support.
- Direct Sales:Vendor-to-enterprise relationships for large-scale deployments with custom firmware requirements.
- System Integrators:Channel partners bundling hardware with network design, deployment, and managed services. Kuwaiti and Qatari government verticals increasingly route procurement through this channel as hardware-as-a-service contracts transfer lifecycle liability to vendor operators.
Offline Retail maintains the largest share, though System Integrators is expanding most quickly through government vertical procurement pivots.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The King Abdulaziz Port expansion in Dammam underwrites Saudi Arabia's dominance in regional router procurement, while the Jebel Ali Port free zone in Dubai anchors UAE logistics-driven demand for low-latency edge hardware.
Saudi Arabia
NEOM and Red Sea Project smart city mandates are pulling enterprise-grade mesh routers into municipal procurement pipelines. The Communications, Space and Technology Commission enforces hardware-level encryption certification that extends type-approval timelines for non-domestic vendors. Riyadh's King Salman Energy Park data center corridor concentrates demand for sub-10 millisecond latency gateway hardware.
United Arab Emirates
Dubai's Jebel Ali Free Zone logistics hubs prioritize Wi-Fi 6E infrastructure for warehouse IoT sensor networks requiring 2.4 GHz backward compatibility. The Telecommunications and Digital Government Regulatory Authority accelerated spectrum licensing in 2024, removing equipment certification bottlenecks. Abu Dhabi free zones now access globally current chipsets previously gated by regional certification delays.
Egypt
Cairo and Alexandria small enterprises still operate on 802.11n infrastructure, creating white space for Wi-Fi 6 migration programs bundled with ISP service contracts. The National Telecom Regulatory Authority enforces type-approval protocols that filter non-compliant hardware from official distribution channels. New Cairo's technology corridor is emerging as a concentration point for enterprise network upgrades.
Qatar
Ministries of education are pivoting to hardware-as-a-service router contracts with bundled lifecycle management. The national communications regulator shapes equipment certification timelines that gate market entry for non-domestic vendors. Doha's Education City cluster is deploying mesh-capable infrastructure for connected campus environments.
Kuwait
Government verticals are transferring firmware update liability to vendor operators through leasing arrangements. The national telecom regulator mandates cybersecurity compliance for network infrastructure procurement that favors vendors with local spare-part depots. Kuwait City's smart government initiatives are driving centralized policy orchestration requirements.
MENA Wireless Routers Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying RF modules and power amplifiers to finished goods assemblers. The vendor base stratifies across three tiers: multinational network infrastructure conglomerates with government certification expertise, regional system integrators bundling hardware with managed services, and price-optimized consumer electronics manufacturers serving residential segments. Strategic moves concentrate on spectrum certification pre-positioning ahead of Gulf Cooperation Council licensing shifts, and channel partnerships with ministries of education for hardware-as-a-service contracts.
Among Asia-Pacific-based network equipment manufacturers, Huawei Technologies Co., Ltd. and TP-Link Technologies Co., Ltd. exemplify divergent positioning archetypes. Huawei Technologies Co., Ltd. anchors the government-vertical tier through deep integration with national broadband initiatives and smart city procurement pipelines. TP-Link Technologies Co., Ltd. occupies the price-performance tier, competing aggressively on cost-optimized specifications for residential and small enterprise segments across North African markets. Cisco Systems, Inc. represents the Western multinational archetype, leveraging channel partnerships with system integrators serving government verticals across Gulf Cooperation Council states. These three players collectively illustrate how certification timelines, localization requirements, and procurement modality shifts are reshaping competitive positioning across the MENA region.
| Leading Market Players |
|---|
| ASUSTeK Computer Inc. |
| Huawei Technologies Co., Ltd. |
| D-Link Systems |
| Nokia Corporation |
| Cisco Systems, Inc. |
| TP-Link Technologies Co., Ltd. |
| NETGEAR, Inc. |
| Hewlett Packard Enterprise |
| Dell Technologies |
| Others |
Pricing and Supply Chain Analysis
Taiwan foundry capacity allocation volatility determines both the spread between enterprise and residential pricing tiers and the geographic configuration of component sourcing across the MENA router market. OEM margins compress when RF frontend module costs spike, forcing distributors to prioritize allocation toward government-certified SKUs with longer contract horizons.
Pricing Analysis
Volume-discount tiering structures separate municipal procurement pipelines from residential retail channels across the MENA region. Three-tier pricing stratification across premium mesh systems, standard enterprise units, and economy standalone devices reflects certification grade and after-sales service bundling. Pricing pressure stems from semiconductor input volatility compressing margins on mid-tier enterprise hardware. Government verticals in Saudi Arabia and Qatar exhibit lowest price sensitivity due to hardware-as-a-service contracting, while Egypt's residential segment remains acutely cost-conscious.
Supply Chain Analysis
Export-control regime restrictions on advanced semiconductor manufacturing equipment limit foundry capacity expansion in Taiwan and South Korea, constraining router SoC availability for MENA distributors. Component sourcing draws from Taiwan for silicon fabrication, China for PCB assembly, and Vietnam for final system integration. Single-source vulnerability concentrates in sub-6 GHz power amplifier modules from three East Asian suppliers. Distribution runs through Dubai's Jebel Ali Free Zone logistics hubs for Gulf Cooperation Council markets and Cairo for North African corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The MENA wireless router market functions as a service-attach opportunity where lifecycle management contracts and firmware subscription layers expand faster than underlying hardware shipments. Hardware-as-a-service procurement pivots in Kuwaiti and Qatari government verticals demonstrate this recurring-revenue acceleration.
For Market Incumbents: Harden certification positioning ahead of Gulf Cooperation Council spectrum harmonization deadlines. Pre-position Wi-Fi 6E SKUs through the UAE Telecommunications and Digital Government Regulatory Authority fast-track pathway before Saudi Arabia's Communications, Space and Technology Commission extends hardware-level encryption mandates. Anchor spare-part depots in Riyadh and Dubai to defend against emerging system integrators offering 24-hour swap guarantees.
For New Entrants and Emerging Players: Build out ISP bundling partnerships in Egypt's underpenetrated SME segment where 802.11n infrastructure still dominates Cairo and Alexandria. Target hardware-as-a-service contracts in Qatar's Ministry of Education vertical where procurement liability shifts to vendor operators. Establish OpenWrt firmware customization capabilities to differentiate from incumbent locked-platform offerings.
For Investors and Strategic Acquirers: The market sits at a certification-window phase that favors vendors with pre-approved spectrum portfolios and localized spare-part infrastructure. Five-to-ten year viability hinges on capturing recurring lifecycle management revenue streams rather than transactional hardware margins. Monitor Saudi giga-project procurement pipeline announcements as the primary inflection signal for enterprise mesh demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Spectrum Certification Pre-Positioning | UAE TDRA harmonization with CEPT frameworks eliminates SKU fragmentation for simultaneous Gulf-EU deployment. |
| Hardware-as-a-Service Contracting | Kuwaiti government leasing arrangements transfer firmware update liability to vendor operators with local depots. |
| Firmware Virtualization Investment | Saudi telecom operators deploy containerized Open RAN stacks on commodity ARM hardware, collapsing proprietary control plane margins. |
| System Integrator Channel Partnership | Qatari education ministries route procurement through bundled managed service providers, excluding direct-ship vendors. |
| Edge Computing Gateway Development | Dubai's Jebel Ali Free Zone logistics hubs demand unified appliances combining cellular failover with SD-WAN policy management. |
Research Methodology
A spread of perspectives from network equipment procurement officers at Gulf Cooperation Council ministries, system integrators serving Saudi giga-project developments, ISP technical directors in Egypt, and distributor inventory managers in Dubai converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against customs trade data, equipment certification filings with the UAE TDRA and Saudi CST, hyperscaler capex disclosures, and router SoC foundry capacity reports. Bottom-up demand modeling from enterprise deployment pipelines and top-down market sizing from distributor shipment aggregates were triangulated to constrain variance.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, connectivity standard tier, end-user scale, and distribution channel sophistication. CAGRs were derived from logistic diffusion curves fitted to replacement cycle data and spectrum licensing schedules. Industry-specific forecast inputs incorporated NEOM and Red Sea Project procurement timelines alongside Egypt ISP bundling contract renewal patterns.
Stress conditions across Taiwan foundry allocation priority shifts, Gulf Cooperation Council cybersecurity compliance timeline extensions, and Egyptian pound volatility were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding spectrum liberalization schedules and smart city infrastructure commitment durability. Material shifts in Saudi giga-project funding velocity or UAE hardware-as-a-service procurement penetration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Global 5G Smart Antenna Market
Network Technology
United States and European Fiber Optic Cable Market
Network Technology
Global Industrial Ethernet Switch Market
Network Technology
Small Cell Networks Market
Network Technology
Global Private 5G Network Market
Network Technology
Global Routing Market
Network Technology
Managed Switches Market
Network Technology
Structured Cabling Market
Network Technology
Home Wi-Fi Router and Extender Market
Network Technology
Malaysia Wireless Router Market
Network Technology
Residential Routers Market
Network Technology
DHCP and IP Address Management Market
Network Technology
Network Telemetry Market
Network Technology
5G Enterprise Private Network Market
Network Technology
US Private 5G Network Market
Network Technology
Philippines Software-Defined Wide Area Network (SD-WAN) Market