
 BYOD Market | 2026-2036
BYOD Market Size, Share, and Industry Trends Forecast 2026-2036
BYOD Market Analysis
The EU AI Act is recalibrating enterprise mobility strategies across Europe by mandating stricter data governance for AI-enabled applications on personal devices. VMware leverages virtualization-layer security to sustain its position in regulated European deployments. BlackBerry Limited anchors its competitive stance through specialized endpoint management for government and defense contractors.
Bring Your Own Device refers to organizational policies permitting employees to use personally owned smartphones, tablets, laptops, and wearables for work purposes, typically enforced through mobile device management platforms with containerized data separation and encryption protocols. The primary commercial purpose is reducing capital expenditure on corporate hardware while maintaining application access and data security boundaries. Smartphones dominate device type adoption due to universal employee ownership and mature management tooling, while wearables represent the fastest-growing category as industrial augmented reality applications expand. Healthcare leads industry vertical penetration given clinical workflow demands for constant connectivity, though finance commands premium security spending per seat.
The US Federal Trade Commission and the Securities and Exchange Commission enforce data breach disclosure rules that directly shape BYOD policy stringency for publicly traded firms. The EU GDPR and the EU AI Act collectively mandate audit trails and automated decision-making transparency that containerization architectures must accommodate. Stakeholders should monitor how NIST cybersecurity framework revisions redefine baseline controls for unmanaged endpoints.
Market Dynamics
Containerization architectures are displacing traditional mobile device management as the primary enforcement mechanism for data separation on employee-owned hardware, driven by GDPR audit-trail mandates and the EU AI Act's automated decision-making transparency requirements.
Growth Catalysts
- GDPR Compliance Mandates:European enterprises are accelerating managed containerization deployments to satisfy automated decision-making transparency and data portability requirements for AI-enabled applications on personal devices.
- Mittelstand Digitization:Germany's mid-sized manufacturing base is expanding field operations connectivity, creating concentrated demand for ruggedized wearable BYOD programs in industrial augmented reality workflows.
- Zero Trust Architecture:Federal agencies and defense contractors are mandating continuous verification protocols that privilege virtualization-layer security over perimeter-based mobile device management approaches.
Market Restraints
- Silicon Supply Concentration:Taiwan-based foundry dominance in secure enclave chip production creates geopolitical exposure for hardware-backed encryption in enterprise mobility stacks.
- Certificate Authority Fragmentation:Inconsistent mutual recognition agreements between national digital identity frameworks complicate cross-border device attestation for multinational deployments.
- Legacy Application Compatibility:Containerized work profiles cannot accommodate on-premise ERP systems lacking API modernization, forcing parallel device fleets in regulated industries.
Strategic Opportunities
- Industrial Wearables Convergence:Integration of augmented reality headsets with computer vision and haptic feedback is opening field service and remote assistance applications in energy and utilities verticals.
- India Manufacturing Incentives:PLI scheme subsidies for electronics assembly are attracting device OEMs to establish local secure supply chains for government and defense BYOD programs.
- Outcome-Based Security Pricing:Cyber insurance carriers are piloting premium adjustments tied to continuous endpoint compliance metrics, creating channel partnerships for managed mobility providers.
Industry Challenges
- Forensic Readiness Gap:Incident response teams lack standardized protocols for extracting evidentiary data from containerized work profiles without compromising personal privacy boundaries.
- Certificate Lifecycle Management:Shortened validity periods for device identity credentials are overwhelming IT operations teams lacking automated renewal infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | BYOD Market |
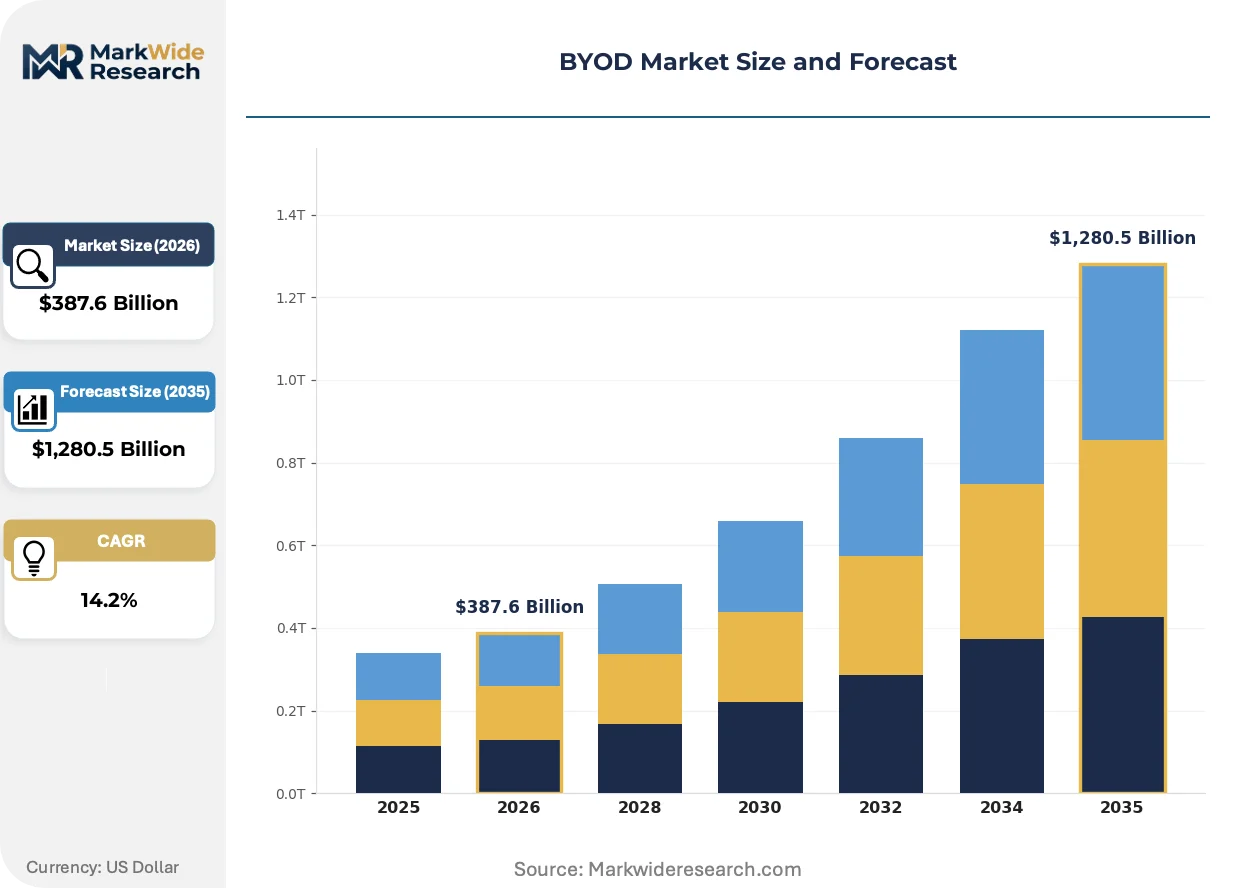
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $1,280.5 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Strict Compliance, Flexible Usage, Minimal Oversight, Collaborative Management Device Type: Smartphones, Tablets, Laptops, Wearables Industry Vertical: Healthcare, Education, Finance, Retail Security Approach: Encryption, Remote Wipe, VPN Access, Multi-Factor Authentication |
| Companies Covered | VMware Inc., Citrix Systems Inc., IBM Corporation, Ivanti Inc., Cisco Systems Inc., SAP SE, BlackBerry Limited, Hewlett Packard Enterprise Company, Oracle Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
BYOD Market Emerging Trajectories
Enterprise mobility stacks are fragmenting into composable security services that decouple policy enforcement from device management consoles, enabling procurement teams to source point solutions for specific compliance domains.
Confidential computing is modularizing hardware-based isolation for sensitive workloads on unmanaged endpoints. Financial services firms are piloting memory-encrypted processing for trading applications on employee-owned laptops, compressing the traditional boundary between corporate device security and personal hardware flexibility. This architecture enables banks to satisfy SEC data breach disclosure rules without mandating hardware standardization.
The EU AI Act is recalibrating audit requirements for machine learning inference on mobile devices. Containerization vendors must now implement automated decision-logging and explainability interfaces that travel with AI models across personal and corporate data boundaries. Healthcare providers in France and Germany are prioritizing solutions that satisfy both GDPR portability mandates and ANSM clinical algorithm validation protocols.
Subscription-based endpoint security is displacing perpetual licensing in mid-market procurement. Channel partners are bundling device management, threat detection, and compliance reporting into seat-based packages that align with finance team preference for operational expenditure treatment. This shift is most visible in UK professional services firms restructuring IT budgets around flexible workforce scaling.
BYOD Market Segmentation
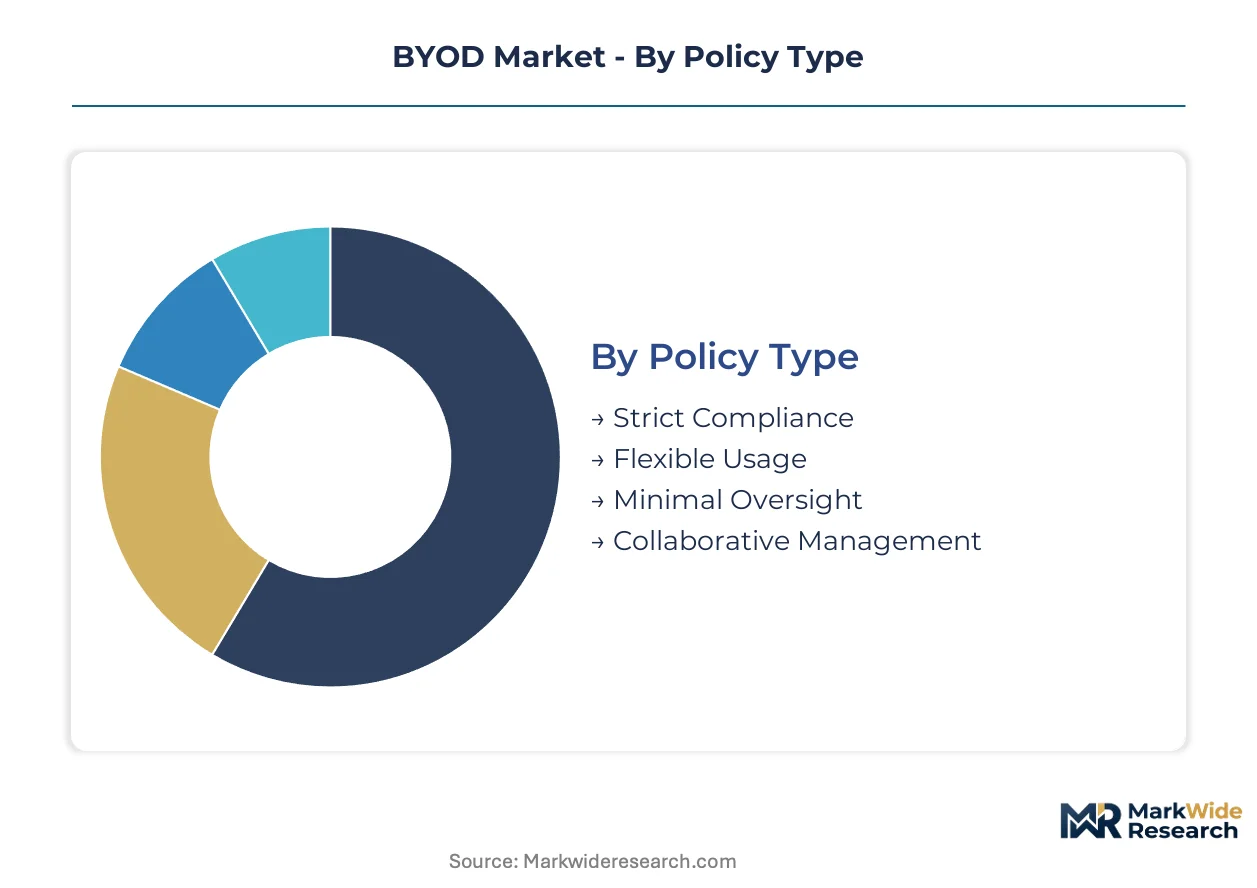
BYOD market segmentation reveals how enterprise mobility strategies fragment across regulatory intensity, hardware diversity, and security architecture choices. Each dimension carries distinct procurement patterns and vendor qualification requirements.
Policy Type:
Standardization dominates at the extremes while hybrid models capture the mid-market.
- Strict Compliance:Mandatory containerization with hardware-backed attestation and continuous monitoring. Financial services firms in Frankfurt and Singapore deploy these frameworks to satisfy SEC disclosure rules and MAS technology risk management guidelines.
- Flexible Usage:Tiered access controls permitting personal applications alongside encrypted work profiles. German Mittelstand manufacturers favor this approach for field engineer tablets where productivity tooling must coexist with personal communications.
- Minimal Oversight:Basic email and calendar access through browser-based portals without device-level agents. Early-stage professional services firms in London and Sydney use this to avoid MDM licensing costs.
- Collaborative Management:Shared governance between IT and employee representatives defining acceptable use boundaries. French healthcare networks negotiate these terms with clinical staff unions under CNIL consultation requirements.
Most installed capacity flows through Flexible Usage. Expansion is steepest in Strict Compliance.
Device Type:
Volume concentration sits with universally owned hardware while specialized form factors command premium security spending.
- Smartphones:Universal employee ownership and mature management tooling make these the default BYOD endpoint. German automotive suppliers standardize on ruggedized Android deployments for plant floor supervisors requiring instant escalation protocols.
- Wearables:Industrial augmented reality headsets with computer vision and haptic feedback integration. Energy utilities in Texas and Alberta pilot these for remote expert assistance in hazardous environment inspections.
- Tablets:Clinical workflow documentation and field service manuals drive healthcare and utilities adoption.
- Laptops:Confidential computing pilots for memory-encrypted trading applications distinguish financial services deployments.
Smartphones absorb the majority of seat licenses. Wearables are climbing the fastest as industrial AR applications mature.
Industry Vertical:
Regulatory intensity and workforce mobility requirements create divergent security spending per endpoint.
- Healthcare:Clinical workflow demands for constant connectivity plus HIPAA and GDPR patient data obligations. French hospital networks prioritize ANSM-validated algorithms for AI-enabled diagnostic tools on personal devices.
- Finance:SEC disclosure rules and EU AI Act audit mandates drive premium containerization spending. Investment banks pilot confidential computing for trading workstations.
- Education:Privacy constraints around student data limit monitoring scope, favoring browser-isolation over device agents.
- Retail:Seasonal workforce scaling favors operational expenditure treatment through subscription endpoint packages.
Healthcare maintains the largest installed base. Finance shows the steepest security spending growth per seat.
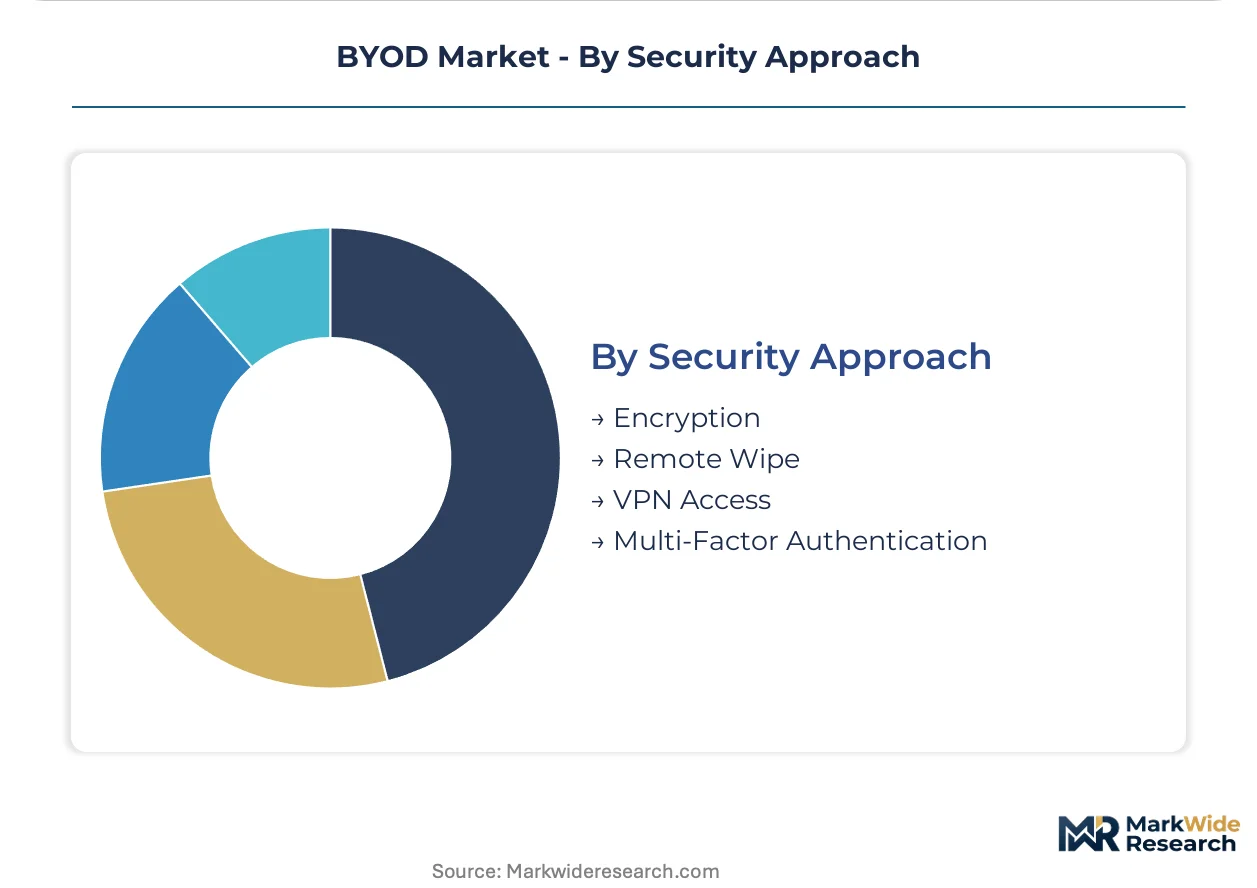
Security Approach:
Defense-in-depth layering versus point-solution procurement reflects organizational cybersecurity maturity.
- Multi-Factor Authentication:Phishing-resistant hardware keys and biometric verification anchor zero trust architectures. US federal agencies mandate FIDO2 compliance for contractor device access under NIST framework revisions.
- Encryption:Hardware-backed full-disk and file-level encryption satisfying GDPR data-at-rest requirements. German automotive suppliers specify secure enclave chip provenance to mitigate Taiwan foundry concentration risk.
- Remote Wipe:Selective container erasure preserving personal data boundaries during incident response.
- VPN Access:Split-tunnel configurations reducing latency for cloud-native applications while maintaining corporate resource protection.
Encryption underpins every deployment. Multi-Factor Authentication is gaining share fastest as phishing campaigns intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise mobility policies first scaled in North American financial centers during the 2010s smartphone proliferation, then migrated to European manufacturing hubs confronting GDPR compliance deadlines. Geographic dispersion now reflects regulatory intensity rather than technology adoption curves.
United States
SEC disclosure rules and FTC data breach enforcement shape stringent containerization requirements for publicly traded firms. Federal agencies mandate FIDO2-compliant zero trust architectures under NIST cybersecurity framework revisions. New York investment banks pilot confidential computing for trader-owned laptops.
Germany
Mittelstand manufacturers digitize field operations through ruggedized wearable BYOD programs for industrial augmented reality workflows. GDPR audit-trail mandates accelerate managed containerization deployments satisfying automated decision-making transparency requirements. Bavarian automotive suppliers specify secure enclave chip provenance to mitigate supply chain concentration risks.
United Kingdom
Professional services firms restructure IT budgets around subscription endpoint packages aligning with finance team preference for operational expenditure treatment. UK regulators emphasize continuous endpoint compliance metrics for cyber insurance premium adjustments. London-based consultancies bundle device management with threat detection services.
France
Healthcare networks negotiate collaborative governance terms with clinical staff unions under CNIL consultation requirements. ANSM clinical algorithm validation protocols intersect with GDPR portability mandates for AI-enabled diagnostic tools on personal devices. Paris hospital clusters prioritize solutions satisfying both regulatory frameworks.
India
PLI scheme subsidies for electronics assembly attract device OEMs establishing local secure supply chains for government and defense BYOD programs. RBI technology risk guidelines shape financial sector containerization requirements. Bangalore IT services firms expand managed mobility offerings for multinational clients.
BYOD Market Vendor Landscape
Capital-heavy infrastructure vendors compete with asset-light software specialists across the enterprise mobility stack. Market structure fragments across virtualization-layer security providers, endpoint management platforms, and integrated enterprise software suites. Three archetypes dominate: legacy enterprise software vendors extending mobility modules, specialized endpoint security pure-plays, and cloud-native containerization specialists. Competitive intensity concentrates on strategic partnerships with cyber insurance carriers and vertical-specific compliance certifications.
Within the legacy enterprise tier, VMware Inc. and Citrix Systems Inc. occupy positions anchored in virtualization-layer security for regulated deployments. BlackBerry Limited exemplifies the specialized endpoint security archetype through government and defense contractor focus. IBM Corporation sits within the integrated software suite category, representing broader enterprise IT consolidation strategies that incorporate mobility management.
| Leading Market Players |
|---|
| VMware Inc. |
| Citrix Systems Inc. |
| IBM Corporation |
| Ivanti Inc. |
| Cisco Systems Inc. |
| SAP SE |
| BlackBerry Limited |
| Hewlett Packard Enterprise Company |
| Oracle Corporation |
| Others |
Supply Flow & Price Mechanics
Containerization architecture migration from traditional mobile device management is compressing deployment costs while redistributing value capture toward virtualization-layer security providers. Taiwan-based secure enclave chip production concentration simultaneously elevates hardware-backed encryption premiums and exposes procurement teams to geopolitical pricing volatility.
Pricing Analysis
Subscription-based seat licensing dominates enterprise mobility procurement, with three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on compliance certification depth and vertical-specific algorithm validation, with healthcare and finance segments absorbing premium tiers for ANSM and SEC-aligned audit capabilities. Cost compression in mid-market containerization is intensifying because channel partners bundle threat detection and compliance reporting into operational expenditure packages. Early-stage professional services firms exhibit highest price sensitivity, while Frankfurt investment banks demonstrate lowest elasticity due to regulatory mandate rigidity.
Supply Chain Analysis
Freight cost escalation for specialized semiconductor components is amplifying total cost of ownership for ruggedized wearable deployments in German field operations. Hardware supply concentrates in Taiwan, South Korea, and China for secure enclave chips, memory modules, and AR headset optical components. Component dependencies span secure processors, encrypted storage controllers, and computer vision sensors. Single-source vulnerability in Taiwan foundry capacity creates procurement contingency planning overhead. Distribution runs through OEM-direct enterprise contracts and regional systems integrators serving Mittelstand manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
BYOD market expansion represents a geographic-arbitrage play where India's PLI scheme subsidies for electronics assembly undercut European hardware procurement costs by 15-25 percent for equivalent security specifications.
For Market Incumbents: Deploy confidential computing partnerships to defend against cloud-native containerization specialists encroaching on financial services accounts. VMware and Citrix must accelerate hardware-backed memory encryption pilots for trader-owned laptops before BlackBerry Limited extends its government contractor positioning into commercial banking. Channel control through cyber insurance carrier partnerships offers defensive moat construction against outcome-based pricing insurgents. For New Entrants and Emerging Players: Capture French healthcare network contracts by prioritizing CNIL-compliant collaborative governance frameworks that incumbent mobility suites lack. Industrial wearables for energy utilities in Texas and Alberta present most penetrable white-space, with remote expert assistance workflows underserved by smartphone-centric legacy platforms. ANSM-validated algorithm explainability interfaces offer differentiated go-to-market positioning against generic containerization vendors. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-market subscription endpoint providers lacking vertical-specific compliance certifications. Long-term viability across the analysis window hinges on EU AI Act audit-trail capability integration rather than device management commoditization. PLI scheme beneficiary OEMs establishing Indian secure supply chains signal inflection toward geographic diversification premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Confidential Computing Pilot Expansion | Memory-encrypted processing for SEC-compliant trading applications on personal laptops compresses hardware standardization requirements. |
| Cyber Insurance Carrier Partnership | Outcome-based premium adjustments tied to continuous endpoint compliance metrics create channel lock-in for managed mobility providers. |
| PLI Scheme Manufacturing Localization | Indian electronics assembly subsidies attract device OEMs establishing secure supply chains for government and defense programs. |
| ANSM-Validated Algorithm Integration | Clinical decision-logging interfaces satisfy both GDPR portability mandates and French medical device validation protocols. |
| Zero Trust Architecture Certification | FIDO2-compliant continuous verification protocols meet NIST framework revisions for federal contractor device access. |
Methodological Framework
Direct dialogue with CISOs at financial services firms, IT procurement officers in German Mittelstand manufacturers, clinical informatics directors at French hospital networks, and channel partners for endpoint security platforms grounded qualitative findings. Secondary validation drew from SEC 10-K cybersecurity disclosures, EMA GDPR enforcement actions, ANSM clinical algorithm validation registers, and NIST cybersecurity framework revision drafts. Bottom-up deployment sizing across policy types, device categories, and security approaches triangulated against top-down enterprise mobility spending estimates from hyperscaler capex disclosures and IT services firm revenue breakdowns.
Market size outputs and growth trajectories across the analysis window reflect segment-level modeling of containerization penetration rates, wearable AR adoption curves, and compliance-driven replacement cycles. Segmentation dimensions spanned policy type, device form factor, industry vertical, and security architecture tier. CAGRs were derived from regression-weighted technology diffusion curves and regulatory mandate implementation timelines. Forecast inputs incorporated EU AI Act audit-trail deployment deadlines and PLI scheme capacity buildout schedules.
Geopolitical escalation in Taiwan semiconductor access, accelerated NIST framework revision adoption, and cyber insurance carrier pricing model standardization are the dominant revision risks to modeled outcomes. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Network Management Systems (NMS) Market
Network Technology
Global Network Monitoring Market
Network Technology
Cloud Managed Access Points Market
Network Technology
Mobile Network Optimization Market
Network Technology
IT Connector Market
Network Technology
Mobile Backhaul Market
Network Technology
Global Carrier Wi-Fi Equipment Market
Network Technology
US Private LTE and 5G Network Market
Network Technology
Network Performance Monitoring Market
Network Technology
Lit Fiber Market
Network Technology
Small Cell Networks Market
Network Technology
Global Internet Transit Market
Network Technology
Wi-Fi 6E Router Market
Network Technology
Global Deep Packet Inspection and Processing Market
Network Technology
Home Wi-Fi Router and Extender Market
Network Technology
Global Wi-Fi Range Extender Market