
 North America Network Management Solutions Market | 2026-2036
North America Network Management Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
North America Network Management Solutions Market Insights
Modular subscription bundling is realigning how enterprises evaluate network management procurement in North America. Cisco Systems leverages its extensive channel partner ecosystem to sustain dominance across enterprise campus deployments. Hewlett Packard Enterprise anchors its position through integrated Aruba networking portfolios that unify wired and wireless management under single-pane dashboards. Juniper Networks differentiates via AI-native operations platforms that automate anomaly detection across multivendor environments.
Network management solutions encompass software platforms, hardware appliances, and cloud services that monitor, configure, and optimize data traffic across enterprise infrastructure using protocols such as SNMP, NetFlow, and streaming telemetry. These systems serve the commercial purpose of ensuring uptime, enforcing security policies, and enabling capacity planning across distributed IT estates. Cloud-based product configurations lead current adoption curves as organizations prioritize OpEx flexibility over perpetual license models. The telecommunications industry vertical commands substantial investment share due to 5G backhaul complexity and service-level agreement enforcement requirements. Edge computing deployment models represent the fastest-expanding segment as manufacturing and healthcare facilities process latency-sensitive workloads closer to source devices.
The Federal Communications Commission governs spectrum allocation and network reliability standards that shape telecommunications provider investment in monitoring infrastructure across the United States. Health Insurance Portability and Accountability Act security rules mandate audit logging and access controls that drive healthcare sector demand for compliant network visibility tools. NIST cybersecurity frameworks further influence product development roadmaps for vendors serving federal contractors and critical infrastructure operators. Stakeholders must weigh the trade-offs between cloud-native agility and data sovereignty requirements as provincial privacy statutes in Canada and state-level regulations in California introduce compliance fragmentation across the regional footprint.
Market Dynamics
Cloud-native telemetry architectures are compressing refresh cycles across enterprise network estates, forcing incumbent vendors to rearchitect licensing models around consumption-based metering rather than perpetual seat counts.
Growth Catalysts
- HIPAA Security Rule mandates:Healthcare providers in the United States must maintain audit logs and access controls on all network touchpoints handling protected health information, creating procurement pull for compliant visibility platforms.
- 5G backhaul complexity:Telecommunications carriers require granular traffic engineering to enforce service-level agreements across radio access network fronthaul and midhaul segments.
- Edge computing deployment:Manufacturing facilities and healthcare clinics process latency-sensitive workloads closer to source devices, demanding localized network orchestration tools.
Market Restraints
- Specialized engineering talent scarcity:Shortages of professionals certified in AI-native operations platforms and streaming telemetry protocols constrain deployment velocity.
- Hybrid infrastructure complexity:Organizations maintaining parallel on-premises and cloud-managed environments face integration friction and duplicated tooling costs.
- Semiconductor supply concentration:Network appliance manufacturers depend on concentrated foundry capacity in East Asia for specialized packet processing silicon.
Strategic Opportunities
- Mid-market enterprise expansion:Texas and California mid-market firms seek scalable infrastructure without capital-intensive hardware refresh cycles, favoring subscription-based consumption models.
- AI-native anomaly detection:Convergence of machine learning inference engines with streaming telemetry enables predictive fault isolation across multivendor environments.
- Canadian provincial privacy fragmentation:Quebec's Bill 64 and British Columbia's data residency requirements create demand for sovereign cloud network management instances.
Industry Challenges
- Multivendor integration complexity:Enterprises struggle to normalize telemetry formats across legacy SNMP-based devices and modern streaming telemetry endpoints.
- Certification timeline compression:Federal contractors must achieve NIST cybersecurity framework compliance on accelerated schedules to maintain eligibility for critical infrastructure awards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Network Management Solutions Market |
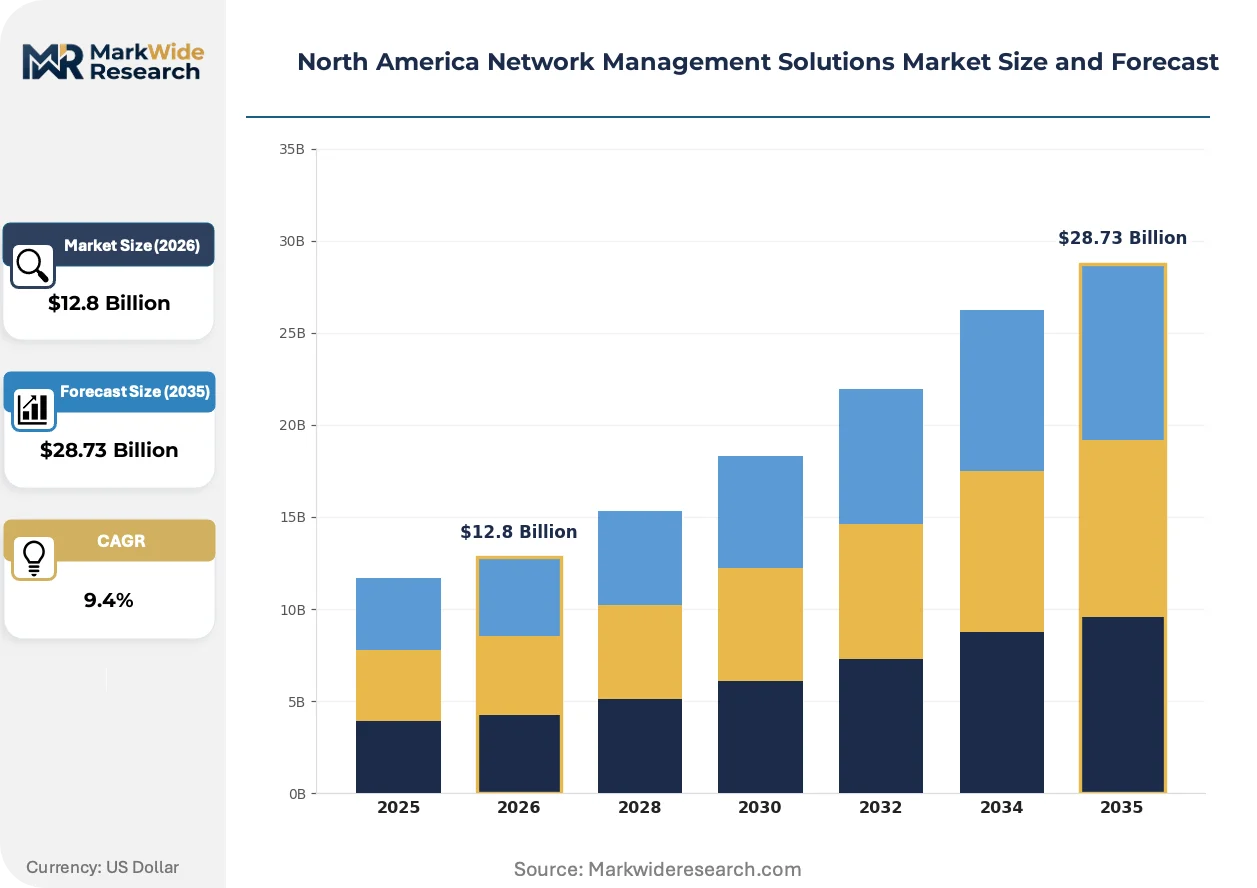
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $28.73 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premise, Hybrid, Software-Defined Service Type: Consulting, Installation, Maintenance, Support Deployment Model: Public Cloud, Private Cloud, Multi-Cloud, Edge Computing Industry Vertical: Telecommunications, Healthcare, Education, Manufacturing |
| Companies Covered | Cisco Systems, Hewlett Packard Enterprise, IBM, Juniper Networks, SolarWinds, NETSCOUT, Extreme Networks, CA Technologies, VIAVI Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Network Management Solutions Market Trends and Innovations
Intent-based networking and autonomous operations are redefining how infrastructure teams interact with distributed estates, shifting human roles from configuration execution to policy validation and exception handling.
Streaming telemetry is modularizing how network devices expose operational state, replacing periodic SNMP polling with continuous structured data feeds. Large enterprises and cloud service providers are adopting gRPC-based telemetry subscriptions to feed real-time analytics pipelines. This architectural shift is modularizing the boundary between data collection and analysis layers, enabling third-party tool integration without vendor lock-in.
FCC network reliability standards are tightening uptime obligations for telecommunications providers serving rural broadband deployments. Carriers must demonstrate redundant path diversity and sub-50ms failover capabilities to maintain spectrum license eligibility. Rural cooperative networks in the Mountain West and Great Plains regions are accelerating investment in redundant fiber backhaul to satisfy these reliability benchmarks.
Enterprise buyers are consolidating vendor relationships around integrated wired-wireless platforms, reducing the number of management dashboards operations teams must monitor. Mid-market enterprises in particular are abandoning best-of-breed point solutions in favor of unified campus fabric architectures. This consolidation pattern is most visible among healthcare systems in the Southeastern United States seeking to simplify HIPAA compliance audits across unified infrastructure estates.
North America Network Management Solutions Market Segmentation
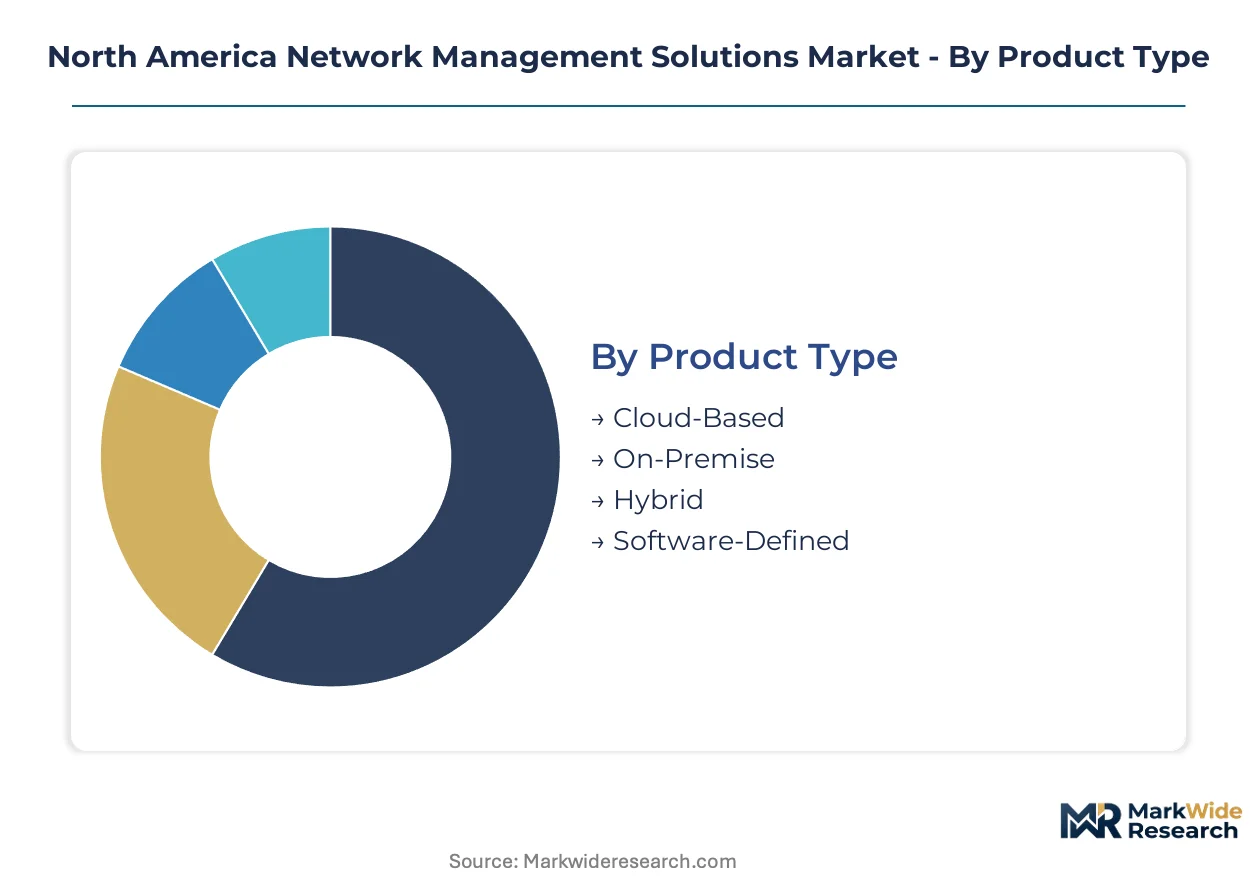
Network management procurement patterns diverge sharply across deployment architectures and compliance burdens. HIPAA-mandated healthcare networks, FCC-regulated telecommunications infrastructure, and NIST-framework federal contractors each impose distinct certification requirements that reshape vendor selection criteria.
Product Type:
HIPAA Security Rule audit logging requirements apply most stringently to cloud-based and hybrid configurations handling protected health information, while on-premise deployments face lighter direct oversight but heavier NIST cybersecurity framework obligations for federal contractors.
- Cloud-Based:Subscription-metered platforms deliver centralized telemetry aggregation without capital-intensive appliance procurement. Texas and California mid-market enterprises concentrate procurement here, driven by OpEx flexibility mandates and rapid scaling requirements for distributed workforces.
- On-Premise:Perpetual-license hardware appliances maintain data sovereignty for organizations with strict residency requirements. Canadian provincial privacy fragmentation—particularly Quebec's Bill 64—sustains demand for sovereign instances in Montreal and Toronto data centers.
- Hybrid:Split-control architectures normalize telemetry across cloud-managed and locally administered segments.
- Software-Defined:Controller-based abstraction layers automate policy propagation across multivendor underlays.
Cloud-Based sits at the top of the volume ranking, with Hybrid climbing the fastest as organizations reconcile agility mandates with sovereignty constraints.
Service Type:
Cost tier stratification separates premium consulting engagements from standardized maintenance contracts, with installation services capturing mid-tier spend as organizations navigate multivendor integration complexity.
- Consulting:Architecture design and compliance roadmap engagements command premium pricing. Healthcare systems in the Southeastern United States drive concentration here, requiring HIPAA-aligned network segmentation strategies ahead of audit cycles.
- Installation:Physical deployment and initial configuration services anchor mid-market procurement. Manufacturing facilities adopting edge computing models in the Great Lakes region generate sustained demand for localized rack-and-stack expertise.
- Maintenance:Reactive break-fix and preventive hardware replacement contracts.
- Support:Tiered response-time guarantees for technical escalation and patch management.
Support commands the largest contract volume, with Consulting expanding most quickly as compliance timelines compress.
Deployment Model:
Application latency requirements determine deployment selection, with edge computing addressing sub-10ms manufacturing workloads and multi-cloud configurations serving resilience-critical telecommunications backhaul.
- Edge Computing:Localized orchestration platforms process telemetry at manufacturing plant floors and healthcare clinics. Rural broadband cooperatives in the Mountain West accelerate investment here to satisfy FCC sub-50ms failover mandates.
- Multi-Cloud:Federated control planes normalize policy across AWS, Azure, and Google Cloud instances. Telecommunications carriers leverage this architecture for 5G backhaul redundancy across geographically dispersed points of presence.
- Public Cloud:Shared-tenant infrastructure with metered consumption billing.
- Private Cloud:Dedicated single-tenant environments with custom hardware profiles.
Public Cloud retains volume leadership, though Edge Computing gains share fastest as latency-sensitive workloads proliferate.
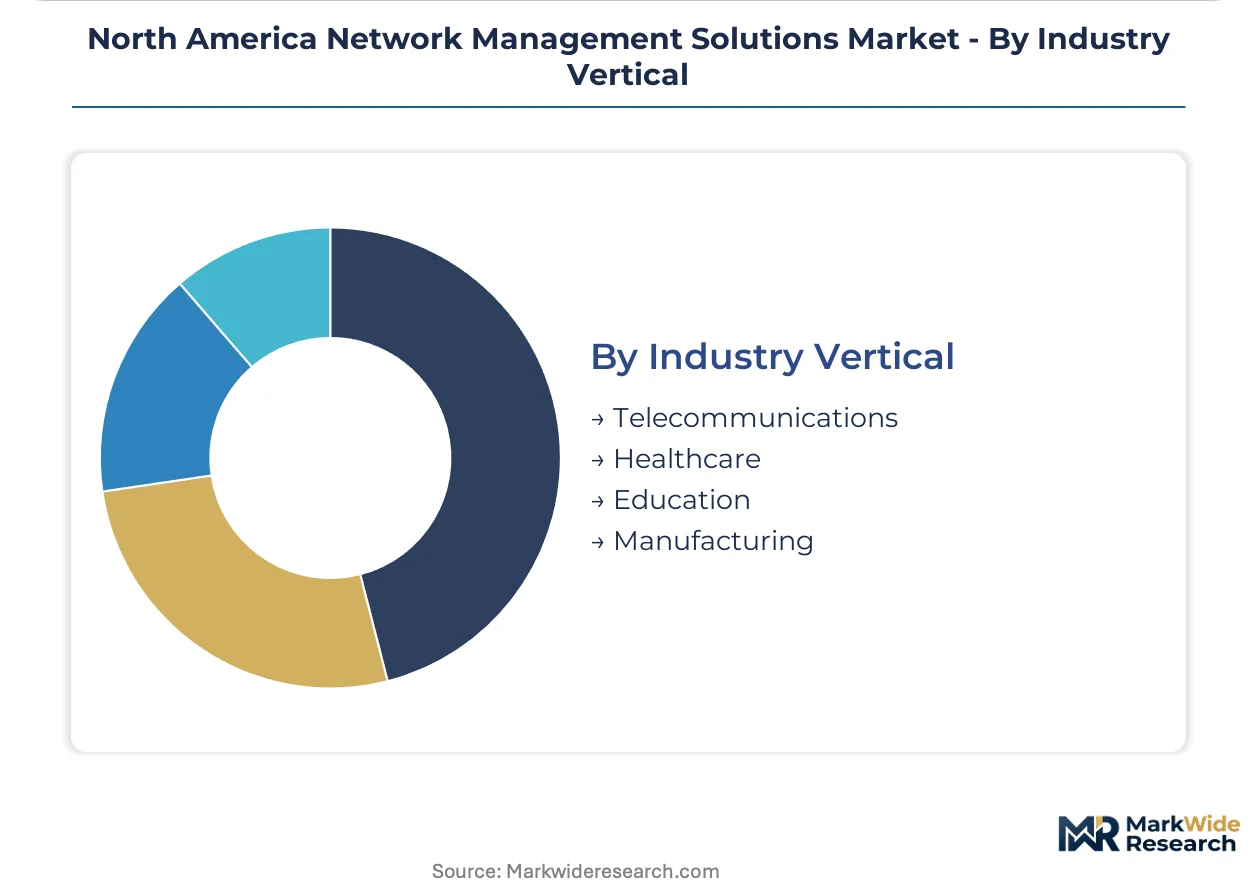
Industry Vertical:
Customer type differentiation separates regulated entities with mandatory audit trails from discretionary adopters, with healthcare and telecommunications facing the heaviest compliance-driven procurement specifications.
- Telecommunications:Granular traffic engineering platforms enforce service-level agreements across radio access network segments. FCC network reliability standards tighten uptime obligations, compelling redundant path diversity investments for rural spectrum license retention.
- Healthcare:Audit logging and access control platforms secure patient data flows under HIPAA mandates. United States health systems expand procurement most aggressively in Texas and California, where patient volume growth intersects with stringent enforcement timelines.
- Education:Campus-wide visibility tools manage bring-your-own-device proliferation and guest network segmentation.
- Manufacturing:Industrial protocol gateways bridge operational technology and information technology network domains.
Telecommunications leads by installed base value, with Healthcare posting the steepest expansion trajectory as breach notification penalties escalate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North American network management industry traces its commercial roots to the early internet infrastructure buildout of the 1990s, when Silicon Valley and Boston-area technology clusters pioneered enterprise routing and monitoring protocols. This historical foundation established the region's enduring concentration of vendor headquarters, systems integrators, and early-adopter enterprise buyers.
United States
Healthcare systems in Texas and California drive concentrated procurement of HIPAA-compliant visibility platforms as patient data volumes surge. FCC network reliability standards compel telecommunications carriers to demonstrate redundant path diversity and sub-50ms failover capabilities. The Southeastern United States anchors unified campus fabric adoption, with health systems consolidating wired-wireless management to simplify compliance audits.
Canada
Quebec's Bill 64 and British Columbia's data residency requirements sustain demand for sovereign cloud network management instances in Montreal and Toronto data centers. Health Canada regulations governing medical device connectivity impose audit logging obligations on hospital networks. Prairie provinces and Atlantic Canada witness accelerating rural broadband cooperative investment to satisfy federal connectivity mandates.
Mexico
Manufacturing facilities in Nuevo León and Baja California deploy edge computing orchestration for latency-sensitive industrial automation workloads. Federal telecommunications reform frameworks shape carrier investment in monitoring infrastructure for mobile network expansion. The Bajío Region's automotive and aerospace clusters generate specialized demand for operational technology-information technology convergence platforms.
North America Network Management Solutions Market Competitive Landscape
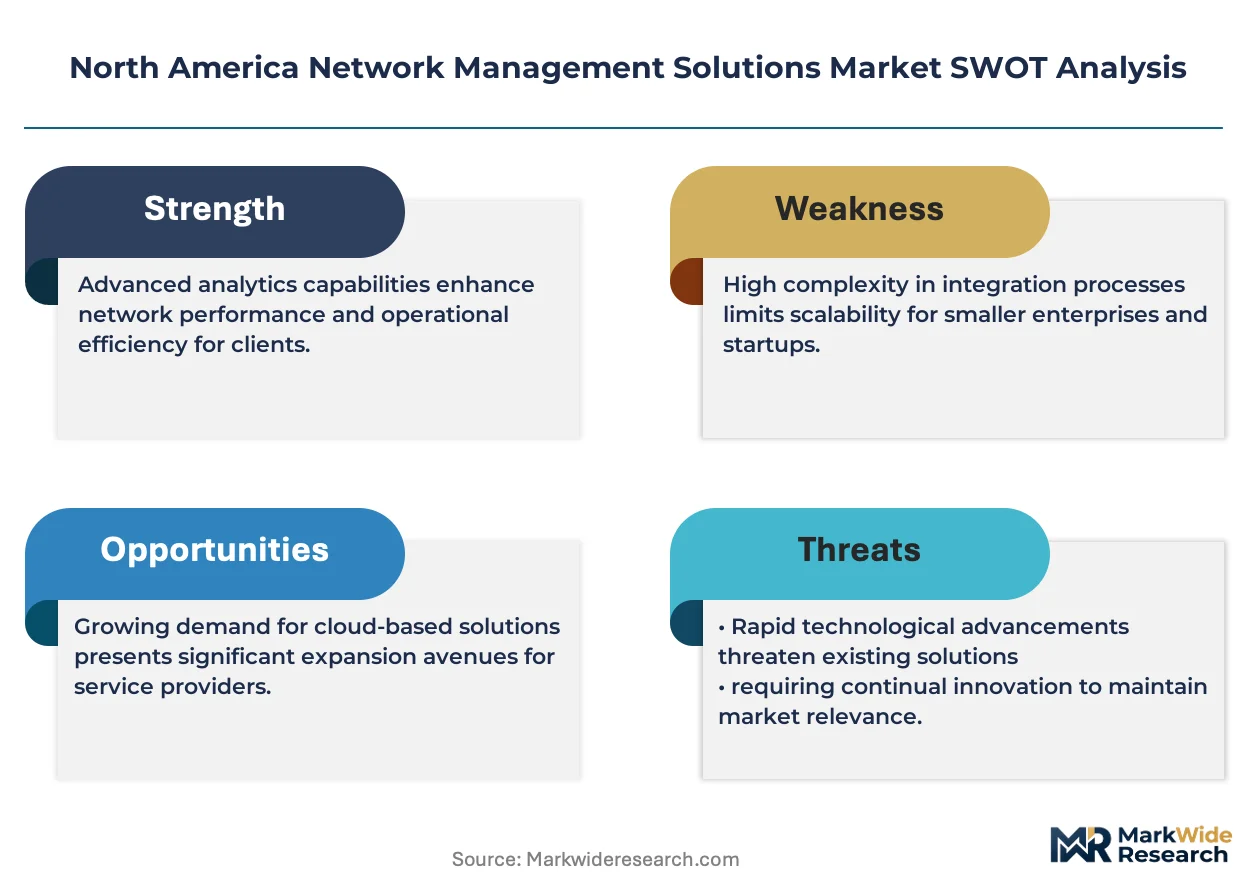
Premium-margin players sit above commodity-margin players across the AI-native operations and integrated campus fabric dimensions, creating a tiered competitive structure. The vendor ecosystem consolidates around three strategic archetypes: full-stack infrastructure incumbents with channel-intensive distribution, AI-native specialists automating multivendor anomaly detection, and modular point-solution providers serving mid-market price sensitivity. Dominant competitive moves include strategic partnerships for telemetry standardization and portfolio diversification into edge computing orchestration.
Within the full-stack infrastructure tier, Cisco Systems and Hewlett Packard Enterprise exemplify channel-anchored market presence, while Juniper Networks occupies a position representing AI-native differentiation. These three companies collectively illustrate how vendor origin—San Jose-based, Palo Alto-based, and Sunnyvale-based respectively—correlates with strategic emphasis on ecosystem breadth, integrated hardware-software portfolios, and autonomous operations platforms.
| Leading Market Players |
|---|
| Cisco Systems |
| Hewlett Packard Enterprise |
| IBM |
| Juniper Networks |
| SolarWinds |
| NETSCOUT |
| Extreme Networks |
| CA Technologies |
| VIAVI Solutions |
| Others |
Pricing and Supply Chain Analysis
Memory chip spot prices and specialized packet processing silicon benchmarks cascade through network appliance manufacturing into three distinct procurement tiers. Cloud-native subscription models absorb upstream volatility through consumption-based metering, while on-premise hardware deployments face sharper cost pass-through from concentrated East Asian foundry capacity.
Pricing Analysis
Consumption-based SaaS metering with tiered feature entitlements now structures enterprise procurement across North America. Price differentiation hinges on AI-native automation depth and HIPAA compliance certification grade, with healthcare systems in Texas and California exhibiting lowest sensitivity due to breach penalty exposure. Pricing pressure intensifies in mid-market segments as Cisco Systems and Hewlett Packard Enterprise compress entry-level bundles to defend against modular point-solution challengers.
Supply Chain Analysis
Trans-Pacific freight rate volatility and port congestion cycles expose hardware-dependent vendors to margin compression during demand surges. Specialized packet processing silicon draws from Taiwan and South Korea foundries, with FPGA and ASIC components resting on concentrated wafer capacity. Single-source vulnerability in advanced node semiconductor fabrication threatens appliance delivery timelines. Distribution runs through channel partner ecosystems anchored by systems integrators in Dallas, Chicago, and Toronto metro areas.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in AI-native operations tiers where automation depth commands premium positioning, while cloud-native delivery architectures compress customer acquisition costs relative to hardware-centric incumbents.
For Market Incumbents: Cement channel control through exclusive telemetry standardization partnerships with hyperscaler marketplaces, insulating against modular point-solution disintermediation. Deepen backward integration into streaming telemetry silicon design to differentiate anomaly detection latency. Prioritize NIST cybersecurity framework pre-certification for federal contractor eligibility maintenance.
For New Entrants and Emerging Players: AI-native intent-based networking platforms offer wedge positioning against legacy SNMP-dependent incumbents in mid-market healthcare verticals. Target rural broadband cooperatives in the Mountain West and Great Plains regions where FCC reliability mandates create procurement urgency without entrenched vendor relationships. Pursue OEM embedding strategies with edge computing hardware manufacturers to bypass direct enterprise sales friction.
For Investors and Strategic Acquirers: Asymmetric upside sits with AI-native operations specialists possessing validated multivendor telemetry normalization capabilities. Five-to-ten-year viability favors platforms demonstrating sustained R&D velocity in autonomous fault isolation. Monitor HIPAA breach notification penalty escalation as demand inflection signal for compliant visibility tool procurement.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Native Platform Launch | Autonomous anomaly detection commands premium positioning against SNMP-dependent legacy dashboards. |
| Hyperscaler Marketplace Integration | AWS and Azure procurement channels unlock mid-market access without direct sales infrastructure. |
| HIPAA Compliance Pre-Certification | Audit-ready logging architectures accelerate healthcare procurement cycles in Texas and California. |
| Edge Computing Orchestration Acquisition | Localized telemetry processing addresses FCC sub-50ms failover mandates for rural broadband cooperatives. |
| Streaming Telemetry Standard Partnership | gRPC-based data feeds reduce multivendor integration friction and customer switching costs. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each national market. The analysis combines structured interviews with network operations executives, healthcare IT procurement officers, telecommunications carrier planning leads, and federal contractor compliance directors with secondary validation against FCC spectrum allocation records, HIPAA enforcement action databases, NIST cybersecurity framework documentation, and hyperscaler capex disclosures. Bottom-up deployment model sizing and top-down vertical spending estimates undergo iterative reconciliation.
Granularity extends to cloud-based, on-premise, hybrid, and software-defined product configurations, with deployment models segmented by edge computing, multi-cloud, public cloud, and private cloud architectures. Industry verticals include telecommunications, healthcare, education, and manufacturing, with service types disaggregated across consulting, installation, maintenance, and support. CAGRs derive from logistic curve adoption modeling calibrated against historical HIPAA compliance investment cycles and 5G capital expenditure trajectories. Inputs include semiconductor foundry capacity utilization trends and provincial privacy statute implementation timelines.
The model holds under sustained HIPAA enforcement intensity and FCC reliability standard maintenance; deviation in federal healthcare funding levels or spectrum license forfeiture thresholds would shift telecommunications and healthcare vertical trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Netops Market
Network Technology
Global Industrial Ethernet Switch Market
Network Technology
Virtual Customer Premises Equipment Market
Network Technology
Global Network Monitoring Market
Network Technology
Europe Video Conferencing Hardware Market
Network Technology
Optical Networking Market
Network Technology
SP Routing and Ethernet Switching Market
Network Technology
Germany Residential Gateway Market
Network Technology
Router and Switch Market
Network Technology
Global Carrier Ethernet Equipment Market
Network Technology
Middle East & Africa Video Conferencing Hardware Market
Network Technology
Intelligent Network Management Market
Network Technology
Self-Healing Networks Market
Network Technology
Mobile Network Optimization Market
Network Technology
Passive Optical Network Market
Network Technology
Wimax Solutions Market