
 Optical Networking Market | 2026-2036
Optical Networking Market Size, Share, and Industry Trends Forecast 2026-2036
Optical Networking Market Outlook
Silicon photonics is restructuring transceiver economics by displacing traditional indium phosphide substrates in high-speed modules. Ciena leverages vertically integrated silicon photonics foundries to control cost curves at 800G and beyond. Huawei Technologies anchors supply chains across Asia through captive manufacturing of coherent DSPs and optical engines. Nokia differentiates in submarine and metro segments with proprietary photonic service engine chips.
Optical networking encompasses the transmission, switching, and amplification of data as light signals through fiber-optic cables, typically operating at wavelengths between 1260 and 1625 nanometers with coherent modulation enabling 800G per lambda. Its primary purpose is to carry high-bandwidth traffic across telecom backbones, data center interconnects, and enterprise WANs with minimal signal degradation over distances exceeding thousands of kilometers. Wavelength division multiplexing occupies the dominant share of transport technology deployments due to its proven scalability across existing fiber plant. Dense wavelength division multiplexing is the fastest-expanding technology segment as cloud providers demand 400G and 800G channel densities for inter-data-center links. Optical transceivers concentrate the largest margin pool because laser and DSP component scarcity grants pricing power to integrated module vendors.
The Federal Communications Commission shapes US deployment timelines through Rural Digital Opportunity Fund disbursements tied to fiber-to-the-premises buildouts. The European Telecommunications Standards Institute and ETSI-mandated open optical standards are forcing incumbents to disaggregate proprietary line systems. China's Ministry of Industry and Information Technology accelerates domestic 400G backbone upgrades through spectrum allocation and infrastructure investment directives. Stakeholders must monitor how open line system interoperability certifications reshape vendor selection criteria and procurement patterns.
Market Dynamics
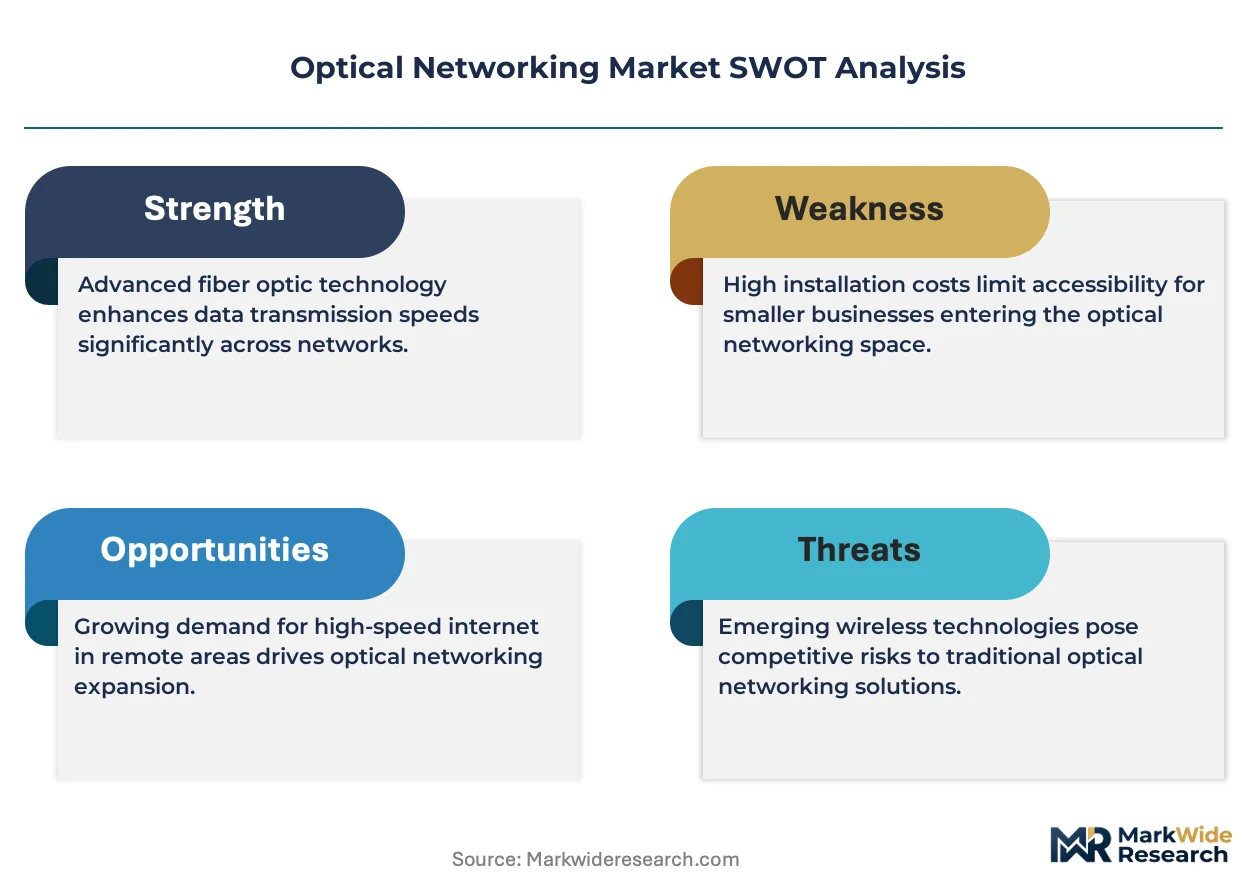
Silicon photonics is restructuring transceiver economics by displacing traditional indium phosphide substrates in high-speed modules, forcing incumbents to retool foundry strategies and rewrite procurement specifications across cloud hyperscaler supply chains.
Growth Catalysts
- FCC Rural Digital Opportunity Fund:Federal broadband subsidies accelerate fiber-to-the-premises buildouts across underserved US counties, creating anchor demand for coherent optical transport gear.
- AI-driven traffic loads:Cloud hyperscalers expand backbone capacity to support machine learning workloads, mandating 800G lambda densities on inter-data-center links.
- ETSI open optical standards:European mandates force hardware-software disaggregation, opening procurement to modular vendors and collapsing incumbent lock-in.
Market Restraints
- Laser and DSP component scarcity:Integrated module vendors concentrate pricing power, squeezing margin pools for systems integrators lacking captive photonics supply.
- Indium phosphide substrate dependence:Legacy transceiver architectures face input cost volatility as silicon photonics scales, stranding capital in depreciating fab equipment.
- REACH substance restrictions:European chemical regulations constrain rare-earth doping processes in fiber amplifiers, complicating supply chain compliance.
Strategic Opportunities
- Submarine cable upgrades:Proprietary photonic service engine architectures enable vendors to capture premium pricing on transoceanic routes requiring ultra-long-haul coherent transmission.
- Open RAN fronthaul optics:Disaggregated radio access networks create white space for pluggable coherent optics in 5G midhaul aggregation.
- China MIIT 400G directives:Domestic backbone upgrade mandates accelerate demand for advanced modulation formats and spectrum-flexible line systems.
Industry Challenges
- Coherent DSP talent scarcity:Algorithm design for probabilistic constellation shaping requires specialized signal processing expertise concentrated at few institutions.
- Interoperability certification timelines:Open line system validation delays vendor qualification for hyperscaler procurement cycles, compressing revenue recognition windows.
- Legacy SONET/SDH integration:Brownfield transport networks demand backward-compatible wavelength provisioning, complicating software-defined control plane rollouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optical Networking Market |
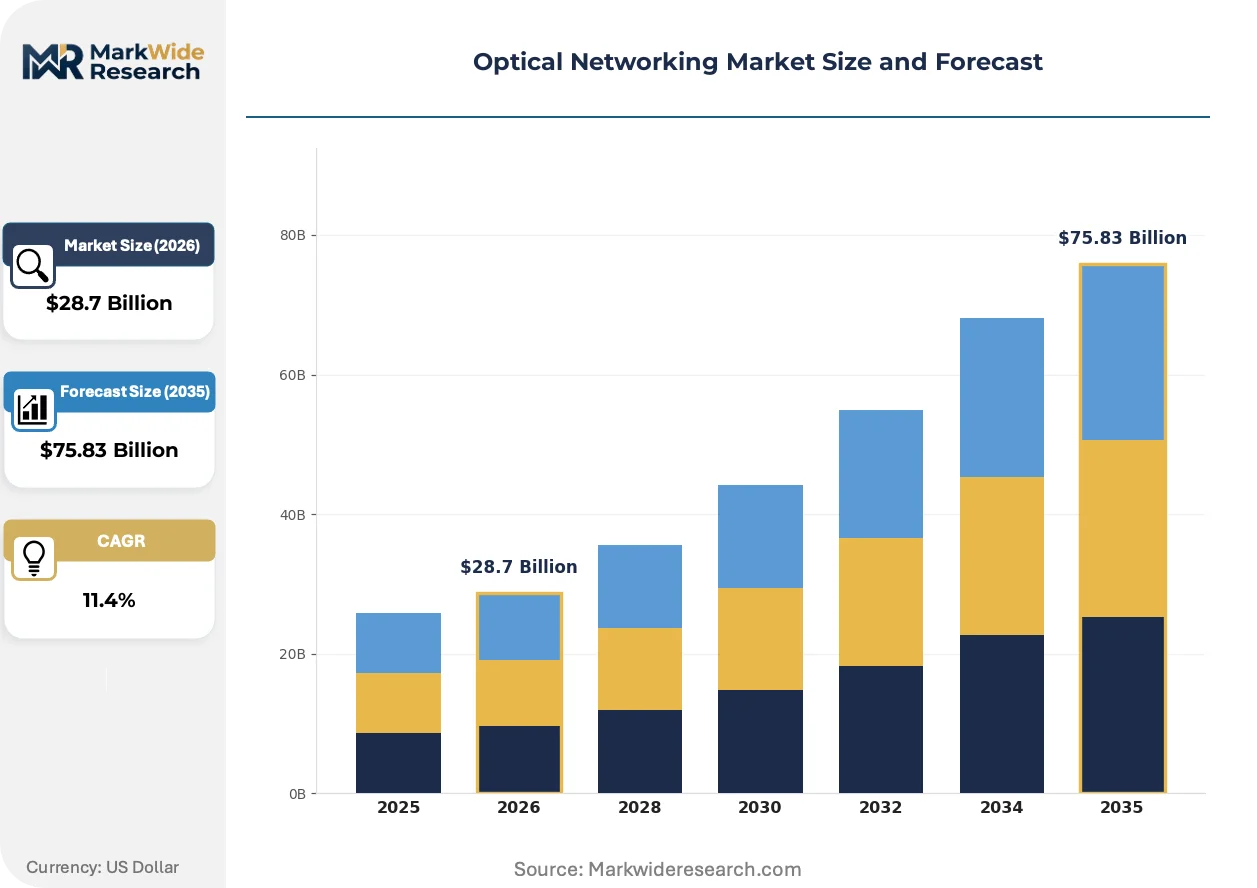
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $75.83 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Transceivers, Optical Amplifiers, Optical Switches, Optical Connectors Technology: Wavelength Division Multiplexing, Dense Wavelength Division Multiplexing, Optical Time-Domain Reflectometry, Passive Optical Networks End User: Telecom Service Providers, Data Centers, Enterprises, Government Deployment: On-Premises, Cloud-Based, Hybrid, Managed |
| Companies Covered | Ciena, Huawei Technologies, Nokia, Infinera, ZTE Corporation, Cisco Systems, ADVA Optical Networking, Fujitsu, Lumentum Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optical Networking Market Strategic Shifts
Coherent modulation formats and packaging architectures are advancing in lockstep, compressing power-per-bit curves while expanding addressable distance-bandwidth combinations beyond traditional metro-regional boundaries.
Silicon photonics is overtaking indium phosphide in 800G transceiver production by integrating lasers, modulators, and detectors on single CMOS-compatible substrates. Cloud providers now specify silicon photonics modules for new data center builds, collapsing the cost premium that previously favored III-V compound semiconductors. This substrate transition is compressing module price curves and redistributing value capture toward foundry operators with 300mm wafer scale.
ETSI-mandated open optical interface specifications are forcing disaggregation of proprietary line systems across European procurement. Incumbent vendors must expose previously closed control planes to third-party transceiver and amplifier suppliers. Metro and regional network operators in Germany, France, and the Netherlands are piloting multi-vendor interoperability certifications, rewriting supplier selection criteria toward module-level compliance.
Hyperscalers now unbundle optical transport procurement from systems integration, contracting directly with transceiver vendors for data center interconnect while sourcing open line systems separately. This bifurcation collapses traditional vendor-captive relationships and concentrates volume with module specialists capable of 800G volume scale. The pattern is most visible in US cloud provider networks, where procurement teams negotiate laser and DSP supply agreements independent of chassis vendors.
Optical Networking Market Segmentation
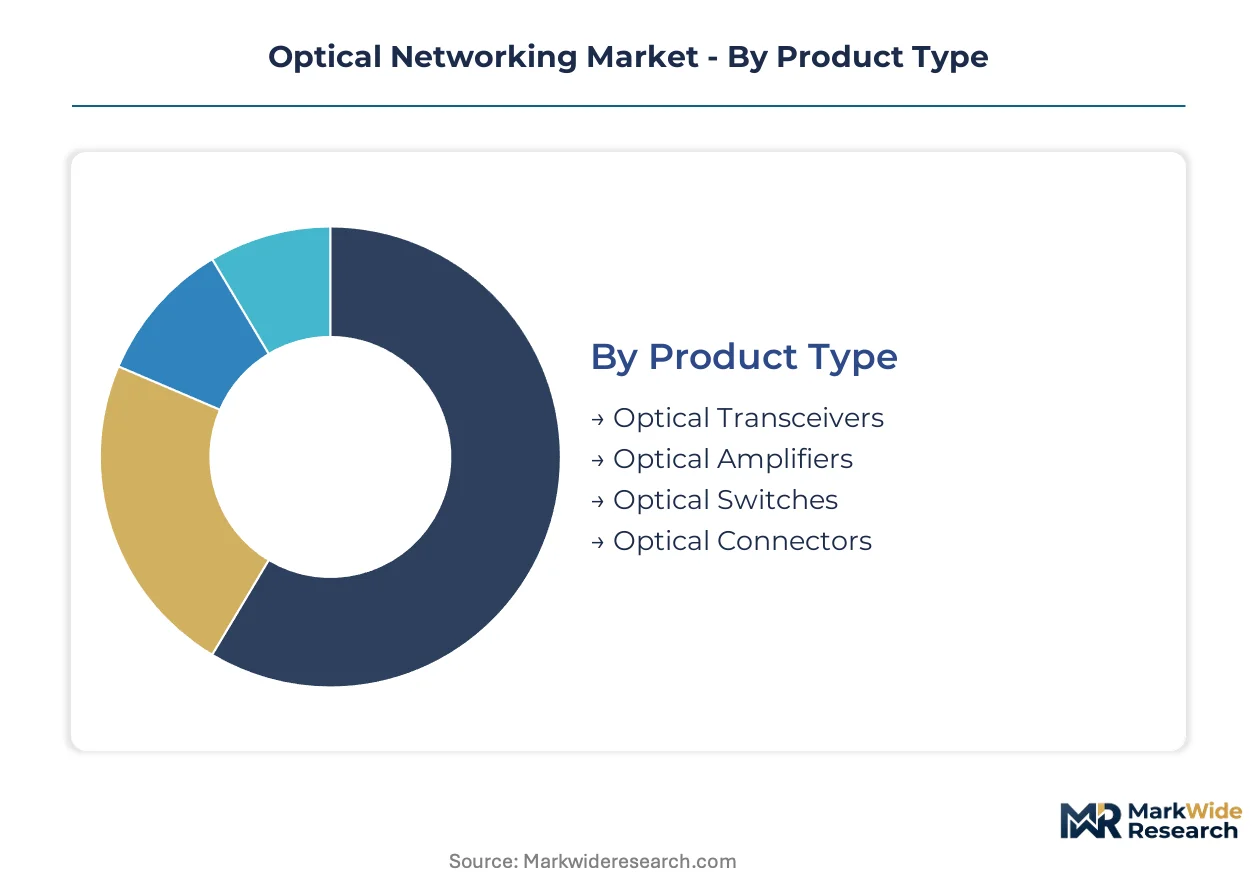
Optical networking equipment varies dramatically in capital requirements, from pluggable transceivers with short depreciation cycles to submarine cable systems requiring decade-long amortization. Understanding these investment profiles helps procurement teams align CapEx planning with technology roadmaps and vendor consolidation strategies.
Product Type:
Capital intensity peaks in coherent line systems requiring specialized foundry equipment, while pluggable modules amortize tooling costs across higher volumes.
- Optical Transceivers:Integrated modules combining lasers, modulators, and DSPs on silicon photonics or indium phosphide substrates. Cloud hyperscalers in the United States now contract directly with transceiver vendors for 800G data center interconnect, bypassing traditional systems integrators and collapsing historical vendor-captive relationships.
- Optical Amplifiers:Erbium-doped fiber amplifiers and Raman amplifiers that boost signal power across long-haul spans. European network operators face compliance complexity as REACH substance restrictions constrain rare-earth doping processes, forcing reformulation of amplifier gain media and qualification of alternative supply chains.
- Optical Switches:Reconfigurable optical add-drop multiplexers and photonic cross-connects enabling wavelength-level traffic steering.
- Optical Connectors:Physical fiber interfaces including MPO, LC, and emerging VSFF formats for high-density patching.
Most installed capacity flows through Optical Transceivers. Expansion is steepest in Optical Amplifiers as 400G and 800G coherent signals demand more frequent amplification.
Technology:
Deployment economics hinge on spectral efficiency trade-offs, with mature WDM platforms competing against newer coherent formats for upgrade budgets.
- Wavelength Division Multiplexing:Foundational technology combining multiple optical signals on single fiber through coarse or dense channel spacing. Incumbent carriers in Germany and France maintain extensive CWDM deployments for metro aggregation, though new builds increasingly specify DWDM for future-proofing.
- Dense Wavelength Division Multiplexing:High-channel-count systems with 100GHz or tighter spacing enabling 400G and 800G per lambda. Cloud providers across the United States, Netherlands, and Japan specify DWDM for inter-data-center links, driving demand for flexible-grid ROADMs and spectrum-flexible transceivers.
- Optical Time-Domain Reflectometry:Diagnostic technique for fiber characterization and fault location in field maintenance operations.
- Passive Optical Networks:Point-to-multipoint fiber access architecture using unpowered splitters for residential and enterprise connectivity.
Legacy Wavelength Division Multiplexing retains the largest installed base. Dense Wavelength Division Multiplexing is gaining share fastest as hyperscalers upgrade backbone capacity.
End User:
Procurement scale and technical sophistication diverge sharply, from volume-driven cloud operators to risk-averse government buyers with extended qualification timelines.
- Telecom Service Providers:Incumbent and competitive carriers operating national and regional fiber networks. Verizon, Deutsche Telekom, and NTT face ETSI-mandated open optical standards that force hardware-software disaggregation and expose previously proprietary control planes to third-party module suppliers.
- Data Centers:Hyperscale cloud operators and colocation providers with massive inter-facility bandwidth requirements. Microsoft, Google, and Amazon Web Services unbundle optical transport procurement, sourcing transceivers directly from module specialists while contracting open line systems separately.
- Enterprises:Financial services, healthcare, and manufacturing organizations deploying private optical networks for campus and metro connectivity.
- Government:Federal, state, and municipal agencies including defense and research networks with security-hardened requirements.
Telecom Service Providers account for the majority of deployed kilometers. Data Centers are expanding capacity fastest as AI training clusters multiply.
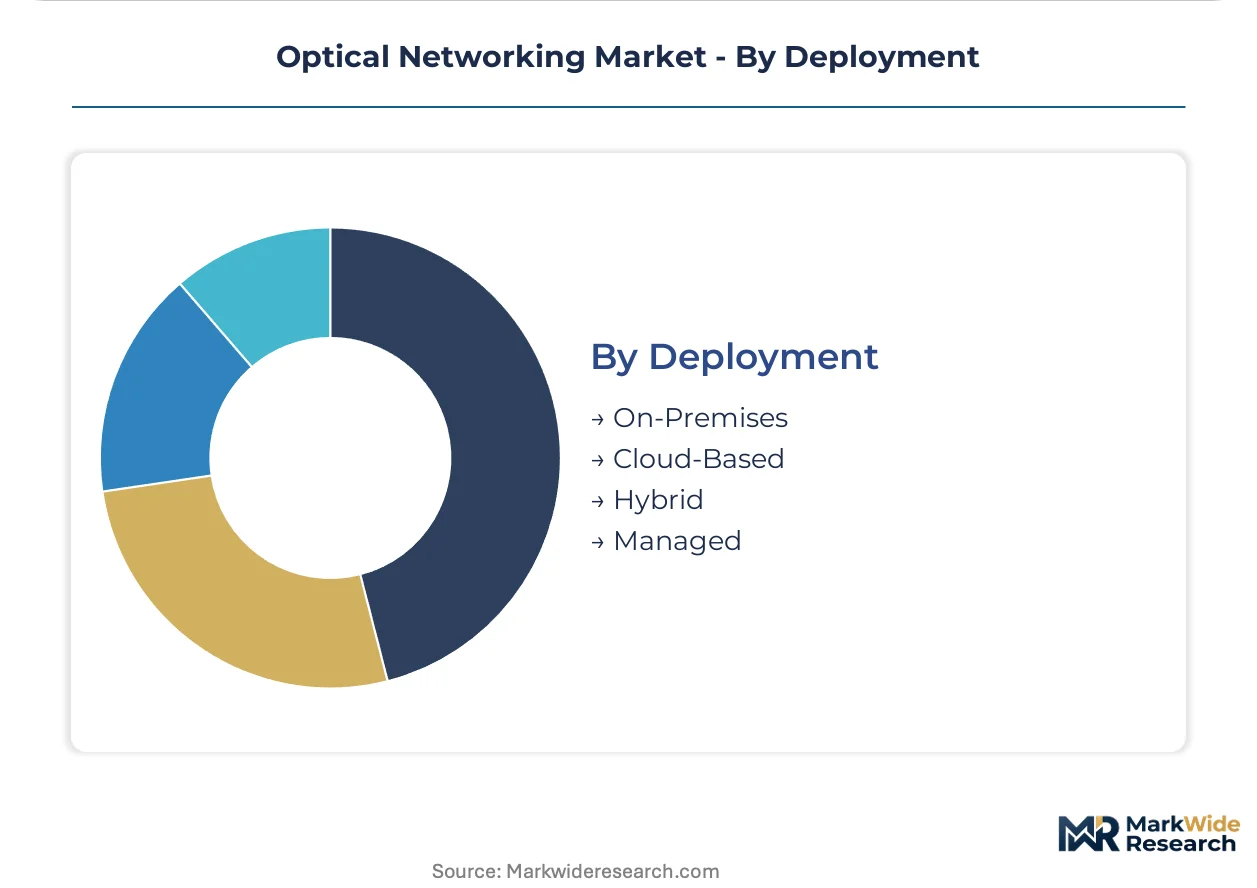
Deployment:
Operational model selection determines who carries depreciation risk and where engineering talent concentrates.
- On-Premises:Customer-owned and operated optical infrastructure with full CapEx burden and operational control. Large enterprises in Japan and South Korea favor this model for low-latency financial trading networks where physical proximity to exchanges matters more than cloud elasticity.
- Cloud-Based:Optical transport delivered as network-as-a-service with usage-based pricing. European operators in the Netherlands and Ireland pilot cloud-native optical control planes that abstract physical layer complexity behind API-driven provisioning.
- Hybrid:Mixed ownership combining owned fiber with leased wavelengths for capacity peaks.
- Managed:Outsourced operations where vendors assume SLAs for availability and performance.
On-Premises retains the largest cumulative investment. Cloud-Based deployment is climbing fastest as operators seek to shift optical infrastructure from balance sheet to operating expense.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley hyperscaler clusters and Shenzhen manufacturing corridors anchor optical networking demand through divergent procurement patterns and technology roadmaps.
United States
Cloud hyperscalers in Northern Virginia and Oregon data center corridors drive 800G transceiver procurement for AI training clusters. FCC Rural Digital Opportunity Fund disbursements accelerate fiber-to-the-premises buildouts across underserved Appalachian and Midwestern counties. Microsoft and Amazon Web Services unbundle optical transport procurement, contracting directly with module specialists while sourcing open line systems separately.
China
Domestic cloud operators and state-owned carriers expand 400G backbone capacity across eastern coastal provinces. MIIT spectrum allocation directives accelerate deployment of advanced modulation formats on national fiber rings. Shenzhen and Dongguan manufacturing clusters anchor captive production of coherent DSPs and optical engines through vertically integrated supply chains.
Germany
Deutsche Telekom and regional carriers pilot multi-vendor interoperability certifications for open optical line systems. ETSI-mandated disaggregation standards expose proprietary control planes to third-party module suppliers. Munich and Frankfurt data center operators specify DWDM for inter-facility links, driving demand for flexible-grid ROADMs.
Japan
NTT and competitive carriers upgrade submarine cable landing stations with coherent transmission gear for transpacific capacity expansion. METI infrastructure investment programs support domestic 400G metro ring deployments. Tokyo and Osaka financial districts favor on-premises optical infrastructure for low-latency trading networks where physical proximity exceeds cloud elasticity.
Netherlands
Amsterdam and Rotterdam data center operators pilot cloud-native optical control planes that abstract physical layer complexity behind API-driven provisioning. ETSI open optical standards compliance enables multi-vendor procurement strategies for metro aggregation networks. Dutch network operators source pluggable coherent optics for 5G midhaul aggregation as Open RAN architectures mature.
Optical Networking Market Competitive Environment
Strategic partnerships dominate the current landscape as module specialists and systems integrators negotiate laser and DSP supply agreements. The vendor base stratifies across three tiers: integrated platform vendors with captive photonics foundries, pure-play transceiver manufacturers scaling silicon photonics volume, and open line system specialists exploiting ETSI-mandated interoperability standards. Competitive positioning hinges on backward integration into III-V compound semiconductor fabrication, geographic proximity to cloud hyperscaler procurement teams, and certification velocity for open optical interface compliance.
Within the integrated platform tier, Ciena and Huawei Technologies exemplify divergent supply chain strategies. Ciena leverages vertically integrated silicon photonics foundries to control cost curves at 800G and beyond. Huawei anchors supply chains across Asia through captive manufacturing capabilities. Nokia occupies a distinct position in submarine and metro segments with proprietary photonic service engine architectures.
| Leading Market Players |
|---|
| Ciena |
| Huawei Technologies |
| Nokia |
| Infinera |
| ZTE Corporation |
| Cisco Systems |
| ADVA Optical Networking |
| Fujitsu |
| Lumentum Holdings |
| Others |
Value Chain & Pricing Dynamics
Coherent DSP algorithm specialists concentrated in Boston and Shenzhen create labor-cost differentials that widen pricing-tier spreads between premium custom-engineered modules and commodity silicon photonics volumes.
Pricing Analysis
Input-cost pass-through from indium phosphide substrate scarcity feeds directly into 800G transceiver pricing, with silicon photonics modules commanding premiums based on CMOS foundry scale and DSP integration density. Three-tier pricing structure across premium, standard, and economy levels separates hyperscaler-direct contracts from systems-integrator bundles and spot-market procurement. Pricing pressure stems from cloud hyperscaler unbundling of transport procurement, which collapses historical vendor-captive markups. Telecom service providers exhibit highest price sensitivity due to amortized legacy infrastructure, while data center operators prioritize performance density over unit cost.
Supply Chain Analysis
Warehouse-distribution layers for optical components concentrate in Shenzhen, Dongguan, and Penang, with regional distribution centers feeding assembly operations across Asia-Pacific and North American hub-and-spoke patterns. Manufacturing draws from Taiwan for advanced foundry services, China for rare-earth amplifier materials and passive component fabrication, and Malaysia for final module assembly and test. Single-source vulnerability concentrates in coherent DSP supply, where algorithm design expertise anchors at fewer than five institutions globally. Distribution runs through direct vendor-to-hyperscaler contracts alongside traditional systems-integrator channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Optical networking functions as a geographic-arbitrage play where ETSI-mandated open optical standards in Europe create procurement cost advantages against FCC-subsidized but vertically integrated US supply chains.
For Market Incumbents: Anticipate silicon photonics substrate transitions by accelerating captive foundry investment or securing multi-year wafer agreements with TSMC and GlobalFoundries. Defend against cloud hyperscaler direct contracting by embedding professional services and software-defined control planes into chassis offerings. Prioritize certification velocity for ETSI open line system interoperability to maintain European procurement access. For New Entrants and Emerging Players: Regional carriers in Germany and the Netherlands represent the most penetrable buyer archetype, as ETSI mandates force multi-vendor procurement strategies and collapse incumbent lock-in. Target submarine cable upgrade cycles with proprietary photonic service engine architectures that command premium pricing on transoceanic routes. Pursue pluggable coherent optics for Open RAN 5G midhaul aggregation as disaggregated radio access networks mature. For Investors and Strategic Acquirers: Cloud hyperscalers are the most active acquirer in this space, seeking vertical control over laser and DSP supply chains to secure 800G volume scale. Long-term viability centers on module specialists with silicon photonics foundry relationships and open optical certification velocity. Watch hyperscaler capex disclosure inflections for AI training cluster buildouts as demand signal indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Photonics Foundry Investment | Ciena and Huawei anchor cost curves at 800G through captive 300mm wafer scale. |
| Open Line System Certification | ETSI-mandated interoperability exposes proprietary control planes to third-party module suppliers. |
| Submarine Cable System Upgrade | Nokia captures premium pricing on transoceanic routes with proprietary photonic service engine architectures. |
| Direct Hyperscaler Contracting | Microsoft and Amazon Web Services unbundle procurement, collapsing traditional vendor-captive relationships. |
| Open RAN Fronthaul Optics Development | Pluggable coherent optics create white space in 5G midhaul aggregation as disaggregated architectures mature. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with optical transport engineering directors, hyperscaler procurement officers, telecom carrier network planners, and coherent DSP design specialists. Secondary validation draws from FCC Rural Digital Opportunity Fund disbursement records, ETSI open optical standards documentation, MIIT spectrum allocation directives, and hyperscaler capital expenditure disclosures. Bottom-up module shipment estimates triangulate against top-down carrier capital intensity benchmarks.
Rate-of-change decomposition separates volume expansion from price trajectory shifts across the projection horizon. Segmentation dimensions modeled include product type, technology format, end-user category, and deployment model, with additional granularity on coherent modulation format adoption curves. CAGRs derive from logistic diffusion modeling of 400G and 800G lambda deployment rates, cross-referenced against fiber route mileage expansion and data center interconnect bandwidth scaling.
Underlying measurement precision varies by segment; optical transceiver volumes carry tighter precision than submarine cable system bookings due to direct vendor reporting. Forecasts reflect assumptions on silicon photonics yield ramp schedules and open optical interoperability certification timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Gigabit Passive Optical Network (GPON) Market
Network Technology
Europe Video Conferencing Hardware Market
Network Technology
Internet Protocol Address Management (IPAM) Market
Network Technology
Cloud Managed Access Points Market
Network Technology
Fiber to the Home (FTTH) Market
Network Technology
Global 5G Smart Antenna Market
Network Technology
Global Ethernet Switch and Routers Market
Network Technology
Managed MPLS Market
Network Technology
RTP Market
Network Technology
Unified Network Management Market
Network Technology
Global Wireless Router Market
Network Technology
Smart Network Interface Card (Smartnic) Market
Network Technology
DNS DHCP and IPAM Market
Network Technology
Asia Pacific Structured Cabling Market
Network Technology
CPE Router Market
Network Technology
Network Management Systems (NMS) Market