
 RTP Market | 2026-2036
RTP Market Size, Share, and Industry Trends Forecast 2026-2036
RTP Market Outlook
North American payment infrastructure is consolidating around real-time rails as the Federal Reserve's FedNow Service and The Clearing House's RTP network expand coverage. ACI Worldwide leverages its global software footprint to serve multiple domestic instant payment schemes. Fiserv sustains competitive relevance through its merchant-facing acquiring technology that integrates with faster payment rails.
Real-time payments (RTP) are electronic fund transfers settled within seconds, typically operating on ISO 20022 messaging standards that carry richer remittance data than legacy batch systems. The technology enables 24/7 availability and immediate finality, serving commercial treasury operations and consumer peer-to-peer needs that tolerate no settlement delay. Instant Payments solutions currently anchor the largest value pool, while Cross-Border Transfers represent the fastest-expanding segment as correspondent banking networks modernize. Banking Institutions dominate end-user demand, though Fintech Companies are capturing disproportionate growth by building overlay services atop open RTP infrastructure.
The Federal Reserve governs FedNow participation rules and liquidity requirements, while the European Banking Authority enforces PSD2 open-banking access standards that compel traditional banks to expose APIs for third-party initiation. India's National Payments Corporation operates the UPI scheme under Reserve Bank of India oversight, creating a regulatory template now studied by emerging-market central banks. Stakeholders must weigh whether to build proprietary instant payment stacks or embed into existing national rail architectures as new geographies activate real-time clearing.
Market Dynamics
The Federal Reserve's FedNow Service and The Clearing House's RTP network are consolidating North American payment infrastructure around real-time rails, forcing banks to modernize core systems or lose transaction volume to faster competitors.
Growth Catalysts
- ISO 20022 migration:The European Union's mandate for richer remittance data is compelling correspondent banks to upgrade messaging infrastructure, opening overlay service opportunities.
- Open banking APIs:PSD2 standards enforced by the European Banking Authority require traditional institutions to expose payment initiation interfaces, accelerating third-party fintech integration.
- UPI ecosystem expansion:India's National Payments Corporation has created a regulatory template under Reserve Bank of India oversight that emerging-market central banks are actively studying for replication.
Market Restraints
- Core system replacement costs:Legacy batch-processing architectures at major banks require multi-year capital commitments to achieve 24/7 availability.
- Liquidity management complexity:Real-time finality demands pre-positioned funds, straining treasury operations at smaller institutions with limited intraday credit access.
- Interoperability fragmentation:Divergent national rail specifications across Brazil, Australia, and Singapore prevent seamless cross-border instant payments without correspondent bridges.
Strategic Opportunities
- Cross-border correspondent modernization:SWIFT gpi and emerging bilateral linkages between national schemes offer white space for overlay foreign-exchange and settlement services.
- Request-to-pay messaging:The structured invoice-presentment capability within ISO 20022 enables B2B treasury automation that batch ACH cannot support.
- Embedded finance integration:Non-bank platforms in Southeast Asia are embedding instant payment initiation into e-commerce and ride-hailing workflows, bypassing traditional banking interfaces entirely.
Industry Challenges
- Fraud prevention latency trade-offs:Sub-second settlement windows compress screening time for sanctions and AML checks, requiring machine-learning models that smaller banks struggle to deploy.
- Technical talent scarcity:ISO 20022 message mapping and cloud-native core banking expertise command premium compensation, constraining implementation timelines at regional institutions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RTP Market |
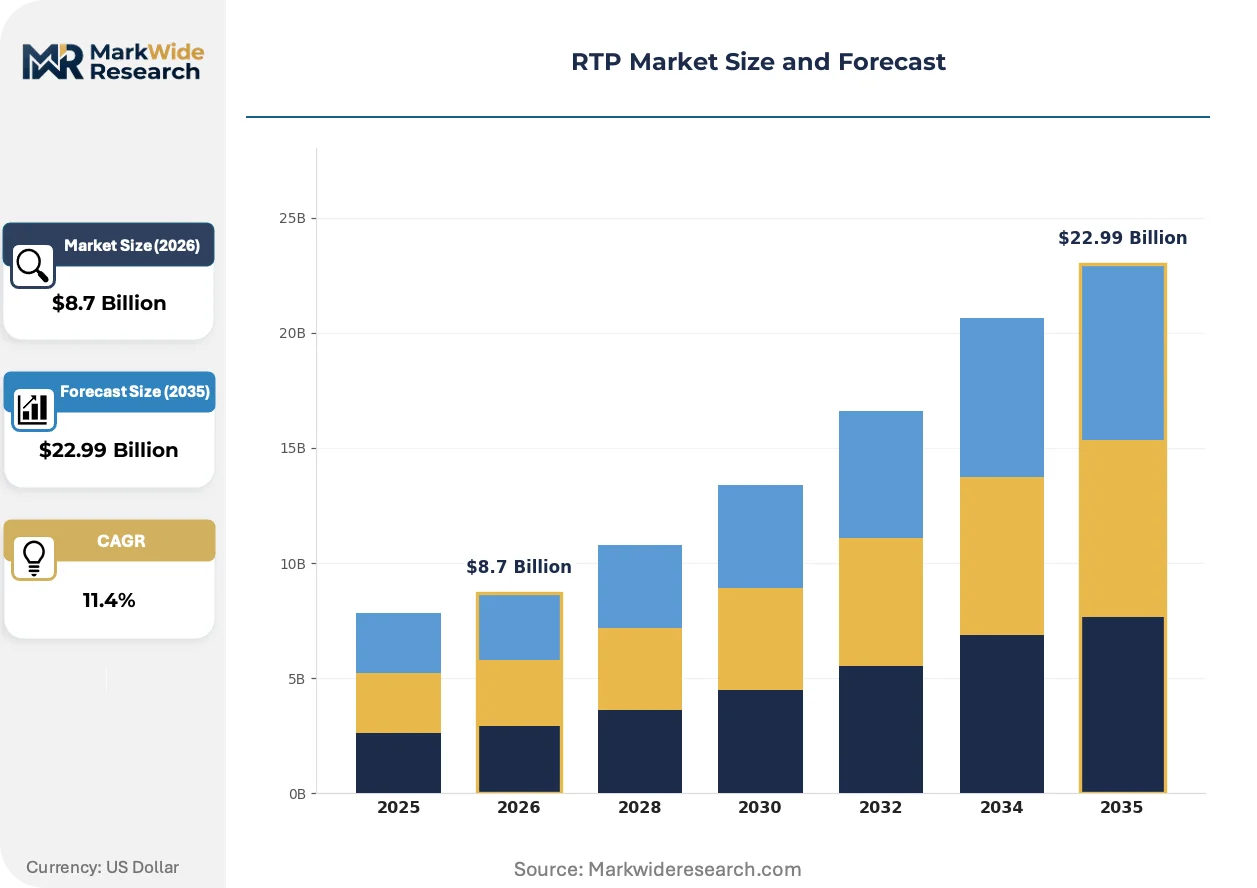
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Instant Payments, Real-Time Processing, Cross-Border Transfers, Mobile Payments End User: Banking Institutions, Payment Processors, E-Commerce Platforms, Fintech Companies Technology: Blockchain, API Integration, Cloud Computing, Distributed Ledger Application: Consumer Payments, Business Transactions, Remittances, Fund Transfers |
| Companies Covered | Mastercard Inc., The Clearing House, ACI Worldwide Inc., Form3, Federal Reserve (FedNow Service), Fiserv Inc., Montran Corporation, Square Inc., PayPal Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RTP Market Strategic Shifts
Real-time payment infrastructure is absorbing artificial intelligence and distributed ledger technologies that promise to compress settlement windows further while introducing new operational complexities for traditional operators.
Artificial intelligence-powered transaction monitoring is absorbing the fraud-detection burden that real-time finality imposes on financial institutions. Large banks in the United States are deploying machine-learning models trained on behavioral biometrics to score payment risk within milliseconds. This compression of screening time is absorbing regulatory scrutiny as supervisors debate whether algorithmic detection meets suspicious-activity reporting standards.
The European Union's Digital Operational Resilience Act is mandating stress-testing and third-party risk management for critical payment infrastructure providers. This regulatory framework is compelling instant payment scheme operators to upgrade cybersecurity controls and incident-response capabilities. Major clearing houses in Germany and France are responding by consolidating vendor relationships and demanding higher assurance certifications from cloud service providers.
Treasury departments at mid-market corporates are unbundling payment initiation from banking relationships, selecting rails based on speed and data richness rather than institutional loyalty. This behavioral shift is fragmenting deposit concentration as finance teams maintain accounts across multiple banks to optimize liquidity positioning. The trend is most visible in the United Kingdom, where open banking APIs have enabled treasury workstation vendors to offer multi-bank aggregation without correspondent banking fees.
RTP Market Segmentation
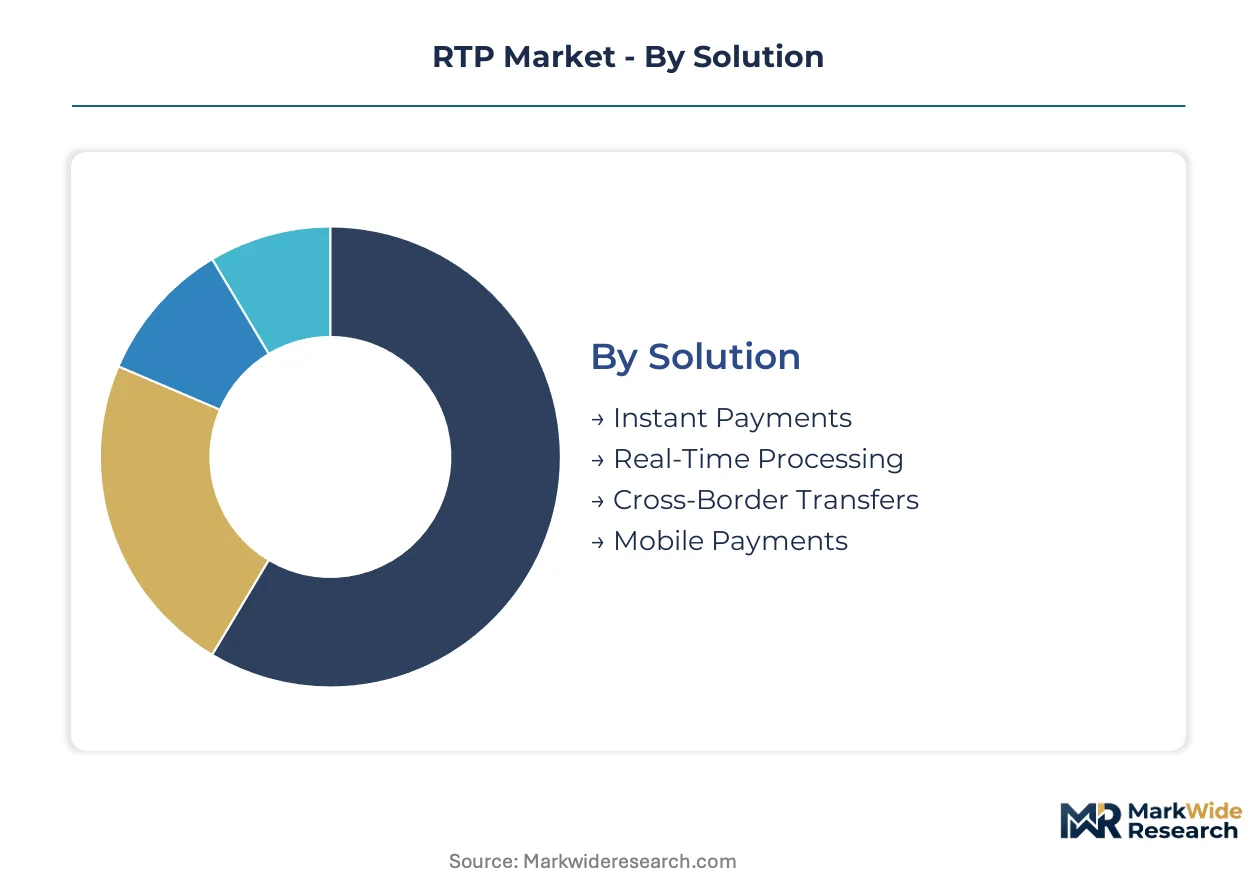
RTP market segmentation reveals how infrastructure investments, regulatory mandates, and end-user requirements fragment across technical architectures and operational models. Solution types and technology stacks determine interoperability costs, while end-user categories expose divergent liquidity and compliance priorities.
Solution:
Technical specifications differentiate settlement speed, message richness, and geographic reach across payment rail architectures.
- Instant Payments:Domestic schemes settle funds within seconds using ISO 20022 messaging that carries structured remittance data unavailable in legacy ACH. Demand concentrates in India where the National Payments Corporation operates the UPI scheme, and in the United States where the Federal Reserve's FedNow Service competes with The Clearing House's RTP network for bank participation.
- Cross-Border Transfers:Correspondent banking modernization compresses settlement windows through SWIFT gpi and bilateral national scheme linkages. Growth is accelerating fastest in Southeast Asia as Singapore's PayNow and Thailand's PromptPay establish regional interoperability, though foreign-exchange overlay services remain underdeveloped.
- Real-Time Processing:Core banking engine upgrades enable 24/7 transaction availability with immediate finality, requiring cloud-native architecture that strains legacy mainframe operators.
- Mobile Payments:Smartphone-native initiation layers embed instant payment rails into merchant apps and social platforms, bypassing traditional banking interfaces in emerging markets.
Mature deployment sits with Instant Payments. Newer deployment is concentrated in Cross-Border Transfers.
End User:
Customer type determines compliance burden, liquidity requirements, and API integration depth.
- Banking Institutions:Traditional deposit-taking institutions face core system replacement costs and pre-positioned liquidity demands to achieve real-time finality. Demand concentrates among mid-tier US banks modernizing to retain corporate treasury relationships as faster competitors capture volume.
- Fintech Companies:Non-bank platforms build overlay services atop open RTP infrastructure without maintaining settlement accounts, exploiting PSD2-mandated API access in the European Union and similar frameworks in Brazil and Singapore.
- Payment Processors:Merchant acquirers integrate instant rails into checkout flows, absorbing fraud screening latency through machine-learning models.
- E-Commerce Platforms:Online marketplaces embed request-to-pay messaging for invoice presentment, leveraging ISO 20022 data fields for automated reconciliation.
Established adoption patterns characterize Banking Institutions. Disproportionate expansion is occurring among Fintech Companies.
Technology:
Underlying infrastructure choices determine scalability, resilience certification requirements, and vendor lock-in exposure.
- Cloud Computing:Elastic capacity supports 24/7 transaction spikes without capital-intensive hardware procurement, though the European Union's Digital Operational Resilience Act mandates stress-testing and third-party risk management that complicates vendor selection.
- API Integration:Standardized interfaces enable third-party initiation under open banking mandates, with India's UPI providing the regulatory template most studied by emerging-market central banks.
- Blockchain:Distributed consensus mechanisms promise settlement finality without correspondent intermediaries, yet regulatory ambiguity constrains wholesale adoption.
- Distributed Ledger:Permissioned networks pilot cross-border settlement efficiency, though interoperability with national fiat rails remains technically unresolved.
Production-scale deployment centers on Cloud Computing. Experimental traction is strongest in Blockchain.
Application:
Use case characteristics dictate transaction size distribution, fraud risk profiles, and data field requirements.
- Business Transactions:B2B treasury operations exploit request-to-pay messaging for automated invoice reconciliation, with structured remittance data eliminating manual matching. Demand concentrates in the United Kingdom where open banking APIs enable multi-bank aggregation without correspondent fees.
- Consumer Payments:Peer-to-peer and retail purchases prioritize speed over data richness, driving volume through mobile wallets in India and Southeast Asia.
- Remittances:Cross-border worker payments seek cost reduction through corridor-specific fintech platforms, though correspondent banking compliance costs persist.
- Fund Transfers:Intra-institutional liquidity positioning and corporate payroll disbursement require immediate finality for treasury optimization.
Operational maturity defines Business Transactions. Volume expansion is steepest in Consumer Payments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's UPI transaction volume anchors real-time payment infrastructure deployment, while regulatory templates from the Reserve Bank of India now propagate across emerging markets. Settlement rail modernization concentrates in jurisdictions with active central bank sponsorship and open banking mandates.
United States
The Federal Reserve's FedNow Service competes with The Clearing House's RTP network for bank participation, forcing core system upgrades among mid-tier institutions. The Federal Reserve governs liquidity requirements and participation rules that shape competitive dynamics. Corporate treasury operations in New York and Chicago drive demand for 24/7 finality and richer remittance data.
India
The National Payments Corporation operates the UPI scheme that processes billions of monthly transactions across mobile wallets and merchant apps. The Reserve Bank of India mandates interoperability standards that fintech platforms exploit for overlay services. Bengaluru and Mumbai host the densest concentration of payment technology development and scheme operator talent.
United Kingdom
Faster Payments infrastructure enables treasury departments to unbundle payment initiation from banking relationships through open banking APIs. The Financial Conduct Authority enforces PSD2-mandated access standards that compel traditional institutions to expose interfaces. London's fintech cluster leads multi-bank aggregation and request-to-pay messaging innovation.
Germany
The Bundesbank oversees TARGET Instant Payment Settlement integration that connects domestic rails to eurozone infrastructure. The Digital Operational Resilience Act mandates stress-testing and third-party risk management for critical payment operators. Frankfurt and Berlin concentrate scheme compliance expertise and cloud-native core banking development.
Singapore
PayNow links domestic instant payments to Thailand's PromptPay and Malaysia's DuitNow through bilateral national scheme agreements. The Monetary Authority of Singapore licenses payment institutions under frameworks that enable non-bank platform participation. The city-state's financial district anchors Southeast Asian cross-border corridor development and foreign-exchange overlay services.
RTP Market Competitive Environment
Global majors compete with regional champions across scheme operation and core banking software, producing a tiered structure where network operators, infrastructure vendors, and fintech platforms occupy distinct value positions. Consolidation pressures concentrate among payment processors seeking 24/7 availability capabilities. Dominant archetypes include central bank-sponsored scheme operators, legacy core banking modernizers, and API-native overlay service builders. Strategic moves center on cross-border correspondent partnerships and embedded finance integration.
Within the scheme operator tier, The Clearing House and Federal Reserve (FedNow Service) anchor North American real-time rail development, representing divergent governance models—private consortium versus public infrastructure. ACI Worldwide Inc. and Fiserv Inc. exemplify the infrastructure software archetype, with the former leveraging global messaging expertise across multiple domestic schemes and the latter sustaining merchant-facing relevance through acquiring technology integration. These three entities collectively illustrate how technical specialization and regulatory relationships determine competitive position without requiring proprietary settlement account maintenance.
| Leading Market Players |
|---|
| Mastercard Inc. |
| The Clearing House |
| ACI Worldwide Inc. |
| Form3 |
| Federal Reserve (FedNow Service) |
| Fiserv Inc. |
| Montran Corporation |
| Square Inc. |
| PayPal Holdings Inc. |
| Others |
Value Chain & Pricing Dynamics
Core banking modernization divides into cloud-native premium deployments and legacy-overlay economy tiers, with the former bundling 24/7 uptime guarantees and ISO 20022 message mapping services while the latter strips out implementation support to hit price points accessible to regional banks. This bifurcation concentrates vendor margins in the premium tier where talent scarcity props pricing power, while supply chain configuration favors vendors with pre-built integrations to FedNow and The Clearing House rails.
Pricing Analysis
Implementation support bundling separates full-service deployment packages from software-only licenses, with premium tiers incorporating dedicated ISO 20022 mapping engineers and regulatory compliance guidance. Price differentiation rests on cloud residency certification and pre-certified connections to national instant payment schemes. Cost compression in the mid-market tier is intensifying because fintech platforms are commoditizing API gateway functionality. Corporate treasury departments at mid-tier banks show highest price sensitivity, while money-center institutions prioritize speed-to-market over license economics.
Supply Chain Analysis
Cross-border data center provisioning costs are reshaping vendor economics as European Digital Operational Resilience Act compliance demands regional cloud presence. Software development concentrates in India, the United States, and Ireland, with Bengaluru and Dublin hosting dense engineering clusters for payment scheme integration. Talent pipelines draw from computer science programs at Indian Institutes of Technology and specialized fintech academies in Singapore. Single-source vulnerability sits with cloud hyperscalers certified for financial services workloads. Distribution runs through direct enterprise sales teams and systems integrators like Accenture and IBM for complex core replacements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Real-time payment infrastructure operates under acute cloud-certified engineering scarcity, with ISO 20022 expertise commanding compensation premiums that prop vendor pricing and constrain implementation timelines at regional banks.
For Market Incumbents: To counter fintech platform disintermediation, incumbent core banking vendors should embed request-to-pay and embedded finance modules natively rather than via partner marketplaces, while securing exclusive certification partnerships with emerging national instant payment schemes in Southeast Asia and Latin America to lock out overlay competitors. For New Entrants and Emerging Players: Enter via cross-border foreign-exchange overlay services linking Singapore's PayNow to Thailand's PromptPay and Malaysia's DuitNow, where regulatory harmonization outpaces vendor supply. The most penetrable segment is mid-market corporate treasury departments in the United Kingdom seeking multi-bank aggregation without correspondent fees. A B2B SaaS pricing model with usage-based tiers aligns with procurement patterns at finance-shared-service centers. For Investors and Strategic Acquirers: Re-rating potential sits with API-native overlay service builders given open banking mandate expansion across Brazil, Singapore, and the European Union as the catalyst compressing customer acquisition costs. Long-term viability favors vendors with pre-built connections to three or more national instant payment schemes. The signal to watch is bilateral scheme linkage announcements between central banks, which typically precede 18-24 month implementation windows.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 20022 Certification Investment | Pre-built message mapping to FedNow and TARGET Instant Payment Settlement accelerates bank onboarding timelines. |
| Cloud-Native Core Banking Migration | Elastic capacity supports 24/7 transaction spikes without capital-intensive mainframe procurement cycles. |
| Cross-Border Scheme Linkage Partnership | Bilateral agreements between Singapore's PayNow and Thailand's PromptPay open foreign-exchange overlay opportunities. |
| Request-to-Pay Module Development | Structured invoice presentment within ISO 20022 enables B2B treasury automation unavailable in batch ACH. |
| Embedded Finance API Integration | Non-bank platforms in Southeast Asia embed instant payment initiation into ride-hailing and e-commerce workflows. |
Study Parameters
SEC filings from ACI Worldwide and Fiserv, SWIFT annual reviews, and Reserve Bank of India payment system reports formed the secondary backbone, cross-referenced against primary interviews with payment scheme operators, core banking software architects, and corporate treasury directors at mid-tier US banks. Bottom-up modeling triangulated vendor-reported transaction volumes with top-down central bank settlement data to anchor market sizing.
Historical trendline analysis tracked adoption curves from Faster Payments in the United Kingdom and UPI in India to parameterize diffusion rates for newer schemes. The analytical framework modeled solution type, end-user category, technology stack, and application use case across the projection horizon, with CAGRs derived from regression against GDP growth and payment digitization indices. Forecast inputs included central bank instant payment scheme launch timelines and open banking regulatory mandate schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt shifts in central bank liquidity requirements or cloud service provider certification withdrawals. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Ethernet Backhaul Equipment Market
Network Technology
Global Deep Packet Inspection and Processing Market
Network Technology
Middle East & Africa Video Conferencing Hardware Market
Network Technology
Global Network Monitoring Market
Network Technology
Cloud Gateway Module Market
Network Technology
GCC Set-Top Box Market
Network Technology
Mobile Backhaul Market
Network Technology
Managed MPLS Market
Network Technology
Wi-Fi Extender Market
Network Technology
Optical Networking Market
Network Technology
Europe Private 5G Network Market
Network Technology
Wi-Fi 6E Router Market
Network Technology
Global Passive Optical Network (PON) Equipment Market
Network Technology
Global Enterprise Session Border Controller (SBC) Market
Network Technology
Service Provider Network Infrastructure Market
Network Technology
Global Intelligent Network Market