
 Global Textile Dyes Market | 2026-2036
Global Textile Dyes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Textile Dyes Market Foresight
Fast-fashion sourcing is collapsing as technical textile buyers and automotive suppliers expand their share of dye procurement. Archroma leverages its specialty chemical portfolio to serve performance-driven segments with lower water-consumption formulations. Huntsman International LLC anchors North American supply through its broad reactive and disperse dye ranges. Zhejiang Longsheng Group Co. Ltd dominates bulk vat and sulfur dye production from its integrated Zhejiang facilities.
Textile dyes are colorant compounds, typically azo-anthraquinone or phthalocyanine based, designed to bond with natural and synthetic fibers through exhaustion, padding, or digital inkjet application at specified temperature and pH parameters. Their primary purpose is to impart color fastness, uniformity, and regulatory compliance to fabrics destined for consumer and industrial end-uses. Reactive dyes lead volume globally because cotton-dominant apparel manufacturing still commands the largest dye off-take, while disperse dyes represent the fastest-expanding structural pool as polyester recycling loops and automotive fabric requirements multiply. Acid dyes occupy a mature, margin-defended niche in wool and silk upholstery production where premium pricing persists.
EPA effluent guidelines in the United States, REACH chemical restrictions in Europe, and ZDHC Manufacturing Restricted Substances List compliance are elevating formulation costs while disqualifying legacy dye chemistries from major brand supply chains. India's Central Pollution Control Board mandates zero liquid discharge for larger dye houses, compressing capacity among non-compliant operators. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and locked capital in non-conforming chemistries.
Market Dynamics
REACH chemical restrictions and ZDHC Manufacturing Restricted Substances List compliance are systematically disqualifying legacy azo-dye chemistries from major brand supply chains, forcing dyehouses to absorb elevated formulation costs or exit the market entirely.
Growth Catalysts
- Polyester recycling infrastructure:Mechanical and chemical recycling loops for polyethylene terephthalate are generating fresh demand for disperse dyes compatible with post-consumer feedstock streams.
- Automotive interior specifications:Technical textile producers serving BMW, Mercedes-Benz, and Tesla are expanding procurement of high-performance dyes with thermal stability above 120°C for seat fabric applications.
- India's zero liquid discharge mandate:The Central Pollution Control Board's enforcement is compressing capacity among non-compliant operators, concentrating volume in integrated Gujarat and Tamil Nadu clusters with captive effluent treatment.
Market Restraints
- Petroleum-based feedstock volatility:Naphtha and benzene derivative costs for anthraquinone intermediates fluctuate with crude oil indices, compressing margin predictability for vat and disperse dye producers.
- Intermediate supply concentration:China dominates global production of dye intermediates including H-acid and J-acid, creating single-source vulnerability for formulators outside integrated Asian supply chains.
- Water intensity thresholds:Conventional reactive dyeing consumes 100-150 liters per kilogram of cotton, exceeding sustainability benchmarks set by ZDHC and limiting access to brand-tier contracts.
Strategic Opportunities
- Digital inkjet penetration in Turkey:The country's denim and home textile exporters are retrofitting flatbed and single-pass inkjet systems, creating demand for pigment ink formulations with reactive-dye color gamut.
- EU Green Deal public procurement:Member state tender rules mandating EU Ecolabel compliance for institutional textile purchases are creating preferential market access for certified dye suppliers.
- Bio-based indigo fermentation:Microbial synthesis pathways from sugar feedstock are converging with enzymatic dyeing processes, offering route to petroleum-independent denim coloration.
Industry Challenges
- Colorimetric expertise scarcity:Formulation chemists capable of matching spectral data across substrate blends are retiring faster than training programs in Germany and Italy can replace them.
- Multi-certification stacking:Simultaneous compliance with OEKO-TEX Standard 100, GOTS, and bluesign requirements demands redundant testing budgets and extended approval timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Textile Dyes Market |
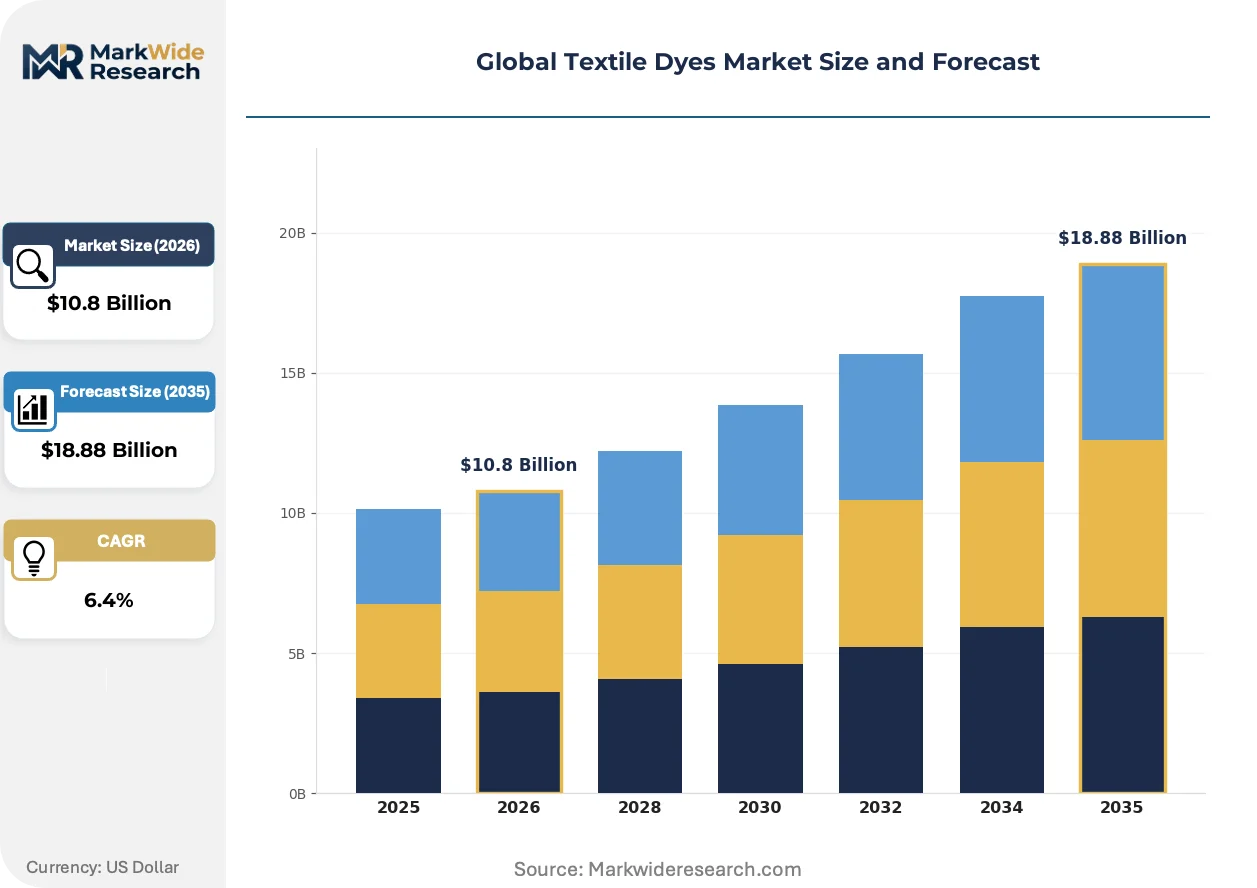
| Market Size in 2026 | $10.8 Billion |
| Market Size in 2035 | $18.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reactive Dyes, Disperse Dyes, Acid Dyes, Direct Dyes, Vat Dyes, Sulfur Dyes Application: Apparel Manufacturing, Upholstery Production, Automotive Fabrics, Technical Textiles, Footwear Materials, Industrial Fabrics End User Industry: Garment Manufacturers, Interior Furnishing Firms, Automotive Suppliers, Sports Equipment Producers, Footwear Companies, Industrial Goods Makers Form: Powder, Liquid, Paste, Granular, Concentrate, Slurry |
| Companies Covered | Archroma, Lanxess AG, Huntsman International LLC, Atul Ltd, Kiri Industries Ltd, Zhejiang Longsheng Group Co. Ltd, Zhejiang Runtu Co. Ltd, DyStar Singapore Pte Ltd, Organic Dyes and Pigments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Textile Dyes Market Shifts & Advancements
Supercritical carbon dioxide dyeing is transitioning from pilot installations to commercial-scale deployment, while regulatory chemistry restrictions and buyer procurement consolidation are simultaneously reshaping competitive positioning across formulation tiers.
Digital pigment ink formulation is bifurcating the coloration technology stack. These water-free systems bond pigment particles to fiber surfaces through resin binders, eliminating effluent discharge entirely. Technical textile producers in Germany and Japan are adopting single-pass inkjet systems at accelerating pace. The technology is bifurcating market structure between high-capacity conventional dyehouses and agile, short-run digital service providers.
REACH Annex XVII restrictions on carcinogenic aromatic amines derived from azo dyes are tightening permissible thresholds across EU member states. Industrial consequence includes mandatory reformulation of black and navy colorways that previously relied on disazo chemistry. Apparel brands sourcing from Bangladesh and Vietnam dyehouses are now requiring third-party amine-testing certificates as standard purchase order terms.
Buyer consolidation among multi-brand retail groups is compressing supplier rosters and extending payment terms. Inditex, H&M, and Fast Retailing are centralizing dye procurement through nominated supplier lists, displacing spot-market purchasing. This concentration is most visible in South India, where Tiruppur knitwear exporters report 40% reduction in active chemical supplier relationships since 2020.
Global Textile Dyes Market Segmentation
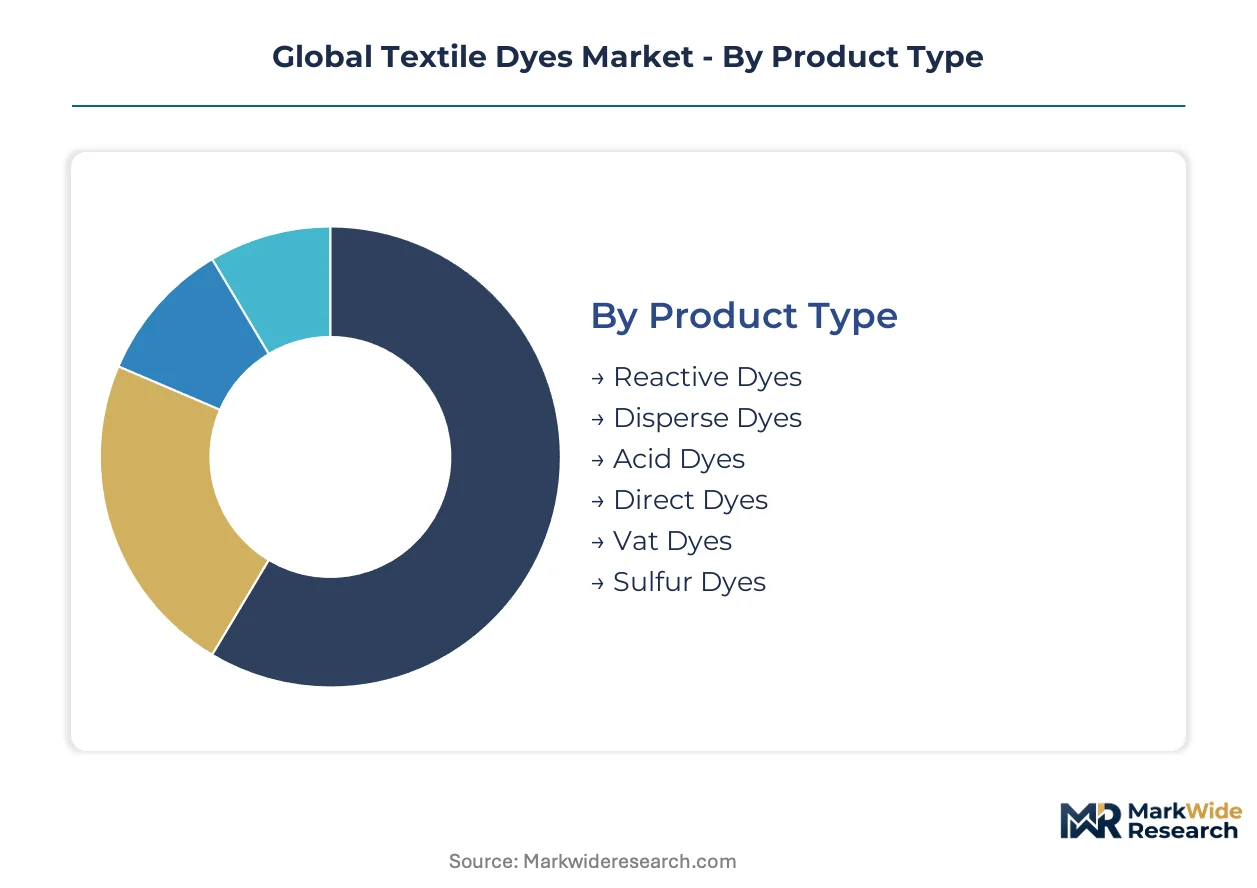
Segmentation in textile dyes reveals how regulatory chemistry restrictions and end-use performance requirements partition value capture across formulation tiers. Buyers select dye categories based on substrate compatibility, effluent compliance, and brand-tier certification requirements rather than commodity pricing alone.
Product Type:
REACH Annex XVII restrictions on carcinogenic aromatic amines and ZDHC MRSL compliance thresholds differentiate permissible chemistries across this category, elevating reformulation costs for legacy azo-based products.
- Reactive Dyes:These azo-anthraquinone compounds form covalent bonds with cellulose fibers through nucleophilic substitution at alkaline pH. Cotton-dominant apparel manufacturing in India and Bangladesh consumes the largest dye off-take, though water intensity of 100-150 liters per kilogram constrains access to ZDHC-compliant brand contracts.
- Disperse Dyes:Low-water-soluble anthraquinone and azo structures designed for hydrophobic synthetic fibers at high-temperature exhaustion. Polyester recycling infrastructure and automotive interior specifications for thermal stability above 120°C are expanding procurement faster than any other structural pool.
- Acid Dyes:Sulfonated azo and anthraquinone variants for protein fibers.
- Direct Dyes:Azo-based structures for cotton without mordant requirements.
- Vat Dyes:Indigoid and anthraquinone insoluble pigments applied via reduction-oxidation.
- Sulfur Dyes:Condensed thiazine structures for cost-sensitive cotton coloration.
Reactive dyes handle the majority of throughput; disperse dyes are the fastest mover on share.
Application:
Cost tier differentiation separates commodity volume applications from premium-margin technical segments where formulation expertise commands pricing power.
- Apparel Manufacturing:Cotton and polyester garment coloration at massive scale.
- Upholstery Production:Wool and silk residential furniture fabric dyeing with premium color fastness requirements.
- Automotive Fabrics:Technical textile specifications from BMW, Mercedes-Benz, and Tesla demand thermal stability above 120°C for seat fabric applications, with thermal aging resistance and low fogging properties mandatory for supplier qualification.
- Technical Textiles:High-performance industrial fabrics for filtration, geotextiles, and medical applications where regulatory compliance and functional performance converge to create the steepest expansion trajectory in procurement value.
- Footwear Materials:Leather alternatives and synthetic upper coloration.
- Industrial Fabrics:Conveyor belts, tarpaulins, and protective equipment.
Apparel manufacturing absorbs the largest dye volumes; technical textiles deliver the fastest value expansion.
End User Industry:
Customer type fragmentation concentrates procurement power among consolidated retail groups while dispersing spot demand across specialized industrial buyers.
- Garment Manufacturers:Tiruppur knitwear exporters and Bangladesh woven apparel producers.
- Interior Furnishing Firms:Residential and contract furniture textile specialists.
- Automotive Suppliers:Tier-1 seating and interior trim manufacturers serving European and North American OEMs with nominated supplier lists and extended qualification timelines.
- Sports Equipment Producers:Performance apparel and gear manufacturers with bluesign and OEKO-TEX certification requirements compressing supplier rosters.
- Footwear Companies:Athletic and fashion shoe producers.
- Industrial Goods Makers:B2B technical textile purchasers.
Garment manufacturers represent the largest customer base; automotive suppliers are climbing the fastest on procurement sophistication.
Form:
Supply concentration in powder and liquid formats reflects manufacturing scale economies, while paste and concentrate variants serve niche digital and automated application systems.
- Powder:Standardized dry formulations for bulk dissolution.
- Liquid:Pre-dissolved concentrates for automated dosing systems in high-volume dye houses.
- Paste:High-solids dispersions for padding and continuous dyeing.
- Granular:Low-dust handling forms for occupational safety compliance.
- Concentrate:Reduced-water formulations for effluent-constrained operations.
- Slurry:Aqueous pigment suspensions for digital inkjet and pigment bonding systems without thermal fixation requirements.
Powder and liquid forms dominate manufacturing throughput; slurry formulations are expanding most quickly alongside digital inkjet penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports disperse dye intermediates to European automotive textile suppliers while India ships reactive dye formulations to Bangladesh garment manufacturers. This bilateral trade structure concentrates procurement power in integrated Asian supply chains.
China
Zhejiang and Jiangsu provinces host anthraquinone intermediate production for disperse dye synthesis. The Ministry of Ecology and Environment enforces dual carbon goals that cap emissions from dye manufacturing facilities. Shaoxing textile cluster operators are retrofitting effluent treatment systems to maintain export eligibility under EU REACH compliance.
India
Gujarat and Tamil Nadu absorb the largest reactive dye volumes for cotton knitwear and woven apparel exports. The Central Pollution Control Board mandates zero liquid discharge for dye houses above specified capacity thresholds. Tiruppur exporters have reduced active chemical supplier relationships by 40 percent since 2020 as procurement consolidates around nominated vendor lists.
Germany
Automotive interior fabric specifications from BMW and Mercedes-Benz drive demand for thermally stable disperse dyes above 120°C. The EU Green Deal public procurement rules mandate EU Ecolabel compliance for institutional textile purchases. Baden-Württemberg technical textile producers are qualifying bluesign-certified dye suppliers for seating applications.
United States
EPA effluent guidelines restrict aromatic amine discharge from reactive dye operations serving domestic apparel brands. Huntsman International LLC anchors North American supply through broad reactive and disperse dye ranges. Southeast textile belt manufacturers face compliance cost elevation as state-level water quality standards tighten beyond federal baselines.
Turkey
Denim and home textile exporters are retrofitting flatbed and single-pass inkjet systems for digital pigment ink application. The country's national environmental regulator enforces industrial wastewater standards that parallel EU directive thresholds. Bursa and Istanbul dye houses are investing in slurry formulation capacity to serve pigment bonding systems without thermal fixation requirements.
Global Textile Dyes Market Competitive Landscape
Listed leaders compete with private specialists across formulation tiers and geographic coverage. The vendor base separates into three structural tiers: integrated multinational chemical conglomerates with broad reactive and disperse portfolios, mid-cap regional formulators serving nominated supplier lists, and specialty digital inkjet pigment suppliers. Strategic moves concentrate on backward integration into intermediate production and technology licensing for supercritical carbon dioxide dyeing systems.
Within the multinational tier, Archroma and Huntsman International LLC exemplify scale-driven positioning across performance-driven segments. Zhejiang Longsheng Group Co. Ltd anchors bulk vat and sulfur dye production from its integrated Zhejiang facilities. DyStar Singapore Pte Ltd occupies a specialist position in digital inkjet and pigment dispersion formulations for water-free coloration systems.
| Leading Market Players |
|---|
| Archroma |
| Lanxess AG |
| Huntsman International LLC |
| Atul Ltd |
| Kiri Industries Ltd |
| Zhejiang Longsheng Group Co. Ltd |
| Zhejiang Runtu Co. Ltd |
| DyStar Singapore Pte Ltd |
| Organic Dyes and Pigments |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between European automotive textile suppliers and Asian dye manufacturers lock in both supply access and price visibility, insulating qualified vendors from naphtha feedstock volatility while compressing margins for spot-market participants.
Pricing Analysis
Current-generation reactive dye formulations command premium positioning over legacy azo-based chemistries facing REACH Annex XVII disqualification, while next-generation supercritical CO2 and digital pigment systems occupy emerging price tiers above conventional exhaustion methods. Three-tier pricing structure across premium, standard, and economy levels separates bluesign-certified automotive grades from commodity apparel formulations and sulfur-dye cost tiers. Price differentiation hinges on certification grade and volume scale, with ZDHC MRSL compliance adding formulation cost premiums. Cost compression in standard-tier reactive dyes is intensifying because water-intensity benchmarks disqualify conventional chemistries from brand-tier contracts. Garment manufacturers in Bangladesh and Vietnam exhibit highest price sensitivity, while automotive suppliers serving BMW and Mercedes-Benz demonstrate lowest sensitivity due to thermal stability specifications above 120°C.
Supply Chain Analysis
Inventory buffers for H-acid and J-acid intermediates stretch lead times when Chinese environmental inspections interrupt Zhejiang and Jiangsu production, forcing formulators to pre-position stock ahead of peak automotive procurement cycles. Geographic supply concentrates in China for anthraquinone intermediates, India for reactive dye formulation, and Germany for automotive-grade disperse dye finishing. Raw material dependencies draw from petroleum-derived naphtha and benzene, sugar-based fermentation feedstocks for bio-indigo, and imported sulfonated intermediates. Single-source vulnerability from China's dominance of dye intermediate production creates supply chain risk for non-integrated formulators. Distribution runs through nominated supplier lists controlled by Inditex, H&M, and Fast Retailing, displacing spot-market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards defensive moats built on regulatory entrenchment, where REACH and ZDHC compliance investments create switching costs that lock automotive and technical textile buyers into qualified supplier relationships.
For Market Incumbents: Compound defensive positioning by deepening backward integration into H-acid and J-acid intermediate production in Zhejiang or Gujarat to offset single-source vulnerability, while extending bluesign and OEKO-TEX certification coverage to capture procurement consolidation among multi-brand retail groups. The priority lever centers on capacity rationalization: exit non-compliant legacy chemistries before stranded inventory accumulates under tightening EU aromatic amine thresholds. For New Entrants and Emerging Players: Differentiate on water-free coloration technology, specifically digital pigment ink formulations and supercritical CO2 dyeing systems where incumbent chemical portfolios lack coverage. Turkey's denim and home textile exporters retrofitting flatbed inkjet systems represent the most penetrable geography, with slurry formulation partnerships offering lowest capital entry path. Target automotive technical textile specifications from Tesla and emerging EV manufacturers not yet locked into incumbent nominated supplier lists. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialty chemical formulators with automotive OEM qualifications, where thermal stability specifications above 120°C create multi-year contract visibility. Acquisition target archetype: mid-cap regional formulators in India or Turkey with zero liquid discharge compliance and digital inkjet pigment capabilities. Watch bio-based indigo fermentation cost curves as inflection indicator for petroleum-independent denim coloration viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Intermediate Production | Captive H-acid supply from Zhejiang facilities insulates Huntsman and Archroma from Chinese environmental shutdowns. |
| Zero Liquid Discharge Compliance Investment | Gujarat and Tamil Nadu clusters with captive effluent treatment consolidate volume as CPCB enforcement compresses non-compliant capacity. |
| Digital Inkjet Pigment Formulation Partnership | Turkey's Bursa dye houses gain access to water-free coloration systems without thermal fixation requirements. |
| Supercritical CO2 Dyeing Technology Licensing | German technical textile producers in Baden-Württemberg eliminate effluent discharge entirely for automotive seating applications. |
| EU Ecolabel Certification Program | Member state tender rules create preferential market access for institutional textile purchases across Germany and France. |
Research Methodology
The analysis maps reactive, disperse, acid, vat, and sulfur dye sub-sectors, each validated through plant managers at integrated dye houses, procurement leads at automotive Tier 1 suppliers, technical R&D directors at specialty chemical formulators, and distribution channel partners across Asian supply chains. Primary interview data triangulates against customs and trade flow records, ACC and Cefic chemical industry reports, SEC 10-K filings from listed dye manufacturers, and ZDHC MRSL compliance databases. Bottom-up volume estimates from individual production facilities reconcile with top-down demand aggregation across end-use industries.
Consistency checks validate volume and value outputs against external benchmarks including regional production capacity disclosures, intermediate consumption patterns, and brand-tier procurement volumes reported by nominated supplier lists. The analytical framework models segmentation across dye chemistry type, substrate compatibility, application method, certification tier, and regional production hub throughout the forecast period. CAGRs derive from regression analysis of historical volume trajectories adjusted for regulatory phase-out schedules and technology substitution curves. Forecast inputs incorporate polyester recycling infrastructure buildout rates and automotive interior specification evolution from European and North American OEMs.
Forecasts assume regulatory continuity in EU REACH, ZDHC MRSL, and India's CPCB zero liquid discharge regimes; material policy shifts would require re-modeling. Outputs reflect assumptions regarding feedstock cost stability, intermediate supply reliability, and certification adoption timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Chemicals, Dyes, and Finishing
Dry Cleaning Solvent for Clothes Market
Textile Chemicals, Dyes, and Finishing
Textile Chemicals Market
Textile Chemicals, Dyes, and Finishing
Leak Detection Dyes Market
Textile Chemicals, Dyes, and Finishing
Textile Leveling Agent Market
Textile Chemicals, Dyes, and Finishing
Textile Transfer Paper Market
Textile Chemicals, Dyes, and Finishing
Europe Textile Dyes Market
Textile Chemicals, Dyes, and Finishing
Dyes Market
Textile Chemicals, Dyes, and Finishing
Functional Textile Finishing Chemicals Market
Textile Chemicals, Dyes, and Finishing
Textile Finishing Agents Market
Textile Chemicals, Dyes, and Finishing
Lining Fabric Market
Textile Chemicals, Dyes, and Finishing
Dye Sublimation Printing Market
Textile Chemicals, Dyes, and Finishing
Global Textile Colorant Market
Textile Chemicals, Dyes, and Finishing
Laminated Fabrics Market
Textile Chemicals, Dyes, and Finishing
Textile Wax Market
Textile Chemicals, Dyes, and Finishing
Functional Textile Finishing Agents Market
Textile Chemicals, Dyes, and Finishing
FD and C Dyes Market