
 Nonwoven Industrial Membrane Market | 2026-2036
Nonwoven Industrial Membrane Market Size, Share, and Industry Trends Forecast 2026-2036
Nonwoven Industrial Membrane Market Intelligence
Buyer concentration among municipal water treatment utilities is realigning procurement standards toward longer-life membrane modules. Freudenberg Group leverages its spunbond expertise to dominate European industrial filtration contracts. Ahlstrom-Munksjö anchors North American healthcare membrane supply through sustained FDA-compliant manufacturing scale. DuPont differentiates via fluoropolymer composite technology leadership in high-temperature separation applications.
Nonwoven industrial membranes are engineered sheet structures manufactured through spunbond, meltblown, needlepunch, or wetlaid processes from thermoplastic polymers such as polypropylene and polyester, designed to perform selective separation or barrier functions under mechanical stress and chemical exposure. Their primary industrial purpose spans liquid filtration, gas separation, geotechnical stabilization, and sterile barrier protection. Polypropylene dominates material-type value pools due to its chemical inertness and cost efficiency in water treatment end uses. Meltblown manufacturing commands premium positioning within filtration applications where sub-micron retention specifications determine product substitution patterns. Medical application demand tracks hospital infection control budgets and single-use surgical protocol adoption across OECD healthcare systems.
EPA effluent limitation guidelines and REACH substance restrictions are reshaping material qualification requirements for membrane producers seeking multi-jurisdiction market access. FDA 21 CFR compliance for medical-grade nonwovens and ISO 10993 biocompatibility testing create tiered certification barriers that filter supplier participation in regulated segments. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions in the European Union and corresponding state-level rulemaking in the United States to anticipate forced material transitions and qualification timeline compression.
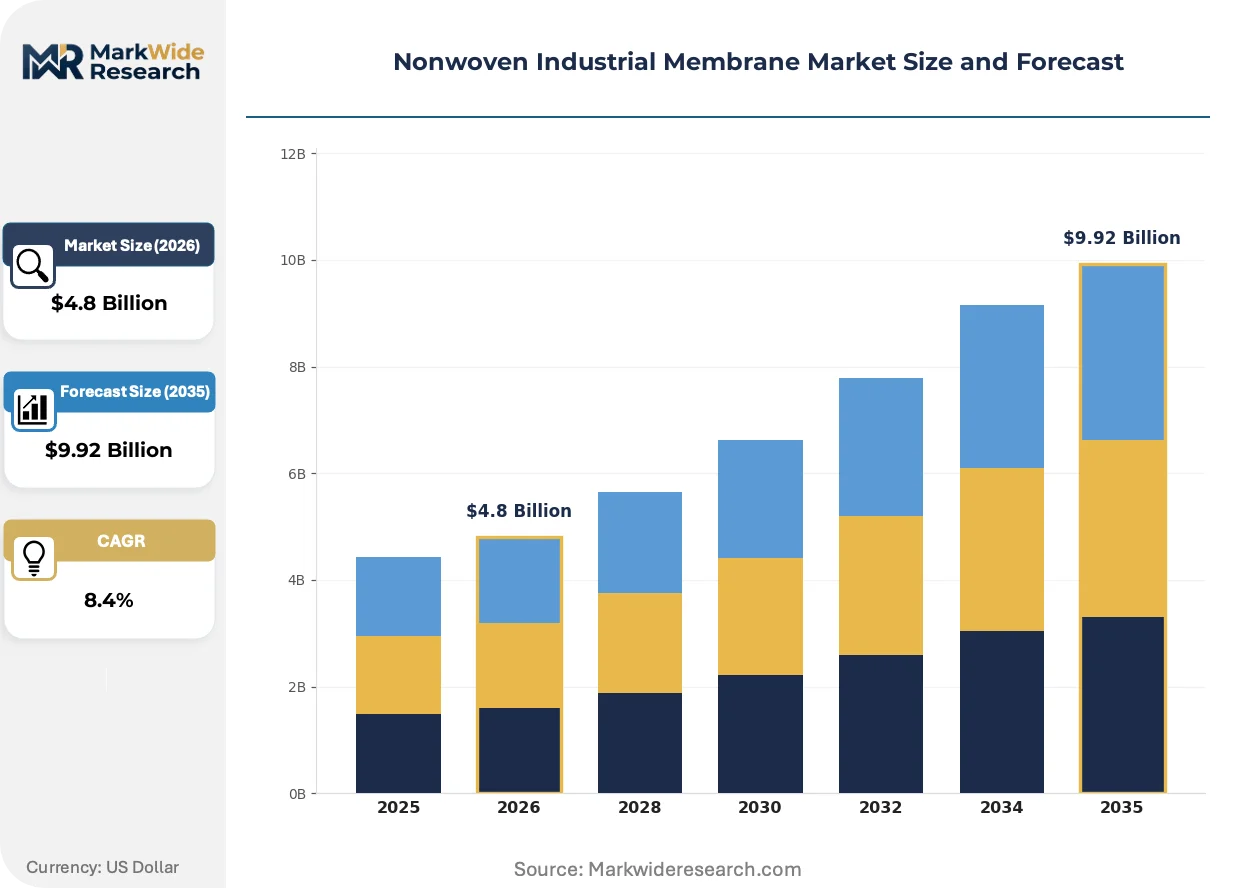
Market Dynamics
Membrane bioreactor deployment in Asia-Pacific water treatment utilities is compressing procurement cycles and forcing material qualification timelines toward polypropylene and fluoropolymer composites.
Growth Catalysts
- EPA Effluent Limitation Guidelines:Stricter discharge standards in United States municipal systems are mandating sub-micron retention capabilities that favor meltblown polypropylene membranes over conventional filtration media.
- Membrane Bioreactor Technology:China's industrial corridor zones around Shanghai and Jiangsu province are scaling MBR installations for textile and chemical wastewater treatment, creating sustained demand for chemically inert separation media.
- REACH Substance Restrictions:European chemical compliance requirements are accelerating substitution away from legacy fluorinated materials toward polyester and polypropylene nonwovens in industrial filtration applications.
Market Restraints
- Fluoropolymer Feedstock Concentration:Supply of high-performance fluoropolymer resins concentrates among a limited set of chemical producers, exposing membrane manufacturers to input cost volatility and allocation constraints.
- Per- and Polyfluoroalkyl Substance Bans:Evolving EU restrictions on PFAS compounds and corresponding state-level rulemaking in the United States are forcing premature material transitions and stranding qualified product inventories.
- Technical Performance Ceilings:Polypropylene membranes face temperature and oxidation resistance limitations that constrain substitution potential in high-temperature industrial separation applications above 80°C operating thresholds.
Strategic Opportunities
- India's Central Pollution Control Board Mandates:Stricter effluent standards for pharmaceutical and textile clusters in Gujarat and Tamil Nadu are opening demand for membrane bioreactor systems in underpenetrated industrial zones.
- Electrospun Nanofiber Convergence:Hybrid manufacturing processes combining meltblown substrate stability with electrospun surface layers are enabling sub-micron retention specifications previously reserved for ceramic membranes.
- ISO 10993 Biocompatibility Certification:Medical-grade membrane demand tracks hospital infection control budgets across OECD healthcare systems, creating premium positioning for FDA-compliant manufacturers with validated sterile barrier protocols.
Industry Challenges
- Multi-Jurisdiction Qualification Timelines:Simultaneous EPA, REACH, and FDA compliance requirements compress product development cycles and strain regulatory affairs capacity at mid-scale membrane producers.
- Specialized Polymer Processing Expertise:Spunbond and meltblown process optimization for sub-micron fiber diameters requires polymer rheology and die design capabilities that concentrate among a narrow technical talent pool.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nonwoven Industrial Membrane Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.92 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polypropylene, Polyester, Polyethylene, Nylon Manufacturing Process: Spunbond, Meltblown, Needlepunch, Wetlaid Application: Filtration, Geotextiles, Hygiene, Medical End User: Construction, Automotive, Healthcare, Agriculture |
| Companies Covered | Freudenberg Group, Ahlstrom-Munksjö, Berry Global Inc., Toray Industries, Fitesa, DuPont, Johns Manville Corporation, Asahi Kasei Corporation, 3M Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nonwoven Industrial Membrane Market Strategic Shifts & Innovations
Electrospinning and nanofiber layering techniques are fragmenting traditional technology hierarchies in industrial membrane manufacturing. Regulatory pressure on fluorinated materials is accelerating material science investment. Buyer consolidation among municipal utilities is reshaping vendor qualification protocols.
Electrospun nanofiber surface modification is decentralizing performance benchmarks across liquid filtration applications. The technology deposits ultrafine fiber layers onto spunbond or meltblown substrates, achieving sub-micron retention without ceramic membrane brittleness. Municipal water treatment utilities in Germany and Japan are piloting these hybrid structures for membrane bioreactor retrofits. The approach is decentralizing supply chains by enabling regional nonwoven producers to compete with established fluoropolymer specialists.
REACH substance restrictions are forcing material portfolio reconstitution across European membrane supply chains. ECHA regulatory proposals targeting per- and polyfluoroalkyl substances are compressing qualification timelines for alternative chemistries. Industrial filtration contracts in the Netherlands and Belgium now require PFAS-free certification, pushing membrane producers toward silicone and polyester composite development. German automotive and chemical end-users are accelerating supplier audits to lock in compliant material streams before restriction deadlines.
Outcome-based service contracting is displacing unit sales in large-scale water treatment procurement. Municipal utilities in Australia and Singapore are unbundling membrane module supply from performance-guaranteed operating contracts. This model transfers fouling risk and replacement scheduling to membrane suppliers, compressing margins for producers without predictive analytics capabilities. Korean and Taiwanese semiconductor manufacturers are replicating this structure for ultrapure water systems, favoring vendors with captive technical service networks.
Nonwoven Industrial Membrane Market Segmentation
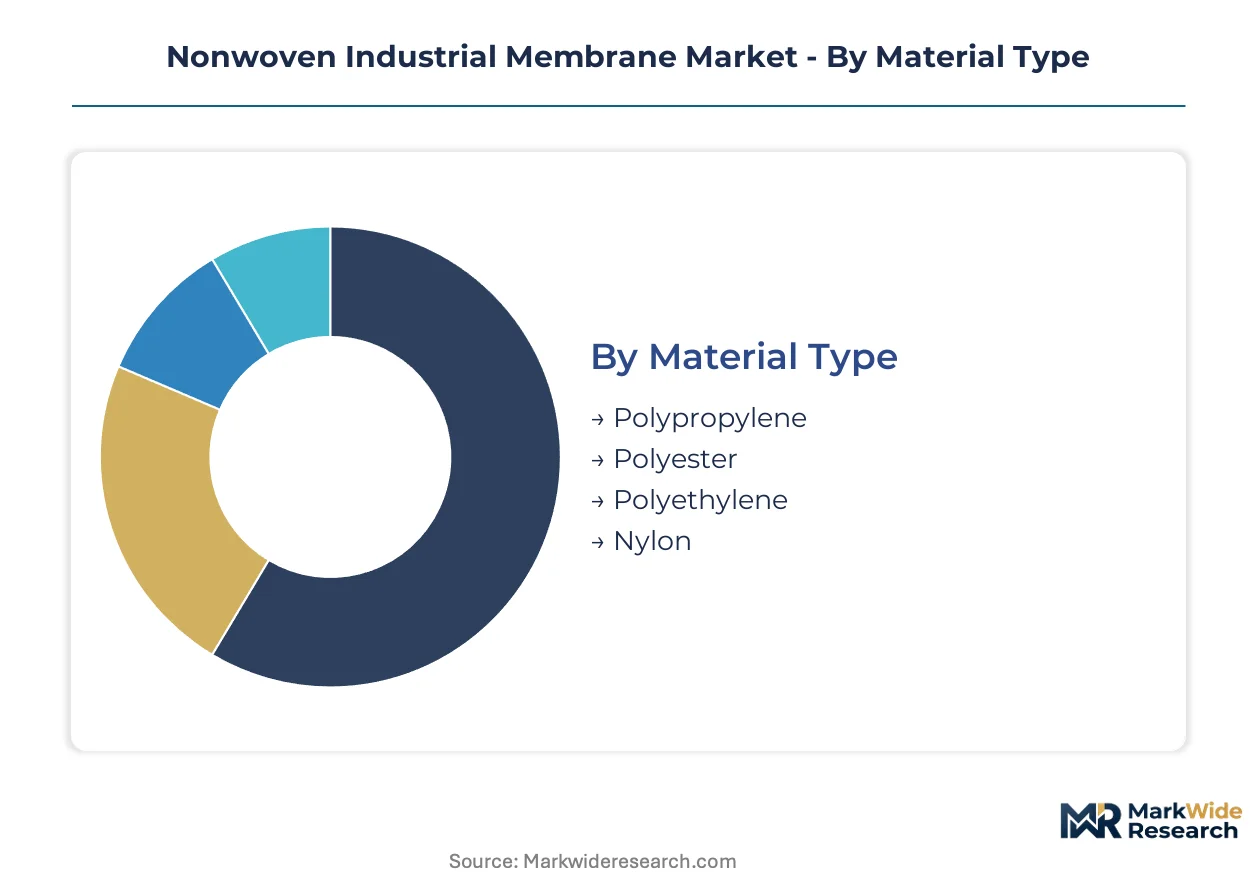
Nonwoven industrial membrane procurement diverges sharply between standalone module replacements and embedded system integrations. Material selection and manufacturing process choices determine compatibility with existing infrastructure, creating distinct commercial pathways for retrofit versus greenfield deployments.
Material Type:
Polypropylene dominates standalone filtration module sales, while polyester and fluoropolymer composites concentrate in embedded high-temperature systems.
- Polypropylene:Thermoplastic polymer with exceptional chemical inertness and cost efficiency. Municipal water treatment utilities in China's Jiangsu province specify this material for membrane bioreactor retrofits due to EPA-aligned sub-micron retention requirements.
- Polyester:Higher oxidation resistance and dimensional stability under thermal stress. REACH-compliant industrial filtration contracts in the Netherlands and Belgium are accelerating substitution toward polyester composites as PFAS restrictions strand fluoropolymer inventories.
- Polyethylene:Lower cost barrier for geotechnical stabilization and secondary containment applications where chemical exposure remains moderate.
- Nylon:Superior abrasion resistance in mechanical filtration environments with high solids loading, though moisture absorption limits hydrophilic deployment.
Polypropylene leads volumes today; polyester is gaining share fastest.
Manufacturing Process:
Process selection maps directly to retention specification tiers, with premium sub-micron capabilities commanding embedded system positions.
- Meltblown:Deposits ultrafine fibers achieving sub-micron retention without ceramic brittleness. German municipal utilities pilot hybrid meltblown-electrospun structures for membrane bioreactor retrofits, displacing traditional fluoropolymer specialists.
- Spunbond:Delivers structural integrity for high-throughput liquid filtration and geotextile stabilization. Freudenberg Group leverages this expertise to dominate European industrial filtration contracts requiring mechanical durability.
- Needlepunch:Mechanical entanglement produces thick, permeable structures for drainage and erosion control in civil engineering applications.
- Wetlaid:Enables uniform fiber distribution for medical-grade sterile barriers where FDA 21 CFR compliance mandates consistent pore structure.
Meltblown commands premium positioning; wetlaid shows steepest expansion trajectory in medical applications.
Application:
Application segmentation reflects divergent certification burdens, with regulated medical and filtration segments separating from commodity geotextile deployment.
- Filtration:Liquid and gas separation media for industrial process streams and municipal water treatment. India's Central Pollution Control Board mandates in Gujarat pharmaceutical clusters are opening membrane bioreactor demand for chemically inert separation media.
- Medical:Sterile barrier protection and single-use surgical protocols. ISO 10993 biocompatibility certification creates tiered barriers filtering supplier participation in OECD healthcare systems.
- Geotextiles:Soil stabilization, drainage, and erosion control in civil infrastructure where specification standards remain less stringent than regulated segments.
- Hygiene:Absorbent cores and fluid management layers in personal care products, tracking consumer packaged goods volume cycles.
Filtration anchors revenue concentration; medical is climbing the fastest on infection control budget expansion.
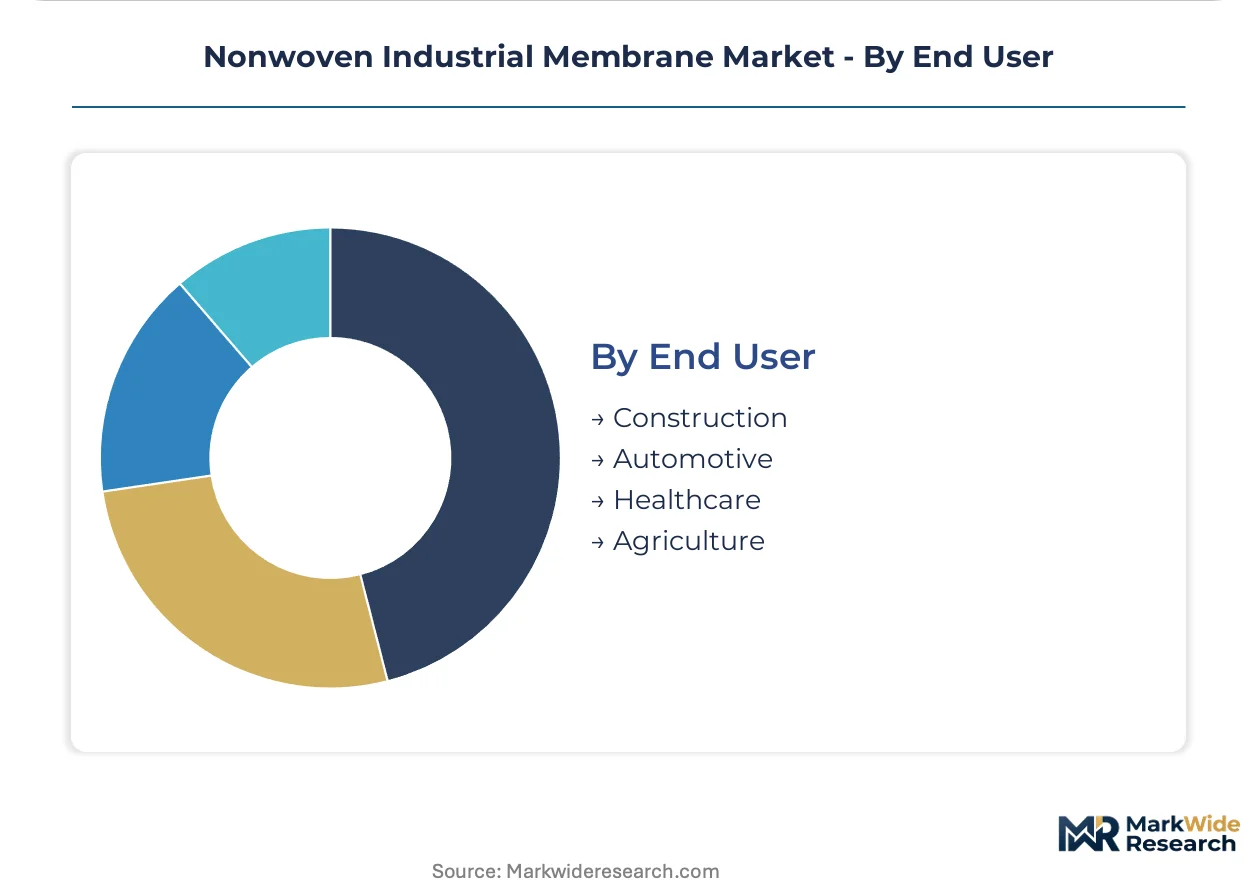
End User:
End user concentration varies by capital intensity, with healthcare and automotive embedding membranes in higher-value finished systems.
- Healthcare:Hospital infection control budgets and single-use surgical protocol adoption drive FDA-compliant membrane demand. Ahlstrom-Munksjö anchors North American supply through sustained sterile barrier manufacturing scale.
- Automotive:Cabin air filtration and battery separator applications in electric vehicle production. Korean and Taiwanese semiconductor manufacturers replicate outcome-based contracting for ultrapure water systems, favoring vendors with captive technical service networks.
- Construction:Geotechnical stabilization and drainage infrastructure where project-based procurement creates volume volatility.
- Agriculture:Irrigation filtration and greenhouse climate control in water-stressed growing regions.
Healthcare leads premium value capture; automotive is expanding most quickly on electrification-driven battery separator demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized polymer rheology engineers concentrate in Germany's industrial belt, China's Yangtze Delta research parks, and Japan's Kansai manufacturing corridor, anchoring membrane process innovation capacity across three continents.
United States
EPA effluent limitation guidelines are mandating sub-micron retention capabilities in municipal water systems across the Great Lakes and Southwest regions. The agency's 2024 discharge standard updates favor meltblown polypropylene membranes over conventional media. Industrial clusters in Texas and Ohio are retrofitting membrane bioreactor installations to meet these specifications.
Germany
Freudenberg Group's spunbond expertise dominates European industrial filtration contracts requiring mechanical durability. ECHA regulatory proposals targeting per- and polyfluoroalkyl substances are compressing qualification timelines for alternative chemistries. Municipal utilities in Bavaria and North Rhine-Westphalia pilot hybrid meltblown-electrospun structures for wastewater treatment retrofits.
China
Membrane bioreactor deployment is accelerating in textile and chemical wastewater treatment across Shanghai and Jiangsu province industrial corridors. The Ministry of Ecology and Environment enforces dual carbon goals that favor energy-efficient separation technologies. Yangtze River Delta manufacturing zones are scaling chemically inert polypropylene membrane production for domestic and export markets.
Japan
Electrospun nanofiber surface modification techniques are decentralizing performance benchmarks in liquid filtration applications. METI industrial technology roadmaps support sub-micron retention development without ceramic membrane brittleness. Kansai region utilities and Osaka-based manufacturers collaborate on membrane bioreactor retrofits displacing traditional fluoropolymer specialists.
India
The Central Pollution Control Board mandates stricter effluent standards for pharmaceutical clusters in Gujarat and Tamil Nadu. BIS certification requirements for industrial filtration equipment are opening membrane bioreactor demand in underpenetrated zones. Ahmedabad and Chennai industrial corridors are qualifying chemically inert separation media for textile and chemical wastewater applications.
Nonwoven Industrial Membrane Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across material qualification tiers. The vendor base stratifies between multinational chemical groups with captive polymer supply and regional fabricators serving municipal retrofit markets. Three archetypes dominate: integrated polymer-to-membrane producers, process-technology licensors, and application-specific converters. Capacity expansion and strategic partnerships represent the dominant competitive moves as qualification timelines compress.
Among diversified industrial groups, Freudenberg Group exemplifies the integrated polymer-to-membrane archetype through sustained European industrial filtration presence. Ahlstrom-Munksjö occupies a position anchoring North American healthcare membrane supply through FDA-compliant manufacturing scale. DuPont represents the high-performance materials tier, with fluoropolymer composite technology leadership in temperature-critical separation applications. These three entities illustrate how geographic origin and historical specialization shape competitive positioning without requiring identical strategic postures.
| Leading Market Players |
|---|
| Freudenberg Group |
| Ahlstrom-Munksjö |
| Berry Global Inc. |
| Toray Industries |
| Fitesa |
| DuPont |
| Johns Manville Corporation |
| Asahi Kasei Corporation |
| 3M Company |
| Others |
Cost & Logistics Intelligence
Fluoropolymer resin costs cascade through membrane manufacturing tiers, compressing margins for producers without captive polymer supply while amplifying pricing power for integrated specialists serving REACH-compliant European industrial filtration contracts.
Pricing Analysis
The bundled-versus-unbundled service split separates outcome-based operating contracts from standalone module sales across municipal water treatment procurement. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with FDA-compliant medical-grade membranes commanding substantial premiums over geotextile commodity tiers. Pricing pressure stems from outcome-based contracting transferring fouling risk to suppliers, compressing margins for producers lacking predictive analytics capabilities. Municipal utilities exhibit highest price sensitivity in standalone replacement cycles, while semiconductor manufacturers show lowest sensitivity in ultrapure water system integrations.
Supply Chain Analysis
Specialized polymer rheology engineers concentrate in Germany's industrial belt, China's Yangtze Delta research parks, and Japan's Kansai manufacturing corridor, constraining process optimization talent availability for regional membrane fabricators. Supply draws from polypropylene and polyester polymer production anchored in China, Germany, and the United States, with fluoropolymer resin supply concentrating among limited chemical producers. Single-source vulnerability in high-performance fluoropolymer feedstocks exposes manufacturers to allocation constraints and input cost volatility. Distribution runs through direct technical service networks for embedded system integrations and regional distributors for standalone module replacements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nonwoven industrial membrane market represents a late-cycle quality story as EPA effluent guidelines and REACH substance restrictions force substitution toward certified polypropylene and polyester nonwovens with validated sub-micron retention specifications.
For Market Incumbents: Hedge against fluoropolymer stranding risk by accelerating polyester composite qualification timelines ahead of EU PFAS restriction deadlines. Deepen backward integration into spunbond and meltblown process capabilities to defend margin position against outcome-based contracting pressure from consolidated municipal utilities. Prioritize captive technical service network expansion in Asia-Pacific membrane bioreactor deployment zones. For New Entrants and Emerging Players: Capture white-space opportunity in India's pharmaceutical and textile clusters where Central Pollution Control Board mandates are opening membrane bioreactor demand ahead of established supplier qualification. Target Gujarat and Tamil Nadu industrial corridors with chemically inert polypropylene offerings priced below European import alternatives. Pursue electrospun nanofiber hybrid manufacturing as a technical differentiation angle against incumbent fluoropolymer specialists. For Investors and Strategic Acquirers: Roll-up economics work for regional membrane fabricators with validated FDA or REACH compliance because qualification timeline compression is filtering supplier participation and creating acquisition currency for compliant assets. Focus on five-to-ten year viability windows for producers with demonstrated sterile barrier or industrial filtration certification trajectories. Monitor ECHA regulatory proposal advancement as the critical signal for forced material transition velocity and portfolio reconstitution timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Supply | Captive polypropylene sourcing insulates margin from fluoropolymer feedstock volatility and allocation constraints. |
| Electrospun Nanofiber Capacity Addition | Hybrid manufacturing enables sub-micron retention specifications competing with ceramic membranes in German municipal retrofits. |
| REACH-Compliant Material Qualification | PFAS-free certification unlocks industrial filtration contracts in Netherlands and Belgium ahead of restriction deadlines. |
| Outcome-Based Service Contracting | Performance-guaranteed operating contracts transfer fouling risk while locking in long-term revenue from Australian and Singapore utilities. |
| ISO 10993 Biocompatibility Certification | FDA-aligned sterile barrier validation filters supplier participation in OECD healthcare infection control procurement. |
Research Approach
Multiple input streams — technical interviews with membrane manufacturing executives, procurement discussions with municipal water treatment utility directors, and regulatory affairs consultations with REACH compliance specialists — were reconciled against customs trade data, EPA effluent guideline filings, and SEC disclosures from diversified industrial groups. Primary fieldwork with spunbond and meltblown process engineers in Germany, China, and Japan anchored polymer rheology and die design capability assessments. Secondary validation drew from ECHA regulatory proposal tracking, ISO certification databases, and membrane bioreactor installation records across Asia-Pacific industrial corridors. Bottom-up module demand estimates and top-down polymer consumption analysis were triangulated for convergence.
Historical capacity utilization patterns were cross-referenced against expert panel input from polymer suppliers and membrane OEMs to inform trajectory assumptions across the projection horizon. Segmentation modeling incorporated material type, manufacturing process, application tier, and end-use industry dimensions with regional regulatory cluster differentiation. CAGRs were derived from slope analysis of qualified demand expansion in membrane bioreactor deployments and medical barrier adoption. Forecast inputs included EPA effluent guideline implementation schedules, ECHA PFAS restriction timelines, and hospital infection control budget trajectories across OECD healthcare systems.
Regulatory acceleration beyond ECHA proposals, premature fluoropolymer inventory stranding, and municipal utility procurement consolidation are the dominant revision risks to modeled demand trajectories. Forecasts embed assumptions regarding qualification timeline compression and material substitution velocity that material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nonwoven Materials
Nonwoven Cleanroom Apparel Market
Nonwoven Materials
United States Non-Woven Fabric Market
Nonwoven Materials
Global Nonwoven Materials and Products Market
Nonwoven Materials
PET Spunbond Nonwoven Market
Nonwoven Materials
Non-Wood Fiber Market
Nonwoven Materials
Global Wet Laid Nonwovens Market
Nonwoven Materials
Nonwoven Dust Cover Market
Nonwoven Materials
Non Woven Fabric Making Machine Market
Nonwoven Materials
Nonwoven Polyester Fabric Market
Nonwoven Materials
Absorbable Nonwoven Textiles Market
Nonwoven Materials
PP Nonwovens Market
Nonwoven Materials
Nonwoven Sponges Market
Nonwoven Materials
Global Nonwoven Disposable Gloves Market
Nonwoven Materials
Global Automotive Nonwoven Fabrics Market
Nonwoven Materials
Non-Woven Glass Fiber Prepreg Market
Nonwoven Materials
Nonwoven Protective Clothing Market