
 Organic Cotton Market | 2026-2036
Organic Cotton Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Cotton Market Intelligence
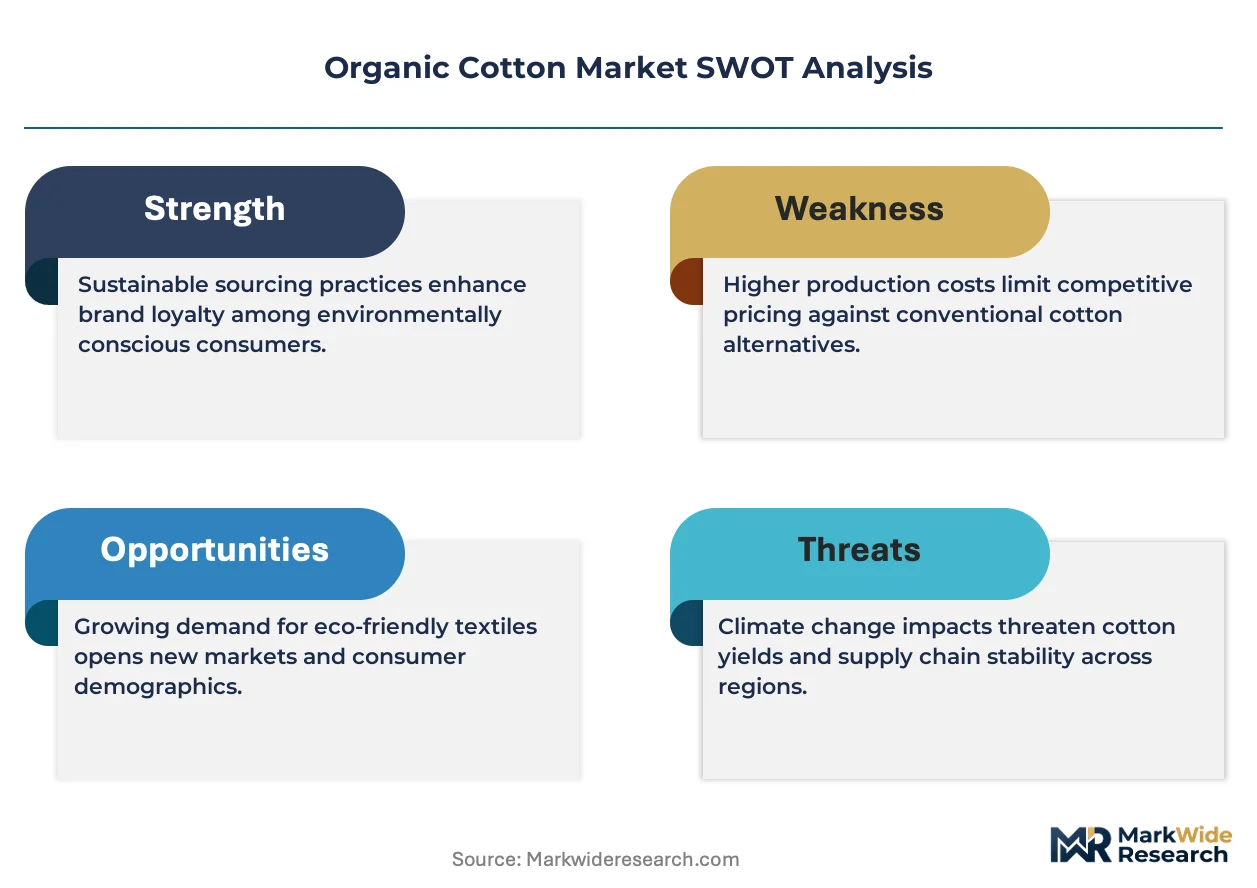
The European Union's Strategy for Sustainable and Circular Textiles is repositioning market access requirements, elevating the costs associated with non-compliance for global apparel brands. Patagonia, Inc. leverages its foundational commitment to organic materials to command premium pricing and sustain customer loyalty. Hanesbrands Inc. competes by integrating organic cotton into its mass-market product lines, focusing on achieving scale and broad consumer accessibility. Eileen Fisher Inc. differentiates its luxury offerings through a strict focus on circular design.
Organic cotton is defined as cotton cultivated from non-genetically modified plants and grown without synthetic agricultural chemicals like fertilizers or pesticides. Its primary purpose is producing textiles for applications with direct skin contact, where its hypoallergenic properties and low environmental footprint are valued. The apparel application segment dominates consumption, driven by consumer demand for sustainable clothing. Finished textiles represent the fastest-growing product type as brands seek complete, certified supply chain solutions.
The market operates under a strict framework of certifications, primarily the Global Organic Textile Standard (GOTS) and the USDA's National Organic Program (NOP). These standards govern the entire production chain, from farm to finished product, ensuring material authenticity and restricting market access for non-certified producers. Stakeholder success will hinge on securing verifiable, fraud-proof supply chains to meet tightening brand and consumer expectations for end-to-end traceability.
Market Dynamics
The push for verifiable, end-to-end traceability is the central force shaping the market. Mandates like the EU's CSRD are transforming organic certification from a marketing claim into a non-negotiable requirement for market access, driving investment in supply chain integrity.
Growth Catalysts
- Regulatory Mandates:The EU's Corporate Sustainability Reporting Directive compels brands to verify and report on supply chain materials, increasing demand for certified organic fibers.
- Premium Apparel Demand:The children's wear and luxury fashion segments continue to specify organic cotton for its hypoallergenic properties and sustainable branding value.
- Favorable Agricultural Policy:Government support for organic farming in India creates a favorable cost structure and expands the certifiable raw material base for its textile industry.
Market Restraints
- Yield Disparity:Organic cultivation methods typically result in lower yields per hectare compared to conventional cotton, constraining the total available supply.
- Certification Costs:The expense and administrative burden of obtaining and maintaining GOTS or USDA NOP certification can be prohibitive for smaller farms and mills.
- Fiber Substitution:Competition from other sustainable fibers, such as lyocell and recycled polyester, presents a threat in applications where performance attributes outweigh organic origin.
Strategic Opportunities
- Non-Apparel Expansion:Significant white space exists in home textiles, including bedding and towels, and in personal care items where hypoallergenic properties are valued.
- Digital Traceability:Implementing blockchain and other digital ledger technologies offers a way to provide fraud-proof, farm-to-garment traceability that meets brand and regulatory demands.
- Geographic Diversification:Establishing and certifying organic cultivation programs in new regions, such as in Africa or Latin America, can mitigate supply chain risks.
Industry Challenges
- Supply Chain Fraud:Preventing the illicit commingling of conventional cotton into the organic supply chain remains a persistent operational challenge requiring robust testing and auditing.
- Compliance Complexity:Navigating the evolving and differing requirements of standards like GOTS and various national organic programs creates a significant compliance burden for producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Cotton Market |
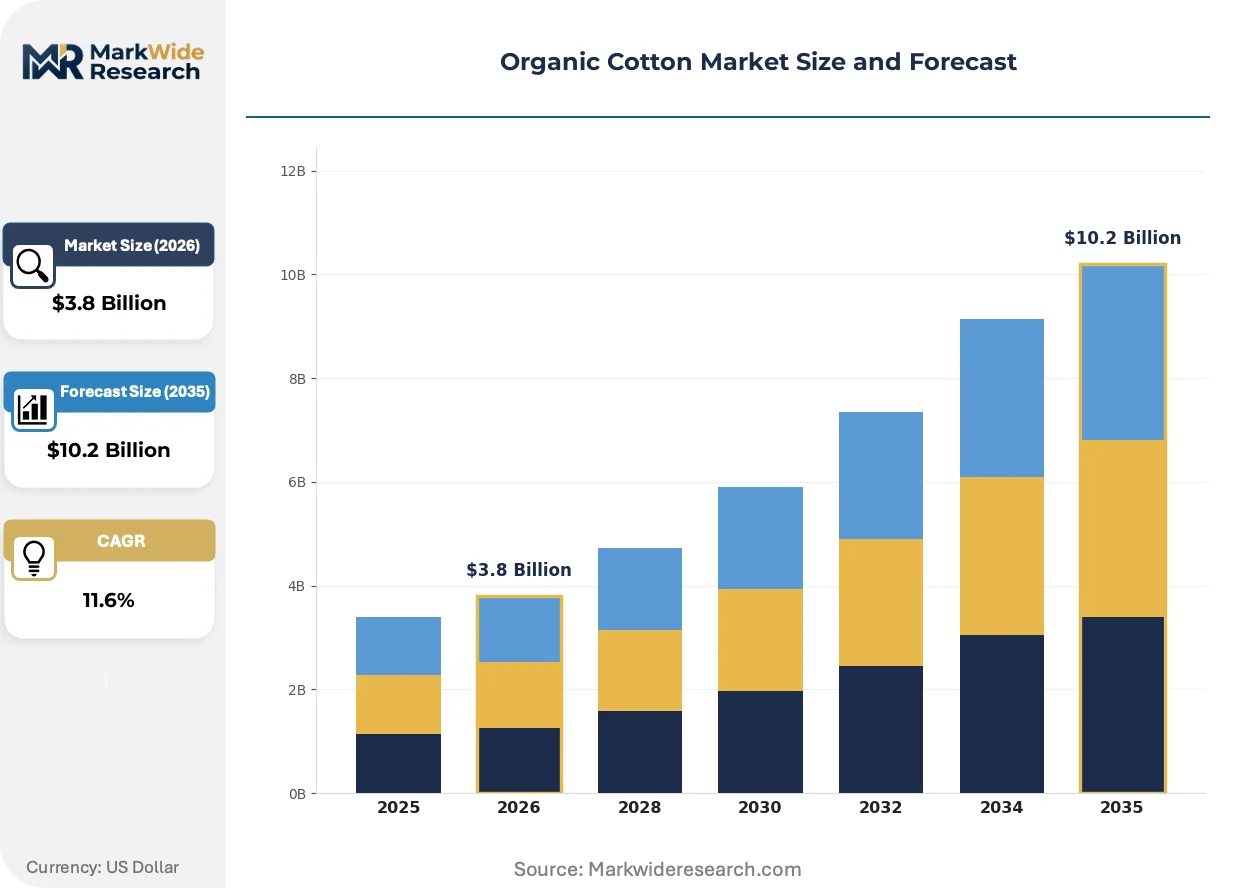
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.2 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Cotton, Yarn, Fabric, Finished Textiles Application: Apparel, Home Textiles, Industrial Textiles, Medical Supplies End User: Fashion Brands, Textile Manufacturers, Healthcare Providers, Industrial Buyers Distribution Channel: Online Retail, Specialty Stores, Wholesale Distributors, Direct-to-Consumer |
| Companies Covered | Eileen Fisher Inc., prAna, Patagonia, Inc., Kotn, Harvest & Mill, Hanesbrands Inc., Coyuchi, Boll & Branch, Pact Apparel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Cotton Market Strategic Shifts & Innovations
Technology and regulation are converging to professionalize the organic cotton supply chain. The market is shifting from a focus on agricultural practices alone toward a system where digital proof of origin and material integrity are paramount for commercial success.
Scientific traceability using DNA or isotopic markers provides definitive proof of a fiber's origin. Apparel brands facing stringent regulations are rapidly adopting these systems to validate their supply chains against fraud. This forensic verification capability is expanding into the testing of finished garments, creating an immutable link from farm to retail.
The European Union's Corporate Sustainability Reporting Directive (CSRD) creates a legal requirement for large companies to report on their supply chain impacts. This is forcing apparel brands to invest heavily in due diligence and data collection for materials like organic cotton. The premium and luxury segments are most affected, needing to substantiate their sustainability claims with auditable data.
Consumer and investor expectations are evolving from demanding sustainable inputs to requiring circular design principles. The emphasis is shifting from just using organic cotton to designing products for disassembly, repair, and recycling at end-of-life. This trend is most pronounced in the European and North American premium fashion markets, influencing product development.
Organic Cotton Market Segmentation
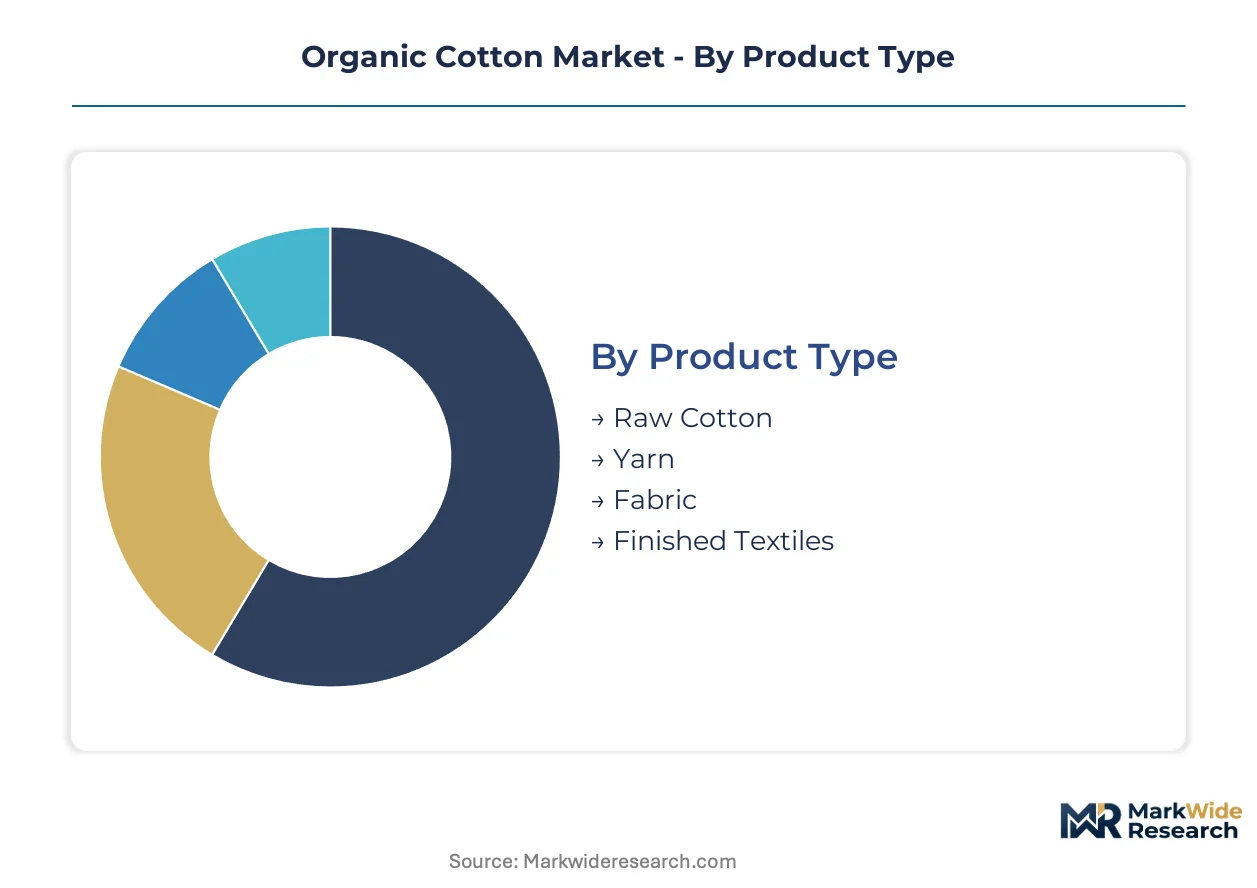
The organic cotton market's segmentation highlights the diverse pathways through which certified materials reach end-users, reflecting varied processing stages, application needs, and distribution strategies. Understanding these distinct segments is critical for stakeholders to identify growth opportunities and navigate compliance complexities across the supply chain.
Product Type:
Buyers in the organic cotton market differentiate their procurement strategies based on the processing stage of the material, influencing both cost and immediate application readiness.
- Raw Cotton:This segment includes unprocessed organic cotton fibers harvested directly from fields, serving as the foundational input for textile manufacturing.
- Yarn:Organic cotton yarn consists of spun fibers, available in various counts and twists, used in weaving and knitting operations.
- Fabric:Organic cotton fabric represents woven or knitted textile materials produced from organic yarn, providing versatility for various garment and home textile applications. Apparel brands in North America drive demand for certified organic fabrics to meet consumer sustainability expectations.
- Finished Textiles:These are fully processed and dyed organic cotton goods, ready for final product assembly, often certified to GOTS standards. Demand is concentrating in the European apparel sector as brands seek complete, auditable supply chain solutions.
Raw Cotton leads volumes today; Finished Textiles is gaining share fastest.
Application:
The diverse applications of organic cotton delineate distinct market segments, each valuing its unique properties for specific end-uses.
- Apparel:This segment encompasses all clothing items manufactured from organic cotton, valued for its hypoallergenic qualities and sustainable production. Consumer demand for sustainable clothing drives significant consumption in this market.
- Home Textiles:Organic cotton finds extensive use in bedding, towels, and upholstery, where its softness and chemical-free nature appeal to health-conscious consumers. Expansion into this segment offers significant white space for market growth.
- Industrial Textiles:This category includes organic cotton used in non-consumer products like filtration media or automotive interiors, where specific material properties are required.
- Medical Supplies:Organic cotton is increasingly adopted for bandages, swabs, and other healthcare products due to its purity and gentle contact with sensitive skin.
Organic cotton consumption is dominated by the Apparel segment, while Home Textiles is expanding most quickly.
End User:
End-user categories reflect distinct purchasing behaviors and certification requirements, shaping demand across the organic cotton value chain.
- Fashion Brands:These entities, ranging from luxury labels to mass-market retailers, procure organic cotton materials to meet consumer sustainability expectations and regulatory mandates like the EU's CSRD. Patagonia and Eileen Fisher exemplify this strategic sourcing.
- Textile Manufacturers:This segment comprises mills and factories that process raw organic cotton into yarns and fabrics, forming a critical link in the supply chain. They require consistent supply of certified raw materials for their production lines.
- Healthcare Providers:Hospitals and clinics purchase organic cotton products for patient care, prioritizing hypoallergenic and chemical-free materials for medical applications.
- Industrial Buyers:Companies in sectors like automotive or filtration source organic cotton for specialized applications, valuing its natural properties over synthetic alternatives.
The largest volume of organic cotton is absorbed by Fashion Brands, with Healthcare Providers showing the steepest expansion trajectory.
Distribution Channel:
The distribution channels for organic cotton products vary significantly, reflecting diverse market access strategies and consumer purchasing preferences.
- Online Retail:This channel includes e-commerce platforms and brand websites, providing direct access to consumers seeking organic cotton apparel and home goods. Digital traceability solutions enhance consumer trust in online purchases.
- Specialty Stores:Boutique retailers and organic product shops offer curated selections of organic cotton items, often emphasizing ethical sourcing and premium quality.
- Wholesale Distributors:These intermediaries supply large volumes of organic cotton yarns, fabrics, and finished goods to manufacturers and retailers globally. They play a crucial role in managing logistics and bulk procurement for the industry.
- Direct-to-Consumer:Brands selling directly to end-users through their own stores or websites control the entire customer experience and messaging around organic cotton products.
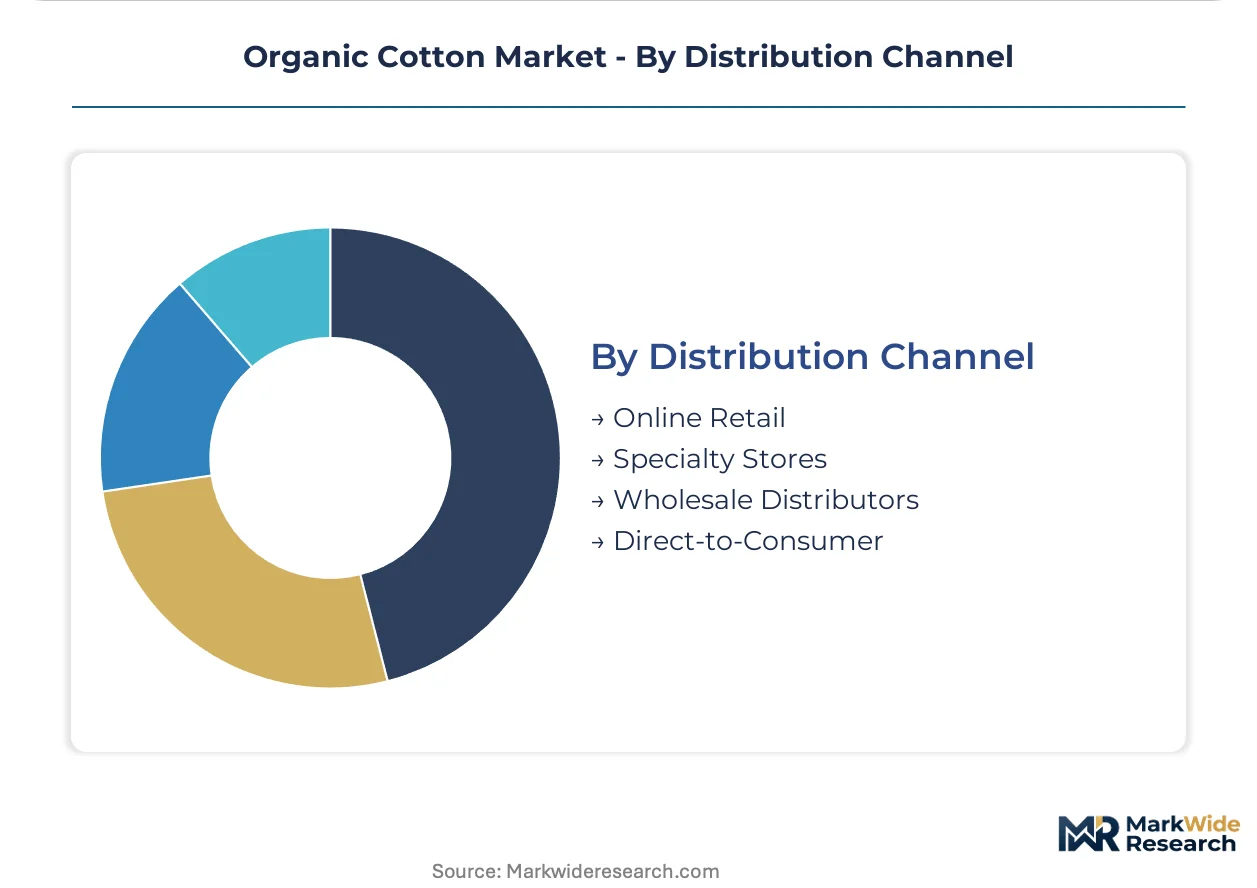
While Wholesale Distributors remains a bedrock for bulk supply, the most dynamic growth is observed in Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled textile artisans and agricultural workers across key regions anchor the global organic cotton market. These regions combine robust manufacturing capabilities with increasing consumer demand for sustainable apparel and home textiles. Regulatory shifts in major economies further shape procurement strategies and supply chain investments.
India
Consumer demand for sustainable clothing and premium apparel drives India's organic cotton production. The Indian government's favorable agricultural policies support organic farming expansion and certification. Textile manufacturing hubs in Gujarat and Maharashtra process significant volumes into yarn and fabric for global export.
Germany
European apparel brands' demand for finished organic textiles drives German imports. The EU's Corporate Sustainability Reporting Directive (CSRD) compels German companies to verify supply chain materials. Textile clusters in North Rhine-Westphalia and Bavaria focus on sourcing certified organic fabrics for high-value garments.
United States
Premium fashion and children's wear segments fuel demand for organic cotton in the United States. The USDA's National Organic Program (NOP) sets standards for organic cotton products sold domestically. Major apparel brands in California and New York concentrate on integrating verified organic fibers into their product lines.
China
Growing domestic consumer demand for sustainable textiles and export markets shape China's organic cotton sector. The country's environmental regulations increasingly encourage sustainable textile production practices. Textile processing zones in the Yangtze River Delta concentrate on manufacturing organic cotton fabrics for both local and international brands.
Organic Cotton Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the organic cotton value chain. The market structure exhibits a tiered approach, with large brands integrating organic materials into mass-market lines and smaller, specialized firms targeting premium niches. Strategic archetypes include vertically integrated producers, certified material suppliers, and consumer-facing brands. Companies pursue capacity expansion and strategic partnerships to secure verifiable supply chains and meet regulatory demands.
Among consumer-facing brands, Eileen Fisher Inc. exemplifies a luxury segment player, differentiating its offerings through a strict focus on circular design principles and material integrity. Patagonia, Inc. represents a premium brand archetype, leveraging its foundational commitment to organic materials to command premium pricing and sustain customer loyalty. Hanesbrands Inc. occupies the mass-market segment, integrating organic cotton into its broad product lines, focusing on achieving scale and broad consumer accessibility. These companies collectively illustrate the varied approaches to organic cotton integration across different market tiers, from high-end fashion to everyday wear.
| Leading Market Players |
|---|
| Eileen Fisher Inc. |
| prAna |
| Patagonia, Inc. |
| Kotn |
| Harvest & Mill |
| Hanesbrands Inc. |
| Coyuchi |
| Boll & Branch |
| Pact Apparel |
| Others |
Cost & Logistics Intelligence
Global organic cotton lint prices directly influence pricing tiers across the supply chain, from yarn to finished textiles, reflecting the cost of certified raw materials. This commodity pricing structure dictates initial material costs for textile manufacturers and ultimately impacts consumer-facing apparel brands.
Pricing Analysis
The procurement of bundled, certified organic cotton solutions, particularly finished textiles, commands a premium over unbundled raw fiber purchases. Contract-based long-term offtake agreements dominate pricing for certified materials, ensuring supply integrity for apparel brands. Price differentiation stems from certification levels like GOTS or USDA NOP, the quality grade of the fiber, and the brand premium associated with sustainable sourcing. Pricing pressure stems from certification costs and lower organic yields, impacting upstream producers, while mass-market retailers exhibit higher price sensitivity than luxury fashion brands for authenticated organic materials.
Supply Chain Analysis
Logistics and freight costs significantly influence the global organic cotton supply chain, particularly for raw materials shipped from production hubs to processing centers. Geographic supply concentration centers on India and China, providing extensive raw material bases and manufacturing capabilities. The supply chain relies on certified organic cotton seeds and natural dyes, but fraud, specifically the illicit commingling of conventional cotton, represents a persistent structural risk. Wholesale Distributors remain critical intermediaries, managing bulk procurement and global distribution for manufacturers and brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The organic cotton market presents a geographic-arbitrage play, as India's favorable agricultural policies create a cost advantage compared to the stringent regulatory landscape for sourcing in the European Union. Stakeholders can leverage these regional differentials to optimize supply chain strategies.
For Market Incumbents:Extend existing GOTS and NOP certifications across new product lines, reinforcing brand trust against the threat of supply chain fraud. Deepen backward integration into organic farming cooperatives in India to secure verifiable raw material supply and mitigate commodity price volatility. Invest in digital traceability solutions, like blockchain, to provide immutable proof of origin from farm to finished garment. This protects market share from emerging competitors leveraging advanced verification technologies.
For New Entrants and Emerging Players:Enter via non-apparel segments like home textiles or medical supplies, which offer significant white space and value hypoallergenic properties. Target the North American market, where consumer demand for sustainable home goods is rapidly expanding. Focus on a direct-to-consumer model, leveraging digital traceability to build trust and differentiate offerings. This approach bypasses established wholesale channels and allows for agile market penetration.
For Investors and Strategic Acquirers:Asymmetric upside sits with specialized technology providers offering fraud-proof digital traceability solutions for organic fiber. The long-term viability of organic cotton hinges on verifiable supply chains over the next decade. Target mid-cap textile manufacturers with strong existing GOTS certification infrastructure and established relationships with Indian organic cotton producers. The signal to watch is the widespread adoption of DNA or isotopic markers for finished garment verification across premium apparel brands.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Digital Traceability Platforms | Implementing blockchain solutions provides fraud-proof farm-to-garment traceability, meeting EU CSRD requirements for global apparel brands. |
| Expand Organic Cultivation in New Regions | Establishing certified organic programs in Africa mitigates supply chain risks associated with over-reliance on Indian production. |
| Acquire GOTS-Certified Processing Facilities | Securing processing capacity ensures material authenticity and reduces compliance complexity for fashion brands. |
| Develop Bio-Based Fiber Blends | Innovating with lyocell blends diversifies product offerings and addresses fiber substitution competition in home textiles. |
| Target Medical Supplies Segment | Expanding into medical applications leverages organic cotton's hypoallergenic properties for healthcare providers. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, informing the organic cotton market analysis. Primary interviews with textile manufacturers, apparel brand procurement managers, certification bodies, and organic farmers provided granular insights. Secondary validation drew from USDA NOP reports, GOTS annual reviews, and EU regulatory documents. This approach employed both bottom-up and top-down triangulation to ensure data accuracy.
The forecast framework anchored to historical reference periods, establishing baseline market performance across the analysis window. Segmentation dimensions modeled included product type, application, end-user, and distribution channel, alongside regional production capacity. Compound annual growth rates were derived through regression analysis of historical data and projected forward based on market dynamics. Key inputs included projected organic cotton yield per hectare and brand sustainability investment trends.
The model holds under current regulatory and certification frameworks; deviations in EU CSRD enforcement or GOTS standard evolution would shift projections. Forecasts reflect assumptions regarding consumer demand for sustainable apparel and India's agricultural policy. Stakeholders should weigh assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Natural Fibers
Modal Fiber Market
Natural Fibers
Natural Fiber Composite (NFC) Market
Natural Fibers
Hessian Sacks Market
Natural Fibers
North America Lyocell Fiber Market
Natural Fibers
Natural Cotton Extract Market
Natural Fibers
Cellulose Fiber Market
Natural Fibers
Sugarcane Fiber Market
Natural Fibers
Bamboo Fibers Market
Natural Fibers
Natural Fibers and Sisal Market
Natural Fibers
Jute Market
Natural Fibers
Silk Market
Natural Fibers
Silk Mask Market
Natural Fibers
Sugarcane Fiber Bowls Market
Natural Fibers
Eco Fibers Market
Natural Fibers
Cashmere Clothing Market
Natural Fibers
Global Cotton Market