
 Global Textile Colorant Market | 2026-2036
Global Textile Colorant Market Size, Share, and Industry Trends Forecast 2026-2036
Global Textile Colorant Market Foresight
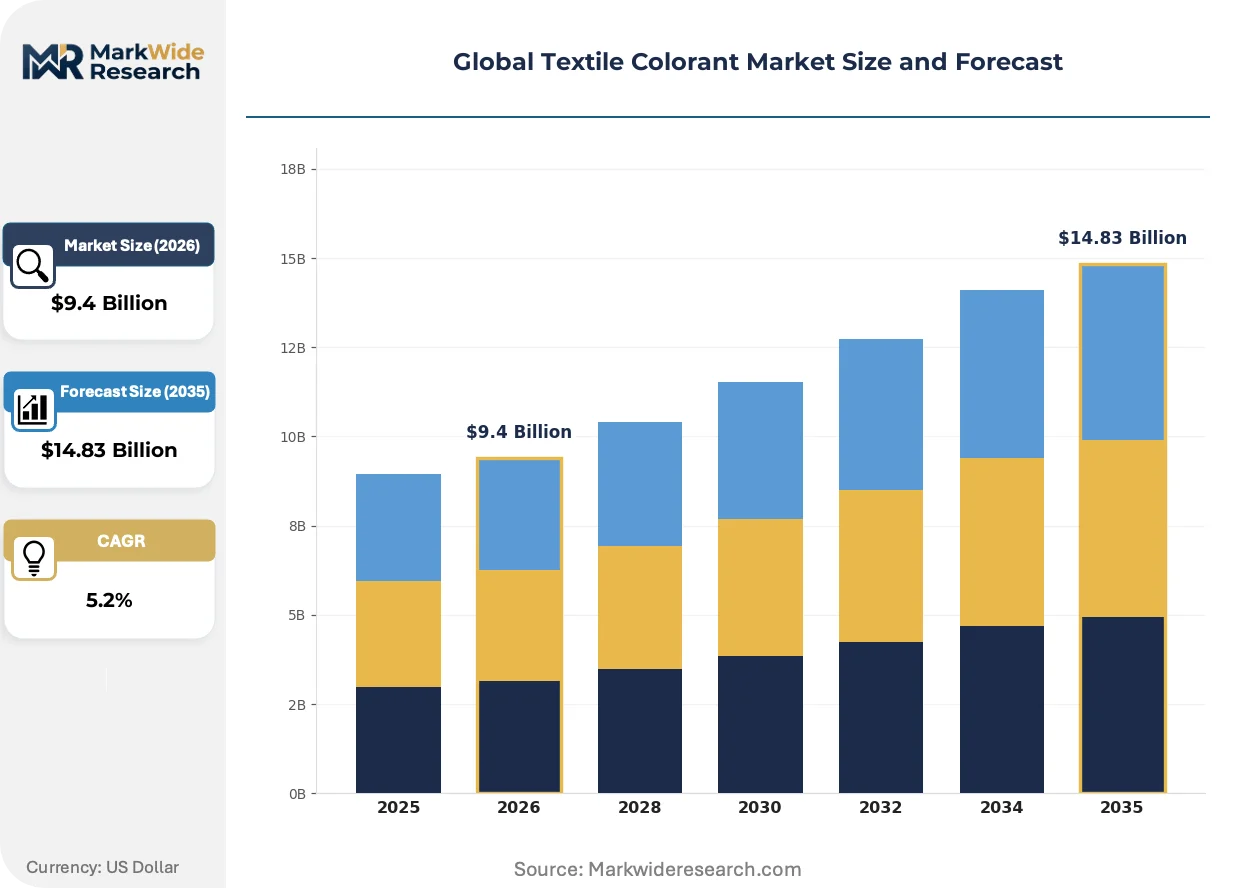
The global textile colorant market is recalibrating around a widening split between premium high-fastness dyes and commodity-grade colorants, with performance specifications now dictating procurement terms rather than price alone. Huntsman Corporation leverages its integrated intermediates-to-dyes pipeline to sustain margin capture across reactive and disperse dye portfolios. Archroma anchors its position through specialty chemical expertise in low-impact dyeing systems for technical textiles. Kiri Industries competes on manufacturing scale in vat and reactive dye intermediates, extending its supply reach into European textile mills.
Textile colorants encompass synthetic and natural chromophoric compounds formulated to impart permanent color to cellulosic, protein, and synthetic fibers through exhaustion, padding, or digital inkjet deposition, with lightfastness ratings and wash durability serving as critical performance benchmarks. Reactive dyes dominate volume throughput for cotton and viscose processing, while disperse dyes command premium positioning in polyester sportswear and automotive textile applications where sublimation transfer precision matters. Acid dyes occupy a mature, stable niche in wool and silk segments, with margin pools concentrating in metal-complex variants for technical fabricators.
REACH in Europe, GB standards under China's SAMR, and India's BIS certification framework collectively restrict azo dye metabolites and heavy metal content, redirecting formulation investment toward compliant chemistries. The EU Green Deal's textile sustainability requirements and California's Proposition 65 enforcement are tightening market access for non-compliant suppliers. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation costs and certification timelines.
Market Dynamics
Formulation chemistry is bifurcating under divergent regulatory stringency, as European REACH metabolite restrictions and China's GB standards force reformulation investments that commodity-grade suppliers cannot absorb, compressing viable supplier pools.
Growth Catalysts
- Polyester sportswear expansion:Athletic apparel brands are scaling sublimation-compatible disperse dye procurement for moisture-wicking performance fabrics, tightening technical specifications on transfer precision and wash durability.
- REACH metabolite restrictions:The European Chemicals Agency's tightening azo dye metabolite thresholds are redirecting procurement toward high-fastness reactive chemistries that command premium positioning in export-oriented mills.
- India's dyeing capacity scaling:Textile clusters in Gujarat and Tamil Nadu are expanding vat and reactive dye uptake to serve apparel export contracts, concentrating volume demand in South Asian processing hubs.
Market Restraints
- Petrochemical feedstock volatility:Naphthalene and anthraquinone intermediate costs swing with crude derivatives, compressing margin predictability for disperse and vat dye manufacturers.
- Intermediate supply concentration:China controls over 70 percent of dye intermediate manufacturing, exposing formulators elsewhere to export license delays and dual carbon policy disruptions.
- Water intensity of cotton dyeing:Exhaust dyeing of cellulosic fibers requires 100-150 liters per kilogram of fabric, triggering wastewater discharge penalties in water-stressed manufacturing zones.
Strategic Opportunities
- Vietnam's apparel export surge:Relocated garment manufacturing from China is creating unmet demand for REACH-compliant reactive dyes in Ho Chi Minh City and Hanoi processing zones.
- Digital textile printing convergence:Inkjet deposition technology paired with low-cure pigment dispersions is opening short-run customization channels for fashion and home textile verticals.
- EU Green Deal textile requirements:Mandatory recycled fiber content thresholds are creating formulation opportunities for dyes compatible with mechanically recycled polyester feedstocks.
Industry Challenges
- Colorimetric formulation expertise gap:Digital color matching and spectrophotometric quality control require analytical chemists that dye houses in emerging manufacturing clusters cannot readily recruit.
- Multi-jurisdiction certification timelines:Simultaneous BIS registration in India, OEKO-TEX certification for EU access, and ZDHC conformance create 18-24 month product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Textile Colorant Market |
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $14.83 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reactive Dyes, Acid Dyes, Disperse Dyes, Direct Dyes, Vat Dyes, Fluorescent Dyes Application: Apparel Fabric, Home Furnishings, Industrial Textiles, Technical Textiles, Automotive Textiles, Sportswear End User: Textile Mills, Dyeing Contractors, Garment Manufacturers, Technical Fabricators, Research Institutes, Outsourced Partners Distribution Channel: Direct Sales, Distributors, E-commerce Platforms, Wholesalers, Retailers, Specialty Stores |
| Companies Covered | Huntsman Corporation, Archroma, BASF SE, Lanxess AG, Kiri Industries, Sumitomo Chemical Co., Ltd, Dystar Group, Zhejiang Longsheng Group Co., Ltd, Atul Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Textile Colorant Market Shifts & Advancements
Digital deposition systems and bio-based chromophores are restructuring colorant application economics, while regulatory metabolite testing protocols are becoming de facto quality gates for supplier qualification.
Supercritical CO2 dyeing is overtaking aqueous exhaust methods in polyester processing, eliminating water discharge entirely while reducing energy inputs by half. Technical fabricators in Germany and Japan are piloting commercial-scale installations. This technology is overtaking conventional jet dyeing in premium sportswear manufacturing where water stewardship certifications determine retail placement.
China's GB 18401-2010 textile safety standards under SAMR enforcement are mandating formaldehyde and heavy metal testing for all domestic-market apparel, forcing reformulation of metal-complex acid dyes. Domestic brands are accelerating compliance investments ahead of anticipated alignment with EU REACH metabolite lists. Wool and silk processors serving dual export-domestic markets face the steepest retesting burdens.
Brand-led chemical management is consolidating supplier lists around ZDHC conformance, with mills in Bangladesh and Turkey now requiring MRSL-compliant dye documentation as a purchase order precondition. Large apparel retailers are unbundling dye procurement from fabric sourcing, inserting direct chemical management contracts. This shift is most visible in European fast-fashion supply chains where transparency mandates drive tier-one mill accountability.
Global Textile Colorant Market Segmentation
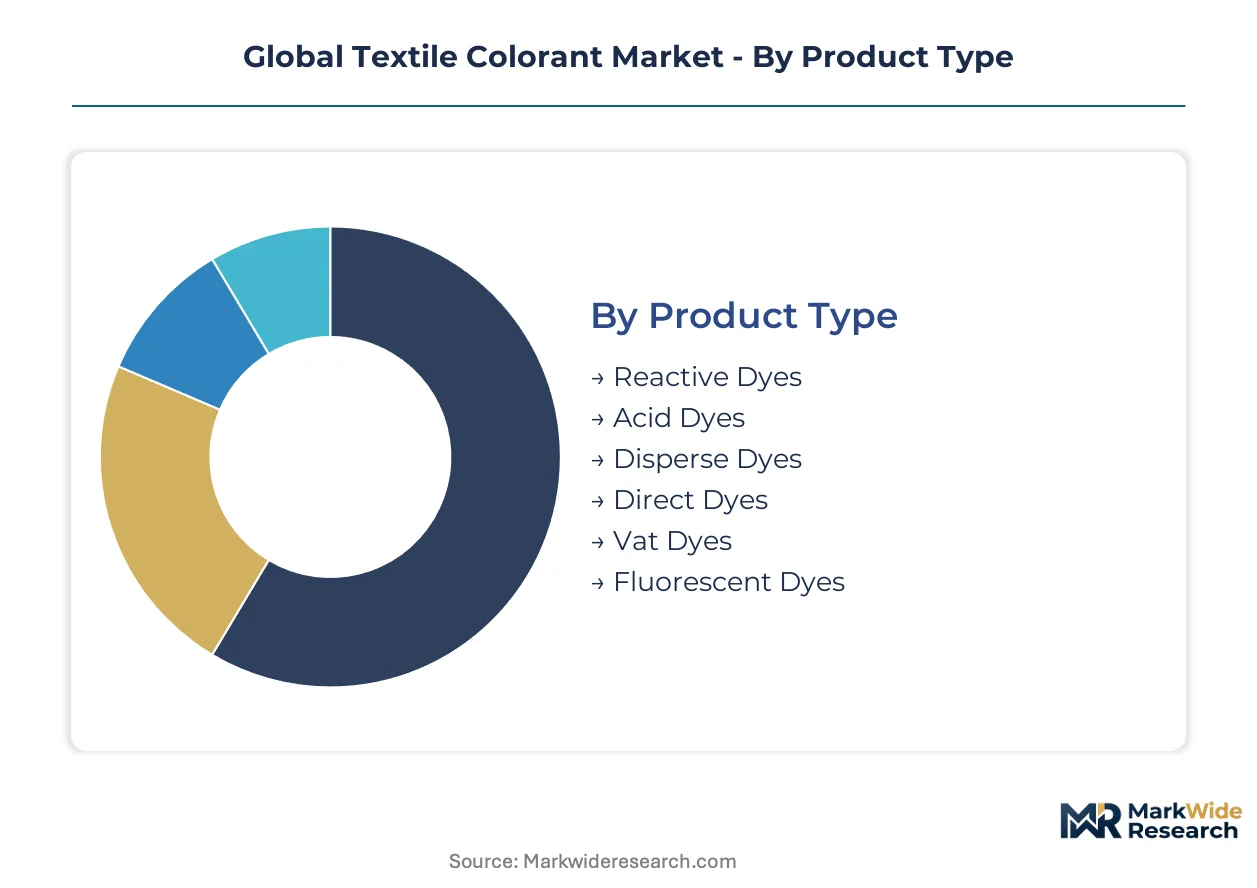
Textile colorant procurement decisions diverge sharply across product chemistries, end-use durability requirements, and supply chain integration levels. Understanding these splits reveals where formulation premiums command pricing power versus where commodity competition erodes margins.
Product Type:
Buyers in this category differentiate primarily by fiber compatibility and fastness specifications rather than unit cost.
- Reactive Dyes:These chromophores form covalent bonds with cellulosic hydroxyl groups, delivering superior wash fastness on cotton and viscose. Demand concentrates in Gujarat and Tamil Nadu textile clusters where export-oriented mills require REACH-compliant formulations for EU apparel contracts.
- Disperse Dyes:Non-ionic structures designed for hydrophobic polyester fibers, these enable sublimation transfer printing with precise color migration control. Procurement is accelerating in Vietnam's Ho Chi Minh City processing zones for moisture-wicking sportswear bound for North American athletic brands.
- Acid Dyes:Anionic compounds for protein fibers, with metal-complex variants serving technical wool applications.
- Direct Dyes:Water-soluble azo structures offering economical cotton shading with moderate fastness trade-offs.
- Vat Dyes:Insoluble pigments applied via reduction-oxidation chemistry, prized for all-round fastness in workwear and military textiles.
- Fluorescent Dyes:High-visibility chromophores absorbing UV and emitting visible light, critical for safety apparel and sportswear accents.
Reactive dyes lead volumes today; disperse dyes are gaining share fastest.
Application:
End-use durability standards and brand compliance requirements separate premium from commodity procurement tiers.
- Apparel Fabric:Exhaust and pad-batch dyeing of woven and knitted fashion fabrics, where fast fashion cycles demand rapid shade matching and bulk consistency. European retailers now mandate ZDHC MRSL documentation as a purchase precondition, redirecting volume toward certified reactive dye suppliers.
- Sportswear:Polyester-dominant performance apparel requiring sublimation-compatible disperse dyes with precise transfer precision. Germany's technical fabricators are piloting supercritical CO2 dyeing installations to eliminate water discharge while meeting water stewardship certification requirements for retail placement.
- Home Furnishings:Curtains, upholstery, and bedding textiles where lightfastness ratings determine specification acceptance.
- Industrial Textiles:Geotextiles, filtration media, and conveyor belting where chemical resistance overrides aesthetic priorities.
- Technical Textiles:Medical, aerospace, and protective applications demanding lot-to-lot spectrophotometric consistency.
- Automotive Textiles:Seat fabrics and interior trim requiring fogging resistance and UV stability under SAE standards.
Apparel fabric commands the largest volume position; sportswear shows the steepest expansion trajectory.
End User:
Integration depth and technical capability determine whether buyers source directly from formulators or through intermediaries.
- Textile Mills:Vertically integrated processors with in-house dyeing, bleaching, and finishing operations. These facilities in Bangladesh and Turkey now require direct chemical management contracts unbundled from fabric sourcing, inserting transparency mandates into procurement terms.
- Dyeing Contractors:Toll processors serving fragmented garment manufacturers, competing on throughput speed and shade accuracy.
- Garment Manufacturers:Cut-make-trim operations outsourcing coloration, vulnerable to intermediate margin stacking.
- Technical Fabricators:Specialty producers of medical, aerospace, and industrial textiles with proprietary fastness specifications.
- Research Institutes:Pilot-scale facilities testing bio-based chromophores and low-impact application methods.
- Outsourced Partners:Third-party logistics and chemical management providers consolidating procurement for mid-scale apparel brands.
Textile mills absorb the majority of volume; technical fabricators are expanding procurement most aggressively.
Distribution Channel:
Service intensity and formulation customization needs shape channel selection across buyer segments.
- Direct Sales:Technical service teams embedding with major mills for shade development and troubleshooting. Huntsman Corporation and Archroma deploy this model for reactive and disperse dye portfolios, capturing margin through formulation expertise rather than commodity trading.
- Distributors:Regional stockists serving fragmented dyeing contractors with standard shades and rapid replenishment.
- E-commerce Platforms:Digital procurement portals for small-batch pigment dispersions and digital inkjet inks.
- Wholesalers:Volume aggregators for commodity-grade direct dyes with limited technical support.
- Retailers:Point-of-sale access for artisan and craft textile producers.
- Specialty Stores:Niche suppliers of natural dyes and heritage vat formulations for luxury positioning.
Direct sales dominates value capture; e-commerce platforms are climbing the fastest as digital printing adoption spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized dye chemists and colorimetric technicians concentrate in Gujarat, Germany, and China's Zhejiang province, anchoring formulation expertise for export-compliant textile processing.
China
Dual carbon policy enforcement under MEE is constraining naphthalene and anthraquinone intermediate output, tightening feedstock availability for disperse and vat dye production. GB standards under SAMR mandate formaldehyde and heavy metal testing for all domestic-market apparel. Textile clusters in Zhejiang province are retooling reactive dye lines to meet anticipated REACH metabolite alignment.
India
BIS certification requirements for textile colorants are extending compliance timelines for export-oriented mills serving European apparel contracts. PLI scheme incentives for technical textiles are accelerating specialty dye procurement in Tamil Nadu. Ahmedabad and Surat processing hubs are expanding vat dye capacity for military and workwear contracts.
Germany
ECHA's tightening azo dye metabolite thresholds are redirecting procurement toward high-fastness reactive chemistries. EU Green Deal textile sustainability requirements are mandating recycled fiber compatibility in new dye formulations. Technical fabricators in Baden-Württemberg are piloting supercritical CO2 dyeing installations for premium sportswear manufacturing.
Vietnam
Relocated garment manufacturing from China is creating unmet demand for REACH-compliant reactive dyes in Ho Chi Minh City processing zones. The country's national textile regulator is aligning domestic chemical safety standards with EU import requirements. Dyeing contractors in Hanoi are scaling disperse dye uptake for moisture-wicking polyester sportswear bound for North American athletic brands.
United States
California's Proposition 65 enforcement is tightening market access for non-compliant textile colorant suppliers. EPA oversight of industrial wastewater discharge is triggering treatment infrastructure investments in Los Angeles apparel manufacturing zones. Technical textile fabricators in North Carolina are demanding lot-to-lot spectrophotometric consistency for medical and aerospace applications.
Global Textile Colorant Market Competitive Landscape
Top-tier vendors anchor integrated intermediates-to-dyes pipelines, while mid-scale specialists compete on regional compliance expertise and shade-matching speed. The supplier base stratifies between formulators with captive intermediate production and toll processors dependent on Chinese feedstock. Three archetypes dominate: integrated chemical conglomerates with backward control over naphthalene and anthraquinone supply, specialty dye houses with ZDHC-certified low-impact portfolios, and regional volume players serving fragmented dyeing contractors. Competitive moves concentrate on strategic partnerships for supercritical CO2 technology licensing and geographic expansion into Vietnam's processing zones.
Among integrated chemical conglomerates, Huntsman Corporation and BASF SE occupy positions defined by captive intermediate supply and reactive dye formulation depth. Specialty dye houses exemplified by Archroma sit within the ZDHC conformance tier, while Kiri Industries represents the scale-driven regional archetype with manufacturing concentration in vat and reactive dye intermediates. These three anchors illustrate how supplier positioning diverges between margin capture through upstream integration and premium positioning through compliance certification.
| Leading Market Players |
|---|
| Huntsman Corporation |
| Archroma |
| BASF SE |
| Lanxess AG |
| Kiri Industries |
| Sumitomo Chemical Co., Ltd |
| Dystar Group |
| Zhejiang Longsheng Group Co., Ltd |
| Atul Ltd |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap dye houses in Gujarat and Zhejiang provinces anchor regional pricing discipline through captive naphthalene intermediate production, insulating margin capture from petrochemical feedstock swings while commodity-grade suppliers absorb cost compression. This ownership pattern concentrates pricing power among integrated formulators as REACH compliance investments force unbundled service premiums for technical support and certification documentation.
Pricing Analysis
Bundled technical service contracts now separate from base dye procurement as mills demand ZDHC MRSL documentation and spectrophotometric shade matching as standalone line items. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with OEKO-TEX and ZDHC-compliant reactive dyes commanding substantial premiums over commodity direct dyes. Pricing pressure stems from naphthalene and anthraquinone cost volatility as China's dual carbon policy constrains intermediate output. Garment manufacturers outsourcing coloration exhibit highest price sensitivity, while technical fabricators for medical and aerospace applications prioritize lot-to-lot consistency over unit cost.
Supply Chain Analysis
Freight cost escalation on naphthalene and anthraquinone intermediates from Chinese ports to European formulators has intensified regional sourcing strategies. Supply concentrates in China, India, and Germany, with Zhejiang province controlling over seventy percent of dye intermediate manufacturing. Raw material dependencies rest on petrochemical derivatives, sulfur-based reduction agents, and metal-complex precursors for acid dye formulations. Single-source vulnerability from Chinese intermediate concentration exposes formulators elsewhere to export license delays and dual carbon policy disruptions. Distribution runs through direct sales teams embedding with major mills, supplemented by regional distributors serving fragmented dyeing contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in specialty dye portfolios as supercritical CO2 application methods displace water-intensive exhaust dyeing, compressing operating costs for polyester processors while premium positioning for REACH-compliant reactive chemistries deepens.
For Market Incumbents: Cement backward integration into naphthalene and anthraquinone intermediates to defend against Chinese dual carbon policy disruptions and feedstock cost volatility. Expand technical service teams in Vietnam's Ho Chi Minh City processing zones to capture relocated garment manufacturing demand. Prioritize ZDHC MRSL certification investments as brand-led chemical management unbundles dye procurement from fabric sourcing. For New Entrants and Emerging Players: Begin with digital textile printing pigment dispersions for short-run customization channels in fashion and home textile verticals, where incumbent presence remains thin. Target Vietnam's apparel export surge as large dye houses have not yet established technical service density. Partner with supercritical CO2 technology licensors to differentiate on water stewardship credentials for premium sportswear contracts. For Investors and Strategic Acquirers: Valuations sit cheapest among regional volume players serving fragmented dyeing contractors, where margin compression from petrochemical feedstock volatility has depressed multiples relative to integrated conglomerates. Five-to-ten year viability favors specialty dye houses with ZDHC-certified low-impact portfolios as regulatory divergence between jurisdictions extends reformulation investment timelines. Monitor ECHA azo dye metabolite threshold announcements as inflection indicators for reactive chemistry demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Intermediates | Captive naphthalene supply insulates Huntsman and BASF from Chinese dual carbon policy disruptions. |
| Supercritical CO2 Technology Licensing | German technical fabricators piloting installations gain water stewardship certifications for retail placement. |
| ZDHC MRSL Certification Investment | Archroma's conformance positioning captures brand-led chemical management contract unbundling. |
| Vietnam Processing Zone Expansion | REACH-compliant reactive dye demand concentrates in Ho Chi Minh City garment manufacturing clusters. |
| Digital Textile Printing Pigment Development | Low-cure dispersions open short-run customization for fashion verticals with limited incumbent presence. |
Research Methodology
Bottom-up textile mill capacity modeling reconciled against top-down dye intermediate production tracking forms the analytical core of this study. Primary interviews with plant managers at Gujarat and Tamil Nadu processing hubs, procurement leads at European apparel brands, technical R&D directors at specialty dye houses, and distribution channel partners in Vietnam supplied operational data. Secondary validation drew from customs and trade databases, chemical industry association reports, SEC 10-K filings of listed dye manufacturers, and ECHA regulatory disclosure filings. Triangulation between demand-side procurement patterns and supply-side intermediate output ensures consistency across estimation procedures.
Input-output matrices mapping fiber throughput to dye consumption coefficients by chemistry type generate volume projections across the analysis window. Segmentation dimensions encompass product chemistry, application durability requirements, end-user integration depth, and regional regulatory cluster. CAGRs derive from weighted average of historical trajectory analysis and forward-looking capacity expansion announcements. Forecast inputs include polyester sportswear production scaling, REACH metabolite restriction implementation timelines, and India's PLI scheme technical textile incentive disbursement rates.
Several conditions sit outside the modeled scope, including abrupt trade policy shifts, force majeure disruptions at concentrated intermediate production facilities, and faster-than-anticipated bio-based chromophore substitution. Forecasts reflect documented assumptions about regulatory enforcement consistency and brand compliance investment continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Chemicals, Dyes, and Finishing
Functional Textile Finishing Agents Market
Textile Chemicals, Dyes, and Finishing
Textile Leveling Agent Market
Textile Chemicals, Dyes, and Finishing
Shellac Market
Textile Chemicals, Dyes, and Finishing
Textile Finishing Agents Market
Textile Chemicals, Dyes, and Finishing
Europe Textile Dyes Market
Textile Chemicals, Dyes, and Finishing
Laminated Fabrics Market
Textile Chemicals, Dyes, and Finishing
PVC Tarpaulin Sheets Market
Textile Chemicals, Dyes, and Finishing
Organic Dyes Market
Textile Chemicals, Dyes, and Finishing
Disperse Dyes Market
Textile Chemicals, Dyes, and Finishing
Textile Wax Market
Textile Chemicals, Dyes, and Finishing
Leather Dyes Market
Textile Chemicals, Dyes, and Finishing
3-Layer Seam Tapes Market
Textile Chemicals, Dyes, and Finishing
Textile Chemicals Market
Textile Chemicals, Dyes, and Finishing
Unbleached Twill Tapes Market
Textile Chemicals, Dyes, and Finishing
Global Textile Dyes Market
Textile Chemicals, Dyes, and Finishing
Waterless Textile Dyeing Services Market