
 Impression Die Forging Market | 2026-2036
Impression Die Forging Market Size, Share, and Industry Trends Forecast 2026-2036
Impression Die Forging Market Foresight
Equipment leasing and project finance is narrowing the capital barrier for mid-scale forge operators seeking multi-ton press capacity. Bharat Forge Limited leverages its integrated steel-to-component pipeline to sustain cost advantages in crankshaft and axle beam production. ATI anchors its position through captive titanium melt capacity and long-term aerospace supply agreements. Ellwood Group Inc. competes via deep vertical integration into tool steel and custom alloy ingot production.
Impression die forging shapes metal between two dies that contain a precut profile of the desired part, typically achieving tolerances of ±0.5 mm and grain flow alignment critical to fatigue resistance. The process produces components with strength-to-weight ratios essential for safety-critical load-bearing applications. Steel dominates material consumption across automotive and heavy equipment end users, though titanium and aluminum segments are expanding fastest as aerospace OEMs reduce airframe weight. Shaft and ring product categories command premium margins due to longer qualification cycles and tighter metallurgical specifications. Structural components and engine parts applications concentrate the highest value demand, particularly where NADCAP and AS9100 certifications gate supplier approval.
FAA airworthiness directives and EPA foundry emissions standards shape product design and facility investment requirements in the United States. EASA certification protocols and REACH substance restrictions govern European market access and material composition disclosures. Stakeholders must monitor evolving sustainability disclosure obligations from the EU Green Deal and CSRD, which will increasingly filter forge supplier selection criteria across automotive and aerospace procurement teams.
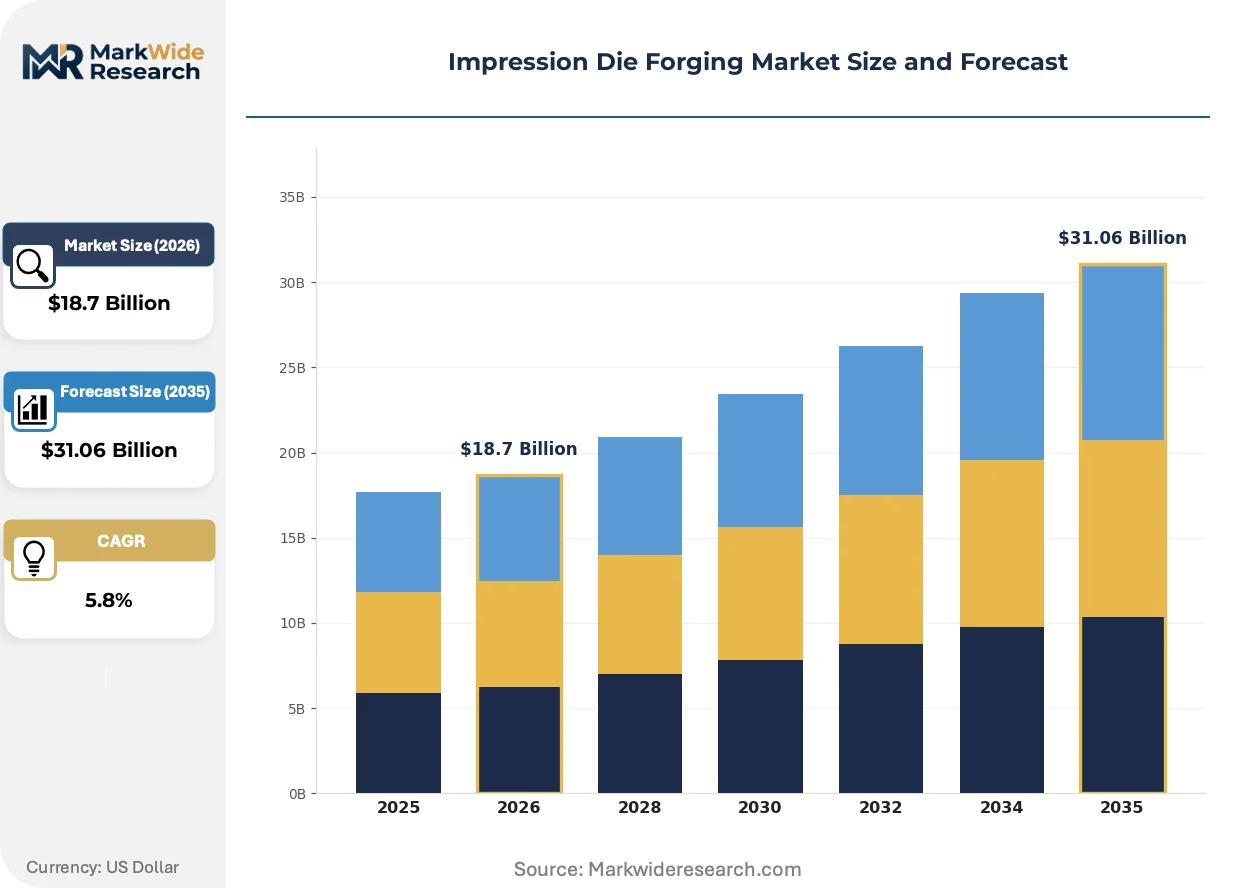
Market Dynamics
REACH substance restrictions and EU Green Deal emissions standards are forcing European forges to reconfigure material sourcing and energy intensity, while aerospace OEMs in Germany and the United States accelerate procurement of titanium structural components to meet airframe weight reduction targets.
Growth Catalysts
- Aerospace lightweighting mandates:Commercial aviation OEMs are specifying forged titanium and aluminum components to reduce fuel consumption, tightening metallurgical specifications and extending qualification cycles for approved suppliers.
- REACH traceability requirements:European chemical disclosure rules are filtering supplier selection criteria across automotive and aerospace procurement teams, advantaging forges with certified material pedigree systems.
- German supplier network density:Automotive OEMs and tier suppliers in Baden-Württemberg and Bavaria maintain concentrated forging ecosystems that reduce logistics costs and accelerate prototype-to-production cycles.
Market Restraints
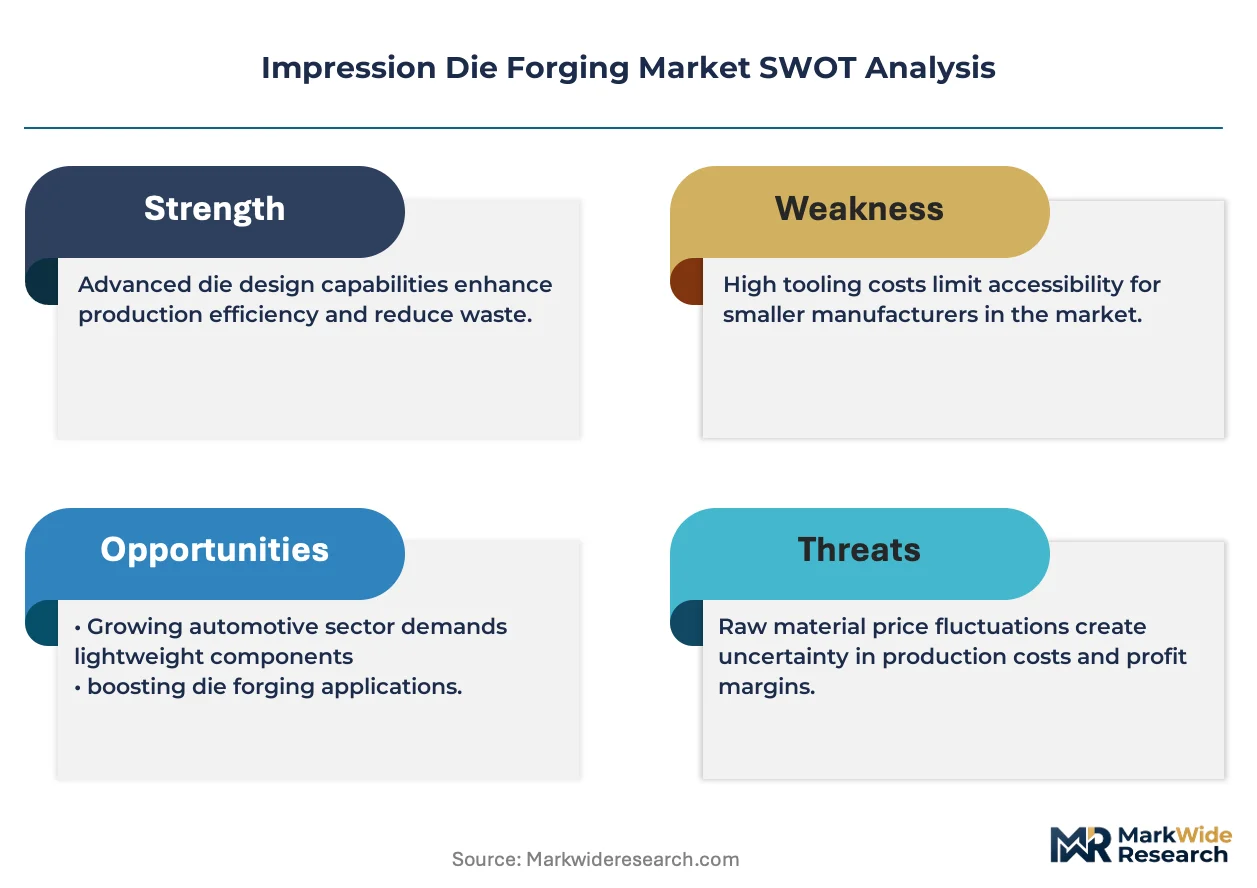
- Scrap steel price volatility:Input cost swings for high-grade steel billets compress margin predictability for automotive crankshaft and axle beam producers operating on annual price contracts.
- Titanium sponge supply concentration:Limited global sources for aerospace-grade titanium raw material create vulnerability to geopolitical disruption and extended lead times for qualified melt stock.
- FAA airworthiness directive compliance:Evolving FAA certification protocols for flight-critical forged components extend qualification timelines and freeze design specifications mid-development.
Strategic Opportunities
- India industrial corridor expansion:PLI scheme incentives for automotive and defense manufacturing are creating demand for domestic forging capacity to serve OEMs establishing assembly operations in Tamil Nadu and Maharashtra.
- CSRD sustainability disclosure alignment:Early compliance with EU corporate sustainability reporting requirements positions forges to capture procurement preference from European automotive and aerospace buyers.
- Hybrid forging-additive manufacturing:Convergence of precision forging with directed energy deposition enables near-net-shape production of complex titanium aerostructures previously machined from solid billets.
Industry Challenges
- NADCAP heat treat auditor scarcity:Limited pool of qualified auditors extends certification timelines for aerospace suppliers seeking special process accreditation for titanium and superalloy components.
- Multi-ton press capital intensity:Greenfield installation of 10,000+ ton mechanical or hydraulic forging presses requires eight-figure investment with decade-long depreciation horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Impression Die Forging Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flange, Gear, Shaft, Ring Material: Steel, Aluminum, Titanium, Copper End User: Aerospace, Automotive, Marine, Heavy Equipment Application: Structural Components, Engine Parts, Transmission Parts, Tooling |
| Companies Covered | Bharat Forge Limited, ATI, Aubert & Duval, Nippon Steel & Sumitomo Metal, Ellwood Group Inc., Mahindra Forgings Europe AG, Böhler Schmiedetechnik GmbH & Co KG, Maschinenfabrik Alfing Kessler GmbH, Bifrangi SpA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Impression Die Forging Market Shifts & Advancements
Digital thread integration across design, simulation, and production is compressing development cycles for complex forged components while regulatory pressure on embodied carbon intensifies material and process scrutiny across supply chains.
Closed-loop forging process control using real-time thermal imaging and machine learning is digitizing quality assurance workflows. Aerospace tier suppliers in Germany and the United States are deploying these systems to reduce inspection bottlenecks and compress first-article approval timelines. The technology is digitizing documentation trails that previously required manual metallurgical review, enabling faster NADCAP and AS9100 surveillance audits.
EU Green Deal carbon border adjustment mechanisms are tightening emissions disclosure requirements for imported steel and aluminum forgings. European automotive OEMs are now mandating supplier-specific carbon intensity data for crankshaft and connecting rod procurement decisions. German forges with electric arc melt capacity and renewable energy sourcing are capturing preference over Southern European competitors reliant on coal-based production.
Consolidated direct sourcing from forge operators is displacing traditional distributor intermediaries in North American aerospace supply chains. Tier 1 aerostructure manufacturers in Wichita and Dallas-Fort Worth are establishing multi-year offtake agreements with qualified titanium forges, bypassing metal service centers that previously managed inventory and logistics. This pattern is most visible in structural component categories where NADCAP special process accreditation gates supplier approval.
Impression Die Forging Market Segmentation
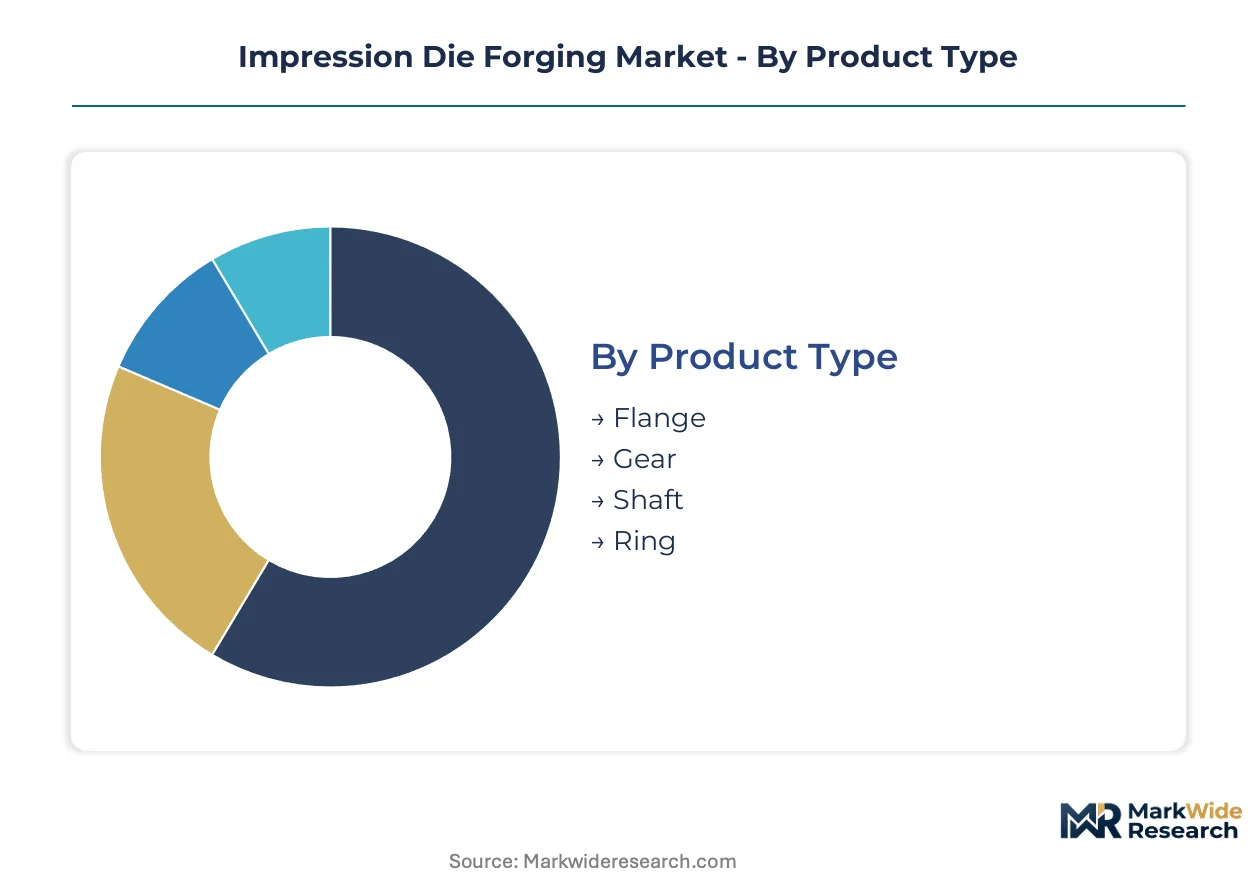
Impression die forging serves divergent performance requirements across aerospace fatigue-critical structures and automotive high-volume drivetrains. Segment-specific metallurgical specifications, qualification cycles, and tooling investments create distinct competitive moats that reshape supplier selection criteria.
Product Type:
After-sales service intensity varies sharply across product categories, with flight-critical shaft and ring components demanding dedicated field engineering support while commodity flanges operate on standard warranty terms.
- Shaft:Longitudinal grain flow alignment delivers torsional fatigue resistance for crankshaft and transmission applications. German automotive OEMs in Baden-Württemberg specify these for high-torque drivetrain architectures, with qualification cycles extending supplier relationships across multiple vehicle platforms.
- Ring:Radial forging produces seamless circumferential grain structures essential for bearing races and turbine casings. Aerospace demand concentrates in Wichita and Dallas-Fort Worth clusters where NADCAP heat treat accreditation gates supplier approval for titanium and superalloy variants.
- Flange:Standardized geometries serve pipeline and structural bolting applications with shorter lead times and lower metallurgical documentation burdens.
- Gear:Precision-forged tooth profiles reduce machining requirements for heavy equipment and automotive transmission producers seeking net-shape economics.
Shaft holds the largest share; momentum sits with Ring as aerospace OEMs expand titanium structural procurement.
Material:
Cost tier stratification separates commodity steel grades from premium titanium alloys, with aluminum occupying a mid-tier position where automotive lightweighting intersects with forgeable specifications.
- Steel:High-grade carbon and alloy steels dominate automotive crankshaft and axle beam production due to established supply chains and mature heat treatment protocols. Bharat Forge Limited leverages integrated steel-to-component pipelines to sustain cost advantages in this segment.
- Titanium:Aerospace-grade sponge sourcing from limited global suppliers creates supply vulnerability, yet forged titanium structural components command premium margins where AS9100 certification and captive melt capacity differentiate ATI and qualified competitors.
- Aluminum:Forged aluminum suspension and structural components serve automotive weight reduction mandates with faster forging cycles than titanium.
- Copper:Electrical conductivity specifications drive demand for forged copper busbars and connector housings in heavy equipment power distribution systems.
Steel retains volume leadership; titanium is expanding most quickly as airframe weight reduction targets tighten metallurgical specifications.
End User:
Customer type segmentation separates specification-intensive aerospace buyers from price-sensitive automotive procurement teams, with marine and heavy equipment occupying intermediate positions on technical documentation requirements.
- Aerospace:FAA airworthiness directives and EASA certification protocols impose extended qualification timelines for flight-critical forged components. Tier 1 aerostructure manufacturers are consolidating direct sourcing relationships with qualified titanium forges, bypassing traditional metal service centers.
- Automotive:Annual price contracts and dense supplier networks in Germany compress margins for crankshaft and connecting rod producers exposed to scrap steel price volatility.
- Heavy Equipment:Mining and construction machinery OEMs specify forged structural components for load-bearing applications with moderate lot sizes and intermittent demand patterns.
- Marine:Corrosion-resistant alloy requirements for propulsion shafting and deck hardware create specialized demand for duplex stainless and nickel-copper forgings.
Aerospace commands premium positioning; automotive anchors volume throughput across forging capacity installations.
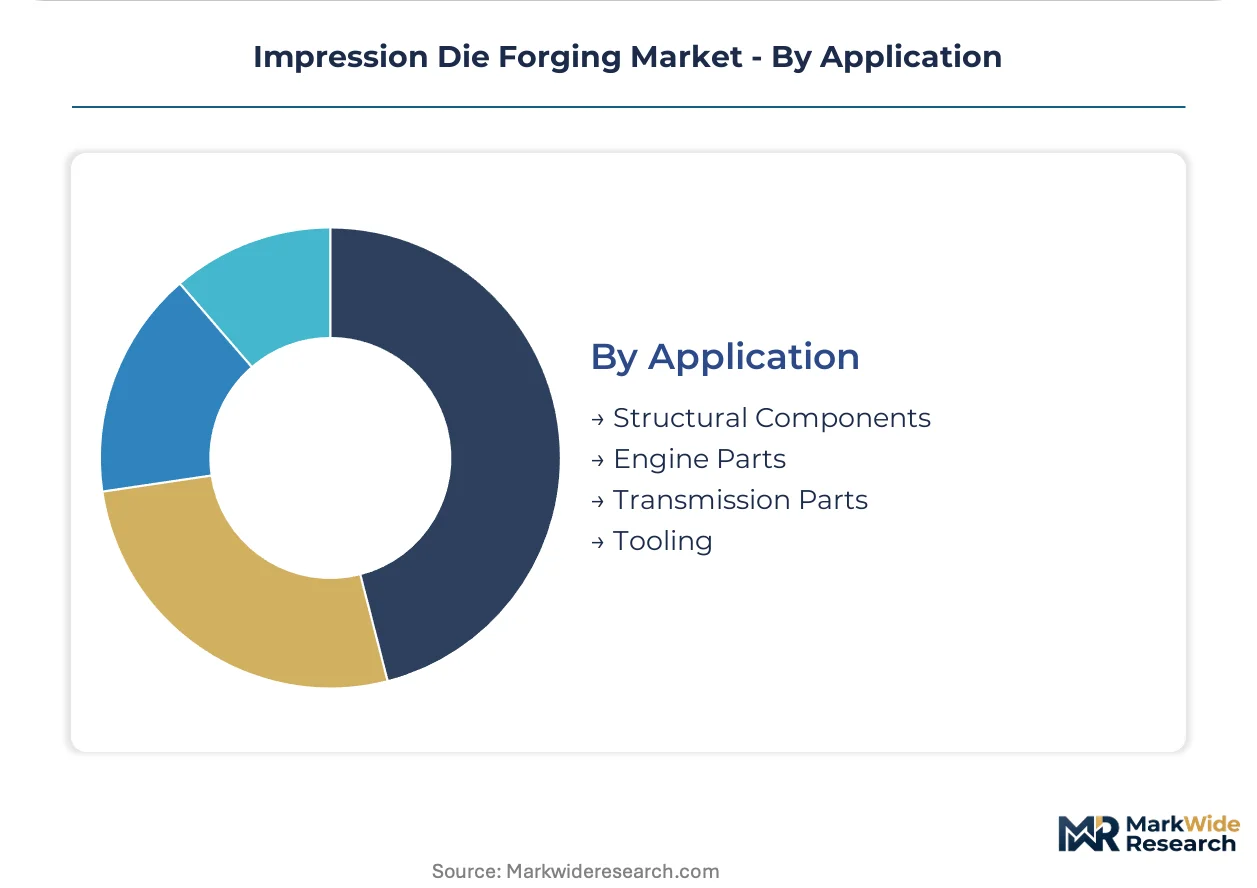
Application:
Supply concentration patterns align with certification barriers, where structural components and engine parts concentrate qualified supplier pools while tooling applications tolerate broader sourcing.
- Structural Components:Wing and fuselage forgings require NADCAP special process accreditation for heat treatment and non-destructive testing. Closed-loop process control using real-time thermal imaging is digitizing quality assurance workflows for German and US aerospace tier suppliers.
- Engine Parts:Turbine disk and compressor blade forgings demand vacuum arc remelt titanium and superalloy specifications with full material pedigree documentation to satisfy REACH traceability requirements.
- Transmission Parts:Synchronizer hubs and gear blanks serve high-volume automotive production with standardized forging sequences and automated inspection protocols.
- Tooling:Die and mold inserts for plastic injection and metal stamping applications utilize tool steel forgings with less stringent certification requirements than aerospace or automotive safety-critical categories.
Structural Components capture the highest value concentration; Engine Parts follow as propulsion system OEMs advance next-generation thermal efficiency targets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German forges command pricing premiums through NADCAP-accredited titanium capacity, while Indian operators capture volume share via PLI-subsidized automotive component exports. This asymmetry reflects divergent certification barriers and energy cost structures across supplier bases.
United States
Wichita and Dallas-Fort Worth aerospace clusters drive titanium structural component demand for commercial aviation programs. FAA airworthiness directives extend qualification timelines for flight-critical forgings, consolidating procurement around NADCAP-accredited suppliers. Tier 1 aerostructure manufacturers are establishing direct offtake agreements with qualified forges, bypassing traditional metal service centers.
Germany
Baden-Württemberg and Bavaria host dense automotive OEM and tier supplier networks that compress logistics costs for crankshaft and axle beam producers. REACH substance restrictions and EU Green Deal emissions standards filter supplier selection toward forges with certified material pedigree systems. Electric arc melt capacity with renewable energy sourcing captures procurement preference over coal-dependent competitors.
India
PLI scheme incentives for automotive and defense manufacturing are creating demand for domestic forging capacity in Tamil Nadu and Maharashtra. Bharat Forge Limited leverages integrated steel-to-component pipelines to sustain cost advantages in high-volume drivetrain applications. Central government defense procurement localization mandates are accelerating indigenization of aerospace-grade titanium capabilities.
China
Dual carbon goals and MIIT industrial upgrading directives are pressuring foundries to reduce coal-based production intensity in the Yangtze River Delta. Domestic aerospace OEMs are expanding procurement of forged aluminum structural components for commercial aircraft programs. SAMR quality certification requirements are tightening metallurgical documentation standards for export-bound automotive forgings.
Japan
METI supply chain resilience initiatives are incentivizing domestic titanium sponge and forging capacity for aerospace and defense applications. JIS standards govern material specifications for automotive transmission components serving Toyota and Honda production networks. Chubu region industrial clusters concentrate precision forging expertise for high-torque drivetrain architectures.
Impression Die Forging Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream on material and process differentiation. The supplier base stratifies between scale-driven automotive producers and certification-intensive aerospace specialists. Three archetypes dominate: integrated steel-to-component operators, captive titanium melt holders, and precision forging technology licensors. Capacity expansion and strategic partnerships constitute the primary competitive vectors as firms seek to bridge certification gaps and secure long-term offtake agreements.
Among the named participants, Bharat Forge Limited represents the integrated steel-to-component archetype with demonstrated cost advantages in high-volume automotive applications. ATI occupies a position anchored by captive titanium melt capacity and aerospace supply relationships. Ellwood Group Inc. exemplifies specialization in custom alloy and tool steel ingot production. Böhler Schmiedetechnik GmbH & Co KG and Maschinenfabrik Alfing Kessler GmbH sit within the German precision forging tier serving automotive OEM qualification requirements.
| Leading Market Players |
|---|
| Bharat Forge Limited |
| ATI |
| Aubert & Duval |
| Nippon Steel & Sumitomo Metal |
| Ellwood Group Inc. |
| Mahindra Forgings Europe AG |
| Böhler Schmiedetechnik GmbH & Co KG |
| Maschinenfabrik Alfing Kessler GmbH |
| Bifrangi SpA |
| Others |
Supply & Pricing Matrix
Baden-Württemberg's dense automotive OEM and tier supplier networks concentrate forging capacity in southwestern Germany, translating into pricing power for NADCAP-accredited operators serving aerospace qualification requirements. REACH traceability mandates and EU Green Deal carbon intensity disclosures filter procurement toward forges with certified material pedigree systems, compressing margins for coal-dependent competitors while rewarding electric arc melt capacity with renewable energy sourcing.
Pricing Analysis
Configured-to-order pricing for flight-critical titanium structural components commands substantial premiums over standard-grade steel crankshaft production. Contract-based long-term offtake agreements dominate aerospace procurement, with price differentiation driven by NADCAP special process accreditation and captive titanium melt capacity. Cost compression in automotive steel forgings is intensifying because annual price contracts expose producers to scrap steel price volatility. Automotive OEM procurement teams exhibit highest price sensitivity, while aerospace tier 1 manufacturers prioritize qualification reliability over unit cost.
Supply Chain Analysis
Supplier-financing facilities and extended payment terms are becoming standard instruments for German and Indian forges managing multi-ton press capital intensity. Geographic supply concentration centers on Germany, India, and the United States, with raw material dependencies on aerospace-grade titanium sponge, high-grade steel billets, and aluminum alloy ingots. Single-source vulnerability in titanium sponge sourcing from limited global suppliers creates structural risk. Distribution runs through direct offtake agreements consolidating procurement relationships between tier 1 aerostructure manufacturers and qualified forges.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Impression die forging sits in early-cycle expansion as aerospace lightweighting mandates accelerate qualification of titanium structural components for next-generation airframe programs. Hybrid forging-additive manufacturing convergence creates additional penetration vectors for near-net-shape production previously machined from solid billets.
For Market Incumbents: Pre-empt emerging competition from Indian PLI-subsidized operators by securing captive titanium melt capacity and accelerating NADCAP heat treat accreditation timelines. Consolidate around backward integration into tool steel and custom alloy ingot production to defend margin position against scrap steel price volatility. Channel control through direct offtake agreements with Wichita and Dallas-Fort Worth aerospace clusters reduces distributor intermediation risk. For New Entrants and Emerging Players: Build out domestic forging capacity in Tamil Nadu and Maharashtra to capture PLI scheme incentives for automotive and defense manufacturing localization. Aerospace-grade titanium capabilities represent the most penetrable white-space target given central government defense procurement indigenization mandates. A go-to-market angle anchored in CSRD sustainability disclosure alignment positions new entrants for European automotive and aerospace procurement preference. For Investors and Strategic Acquirers: Long-term, this sits as a certification-intensive industrial play because NADCAP and AS9100 accreditation gates create durable competitive moats with decade-long supplier relationships. Acquisition targets should display integrated steel-to-component pipelines or captive titanium melt capacity. The signal to watch is consolidation of direct sourcing relationships bypassing metal service centers in North American aerospace supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Titanium Melt Capacity | Captive sponge-to-forge pipelines secure supply continuity against geopolitical disruption of limited global sources. |
| NADCAP Heat Treat Accreditation Investment | Special process certification gates supplier approval for flight-critical components in Wichita and Dallas-Fort Worth clusters. |
| CSRD Sustainability Disclosure Alignment | Early compliance positions forges to capture procurement preference from European automotive and aerospace buyers. |
| Hybrid Forging-Additive Manufacturing Deployment | Directed energy deposition convergence enables near-net-shape production of complex titanium aerostructures. |
| Direct Offtake Agreement Consolidation | Bypassing metal service centers strengthens tier 1 aerostructure manufacturer relationships in North American supply chains. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with aerospace procurement directors, automotive tier 1 supplier quality managers, forging plant operations heads, and metallurgical engineering consultants. Secondary validation drew from FAA airworthiness directive filings, EASA certification protocols, SEC 10-K disclosures from publicly traded forge operators, and EU Green Deal implementation guidance documents. Bottom-up capacity installation data and top-down end-use demand estimates were triangulated to anchor market sizing.
Calibration against historical qualification cycle timelines and press capacity utilization rates informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, material grade tier, end-user industry, and application certification level, with regional production cluster dynamics as an industry-specific overlay. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion announcements, incorporating titanium sponge supply constraints and PLI scheme incentive trajectories as forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by state-subsidized Indian operators or rapid Chinese aerospace-grade capacity buildout would shift outcomes beyond modeled ranges. Macroeconomic deviation, regulatory acceleration of REACH substance restrictions, or breakthroughs in solid-state forging technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Precision Mechanics and Electrics
Global Ball Screw Market
Precision Mechanics and Electrics
Precision Engineering Machines Market
Precision Mechanics and Electrics
Precision Roller Levelers Market
Precision Mechanics and Electrics
Industrial Spindles Market
Precision Mechanics and Electrics
Laser Surface Texturing Market
Precision Mechanics and Electrics
Precision Strain Wave Reducer Gearboxes Market
Precision Mechanics and Electrics
Precision Turned Product Manufacturing Market
Precision Mechanics and Electrics
Turning Machining Product Market
Precision Mechanics and Electrics
Asia-Pacific Precision Turned Product Manufacturing Market
Precision Mechanics and Electrics
Right Angle Fastener Market
Precision Mechanics and Electrics
Laser Cladding Market
Precision Mechanics and Electrics
High Precision Worm Shaft Market
Precision Mechanics and Electrics
North America Precision Turned Product Manufacturing Market
Precision Mechanics and Electrics
Precision Adjustment Screw Market