
 Steam Boiler Market | 2026-2036
Steam Boiler Market Size, Share, and Industry Trends Forecast 2026-2036
Steam Boiler Market Analysis
China's industrial heartland is reshaping competitive dynamics in steam boiler supply. Babcock & Wilcox Enterprises leverages its legacy in supercritical boiler technology to sustain premium positioning in utility-scale installations. Mitsubishi Heavy Industries anchors its presence through integrated energy systems that combine boiler output with turbine co-generation. Siemens competes on digital control architectures that optimize combustion efficiency across distributed steam networks.
A steam boiler is a closed vessel that converts water to steam through thermal energy transfer, operating at pressures typically ranging from 15 psi to over 3,200 psi depending on application requirements, and serves as the thermal backbone for power generation, process heating, and district heating systems. Water-tube configurations dominate utility and power generation installations where higher pressures and superheated steam are required, while fire-tube designs retain cost advantages in smaller industrial footprints. Electric boilers are gaining traction in food processing and healthcare end-user segments where emissions restrictions and precise temperature control outweigh fuel cost considerations.
The EPA enforces Maximum Achievable Control Technology standards for industrial boilers under the Clean Air Act, while the EU Green Deal's F-Gas Regulation and Ecodesign requirements are phasing out high-emission combustion systems across member states. India's Central Pollution Control Board mandates particulate matter limits that compel manufacturing facilities to retrofit or replace aging coal-fired units with natural gas or biomass alternatives. Stakeholders must monitor how carbon border adjustment mechanisms and evolving efficiency mandates redistribute equipment demand across fuel types and installation configurations.
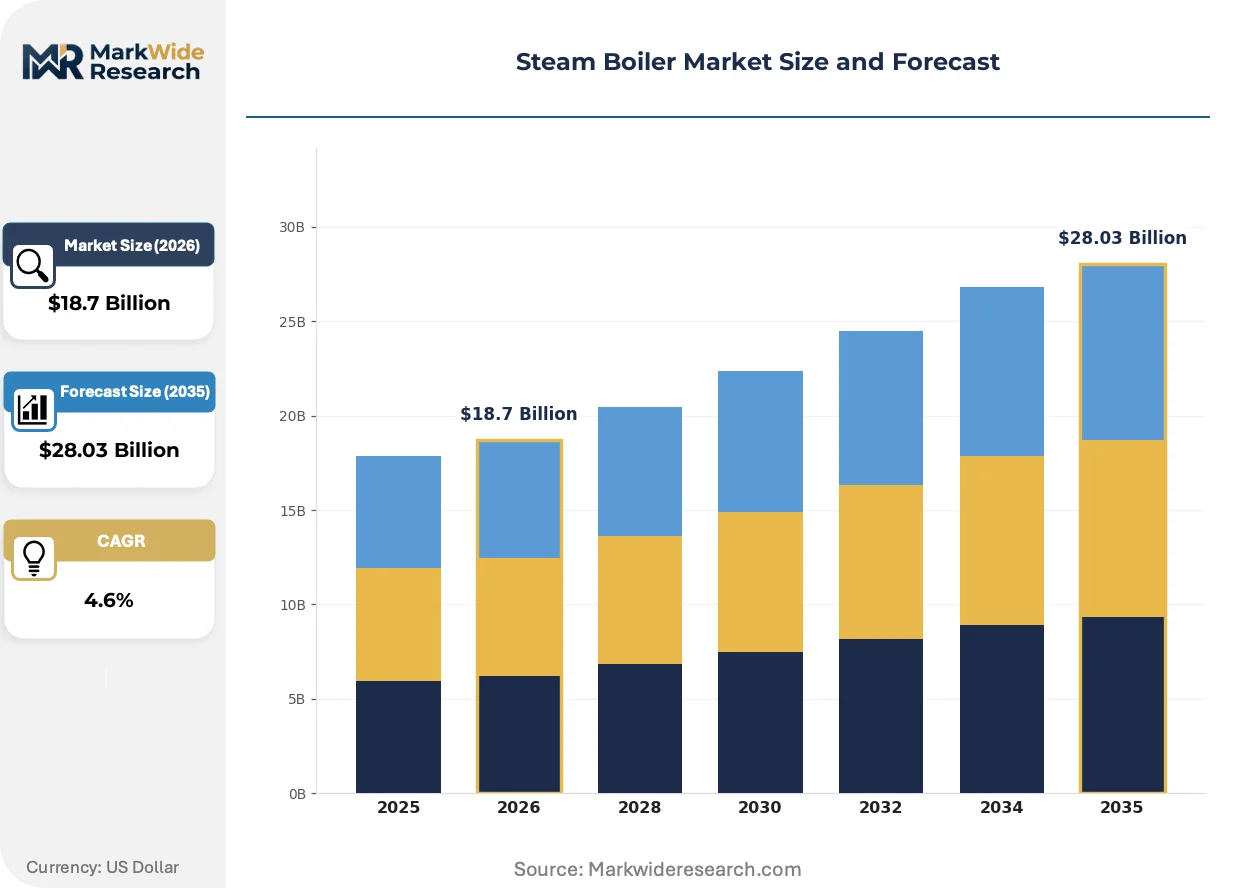
Market Dynamics
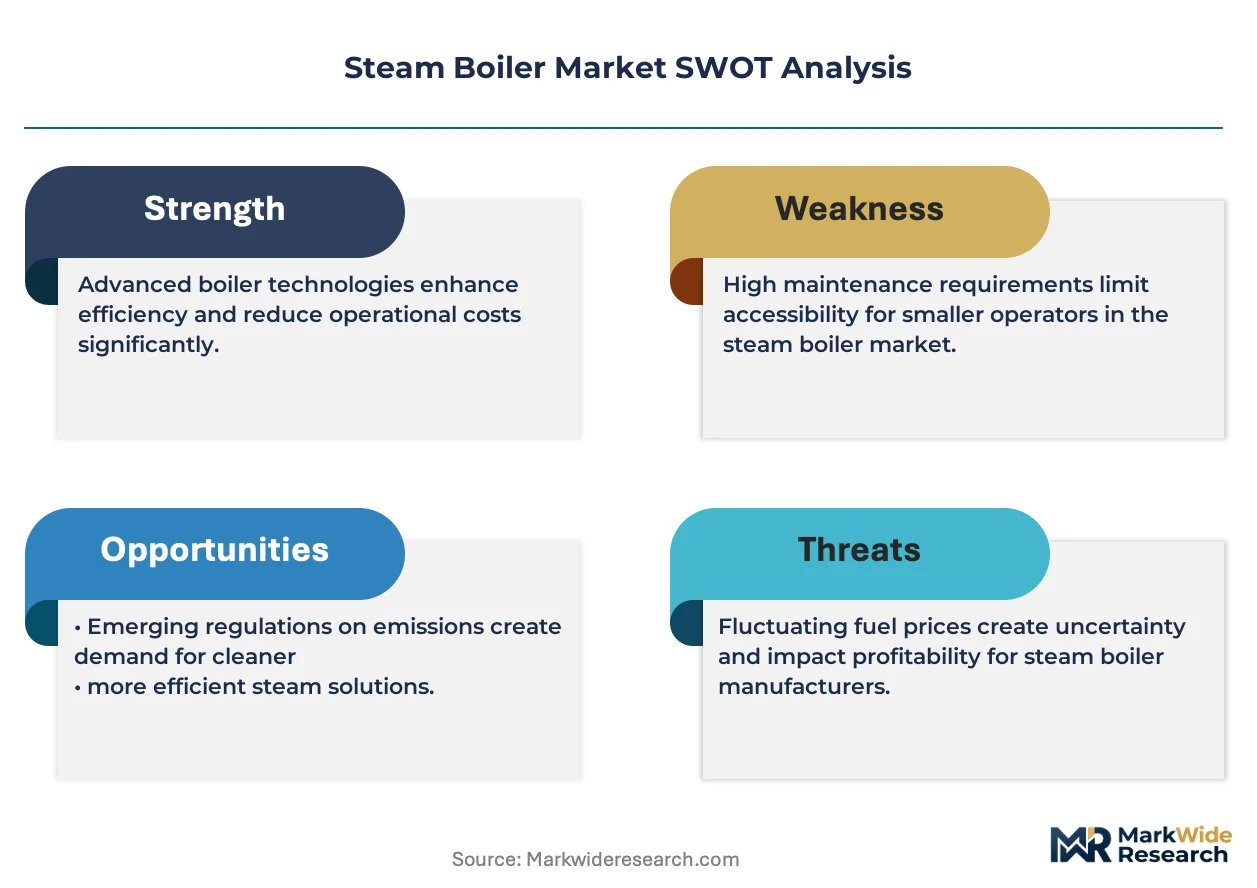
EPA Maximum Achievable Control Technology standards and the EU Green Deal's F-Gas Regulation are forcing steam boiler operators to retire coal-fired assets and absorb retrofit costs that alter fleet economics across industrial clusters.
Growth Catalysts
- India's PLI scheme for manufacturing:Domestic energy security targets are accelerating boiler fleet modernization in chemical and textile processing facilities. The Central Electricity Authority mandates efficiency upgrades that drive replacement cycles.
- Biomass co-firing technology:Agricultural residue combustion systems enable carbon-neutral steam generation for food processing plants in Southeast Asia. Installations are expanding in palm oil processing corridors.
- EU Ecodesign requirements:Phase-out mandates for high-emission combustion systems are creating replacement demand across member state industrial parks. Natural gas and electric alternatives are capturing displaced coal capacity.
Market Restraints
- Steel alloy price volatility:Superheater tube materials and pressure vessel-grade carbon steel exhibit cyclical cost swings that compress fabrication margins. Chinese mill output fluctuations transmit directly to boiler OEM cost structures.
- Specialized welder scarcity:ASME Section IX certified pressure vessel welders concentrate in legacy manufacturing regions. Training pipeline gaps extend fabrication lead times for custom water-tube configurations.
- Electrification substitution:Industrial heat pumps and thermal storage systems capture low-temperature process loads below 150°C that previously required saturated steam. Food sterilization and CIP applications are pivoting first.
Strategic Opportunities
- Indonesia's nickel processing corridor:Hydrometallurgical refining facilities require high-pressure steam for leaching operations. Domestic boiler fabrication capacity is underdeveloped relative to demand scale.
- Carbon capture integration:Post-combustion amine scrubbing retrofits on existing natural gas boilers create aftermarket service revenue streams. Netherlands and UK industrial clusters are piloting bundled steam-plus-capture offerings.
- Digital twin convergence:Real-time combustion optimization layered with predictive maintenance algorithms reduces unplanned outages. German automotive suppliers are early adopters for just-in-time thermal reliability.
Industry Challenges
- ASME stamp certification timelines:Third-party inspection backlogs for Section I power boiler and Section VIII pressure vessel approvals extend project commissioning schedules. Expedited review fees add 8-12% to project soft costs.
- Legacy DCS integration friction:Modern boiler control architectures must interface with decades-old distributed control systems in established process plants. Protocol translation and cybersecurity hardening consume engineering resources.
- Commissioning engineer mobility:Field startup specialists for supercritical units concentrate with OEM engineering teams. Project site dispersion across emerging markets strains deployment capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steam Boiler Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fire-Tube, Water-Tube, Electric, Biomass End User: Manufacturing, Power Generation, Food Processing, Healthcare Fuel Type: Natural Gas, Coal, Oil, Wood Installation: On-Premises, Off-Site, Modular, Centralized |
| Companies Covered | Babcock & Wilcox Enterprises, Mitsubishi Heavy Industries, General Electric, Siemens, Alfa Laval, Thermax, Fulton Boiler Works, Cleaver-Brooks, Larsen & Toubro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steam Boiler Market Emerging Trajectories
Steam generation technology is bifurcating between ultra-high-efficiency supercritical systems for power generation and modular electric configurations for distributed process heat, with digital integration threading both pathways.
Electrode boiler technology is hybridizing with thermal storage media to deliver dispatchable steam for grid-balancing applications. Nordic district heating operators are deploying megawatt-scale installations to arbitrage electricity price volatility. This configuration is compressing the operational window for peaking gas boilers in combined heat and power networks.
The EU F-Gas Regulation's phase-down schedule for fluorinated greenhouse gases is compelling refrigerant-based heat pump manufacturers to accelerate CO2 transcritical cycle development. Industrial process heat applications above 90°C previously served by steam are now technically accessible to high-pressure CO2 systems. German chemical parks are piloting this displacement in low-pressure steam zones.
Asset-as-a-service contracting is displacing traditional capital purchase models for packaged boiler systems. Food and beverage processors in the UK are prioritizing opex-aligned agreements that bundle fuel management, maintenance, and emissions compliance. This preference shift is concentrating procurement authority with energy service companies and compressing direct OEM sales channels.
Steam Boiler Market Segmentation
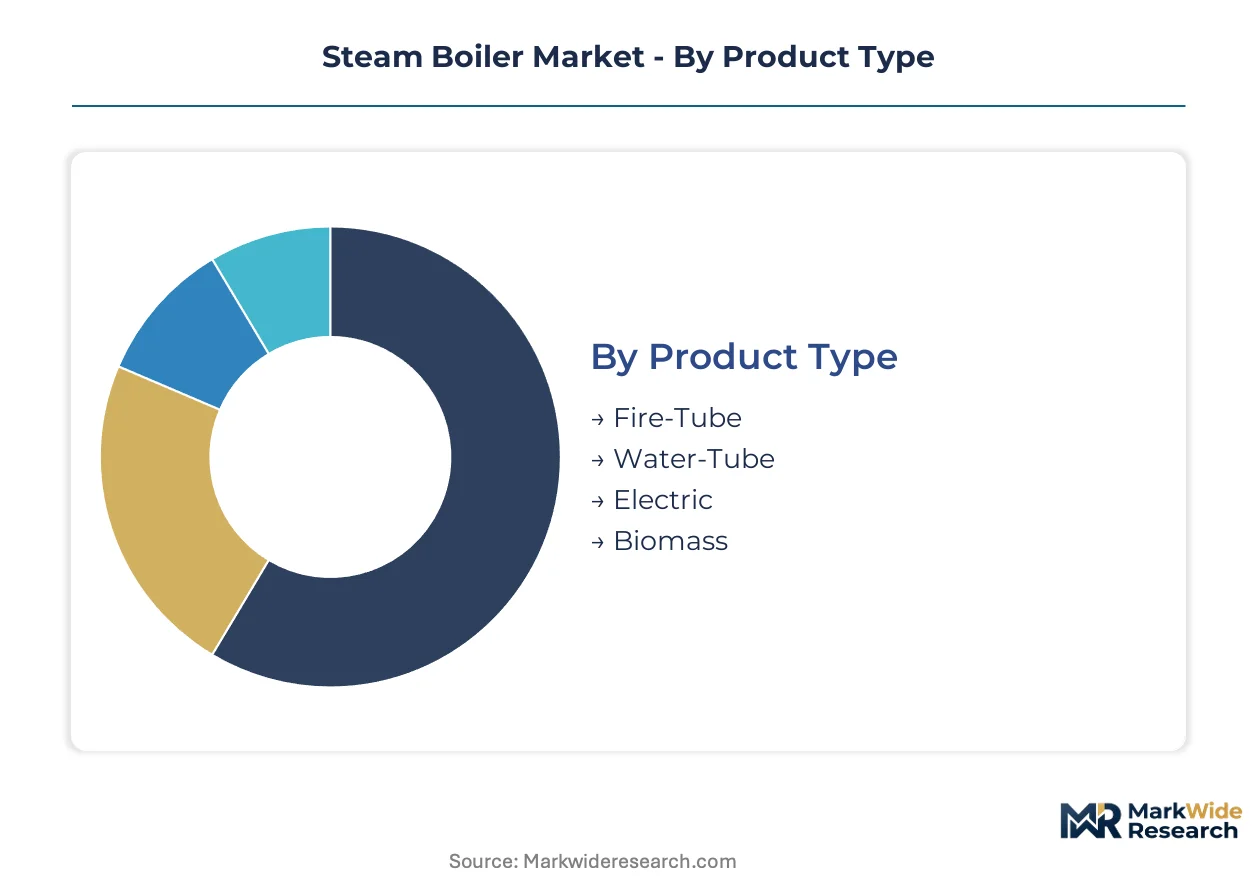
Steam boiler procurement patterns diverge sharply across technical configurations and operational contexts. Segmentation reveals where replacement cycles compress under regulatory pressure versus where legacy assets persist despite efficiency penalties.
Product Type:
Fire-tube units turn over fastest in small industrial footprints where capital constraints dominate, while water-tube systems in utility installations cycle slowest due to extended amortization schedules and integration complexity.
- Fire-Tube:Hot gases pass through tubes submerged in water, enabling rapid steam production at lower pressure ratings. Food processing facilities in India favor these for batch operations where intermittent demand patterns match quick-start thermal profiles. The PLI scheme's capital subsidies accelerate replacement of aging coal-fired fire-tube units in textile corridors.
- Water-Tube:Water circulates through tubes exposed to combustion heat, accommodating supercritical pressures above 3,200 psi. Southeast Asian chemical manufacturers specify these for continuous process steam where unplanned outages carry catastrophic yield losses. Hydrometallurgical nickel refining in Indonesia demands high-pressure configurations that only water-tube architectures deliver.
- Electric:Resistance or electrode elements convert electrical energy directly to steam without combustion emissions. Healthcare facilities in EU member states specify these where F-Gas Regulation compliance eliminates fossil fuel alternatives.
- Biomass:Agricultural residue combustion systems generate carbon-neutral steam through controlled gasification or direct firing. Palm oil processing clusters in Malaysia and Indonesia deploy these to monetize empty fruit bunch waste streams.
Fire-tube designs dominate installed base across small and medium industrial facilities. Water-tube configurations are where expansion concentrates as process industries scale steam-intensive capacity.
End User:
Cost tier separation is pronounced: power generation and large manufacturing absorb premium supercritical systems while healthcare and food processing optimize for opex flexibility and emissions compliance.
- Manufacturing:Chemical, textile, and metal fabrication facilities consume saturated steam for process heating, drying, and reaction vessel temperature control. India's Central Electricity Authority mandates efficiency upgrades that compel boiler fleet modernization across state industrial parks.
- Power Generation:Utility-scale installations require superheated steam at extreme pressures to drive turbine efficiency. Coal-to-gas conversion projects in Germany and the Netherlands favor natural gas-fired water-tube units with integrated carbon capture readiness.
- Food Processing:Sterilization, pasteurization, and clean-in-place operations demand precise temperature control and rapid thermal response. UK processors increasingly specify asset-as-a-service contracts that bundle fuel management with emissions compliance.
- Healthcare:Hospitals require redundant steam supply for sterilization, humidification, and kitchen operations where reliability failures risk patient safety. Electric boilers gain preference where local air quality regulations prohibit on-site combustion.
Manufacturing absorbs the largest share of annual unit shipments. Power generation is where technology upgrading concentrates as utilities navigate decarbonization pathways.
Fuel Type:
Application context determines fuel selection: natural gas where pipeline infrastructure exists, biomass where agricultural residue supply chains are mature, and coal only where legacy assets face delayed retirement.
- Natural Gas:Cleanest fossil combustion profile with sub-50 ppm NOx achievable through lean-burn burner technology. EU Ecodesign requirements and carbon border adjustment mechanisms accelerate displacement of coal capacity with natural gas alternatives.
- Coal:Lowest fuel cost per thermal unit but highest emissions intensity and regulatory compliance burden. India's Central Pollution Control Board particulate matter limits force manufacturing facilities to retrofit or retire aging coal-fired units.
- Oil:Distillate and residual fuel oils serve remote installations lacking pipeline gas access or as backup fuel for dual-fuel systems. Maritime and island industrial facilities retain oil-fired capacity for supply security.
- Wood:Processed wood chips and pellets deliver carbon-neutral steam generation where sustainable forestry certification assures supply chain integrity. Nordic district heating networks and Central European industrial parks anchor demand.
Natural gas dominates new capacity additions. Biomass is where carbon-neutral positioning drives fastest expansion as sustainability commitments harden.
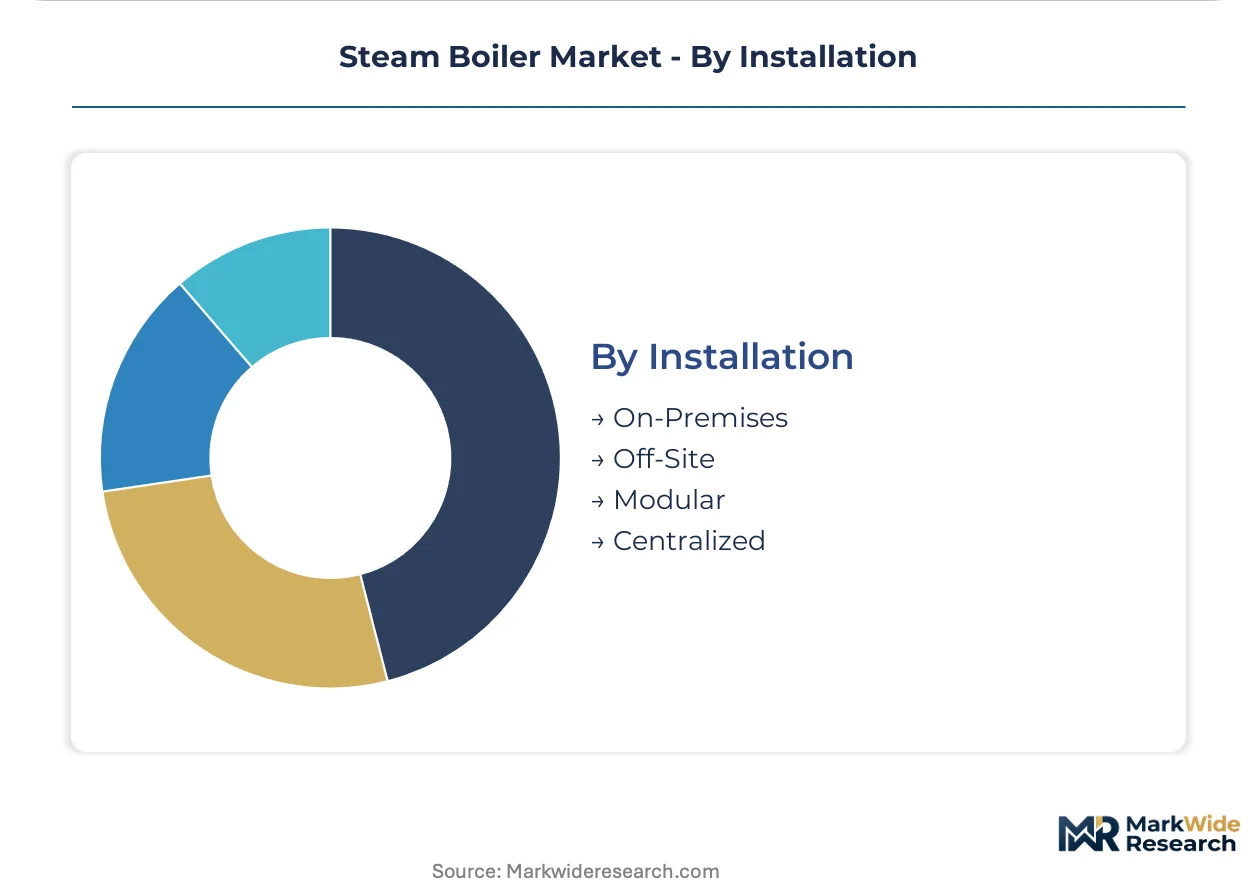
Installation:
Customer type and project scale dictate configuration: centralized utility installations versus modular distributed systems for process industries with evolving thermal footprints.
- On-Premises:Permanently sited boiler plants integrated with facility infrastructure and fuel supply systems. Large manufacturing complexes in India and Southeast Asia favor this model where energy security priorities outweigh operational flexibility.
- Off-Site:Centralized steam generation facilities serving multiple industrial customers through district heating or industrial park networks. Netherlands and UK industrial clusters pilot bundled steam-plus-capture offerings that amortize carbon capture across multiple offtakers.
- Modular:Skid-mounted or containerized units enabling rapid deployment and capacity scaling. Indonesian nickel processing corridors favor these where construction timelines compress against commodity price cycles.
- Centralized:Single large-scale installation serving unified process demand with optimized thermal efficiency. German automotive suppliers deploy these for just-in-time manufacturing where thermal reliability underpins production continuity.
On-premises installations retain largest installed base. Modular configurations are where project velocity and capital flexibility concentrate demand growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Central Electricity Authority anchors demand formation through mandatory efficiency upgrades, while the EU Green Deal and EPA standards reshape fleet economics across industrial clusters in Germany and the United States.
United States
EPA Maximum Achievable Control Technology standards force coal-fired boiler retirements across Ohio River Valley manufacturing corridors. Chemical processors in Texas and Louisiana absorb retrofit costs for NOx compliance on natural gas units. Houston's petrochemical cluster drives replacement demand as facilities phase out aging combustion assets.
Germany
EU Ecodesign requirements and carbon border adjustment mechanisms accelerate coal-to-gas conversion projects in industrial parks. The Netherlands and UK industrial clusters pilot bundled steam-plus-carbon-capture offerings that German utilities observe for replication. Ruhr Valley manufacturing facilities modernize water-tube installations to meet phase-out mandates for high-emission systems.
India
PLI scheme capital subsidies and Central Electricity Authority mandates compress replacement cycles for aging coal-fired fire-tube units. Textile corridors in Gujarat and Maharashtra deploy biomass co-firing systems to meet Central Pollution Control Board particulate limits. Tamil Nadu's chemical processing belt scales water-tube capacity for continuous steam-intensive operations.
Indonesia
Hydrometallurgical nickel refining facilities in Sulawesi and Halmahera require high-pressure steam for leaching operations that domestic fabrication capacity cannot match. Palm oil processing clusters in Sumatra deploy biomass boilers to monetize empty fruit bunch waste streams. Modularity preferences dominate procurement as construction timelines compress against commodity price volatility.
United Kingdom
Asset-as-a-service contracting displaces capital purchase models among food and beverage processors seeking opex-aligned agreements. NHS trusts specify electric boiler redundancy where local air quality regulations prohibit on-site combustion. Midlands manufacturing parks pilot district heating networks with bundled emissions compliance services.
Steam Boiler Market Vendor Landscape
Legacy boiler OEMs and integrated energy conglomerates split the market across utility-scale and distributed process heat applications. The vendor base concentrates around three strategic archetypes: supercritical technology specialists, digital control integrators, and modular packaged system fabricators. Capacity expansion in Southeast Asian fabrication hubs and technology licensing for biomass co-firing systems represent dominant competitive moves.
Within the legacy technology tier, Babcock & Wilcox Enterprises and Mitsubishi Heavy Industries occupy positions shaped by supercritical boiler heritage and integrated energy system architectures respectively. Siemens exemplifies the digital control archetype through combustion optimization platforms. Thermax represents the modular fabrication vector with packaged boiler configurations suited to India's PLI-driven replacement cycles.
| Leading Market Players |
|---|
| Babcock & Wilcox Enterprises |
| Mitsubishi Heavy Industries |
| General Electric |
| Siemens |
| Alfa Laval |
| Thermax |
| Fulton Boiler Works |
| Cleaver-Brooks |
| Larsen & Toubro |
| Others |
Supply Flow & Price Mechanics
Chinese steel mill clusters in Hebei and Jiangsu provinces anchor global pressure vessel fabrication capacity, transmitting alloy price volatility directly to boiler OEM cost structures and compressing margin buffers for European and Indian fabricators competing on project bids. This geographic concentration of metallurgical supply creates asymmetric pricing power that favors integrated producers with captive steel sourcing over independent boiler fabricators exposed to spot market swings.
Pricing Analysis
Regional price spreads between Asian fabrication hubs and European assembly plants exceed 15% for equivalent water-tube specifications, reflecting labor cost differentials and steel input proximity. Three-tier pricing structure across ASME-stamped premium, ISO-certified standard, and non-certified economy levels separates utility-scale projects from packaged industrial units. Cost compression in the economy tier intensifies as Chinese OEMs absorb margin erosion to secure Indonesian nickel corridor contracts. Price sensitivity concentrates among Southeast Asian hydrometallurgical developers where commodity price volatility compresses capital deployment timelines.
Supply Chain Analysis
Supplier financing facilities with 180-day extended terms have become standard for Southeast Asian EPC contractors procuring superheater tube assemblies from South Korean and Japanese specialty steel mills. Raw material dependencies center on chromium-molybdenum alloy grades from South Korea, nickel-bearing stainless from Indonesia, and pressure vessel carbon steel from China. Single-source vulnerability in ASME-certified forging capacity creates project delay risk when inspection backlogs extend lead times. Distribution runs through OEM-direct channels for utility-scale installations and regional distributor networks for packaged fire-tube units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket service revenue streams including predictive maintenance subscriptions and emissions compliance monitoring are expanding faster than hardware shipments as asset-as-a-service contracting displaces capital purchase models across European food processing and UK healthcare installations.
For Market Incumbents: Insulate premium positioning in supercritical utility segments by deepening backward integration into specialty alloy supply and accelerating digital twin deployment for combustion optimization. Electrification substitution from industrial heat pumps threatens saturated steam demand below 150°C, making ASME Section I certification maintenance and carbon capture retrofit readiness essential defensive investments. For New Entrants and Emerging Players: Establish a beachhead in Indonesia's nickel processing corridor where domestic fabrication capacity lags hydrometallurgical steam demand and modular deployment preferences favor agile project execution. Biomass co-firing technology licensing for palm oil waste streams in Malaysia offers a second penetrable entry point with lower capital intensity than utility-scale water-tube competition. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with stranded boiler divisions lacking digital service capabilities or carbon capture integration expertise. Long-term viability hinges on aftermarket revenue attachment rates and regulatory compliance service bundling rather than pure hardware shipment volumes. Watch for inflection when carbon border adjustment mechanisms trigger accelerated coal-to-gas conversion project announcements in German and Dutch industrial clusters.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Alloy Supply | Captive sourcing of chromium-molybdenum grades from South Korean mills insulates margin compression from Chinese steel volatility. |
| Carbon Capture Retrofit Bundling | Netherlands and UK industrial clusters pilot steam-plus-capture offerings that amortize compliance costs across multiple offtakers. |
| Digital Twin Platform Deployment | Real-time combustion optimization layered with predictive algorithms reduces unplanned outages for German automotive suppliers. |
| Biomass Co-firing Technology Licensing | Agricultural residue combustion systems enable carbon-neutral positioning for palm oil processors in Malaysia and Indonesia. |
| Asset-as-a-Service Contract Expansion | Opex-aligned agreements bundling fuel management and emissions compliance concentrate procurement authority with energy service companies. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with plant engineers at chemical processing facilities, procurement leads at Southeast Asian nickel refiners, aftermarket service heads at European boiler OEMs, and EPC contractors specializing in industrial steam systems. Secondary validation drew from EPA enforcement databases, EU Ecodesign directive implementation reports, Indian Central Electricity Authority efficiency mandate filings, and customs trade data on pressure vessel steel imports. Bottom-up unit shipment estimates triangulated against top-down energy consumption projections across manufacturing and power generation end uses.
Calibration against historical replacement cycle data and regulatory compliance deadline clustering shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include boiler configuration type, fuel source, installation scale, and end-user industry vertical with specific weighting for regulatory-driven replacement intensity in EU member states and India. CAGRs were derived from installed base turnover rates and efficiency mandate compliance timelines rather than extrapolated shipment trends. Forecast inputs incorporated steel alloy price cycle assumptions and ASME certification backlog duration estimates.
Stress conditions across Chinese steel export restrictions, EU carbon border adjustment implementation pace, and Indonesian nickel project development velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement consistency and technology substitution thresholds. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Boilers
Gas Condensing Boiler Market
Boilers
Waste Heat Boiler Market
Boilers
Superheater Market
Boilers
Global Marine Boilers Market
Boilers
US Combined Heat and Power (CHP) Market
Boilers
Oil-Fired Boiler Market
Boilers
Advanced Utility Boilers Market
Boilers
Field Erected Boiler Market
Boilers
District Heating Market
Boilers
Coal-Saving Combustion-Supporting Agent Market
Boilers
Power Boiler Market
Boilers
Boiler System Market
Boilers
Brazil Combined Heat and Power Market
Boilers
Netherlands Combined Heat and Power Market
Boilers
Germany Combined Heat and Power Market
Boilers
US Boiler Market