
 Gas Condensing Boiler Market | 2026-2036
Gas Condensing Boiler Market Size, Share, and Industry Trends Forecast 2026-2036
Gas Condensing Boiler Market Analysis
Stainless steel and aluminum-silicon heat exchangers are broadening the durability calculus for gas condensing boiler manufacturers against traditional cast-iron designs. Viessmann Climate Solutions SE leverages in-house heat exchanger production to sustain margin control across European supply chains. Robert Bosch GmbH anchors its position through smart thermostat integration and connected-home ecosystems. Daikin Industries Ltd. competes by extending its HVAC portfolio into hybrid heat pump-condensing boiler systems.
A gas condensing boiler recovers latent heat from water vapor in exhaust gases through a secondary heat exchanger, achieving thermal efficiencies above 90% AFUE by condensing flue gases below their dew point. The technology serves residential and commercial heating applications where space constraints, fuel availability, or retrofit compatibility limit heat pump deployment. Wall-mounted units lead volume in multi-family residential retrofits where footprint minimization commands premium positioning. Smart Technology integration represents the fastest-expanding technology segment as modulating burners pair with IoT-enabled diagnostics to reduce service costs. Natural gas dominates fuel type demand where grid infrastructure exists, though biogas compatibility is gaining specification in district heating schemes.
EMA efficiency benchmarks under the EU Ecodesign Directive mandate minimum seasonal space heating efficiencies that effectively bar non-condensing designs from European markets. CE marking and the F-Gas Regulation shape product certification requirements and refrigerant handling protocols for hybrid systems. The EU Green Deal's building renovation targets will tighten enforcement timelines across member states. Stakeholders must monitor hydrogen-readiness certifications and burner adaptability standards as gas grid blending mandates advance.
Market Dynamics
The EU Ecodesign Directive's tightening efficiency thresholds are systematically eliminating non-condensing boiler inventory across European distribution channels, forcing wholesale product portfolio restructuring by manufacturers and installers alike.
Growth Catalysts
- Residential Retrofit Mandates:Germany's building renovation programs specify high-efficiency gas condensing units for subsidy eligibility, accelerating replacement cycles in aging multi-family housing stock.
- F-Gas Regulation Phase-Out:The EU's refrigerant restrictions on hybrid heat pump systems create specification windows for gas condensing boilers in transitional heating architectures.
- Stainless Steel Heat Exchangers:Extended service life metrics from corrosion-resistant alloys justify premium positioning in coastal and high-humidity installation environments.
Market Restraints
- Copper and Aluminum Price Volatility:Heat exchanger material costs fluctuate with commodity markets, compressing manufacturing margins during input inflation cycles.
- Heat Pump Substitution:Air-source and ground-source electric systems capture new-build specifications where electrical infrastructure permits, constraining greenfield gas condensing penetration.
- Hydrogen Grid Uncertainty:Incomplete burner adaptability standards for blended hydrogen-natural gas mixtures create specification paralysis among risk-averse commercial developers.
Strategic Opportunities
- Hybrid System Integration:Converging gas condensing boilers with air-to-water heat pumps addresses load-matching inefficiencies in cold-climate residential retrofits.
- Biogas-Ready Burner Certification:District heating schemes in Denmark and Sweden specify renewable gas compatibility, opening premium product tiers for adaptable combustion systems.
- Direct-to-Installer Digital Channels:Bypassing traditional wholesale distribution through B2B e-commerce platforms captures margin and reduces lead times for emergency replacements.
Industry Challenges
- Certified Hydrogen-Ready Technician Shortage:Conversion and maintenance of blended-fuel systems requires specialized training pipelines that regional vocational programs have not yet scaled.
- Legacy Control System Integration:Smart thermostat protocols from established HVAC ecosystems create interoperability friction for independent boiler manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gas Condensing Boiler Market |
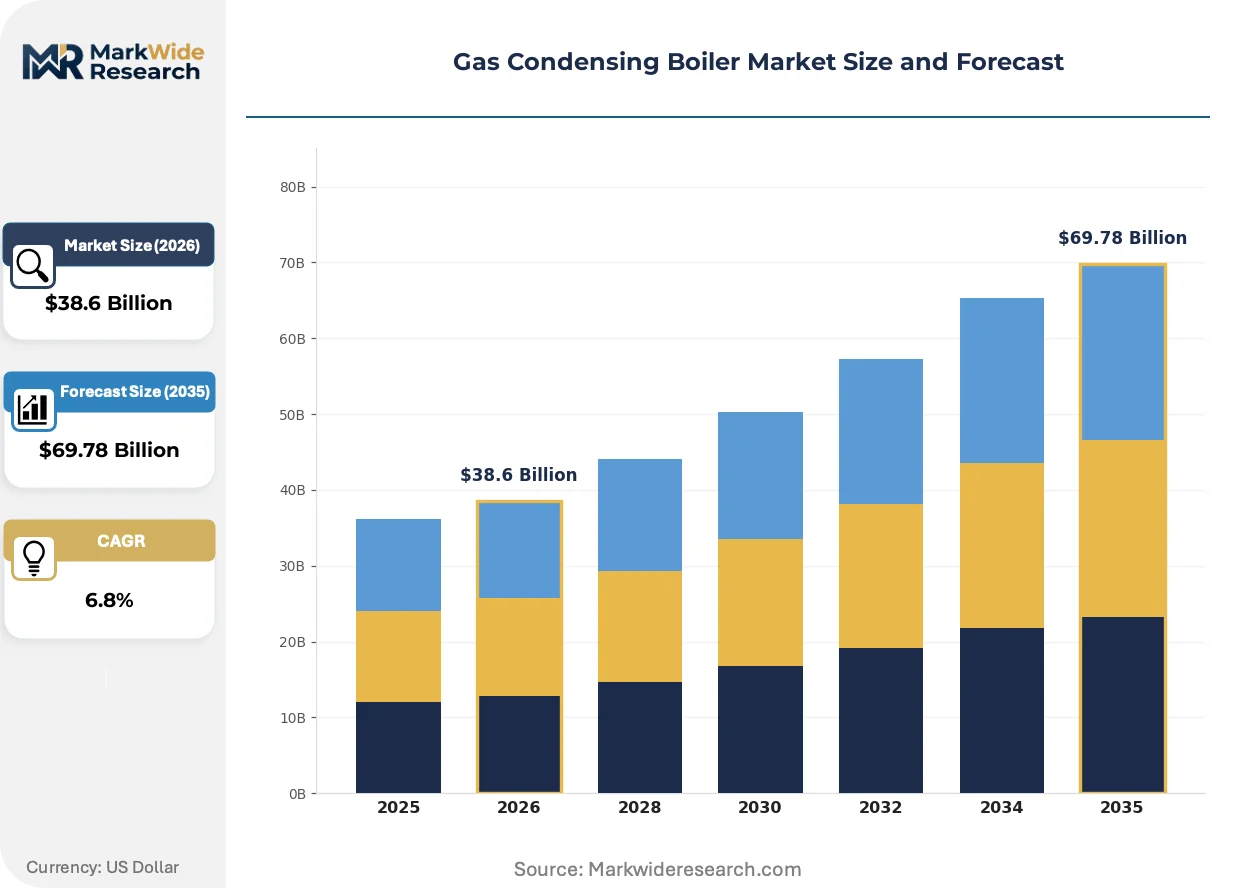
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall-Mounted, Floor-Standing, Combination, System End User: Residential, Commercial, Industrial, Institutional Fuel Type: Natural Gas, Propane, Biogas, Others Technology: Modulating, Controlling System, Smart Technology, Traditional |
| Companies Covered | Daikin Industries Ltd., Navien Inc., Viessmann Climate Solutions SE, BDR Thermea Group, Ariston Holding NV, Robert Bosch GmbH, A. O. Smith Corp., Ferroli Spa, Vaillant Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gas Condensing Boiler Market Emerging Trajectories
Connected diagnostics and adaptive combustion control are redefining service economics across the installed base, shifting value capture from hardware margins to recurring software-enabled maintenance revenues.
Modulating burner technology with real-time flue gas analysis is converging with cloud-based predictive maintenance platforms. Commercial facility managers in the Netherlands and Belgium are specifying these systems for multi-building portfolios. The integration is compressing traditional service contract structures by enabling remote fault detection before on-site dispatch.
The EU Green Deal's building renovation targets are accelerating enforcement timelines for member state implementation of Ecodesign-derived national building codes. Minimum seasonal efficiency thresholds now effectively prohibit non-condensing replacements in major renovation triggers. German and Austrian regulators are tightening compliance verification through mandatory energy performance certificates at point of sale.
Installer purchasing behavior is consolidating around bundled HVAC ecosystem providers rather than standalone boiler procurement. Independent heating contractors in the United Kingdom are migrating toward preferred supplier agreements with integrated controls and ventilation manufacturers. This concentration is most visible in London and Southeast England where multi-trade consolidation has advanced furthest.
Gas Condensing Boiler Market Segmentation
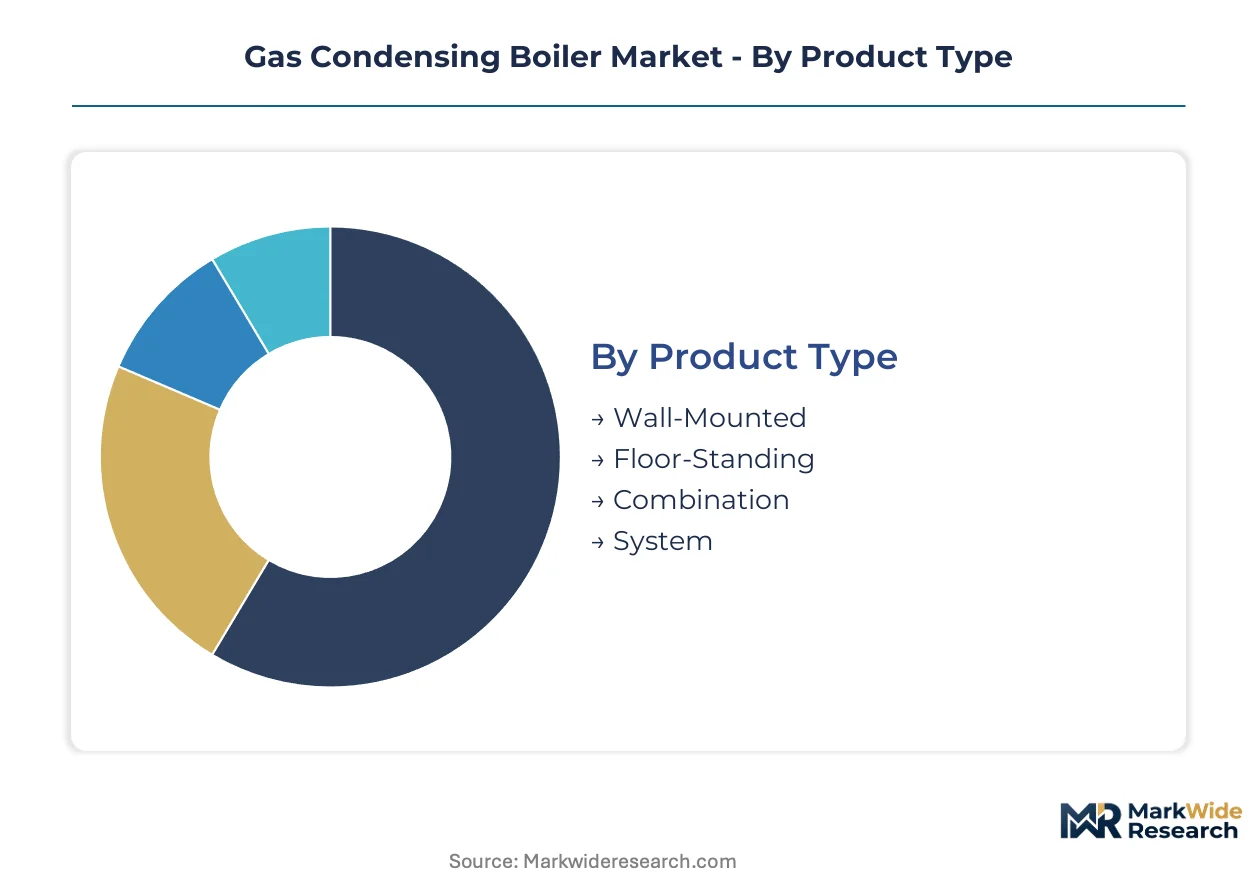
Product architecture in the gas condensing boiler market determines installation economics, service accessibility, and retrofit compatibility across European building stock. Segment boundaries reflect divergent margin structures between mass-market residential replacements and specialized commercial applications.
Product Type:
Supply concentration favors manufacturers with captive heat exchanger production and modular platform architectures that span multiple form factors.
- Wall-Mounted:Compact units with integrated pumps and expansion vessels reduce installation labor in multi-family retrofits. Demand concentrates in German urban centers and Dutch row-house renovations where spatial constraints eliminate floor-standing alternatives. The segment commands premium positioning through stainless steel heat exchanger specifications.
- Floor-Standing:Higher output ranges serve commercial and large residential applications with separate hydraulic components. United Kingdom installations in period properties and rural estates favor these units for compatibility with legacy heating circuits and higher hot-water demand profiles.
- Combination:Integrated domestic hot-water production eliminates cylinder requirements in space-constrained dwellings.
- System:Heat-only designs pair with separate hot-water cylinders for properties with high simultaneous demand.
Today's leader: Wall-Mounted. Tomorrow's challenger: Floor-Standing.
End User:
Application-driven procurement patterns separate price-sensitive residential replacements from performance-guaranteed commercial contracts with extended service obligations.
- Residential:Single-family and multi-family dwellings drive volume through subsidy-triggered replacement cycles. German KfW renovation programs and Dutch ISDE incentives concentrate demand in owner-occupied and housing association properties respectively.
- Commercial:Office buildings, retail, and hospitality specify higher-output units with remote monitoring capabilities. Belgian facility managers in Flanders prioritize modulating systems for portfolio-wide energy accounting.
- Industrial:Process heating and warehouse applications require robust construction and extended warranty terms.
- Institutional:Schools, hospitals, and government buildings mandate compliance with public procurement efficiency standards.
Residential dominates current volumes; commercial applications are climbing the fastest as service-contract economics improve.
Fuel Type:
Grid infrastructure availability and carbon intensity regulations determine fuel specification windows across national markets.
- Natural Gas:Mains-connected properties in Germany, the Netherlands, and the United Kingdom specify these units exclusively. Grid density in North Rhine-Westphalia and Randstad conurbations sustains concentrated demand clusters.
- Propane:Rural properties beyond mains reach in France and Spain require storage tank compatibility and adapted burner configurations.
- Biogas:District heating schemes in Denmark and agricultural biogas networks in Bavaria specify renewable gas-ready burners.
- Others:Hydrogen-blend trials and synthetic methane pilots occupy niche specification status pending standardization.
Natural gas anchors current deployment; biogas compatibility is gaining share fastest amid district heating decarbonization mandates.
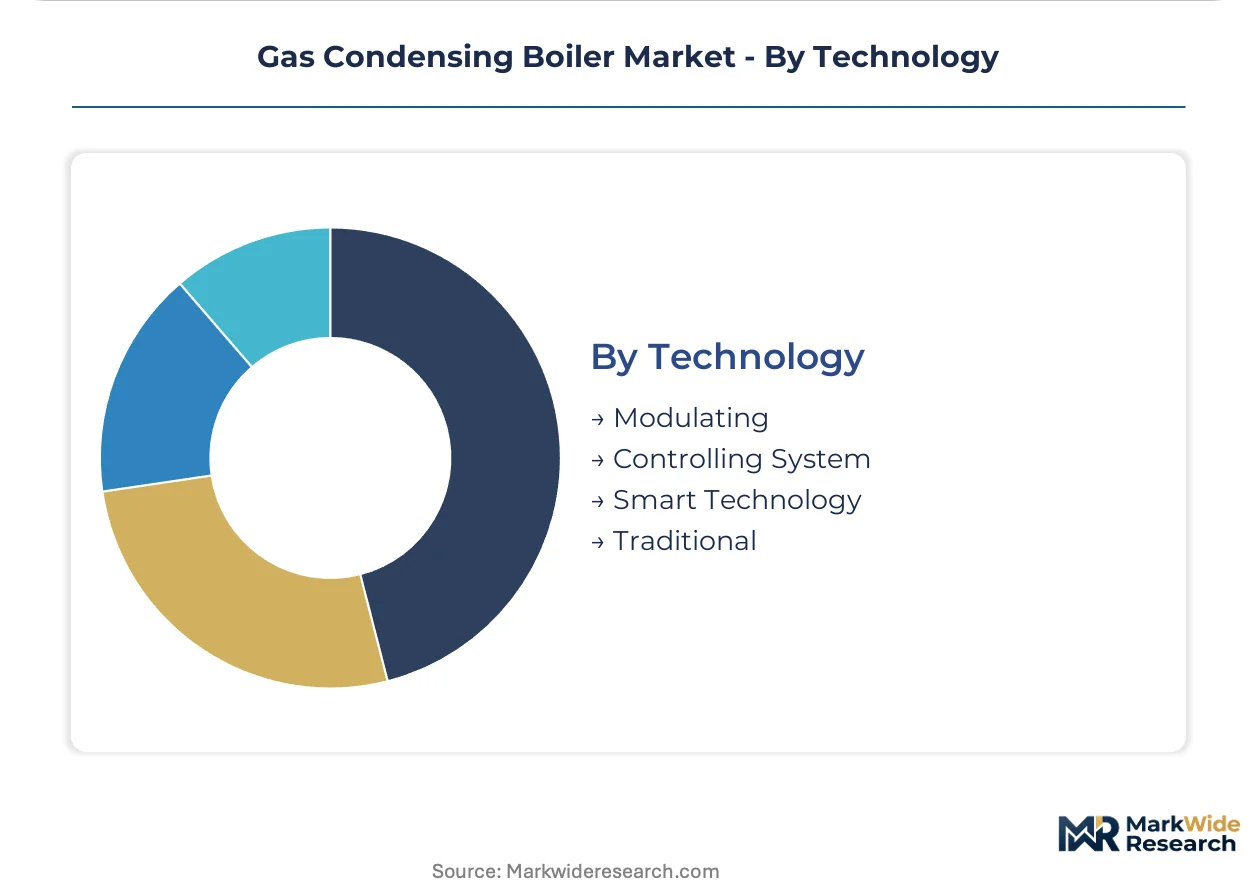
Technology:
Margin differentiation increasingly depends on software-enabled service revenue rather than hardware specification alone.
- Smart Technology:IoT-connected diagnostics, predictive maintenance algorithms, and remote modulation optimize service dispatch economics. Dutch housing corporations in Amsterdam and Rotterdam specify these systems for portfolio-scale energy management.
- Modulating:Variable-output burners match heat delivery to demand profiles, reducing cycling losses in well-insulated building stock.
- Controlling System:Integrated thermostat and zone-control compatibility simplifies specification for installer ecosystem providers.
- Traditional:Basic on/off control occupies economy tier positioning in price-sensitive replacement markets.
Smart Technology leads premium positioning; modulating systems are expanding most quickly as efficiency thresholds tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr metropolitan region anchors European gas condensing boiler deployment through dense building stock renovation and mature natural gas infrastructure. National policy frameworks and subsidy architectures determine replacement velocity across mature heating markets. Installer network density and certification requirements shape competitive access in each territory.
Germany
KfW renovation programs mandate high-efficiency condensing units for subsidy eligibility, accelerating multi-family housing retrofits in Berlin and Hamburg. The Federal Emission Control Ordinance enforces minimum seasonal efficiency thresholds that exclude non-condensing replacements. Manufacturing concentration in North Rhine-Westphalia supports rapid installer response times across the Ruhr industrial corridor.
United Kingdom
Building regulations Part L revisions prohibit non-condensing installations in new-build and major renovation triggers. The Boiler Upgrade Scheme redirects some demand toward heat pumps, though gas condensing units retain dominance in legacy housing stock. Installer purchasing consolidates around integrated HVAC ecosystem providers in London and Southeast England.
Netherlands
ISDE subsidies concentrate demand in housing association portfolios across Amsterdam and Rotterdam. The national natural gas phase-out timeline creates transitional specification windows for hydrogen-ready condensing units. Dutch housing corporations specify smart-connected systems for portfolio-scale energy management.
France
MaPrimeRénov' renovation incentives specify condensing efficiency tiers for grant eligibility. The country's national energy regulator enforces building code compliance verification through mandatory energy performance certificates. Rural properties beyond mains reach in Auvergne and Provence sustain propane-compatible burner demand.
Belgium
Flemish facility managers prioritize modulating systems for multi-building portfolio energy accounting. Regional building codes derived from EU Ecodesign Directive implementation tighten replacement efficiency minimums. Brussels and Antwerp commercial districts specify remote monitoring capabilities for service contract optimization.
Gas Condensing Boiler Market Vendor Landscape
Global majors compete with regional champions across heat exchanger technology and installer channel access. The vendor base separates into captive heat exchanger producers, integrated HVAC ecosystem providers, and standalone boiler specialists. Three archetypes dominate: vertically integrated manufacturers controlling core component supply, diversified industrial conglomerates leveraging smart home platforms, and pure-play heating specialists focused on combustion engineering. Competitive positioning depends on backward integration into heat exchanger production and forward integration into connected diagnostics platforms.
Among German-based industrial groups, Viessmann Climate Solutions SE and Robert Bosch GmbH exemplify divergent strategic paths. Viessmann anchors premium positioning through in-house heat exchanger manufacturing. Bosch occupies ecosystem-provider status through smart thermostat integration. Daikin Industries Ltd. represents the diversified HVAC conglomerate archetype extending climate control portfolios into hybrid system configurations. Each occupies distinct competitive terrain based on supply chain control depth and service revenue capture models.
| Leading Market Players |
|---|
| Daikin Industries Ltd. |
| Navien Inc. |
| Viessmann Climate Solutions SE |
| BDR Thermea Group |
| Ariston Holding NV |
| Robert Bosch GmbH |
| A. O. Smith Corp. |
| Ferroli Spa |
| Vaillant Group |
| Others |
Supply Flow & Price Mechanics
The EU Ecodesign Directive's minimum seasonal efficiency thresholds gate qualified supply and premium-tier pricing access, compressing margins for manufacturers lacking certified heat exchanger production while rewarding stainless steel specification with sustained premium positioning across German and Dutch distribution channels.
Pricing Analysis
Input-cost pass-through from copper and aluminum-silicon alloy volatility shapes manufacturer margin structures, with commodity inflation cycles compressing returns on economy-tier cast-iron heat exchanger models. Price differentiation hinges on corrosion-resistance certification grade and bundled smart diagnostics service contracts, with residential retrofit contractors in the United Kingdom exhibiting highest sensitivity to upfront unit costs while Dutch housing corporations absorb premiums for portfolio-scale energy management integration. Pricing pressure stems from heat pump substitution in new-build segments, eroding greenfield specification opportunities and forcing defensive discounting on basic modulating systems.
Supply Chain Analysis
Reverse-logistics flows for warranty heat exchanger returns and refurbishment programs concentrate service parts inventory in Germany and the Netherlands, with end-of-life unit recovery schemes mandated by WEEE Directive compliance creating secondary material streams for aluminum-silicon reclamation. Manufacturing draws from stainless steel coil supply in Germany, aluminum foundry capacity in Italy, and electronic control module assembly in Poland. Single-source vulnerability sits with specialized corrosion-resistant alloy suppliers serving coastal specification markets. Distribution runs through installer-anchored wholesale channels in North Rhine-Westphalia and direct-to-contractor digital platforms in Southeast England.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gas condensing boiler market functions as a regulatory compounder, with the EU Green Deal's building renovation targets systematically expanding replacement demand through mandatory efficiency thresholds that eliminate non-condensing alternatives.
For Market Incumbents: Deepen backward integration into heat exchanger production to defend margin structures against commodity volatility, while accelerating hydrogen-ready burner certification to preempt specification paralysis as grid blending mandates advance. Capture installer ecosystem lock-in through smart thermostat protocol integration, neutralizing interoperability friction from independent control platforms.
For New Entrants and Emerging Players: Begin with biogas-ready burner specialization for Danish and Swedish district heating schemes, where renewable gas compatibility commands premium positioning absent from established portfolios. Target propane-compatible rural retrofits in France and Spain, leveraging storage tank integration expertise overlooked by mains-gas-focused incumbents. Pursue direct-to-installer digital channels to bypass wholesale margin capture in emergency replacement markets.
For Investors and Strategic Acquirers: Roll-up economics work for regional heating specialists with captive service networks because installer consolidation in London and Southeast England creates platform value through recurring maintenance contract capture. Five-to-ten year viability hinges on hydrogen adaptation capability rather than pure combustion engineering scale. Monitor hydrogen-readiness certification adoption rates as inflection indicator for stranded asset risk in legacy burner portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid System Integration | Converging gas condensing with air-to-water heat pumps addresses cold-climate load-matching inefficiencies in German retrofits. |
| Hydrogen-Ready Burner Certification | Early compliance with blended-fuel standards secures specification priority as Dutch and German grid mandates advance. |
| Smart Diagnostics Platform Launch | Cloud-based predictive maintenance shifts value capture from hardware margins to recurring software-enabled service revenues. |
| Biogas Compatibility Investment | Renewable gas-ready specifications unlock premium tiers in Danish district heating and Bavarian agricultural networks. |
| Direct-to-Installer Digital Channel | Bypassing wholesale distribution captures margin compression relief and reduces lead times for UK emergency replacements. |
Methodological Framework
Bottom-up residential and commercial installation modeling reconciled against top-down heat exchanger production tracking forms the analytical core, combining primary interviews with heating system installers, facility managers at Dutch housing corporations, German regulatory affairs specialists, and OEM procurement leads with secondary validation from EU Ecodesign Directive implementation reports, KfW subsidy disbursement data, and national energy performance certificate registries.
Historical trendline analysis of replacement cycle velocities and subsidy-triggered demand spikes across the analysis window informed projection frameworks, with segmentation modeling spanning product architecture, end-use application, fuel type specification, and technology tier. CAGRs derive from unit shipment trajectories weighted by efficiency-tier pricing differentials, incorporating hydrogen grid blending timeline assumptions and heat pump substitution elasticity in new-build specifications.
Several conditions sit outside the modeled scope, including unannounced revisions to EU F-Gas Regulation timelines, abrupt natural gas price discontinuities, and accelerated hydrogen grid conversion schedules. Forecasts reflect documented assumptions regarding subsidy program continuity and installer network density maintenance. Practitioners should monitor hydrogen-readiness certification adoption rates and heat pump cost parity trajectories for early signals of demand inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Boilers
US Commercial Boiler Market
Boilers
Superheater Tubes Market
Boilers
Industrial Biomass Boiler Market
Boilers
Global Package Boilers Market
Boilers
Industrial and Residential Heating Market
Boilers
GCC Electric Water Heater Market
Boilers
Water Tube Industrial Boiler Market
Boilers
Boiler Control Solutions Market
Boilers
Germany Combined Heat and Power Market
Boilers
Coal-Saving Combustion-Supporting Agent Market
Boilers
Netherlands Combined Heat and Power Market
Boilers
Industrial Boiler MRO Market
Boilers
Europe Power Plant Boiler Market
Boilers
Global Boiler Market
Boilers
Marine Boiler Burner Market
Boilers
Circulating Fluidized Bed Boilers Market