
 Global Biomass Market | 2026-2036
Global Biomass Market Size, Share, and Industry Trends Forecast 2026-2036
Global Biomass Market Analysis
Market Context
The capital-intensity divergence between integrated pellet producers and merchant traders is collapsing as feedstock security becomes the decisive cost variable. Enviva leverages long-term offtake contracts with European utilities to sustain volume certainty through commodity cycles. Drax Biomass anchors its position through proprietary port infrastructure and dedicated export capacity on the US Gulf Coast. Graanul Invest Group differentiates via Baltic Sea logistics dominance and proximity to Scandinavian district heating demand.
Technical Definition and Segment Structure
Biomass denotes organic material derived from plants, agricultural residues, and purpose-grown energy crops, typically processed to achieve moisture content below 10% and energy density exceeding 17 GJ per tonne for combustion applications. Its primary commercial purpose is substituting fossil coal in baseload thermal power and industrial process heat without requiring full grid infrastructure replacement. Wood pellets currently command the largest revenue pool across product categories, while biogas from anaerobic digestion represents the fastest-expanding segment due to waste-to-energy policy mandates in multiple jurisdictions. The utilities end-user segment absorbs the dominant share of industrial-scale volume, though residential heating in Northern Europe sustains premium pricing for certified ENplus pellets.
Regulatory Framework and Outlook
The EU Green Deal and its accompanying Renewable Energy Directive, alongside the EPA's renewable fuel standards in the United States, collectively shape feedstock eligibility criteria and sustainability certification requirements that determine market access for international suppliers. Japan's FIT scheme and South Korea's RPS quota system further redirect seaborne trade flows toward Asia-Pacific buyers with stringent origin-tracking protocols. Stakeholders must monitor evolving lifecycle carbon accounting methodologies, as proposed changes to embodied-emission thresholds threaten to disqualify certain long-haul supply chains from qualifying renewable obligations.
Market Dynamics
Feedstock security now dictates competitive survival as long-haul supply chains face carbon-accounting scrutiny under evolving EU Green Deal lifecycle methodologies.
Growth Catalysts
- EU Green Deal tightening:Renewable Energy Directive revisions are hardening embodied-emission thresholds for imported pellets, redirecting procurement toward Baltic and US Southeast supply basins with shorter transport distances.
- Japan's FIT scheme:Power utilities under METI mandates are accelerating long-term offtake contracting for wood pellets to meet renewable portfolio obligations without grid infrastructure replacement.
- Anaerobic digestion scale-up:Waste-to-energy policy mandates across multiple jurisdictions are expanding biogas capacity faster than combustion pellet installations.
Market Restraints
- Forestry residue concentration:Supply chains concentrate in Estonia, Latvia, and the US Southeast, creating geographic vulnerability to weather-driven harvest disruptions.
- Natural gas price volatility:Industrial process heat users retain switching capability to gas when biomass feedstock costs spike, capping pricing power.
- Lifecycle carbon accounting uncertainty:Proposed changes to ISO 14040 methodologies threaten to disqualify transatlantic pellet shipments from renewable obligation schemes.
Strategic Opportunities
- South Korea RPS quota expansion:KEPCO-affiliated generators are tendering for new seaborne supply with stringent Korean-origin tracking protocols that favor integrated producers.
- District heating convergence:Scandinavian municipal networks are blending biomass with heat pumps, creating hybrid procurement contracts for baseload thermal.
- Agricultural residue valorization:Straw and rice husk pelletization is opening feedstock pools outside forest-dependent regions in India and Southeast Asia.
Industry Challenges
- Sustainability certification bottlenecks:ENplus and SBP scheme audits face 12-18 month backlogs, delaying market access for new production capacity.
- Port infrastructure capex intensity:Dedicated export terminals on the US Gulf Coast require capital deployment that merchant traders cannot finance without offtake security.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Biomass Market |
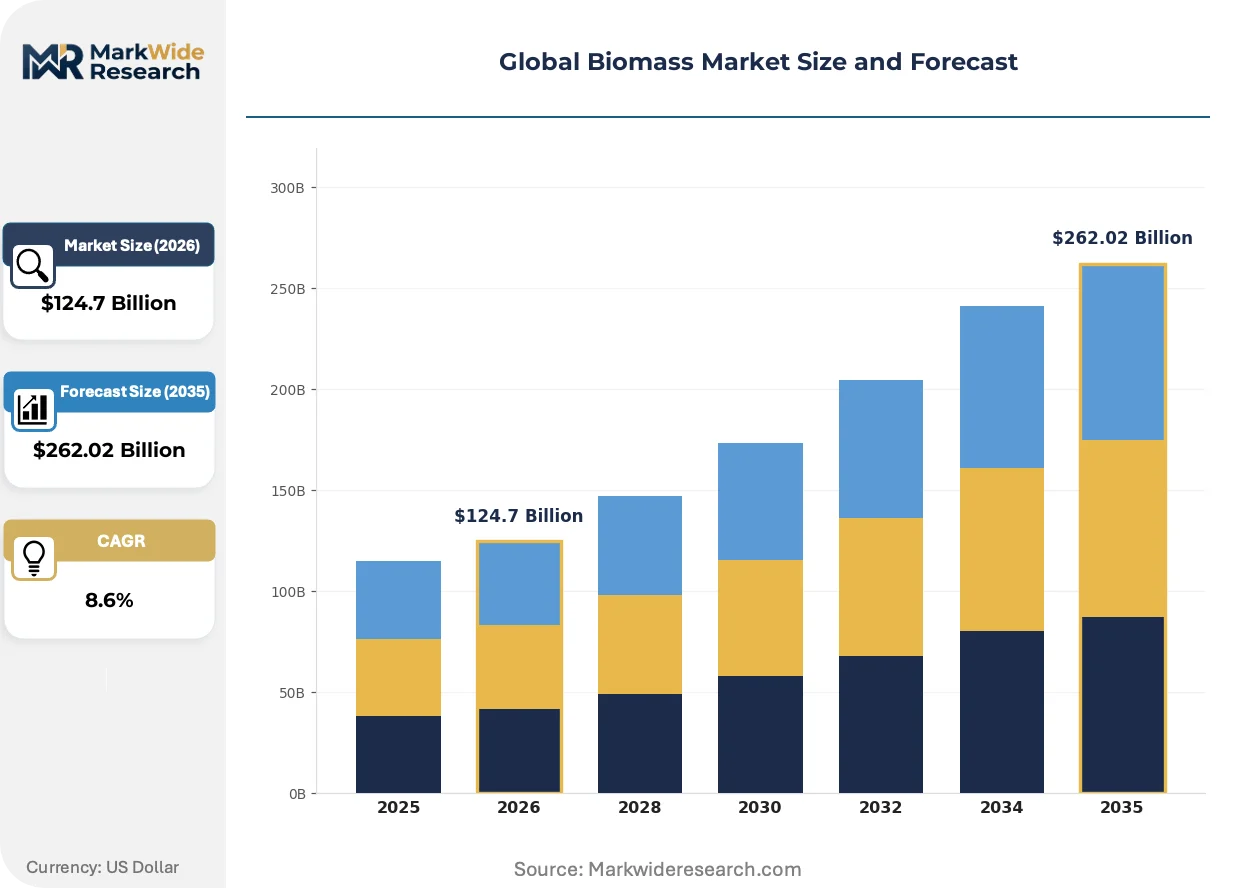
| Market Size in 2026 | $124.7 Billion |
| Market Size in 2035 | $262.02 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wood Pellets, Agricultural Residues, Energy Crops, Biogas Application: Power Generation, Heating, Transportation, Biofuels End User: Residential, Commercial, Industrial, Utilities Technology: Combustion, Gasification, Anaerobic Digestion, Fermentation |
| Companies Covered | Pacific BioEnergy, Lignetics, Enviva, Vyborgskaya Cellulose, Drax Biomass, Pinnacle Renewable Energy Group, RWE Innogy, E-pellets, Graanul Invest Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Biomass Market Emerging Trajectories
Torrefaction and steam explosion preprocessing are altering feedstock economics, while digital traceability systems reshape how origin verification satisfies regulatory compliance.
Torrefaction—thermal treatment at 200-300°C in oxygen-limited conditions—is upgrading agricultural residues to coal-compatible energy density above 20 GJ per tonne. German and Dutch coal-to-biomass conversion plants are piloting torrefied pellets at 10-15% blend ratios. This preprocessing is displacing raw wood pellet demand in industrial cofiring applications where grindability matching matters.
The EU Green Deal's Carbon Border Adjustment Mechanism is extending to embodied emissions in biomass imports, forcing non-EU suppliers to document supply chain carbon intensity through certified mass-balance accounting. Baltic producers with rail-to-port logistics are gaining compliance advantage over US Gulf exporters facing longer ocean legs. Drax and Graanul Invest are restructuring shipping contracts to minimize transshipment carbon leakage.
Utility procurement departments are consolidating supplier panels from 15-20 merchant traders toward 3-5 integrated producers with captive port capacity and sustainability certification. Long-term offtake contracts now dominate volume allocation, squeezing spot-market liquidity. This concentration is most visible in Japanese utility procurement, where JERA and Chubu Electric have reduced approved supplier lists by 60% since 2022.
Global Biomass Market Segmentation
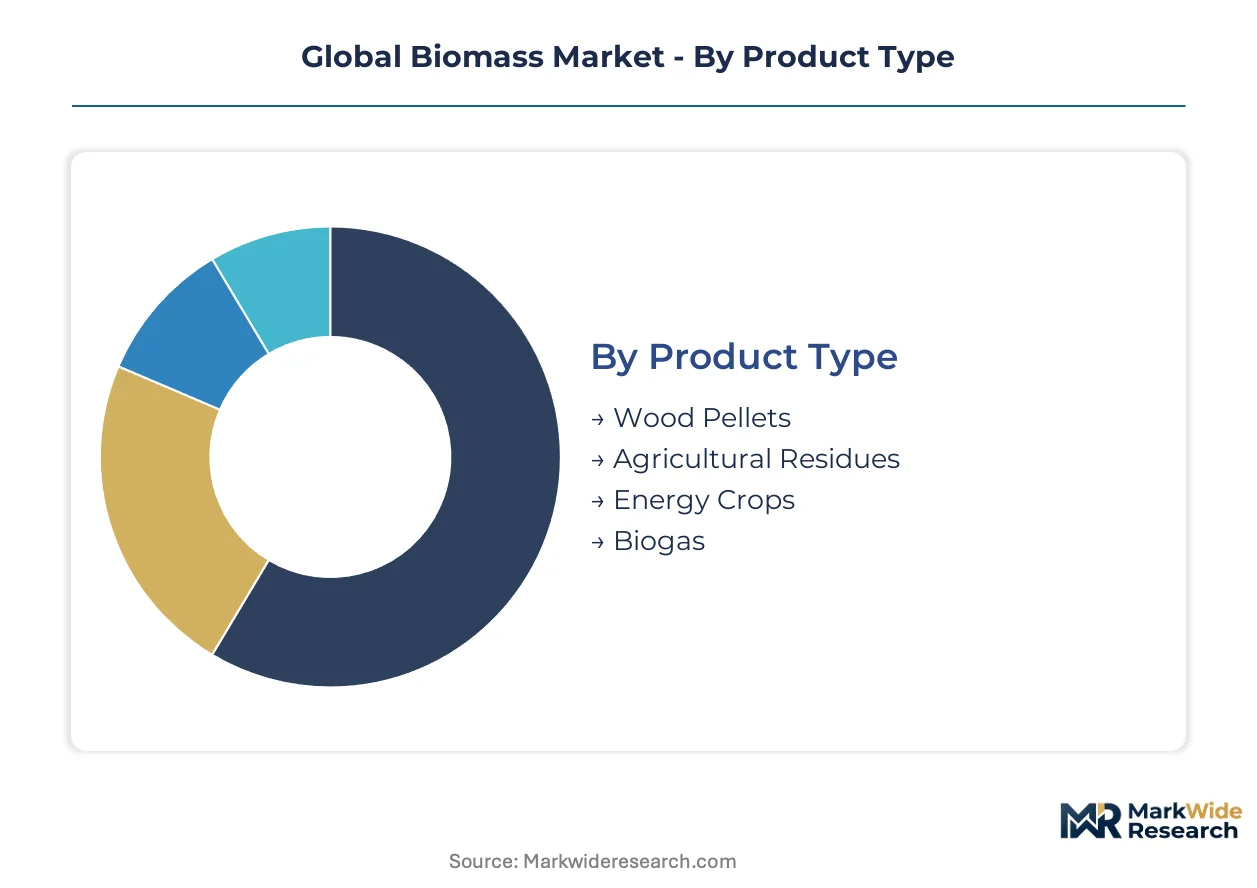
Biomass market segmentation reveals where capital allocation and policy incentives intersect. Feedstock type determines carbon accounting eligibility under EU Green Deal methodologies, while end-user concentration shapes contract structures and pricing power.
Product Type:
Margin pools concentrate in densified solid fuels where transport economics and certification premiums compound.
- Wood Pellets:Densified sawdust and forest residue compressed to 6-8mm diameter with moisture content below 10% and energy density exceeding 17 GJ per tonne. Drax and Graanul Invest capture premium pricing through ENplus certification for residential heating in Germany and Denmark, where district heating networks mandate origin-verified supply.
- Agricultural Residues:Straw, rice husk, and corn stover pelletized or baled for combustion applications. Demand is concentrating in India's Punjab and Haryana states under the country's biomass co-firing mandates for coal plants, though supply chain fragmentation limits pricing power.
- Energy Crops:Purpose-grown miscanthus, switchgrass, and short-rotation coppice cultivated for dedicated fuel supply. Cultivation contracts in the UK and Poland face land-use competition with food production.
- Biogas:Methane-rich output from anaerobic digestion of organic waste, upgraded to biomethane for grid injection or vehicle fuel. Germany's EEG feed-in tariff and France's injection tariffs are expanding capacity faster than solid biomass installations.
The dominant share belongs to wood pellets, while biogas is closing the gap fastest.
Application:
Application segmentation tracks where fossil substitution delivers the highest carbon price arbitrage.
- Power Generation:Cofiring biomass with coal or dedicated biomass plants supplying baseload electricity. Japan's FIT scheme and South Korea's RPS quotas are redirecting seaborne pellet flows toward Asia-Pacific buyers with stringent Korean-origin tracking protocols.
- Heating:District heating networks and residential stoves consuming pellets or wood chips. Scandinavian municipal networks in Sweden and Finland blend biomass with heat pumps, creating hybrid procurement contracts.
- Transportation:Liquid biofuels including biodiesel and bioethanol for road and aviation use. The EU's ReFuelEU Aviation mandate is forcing SAF offtake commitments from carriers at Rotterdam and Amsterdam Schiphol.
- Biofuels:Processed liquid and gaseous fuels for industrial and transport applications. US EPA renewable volume obligations under RFS2 sustain corn ethanol demand despite electrification headwinds.
Power generation commands the largest volume allocation, yet heating applications sustain the steepest margin expansion.
End User:
Customer type determines contract duration and feedstock specification requirements.
- Residential:Individual households purchasing bagged pellets for stove heating. ENplus-A1 certification commands 15-20% price premiums in Northern European retail channels.
- Commercial:Hotels, hospitals, and institutional buildings with medium-scale boiler installations. Germany's BAFA subsidy program accelerates oil-to-biomass conversions in commercial buildings.
- Industrial:Process heat users in food processing, paper, and chemicals sectors. Natural gas price volatility in the Netherlands and Belgium triggers fuel switching that caps biomass pricing power.
- Utilities:Large-scale power generators with long-term offtake contracts and dedicated handling infrastructure. JERA and Chubu Electric in Japan have consolidated supplier panels from 15-20 merchant traders toward 3-5 integrated producers with captive port capacity.
Utilities absorb the dominant volume share, while commercial segment expansion is gaining share fastest.
Technology:
Technology choice locks in feedstock flexibility and emission profiles for decades.
- Combustion:Direct burning of solid biomass in grate, fluidized bed, or pulverized fuel systems. Drax's Selby facility in the UK represents the largest dedicated biomass combustion installation globally.
- Gasification:Partial oxidation to produce syngas for power or chemical synthesis. Pilot plants in the Netherlands and Sweden struggle with tar cracking economics at commercial scale.
- Anaerobic Digestion:Microbial breakdown of organic matter in oxygen-free environments producing biogas. Denmark's centralized farm-based digesters and France's agro-industrial facilities dominate European capacity.
- Fermentation:Biological conversion of sugars to ethanol or other platform chemicals. US corn ethanol mills and Brazilian sugarcane distilleries define global production economics.
Combustion retains the dominant installed base, though anaerobic digestion is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese utilities exhibit the lowest price elasticity, locking in decade-long offtake contracts at fixed spreads, while German industrial heat buyers switch to natural gas within weeks when pellet costs spike. This demand-elasticity divergence reshapes where producers anchor capacity investments.
United States
Power utilities in the Southeast dominate procurement volumes, with Georgia and Alabama hosting the densest clusters of dedicated biomass generation capacity. EPA renewable fuel standards under RFS2 sustain feedstock eligibility for agricultural residue pelletization. The US Gulf Coast corridor from Houston to Mobile anchors export terminal infrastructure that supplies European and Asian buyers.
Germany
District heating networks in Bavaria and North Rhine-Westphalia blend biomass with heat pumps under municipal decarbonization mandates. BAFA subsidy programs accelerate oil-to-biomass conversions in commercial buildings, tightening feedstock specifications. The Port of Hamburg serves as the primary Baltic Sea entry point for ENplus-certified pellet imports from Estonia and Latvia.
Japan
JERA and Chubu Electric have consolidated supplier panels from fifteen merchant traders to five integrated producers since 2022. METI's FIT scheme mandates renewable portfolio obligations without grid infrastructure replacement, locking in long-term contracting. The Port of Nagoya and Yokkaichi terminals handle the majority of seaborne wood pellet intake for Kansai and Chubu regional utilities.
South Korea
KEPCO-affiliated generators tender for seaborne supply with stringent Korean-origin tracking protocols that favor integrated producers over merchant traders. The RPS quota expansion redirects pellet flows from Atlantic to Pacific basin suppliers. Busan-Ulsan industrial corridor hosts the primary biomass cofiring installations serving the Seoul Capital Area grid.
United Kingdom
Drax's Selby facility in Yorkshire represents the largest dedicated biomass combustion installation globally, consuming pellets from US Gulf and Baltic suppliers. The UK's biomass conversion strategy under previous renewable obligation certificates created dedicated import infrastructure at Hull and Immingham. Scottish district heating networks in Aberdeen and Edinburgh sustain premium demand for certified wood chips.
Global Biomass Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated producers commanding feedstock security while merchant traders compete on spot-market logistics. The market structure concentrates around five vertically integrated entities with captive port capacity, squeezing thirty-plus regional pellet mills into commodity pricing. Two strategic archetypes dominate: Baltic Sea logistics specialists with rail-to-port control, and US Gulf exporters with long-term utility offtake structures. Competitive moves center on sustainability certification pre-positioning and transshipment carbon leakage minimization.
Among North American integrated producers, Enviva and Drax Biomass exemplify the long-term offtake archetype, anchoring positions through dedicated export terminal control. Graanul Invest occupies a parallel position in the Baltic tier, leveraging proximity to Scandinavian district heating demand. These three entities represent the consolidation trajectory as utility procurement panels shrink from fragmented merchant networks toward captive-supply relationships.
| Leading Market Players |
|---|
| Pacific BioEnergy |
| Lignetics |
| Enviva |
| Vyborgskaya Cellulose |
| Drax Biomass |
| Pinnacle Renewable Energy Group |
| RWE Innogy |
| E-pellets |
| Graanul Invest Group |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at dedicated export terminals on the US Gulf Coast and Baltic Sea rail-to-port complexes shapes both supply concentration and price floors for industrial-scale procurement. Long-term offtake contracts with European and Japanese utilities lock in volume certainty that merchant traders cannot match, compressing spot-market liquidity and anchoring premium pricing to captive infrastructure control.
Pricing Analysis
After-sales revenue from sustainability certification audits and mass-balance documentation services drives lifetime value beyond the physical pellet transaction. Three-tier pricing structure across ENplus-A1 premium, industrial utility standard, and spot-market economy levels separates residential heating premiums from baseload power procurement. Cost compression in the standard tier is intensifying because Baltic producers with shorter transport distances gain compliance advantage under EU Green Deal carbon-accounting methodologies. German district heating networks exhibit the lowest price elasticity, while US Southeast industrial heat buyers retain fuel-switching capability to natural gas.
Supply Chain Analysis
Baltic Sea port congestion at Riga and Tallinn underwrites supply security premiums for Scandinavian district heating buyers. Feedstock supply concentrates in Estonia, Latvia, and the US Southeast, with forestry residue availability drawing from sawmill byproduct streams and low-grade timber harvests. The production base rests on specialized pellet mill equipment and ENplus certification infrastructure that creates single-source vulnerability during audit backlogs. Distribution runs through dedicated export terminals with captive storage and vessel loading capacity, bypassing fragmented merchant trader networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certification-as-a-service revenue layers are expanding faster than raw pellet production as utilities demand documented carbon intensity and origin verification for compliance. Recurring audit contracts and digital traceability subscriptions create annuity streams that hardware margins cannot match.
For Market Incumbents: Fortify feedstock security through backward integration into forestry residue collection networks in the US Southeast and Baltic states, countering merchant trader encroachment on spot volumes. Invest in torrefaction preprocessing capabilities to capture industrial cofiring demand as coal-compatible energy density becomes a procurement specification. Prioritize ENplus and SBP certification pre-positioning to exploit 12-18 month audit backlogs that delay competitor market access. For New Entrants and Emerging Players: Anchor in agricultural residue pelletization for India's Punjab and Haryana state cofiring mandates, where supply chain fragmentation limits incumbent pricing power. Target straw and rice husk feedstock pools outside forest-dependent regions to bypass Baltic and US Southeast supply concentration. Pursue district heating hybrid procurement contracts in Scandinavian municipal networks blending biomass with heat pump baseload. For Investors and Strategic Acquirers: Integrated producers with captive port infrastructure and long-term utility offtake structures represent the most defensible acquisition archetype as procurement panels consolidate. Long-term viability hinges on feedstock security and certification compliance rather than commodity trading margins. Monitor proposed ISO 14040 lifecycle methodology revisions as the critical inflection signal for transatlantic supply chain disqualification risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Forestry Residue Collection | Captive feedstock security neutralizes merchant trader price volatility in Baltic and US Southeast supply basins. |
| Torrefaction Preprocessing Capacity Buildout | Coal-compatible grindability opens industrial cofiring demand from German and Dutch conversion plants. |
| ENplus Certification Fast-Track Investment | Audit backlog exploitation delays competitor access to German and Danish residential heating premiums. |
| Digital Traceability Platform Deployment | Mass-balance documentation satisfies EU Green Deal Carbon Border Adjustment Mechanism compliance requirements. |
| Long-Term Utility Offtake Restructuring | Fixed-spread contracts with JERA and Chubu Electric lock in volume certainty through commodity cycles. |
Methodological Framework
A standing panel of utility procurement officers, pellet mill operations managers, sustainability certification auditors, and port terminal logistics coordinators provided ongoing calibration across the primary research phase. Secondary validation drew from EPA renewable fuel standard filings, EU Renewable Energy Directive implementation documents, METI FIT scheme procurement disclosures, and customs trade data tracking seaborne pellet flows. Bottom-up capacity modeling triangulated against top-down utility demand aggregation to reconcile supply-demand balances.
Consistency checks against IEA bioenergy statistics and FERC generator fuel disclosures validated volume and value outputs across the projection horizon. Segmentation modeling tracked feedstock type, application, end-user category, and technology choice dimensions. CAGRs were derived from regression analysis of historical procurement volumes against policy mandate trajectories, with carbon price arbitrage and fuel-switching elasticity as biomass-specific forecast inputs.
Decision-makers should treat outputs as directional under sustained EU Green Deal enforcement and Japanese FIT scheme continuity; material deviation in lifecycle carbon accounting methodologies would warrant model refresh. Practitioners should keep alternative scenarios live as ISO 14040 embodied-emission threshold proposals and South Korean RPS quota expansions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomass Energy Systems
Energy Harvesting Trees Market
Biomass Energy Systems
Global Wood Fuel Pellets Market
Biomass Energy Systems
Europe Biomass Gasification Market
Biomass Energy Systems
Biomass Gasification Market
Biomass Energy Systems
Global Biomass Power Market
Biomass Energy Systems
North America Biomass Gasification Market
Biomass Energy Systems
Europe Wood Pellet Heating Systems Market
Biomass Energy Systems
Solar Bio-Gas Hybrid Power System Market
Biomass Energy Systems
Biomass Pellets Market
Biomass Energy Systems
Gasification Market
Biomass Energy Systems
Biomass Power Generation Market
Biomass Energy Systems
Modular Biomass Power Plant Market
Biomass Energy Systems
Gasifier Market