
 GCC Portable Air Conditioners Market | 2026-2036
GCC Portable Air Conditioners Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Portable Air Conditioners Market Insights
Asset-light leasing and rental financing is fragmenting the competitive landscape for portable cooling equipment across the Gulf. Carrier Global Corporation leverages its service-contract bundling to anchor long-term commercial relationships. Gree Electric Appliances competes through manufacturing scale that sustains aggressive pricing in the single-hose segment. Daikin Industries, Ltd. differentiates via inverter technology leadership that commands premium positioning among UAE commercial buyers.
Portable air conditioners are self-contained cooling systems with capacities typically spanning 8,000 to 14,000 BTU per hour, designed for spaces lacking permanent HVAC infrastructure or requiring supplemental temperature control. These units employ vapor-compression refrigeration cycles with condensate management systems suited to high-ambient desert conditions prevalent across Gulf Cooperation Council states. Single-hose configurations dominate residential demand due to lower acquisition cost and simpler installation, while double-hose designs capture faster growth in commercial temporary cooling where thermal efficiency offsets higher upfront outlay. Smart controls and mobile app connectivity represent an emerging margin pool as property managers in Saudi Arabia and Qatar seek remote monitoring capabilities for distributed equipment fleets.
Saudi Standards, Metrology and Quality Organization and Emirates Authority for Standardization and Metrology enforce escalating minimum energy performance standards that filter lower-efficiency imports from non-compliant manufacturers. The UAE's MOHAP building safety codes and Saudi CEDA efficiency directives together reshape product certification requirements, compelling redesigns of compressor systems and refrigerant selections. Stakeholders must monitor how Gulf regulatory harmonization around cooling-season performance metrics will redistribute competitive advantage between established HVAC conglomerates and emerging regional assemblers.
Market Dynamics
Saudi Arabia's tightening energy-labeling mandates from the Saudi Standards, Metrology and Quality Organization are forcing compressor redesigns and refrigerant transitions across the GCC portable cooling supply base, compressing margins for non-compliant assemblers while rewarding inverter-ready manufacturers.
Growth Catalysts
- Exhibition Infrastructure Buildout:Dubai's hospitality and events sector is expanding temporary cooling capacity for international expos and corporate gatherings, driving fleet orders for double-hose commercial units.
- SASO Efficiency Thresholds:The Saudi Standards, Metrology and Quality Organization's escalating minimum energy performance standards are filtering out low-efficiency imports, creating shelf space for premium inverter-equipped models.
- Smart Fleet Management:Property managers in Qatar are deploying mobile-connected portable units with remote monitoring capabilities to manage distributed residential cooling assets across multiple compounds.
Market Restraints
- Copper-Aluminum Price Volatility:Heat exchanger materials face input cost swings that compress manufacturing margins and destabilize pricing for single-hose residential units.
- Refrigerant Supply Concentration:Gulf states depend on concentrated Asian feedstock suppliers for R-32 and R-410A alternatives, exposing assemblers to quota restrictions and shipping bottlenecks.
- Thermal Efficiency Ceiling:Single-hose configurations face fundamental thermodynamic limits in 50°C ambient conditions, restricting deployment duration in Saudi interior construction sites.
Strategic Opportunities
- Qatar's Post-Event Asset Repositioning:Stadium and hospitality portable cooling fleets from the 2022 World Cup are entering secondary commercial rental markets, creating a liquid used-equipment channel.
- Rooftop Solar Pairing:Photovoltaic-integrated portable units are emerging for off-grid construction camps in Oman and remote Saudi industrial zones, cutting diesel generator dependency.
- MOHAP Building Code Alignment:The UAE's Ministry of Health and Prevention safety directives are mandating temporary cooling redundancy for healthcare facility expansion, opening institutional procurement pathways.
Industry Challenges
- Inverter Technician Scarcity:Variable-speed compressor servicing requires specialized training that Gulf vocational programs have not scaled to match deployment volume.
- Dual Certification Timelines:Manufacturers seeking simultaneous SASO and ESMA approval face sequential testing protocols that delay product launches by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Portable Air Conditioners Market |
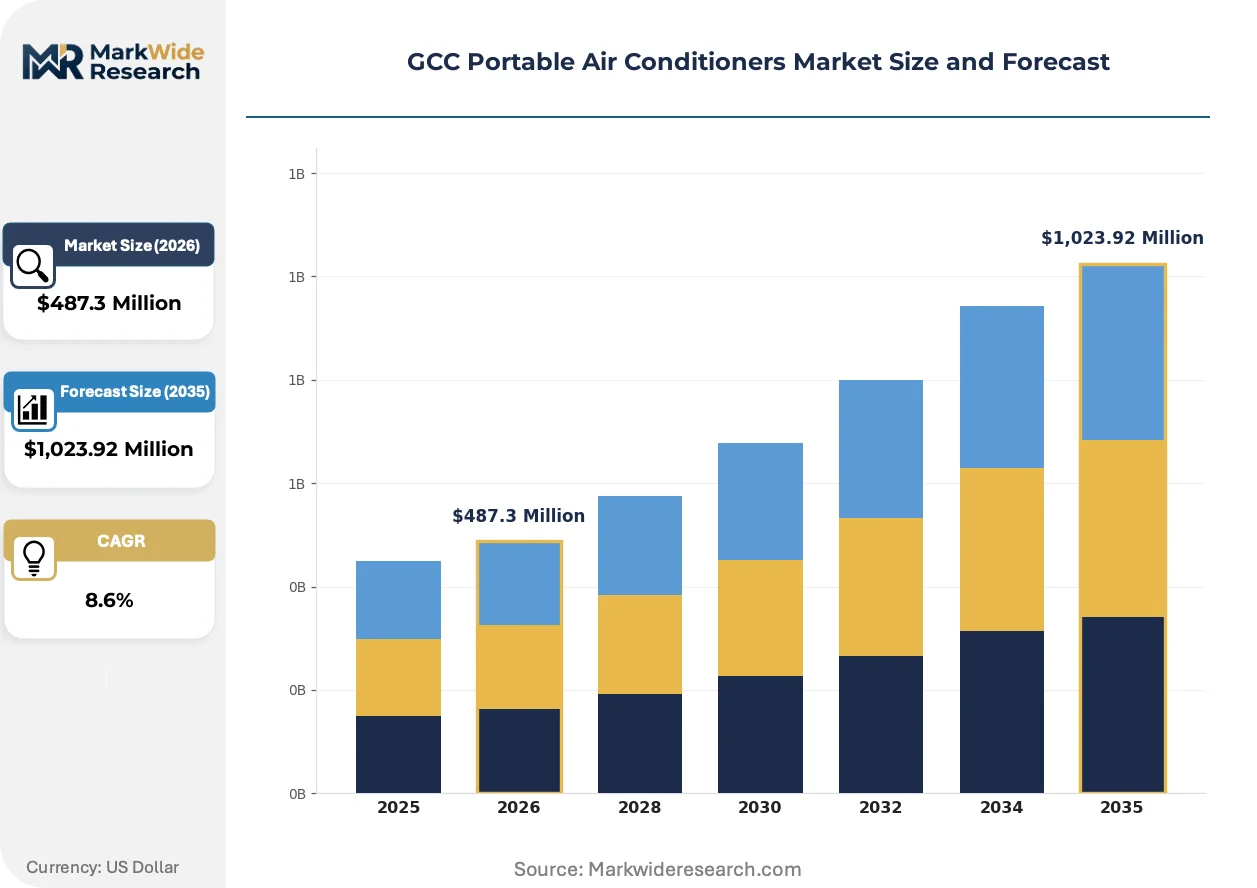
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,023.92 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Hose, Double-Hose, Window-Mounted, Through-the-Wall Application: Residential, Commercial, Industrial, Temporary Cooling Technology: Inverter, Non-Inverter, Smart Controls, Mobile Apps End User: Homeowners, Renters, Small Enterprises, Event Organizers |
| Companies Covered | Daikin Industries, Ltd., Carrier Global Corporation, Mitsubishi Electric Corporation, LG Electronics Inc., Fujitsu General Limited, Gree Electric Appliances, Samsung Gulf Electronics, Lennox, Toshiba Corporation, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Portable Air Conditioners Market Trends and Innovations
Digital control architectures and refrigerant chemistry are converging to redefine portable cooling performance benchmarks across Gulf markets. Equipment buyers now prioritize connectivity-enabled fleet oversight alongside raw thermal output.
Inverter-driven compressor modulation is virtualizing the traditional fixed-speed capacity ladder. Saudi commercial property managers are specifying variable-output units for exhibition halls and temporary office pods. This technology is compressing the addressable market for entry-level single-hose models by delivering superior part-load efficiency in high-ambient conditions.
SASO and ESMA are harmonizing cooling-season performance metrics around seasonal energy efficiency ratios that penalize legacy fixed-speed designs. Manufacturers must redesign control algorithms and expand testing facilities to meet dual-jurisdiction validation requirements. The UAE's commercial segment is responding fastest, with Dubai-based rental fleets accelerating inverter unit procurement ahead of 2026 compliance deadlines.
Asset-light leasing is displacing direct purchase for temporary cooling needs. Qatari construction contractors and Saudi event organizers now specify monthly rental rates with full maintenance inclusion rather than capital expenditure approval. This shift concentrates fleet ownership among specialized rental providers with in-house technical service capabilities, marginalizing traditional distributor-retail channels in commercial segments.
GCC Portable Air Conditioners Market Segmentation
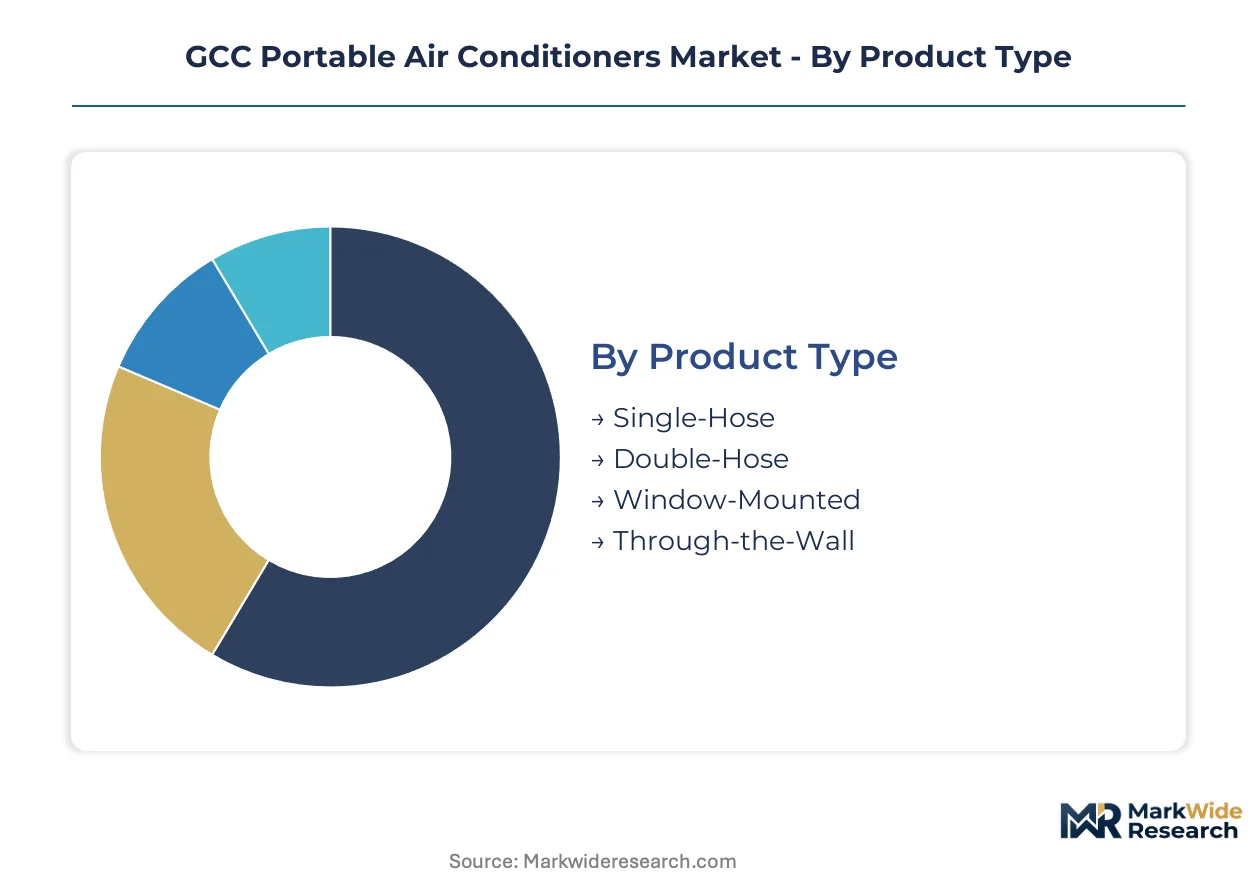
Portable cooling equipment in the GCC demands distinct service protocols across each product configuration. Saudi SASO efficiency mandates and UAE MOHAP safety codes create divergent certification pathways that reshape how segments compete on lifecycle cost rather than upfront price alone.
Product Type:
After-sales service intensity varies sharply by hose configuration, with double-hose units requiring specialized compressor calibration that only inverter-certified technicians can perform.
- Single-Hose:Condenser air intake and exhaust share one duct, creating negative pressure that draws hot ambient air through building envelopes. Saudi residential complexes favor these units for seasonal bedroom cooling where installation speed outweighs efficiency penalties. Service needs concentrate on condensate pump replacement and filter maintenance.
- Double-Hose:Separate intake and exhaust ducts isolate conditioned spaces from infiltration, delivering thermal efficiency gains critical for Dubai exhibition halls and Qatar event infrastructure. The secondary hose adds failure points that demand predictive maintenance contracts.
- Window-Mounted:Semi-permanent installation through wall apertures suits Saudi rental compounds seeking cooling without landlord modifications.
- Through-the-Wall:Sleeve-mounted designs serve UAE hospitality renovations requiring discrete climate control without floor footprint.
By volume, Single-Hose leads. By growth pace, Double-Hose is ahead.
Application:
Cost tier stratification separates capital-purchase residential buyers from rental-fleet commercial operators across the Gulf.
- Residential:Individual unit purchases dominate Saudi homeowner demand, with renters in Riyadh and Jeddah prioritizing sub-10,000 BTU models for apartment cooling. SASO energy-label visibility drives selection behavior at retail.
- Commercial:Dubai hospitality and retail sectors deploy fleet-scale rentals with full maintenance inclusion, concentrating ownership among specialized providers.
- Industrial:Construction camps in remote Saudi zones and Omani oilfield expansions specify ruggedized enclosures with extended duty cycles.
- Temporary Cooling:Qatar's post-World Cup asset redeployment and UAE expo infrastructure create liquid secondary markets for short-term deployment.
Residential commands absolute unit volume. Temporary Cooling is climbing the fastest as event infrastructure multiplies.
Technology:
Margin structure inverts toward connected control architectures as property managers seek fleet visibility.
- Inverter:Variable-speed compressor modulation optimizes part-load efficiency in 45°C-plus ambient conditions prevalent across Gulf interiors. UAE commercial buyers specify these for exhibition halls where load fluctuates with occupancy.
- Non-Inverter:Fixed-speed cycling dominates Saudi price-sensitive residential channels, though SASO efficiency thresholds are compressing their addressable market.
- Smart Controls:WiFi-enabled thermostats and scheduling algorithms serve Qatari compound managers overseeing distributed residential assets.
- Mobile Apps:Remote monitoring and diagnostic alerts reduce technician dispatch frequency for rental fleet operators in Dubai.
Non-Inverter retains installed base dominance. Inverter is gaining share fastest as efficiency regulations tighten.
End User:
Customer type determines procurement channel and service expectation intensity.
- Homeowners:Saudi nationals in Riyadh and Jeddah purchase through retail channels with extended warranty preferences.
- Renters:Expatriate populations in UAE and Qatar favor portable solutions avoiding permanent installation restrictions.
- Small Enterprises:Retail shops and clinics in Oman and Bahrain require supplemental cooling without HVAC capital expenditure.
- Event Organizers:Dubai exhibition contractors and Saudi festival operators specify rental-only procurement with 24-hour technical response.
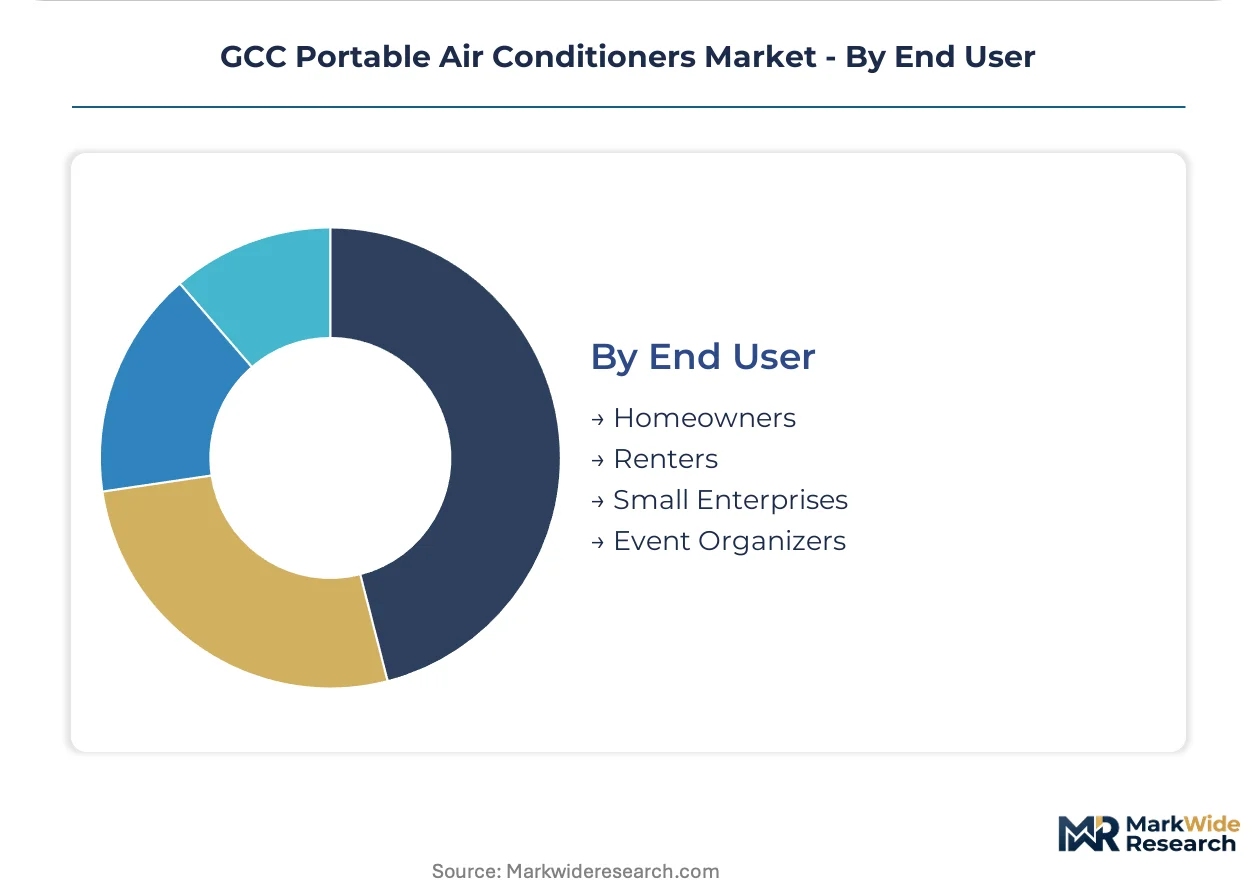
Homeowners represent the largest addressable population. Event Organizers show the steepest expansion trajectory as hospitality infrastructure scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency shapes competitive dynamics across GCC portable cooling markets, with Saudi Arabia and the UAE absorbing the majority of regional equipment inflows. Local assembly remains limited, concentrating value-added activity in distribution and rental fleet management rather than manufacturing.
Saudi Arabia
Riyadh's residential construction boom and Jeddah's hospitality retrofit cycle drive sustained equipment demand. SASO energy-labeling mandates are compressing margins for non-compliant imports while rewarding inverter-ready manufacturers. Eastern Province industrial zones are deploying ruggedized units for remote construction camps.
United Arab Emirates
Dubai's exhibition infrastructure and Abu Dhabi's healthcare expansion anchor commercial fleet procurement. MOHAP building safety codes mandate temporary cooling redundancy for hospital renovations. Sharjah's manufacturing free zones are emerging as regional distribution hubs for re-export to African markets.
Qatar
Post-2022 World Cup asset redeployment has created liquid secondary markets for portable cooling equipment. Doha's property managers are specifying smart-connected units for distributed residential compounds. The country's national standardization body is aligning efficiency metrics with Saudi and Emirati frameworks.
Kuwait
Summer peak demand strains grid capacity, accelerating rental fleet procurement for commercial backup cooling. The Ministry of Electricity and Water efficiency directives are filtering single-hose residential imports. Hawalli Governorate retail clusters are prioritizing SASO-labeled inventory.
Oman
Remote oilfield expansions and off-grid construction camps are driving demand for solar-integrated portable units. The Directorate General of Standards and Metrology is implementing cooling-season performance testing protocols. Duqm Special Economic Zone infrastructure projects are specifying extended-duty-cycle equipment.
GCC Portable Air Conditioners Market Competitive Landscape
On the supply side, the industry is bifurcated between diversified HVAC conglomerates and specialized rental fleet operators. Japanese and Korean electronics groups anchor premium inverter segments through technology licensing networks. Chinese manufacturing groups compete on acquisition cost in single-hose residential channels. Gulf-based rental specialists are consolidating fleet ownership through asset-light leasing structures. Competitive moves center on service-contract bundling and predictive maintenance capability deployment.
Within the diversified HVAC conglomerate tier, Daikin Industries, Ltd. and Carrier Global Corporation exemplify contrasting strategic positions. Daikin anchors premium commercial positioning through inverter technology representation. Carrier occupies the service-integration archetype, bundling equipment with long-term maintenance contracts. Gree Electric Appliances sits within the manufacturing-scale tier, competing on cost structures in price-sensitive residential segments. Samsung Gulf Electronics represents the regional subsidiary model, leveraging local distribution infrastructure for rapid market response.
| Leading Market Players |
|---|
| Daikin Industries, Ltd. |
| Carrier Global Corporation |
| Mitsubishi Electric Corporation |
| LG Electronics Inc. |
| Fujitsu General Limited |
| Gree Electric Appliances |
| Samsung Gulf Electronics |
| Lennox |
| Toshiba Corporation |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Chinese compressor manufacturing is compressing export pricing for GCC-bound portable cooling equipment while simultaneously pressuring regional assemblers to absorb margin erosion or cede share to direct imports. This utilization dynamic rewards inverter-ready manufacturers with SASO certification while squeezing non-compliant single-hose assemblers out of Saudi retail channels.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the GCC portable cooling market. Price differentiation rests on inverter certification status and after-sales service bundling intensity. Cost compression in the single-hose residential tier is intensifying because Saudi SASO efficiency mandates are filtering out legacy fixed-speed imports. Expatriate renters in Qatar and UAE represent the most price-sensitive segment, while Dubai exhibition contractors demonstrate lowest sensitivity due to rental-fleet procurement with full maintenance inclusion.
Supply Chain Analysis
Extended payment terms from Chinese compressor manufacturers are reshaping working capital requirements for GCC-based rental fleet operators and regional distributors. Geographic supply concentration centers on China for rotary compressors and heat exchangers, South Korea for inverter control modules, and Thailand for condensate pump assemblies. Raw material dependencies draw from copper-aluminum alloys for coils, R-32 and R-410A refrigerant feedstocks, and ABS enclosures. Single-source vulnerability around Asian refrigerant suppliers exposes assemblers to quota restrictions. Distribution runs through Sharjah's free zone hubs for re-export and direct-to-fleet rental providers bypassing traditional retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asset-light leasing fragmentation across the GCC is creating specialist niches for technical service providers and inverter-certified maintenance networks. Temporary cooling demand from Dubai's exhibition infrastructure and Qatar's post-Event asset redeployment is splintering procurement authority away from traditional HVAC distributors.
For Market Incumbents: Build certification moats through simultaneous SASO and ESMA approval capacity to compress competitor launch timelines by 8-14 months. Incumbents should deepen backward integration into inverter control module sourcing to offset Asian feedstock concentration risk. Channel control through exclusive service-contract bundling defends against rental-fleet operators consolidating fleet ownership. R&D investment in solar-integrated portable units for Oman's off-grid construction camps creates differentiation against pure-play imports. For New Entrants and Emerging Players: Mid-market commercial buildings in Saudi Arabia's Eastern Province industrial zones represent the most penetrable entry point for ruggedized extended-duty-cycle equipment. Qatar's smart-connected residential compound market offers white-space for WiFi-enabled fleet management platforms targeting property managers overseeing distributed assets. A direct rental-fleet partnership model with Dubai exhibition contractors bypasses capital-intensive distributor network buildout. For Investors and Strategic Acquirers: Capital is best deployed toward specialized rental fleet operators with in-house inverter technician training capabilities and predictive maintenance infrastructure. Long-term viability across the analysis window favors asset-light models with technical service density over pure manufacturing scale. The signal to watch is Saudi SASO efficiency threshold escalation pace, which determines the rate of fixed-speed model obsolescence and inverter replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Inverter Certification Investment | Dual SASO-ESMA approval compresses competitor product launch windows by sequential testing protocols. |
| Backward Integration into Compressor Sourcing | Captive supply of rotary compressors from Chinese manufacturers insulates margin from refrigerant feedstock volatility. |
| Smart Fleet Management Platform Launch | WiFi-enabled remote monitoring addresses Qatari property manager demand for distributed residential asset oversight. |
| Solar-Integrated Product Line Extension | Photovoltaic pairing targets Omani off-grid construction camps and remote Saudi industrial zones cutting diesel dependency. |
| Rental Fleet Operator Acquisition | Consolidated fleet ownership with in-house technical service captures asset-light leasing displacement of direct purchase. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with rental fleet managers, HVAC distributor procurement heads, inverter-certified service technicians, and Saudi SASO compliance officers. Secondary validation drew from SASO energy-labeling databases, ESMA product registration filings, customs import manifests for GCC cooling equipment, and trade association shipment reports. Bottom-up equipment unit deployment estimates and top-down market value reconstruction were triangulated to cross-validate segmentation outputs.
Calibration against historical efficiency regulation implementation timelines anchored the projection framework across the analysis window. Segmentation dimensions modeled include hose configuration, inverter versus fixed-speed technology, application category, and end-user procurement channel. CAGRs were derived from regression analysis of regulatory compliance cost pass-through and rental-fleet penetration curves. Industry-specific forecast inputs incorporated copper-aluminum price volatility assumptions and refrigerant quota restriction scenarios.
Practitioners should monitor SASO cooling-season performance metric harmonization with ESMA frameworks for early signals of competitive repositioning. Forecasts reflect documented assumptions around regulatory enforcement intensity and rental-fleet ownership consolidation velocity. Macroeconomic deviation in Gulf construction activity, regulatory acceleration beyond published efficiency thresholds, or breakthrough solar-integration cost reduction would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Chilled Beams Market
HVAC Equipment
Canada HVAC Equipment Market
HVAC Equipment
Industrial Electric Boiler Market
HVAC Equipment
Screw Compressor Market
HVAC Equipment
Underfloor Air Distribution Systems Market
HVAC Equipment
United Kingdom Heating Equipment Market
HVAC Equipment
HVAC Airflow and Blend Door Actuator Systems Market
HVAC Equipment
Latin America Heat Exchanger Market
HVAC Equipment
Industrial Dehumidifiers Market
HVAC Equipment
Warm Air Heater Market
HVAC Equipment
United Kingdom HVAC Market
HVAC Equipment
North America Ceiling Cassette Market
HVAC Equipment
Dedicated Outdoor Air System Market
HVAC Equipment
Global Smart Vent Market
HVAC Equipment
Air-Cooled Heat Exchangers Market
HVAC Equipment
Compressor Controllers Market