
 Regenerative Heat Exchanger Market | 2026-2036
Regenerative Heat Exchanger Market Size, Share, and Industry Trends Forecast 2026-2036
Regenerative Heat Exchanger Market Analytics
Aftermarket service contracts and remote monitoring subscriptions is consolidating around hardware vendors as a recurring revenue layer. Alfa Laval AB leverages its installed base to bundle predictive maintenance with plate heat exchanger retrofits. Kelvion Holding GmbH anchors its competitiveness through regionally staffed service hubs that reduce client downtime. Hisaka Works, Ltd. specializes in compact regenerative designs where post-sale thermal audits drive repeat engagement.
Regenerative heat exchangers are thermal recovery devices that store and release heat via cyclic flow reversal through a packed ceramic or metallic matrix, typically achieving thermal effectiveness above 80 percent in industrial exhaust streams. Their primary purpose is to preheat combustion air or process fluids using waste heat that would otherwise vent to atmosphere. Shell and tube configurations dominate heavy-process installations where pressure tolerance and fouling resistance matter most, while plate heat exchangers capture margin pools in HVAC and food processing where compact footprint and cleanability command premium pricing. Waste heat recovery applications lead volume demand across power generation and chemical processing sectors.
EPA rules under the Clean Air Act shape stack temperature limits for US industrial facilities, while REACH and EU F-Gas Regulation restrict refrigerant choices in European cooling-integrated regenerative systems. Japan's METI energy efficiency standards push domestic process industries toward higher-effectiveness ceramic matrix designs. Stakeholders must monitor how carbon border adjustment mechanisms in key export markets reshape total cost of ownership calculations for heat recovery investments.
Market Dynamics
Chemical processing plants and power generators are accelerating regenerative heat exchanger procurement as EPA stack temperature limits and EU F-Gas thermal efficiency mandates force capital redeployment toward exhaust energy capture systems.
Growth Catalysts
- EPA Clean Air Act enforcement:US industrial facilities face tightening stack temperature thresholds that mandate waste heat recovery installation.
- Ceramic matrix thermal effectiveness:Advanced honeycomb and structured packing designs now exceed 80 percent effectiveness in high-temperature exhaust streams.
- German process industry density:Engineering-intensive chemical and petrochemical clusters anchor procurement of high-efficiency regenerative units.
Market Restraints
- Refractory ceramic supply concentration:High-purity alumina and silicon carbide substrates depend on limited specialty materials suppliers in China and Germany.
- REACH compliance friction:EU chemical registration requirements delay material qualification timelines for new ceramic matrix formulations.
- Compact plate heat exchanger substitution:HVAC and food processing buyers increasingly specify plate designs where footprint and cleanability outweigh thermal effectiveness.
Strategic Opportunities
- India petrochemical expansion:Reliance Industries and Indian Oil Corporation are building crackers and aromatics complexes requiring exhaust heat recovery.
- Carbon border adjustment mechanism preparation:EU importers are pre-investing in thermal efficiency to defend against embedded carbon tariffs on steel and chemicals.
- Predictive maintenance convergence:IoT sensor networks and thermal audit software are creating bundled hardware-service offerings.
Industry Challenges
- Ceramic matrix thermal stress modeling:Engineers with cyclic fatigue simulation expertise remain scarce relative to deployment timelines.
- Legacy shell-and-tube integration:Brownfield chemical plants require custom ducting and control retrofits that extend commissioning schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Regenerative Heat Exchanger Market |
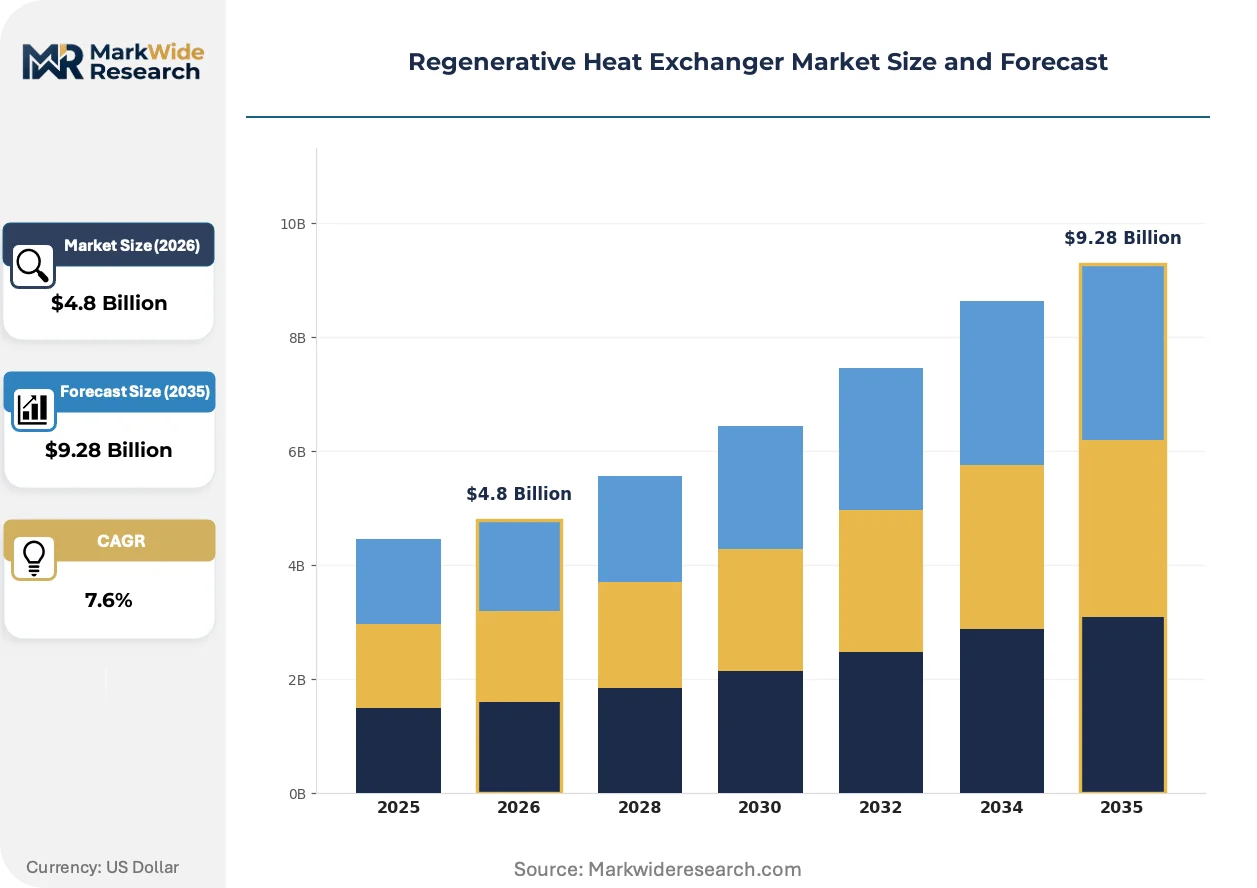
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
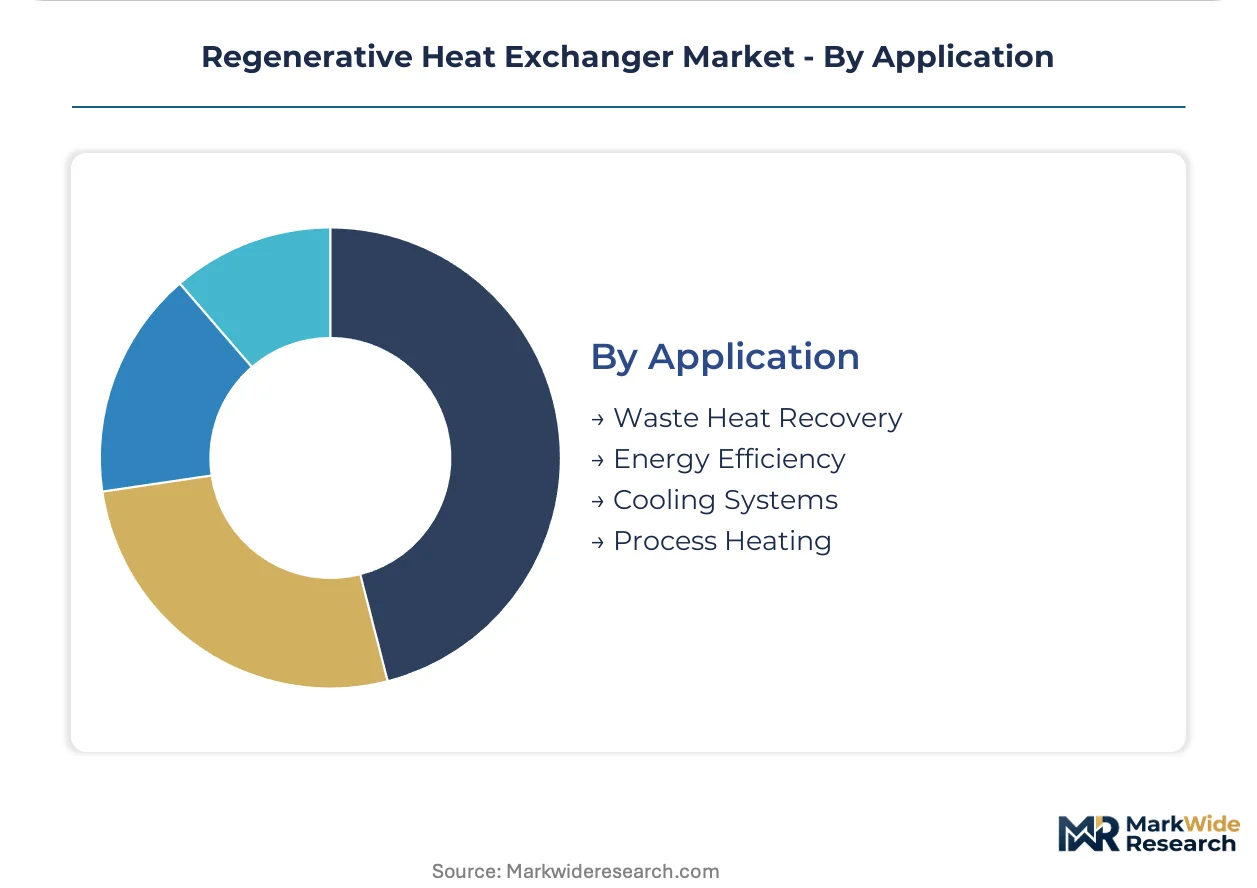
| Segmentation | Product Type: Plate Heat Exchanger, Shell and Tube, Double-Pipe Heat Exchanger, Air-to-Air Heat Exchanger End User: Power Generation, Chemical Processing, HVAC, Food and Beverage Technology: Convection, Radiation, Evaporation, Condensation Application: Waste Heat Recovery, Energy Efficiency, Cooling Systems, Process Heating |
| Companies Covered | Alfa Laval AB, Kelvion Holding GmbH, Danfoss A/S, GEA Group AG, SPX Flow Inc., Xylem Inc., API Heat Transfer Inc., Hisaka Works, Ltd., Hindustan Dorr-Oliver Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Regenerative Heat Exchanger Market Evolving Landscape
Three forces are compressing regenerative heat exchanger development cycles: ceramic matrix material science breakthroughs, transatlantic regulatory alignment on thermal efficiency, and buyer migration toward performance-guaranteed service contracts over capital purchase.
Additive manufacturing of structured ceramic packing is rewriting regenerator design economics. 3D-printed lattice geometries achieve surface-area-to-volume ratios impossible with extruded honeycomb. Power generation OEMs including boiler manufacturers are qualifying these designs for cyclic duty. The technology is compressing lead times from eighteen months to eight weeks for custom matrix geometries.
EU F-Gas Regulation phase-down schedules are forcing cooling-integrated regenerative system redesigns. Equipment suppliers must qualify alternative working fluids with lower global warming potential. Chemical processing installations in Germany and the Netherlands face 2027 compliance deadlines that accelerate procurement of refrigerant-free air preheaters.
Buyers are unbundling hardware procurement from thermal performance guarantees. Energy service companies now underwrite heat recovery output, shifting operational risk from plant operators to vendors. This model is concentrating in US refineries and EU steel mills where carbon accounting transparency affects product marketability.
Regenerative Heat Exchanger Market Segmentation
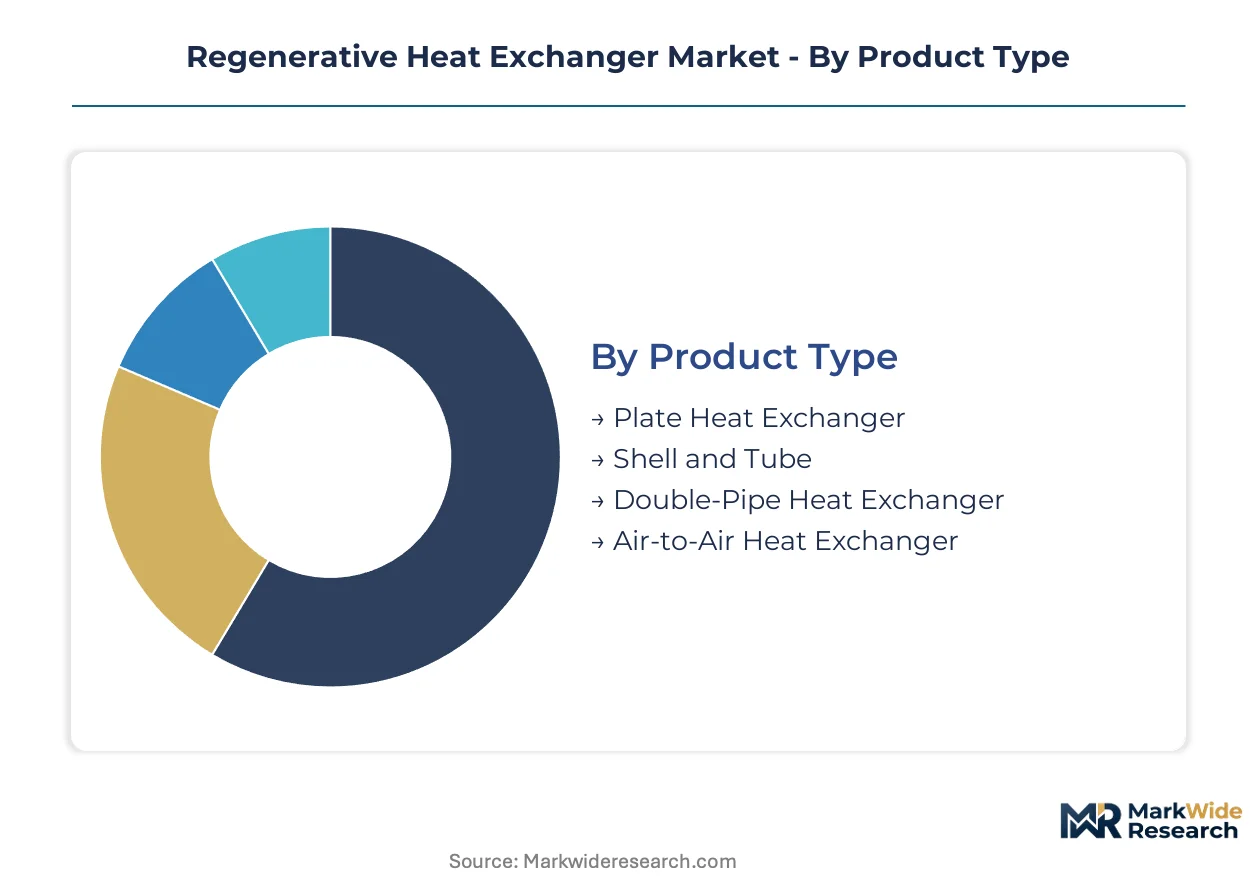
Segmentation in regenerative heat exchangers reflects divergent engineering priorities across temperature ranges, fouling tolerance, and thermal effectiveness targets. Procurement patterns vary sharply between heavy-process industries demanding pressure-rated shell configurations and commercial buyers prioritizing compact footprint.
Product Type:
Customization intensity spans from standardized plate geometries to fully engineered shell-and-tube assemblies for extreme pressure differentials.
- Shell and Tube:Cylindrical pressure vessels containing tube bundles withstand thermal cycling above 500°C in chemical crackers and reformers. Demand concentrates in US Gulf Coast petrochemical complexes where EPA stack temperature enforcement mandates exhaust heat capture retrofitting.
- Plate Heat Exchanger:Corrugated metal plates create turbulent flow in compact footprints, achieving effectiveness above 85% in clean service. German HVAC and food processing buyers specify these for cleanability and modularity, though gasket material selection faces REACH registration delays.
- Double-Pipe Heat Exchanger:Concentric tube designs serve high-viscosity fluids in small-batch chemical operations.
- Air-to-Air Heat Exchanger:Direct gas-to-gas recovery dominates power plant combustion air preheating with minimal pressure drop.
Most installed capacity flows through Shell and Tube. Expansion is steepest in Plate Heat Exchanger.
End User:
Application maturity ranges from century-old power generation deployment to emerging food processing specifications driven by energy cost volatility.
- Chemical Processing:Regenerative units preheat feedstocks and recover exothermic reaction heat across ethylene crackers, ammonia loops, and aromatics complexes. Indian petrochemical expansion at Reliance and IOCL complexes is driving procurement of ceramic matrix units for exhaust streams above 800°C.
- Power Generation:Boiler combustion air preheaters represent the largest installed base, with rotary regenerators achieving 70-80% effectiveness in coal and combined-cycle plants. German utilities retrofitting lignite units face EU F-Gas Regulation deadlines for refrigerant-integrated cooling systems.
- HVAC:Building energy recovery ventilators specify compact regenerative wheels for sensible and latent heat recovery.
- Food and Beverage:Pasteurization and drying processes adopt hygienic plate designs with CIP compatibility.
Volume leadership sits with Power Generation. Chemical Processing is gaining share fastest.
Technology:
Heat transfer mechanism selection depends on whether the application prioritizes maximum recovery rate or tolerance of extreme temperature differentials.
- Convection:Forced gas or liquid flow across packed ceramic or metallic matrices dominates industrial regenerative design, achieving effectiveness above 80% in cyclic operation. Japanese METI efficiency standards push domestic industries toward advanced honeycomb geometries.
- Radiation:High-temperature exhaust streams above 1000°C in steel reheating furnaces employ radiative heat transfer to ceramic media.
- Evaporation:Phase-change working fluids enable thermal storage in compact configurations.
- Condensation:Latent heat recovery from moisture-laden exhaust improves net efficiency in drying applications.
Convection handles the bulk of throughput. Radiation is climbing fastest in steel and glass sectors.
Application:
Buyer value propositions range from compliance-driven stack temperature reduction to output-guaranteed energy service contracts.
- Waste Heat Recovery:Exhaust stream energy capture preheats combustion air or process feeds, directly addressing EPA Clean Air Act limits and EU carbon border adjustment exposure. US refineries and EU steel mills now procure through energy service companies that underwrite thermal output.
- Energy Efficiency:Building codes and industrial energy intensity targets drive specification of high-effectiveness regenerative units. German process industry clusters anchor European demand for systems exceeding 85% thermal effectiveness.
- Cooling Systems:Integrated regenerative precooling reduces mechanical refrigeration load in data centers and district cooling.
- Process Heating:Direct thermal integration raises reaction temperatures without incremental fuel burn.
Waste Heat Recovery commands the largest project pipeline. Energy Efficiency is expanding most quickly as carbon accounting transparency reshapes procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering-intensive process industries anchor European procurement of high-effectiveness regenerative units, while Indian petrochemical expansion drives the steepest capacity additions in Asia-Pacific.
United States
Gulf Coast petrochemical complexes and refinery retrofits dominate procurement as EPA Clean Air Act enforcement tightens stack temperature thresholds. The EPA mandates waste heat recovery installation across ethylene crackers and reformers. Houston and Corpus Christi industrial clusters are accelerating exhaust energy capture system deployment to meet compliance deadlines.
Germany
Chemical and steel sectors concentrate demand for ceramic matrix designs exceeding 85% thermal effectiveness. The EU F-Gas Regulation forces refrigerant-free air preheater procurement ahead of 2027 deadlines. The Ruhr industrial basin and Ludwigshafen chemical cluster anchor high-efficiency regenerative unit specification for lignite unit retrofits and aromatics complexes.
India
Reliance Industries and Indian Oil Corporation are building crackers and aromatics complexes requiring exhaust heat recovery above 800°C. The Bureau of Indian Standards and CEA efficiency codes push domestic industries toward advanced heat recovery. Gujarat and Maharashtra petrochemical corridors are driving ceramic matrix regenerative unit procurement for new capacity.
Japan
Domestic process industries adopt higher-effectiveness ceramic matrix designs under METI energy efficiency standards. METI mandates push steel and chemical sectors toward advanced honeycomb geometries. The Chubu industrial region around Nagoya and Keihin corridor near Tokyo concentrate retrofit activity for cyclic duty regenerators.
China
Power generation and chemical processing sectors deploy regenerative units for waste heat recovery amid dual carbon goals and MEE emissions standards. MIIT efficiency targets accelerate ceramic matrix adoption in high-temperature exhaust streams. The Yangtze River Delta and Shandong Peninsula industrial clusters lead procurement for coal and combined-cycle plant retrofits.
Regenerative Heat Exchanger Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with engineering-intensive applications favoring integrated solution providers while standardized HVAC procurement tilts toward volume fabricators. The vendor base organizes into three tiers: full-service thermal engineering houses, regional plate heat exchanger specialists, and Asian-scale metal fabricators. Consolidation pressure is accelerating as energy service companies demand performance guarantees that smaller players cannot underwrite. Dominant competitive moves include predictive maintenance bundling and ceramic matrix material science partnerships.
Among European-based thermal engineering houses, Alfa Laval AB and Kelvion Holding GmbH exemplify the full-service archetype, while Hisaka Works, Ltd. represents Japanese precision in compact regenerative design. These three occupy positions where installed base scale and regional service density create defensive moats against Asian cost competition. Alfa Laval leverages its global footprint to anchor predictive maintenance offerings, Kelvion staffs regionally clustered service hubs, and Hisaka drives repeat engagement through post-sale thermal audit programs.
| Leading Market Players |
|---|
| Alfa Laval AB |
| Kelvion Holding GmbH |
| Danfoss A/S |
| GEA Group AG |
| SPX Flow Inc. |
| Xylem Inc. |
| API Heat Transfer Inc. |
| Hisaka Works, Ltd. |
| Hindustan Dorr-Oliver Ltd. |
| Others |
Value Network & Pricing Analysis
EU F-Gas Regulation phase-down schedules gate qualified supply for refrigerant-integrated regenerative systems, reserving premium-tier pricing access to vendors with certified alternative working fluid portfolios. Buyers in Germany and the Netherlands face compliance deadlines that compress procurement timelines and concentrate purchasing power among pre-qualified engineering houses.
Pricing Analysis
Capacity additions in China are reshaping price floors for standardized ceramic matrix substrates, pressuring margin structures for European and Japanese incumbents. Three-tier pricing structure across premium, standard, and economy levels separates ASME-certified pressure vessel assemblies from modular plate designs and commodity replacement cores. Price differentiation hinges on thermal effectiveness guarantees and bundled predictive maintenance subscriptions. Cost compression in economy-tier plate heat exchangers is intensifying because Asian fabricators are scaling automated welding capacity. HVAC and food processing buyers exhibit highest price sensitivity, while chemical crackers and power generators prioritize performance guarantees over unit cost.
Supply Chain Analysis
REACH registration and ASME certification requirements gate qualified supply of gasket materials and pressure-rated steel alloys, elongating vendor onboarding timelines. High-purity alumina and silicon carbide substrates draw from concentrated specialty ceramics production in China and Germany, with secondary sourcing from Japan. Supply chain risk centers on single-source vulnerability for honeycomb extrusion dies and refractory-grade binders. Distribution runs through OEM-direct channels for engineered shell-and-tube assemblies and regional distributors for standardized plate heat exchanger retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA Clean Air Act stack temperature enforcement and EU F-Gas phase-down schedules mechanically expand addressable demand for exhaust heat recovery systems.
For Market Incumbents: Extend predictive maintenance bundling to capture recurring revenue streams and defend against Asian cost competition in standardized plate segments. Deepen backward integration into ceramic matrix material science partnerships to secure honeycomb supply and accelerate additive manufacturing qualification cycles. Anchor competitiveness through regionally staffed service hubs that reduce client downtime in chemical processing corridors.
For New Entrants and Emerging Players: Additive manufacturing of structured ceramic packing offers a technology-first wedge into custom regenerator geometries where lead time compression commands premium pricing. Target India's petrochemical expansion corridors where Reliance Industries and Indian Oil Corporation procurement lacks established service infrastructure. Pursue energy service company partnerships that underwrite thermal output and shift operational risk from plant operators.
For Investors and Strategic Acquirers: Roll-up economics work for regional plate heat exchanger specialists because customer concentration in HVAC and food processing creates cross-selling leverage for predictive maintenance platforms. Five-to-ten year viability hinges on carbon border adjustment mechanism preparation driving EU importer pre-investment in thermal efficiency. Monitor ceramic matrix thermal stress modeling talent scarcity as an inflection indicator for engineering-intensive acquisition premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Matrix Supply | Captive access to high-purity alumina hedges against China supply concentration and REACH registration delays. |
| Predictive Maintenance Platform Launch | IoT sensor networks bundled with hardware create recurring revenue layers that Asian fabricators cannot replicate. |
| Additive Manufacturing Qualification | 3D-printed lattice geometries compress custom regenerator lead times from eighteen months to eight weeks for power generation OEMs. |
| Energy Service Company Partnership | Performance-guaranteed contracts shift operational risk and concentrate procurement authority with underwriters in US refineries. |
| Regional Service Hub Expansion | Staffed maintenance presence in Gujarat and Maharashtra corridors captures Indian petrochemical procurement lacking local vendor density. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with plant engineers, OEM procurement teams, aftermarket service heads, and thermal audit specialists against secondary validation. Bottom-up sizing drew from customs data, industrial equipment trade associations, and SEC filings of listed thermal engineering houses, while top-down triangulation cross-checked against national energy efficiency agency disclosures and EPA enforcement databases.
Segment-weighting approaches distributed volume and value across product type, end-use industry, heat transfer mechanism, and application across the analysis window. Modeled dimensions included shell-and-tube versus plate versus ceramic matrix configurations, chemical processing versus power generation versus HVAC demand clusters, and convection versus radiation versus phase-change technologies. CAGRs derived from regression against industrial capacity expansion pipelines and regulatory milestone calendars, with specific inputs from METI efficiency standard trajectories and EU carbon border adjustment implementation timelines.
The model holds under sustained EPA enforcement and EU F-Gas compliance deadlines; deviation in ceramic matrix material qualification timelines or refractory supply disruptions would shift deployment schedules. Forecasts reflect documented assumptions regarding industrial energy intensity targets and carbon accounting transparency requirements. A model refresh is warranted upon material change in transatlantic regulatory alignment or breakthroughs in compact plate heat exchanger thermal effectiveness.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Systems
Europe District Cooling Pipeline Network Market
HVAC Systems
Global Tunnel and Metro Ventilation Market
HVAC Systems
HVAC and Fire Protection Insulation Market
HVAC Systems
Hydronic Control Market
HVAC Systems
Europe HVAC Services Market
HVAC Systems
Europe Residential Heat Pump Market
HVAC Systems
UK Commercial Boiler Market
HVAC Systems
Global Commercial Insulation Market
HVAC Systems
Aeration System Market
HVAC Systems
Malaysia Building Thermal Insulation Material Market
HVAC Systems
Greenhouse Ventilation System Market
HVAC Systems
Reverse Flame Steam Boiler Market
HVAC Systems
Global Ventilation Grills Market
HVAC Systems
Marine HVAC System Market
HVAC Systems
Air Pressure Booster System Market
HVAC Systems
North America Scrubber System Market