
 Global Industrial Fans and Blowers Market | 2026-2036
Global Industrial Fans and Blowers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Industrial Fans and Blowers Market Outlook
Aftermarket service revenue is reshaping margin distribution across the Global Industrial Fans and Blowers Market as original equipment profitability compresses. Atlas Copco leverages its global compressor service infrastructure to cross-sell fan maintenance contracts. Ingersoll Rand anchors its position through integrated air system lifecycle management. Greenheck Fan Corporation specializes in custom engineered solutions for critical ventilation applications.
Industrial fans and blowers are mechanical devices engineered to move air or gases at pressures ranging from a few hundred pascals to several kilopascals, utilizing impeller designs optimized for specific flow regimes and efficiency targets. Centrifugal fans dominate heavy-process applications where higher static pressures are required for material handling and combustion air supply. The aluminum segment is gaining ground in corrosive environments and weight-sensitive installations. By end user, HVAC applications are absorbing volume as building energy codes tighten across major economies.
The US EPA enforces emissions standards that mandate efficient ventilation in chemical processing and power generation facilities, while the EU F-Gas Regulation restricts fluorinated gas use in cooling systems, elevating demand for advanced air-moving equipment. China's MEE implements industrial emission limits that require upgraded exhaust and dust collection systems in steel and cement plants. Stakeholders must monitor evolving carbon border mechanisms and efficiency labeling schemes that will determine competitive access across major demand centers.
Market Dynamics
Aftermarket service revenue is compressing original equipment margins and forcing manufacturers to restructure their business models around lifecycle value capture rather than upfront equipment sales.
Growth Catalysts
- EU F-Gas Regulation:Restrictions on fluorinated refrigerants in cooling systems are elevating demand for advanced air-moving equipment as direct substitutes in industrial climate control.
- Hyperscale data centers:Multi-megawatt facilities require precision cooling infrastructure, driving specification of high-efficiency centrifugal and axial fan arrays.
- China's industrial automation:Steel and cement plants under MEE emission mandates are retrofitting exhaust and dust collection systems with upgraded blowers.
Market Restraints
- Aluminum price volatility:Raw material swings for corrosion-resistant impeller alloys compress margin predictability for engineered-to-order manufacturers.
- Supply concentration in rare-earth magnets:Permanent magnet motor dependencies create vulnerability in high-efficiency EC fan production chains.
- Technical ceiling in static pressure:Conventional centrifugal designs face physical limits for material handling applications above 15 kilopascals without radical geometry changes.
Strategic Opportunities
- India's PLI scheme for manufacturing:Incentive structures for capital goods localization offer entry points for blower assembly and component sourcing.
- Digital twin convergence:Integration of CFD modeling with IoT sensor networks enables predictive maintenance contracts for critical ventilation infrastructure.
- Green hydrogen electrolysis:Emerging gigawatt-scale electrolyzer facilities require specialized hydrogen-compatible blower systems for gas circulation and purification.
Industry Challenges
- Aerodynamics simulation talent scarcity:Computational fluid dynamics expertise for custom impeller design concentrates in a handful of technical institutes and specialist consultancies.
- ATEX certification timelines:Explosion-proof fan approvals for chemical and petrochemical environments extend 12-18 months, delaying project revenue recognition.
- Legacy BAS integration:Building automation system protocols vary across installed bases, complicating smart fan retrofit deployments in commercial HVAC.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Industrial Fans and Blowers Market |
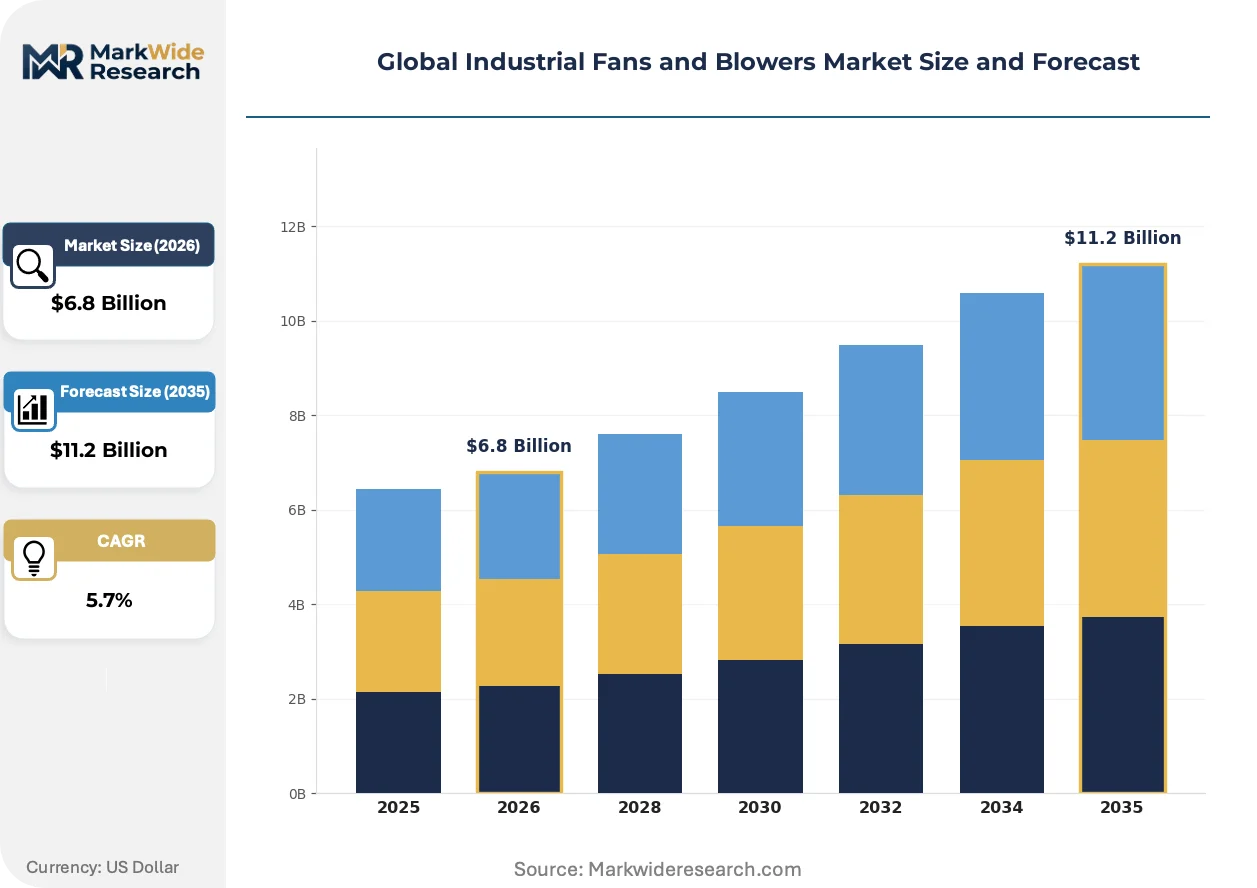
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Axial Fans, Centrifugal Fans, Blowers, Mixed Flow Fans End User: Manufacturing, Construction, Mining, HVAC Material: Aluminum, Steel, Plastic, Composite Application: Ventilation, Cooling, Drying, Exhaust |
| Companies Covered | Atlas Copco, Ingersoll Rand, Greenheck Fan Corporation, Howden Group, Systemair AB, Aerzen, Kaeser Kompressoren, New York Blower, Twin City Fan Companies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Industrial Fans and Blowers Market Strategic Shifts
Digital engineering tools are compressing product development cycles while regulatory pressure on energy efficiency is forcing redesign of core aerodynamic architectures across all pressure classes.
Computational fluid dynamics software combined with generative design algorithms is virtualizing the traditional prototype-test-iterate development model for centrifugal impellers. Fan manufacturers now simulate 50-100 geometry variants before physical validation, cutting R&D expenditure and time-to-market for custom engineered solutions. Data center operators and pharmaceutical cleanroom specifiers are adopting these virtually validated designs at accelerating pace, collapsing the competitive advantage of incumbent physical test facilities.
The EU F-Gas Regulation's phase-down schedule is mandating refrigerant containment and leak detection in industrial cooling circuits. This policy is redirecting capital expenditure toward air-side economization and evaporative cooling systems that depend on high-volume, low-pressure fan arrays. Food processing and cold chain logistics facilities across Germany, France, and the Netherlands are retrofitting rooftop ventilation packages to maintain operational compliance.
Specification authority is migrating from mechanical contractors to energy performance consultants who model total cost of ownership across 15-20 year horizons. This behavioral shift elevates premium-efficiency EC motor fans over standard AC alternatives in competitive bidding for healthcare and education sector projects. The transition is most visible in Nordic markets where public procurement mandates reference ISO 12759 fan efficiency grades as minimum technical compliance thresholds.
Global Industrial Fans and Blowers Market Segmentation
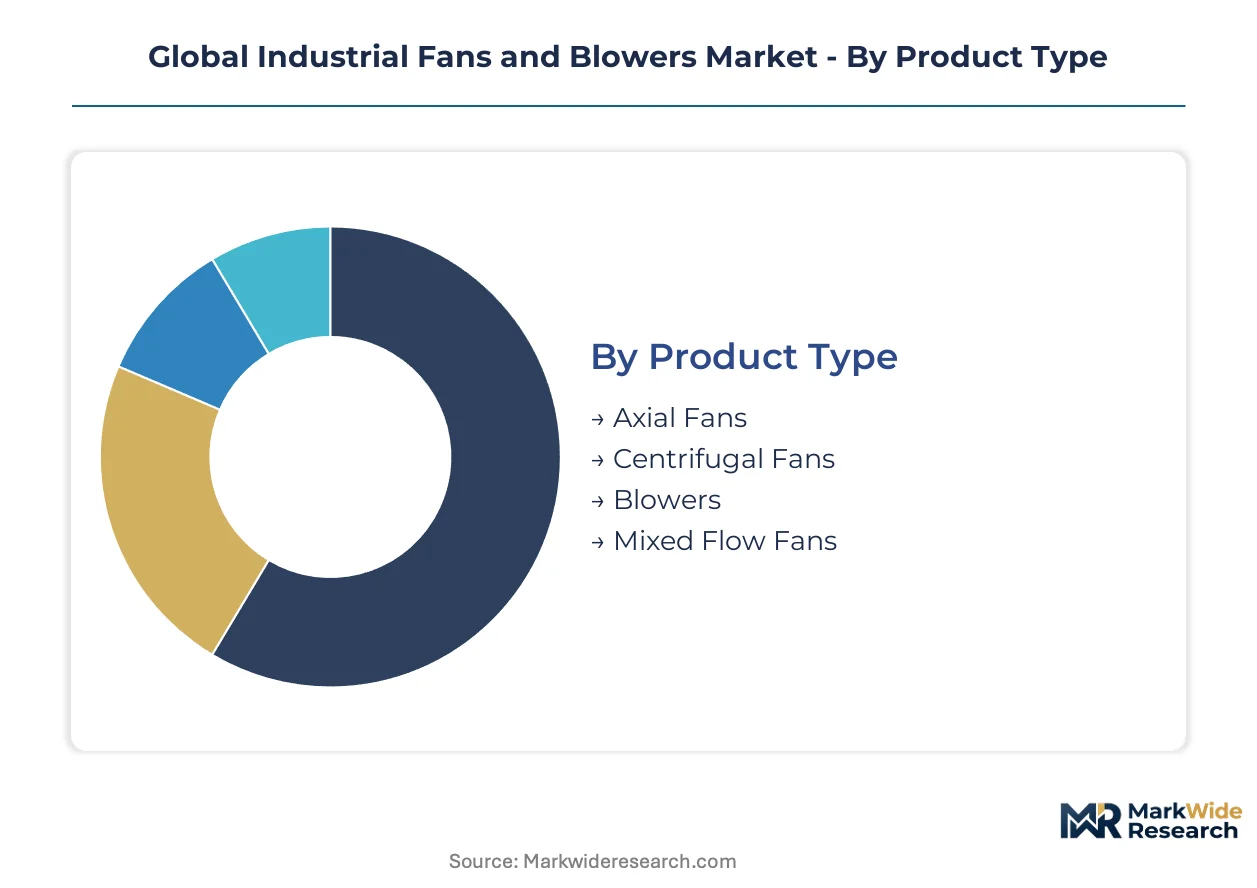
Segmentation in the Global Industrial Fans and Blowers Market reveals distinct service intensity profiles. Aftermarket revenue concentration varies dramatically by product complexity and operating environment, reshaping how manufacturers allocate field engineering resources.
Product Type:
Aftermarket service intensity escalates with impeller complexity and bearing system sophistication, creating divergent margin profiles across mechanical architectures.
- Axial Fans:Propeller-style impellers generate airflow parallel to the drive shaft, delivering high volume at low static pressure. Data center cooling arrays in Virginia, Singapore, and Frankfurt specify these for precision thermal management under hyperscale operator procurement standards.
- Centrifugal Fans:Radial blade configurations accelerate air perpendicular to intake, achieving pressure ratios critical for material handling and combustion processes. Steel mills across China's Hebei province and cement plants in India's Rajasthan deploy these for MEE-mandated dust collection retrofits.
- Blowers:Positive-displacement or regenerative designs deliver sustained pressure for pneumatic conveying and aeration systems.
- Mixed Flow Fans:Diagonal impeller geometries blend axial and centrifugal characteristics for space-constrained HVAC installations.
Centrifugal fans hold the largest share; momentum sits with axial configurations in data center specification.
End User:
Cost tier stratification separates specification authority between capital-project engineering teams and facility operations managers with competing procurement priorities.
- Manufacturing:Process ventilation demands span semiconductor cleanrooms to automotive paint booths, with uptime requirements driving premium service contracts. Automotive assembly plants in Germany's Baden-Württemberg and electronics foundries in South Korea's Gyeonggi-do anchor replacement part demand.
- HVAC:Building climate systems specify fans across commercial, institutional, and residential scales, with efficiency grades tightening under national building codes. Nordic public procurement mandates ISO 12759 compliance for healthcare and education sector awards.
- Construction:Temporary ventilation and dust control for tunneling and high-rise projects create episodic demand spikes.
- Mining:Underground ventilation and mineral processing exhaust operate in abrasive, high-moisture environments demanding corrosion-resistant alloys.
HVAC commands the largest installed base; manufacturing applications are climbing fastest on automation investment cycles.
Material:
Volume concentration in commodity steel contrasts with margin capture in corrosion-resistant specialty alloys for chemical and coastal installations.
- Steel:Carbon and stainless grades dominate bulk industrial applications where weight and cost efficiency outweigh chemical resistance requirements. Power generation facilities across the US Midwest and Poland's Silesia region specify these for combustion air and flue gas handling.
- Aluminum:Lightweight, corrosion-resistant castings suit marine environments, food processing, and weight-sensitive rooftop installations. Coastal desalination plants in Saudi Arabia's Eastern Province and Australia's Perth deploy these for salt-air durability.
- Plastic:Polymer impeller and housing assemblies serve fume exhaust and corrosive chemical handling at lower pressure ratings.
- Composite:Fiber-reinforced polymers combine strength-to-weight advantages with advanced chemical resistance for specialized process environments.
Steel holds the largest share; aluminum is expanding most quickly on coastal infrastructure and weight-reduction specifications.
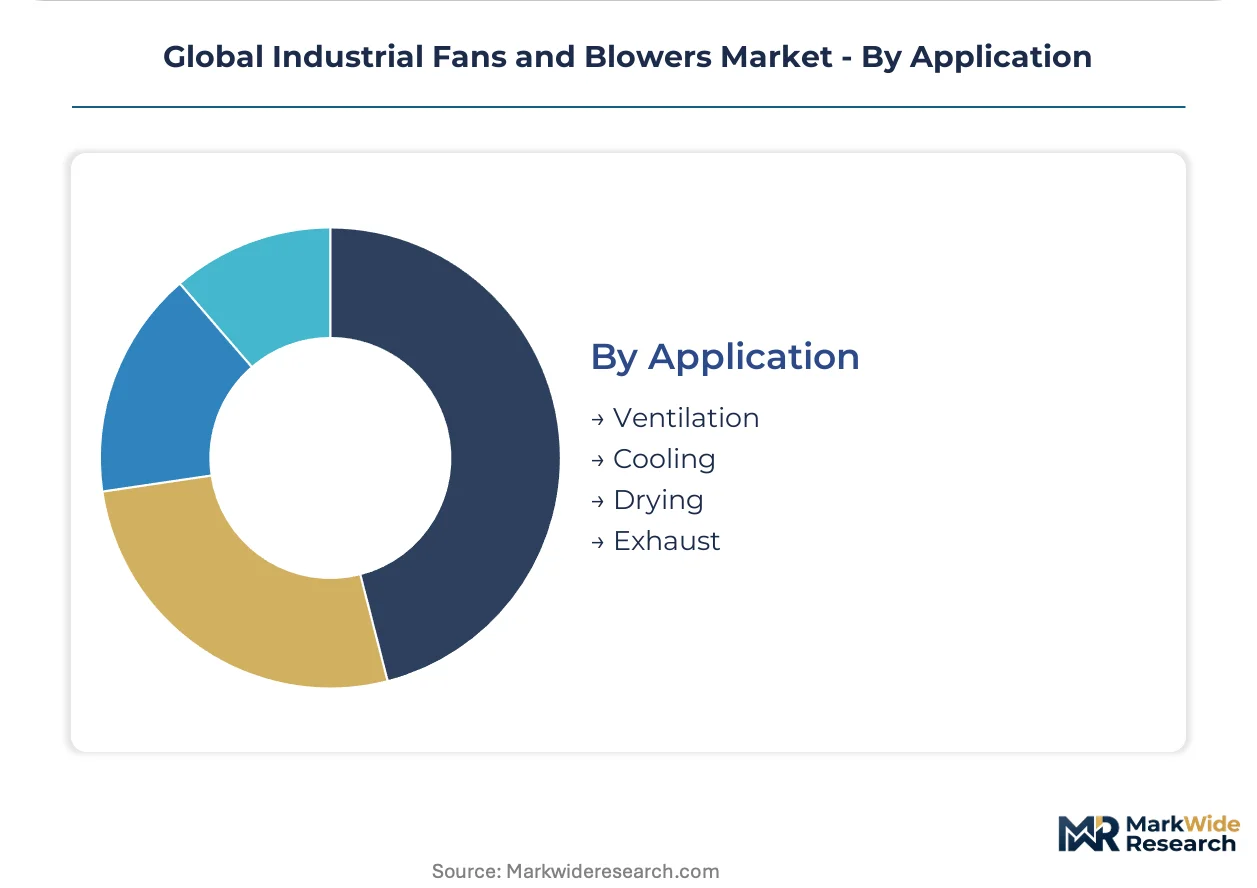
Application:
Customer type bifurcation separates original equipment manufacturers integrating fans into system packages from end-user facilities managing direct procurement.
- Ventilation:General air exchange and fresh air supply systems serve occupancy comfort and contaminant dilution across commercial and industrial buildings. School districts in Ontario, Canada and hospital networks in France's Île-de-France drive specification of EC motor efficiency grades.
- Cooling:Heat rejection and process temperature control applications span data center CRAC units to industrial chiller towers. Hyperscale facilities in Ireland's Dublin and the Netherlands' Amsterdam metro areas absorb high-efficiency centrifugal and axial arrays.
- Drying:Moisture removal processes in paper manufacturing, textile finishing, and agricultural product processing require heated air circulation.
- Exhaust:Contaminant and fume extraction systems capture particulates, vapors, and combustion byproducts at source points.
Cooling holds the largest share; ventilation is gaining share fastest on building energy code tightening across major economies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial buyers in Germany and Japan exhibit the lowest price elasticity, prioritizing efficiency grades and lifecycle cost over upfront capital expenditure. Chinese steel and cement producers show acute sensitivity to equipment pricing amid margin compression from overcapacity. Indian procurement teams balance first-cost constraints against PLI scheme localization incentives.
United States
Data center construction in Northern Virginia and Dallas-Fort Worth absorbs high-efficiency centrifugal and axial fan arrays under hyperscale operator specifications. The EPA enforces emissions standards mandating efficient ventilation in chemical processing and power generation facilities. Midwest power generation clusters across Illinois and Ohio specify carbon steel fans for combustion air handling.
China
Steel mills in Hebei province and cement plants across Shandong retrofit exhaust systems under MEE industrial emission mandates. The Ministry of Ecology and Environment implements tightening limits on particulate and NOx emissions from heavy industry. Yangtze River Delta manufacturing hubs in Jiangsu and Zhejiang drive specification of aluminum impellers for weight-sensitive automation lines.
Germany
Automotive paint booths in Baden-Württemberg and semiconductor cleanrooms in Saxony demand premium service contracts with uptime guarantees. The EU F-Gas Regulation accelerates refrigerant phase-down, elevating air-side economization projects. Food processing facilities across Bavaria retrofit rooftop ventilation to maintain cold chain compliance.
India
Steel and cement producers in Rajasthan and Gujarat upgrade dust collection infrastructure under tightening state pollution control board norms. The PLI scheme for capital goods manufacturing incentivizes blower assembly localization. Automotive component clusters in Tamil Nadu's Sriperumbudur belt specify corrosion-resistant aluminum fans for paint shop humidity control.
Netherlands
Hyperscale data centers in Amsterdam's Schiphol-Rijk corridor and Eemshaven deploy precision cooling arrays for thermal management. National building codes reference ISO 12759 fan efficiency grades as minimum thresholds for public procurement. Cold chain logistics facilities around Rotterdam retrofit high-volume low-pressure ventilation packages for F-Gas compliance.
Global Industrial Fans and Blowers Market Competitive Environment
Full-line industrial conglomerates and specialized ventilation engineering houses split the market across distinct value capture models. The vendor base concentrates around three strategic archetypes: integrated air system lifecycle managers, custom-engineered solution specialists, and scale-driven component fabricators. Consolidation pressure intensifies as aftermarket service revenue compresses original equipment margins, forcing portfolio diversification and geographic expansion as dominant competitive moves.
Within the full-line industrial tier, Atlas Copco and Ingersoll Rand occupy positions anchored by global compressor service infrastructure that cross-sells into fan maintenance contracts. Greenheck Fan Corporation exemplifies the custom-engineered specialist archetype, concentrating on critical ventilation applications where specification authority rests with energy performance consultants rather than mechanical contractors. These three entities represent divergent responses to the same structural pressure: lifecycle value capture displacing upfront equipment sales as the primary profit engine.
| Leading Market Players |
|---|
| Atlas Copco |
| Ingersoll Rand |
| Greenheck Fan Corporation |
| Howden Group |
| Systemair AB |
| Aerzen |
| Kaeser Kompressoren |
| New York Blower |
| Twin City Fan Companies |
| Others |
Value Chain & Pricing Dynamics
Jiangsu province's Yangtze River Delta manufacturing clusters anchor global capacity for high-efficiency EC motor production, concentrating pricing leverage among permanent magnet suppliers while downstream OEMs absorb margin compression through service bundling.
Pricing Analysis
Aftermarket service contracts and extended maintenance agreements drive lifetime value capture as original equipment margins compress. Pricing stratifies across premium EC motor efficiency grades, standard AC induction configurations, and economy-tier commodity blowers, with differentiation resting on ISO 12759 certification levels and predictive maintenance bundling. Cost compression in standard centrifugal tiers is intensifying because Chinese steel and cement producers prioritize first-cost minimization under MEE emission retrofit mandates. Manufacturing end-users in Germany and Japan exhibit lowest price sensitivity, while Indian procurement teams balance PLI localization incentives against capital constraints.
Supply Chain Analysis
Export controls on rare-earth processing technology and permanent magnet alloys limit flow concentration from Chinese separation facilities to global motor manufacturers. Production draws from China for rare-earth magnets and aluminum castings, Germany for precision bearings and CFD engineering talent, and India for PLI-incentivized blower assembly. Raw material dependencies center on neodymium-iron-boron magnet supply, corrosion-resistant aluminum alloys, and specialty bearing steels. Single-source vulnerability in rare-earth magnet refining creates structural risk. Distribution runs through authorized service networks for aftermarket capture and direct OEM procurement for greenfield projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates entry opportunities as specification authority migrates from mechanical contractors to energy performance consultants, fragmenting demand across efficiency grades and service intensity tiers.
For Market Incumbents: Entrench lifecycle value capture by cross-selling predictive maintenance contracts through existing compressor service infrastructure and deepening backward integration into permanent magnet motor production to offset rare-earth supply volatility. Atlas Copco and Ingersoll Rand anchor positions through integrated air system management; Greenheck defends custom engineering margins through CFD-validated impeller specialization. For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point, with Indonesia's Jakarta corridor and Vietnam's Ho Chi Minh City industrial zones absorbing ISO 12759-compliant ventilation retrofits ahead of building code tightening. Target India's PLI scheme for capital goods localization to establish blower assembly operations serving Rajasthan cement and Tamil Nadu automotive clusters. Lead with digital twin-enabled predictive maintenance as differentiated go-to-market positioning. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors aftermarket service platform consolidators over pure-play equipment fabricators. Long-term viability hinges on IoT-enabled lifecycle management capabilities and rare-earth magnet supply chain resilience. Target acquisition archetypes include EC motor specialists with ATEX certification portfolios and regional service networks with established maintenance director relationships. Monitor hyperscale data center capex cycles and EU F-Gas Regulation phase-down enforcement as inflection indicators for air-side economization demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Magnet Supply | Captive magnet sourcing insulates EC motor production from Chinese export control volatility. |
| Digital Twin Platform Deployment | CFD-IoT convergence enables predictive maintenance contracts for Virginia and Frankfurt data center operators. |
| PLI Scheme Localization in India | Tamil Nadu and Gujarat assembly operations capture steel and cement retrofit demand under state pollution mandates. |
| ATEX Certification Portfolio Expansion | Explosion-proof approvals unlock German chemical and petrochemical specification authority. |
| Air-Side Economization System Integration | F-Gas Regulation compliance drives Bavaria food processing and Netherlands cold chain retrofit demand. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, EU MRV emissions disclosures, and customs trade data for industrial equipment imports. Interviews with maintenance directors at Hebei steel mills, plant engineers at Baden-Württemberg automotive facilities, and aftermarket service heads at compressor OEMs ground quantitative estimates. Bottom-up unit economics triangulate against top-down sectoral demand modeling from MEE emission mandate implementation schedules and hyperscale data center construction pipelines.
Forecast inputs include centrifugal and axial fan shipment volumes, aluminum and steel price indices, and EC motor adoption rates across HVAC and manufacturing end-uses. Segmentation dimensions cover product type, material grade, application, and regional regulatory cluster. CAGRs derive from installed base replacement cycles and efficiency upgrade elasticity under tightening building codes. Industry-specific inputs incorporate EU F-Gas Regulation phase-down timelines and China's dual carbon goals for industrial emission intensity.
Practitioners should monitor rare-earth magnet export licensing, EU carbon border adjustment implementation, and hyperscale operator thermal design standard revisions for early signals. Forecasts reflect assumptions on MEE enforcement consistency, PLI scheme continuity, and aluminum alloy price stability. Material shifts in Sino-Western technology controls or EU refrigerant phase-down acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Electric Underfloor Heating Market
HVAC Equipment
Global HVAC Linesets Market
HVAC Equipment
Ceiling Cassettes Market
HVAC Equipment
Industrial Blowers Market
HVAC Equipment
Asia-Pacific Industrial Heat Pump Market
HVAC Equipment
HVAC Systems Market
HVAC Equipment
Global Submerged Coil Heat Exchanger Market
HVAC Equipment
Europe Dehumidifier Market
HVAC Equipment
HVAC System Analyzer Market
HVAC Equipment
HVAC Pumps Market
HVAC Equipment
Industrial Electric Boiler Market
HVAC Equipment
Warming Cabinet Market
HVAC Equipment
Air-Cooled Heat Exchangers Market
HVAC Equipment
Global Fan Coil Unit Market
HVAC Equipment
India Chillers Market
HVAC Equipment
Canada Commercial HVAC Market