
 HVAC Air Duct Market | 2026-2036
HVAC Air Duct Market Size, Share, and Industry Trends Forecast 2026-2036
HVAC Air Duct Market Analysis
Maintenance contracts and software-enabled airflow monitoring is shifting how HVAC air duct vendors capture recurring revenue. Lindab leverages its European fabrication network to sustain project margins on large commercial installations. Thermaflex anchors its position through specialized pre-insulated flexible duct systems that reduce on-site labor. Imperial Manufacturing Group competes across North America with broad sheet metal and fiberglass product lines.
HVAC air ducts are pressure-rated conduits, typically fabricated from galvanized steel, aluminum, or fiberglass composites, engineered to distribute conditioned air through buildings with minimal thermal loss or leakage. Rigid galvanized steel ducts dominate commercial and industrial specifications due to durability and fire resistance, while flexible ducts gain share in residential and retrofit applications where installation access is constrained. The material segment shows diverging margin pools: aluminum commands premium pricing in cleanroom and healthcare environments, whereas PVC faces substitution pressure in high-temperature commercial zones.
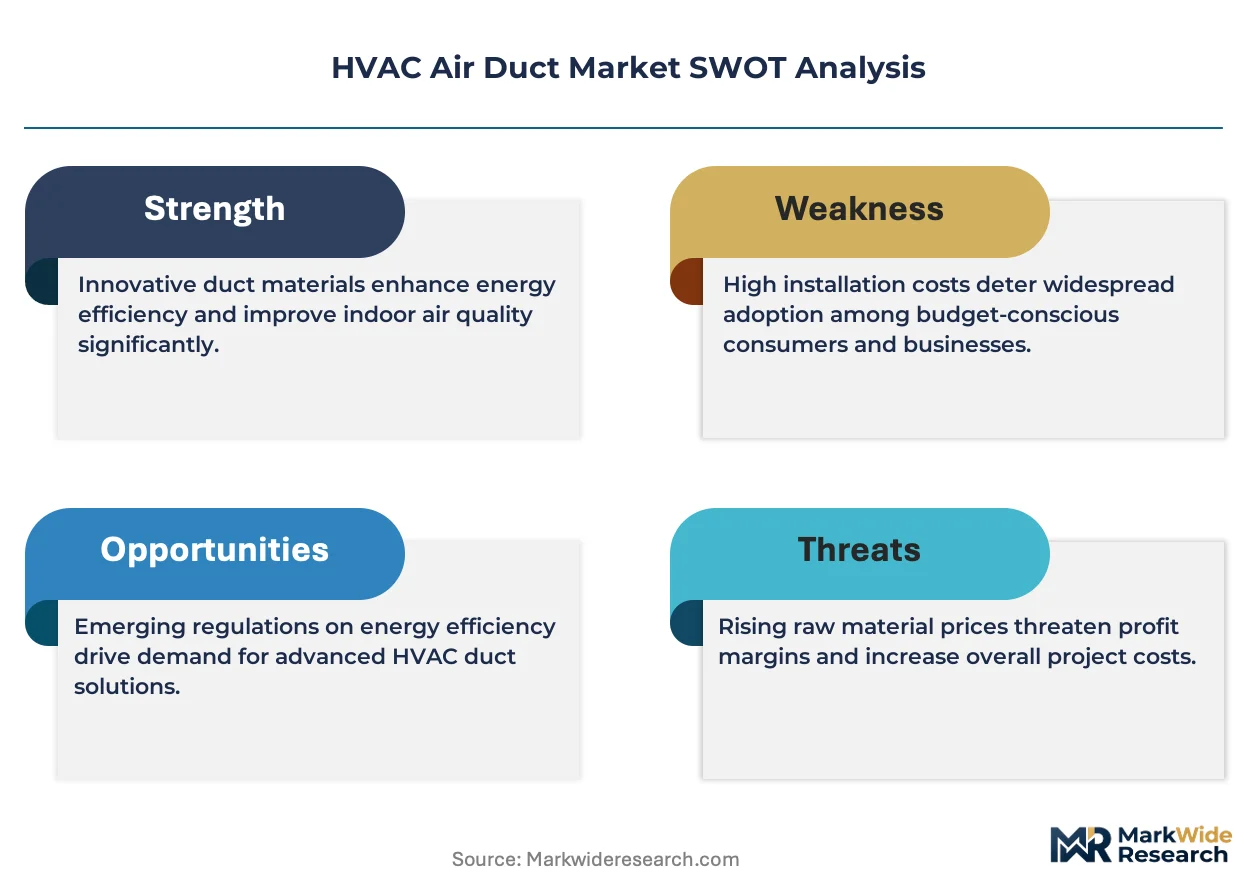
The U.S. EPA and OSHA set baseline indoor air quality and workplace exposure thresholds that directly influence duct sealing standards and material specifications. The EU Green Deal and REACH chemical compliance frameworks restrict certain insulation chemistries, redirecting R&D toward bio-based and recycled-content alternatives. Stakeholders must monitor evolving ASHRAE ventilation standards and local energy stretch codes, as these will determine which duct configurations qualify for public project bidding and green building certification programs.
Market Dynamics
Energy code tightening across major economies is forcing a wholesale upgrade cycle in commercial building infrastructure, with thermal performance specifications now dictating material selection and fabrication methods for new duct installations.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon refrigerants is accelerating investment in leak-tight duct systems that minimize climate impact and improve system efficiency in European commercial buildings.
- China's megacity buildouts:Infrastructure expansion in Chengdu, Xi'an, and Wuhan requires massive climate control distribution networks for high-rise residential and mixed-use developments.
- Pre-insulated flexible systems:Labor cost inflation in North American construction markets is driving specification of factory-insulated duct products that reduce on-site installation hours.
Market Restraints
- Galvanized steel price volatility:Input cost swings for zinc-coated sheet metal compress fabrication margins and complicate long-term project bidding for commercial contractors.
- REACH chemical restrictions:The EU's evolving framework on substance hazards limits certain insulation chemistries, forcing reformulation cycles that extend product development timelines.
- Cross-laminated timber construction:Emerging mass timber building methods in Nordic markets reduce overall HVAC load requirements and duct run complexity in mid-rise structures.
Strategic Opportunities
- Software-enabled airflow monitoring:Integration of IoT sensors with duct networks creates recurring revenue streams through predictive maintenance contracts and performance optimization services.
- German green building mandates:The federal government's efficiency standards for public buildings are expanding specification-grade demand for thermally optimized duct configurations.
- Healthcare cleanroom specifications:Aluminum duct systems with antimicrobial coatings are penetrating hospital and pharmaceutical manufacturing environments where particle control is critical.
Industry Challenges
- Sheet metal fabrication skills gap:Aging workforces in industrialized markets constrain capacity expansion for precision spiral and rectangular duct production.
- ASHRAE ventilation standard compliance:Evolving indoor air quality guidelines require continuous recertification of existing product lines, extending time-to-market for new duct configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HVAC Air Duct Market |
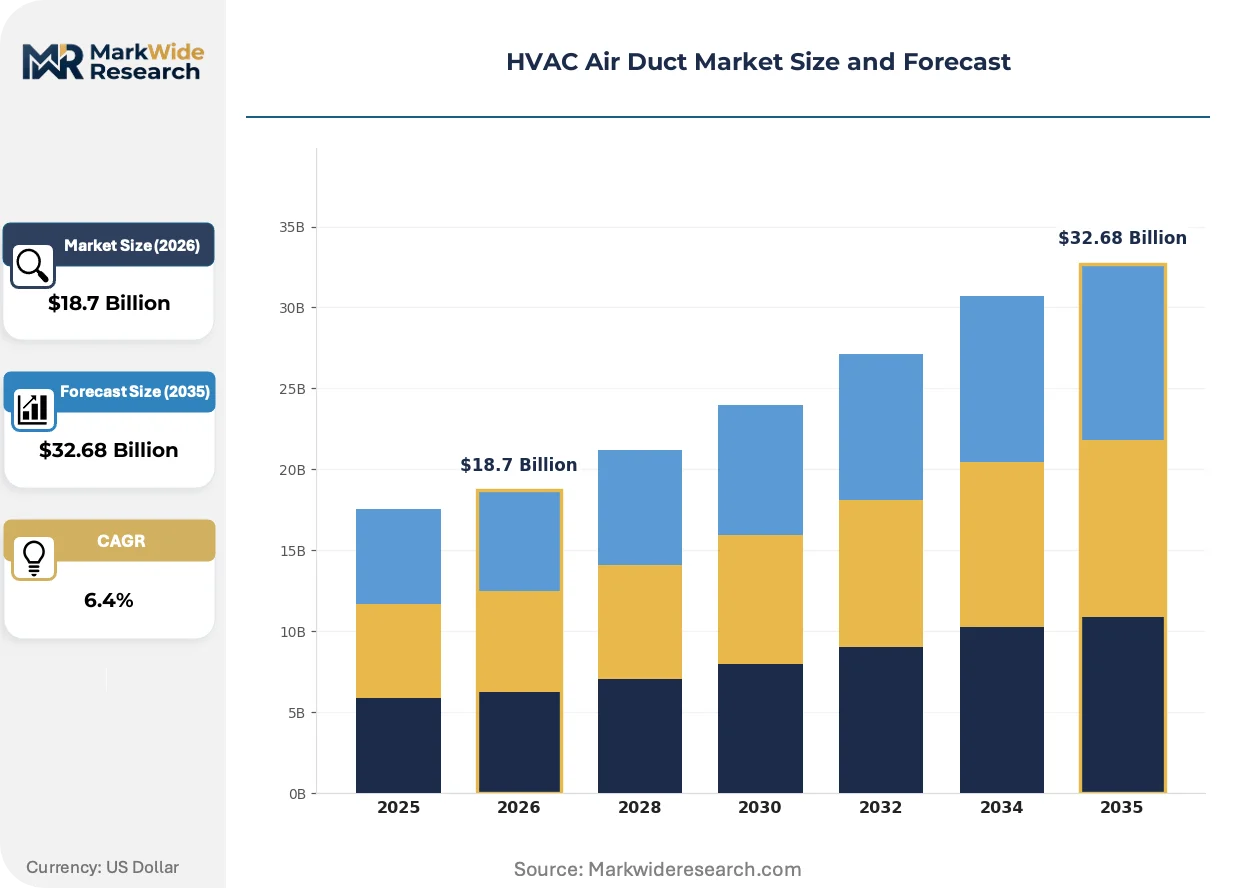
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Ducts, Rigid Ducts, Sheet Metal Ducts, Insulated Ducts Material: Aluminum, Galvanized Steel, Fiberglass, PVC Installation Type: New Construction, Renovation, Retrofit, DIY End User: Residential, Commercial, Industrial, Institutional |
| Companies Covered | Airmake Cooling Systems, ALAN Manufacturing, CMS Global, Imperial Manufacturing Group, Texas Duct Systems, DuctSox, Airtrace Sheet Metal, Thermaflex, Lindab, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HVAC Air Duct Market Emerging Trajectories
Digital fabrication and predictive analytics are converging with material science advances to reshape how duct systems are engineered, manufactured, and maintained across building lifecycles.
Antimicrobial-coated aluminum ductwork is expanding into healthcare and food processing environments where surface contamination control is paramount. Hospital facility managers in Germany and the Netherlands are specifying these systems for operating theaters and pharmaceutical cleanrooms. The technology is compressing the traditional steel-aluminum price gap in premium segments while enabling longer maintenance intervals.
REACH chemical compliance frameworks are redirecting insulation R&D toward bio-based and recycled-content alternatives across European supply chains. Manufacturers reformulating elastomeric and fiberglass insulations must now validate thermal performance under stricter emission protocols. Germany's construction sector is absorbing the first wave of certified low-chemistry duct products through public project mandates.
Building owners are unbundling after-sales service from initial equipment procurement, creating standalone contracts for airflow balancing and leakage remediation. Mechanical contractors in the United States are responding by developing captive service divisions that capture recurring revenue from previously one-off installation work. This shift is most visible in commercial office retrofits where energy benchmarking requirements expose underperforming legacy systems.
HVAC Air Duct Market Segmentation
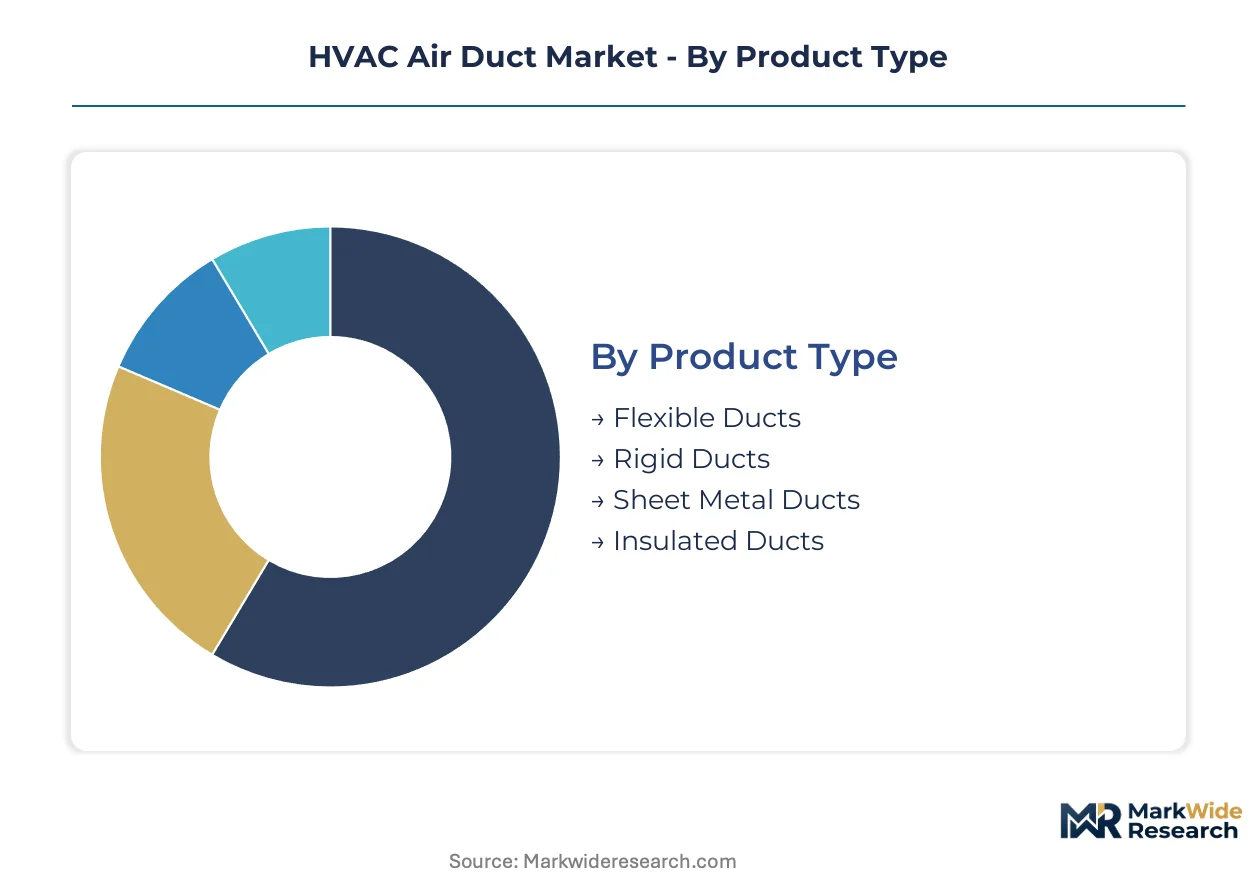
Product configuration determines whether HVAC ducts function as standalone distribution networks or integrate with building management systems. Specification depth varies sharply across installation contexts, from standardized residential retrofits to engineered commercial systems requiring thermal modeling.
Product Type:
Flexible ducts embed directly into finished cavities and tight spaces, while rigid systems anchor permanent infrastructure requiring precise airflow engineering.
- Flexible Ducts:Spiral-wire helix wrapped with polymer film and insulation blanket. Demand concentrates in North American residential retrofits where attic and crawl space access constraints favor bendable routing. Labor cost inflation drives factory-insulated specifications that compress on-site installation hours.
- Rigid Ducts:Fixed-dimension conduits fabricated from sheet metal or fiberglass composites, engineered for pressure-rated commercial distribution. German commercial real estate developers specify these for tight energy code compliance in public building mandates.
- Sheet Metal Ducts:Galvanized steel or aluminum fabricated into rectangular, spiral, or oval profiles for industrial ventilation loads.
- Insulated Ducts:Factory-laminated thermal barriers reducing condensation risk and energy loss in unconditioned spaces.
Sheet metal ducts lead volumes today; flexible ducts are gaining share fastest in residential retrofit channels.
Material:
Cost tiers separate commodity construction inputs from specification-grade alloys commanding premium positioning in controlled environments.
- Galvanized Steel:Zinc-coated carbon steel delivering fire resistance and structural durability for commercial and industrial specifications. U.S. commercial contractors face margin compression from zinc price volatility complicating long-term project bidding.
- Aluminum:Lightweight alloy with corrosion resistance and clean surface properties. Hospital facility managers in Germany and the Netherlands specify antimicrobial-coated aluminum for operating theaters and pharmaceutical cleanrooms where particle control is critical.
- Fiberglass:Reinforced polymer composite offering thermal insulation and acoustic dampening in built-up systems.
- PVC:Thermoplastic polymer facing substitution pressure in high-temperature commercial zones due to thermal deformation limits.
Galvanized steel dominates installed base; aluminum shows steepest expansion trajectory in healthcare and cleanroom applications.
Installation Type:
Customer type determines whether procurement flows through contractor networks or direct-to-consumer retail channels.
- New Construction:Engineered duct systems specified during architectural design phase. China's megacity buildouts in Chengdu, Xi'an, and Wuhan require massive climate control distribution networks integrated from foundation.
- Renovation:Partial system replacement within occupied buildings. U.S. commercial office retrofits expose underperforming legacy systems to energy benchmarking requirements.
- Retrofit:Complete duct replacement in existing structures without major architectural modification.
- DIY:Consumer-purchased components for minor repairs and extensions in residential settings.
New construction absorbs highest absolute volumes; renovation contracts are climbing fastest as building stock ages and codes tighten.
End User:
Application context dictates specification complexity, from standardized residential packages to engineered industrial systems requiring pressure balancing.
- Commercial:Office, retail, and hospitality installations governed by ASHRAE ventilation standards and local energy stretch codes. Building owners unbundle after-sales service from initial procurement, creating standalone contracts for airflow balancing.
- Residential:Single-family and multi-family climate control systems. Pre-insulated flexible products reduce on-site labor in North American construction markets facing skilled trades shortages.
- Industrial:Manufacturing and process ventilation requiring heavy-gauge fabrication and contaminant extraction.
- Institutional:Schools, hospitals, and government facilities with extended lifecycle requirements and public procurement protocols.
Commercial applications lead specification-grade revenue; residential retrofits show fastest volume growth in aging building stock markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany enforces stricter energy codes than the United States, yet China's infrastructure buildouts dwarf both markets in absolute duct volumes. National regulatory frameworks and construction cycles create divergent demand patterns across major economies.
United States
Commercial real estate developers in Texas and California are expanding specification-grade duct installations as ASHRAE ventilation standards tighten. The EPA and OSHA set baseline indoor air quality thresholds that directly influence duct sealing standards and material specifications. Dallas-Fort Worth and Houston anchor demand clusters where energy benchmarking requirements expose underperforming legacy systems in office retrofits.
Germany
The federal government's efficiency standards for public buildings are expanding specification-grade demand for thermally optimized duct configurations. The EU F-Gas Regulation and REACH chemical compliance frameworks restrict certain insulation chemistries, redirecting R&D toward bio-based alternatives. Munich and Frankfurt facility managers specify antimicrobial-coated aluminum systems for hospital operating theaters and pharmaceutical cleanrooms.
China
Megacity infrastructure buildouts in Chengdu, Xi'an, and Wuhan require massive climate control distribution networks for high-rise residential and mixed-use developments. The country's dual carbon goals and GB standards for building energy efficiency shape procurement protocols for new construction. Yangtze River Delta contractors integrate engineered duct systems from foundation phase in government-backed smart city projects.
Netherlands
Hospital facility managers in Amsterdam and Rotterdam specify aluminum ductwork with antimicrobial coatings for healthcare environments where particle control is critical. The EU Green Deal and evolving REACH frameworks accelerate validation of low-chemistry insulation products through public project mandates. Eindhoven's construction sector absorbs early volumes of certified bio-based duct insulations.
India
Commercial building stock expansion in Mumbai and Delhi-NCR drives demand for galvanized steel and aluminum duct systems in IT parks and retail complexes. The Bureau of Indian Standards and state-level energy conservation building codes establish baseline thermal performance requirements. Gujarat and Maharashtra fabrication clusters supply precision spiral and rectangular ducts for industrial ventilation loads.
HVAC Air Duct Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with specification-grade commercial projects favoring established fabricators while residential retrofits tolerate broader sourcing. The vendor base organizes into three tiers: multinational systems suppliers with European fabrication networks, regional sheet metal specialists serving contractor channels, and flexible duct manufacturers optimizing for labor-cost-sensitive installation markets. Two dominant competitive moves are reshaping positioning: backward integration into zinc-coated sheet metal supply to buffer raw material volatility, and captive service divisions capturing recurring revenue from airflow balancing contracts.
Among European-based fabricators, Lindab and Thermaflex exemplify divergent specialization strategies within the same regulatory environment. Lindab occupies a position as a multinational systems supplier leveraging continental fabrication networks for large commercial installations. Thermaflex anchors the flexible duct tier through factory-insulated product configurations that address North American labor cost inflation. Texas Duct Systems represents regional scale specialists competing across sheet metal and fiberglass product lines in contractor-driven procurement channels.
| Leading Market Players |
|---|
| Airmake Cooling Systems |
| ALAN Manufacturing |
| CMS Global |
| Imperial Manufacturing Group |
| Texas Duct Systems |
| DuctSox |
| Airtrace Sheet Metal |
| Thermaflex |
| Lindab |
| Others |
Supply Flow & Price Mechanics
EU F-Gas Regulation compliance gates both qualified supply access and premium-tier pricing power, as leak-tight duct configurations certified under the phasedown framework command material premiums over commodity alternatives. German public procurement mandates for thermally optimized systems concentrate demand among fabricators with validated bio-based insulation formulations, compressing margins for non-compliant competitors.
Pricing Analysis
Capacity additions in China's Yangtze River Delta fabrication clusters are reshaping price floors for galvanized steel spiral duct systems. Three-tier pricing structure across specification-grade, commercial-standard, and economy-level products separates project-based contract values by certification tier and thermal performance rating. Price differentiation centers on ASHRAE compliance validation and factory-insulated configurations that reduce on-site labor hours. Cost compression in economy-tier sheet metal runs through zinc price volatility and aggressive bidding from regional contractor-direct suppliers.
Supply Chain Analysis
Regional distribution centers in Germany, the Netherlands, and Texas anchor hub-and-spoke patterns for specification-grade commercial deliveries. Raw material flows draw from Chinese zinc-coated steel production, Indian aluminum smelting, and European bio-based insulation polymer development. Single-source vulnerability concentrates in antimicrobial coating chemistries subject to REACH reformulation cycles. Distribution runs through mechanical contractor networks and direct-to-fabricator procurement for large commercial installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation operates as a regulatory compounder, with each phasedown milestone expanding specification-grade demand for leak-tight, thermally efficient duct configurations in European commercial buildings.
For Market Incumbents: Anchor position through backward integration into zinc-coated sheet metal supply and captive service divisions capturing recurring airflow balancing contracts. Defend against emerging pre-insulated flexible specialists by accelerating antimicrobial-coated aluminum certification for healthcare cleanroom specifications. Prioritize R&D investment in bio-based insulation formulations that satisfy evolving REACH emission protocols. For New Entrants and Emerging Players: Mechanical contractor networks in Texas and California represent the most penetrable channel for specification-grade sheet metal penetration. Target U.S. commercial office retrofit segments where energy benchmarking requirements expose underperforming legacy systems. Lead with factory-insulated flexible configurations that compress installation hours in labor-constrained construction markets. For Investors and Strategic Acquirers: Roll-up economics work for regional sheet metal specialists with established contractor relationships because ASHRAE ventilation standard compliance creates certification barriers that fragment competitive positioning. Long-term viability across the analysis window rests on acquiring fabricators with validated thermal modeling capabilities and public project bidding credentials. Watch German federal efficiency standard enforcement as the inflection signal for specification-grade demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Zinc-Coated Steel Supply | Buffers margin compression from London Metal Exchange zinc price volatility for commercial contractors. |
| Antimicrobial Aluminum Certification Investment | Unlocks hospital operating theater specifications in Munich and Amsterdam healthcare construction markets. |
| Captive Service Division Development | Captures recurring revenue from airflow balancing contracts unbundled from initial equipment procurement. |
| Bio-Based Insulation R&D Partnership | Positions products for German public building mandates restricting traditional elastomeric chemistries. |
| Software-Enabled Airflow Monitoring Integration | Creates predictive maintenance subscription revenue from IoT sensor networks in commercial installations. |
Methodological Framework
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with commercial real estate developers, mechanical contractors, hospital facility managers, and sheet metal fabrication plant managers were validated against customs trade records, ASHRAE standard documentation, EU ECHA regulatory filings, and SEC 10-K disclosures from publicly traded building products manufacturers. Triangulation across stakeholder input and secondary data sources ensures segmentation integrity.
Input-output matrices map raw material flows through fabrication stages to end-use installation channels across the projection horizon. Segmentation dimensions modeled include product type, material grade, installation context, and end-user application, with regional regulatory clusters treated as cross-cutting variables. CAGRs were derived from installation volume trajectories and average selling price movements informed by contractor bidding data and public procurement records. Forecast inputs incorporate energy code adoption timelines and REACH chemical restriction phase-in schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to galvanized steel price volatility, ASHRAE standard revision timing, and EU F-Gas Regulation enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
HVAC Airflow and Blend Door Actuator Systems Market
HVAC Equipment
Compressor Market
HVAC Equipment
Chilled Beams Market
HVAC Equipment
United States HVAC Equipment and Services Market
HVAC Equipment
Centrifugal Chillers Market
HVAC Equipment
Fabric Air Ducts Market
HVAC Equipment
US Heating Equipment Market
HVAC Equipment
US HVAC Services Market
HVAC Equipment
Kitchen Hood Market
HVAC Equipment
Global Air-To-Air Heat Pumps Market
HVAC Equipment
Compressor Controllers Market
HVAC Equipment
United States HVAC Equipment Market
HVAC Equipment
Global Radiant Floor Heating Market
HVAC Equipment
Steam Operated Condensate Pump Market
HVAC Equipment
HVAC Louvers Market
HVAC Equipment
Europe Dehumidifier Market