
 South Europe Renewable Energy Market | 2026-2036
South Europe Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
South Europe Renewable Energy Market Analytics
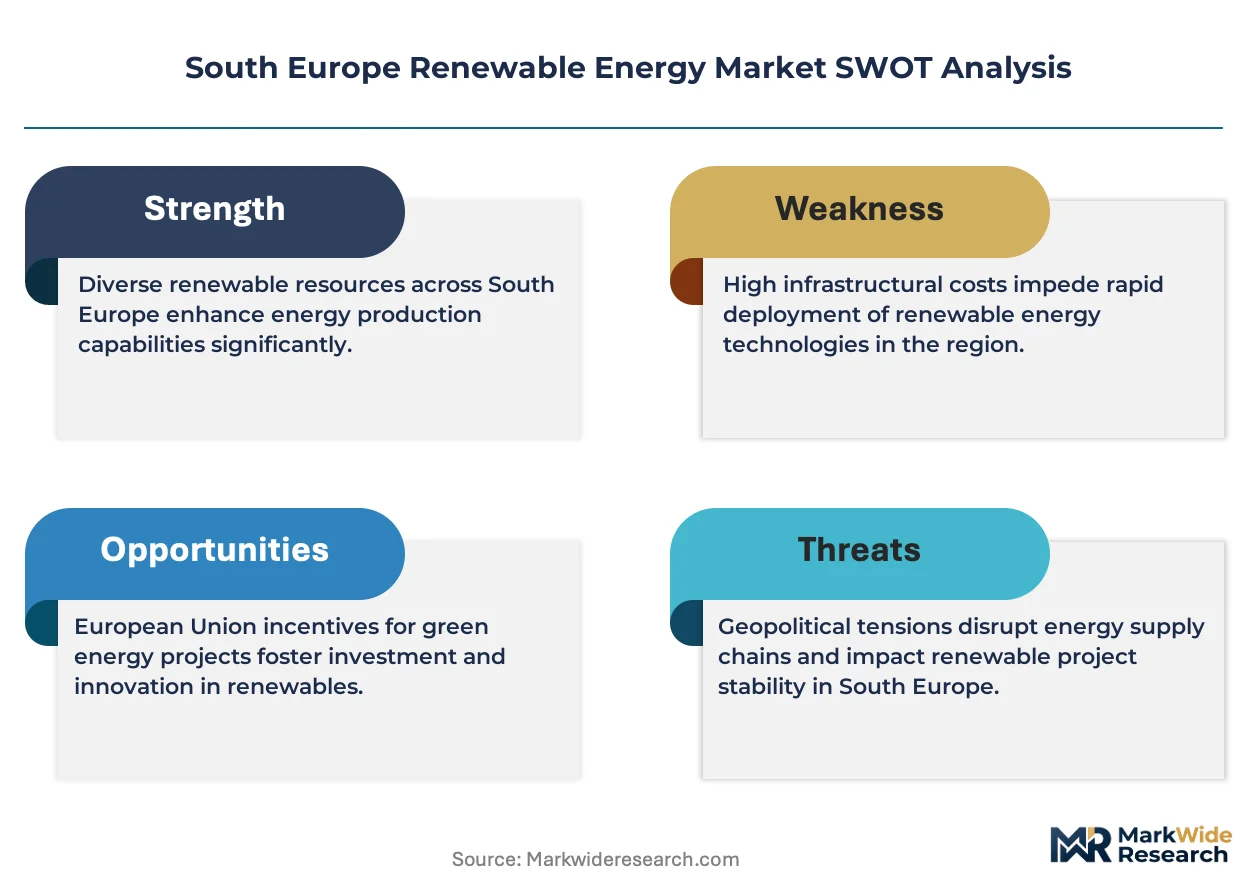
Utility-scale solar developers across Spain and Portugal is expanding manufacturing partnerships to secure polysilicon supply for projected capacity ramps. Enel Green Power leverages its Sicilian project pipeline to anchor Italian market presence across photovoltaic and onshore wind installations. Iberdrola sustains technology leadership through dedicated offshore wind development in the Bay of Biscay. Acciona differentiates via integrated engineering-procurement-construction capabilities that control project delivery timelines across the Mediterranean basin.
South Europe renewable energy encompasses power generation systems that convert solar irradiance, wind kinetic energy, biomass organic matter, or hydropower gravitational force into grid-ready electricity through photovoltaic cells, turbine generators, or thermal conversion processes operating at voltages from low-distribution to high-transmission levels. Solar photovoltaics dominates current capacity additions due to declining module costs and favorable irradiance profiles across Andalusia, Alentejo, and Sicily. Onshore wind maintains structural importance in northern Spain and southern France where topography channels consistent air masses. Offshore wind represents the fastest-expanding technology segment as floating foundation designs unlock deeper-water sites in the Mediterranean and Atlantic approaches.
Spain's National Integrated Energy and Climate Plan operates alongside Portugal's National Energy and Climate Plan and Italy's National Recovery and Resilience Plan to mandate renewable capacity auctions, streamline permitting timelines, and condition grid access on storage co-location requirements. The EU Green Deal and REPowerEU framework impose binding renewable targets that national regulators transpose into feed-in tariff adjustments and power purchase agreement standardization. Stakeholders must monitor auction design evolution and cross-border interconnector commissioning schedules to time capital allocation across the Iberian-Italian corridor.
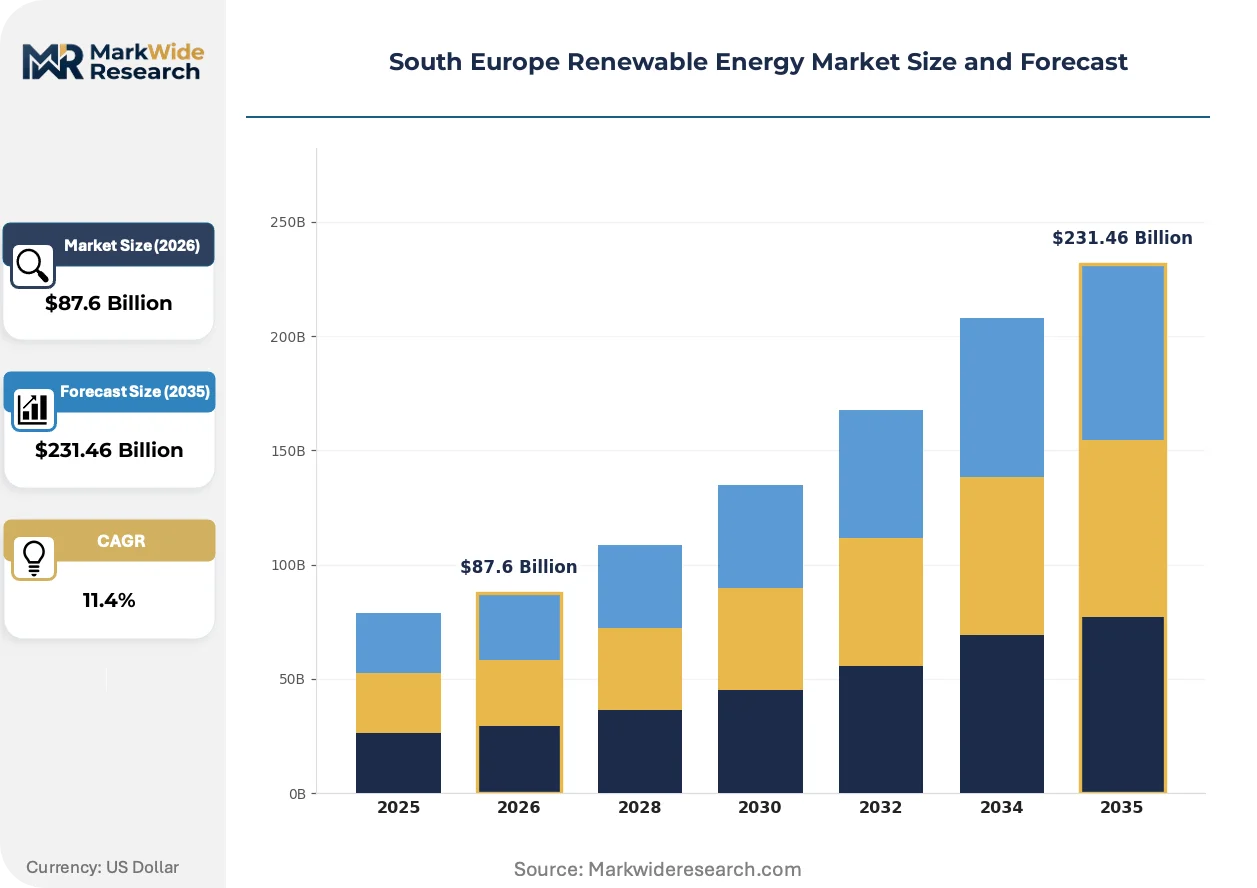
Market Dynamics
Spain's binding renewable capacity auctions under the National Integrated Energy and Climate Plan are compressing developer margins while accelerating deployment timelines across the Iberian Peninsula. This auction-driven procurement model is forcing capital reallocation toward storage-co-located projects and grid-enhancement investments.
Growth Catalysts
- EU Green Deal mandates:Binding renewable targets transposed into national auction schedules are pulling forward utility-scale solar and offshore wind investments across Italy, Spain, and Portugal.
- Industrial self-consumption clusters:Italian manufacturing complexes are procuring captive solar capacity to hedge against wholesale electricity price volatility and secure operational cost predictability.
- Floating foundation advances:Deeper-water Atlantic and Mediterranean sites previously inaccessible to fixed-bottom turbines are now viable through semi-submersible platform designs.
Market Restraints
- Polysilicon supply concentration:European module assemblers remain dependent on Asian polysilicon refiners, exposing project pipelines to input cost volatility and logistics bottlenecks.
- Grid interconnection queues:Transmission reinforcement timelines in southern Spain and rural Portugal lag behind generation capacity additions, creating curtailment risk for completed assets.
- Permitting fragmentation:Regional environmental impact assessments across Italian regions and Spanish autonomous communities impose inconsistent procedural delays without harmonized standards.
Strategic Opportunities
- Portuguese floating solar:Reservoir-based photovoltaic installations on Alqueva and other dam complexes offer land-constrained capacity expansion with minimal grid upgrade requirements.
- Green hydrogen offtake:Electrolyzer deployments tied to industrial ports in Tarragona, Augusta, and Sines are creating anchor demand for curtailed renewable generation.
- Cross-border PPAs:Corporate buyers are structuring multi-country power purchase agreements spanning Spain-Portugal interconnection capacity to diversify supply risk.
Industry Challenges
- Specialized vessel shortages:Heavy-lift jack-up units capable of installing floating offshore foundations in Atlantic swell conditions face multi-year charter backlogs.
- Grid-code compliance timelines:Spanish and Portuguese transmission system operators are revising connection requirements for inverter-based resources faster than certification bodies can validate equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Europe Renewable Energy Market |
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $231.46 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Energy Source: Solar, Wind, Biomass, Hydropower Technology: Photovoltaics, Onshore Wind, Offshore Wind, Bioenergy End User: Residential, Commercial, Industrial, Government Deployment Model: Grid-connected, Off-grid, Hybrid, Distributed |
| Companies Covered | Enel Green Power, Iberdrola, Acciona, EDP Renewables, Endesa, Ørsted, RWE, Vattenfall, Vestas Wind Systems, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Europe Renewable Energy Market Evolving Landscape
Bifacial photovoltaic modules paired with tracking systems are reshaping project economics across Andalusia and Alentejo. This hardware evolution is compressing levelized cost thresholds while demanding new engineering competencies from EPC contractors.
Agrivoltaic installations is converging with agricultural land-use planning across Sicilian olive groves and Extremaduran pasturelands. Farmers are leasing elevated solar canopy structures that permit continued cultivation beneath panels. This dual-use model is unlocking previously restricted land access for developers while generating supplemental revenue streams for agricultural operators.
Portugal's National Energy and Climate Plan now mandates storage co-location for utility-scale auction winners, forcing battery integrators to front-of-meter project designs. This requirement is accelerating lithium-ion and emerging flow battery deployments alongside solar and wind assets. Developers are responding by restructuring EPC contracts to unified generation-plus-storage delivery timelines.
Corporate buyers are consolidating renewable energy procurement through multi-technology portfolio tenders rather than single-asset power purchase agreements. Large industrial consumers in Catalonia and Lombardy are bundling solar, wind, and storage volumes to match baseload consumption profiles. This aggregation behavior is compressing developer sales cycles while raising creditworthiness thresholds for counterparties.
South Europe Renewable Energy Market Segmentation
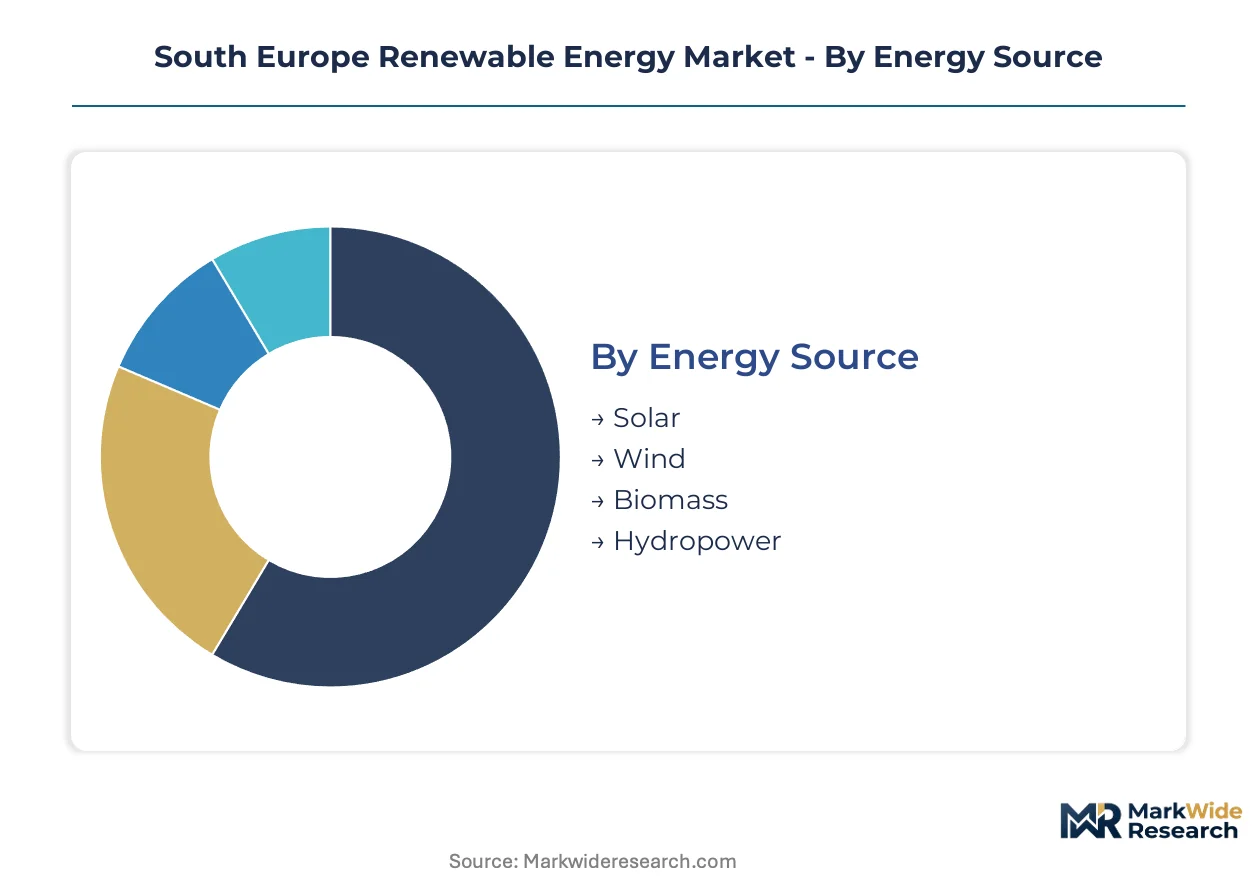
Technology differentiation and deployment configuration determine capital allocation patterns across the Iberian-Italian corridor. Segment boundaries shift as storage co-location mandates and floating foundation advances reshape project economics.
Energy Source:
Technology specifications define resource conversion efficiency and grid integration requirements.
- Solar:Photovoltaic cells convert irradiance into direct current at 15-22% conversion efficiency depending on silicon grade. Spanish and Portuguese developers concentrate procurement in Andalusia and Alentejo where annual irradiance exceeds 1,800 kWh/m². Module cost declines below $0.30 per watt are compressing levelized cost thresholds faster than competing sources.
- Wind:Kinetic energy capture through horizontal-axis turbines scales from 2 MW onshore units to 15 MW offshore platforms. Northern Spain's topography channels consistent Atlantic air masses through Galicia and Asturias, anchoring capacity clusters where mean wind speeds exceed 7 m/s at hub height.
- Biomass:Organic matter combustion and anaerobic digestion systems convert agricultural residues into dispatchable baseload power. Italian biogas facilities cluster in Lombardy and Emilia-Romagna near livestock operations.
- Hydropower:Gravitational force drives turbine generators at run-of-river and pumped-storage installations. Portugal's dam complexes on the Tagus and Douro provide flexible peaking capacity.
Solar leads on scale; offshore wind leads on momentum.
Technology:
Hardware specifications determine project development timelines and EPC contract structures.
- Photovoltaics:Crystalline silicon modules dominate utility-scale deployment, with bifacial designs capturing reflected irradiance from ground surfaces. Tracking systems in Extremadura boost yield 20-25% over fixed-tilt configurations.
- Onshore Wind:Turbine hub heights reaching 150 meters access steadier wind regimes. Spanish permitting reforms under the National Integrated Energy and Climate Plan are compressing authorization timelines for repowering aging fleets.
- Offshore Wind:Floating semi-submersible platforms unlock Mediterranean depths beyond 60 meters. Italian auctions in the Ionian and Tyrrhenian Seas are attracting consortia with heavy-lift vessel access.
- Bioenergy:Combined heat and power systems and biomethane upgrading units serve industrial thermal demand. Portuguese sugar beet processing facilities anchor regional supply chains.
Photovoltaics commands installed capacity; floating offshore platforms are climbing the fastest.
End User:
Customer scale and creditworthiness shape offtake contract structures and financing terms.
- Industrial:Manufacturing complexes in Catalonia and Lombardy procure captive solar capacity through 10-15 year power purchase agreements. Energy cost predictability drives procurement decisions more than sustainability credentials alone.
- Commercial:Retail chains and logistics operators deploy rooftop systems across Spanish and Portuguese distribution centers. Self-consumption ratios above 70% justify capital deployment despite constrained roof areas.
- Residential:Distributed rooftop installations benefit from net metering regimes in Italy and simplified permitting in Portugal. Battery co-location rates are rising as time-of-use tariffs widen peak-off-peak spreads.
- Government:Public buildings and municipal utilities anchor procurement through auction-backed contracts. EU Recovery and Resilience Plan funding accelerates deployment timelines for state-owned assets.
Industrial offtake leads on contract value; residential deployment is expanding most quickly.
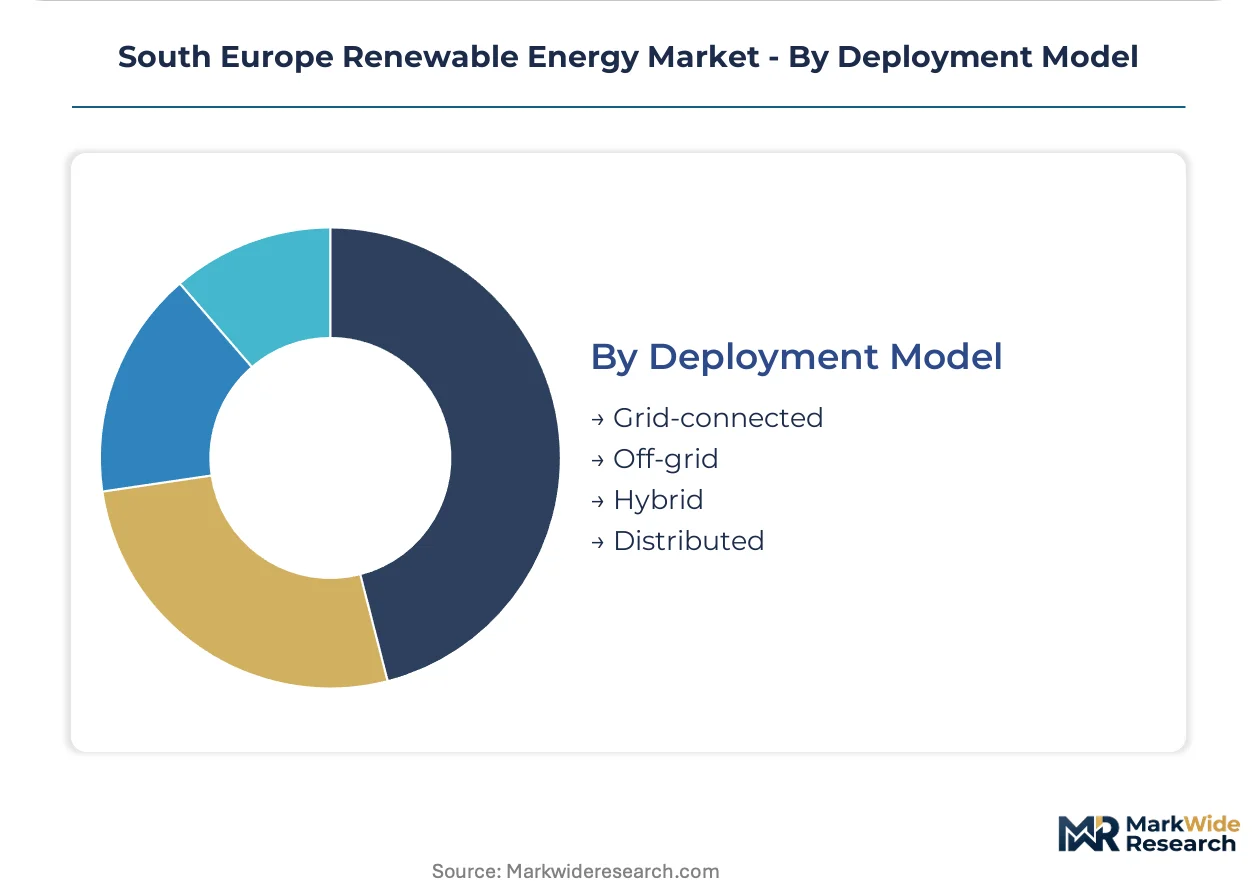
Deployment Model:
Grid interface configuration determines regulatory compliance burdens and revenue stacking opportunities.
- Grid-connected:Utility-scale assets inject power at transmission voltages through standardized interconnection protocols. Spanish grid-code revisions for inverter-based resources are forcing equipment recertification cycles.
- Hybrid:Co-located solar-plus-storage or wind-plus-hydrogen systems optimize capacity factor and capture price arbitrage. Portuguese auction mandates now require storage pairing for new renewable capacity.
- Distributed:Behind-the-meter generation serves localized demand without transmission access. Italian agrivoltaic installations on Sicilian olive groves exemplify dual-use land configurations.
- Off-grid:Island and remote industrial sites deploy diesel displacement systems. Mining operations in rural Spain and Portugal anchor demand for robust hybrid microgrids.
Grid-connected assets lead on installed capacity; hybrid configurations are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain deploys utility-scale solar faster than Italy builds offshore wind, yet both countries anchor the Mediterranean corridor's capacity expansion. Portugal captures floating foundation advances while Greece unlocks Aegean sites. National climate plans across these markets compress permitting timelines and mandate storage co-location.
Spain
Andalusian solar parks and Extremaduran wind clusters drive Iberian capacity additions. The National Integrated Energy and Climate Plan binds developers to auction schedules with storage pairing requirements. Tarragona's industrial port anchors green hydrogen electrolyzer deployments that absorb curtailed renewable generation.
Italy
Sicilian photovoltaic installations and Ionian offshore wind leases attract concentrated developer interest. The National Recovery and Resilience Plan channels EU funding toward auction-backed renewable procurement. Lombard manufacturing complexes in Brescia and Bergamo procure captive solar capacity through long-term power purchase agreements.
Portugal
Alentejo's irradiance profile and Alqueva reservoir floating solar anchor land-constrained expansion. The National Energy and Climate Plan mandates battery co-location for utility-scale auction winners. Sines industrial port hosts electrolyzer deployments tied to Atlantic offshore wind offtake.
Greece
Cycladic island interconnections and Crete's wind corridors drive Aegean renewable deployment. EU Green Deal targets transposed into national auction schedules accelerate utility-scale solar procurement. Piraeus port clusters anchor corporate power purchase agreements spanning solar and offshore wind volumes.
South Europe Renewable Energy Market Competitive Landscape
Iberian producers anchor one tier; Italian and Nordic specialists hold differentiated positions in Mediterranean offshore development. The market structure concentrates around integrated utilities with captive project pipelines and independent power producers bidding auction slots. Three archetypes dominate: state-linked energy majors controlling transmission access, engineering-procurement-construction integrators compressing delivery timelines, and offshore wind pure-plays securing floating foundation patents. Competitive intensity manifests through auction pre-qualification alliances and cross-border power purchase agreement origination.
Within the integrated utility tier, Enel Green Power and Iberdrola exemplify geographic anchoring strategies that lock in pipeline visibility. EDP Renewables occupies a position bridging Iberian auction markets with floating technology exposure. These three entities represent distinct capital allocation postures: Italian pipeline depth, Spanish offshore leadership, and Portuguese hybrid project origination.
| Leading Market Players |
|---|
| Enel Green Power |
| Iberdrola |
| Acciona |
| EDP Renewables |
| Endesa |
| Ørsted |
| RWE |
| Vattenfall |
| Vestas Wind Systems |
| Others |
Value Network & Pricing Analysis
Specialized offshore wind vessel crews concentrated in northern Spain and southern France command wage premiums that widen spreads between premium and standard EPC contract tiers. This labor-cost differential compounds with polysilicon input volatility to stratify pricing across integrated and non-integrated developer archetypes.
Pricing Analysis
Capacity additions in Andalusia and Alentejo are reshaping price floors for utility-scale solar EPC contracts across the Iberian Peninsula. Three-tier pricing structure across premium, standard, and economy levels reflects bifacial module grades and storage co-location depth. Cost compression in the economy tier is intensifying because Portuguese auction winners face mandated battery pairing requirements. Industrial offtakers in Lombardy exhibit lowest price sensitivity due to captive consumption economics, while commercial rooftop buyers in Portuguese retail chains show highest sensitivity to module cost swings.
Supply Chain Analysis
Direct-to-utility channels handle hyperscale auction demand from Spanish and Portuguese transmission operators. Polysilicon refining concentrates in China, Malaysia, and Germany, while turbine nacelle assembly feeds from Denmark, Spain, and India. European module assemblers draw from Asian wafer suppliers, exposing project pipelines to logistics chokepoint risk at Mediterranean port terminals. Distribution runs through EPC integrators with captive installation fleets rather than merchant wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South Europe renewable energy market operates as a regulatory compounder where EU Green Deal targets transposed into national auction schedules continuously pull forward capital deployment timelines.
For Market Incumbents: Lock in floating foundation engineering capabilities before specialized vessel shortages harden into multi-year bottlenecks. Secure backward integration into polysilicon supply through offtake agreements with Southeast Asian refiners to defend margins against input cost volatility. Iberdrola and Enel Green Power anchor positions through early-mover port access at Tarragona and Augusta. For New Entrants and Emerging Players: Begin with Portuguese floating solar reservoir installations where land constraints and minimal grid upgrade requirements lower competitive barriers. Target agrivoltaic dual-use configurations across Sicilian olive groves and Extremaduran pasturelands as the most penetrable deployment model. Originate corporate PPA structures bundling solar, wind, and storage volumes to match baseload profiles of Lombard manufacturing complexes. For Investors and Strategic Acquirers: Integrated utilities with captive pipeline visibility are the most active acquirer in this space, consolidating EPC capabilities and offshore wind lease positions. Long-term viability centers on developers with demonstrated grid-code compliance and storage integration expertise. Watch Italian Ionian Sea auction participation rates as the inflection indicator for floating platform technology maturation.| Strategic Initiative | Industry Significance |
|---|---|
| Storage Co-location Mandate Compliance | Portuguese auction winners must pair battery assets, accelerating lithium-ion and flow battery deployments. |
| Floating Foundation Patent Licensing | Semi-submersible platform designs unlock Mediterranean depths beyond 60 meters for Italian offshore wind. |
| Agrivoltaic Land-Use Partnerships | Sicilian olive growers lease elevated solar canopies, unlocking restricted land access for developers. |
| Cross-Border PPA Structuring | Corporate buyers span Spain-Portugal interconnection capacity to diversify supply risk through multi-country contracts. |
| Green Hydrogen Electrolyzer Deployment | Tarragona, Augusta, and Sines industrial ports anchor demand for curtailed renewable generation offtake. |
Research Methodology
Coverage spans the Iberian Peninsula, Italy, and Greece, with primary inputs from each national market. The research combines structured interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators with secondary validation against IEA reports, EIA data, and FERC filings. Bottom-up project pipeline tracking triangulates with top-down national climate plan targets to ensure consistency across modeling approaches.
Segmentation was modeled at technology, deployment configuration, and end-user granularity throughout the forecast period. Fuel source splits, generation capacity tiers, and regulatory framework clusters anchor the analytical framework. CAGRs were derived from capacity addition schedules and auction award trajectories. Forecast inputs include grid interconnector commissioning timelines and storage cost decline curves.
Several conditions sit outside the modeled scope, including unannounced regulatory revisions, force majeure disruptions to polysilicon supply, and technology breakthroughs in perovskite cell efficiency. Forecasts reflect assumptions about auction design stability and transmission reinforcement pacing. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Asia-Pacific Renewable Energy Market
Renewable Energy
Algeria Renewable Energy Market
Renewable Energy
North America Ocean Power Market
Renewable Energy
West Africa Renewable Energy Market
Renewable Energy
Poland Renewable Energy Market
Renewable Energy
Europe Power to Gas Market
Renewable Energy
Philippines Wind Energy Market
Renewable Energy
China Wind Power Market
Renewable Energy
Africa Solar E-Bike Market
Renewable Energy
Singapore Renewable Energy Market
Renewable Energy
North America Renewable Energy Market
Renewable Energy
Philippines Power Market
Renewable Energy
Egypt Renewable Energy Market
Renewable Energy
Renewable Energy Policy Fit Analysis Market
Renewable Energy
New Zealand Renewable Energy Market
Renewable Energy
Blockchain in Renewable Energy Market