
 Europe IoT in Renewable Energy Market | 2026-2036
Europe IoT in Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Europe IoT in Renewable Energy Market Intelligence
The EU Green Deal is realigning procurement criteria for grid-connected renewable assets across member states. Siemens leverages its digital twin portfolio to dominate turbine-to-grid data orchestration. Schneider Electric anchors its European position through edge computing hardware purpose-built for solar inverters and battery management systems.
IoT in renewable energy denotes networked sensor, actuator, and analytics infrastructure that monitors generation assets, optimizes energy flows, and automates grid responses through protocols such as IEC 61850 and MQTT-based telemetry. Smart meter deployments across European distribution networks represent a mature revenue pool with replacement cycles now driving service contracts, while edge computing for sub-second turbine pitch control commands premium pricing due to latency requirements. Predictive maintenance applications are expanding fastest as asset owners shift from scheduled to condition-based servicing of offshore wind gearboxes and photovoltaic string inverters.
EU AI Act risk classifications and REACH material compliance for sensor hardware are tightening product qualification pathways for vendors serving European utilities. ECHA substance restrictions on battery sensor coatings intersect with CE marking obligations under the Machinery Directive, creating compound certification burdens. Stakeholders must track how the F-Gas Regulation phase-down reshapes cooling requirements for edge data centers co-located with solar farms.
Market Dynamics
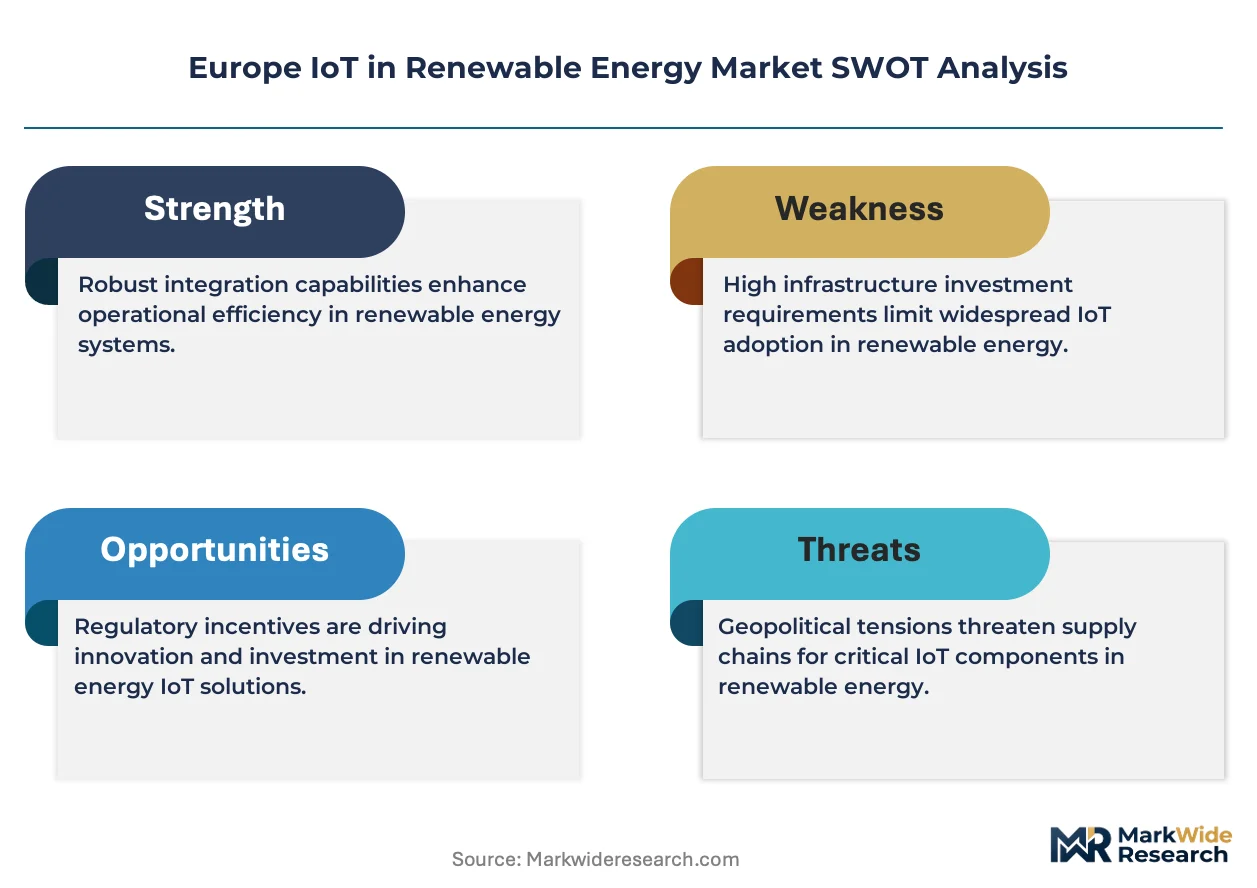
EU Green Deal grid modernization mandates are forcing utility-scale solar and offshore wind operators to replace legacy SCADA with IEC 61850-compliant sensor networks, compressing procurement cycles and concentrating vendor selection around cybersecurity certification.
Growth Catalysts
- EU AI Act risk classification:High-risk AI system requirements for predictive maintenance algorithms are accelerating vendor investment in explainable telemetry models for turbine gearbox monitoring.
- Offshore wind expansion:Denmark's North Sea corridor operators are deploying edge computing nodes for sub-second pitch control, creating concentrated demand for low-latency sensor hardware.
- F-Gas Regulation phase-down:Cooling system retrofits for solar farm edge data centers are driving replacement cycles in thermal management sensors across Spain and Italy.
Market Restraints
- REACH substance restrictions:ECHA limitations on battery sensor coatings compound CE marking obligations, extending product qualification timelines by eight to fourteen months.
- Semiconductor supply concentration:Edge computing chip fabrication concentrates in East Asian foundries, exposing European inverter manufacturers to geopolitical supply interruptions.
- Interoperability fragmentation:Proprietary OEM protocols lock turbine telemetry data, preventing cross-fleet analytics standardization.
Strategic Opportunities
- Poland utility-scale solar:Grid connection backlogs are creating demand for IoT-enabled curtailment forecasting to optimize dispatch timing.
- Digital twin convergence:Physics-based simulation merged with real-time SCADA streams enables predictive degradation modeling for photovoltaic string inverters.
- CSRD disclosure mandates:Scope emissions reporting requirements for asset owners are opening service contracts for automated carbon accounting middleware.
Industry Challenges
- Cybersecurity skill scarcity:IEC 62443 certification for industrial IoT networks exceeds available European systems integrator capacity, delaying deployment schedules.
- Legacy asset integration:Pre-2015 wind turbines lack native Ethernet connectivity, requiring costly retrofit gateways for MQTT-based telemetry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe IoT in Renewable Energy Market |
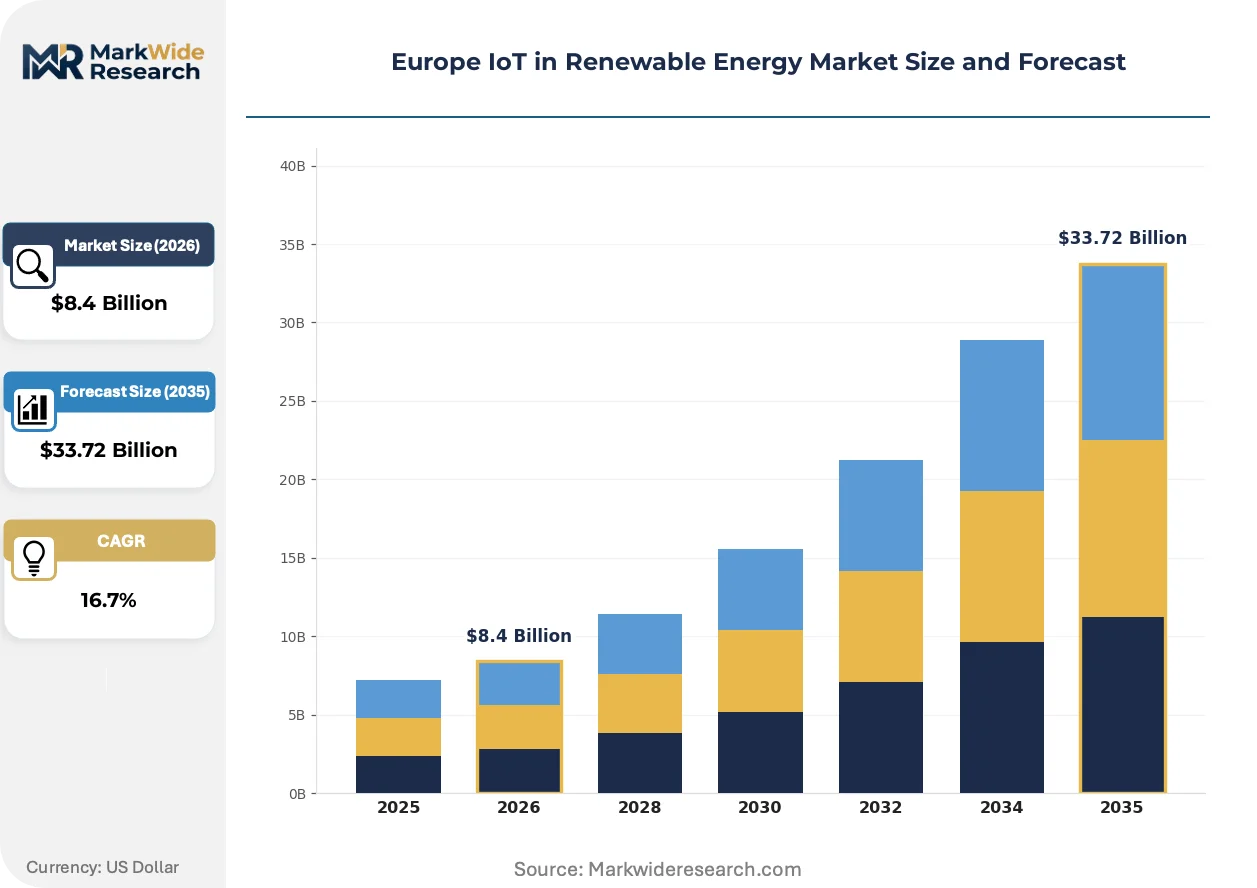
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $33.72 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Wireless Sensor Networks, Smart Meters, Data Analytics, Cloud Computing, Edge Computing Application: Wind Farm Monitoring, Solar Panel Management, Energy Storage Optimization, Grid Automation, Predictive Maintenance End User: Utility Companies, Energy Service Providers, Grid Operators, Renewable Asset Managers, System Integrators Deployment: On-Premises, Hybrid Cloud, Public Cloud, Private Cloud, Multi-Cloud |
| Companies Covered | Siemens, Bosch, Schneider Electric, ABB, Enel Green Power, Ørsted, Iberdrola, SAP, Ericsson, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe IoT in Renewable Energy Market Strategic Shifts & Innovations
Telemetry architectures are fragmenting between centralized cloud analytics and distributed edge inference, with regulatory latency requirements and data sovereignty rules determining deployment topology across European renewable portfolios.
Containerized microservices for wind turbine condition monitoring are modularizing software delivery, allowing Spanish and German operators to deploy predictive algorithms incrementally without full SCADA replacement. Mid-sized independent power producers are adopting these modules fastest, compressing vendor sales cycles from eighteen months to six. The shift is modularizing competition away from integrated platform vendors toward specialized algorithm providers.
EU AI Act high-risk system obligations are mandating human-in-the-loop oversight for automated curtailment decisions, forcing IoT platform vendors to rebuild inference pipelines with auditable decision trails. Solar inverter manufacturers serving utility-scale projects face the steepest compliance costs. Danish and Dutch operators are responding by centralizing algorithm governance through dedicated AI risk committees.
Spanish solar developers are unbundling hardware procurement from software subscriptions, separating sensor capex from analytics opex to improve project finance metrics. This disintermediation pressures traditional integrated vendors and opens entry paths for pure-play software firms. The pattern is most pronounced in Andalusia and Extremadura, where independent asset managers now dominate project ownership.
Europe IoT in Renewable Energy Market Segmentation
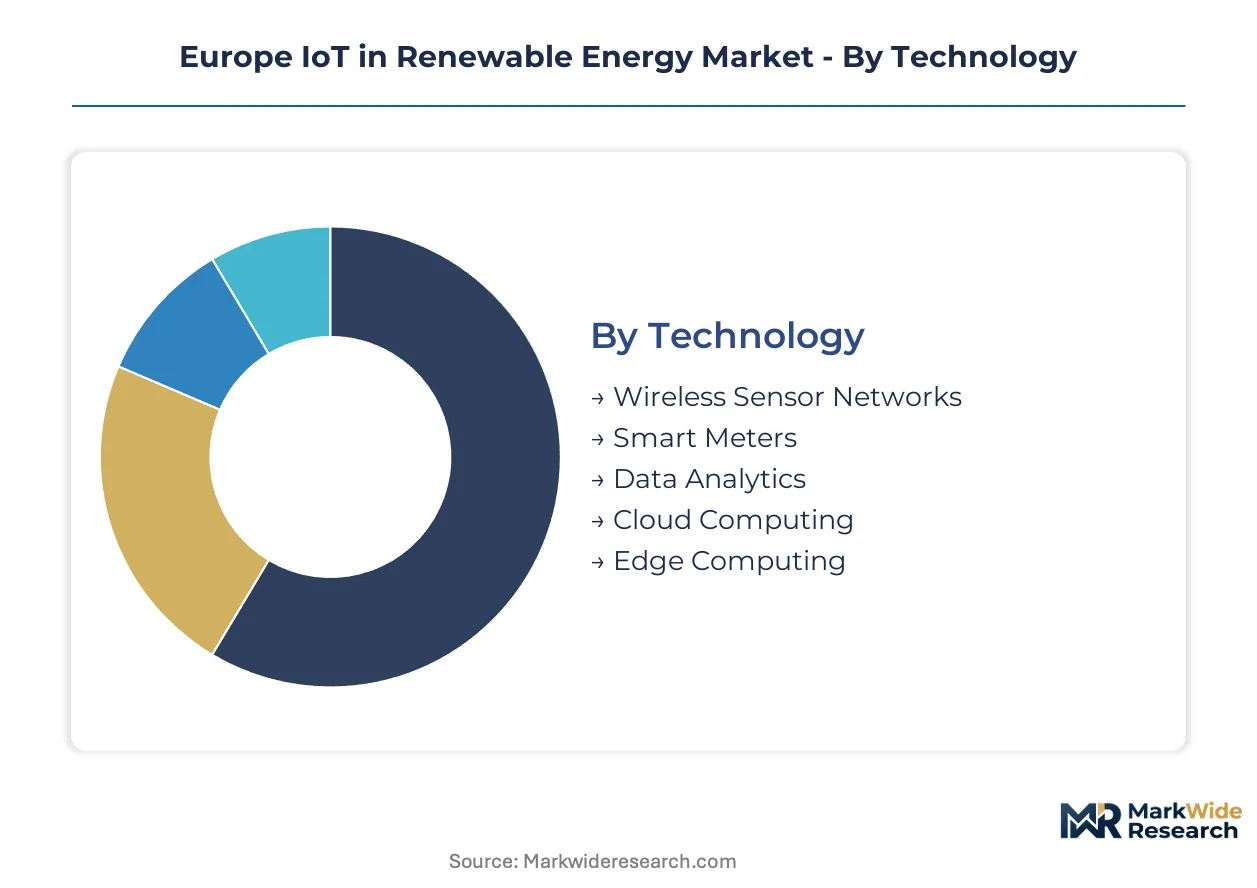
Technology choices in European renewable IoT deployments track directly to regulatory latency mandates and data sovereignty requirements. Buyers segment procurement across telemetry hardware, analytics platforms, and deployment architectures based on asset type and grid connection voltage levels.
Technology:
Procurement patterns diverge sharply between asset operators seeking sub-second control response and those prioritizing centralized fleet analytics.
- Edge Computing:Distributed inference nodes process turbine pitch commands and inverter switching signals locally. Danish North Sea operators deploy these systems to meet IEC 61850-90-12 latency requirements for fault ride-through sequences.
- Smart Meters:Advanced metering infrastructure with MQTT telemetry dominates distribution grid visibility projects. Spanish and German utilities are replacing first-generation AMR devices with DLMS/COSEM-compliant units to support EU Green Deal flexibility markets.
- Wireless Sensor Networks:Mesh protocols for photovoltaic string monitoring.
- Data Analytics:Predictive algorithms for gearbox degradation modeling.
- Cloud Computing:Centralized SCADA historian aggregation for multi-site portfolios.
Edge computing leads volumes today; smart meters are gaining share fastest through mandated replacement cycles.
Application:
Functional requirements map to asset class revenue exposure and operational risk profiles.
- Predictive Maintenance:Condition-based monitoring algorithms analyze vibration signatures and thermal patterns from offshore wind gearboxes. Operators in the German Bight corridor prioritize these systems to reduce unplanned outage penalties under grid connection agreements.
- Wind Farm Monitoring:Integrated telemetry for turbine availability and power curve optimization. Danish developers concentrate demand here due to capacity factor guarantees in offtake contracts.
- Solar Panel Management:String-level IV curve tracing and soiling detection.
- Energy Storage Optimization:Battery management system telemetry for state-of-charge balancing.
- Grid Automation:Substation RTU networks for voltage regulation.
Predictive maintenance leads volumes today; grid automation is climbing the fastest as connection queue pressures intensify.
End User:
Buyer sophistication varies with in-house engineering depth and regulatory compliance burden.
- Utility Companies:Vertically integrated grid operators procure end-to-end IoT stacks spanning generation telemetry through distribution SCADA. Iberdrola and RWE operate captive integration teams that specify IEC 62443 security zones across their European portfolios.
- Renewable Asset Managers:Independent owners of Spanish and Italian solar parks purchase modular analytics subscriptions. These buyers separate sensor hardware procurement from software licensing to optimize project finance structures.
- Energy Service Providers:Third-party operators of behind-the-meter installations.
- Grid Operators:Transmission system operators with wide-area monitoring requirements.
- System Integrators:Engineering firms bridging OEM protocols and utility standards.
Utility companies lead volumes today; renewable asset managers are expanding most quickly through independent power producer consolidation.
Deployment:
Architecture selection hinges on data residency requirements and real-time control loop specifications.
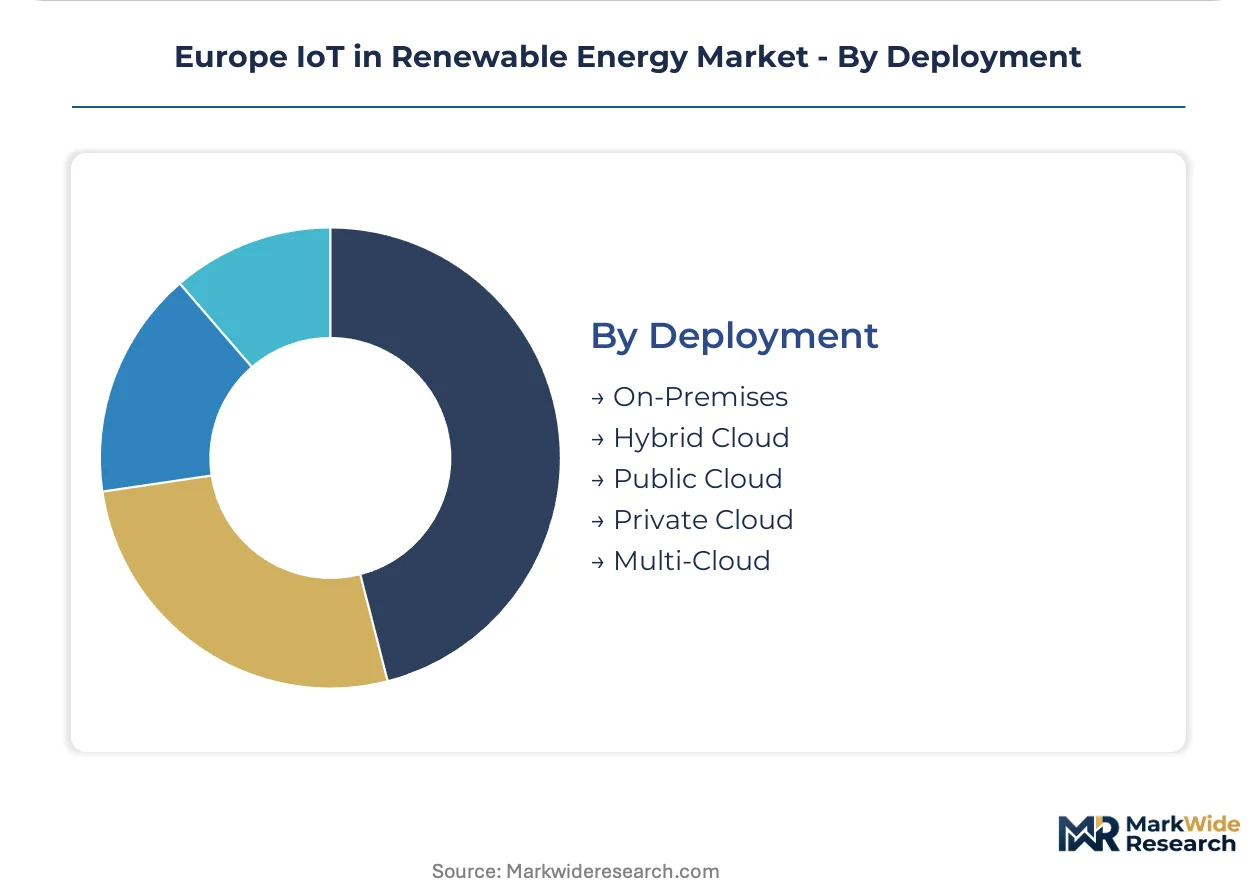
- Hybrid Cloud:Split processing architectures keep sensitive operational data on-premises while pushing non-critical analytics to hosted environments. German operators favor this model to satisfy GDPR localization obligations for turbine SCADA streams.
- On-Premises:Fully air-gapped systems for critical infrastructure protection. French nuclear-hybrid renewable sites mandate this architecture under national cybersecurity directives.
- Public Cloud:Scalable compute for non-critical fleet optimization.
- Private Cloud:Dedicated infrastructure for multi-asset owner consortia.
- Multi-Cloud:Vendor-distributed resilience strategies for large portfolios.
Hybrid cloud leads volumes today; on-premises is gaining share fastest through critical infrastructure reclassification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Denmark's offshore wind engineering clusters and Germany's industrial automation workforce anchor European IoT deployment capacity for renewable assets.
Germany
Utility-scale solar operators in Bavaria and North Rhine-Westphalia are retrofitting inverter telemetry to meet EU Green Deal grid codes. The F-Gas Regulation is accelerating cooling system sensor replacements at edge data centers co-located with solar farms. Siemens anchors turbine-to-grid data orchestration from its Munich engineering base.
Denmark
North Sea offshore wind developers deploy sub-second pitch control systems requiring low-latency edge computing nodes. The EU AI Act high-risk classification for automated curtailment algorithms forces human-in-the-loop oversight redesigns. Ørsted concentrates demand in the Esbjerg corridor for gearbox predictive maintenance telemetry.
Spain
Andalusian and Extremadura solar parks unbundle hardware procurement from analytics subscriptions to optimize project finance structures. The EU Green Deal mandates IEC 61850-compliant sensor networks for grid connection compliance. Iberdrola operates captive integration teams specifying security zones across its peninsular portfolio.
Poland
Grid connection backlogs for utility-scale solar create demand for IoT-enabled curtailment forecasting to optimize dispatch timing. REACH substance restrictions on battery sensor coatings extend product qualification timelines for Polish distributors. Warsaw-based asset managers are consolidating independent power producer holdings fastest.
Netherlands
Rotterdam port clusters host edge computing fabrication for North Sea wind telemetry hardware. The CSRD disclosure mandates open service contracts for automated carbon accounting middleware among Dutch renewable asset owners. Eindhoven's semiconductor design firms supply low-latency chips for turbine control systems.
Europe IoT in Renewable Energy Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the European renewable IoT stack. Siemens and ABB anchor integrated platform offerings spanning hardware through analytics, while specialized algorithm vendors modularize software delivery for mid-sized independent power producers. Two strategic archetypes dominate: vertically integrated industrial conglomerates with captive digital twin portfolios, and pure-play software firms exploiting procurement unbundling trends. Competitive moves concentrate on cybersecurity certification racing for IEC 62443 compliance and strategic partnerships bridging OEM protocol fragmentation.
Among Germany-based industrial conglomerates, Siemens and Bosch exemplify the integrated archetype with end-to-end control over turbine telemetry hardware and grid orchestration software. France's Schneider Electric occupies a parallel position in solar inverter edge computing and battery management systems. Denmark's Ørsted represents the asset-operator-as-technology-adopter model, internalizing IoT deployment expertise across its North Sea offshore wind portfolio rather than outsourcing to third-party vendors.
| Leading Market Players |
|---|
| Siemens |
| Bosch |
| Schneider Electric |
| ABB |
| Enel Green Power |
| Ørsted |
| Iberdrola |
| SAP |
| Ericsson |
| Others |
Cost & Logistics Intelligence
EU Green Deal IEC 61850 compliance mandates are forcing utility-scale solar operators to unbundle sensor hardware from software subscriptions, compelling supply chains to absorb certification costs while pricing pressure concentrates in the analytics tier.
Pricing Analysis
The bundled-vs-unbundled service split now defines procurement economics across European renewable portfolios. Subscription-based SaaS tiers for predictive maintenance algorithms command premium positioning against transactional hardware sales, with IEC 62443 cybersecurity certification emerging as the primary price differentiation driver alongside after-sales service bundling. Cost compression in edge computing hardware intensifies as Spanish and German utilities consolidate vendor panels, while independent power producers exhibit the sharpest price sensitivity due to project finance constraints.
Supply Chain Analysis
Freight cost volatility from East Asian semiconductor foundries to Danish offshore wind clusters is reshaping inventory strategies for low-latency control chips. Supply concentrates in Taiwan, South Korea, and Germany for edge computing processors, rare earth magnet sensors, and industrial Ethernet switches respectively, with raw material dependencies spanning gallium nitride wafers, lithium-ion battery coatings, and fluorinated cooling agents. Single-source vulnerability in advanced node fabrication exposes European inverter manufacturers to geopolitical disruption, while distribution runs through authorized systems integrator networks rather than direct OEM channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where procurement unbundling and cybersecurity certification requirements favor vendors with demonstrable IEC 62443 compliance and explainable AI telemetry architectures.
For Market Incumbents: To counter modular software entrants fragmenting the analytics layer, Siemens and Schneider Electric should deepen backward integration into edge computing chip design while locking in long-term service contracts with Iberdrola and RWE through captive cybersecurity certification programs. For New Entrants and Emerging Players: Enter via Poland's grid connection backlog crisis, where IoT-enabled curtailment forecasting for utility-scale solar remains underpenetrated, and exploit the Spanish independent power producer consolidation wave through pure-play algorithm subscriptions unbundled from hardware procurement. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized AI telemetry vendors holding EU AI Act high-risk system compliance and Danish offshore wind reference contracts, with the inflection signal being human-in-the-loop oversight mandate enforcement accelerating replacement cycles for non-compliant legacy platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Certification Program | IEC 62443 compliance unlocks utility procurement panels in Germany and Denmark. |
| Predictive Maintenance Algorithm Licensing | Explainable AI models satisfy EU AI Act high-risk system obligations for gearbox monitoring. |
| Hardware-Software Unbundling | Subscription analytics improve project finance metrics for Spanish independent power producers. |
| Offshore Wind Telemetry Partnership | Sub-second pitch control systems anchor demand in Denmark's North Sea corridor. |
| CSRD Carbon Accounting Middleware | Automated emissions reporting captures service contracts from Dutch asset managers. |
Research Approach
Bottom-up renewable asset operator modeling reconciled against top-down sensor hardware shipment tracking forms the analytical core of this study. Primary interviews with utility planning officers, independent power producer project developers, EPC contractors, and grid operators across Germany, Spain, Denmark, and Poland combined with secondary validation from IEA renewable deployment databases, EU Green Deal implementation reports, ECHA substance restriction filings, and IEC standards documentation. Triangulation between installation forecasts and component bill-of-materials estimates grounds volume projections.
Input-output matrices map edge computing node deployments, smart meter replacement cycles, and predictive maintenance algorithm subscriptions against generation capacity additions and regulatory compliance deadlines across the projection horizon. Segmentation dimensions span technology tier, application function, end-user archetype, and deployment architecture, with CAGRs derived from regression analysis of historical procurement patterns against policy mandate acceleration curves. Forecast inputs incorporate F-Gas Regulation phase-down timelines and EU AI Act enforcement sequencing.
The model holds under continued EU Green Deal implementation and REACH substance restriction enforcement; deviation in semiconductor supply chain reshoring timelines or cybersecurity certification capacity constraints would shift deployment trajectories. Stakeholders should weight assumptions against their own operating context and regulatory compliance calendars.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Renewable Energy Contractor Market
Renewable Energy
Drone Inspection Service for Renewable Energy Market
Renewable Energy
New Zealand Renewable Energy Market
Renewable Energy
Solar Navigation Light Market
Renewable Energy
China Wind Power Market
Renewable Energy
Argentina Renewable Energy Market
Renewable Energy
Europe Renewable Energy Market
Renewable Energy
Kazakhstan Renewable Energy Market
Renewable Energy
South Africa Renewable Energy Market
Renewable Energy
Solar Chimney Market
Renewable Energy
Malaysia Renewable Energy Market
Renewable Energy
Africa Solar E-Bike Market
Renewable Energy
Tunisia Renewable Energy Market
Renewable Energy
Renewable Energy Consulting Service Market
Renewable Energy
South Europe Renewable Energy Market
Renewable Energy
Ocean Power Market