
 East Africa Renewable Energy Market | 2026-2036
East Africa Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
East Africa Renewable Energy Market Foresight
Lithium-ion battery storage is restructuring solar-plus-storage economics across East African commercial installations. Kenya Electricity Generating Company PLC leverages its geothermal dominance to anchor utility-scale expansion in the Rift Valley. Voith GmbH & Co. KGaA competes in hydro turbine supply for Ethiopia's dam infrastructure. Serengeti Energy specializes in run-of-river projects that navigate fragmented grid access across Tanzania and Uganda.
East Africa renewable energy encompasses power generation from solar photovoltaic, wind, biomass combustion, and hydroelectric systems with typical solar installations ranging from 50 kW residential arrays to 100 MW utility plants serving national grids and isolated mini-grids. Its primary purpose displaces diesel-fired generation while reducing electricity access deficits across rural and peri-urban populations. Solar technology leads installed capacity growth due to modular deployment and declining module costs, while hydro maintains the largest share of existing generation through Ethiopia's mega-dam program and Uganda's Nile basin infrastructure. Off-grid application segments attract financing innovation as pay-as-you-go solar companies extend consumer reach beyond centralized grid boundaries.
Kenya's Energy Regulatory Authority enforces feed-in tariff structures that shape independent power producer participation, while Ethiopia's Electric Power authority controls generation licensing through state-directed procurement. Tanzania's Energy and Water Utilities Regulatory Authority mandates rural electrification targets that channel development finance toward decentralized systems. Stakeholders must monitor how regional power pool integration and cross-border transmission commitments alter project economics for developers operating across multiple jurisdictions.
Market Dynamics
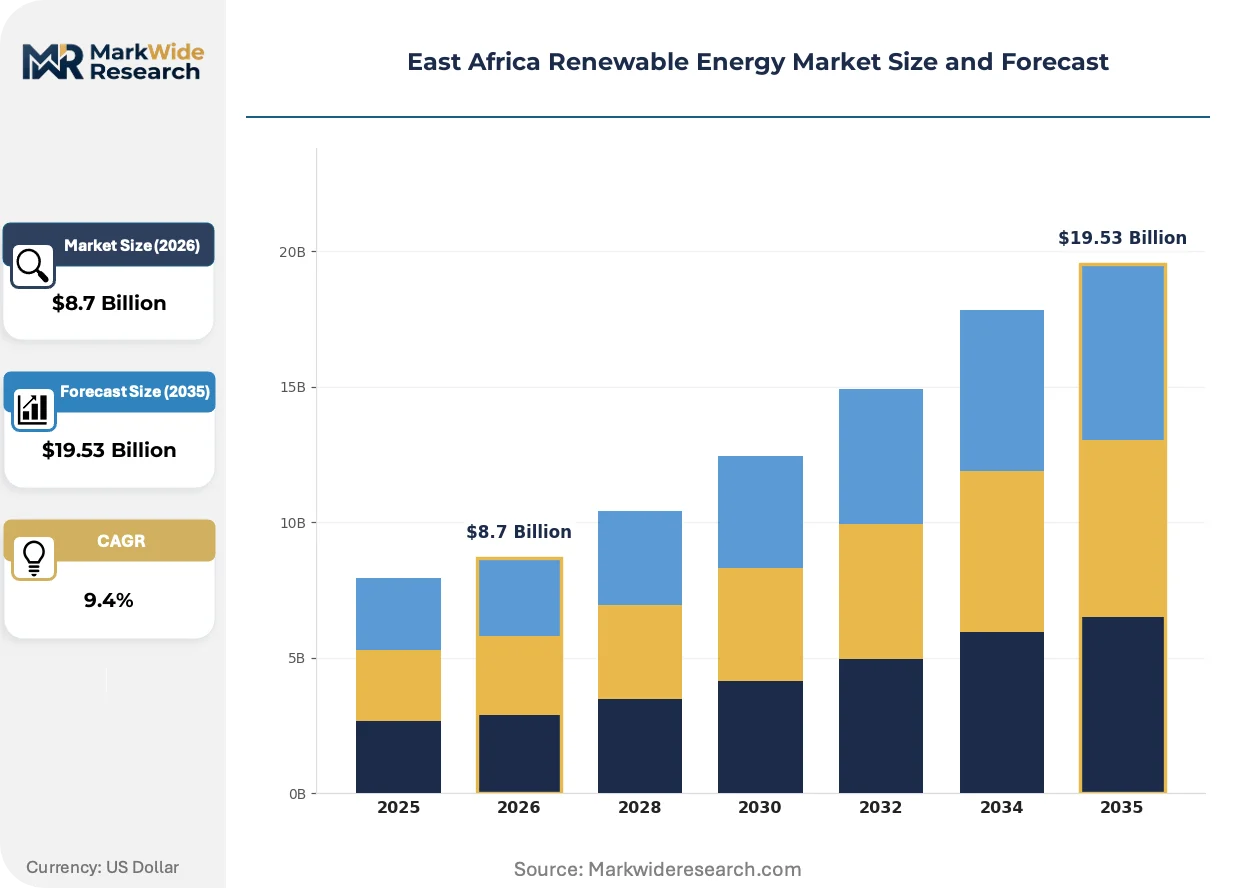
Kenya's feed-in tariff framework and Ethiopia's state-directed dam procurement are redirecting capital flows toward geothermal and hydroelectric infrastructure, compressing development timelines for independent power producers while fragmenting financing access across national boundaries.
Growth Catalysts
- Kenya's Feed-in Tariff Policy:Kenya's Energy Regulatory Authority enforces guaranteed purchase prices for renewable generators, de-risking independent power producer investments in geothermal and solar installations across the Rift Valley corridor.
- Pay-as-you-go Solar Models:Mobile money-enabled financing platforms extend consumer credit to rural households beyond centralized grid boundaries, accelerating off-grid solar penetration in Tanzania and Uganda.
- Ethiopia's Dam Construction Pipeline:State-backed mega-dam programs on the Blue Nile and Omo River basins anchor regional hydroelectric capacity expansion, creating anchor demand for turbine and transmission infrastructure.
Market Restraints
- Foreign Exchange Concentration Risk:Project debt denominated in USD and EUR exposes developers to local currency depreciation against the Ethiopian birr and Kenyan shilling, elevating refinancing costs.
- Grid Interconnection Backlogs:Transmission infrastructure deficits in Tanzania and Uganda delay commercial operation dates for completed solar and wind assets, trapping capital in idle generation capacity.
- Diesel Generator Substitution Economics:Volatile global oil prices periodically compress the cost gap between solar-plus-storage and diesel-fired backup systems, slowing displacement in commercial segments.
Strategic Opportunities
- Rural Electrification Mandates:Tanzania's Energy and Water Utilities Regulatory Authority mandates specific connection targets for decentralized systems, channeling development finance toward mini-grid developers.
- Battery Storage Convergence:Lithium-ion cost declines are enabling solar-plus-storage configurations that displace diesel entirely for agricultural processing cooperatives and commercial estates.
- Regional Power Pool Integration:East African Power Pool cross-border transmission commitments alter project economics for developers operating across Kenya, Ethiopia, and Tanzania jurisdictions.
Industry Challenges
- Geotechnical Survey Capacity Scarcity:Limited domestic expertise in geothermal reservoir assessment and hydrological modeling extends pre-construction timelines for greenfield developments.
- Land Tenure Documentation Complexity:Customary land rights and overlapping claims in Ethiopia's Omo Valley and Kenya's Turkana region stall site acquisition for utility-scale solar and wind farms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | East Africa Renewable Energy Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Solar, Wind, Biomass, Hydro Product Type: Solar Panels, Wind Turbines, Biogas Systems, Hydro Turbines Application: Residential, Industrial, Commercial, Off-grid Service Type: Installation, Maintenance, Consulting, Financing |
| Companies Covered | Kenya Electricity Generating Company PLC, Voith GmbH & Co. KGaA, Serengeti Energy, Salini Costruttori S.p.A., Vergnet SA, Milele Energy, Hewani Energy, REDAVIA GmbH, Eleqtra Inc., Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
East Africa Renewable Energy Market Shifts & Advancements
Solar photovoltaic technology is fragmenting into scalable building blocks that match generation assets to demand profiles across grid-connected and isolated mini-grid environments. This modular architecture is compressing procurement cycles and enabling new financing structures.
Solar-plus-storage systems are modularizing across East African commercial installations. Agricultural processing cooperatives in Kenya's Rift Valley adopt containerized battery units paired with 500 kW to 2 MW solar arrays. This configuration is displacing diesel-fired generation during daylight hours while providing evening load coverage, compressing payback periods to four-to-six years for eligible offtakers.
Ethiopia's Electric Power authority controls generation licensing through centralized procurement frameworks that prioritize hydroelectric and geothermal capacity additions. This state-directed model limits independent power producer participation in generation assets while concentrating equipment supply relationships with state-owned engineering firms. Developers seeking market entry must align with public-private partnership structures or equipment export arrangements.
Pay-as-you-go solar companies extend consumer reach through mobile money platforms that bypass traditional banking infrastructure. Rural households in Tanzania and Uganda purchase 50-200 watt home systems through daily micro-payments. This channel disintermediation shifts customer acquisition costs toward digital marketing and agent networks, compressing the addressable market for conventional grid extension programs.
East Africa Renewable Energy Market Segmentation
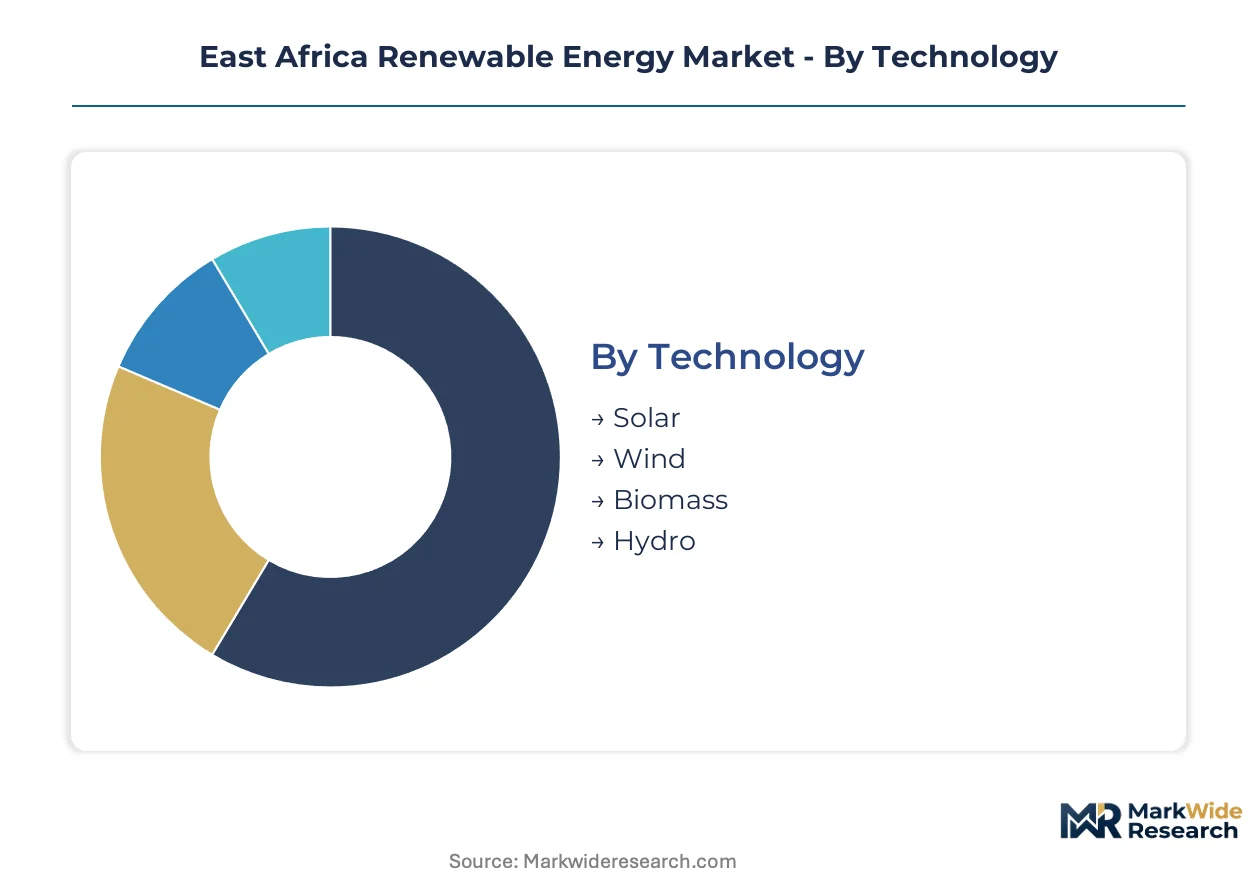
Technology choices in East Africa renewable energy directly determine financing structures, deployment timelines, and regulatory pathways across Kenya, Ethiopia, and Tanzania. Each segmentation axis reveals distinct competitive dynamics between state-directed procurement and private capital deployment.
Technology:
Solar photovoltaic and geothermal systems dominate capital allocation decisions across East African utilities and independent power producers.
- Solar:Modular photovoltaic arrays scale from 50 kW residential installations to 100 MW utility plants. Kenyan agricultural cooperatives in the Rift Valley deploy solar-plus-storage configurations to displace diesel generation during irrigation seasons.
- Hydro:Run-of-river and mega-dam infrastructure anchor Ethiopia's state-directed generation expansion on the Blue Nile and Omo River basins. Serengeti Energy navigates fragmented grid access with small-scale hydro across Tanzania and Uganda.
- Wind:Turkana Wind Power in northern Kenya operates Africa's largest wind farm, though geotechnical survey scarcity extends pre-construction timelines for greenfield developments.
- Biomass:Agricultural residue combustion serves tea and sugar processing estates in Kenya's highlands, leveraging captive feedstock supply from estate operations.
Solar leads on scale; hydro leads on momentum through Ethiopia's dam construction pipeline.
Product Type:
Equipment specifications align with national procurement frameworks and grid interconnection standards.
- Solar Panels:Crystalline silicon modules dominate utility-scale procurement, with declining lithium-ion battery costs enabling solar-plus-storage economics for commercial offtakers.
- Hydro Turbines:Voith GmbH & Co. KGaA supplies turbine infrastructure for Ethiopia's dam program under state-directed equipment procurement relationships.
- Wind Turbines:Horizontal-axis units require specialized logistics for delivery to remote highland sites in Kenya and Tanzania.
- Biogas Systems:Anaerobic digesters process agricultural waste at estate scale, with limited domestic manufacturing capacity constraining deployment velocity.
Solar panels command the broadest addressable market; hydro turbines concentrate the highest contract values per project.
Application:
End-use segmentation separates grid-connected capacity additions from decentralized rural electrification programs.
- Off-grid:Pay-as-you-go solar companies extend consumer reach through mobile money platforms in Tanzania and Uganda, bypassing traditional banking infrastructure.
- Industrial:Agricultural processing cooperatives adopt containerized battery units paired with 500 kW to 2 MW solar arrays, compressing payback periods to four-to-six years.
- Residential:Rural households purchase 50-200 watt home systems through daily micro-payments, shifting customer acquisition costs toward digital marketing.
- Commercial:Urban enterprises in Nairobi and Addis Ababa prioritize grid-connected solar to manage electricity tariff exposure.
Off-grid applications are expanding most quickly; industrial segments concentrate the highest revenue per connection.
Service Type:
Service delivery models fragment across state utility channels and private developer ecosystems.
- Installation:EPC contractors navigate land tenure documentation complexity in Ethiopia's Omo Valley and Kenya's Turkana region.
- Financing:Development finance institutions channel capital toward decentralized systems under Tanzania's rural electrification mandates.
- Maintenance:Geothermal reservoir assessment expertise scarcity extends service contract timelines for Kenya Electricity Generating Company PLC assets.
- Consulting:Regulatory advisory focuses on Kenya's Energy Regulatory Authority feed-in tariff compliance and Ethiopia's centralized licensing frameworks.
Installation commands the largest workforce deployment; financing represents the steepest expansion trajectory as pay-as-you-go models scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Great Rift Valley anchors East Africa's renewable energy infrastructure, with geothermal fields, river basins, and solar corridors concentrating development capital across Kenya, Ethiopia, Tanzania, and Uganda.
Kenya
Geothermal reservoirs in the Olkaria and Menengai fields drive baseload capacity expansion. Kenya's Energy Regulatory Authority enforces feed-in tariffs that de-risk independent power producer investments. The Rift Valley corridor hosts utility-scale solar-plus-storage installations serving agricultural processing cooperatives.
Ethiopia
State-directed dam procurement on the Blue Nile and Omo River basins anchors regional hydroelectric capacity. The Ethiopian Electric Power authority controls generation licensing through centralized frameworks. The Grand Ethiopian Renaissance Dam creates anchor demand for turbine infrastructure and transmission equipment.
Tanzania
Run-of-river hydro and off-grid solar penetration accelerate under rural electrification mandates. The Energy and Water Utilities Regulatory Authority channels development finance toward decentralized mini-grid systems. Lake Victoria basin communities adopt pay-as-you-go solar through mobile money platforms.
Uganda
Nile basin hydro infrastructure and isolated grid access drive small-scale project development. The country's rural electrification agency prioritizes decentralized systems in regions beyond national grid reach. Western districts attract run-of-river developers navigating fragmented transmission networks.
East Africa Renewable Energy Market Competitive Landscape
Global majors compete with regional champions across equipment supply and project development, creating a tiered structure where European turbine manufacturers and African independent power producers occupy distinct strategic positions. State-owned utilities control generation licensing in Ethiopia, while private developers dominate Kenya's feed-in tariff market. Three archetypes define competitive positioning: state-backed engineering conglomerates, specialized renewable developers, and equipment suppliers with long-term service contracts. Capacity expansion and strategic partnerships represent the dominant competitive moves, with developers seeking to secure offtake agreements across multiple jurisdictions.
Within the state-backed infrastructure tier, Salini Costruttori S.p.A. and Voith GmbH & Co. KGaA exemplify equipment and engineering concentration around Ethiopia's dam construction pipeline. Among regional independent power producers, Kenya Electricity Generating Company PLC occupies a position as the dominant geothermal generator, while Serengeti Energy represents the specialized run-of-river developer archetype across Tanzania and Uganda.
| Leading Market Players |
|---|
| Kenya Electricity Generating Company PLC |
| Voith GmbH & Co. KGaA |
| Serengeti Energy |
| Salini Costruttori S.p.A. |
| Vergnet SA |
| Milele Energy |
| Hewani Energy |
| REDAVIA GmbH |
| Eleqtra Inc. |
| Others |
Supply & Pricing Matrix
Equipment-grade bifurcation between utility-scale turbine infrastructure and modular solar-plus-storage systems manifests divergent pricing architectures and procurement pathways across East African markets. Premium-tier hydroelectric equipment commands long-term offtake contracts through Ethiopia's state-directed procurement, while containerized battery-solar configurations trade on standardized per-kilowatt pricing accessible to agricultural cooperatives.
Pricing Analysis
Input-cost pass-through from lithium-ion cell markets and polysilicon wafer pricing directly shapes solar-plus-storage economics for commercial offtakers in Kenya's Rift Valley. Project-based long-term offtake agreements dominate utility-scale hydro and geothermal segments, while pay-as-you-go solar employs subscription-tiered pricing through mobile money platforms. Price differentiation rests on certification grade for grid-interconnection compliance and volume scale for agricultural cooperative deployments. Cost compression in battery storage intensifies as Chinese cell manufacturers expand export capacity. Rural households exhibit highest price sensitivity, while state utilities demonstrate lowest sensitivity due to concessional development finance access.
Supply Chain Analysis
Reverse-logistics networks for turbine refurbishment and battery recycling remain embryonic across East African markets, construring circular economy participation. Equipment supply concentrates in China for photovoltaic modules and lithium-ion cells, Germany for hydro turbine precision engineering, and India for balance-of-system components. Raw material dependencies span polysilicon wafers, rare-earth magnets for wind generators, and copper cabling for grid interconnection. Single-source vulnerability pervades Ethiopian dam equipment procurement given Voith GmbH & Co. KGaA's entrenched supplier relationships. Distribution runs through state utility procurement channels for grid-connected capacity and pay-as-you-go agent networks for decentralized systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
East Africa renewable energy functions as a regulatory compounder where Kenya's Energy Regulatory Authority feed-in tariff revisions and Ethiopia's Electric Power licensing frameworks sequentially amplify investment returns for aligned developers.
For Market Incumbents: Acquire geothermal reservoir assessment capabilities and hydrological modeling expertise to compress pre-construction timelines threatened by domestic technical talent scarcity. Secure backward integration into lithium-ion battery assembly to capture storage margin compression from Chinese cell imports. Prioritize certification investment for Kenya's grid-interconnection standards to defend against emerging EPC contractors from South Africa and UAE. For New Entrants and Emerging Players: Tanzania's Energy and Water Utilities Regulatory Authority rural electrification mandates open a window for mini-grid developers targeting Lake Victoria basin communities beyond centralized grid reach. Pay-as-you-go solar penetration in Uganda presents the most penetrable white-space target given lower incumbent density versus Kenya. Pursue strategic partnership structures with mobile money platforms to bypass traditional banking infrastructure and compress customer acquisition costs. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized run-of-river developers possessing operational assets across multiple East African jurisdictions. Long-term viability over a five-to-ten year window favors developers with secured offtake agreements under Kenya's feed-in tariff and Tanzania's rural electrification mandates rather than pure equipment suppliers exposed to procurement cycle volatility. Monitor Ethiopia's foreign exchange reserve trajectory and birr depreciation patterns as the critical inflection indicator for project refinancing risk.| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement | Long-term offtake contracts with Kenya Electricity Generating Company PLC de-risk geothermal capacity additions. |
| Vertical Integration into Storage | Containerized battery assembly captures margin from declining lithium-ion cell costs for agricultural cooperatives. |
| Technology Licensing | Voith GmbH & Co. KGaA turbine technology transfers anchor Ethiopian dam equipment procurement relationships. |
| Capacity Buildout | Run-of-river hydro expansion across Tanzania and Uganda leverages Serengeti Energy's fragmented grid expertise. |
| Green Certification Program | Grid-interconnection compliance under Kenya's Energy Regulatory Authority standards unlocks feed-in tariff eligibility. |
Research Methodology
Coverage spans Kenya, Ethiopia, Tanzania, and Uganda, with primary inputs from each market's utility planning officers, independent power producer project developers, EPC contractors, and grid operators. Secondary validation draws from East African Power Pool transmission commitment disclosures, national regulatory authority tariff filings, International Energy Agency renewable energy databases, and project finance transaction registries. Bottom-up capacity installation tracking triangulates with top-down national energy master plan targets to reconcile supply-side and demand-side perspectives.
Rate-of-change decomposition separates capacity addition velocity from tariff evolution and technology cost trajectories across the analysis window. Segmentation dimensions modeled encompass fuel source, generation capacity tier, project scale, regulatory framework, and regional grid type. CAGRs derive from installed capacity build-up schedules and revenue-per-megawatt assumptions calibrated to disclosed offtake pricing. Forecast inputs incorporate Ethiopia's dam construction pipeline milestones and Kenya's geothermal field development timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under foreign exchange volatility in Ethiopia and prolonged grid interconnection backlogs in Tanzania. Projections reflect assumptions regarding regulatory continuity for feed-in tariffs and state-directed procurement frameworks. Practitioners should monitor Ethiopia's birr liquidity conditions and Tanzania's transmission infrastructure investment commitments for early signals of forecast deviation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Green Energy Lighting Market
Renewable Energy
Netherlands Renewable Energy Market
Renewable Energy
Renewable Energy Monitoring and Control System Market
Renewable Energy
Botswana Renewable Energy Market
Renewable Energy
Portugal Renewable Energy Market
Renewable Energy
Europe Renewable Energy Market
Renewable Energy
LAMEA Wave and Tidal Energy Market
Renewable Energy
Composite Materials in Renewable Energy Market
Renewable Energy
Biomethane Certificate Trading Platform Market
Renewable Energy
Variable Renewable Energy Market
Renewable Energy
Europe IoT in Renewable Energy Market
Renewable Energy
Global Solar Home Lighting Market
Renewable Energy
Tidal Turbines Market
Renewable Energy
North Africa Renewable Energy Market
Renewable Energy
Global Organic Rankine Cycle Market
Renewable Energy
United Arab Emirates Renewable Energy Market