
 Denmark Renewable Energy Market | 2026-2036
Denmark Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Denmark Renewable Energy Market Outlook
A capital-intensity divergence between offshore wind developers and distributed solar installers is unwinding competitive parity across the Danish renewable energy landscape. Ørsted A/S leverages its proprietary offshore installation vessels and grid connection expertise to dominate deep-water project pipelines. Vestas Wind Systems anchors onshore turbine supply through its Ringkøbing manufacturing footprint and service network density. European Energy A/S specializes in utility-scale solar and Power-to-X project development, competing for land access and grid queue positions against traditional wind incumbents.
Denmark renewable energy encompasses electricity and heat generation from wind, solar, biomass, and hydropower assets, with offshore wind turbines typically rated at 8-15 MW and foundation structures designed for water depths exceeding 30 meters in the North Sea. The primary purpose is decarbonizing Denmark's energy system while exporting surplus green power through interconnections to Germany, Sweden, and Norway. Wind energy occupies the largest installed capacity share and attracts the majority of capital expenditure, while solar photovoltaic installations accelerate fastest from a smaller base as agricultural land leases and rooftop programs expand. Energy storage through battery and green hydrogen systems captures emerging margin pools as grid balancing requirements intensify with variable renewable penetration.
The Danish Energy Agency implements national energy planning under the Climate Act framework, while EU Green Deal targets and the F-Gas Regulation shape equipment standards and refrigerant transitions for heat pumps. Grid codes enforced by Energinet mandate frequency response capabilities and reactive power control from renewable generators, raising technical barriers for new market entrants. Stakeholders must monitor auction design evolution for seabed leases and the pace of electrolyzer manufacturing scale-up to assess whether domestic supply chains or imported equipment will capture hydrogen infrastructure value.
Market Dynamics
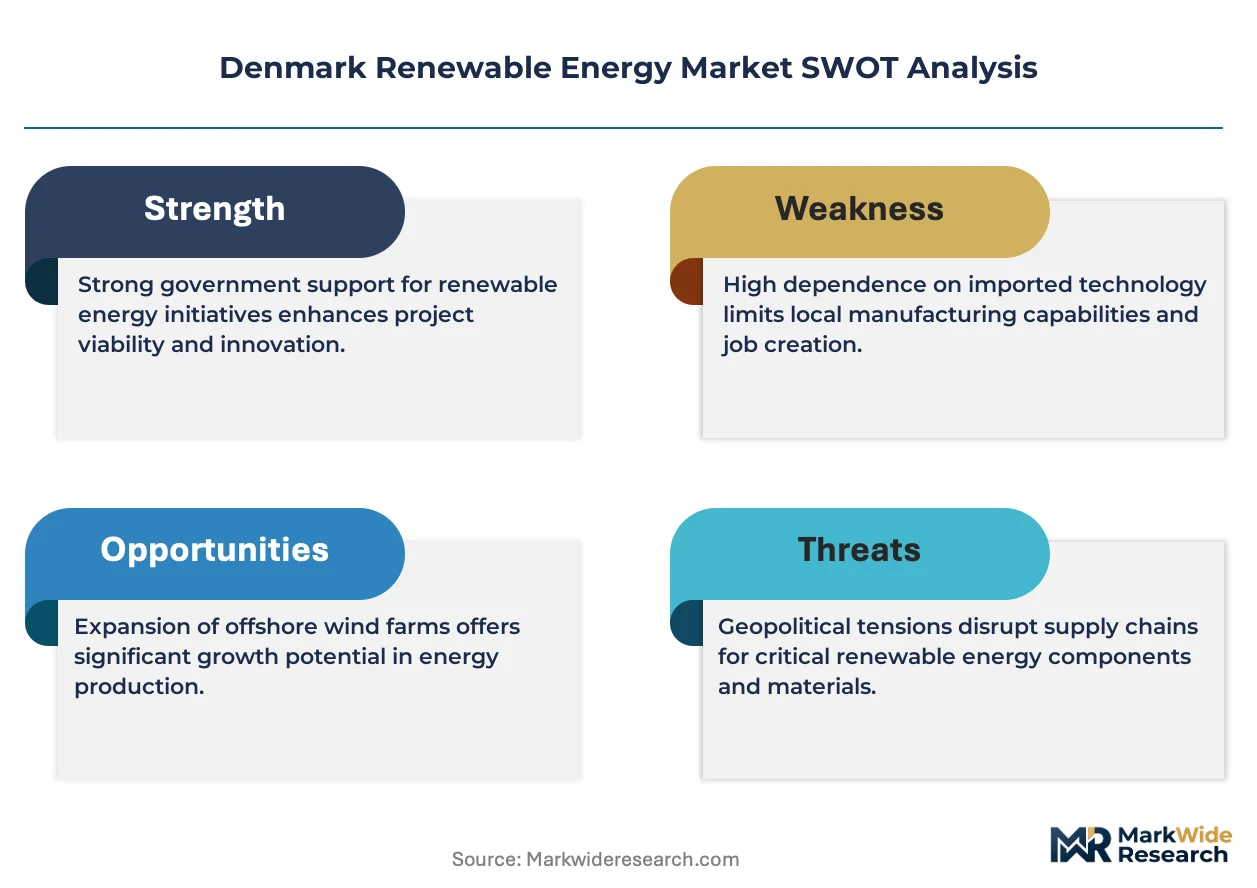
The Danish renewable energy market is undergoing a structural transformation driven by the Energy Agreement framework's fossil-fuel phase-out mandates, which force district heating utilities and power generators to reconfigure supply portfolios while competing for scarce seabed leases and grid interconnection capacity.
Growth Catalysts
- Energy Agreement mandates:The Danish Climate Act imposes binding carbon reduction targets that compel utilities to accelerate renewable procurement timelines and retire coal and natural gas assets ahead of schedule.
- Offshore wind foundation engineering:Monopile and jacket structures designed for 30-50 meter water depths in the North Sea and Kattegat enable larger turbine deployments that capture higher capacity factors.
- Power-to-X electrolyzer manufacturing:Green hydrogen production facilities under development in Esbjerg and Frederikshavn create anchor demand for surplus offshore wind generation and attract industrial off-takers.
Market Restraints
- Copper and rare earth magnet supply concentration:Dependence on Chinese processing facilities for neodymium and dysprosium used in direct-drive turbine generators exposes developers to export restriction risks and price volatility.
- Grid connection queue congestion:Energinet's technical assessment backlog for new renewable interconnections extends project commissioning timelines and traps capital in pre-construction phases.
- Seabed lease auction design:The Danish Energy Agency's competitive bidding rounds for offshore zones concentrate developer participation among capital-heavy incumbents with proprietary vessel fleets.
Strategic Opportunities
- Agricultural land lease conversion:Utility-scale solar developers are securing long-term agreements with Jutland farming cooperatives to deploy agrivoltaic systems that maintain crop production while generating electricity.
- Building-integrated heat pump deployment:The EU F-Gas Regulation's refrigerant phase-down timeline accelerates replacement demand for natural gas boilers in Copenhagen and Aarhus residential districts.
- Battery energy storage co-location:Grid-scale lithium-ion systems paired with existing onshore wind farms in western Denmark capture frequency regulation revenues and defer transmission upgrades.
Industry Challenges
- High-voltage cable installation vessel scarcity:The specialized fleet capable of laying 220 kV subsea interconnectors is fully contracted through 2027, forcing project developers to accept premium charter rates or delay construction windows.
- Electrolyzer stack certification timelines:Type approval processes for alkaline and PEM electrolysis systems under EU pressure equipment directives extend equipment delivery schedules and compress project execution margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Denmark Renewable Energy Market |
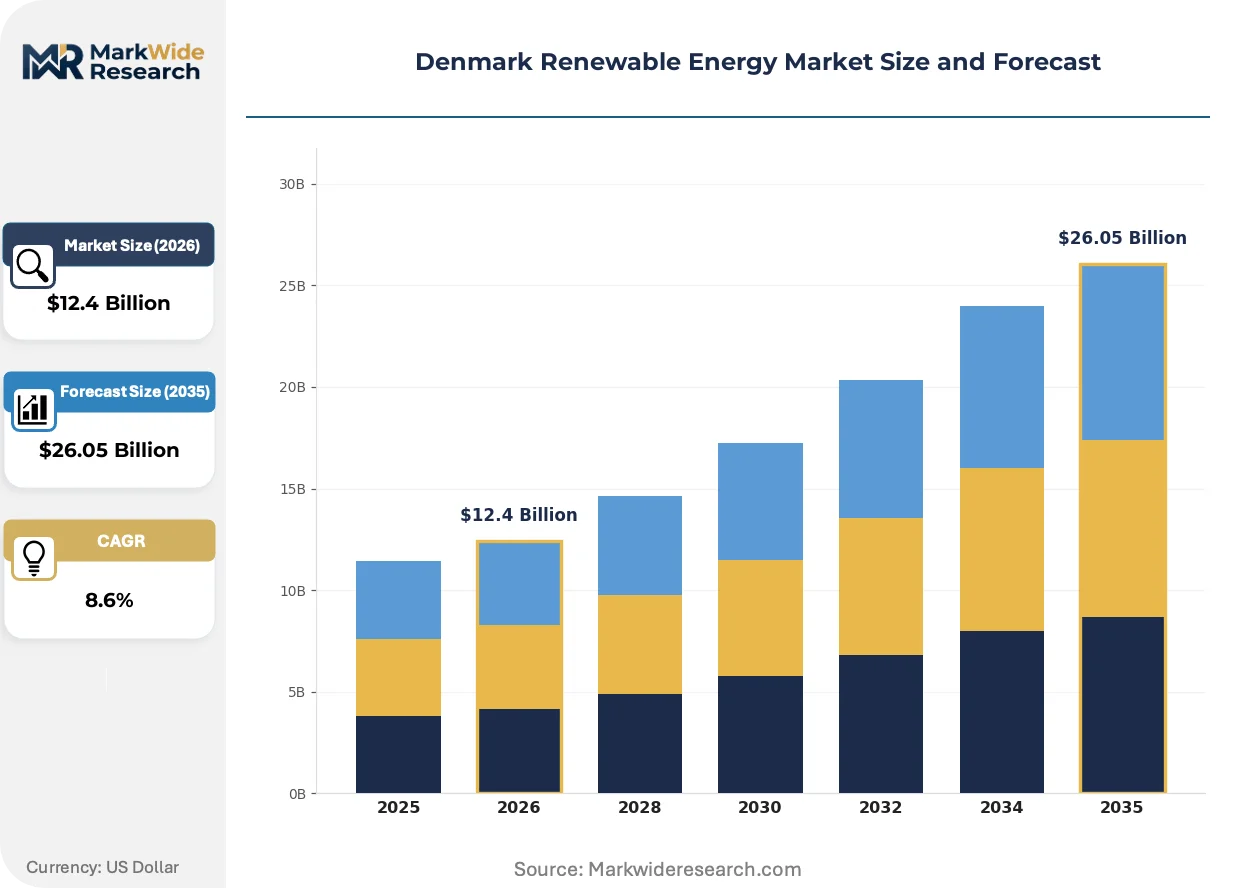
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $26.05 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Energy Type: Wind, Solar, Biomass, Hydropower End User: Residential, Commercial, Industrial, Government Installation Type: Onshore, Offshore, Ground-mounted, Rooftop Technology: Photovoltaic, Turbines, Geothermal, Energy Storage |
| Companies Covered | Arcon-Sunmark A/S, Siemens Gamesa Renewable Energy, Ørsted A/S, Copenhagen Infrastructure Partners, European Energy A/S, Vestas Wind Systems, Better Energy A/S, Aalborg CSP A/S, Vattenfall, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Denmark Renewable Energy Market Strategic Shifts
Technology convergence and regulatory tightening are compressing traditional equipment procurement cycles while opening margin pools in grid flexibility services. Danish developers now prioritize integrated asset configurations that combine generation, storage, and sector-coupling infrastructure.
Next-generation 15 MW offshore wind turbines with swept areas exceeding 22,000 square meters are displacing 8-10 MW units in North Sea project pipelines. Ørsted and European Energy are specifying these machines for Kriegers Flak and Thor zone developments. The capacity step-change is compressing levelized cost trajectories while concentrating foundation and installation vessel requirements among fewer suppliers.
The EU Green Deal's 55% emissions reduction target for 2030 is tightening F-Gas Regulation enforcement across heat pump and grid equipment categories. Danish manufacturers face accelerated refrigerant transition schedules for R-410A and R-134a systems. The regulatory pressure is redirecting R&D investment toward CO2 and hydrocarbon-based heat pump architectures while raising compliance costs for incumbent product lines.
Corporate power purchase agreements are displacing traditional utility green tariff programs as the dominant procurement channel for industrial electricity consumers. Carlsberg, Novo Nordisk, and Maersk are negotiating 10-15 year contracts directly with offshore wind and solar developers. The bilateral contracting trend is most visible in Zealand and Funen manufacturing clusters where energy costs dominate operational expenditure calculations.
Denmark Renewable Energy Market Segmentation
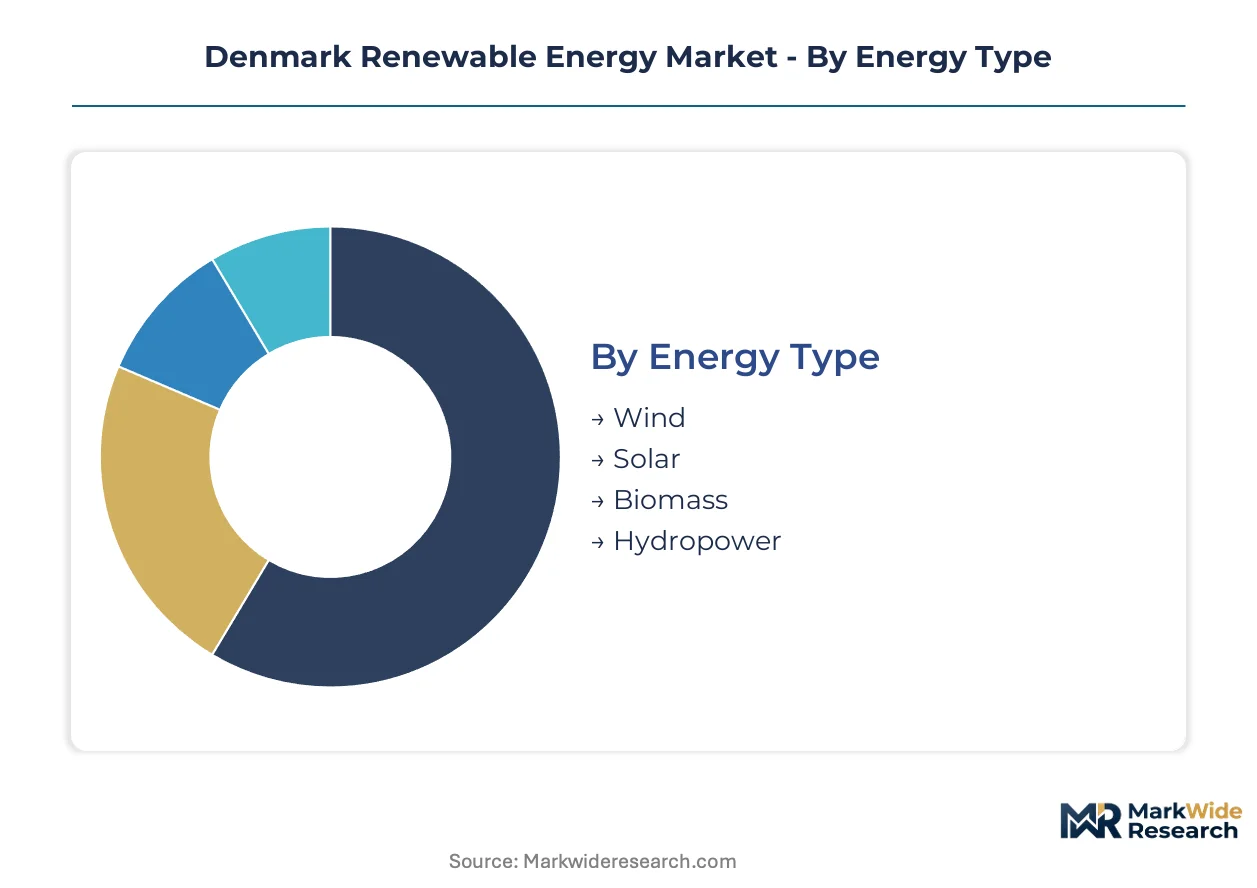
Denmark's renewable energy market segments reflect distinct capital deployment patterns, regulatory exposure profiles, and grid integration requirements that shape competitive positioning across developers and equipment suppliers.
Energy Type:
Wind and solar dominate domestic capacity expansion, while biomass and hydropower segments serve established district heating networks and legacy grid balancing roles.
- Wind:Offshore installations in the North Sea and Kattegat utilize 8-15 MW turbines on monopile foundations engineered for 30-50 meter depths. Copenhagen-based utilities and Esbjerg port clusters anchor procurement for Kriegers Flak and Thor zone developments, constrained by specialized installation vessel availability through 2027.
- Solar:Photovoltaic arrays concentrate in Jutland agricultural regions through agrivoltaic lease structures that preserve crop production. European Energy A/S and land cooperatives drive ground-mounted deployment, competing for grid queue positions against wind incumbents in western Denmark interconnection backlogs.
- Biomass:Wood chip and straw-fired combined heat and power plants supply district heating networks in Aarhus and Odense under Energy Agreement phase-out mandates.
- Hydropower:Small-scale run-of-river installations contribute marginal generation shares, concentrated in northern Jutland watercourses with limited expansion headroom.
Wind holds the largest share; momentum sits with solar.
End User:
Industrial offtakers command bilateral contracting leverage, while residential and commercial segments respond to building code mandates and heat pump substitution incentives.
- Residential:Single-family and multi-unit buildings in Copenhagen and Aarhus drive heat pump installations and rooftop solar deployment. F-Gas Regulation refrigerant phase-downs accelerate natural gas boiler replacements, with Energinet grid codes mandating frequency response capabilities for distributed generation.
- Commercial:Retail and office facilities in Zealand and Funen procure green electricity through corporate power purchase agreements. Carlsberg and Novo Nordisk negotiate 10-15 year contracts directly with offshore wind developers, bypassing traditional utility tariff structures.
- Industrial:Heavy manufacturing and chemical processing in Frederikshavn and Esbjerg anchor Power-to-X electrolyzer demand for green hydrogen feedstock. Maersk shipping operations and fertilizer producers compete for surplus offshore wind offtake in coastal industrial zones.
- Government:Municipal buildings and public infrastructure projects in Aalborg and Roskilde procure renewable electricity through centralized tendering frameworks administered by the Danish Energy Agency.
Industrial offtakers capture the steepest expansion trajectory; residential retrofits face equipment supply bottlenecks.
Installation Type:
Foundation engineering and grid connection economics create divergent margin structures between centralized offshore assets and distributed rooftop systems.
- Onshore:Vestas Wind Systems manufactures turbines at its Ringkøbing facility for deployment across Jutland and Funen wind corridors. Land lease negotiations with agricultural cooperatives and visual impact assessments constrain project development timelines.
- Offshore:Ørsted A/S deploys proprietary installation vessels for deep-water projects in the North Sea, leveraging grid connection expertise that concentrates capital deployment among capital-heavy incumbents.
- Ground-mounted:Utility-scale solar arrays occupy former agricultural land in western Denmark, with developers securing 25-30 year leases from farming cooperatives.
- Rooftop:Residential and commercial building-integrated systems face permitting complexity across Copenhagen municipality zoning districts and homeowner association restrictions.
Offshore installations command the highest capital intensity; rooftop deployment expands most quickly from a smaller base.
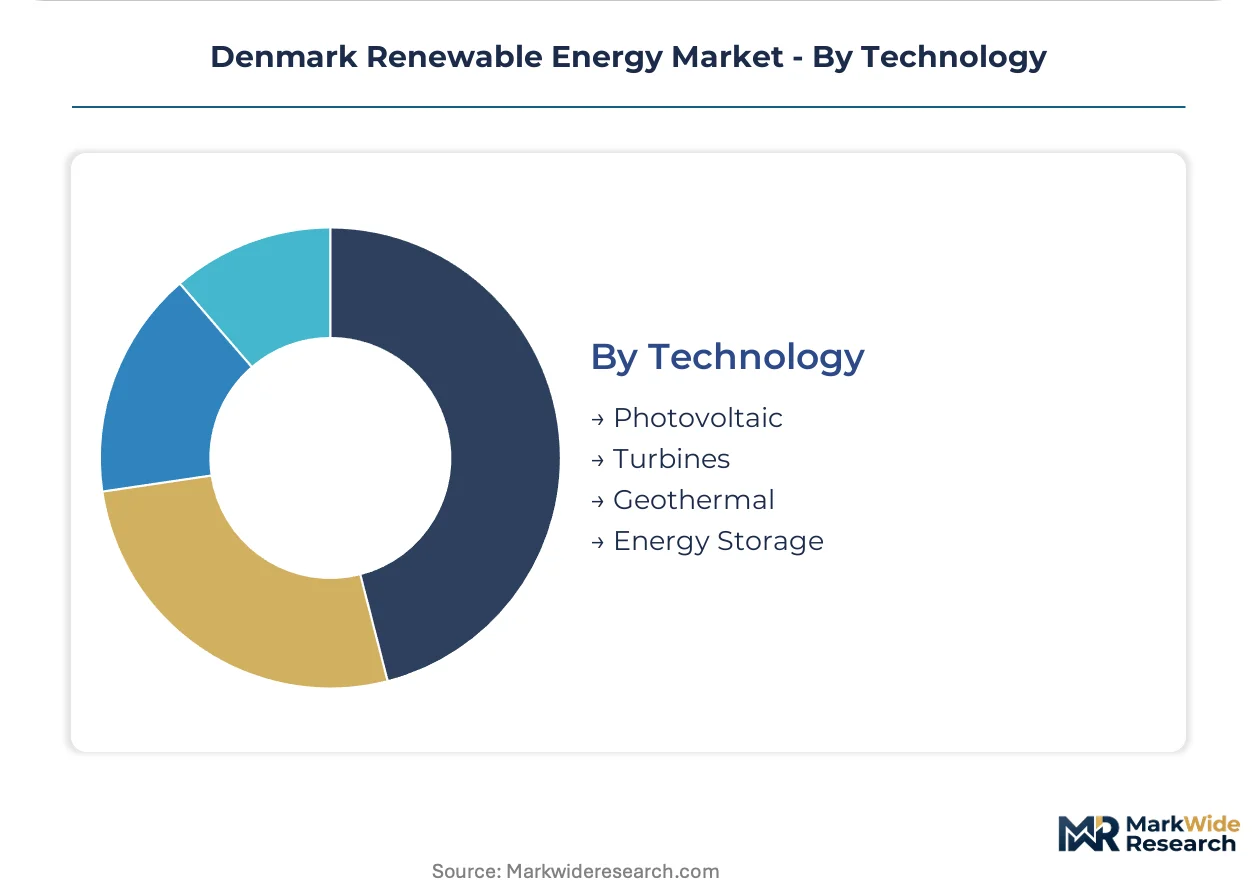
Technology:
Equipment specification trends favor larger turbine ratings and integrated storage configurations that capture ancillary service revenues.
- Photovoltaic:Crystalline silicon modules dominate utility-scale and distributed installations, with agrivoltaic systems gaining traction in Jutland farming regions.
- Turbines:Next-generation 15 MW offshore units with 22,000+ square meter swept areas displace 8-10 MW machines in North Sea project pipelines, compressing levelized cost trajectories.
- Geothermal:District heating networks in Thisted and Copenhagen explore deep drilling for baseload thermal supply, constrained by exploration risk and capital requirements.
- Energy Storage:Lithium-ion battery systems co-located with onshore wind farms in western Denmark capture frequency regulation revenues and defer transmission upgrade investments.
Turbine technology absorbs the dominant capital share; energy storage gains share fastest as grid balancing requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Capital deployment in Copenhagen and North Sea port clusters commands premium grid access terms, while Jutland agricultural regions absorb solar lease rates at 40% discounts to Zealand industrial zones. This pricing-power asymmetry shapes developer site selection and utility procurement strategies across Danish sub-regions.
Capital Region
Copenhagen's district heating networks drive biomass and heat pump substitution under Energy Agreement mandates. The Danish Energy Agency administers municipal tendering frameworks for public building retrofits. Ørsted A/S anchors offshore wind headquarters and grid interconnection planning in the metropolitan cluster.
North Denmark Region
Frederikshavn industrial zones anchor Power-to-X electrolyzer demand for green hydrogen feedstock. The EU F-Gas Regulation accelerates natural gas boiler replacements in Aalborg residential districts. Vestas Wind Systems maintains manufacturing and service operations across the northern Jutland wind corridor.
Central Denmark Region
Aarhus commercial facilities procure renewable electricity through corporate power purchase agreements bypassing utility tariffs. Energinet grid codes mandate frequency response capabilities for distributed generation installations. European Energy A/S competes for agricultural land leases in the western Jutland solar development zone.
Region of Southern Denmark
Odense biomass-fired combined heat and power plants supply district heating networks under fossil-fuel phase-out timelines. The Danish Climate Act imposes binding carbon reduction targets on regional utilities. Better Energy A/S secures rooftop solar deployments across Funen commercial and industrial facilities.
Region Zealand
Kalundborg industrial clusters negotiate 10-15 year bilateral contracts directly with offshore wind developers. Carlsberg and Novo Nordisk manufacturing operations drive procurement leverage in the eastern renewable energy corridor. Copenhagen Infrastructure Partners concentrates capital deployment in seabed lease auctions for Kriegers Flak zone developments.
Denmark Renewable Energy Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Danish renewable energy market. Offshore wind development concentrates among capital-heavy incumbents with proprietary installation vessel fleets and grid connection expertise, while distributed solar and Power-to-X segments fragment across specialized developers competing for land access and electrolyzer manufacturing scale. Three strategic archetypes dominate: integrated offshore developers, turbine manufacturers with domestic production footprints, and utility-scale solar specialists pursuing agrivoltaic lease structures. Competitive dynamics center on seabed lease auction participation and strategic partnerships for electrolyzer offtake agreements.
Among Copenhagen-based integrated developers, Ørsted A/S and Copenhagen Infrastructure Partners occupy positions exemplifying the capital-intensive offshore archetype, leveraging North Sea project pipelines and proprietary vessel access. Vestas Wind Systems anchors the manufacturing tier through its Ringkøbing production footprint and service network density. European Energy A/S represents the utility-scale solar and Power-to-X development vector, competing for grid queue positions against traditional wind incumbents in western Denmark interconnection backlogs.
| Leading Market Players |
|---|
| Arcon-Sunmark A/S |
| Siemens Gamesa Renewable Energy |
| Ørsted A/S |
| Copenhagen Infrastructure Partners |
| European Energy A/S |
| Vestas Wind Systems |
| Better Energy A/S |
| Aalborg CSP A/S |
| Vattenfall |
| Others |
Value Chain & Pricing Dynamics
Forty-five-day installation vessel charter lead-times concentrate pricing power among North Sea offshore developers with captive fleet access, while standard component procurement cycles compress margins for distributed solar installers competing on commodity module costs.
Pricing Analysis
The customization-premium spread separates Ørsted's proprietary vessel-deployed offshore projects from standardized onshore wind turbine transactions. Project-based long-term offtake contracts dominate, with price differentiation resting on foundation engineering complexity and grid connection certainty. Cost compression in utility-scale solar intensifies because Chinese module oversupply floods European markets. Agricultural cooperatives in Jutland exhibit highest price sensitivity, while Copenhagen industrial clusters prioritize delivery certainty over unit economics.
Supply Chain Analysis
Inventory buffers for rare earth magnets and high-voltage cable stretch to ninety days as Danish developers hedge Chinese export restriction exposure. Supply concentration centers on China for neodymium processing, South Korea for electrolyzer stack manufacturing, and Germany for specialized transformer production. The chain draws from copper concentrate, direct-drive generator assemblies, and PEM membrane electrode units. Single-source vulnerability in installation vessel chartering threatens project execution windows. Distribution runs through Esbjerg port consolidation points and Energinet grid interconnection queues.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized marine engineering talent and seabed lease auction participation rights constitute the binding constraints that separate deployable project pipelines from speculative development backlogs.
For Market Incumbents: Compound grid connection expertise through strategic hiring at Energinet and certification body alumni networks. Secure backward integration into foundation steel fabrication to capture margin pools threatened by European mill capacity constraints. Prioritize electrolyzer manufacturing partnerships in Frederikshavn before equipment supply queues extend beyond vessel availability windows. For New Entrants and Emerging Players: Differentiate on agrivoltaic system design that preserves Danish agricultural subsidy eligibility for host landowners. Target western Jutland solar deployment zones where grid queue positions remain accessible compared to North Sea offshore auction concentration. Pursue corporate power purchase agreement origination as the primary go-to-market channel, bypassing utility tariff intermediation. For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-transition play because fossil-fuel phase-out mandates create irreversible demand displacement. Acquisition candidates include mid-cap solar developers with secured land lease pipelines and electrolyzer engineering firms with Danish Energy Agency pre-certification. Monitor seabed lease auction participation rates as the inflection signal for offshore wind capital deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Electrolyzer Manufacturing Scale-Up | Anchor demand for surplus offshore wind generation attracts Maersk and fertilizer producer offtake commitments. |
| Power Purchase Agreement Origination | Carlsberg and Novo Nordisk bilateral contracts displace traditional utility green tariff procurement channels. |
| Agrivoltaic Lease Structure Innovation | Jutland farming cooperatives preserve crop production eligibility while hosting utility-scale photovoltaic arrays. |
| Installation Vessel Fleet Expansion | Specialized marine asset scarcity through 2027 forces premium charter rates or construction window delays. |
| Grid Interconnection Queue Positioning | Energinet technical assessment backlogs trap capital in pre-construction phases for western Denmark projects. |
Study Parameters
Initial hypotheses were tested against primary input from utility planning officers, IPP project developers, EPC contractors, and grid operators and refined through secondary validation against Danish Energy Agency auction records, Energinet transmission planning documents, EU ETS registry data, and customs trade statistics for wind turbine component imports. Bottom-up project pipeline enumeration triangulated against top-down capacity deployment targets under the Climate Act framework.
Variance decomposition across technology segments, project scale tiers, and regional grid configurations shaped the analytical framework over the projection horizon. CAGRs derived from installed capacity build-out trajectories, capacity factor assumptions for North Sea wind zones, and electrolyzer manufacturing cost curves. Specific inputs included seabed lease auction award timelines and F-Gas Regulation refrigerant phase-down enforcement schedules.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal funding commitment or Chinese rare earth export policy stability would require recalibration. Forecasts reflect documented assumptions regarding vessel fleet availability and grid reinforcement investment pacing. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Tidal Turbines Market
Renewable Energy
Solar Showers Market
Renewable Energy
Middle East Renewable Energy Market
Renewable Energy
Thailand Renewable Energy Market
Renewable Energy
Wave Energy Market
Renewable Energy
Japan Renewable Energy Market
Renewable Energy
Solar Bicycle Shed Market
Renewable Energy
Philippines Wind Energy Market
Renewable Energy
South America Renewable Energy Market
Renewable Energy
Solar Street Lighting Market
Renewable Energy
Spain Renewable Energy Market
Renewable Energy
Solar Autoclave Market
Renewable Energy
Africa Solar E-Bike Market
Renewable Energy
Renewable Energy Inverters Market
Renewable Energy
United States Renewable Energy Market
Renewable Energy
Russian Federation Renewable Energy Market