
 Variable Renewable Energy Market | 2026-2036
Variable Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Variable Renewable Energy Market Analytics
Utility procurement channels is reshaping competitive dynamics in variable renewable energy. Vestas Wind Systems leverages its offshore turbine specialization to anchor premium project pipelines across Northern Europe. GE Vernova sustains manufacturing scale in onshore wind through integrated nacelle assembly in North America. Siemens Energy competes on grid integration technology, positioning its power transmission systems as critical enablers for utility-scale solar and wind interconnection.
Variable renewable energy encompasses solar photovoltaic, wind turbine, hydroelectric, and biomass generation systems whose output fluctuates with weather conditions and requires grid balancing infrastructure. Modern wind turbines now exceed fifteen megawatts in rated capacity with rotor diameters surpassing two hundred meters, while bifacial solar modules capture reflected irradiance to boost yield by eight to twenty percent depending on albedo conditions. Solar PV dominates installed capacity globally due to module cost declines and distributed rooftop accessibility, though offshore wind commands higher margin pools per megawatt because of specialized installation vessels and subsea cable requirements. Grid Integration applications absorb the largest share of capital deployment as utilities modernize substations and deploy battery storage co-located with renewable assets.
The EU Green Deal and F-Gas Regulation mandate refrigerant phase-downs in grid-connected heat pumps and cooling systems tied to renewable microgrids, while the EPA enforces New Source Performance Standards for greenhouse gas emissions from modified power plants that accelerate coal-to-renewables switching in the United States. China's National Energy Administration enforces dual carbon goals through provincial renewable portfolio standards that mandate utility procurement quotas. Stakeholders must monitor evolving grid codes and interconnection queue reforms that determine project commercialization timelines and capital recovery profiles.
Market Dynamics
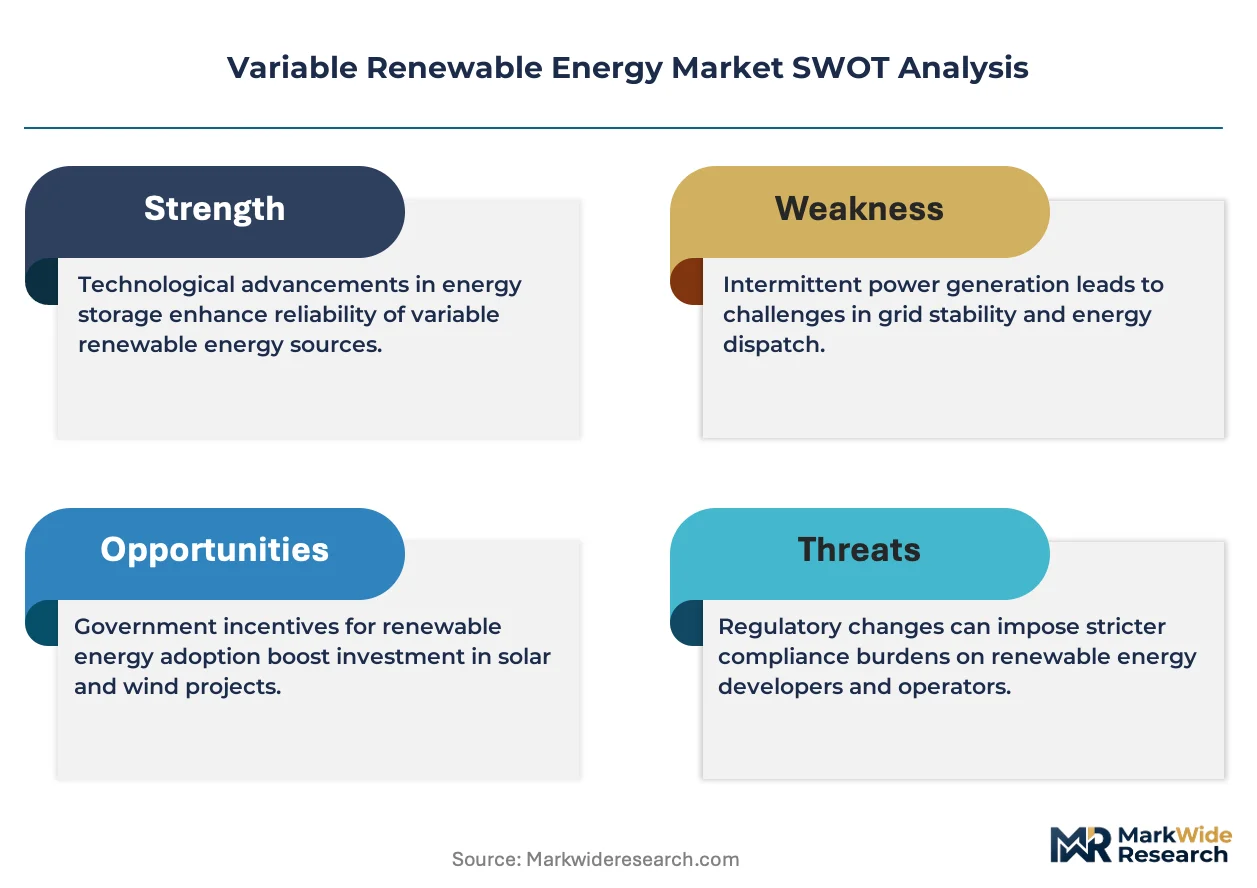
Grid interconnection queues stretching across multiple years are forcing developers to co-locate battery storage with solar and wind assets, transforming project economics and vendor selection criteria toward integrated system providers.
Growth Catalysts
- China's dual carbon goals:Provincial renewable portfolio standards mandate utility procurement quotas, accelerating wind-solar hybrid deployment across coastal provinces.
- Offshore wind specialization:Installation vessel fleets and subsea cable manufacturing capacity are concentrating in Northern Europe, creating dedicated supply corridors for gigawatt-scale projects.
- F-Gas Regulation:The EU mandate for refrigerant phase-downs in grid-connected heat pumps tied to renewable microgrids is accelerating heat pump-electrification convergence.
Market Restraints
- Critical mineral concentration:Rare earth processing for permanent magnet turbines concentrates in China, exposing non-Chinese turbine manufacturers to supply disruption risk.
- Interconnection timeline inflation:Grid operator study backlogs in the United States now extend project commercialization timelines beyond capital recovery windows assumed in original financing.
- Aluminum-copper volatility:Conductor raw material price swings compress EPC margins on transmission infrastructure builds required for remote renewable sites.
Strategic Opportunities
- India's green hydrogen mandate:National hydrogen mission targets create dedicated offtake for renewable curtailment, enabling merchant solar-wind hybrids without PPA dependency.
- Agrivoltaics expansion:Bifacial module deployment over agricultural land creates dual revenue streams for farmers in water-stressed regions of Spain and Italy.
- Corporate PPA aggregation:Energy attribute certificate bundling platforms are emerging as new procurement channels for mid-market commercial offtakers lacking direct utility relationships.
Industry Challenges
- Grid code harmonization:Inverter interoperability standards vary across Germany, Denmark, and the Netherlands, forcing manufacturers to maintain multiple firmware configurations.
- Specialized vessel scarcity:Heavy-lift installation ships for fifteen-megawatt turbines command day rates that consume twelve to eighteen percent of offshore project capex.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Variable Renewable Energy Market |
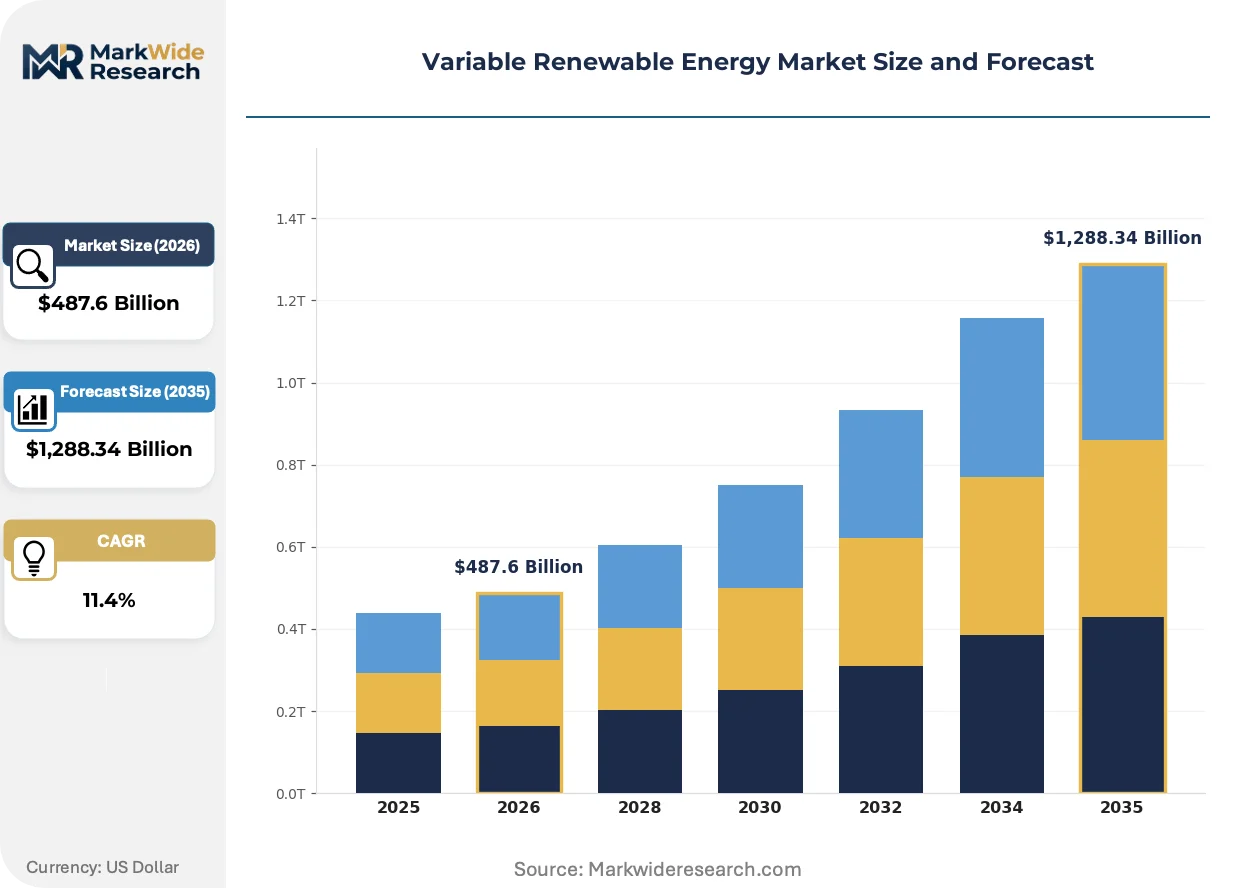
| Market Size in 2026 | $487.6 Billion |
| Market Size in 2035 | $1,288.34 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Solar PV, Wind Turbine, Hydro, Biomass Application: Grid Integration, Off-Grid Systems, Electric Mobility, Microgrids End User: Utilities, Commercial, Residential, Institutional Deployment: Onshore, Offshore, Rooftop, Ground-Mounted |
| Companies Covered | NextEra Energy, Vestas Wind Systems, GE Vernova, Orsted, Iberdrola, Enel, ACWA Power, Adani Green Energy, Siemens Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Variable Renewable Energy Market Evolving Landscape
Technology convergence between generation and storage assets is compressing project development timelines while regulatory pressure on refrigerants and grid codes is reshaping equipment specifications across major deployment zones.
Wind-solar hybrid control systems is hybridizing power forecasting and grid dispatch optimization. Utility procurement teams in Texas and California are specifying integrated assets in RFPs to reduce interconnection queue positions. This convergence is compressing vendor margins on standalone equipment sales while expanding service contract attach rates.
The EU F-Gas Regulation mandates refrigerant phase-downs in grid-connected heat pumps and cooling systems tied to renewable microgrids. Industrial consequence includes accelerated R&D spending on natural refrigerant architectures by HVAC manufacturers serving the building electrification segment. Germany's heat pump sector is responding with CO2-based systems that maintain efficiency at low ambient temperatures.
Long-term service agreements are displacing traditional equipment-only sales in utility procurement. Independent power producers in Australia and the United Kingdom are unbundling O&M from EPC contracts to retain operational control. This shift is most visible in offshore wind, where twenty-year service contracts now exceed turbine hardware value in total contract value.
Variable Renewable Energy Market Segmentation
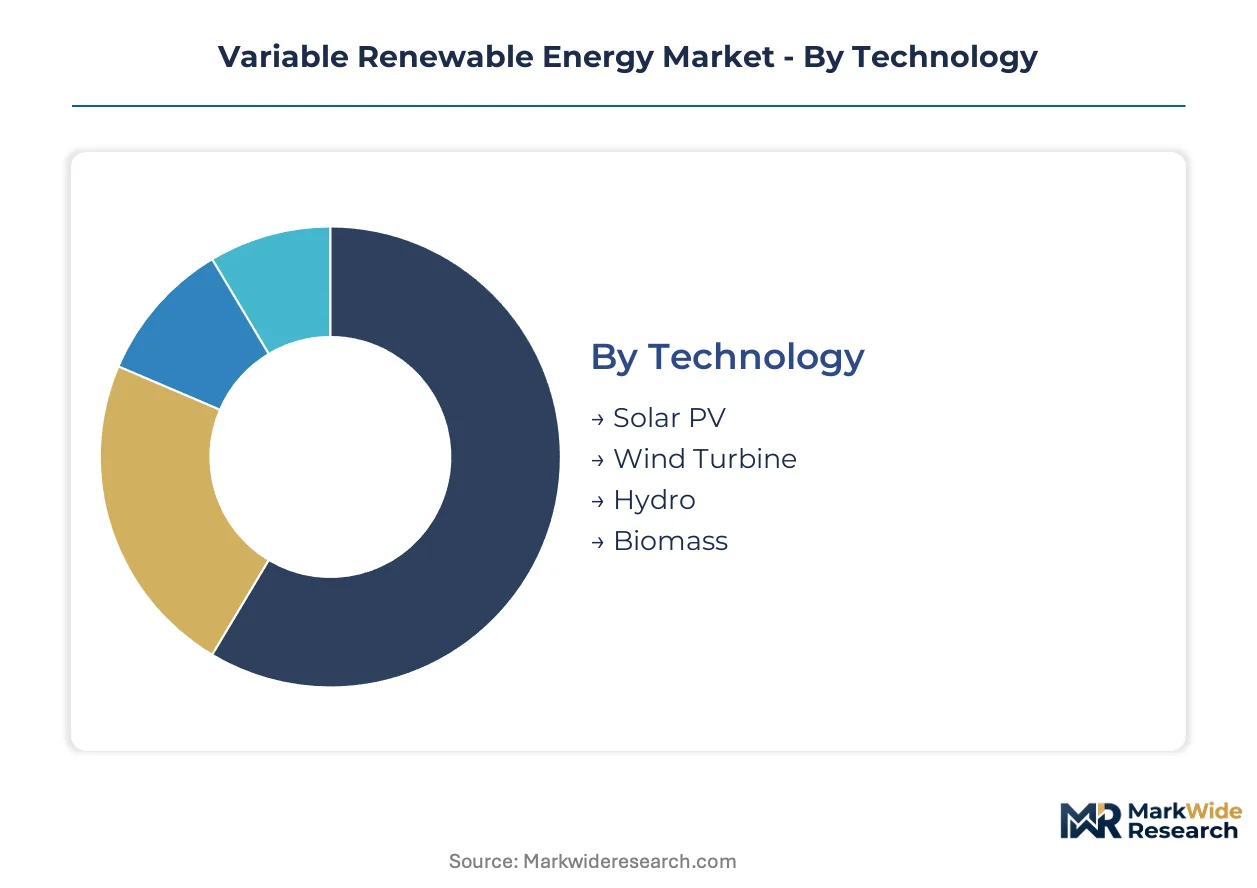
Technology heterogeneity in variable renewable energy creates distinct supply chains, capital intensity profiles, and regulatory exposure. Each segment demands specialized installation expertise and grid interconnection protocols that shape vendor selection and project economics.
Technology:
Cost tier stratification separates capital-light distributed assets from infrastructure-heavy centralized generation.
- Solar PV:Crystalline silicon modules with bifacial architectures capture reflected irradiance to boost yield. Module cost declines concentrate demand in China's provincial renewable portfolio standards and India's green hydrogen corridors.
- Wind Turbine:Horizontal-axis systems with permanent magnet direct-drive generators exceed fifteen megawatt ratings offshore. Northern European installation vessel fleets and subsea cable manufacturing create dedicated supply corridors for gigawatt-scale projects.
- Hydro:Run-of-river configurations dominate small-scale deployment without reservoir requirements.
- Biomass:Combustion and anaerobic digestion systems serve agricultural waste feedstock regions.
Solar PV commands the established base. The steepest expansion runs through Wind Turbine.
Application:
Application scope determines interconnection complexity and revenue model structure.
- Grid Integration:Utility-scale substation modernization and transmission infrastructure absorb the largest capital deployment. FERC interconnection queue reforms in the United States and EU grid code harmonization efforts reshape equipment specifications.
- Off-Grid Systems:Standalone battery-coupled solar serves remote industrial loads and rural electrification. Sub-Saharan African mining operations and Southeast Asian island communities drive procurement.
- Electric Mobility:Charging infrastructure powered by renewable microgrids supports fleet electrification mandates.
- Microgrids:Campus-scale distributed generation with islanding capability serves critical facility resilience requirements.
Grid Integration anchors current investment. The fastest volume gains emerge in Electric Mobility.
End User:
Customer type dictates procurement scale, contract duration, and financing structure.
- Utilities:Vertically integrated power providers with twenty-year asset horizons dominate offshore wind and utility-scale solar. China's National Energy Administration provincial quotas and United States state renewable portfolio standards mandate procurement volumes.
- Commercial:Corporate PPA aggregation platforms serve mid-market offtakers lacking direct utility relationships. Energy attribute certificate bundling creates new procurement channels.
- Residential:Distributed rooftop solar with net metering tariffs.
- Institutional:University and hospital microgrids with resilience requirements.
Utilities retain the dominant share. Commercial segments are gaining share fastest.
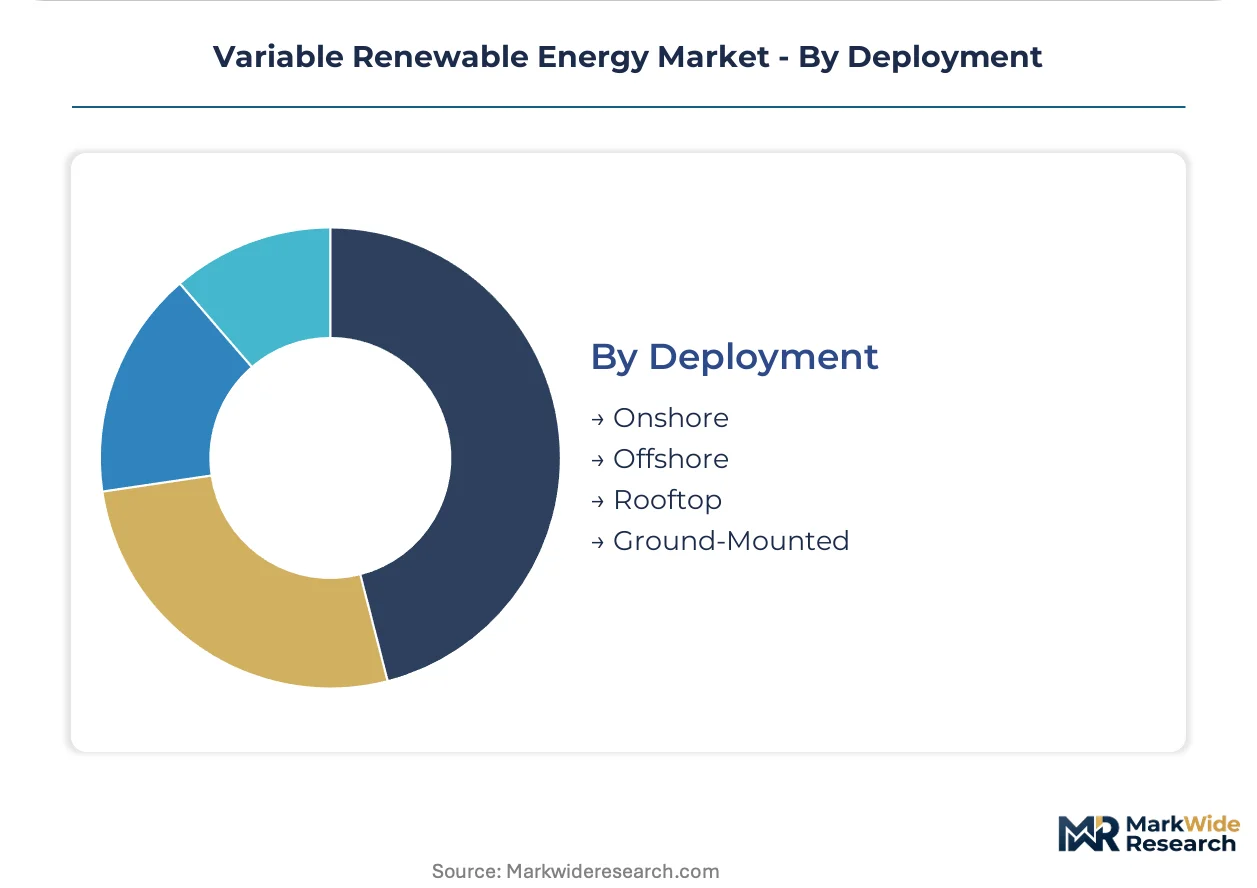
Deployment:
Physical siting determines labor requirements, permitting pathways, and equipment specifications.
- Onshore:Terrestrial wind farms and ground-mounted solar arrays with established EPC workflows. Texas and California utility procurement teams specify hybrid assets to compress interconnection queue positions.
- Offshore:Subsea foundation installation and specialized heavy-lift vessels command twelve to eighteen percent of project capex. Installation vessel day rate scarcity constrains Northern European project timelines.
- Rooftop:Distributed solar with simplified permitting and behind-the-meter economics.
- Ground-Mounted:Utility-scale solar with tracking systems and agrivoltaics dual-use potential.
Onshore deployment holds the installed base. Offshore deployment shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
National renewable portfolio standards and dual carbon mandates are redirecting utility procurement across major deployment zones. Subsidies for offshore wind and agrivoltaics are concentrating investment in coastal provinces and Mediterranean agricultural regions.
China
Provincial renewable portfolio standards in Jiangsu and Guangdong mandate utility procurement quotas for wind-solar hybrid projects. The National Energy Administration enforces dual carbon goals through provincial renewable portfolio standards that mandate utility procurement quotas. The Yangtze River Delta hosts gigawatt-scale offshore wind fabrication yards serving domestic and export markets.
United States
State-level renewable portfolio standards in Texas and California drive utility-scale solar and wind deployment with hybrid asset specifications. FERC interconnection queue reforms and EPA New Source Performance Standards accelerate coal-to-renewables switching. The ERCOT grid in Texas leads merchant solar-wind hybrid development without long-term PPA dependency.
Germany
The EU Green Deal and F-Gas Regulation mandate refrigerant phase-downs in grid-connected heat pumps tied to renewable microgrids. Grid code harmonization efforts with Denmark and the Netherlands reshape inverter interoperability standards. Northern German ports host specialized heavy-lift installation vessels for fifteen-megawatt offshore turbines.
India
The national hydrogen mission targets create dedicated offtake for renewable curtailment from merchant solar-wind hybrids. Central Electricity Authority mandates and state-level renewable purchase obligations drive deployment in Gujarat and Rajasthan. The Khavda renewable energy park in Gujarat concentrates gigawatt-scale solar-wind hybrid capacity with green hydrogen integration.
Spain
Agrivoltaics expansion with bifacial module deployment over agricultural land creates dual revenue streams in water-stressed regions. EU F-Gas Regulation compliance accelerates natural refrigerant heat pump adoption in building electrification. Extremadura and Andalusia host utility-scale solar tracking systems with agricultural co-use permits.
Variable Renewable Energy Market Competitive Landscape
On the supply side, the industry is consolidating around integrated system providers capable of delivering generation-plus-storage solutions. Turbine manufacturers, solar module producers, and grid technology vendors now compete on total project economics rather than equipment-only pricing. Two strategic archetypes dominate: offshore wind specialists with vessel and subsea cable capabilities, and hybrid system integrators bundling solar, wind, and battery assets. Competitive moves center on long-term service contract unbundling and geographic expansion into hydrogen-linked renewable corridors.
Among European offshore wind specialists, Vestas Wind Systems and Orsted occupy positions exemplifying the premium-project archetype through Northern European gigawatt-scale development. Siemens Energy sits within the grid integration tier, anchoring power transmission systems as critical enablers for utility-scale interconnection. GE Vernova represents the North American manufacturing-scale archetype through integrated nacelle assembly serving onshore wind procurement.
| Leading Market Players |
|---|
| NextEra Energy |
| Vestas Wind Systems |
| GE Vernova |
| Orsted |
| Iberdrola |
| Enel |
| ACWA Power |
| Adani Green Energy |
| Siemens Energy |
| Others |
Value Network & Pricing Analysis
The Shanghai-Rotterdam maritime corridor's freight cost volatility compresses margins on turbine nacelles and solar module imports, concentrating pricing power with integrated manufacturers who control both fabrication and logistics networks while forcing project developers toward long-term offtake contracts that lock in equipment delivery premiums.
Pricing Analysis
Performance tier certification creates the primary spread between offshore wind and distributed solar assets. Project-based contract structures dominate, with price differentiation anchored in turbine capacity ratings and module efficiency grades. Cost compression in utility-scale solar intensifies because Chinese provincial quotas flood procurement channels with bifacial supply. Commercial offtakers exhibit highest price sensitivity, while utilities with mandated renewable portfolio obligations absorb premium tiering for grid-scale assets.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk assessment for permanent magnet turbines. Rare earth processing concentrates in China, with neodymium magnet fabrication and blade composite manufacturing drawing from concentrated coastal provinces. Single-source vulnerability in heavy-lift installation vessel fleets constrains Northern European project timelines. Distribution runs through EPC contractors who bundle generation assets with grid interconnection infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Variable renewable energy constitutes a high-growth disruption propelled by the EU F-Gas Regulation's refrigerant phase-down mandate, which forces HVAC-electrification convergence and expands addressable demand for grid-connected heat pump infrastructure.
For Market Incumbents: Entrench offshore wind positions through captive installation vessel fleets and subsea cable manufacturing capacity. Vestas and Orsted archetypes must defend against hybrid system integrators bundling solar-wind-storage assets by deepening service contract attach rates. Vertical integration into power forecasting software preserves margin pools as equipment-only sales erode.
For New Entrants and Emerging Players: Establish a beachhead in India's green hydrogen corridors where national hydrogen mission targets create dedicated offtake for renewable curtailment. Agrivoltaics deployment in Spain and Italy offers penetrable white-space with dual-use permitting pathways. Pursue corporate PPA aggregation platforms as the primary go-to-market angle for mid-market commercial offtakers lacking direct utility relationships.
For Investors and Strategic Acquirers: The EU Green Deal's grid code harmonization mandates reshape the acquisition landscape toward inverter interoperability specialists and battery storage system integrators. Long-term viability frames around five-to-ten year service contract visibility rather than equipment shipment volumes. Target acquisition archetypes include hybrid control system vendors with utility-scale project references. Monitor FERC interconnection queue reform implementation as the signal indicating project commercialization timeline compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Offshore Wind Capacity Buildout | Gigawatt-scale projects in Northern European waters anchor long-term service revenue streams. |
| Power Purchase Agreement Structuring | Merchant solar-wind hybrids in ERCOT reduce PPA dependency while capturing price volatility upside. |
| Technology Licensing for Bifacial Modules | Yield enhancement architectures transfer to agrivoltaics deployments in water-stressed Mediterranean regions. |
| Vertical Integration into Battery Storage | Co-located assets compress interconnection queue positions and transform vendor selection criteria. |
| Green Certification Program | Energy attribute certificate bundling platforms unlock mid-market commercial procurement channels. |
Research Methodology
Operator-level perspectives from utility planning officers, IPP project developers, EPC contractors, and grid operators anchored the qualitative base. Primary interviews combined with secondary validation from EIA data, IEA reports, FERC filings, and project development databases. Bottom-up capacity installation tracking and top-down policy mandate analysis enabled triangulation across modeling approaches.
Scenario-bracketing framed the analytical approach across the projection horizon. Segmentation dimensions spanned technology type, deployment configuration, application scope, and regional regulatory framework. CAGRs derived from capacity deployment trajectories, equipment cost curves, and interconnection timeline assumptions. Industry-specific forecast inputs included installation vessel fleet utilization rates and provincial renewable portfolio standard enforcement intensity.
Stress conditions across commodity price volatility, interconnection queue duration, and tariff regime shifts were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about policy continuity and technology cost reduction trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Middle East Renewable Energy Market
Renewable Energy
Australia Renewable Energy Market
Renewable Energy
Point Absorber Market
Renewable Energy
Africa Renewable Energy Market
Renewable Energy
Malaysia Renewable Energy Market
Renewable Energy
Kazakhstan Renewable Energy Market
Renewable Energy
South Africa Solar Photovoltaic (PV) Market
Renewable Energy
Solar Thermal Water Heater Market
Renewable Energy
Russian Federation Renewable Energy Market
Renewable Energy
Solar Drying System Market
Renewable Energy
Solar PV and Wind Energy Market
Renewable Energy
Solar Showers Market
Renewable Energy
Canada Renewable Energy Market
Renewable Energy
Solar Boat Market
Renewable Energy
Hybrid Power System Market
Renewable Energy
Solar Panel Mounting Structure Market