
 Geothermal Energy Market | 2026-2036
Geothermal Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Geothermal Energy Market Analysis
Electric utility procurement is decoupling from pure solar-wind portfolios as grid operators prioritize dispatchable clean capacity. Ormat Technologies leverages its vertical equipment-manufacturing footprint to sustain cost advantages across binary and flash plant deployments. Mitsubishi Heavy Industries anchors Asian supply chains through specialized turbine fabrication for high-enthalpy resources.
Geothermal energy harnesses subsurface heat from hydrothermal reservoirs, hot dry rock, or geopressured formations to drive turbines or supply direct thermal applications, with reservoir temperatures typically ranging from 150°C to 300°C for electricity generation. Binary cycle technology dominates new installations where moderate-temperature fluids prevail, while Enhanced Geothermal Systems represent the fastest-expanding technology segment as engineered reservoir creation unlocks previously inaccessible resources. Flash steam installations retain the largest installed base globally but face margin compression in markets where binary units achieve lower parasitic load.
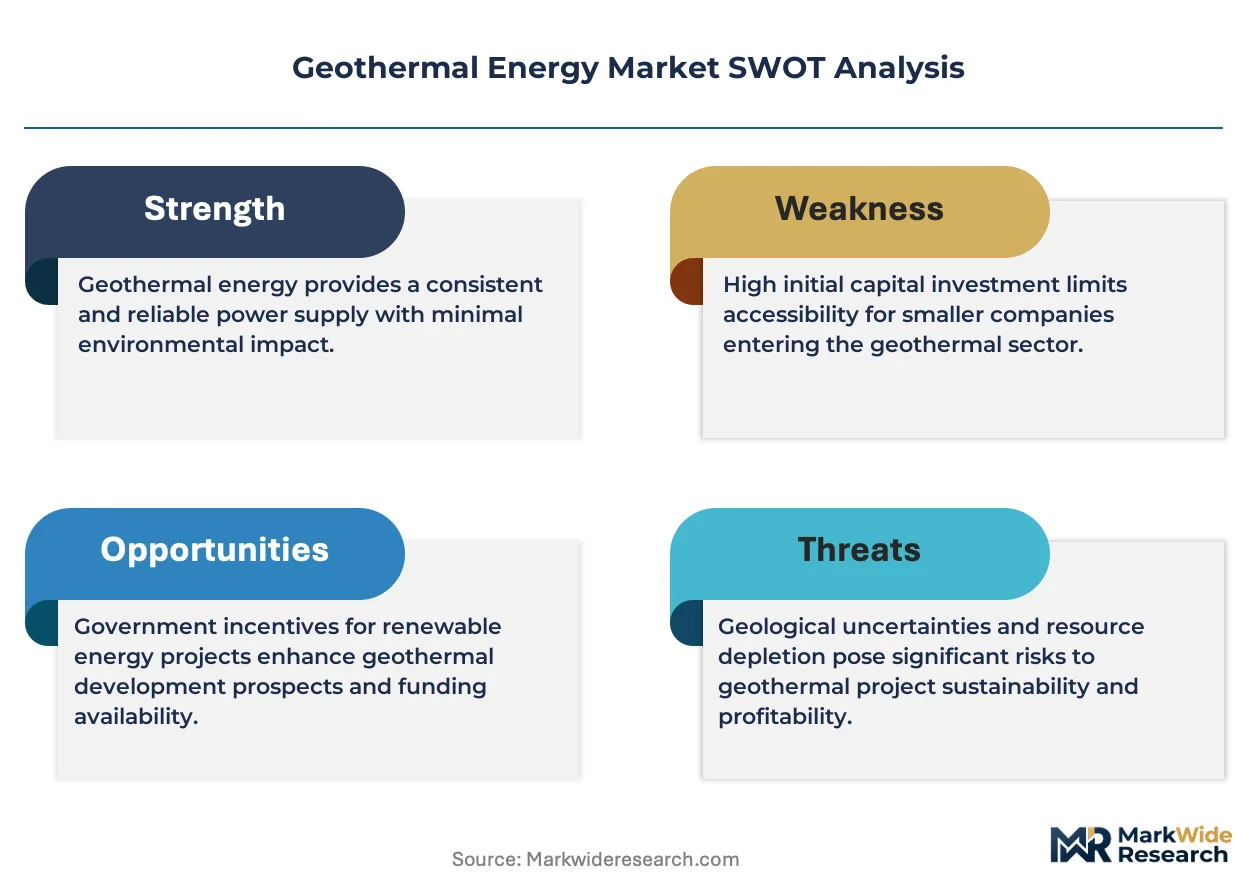
The U.S. Department of Energy, Indonesia's Ministry of Energy and Mineral Resources, and Kenya's Energy and Petroleum Regulatory Authority each shape project economics through resource risk mitigation programs, feed-in tariff structures, and drilling cost guarantees. The EU Green Deal and F-Gas Regulation additionally constrain working fluid choices in European binary plants, redirecting technology selection toward lower-global-warming-potential alternatives. Stakeholders must monitor regulatory shifts around subsurface mineral rights and induced seismicity protocols that could accelerate or arrest project timelines in high-growth basins.
Market Dynamics
Grid operators across Southeast Asia are rewriting procurement protocols to prioritize firm renewable capacity over intermittent solar-wind portfolios, forcing developers to demonstrate dispatchability guarantees before securing power purchase agreements. This structural pivot toward baseload reliability is compressing project timelines and reshaping technology selection criteria.
Growth Catalysts
- EU Green Deal innovation grants:European funding streams are de-risking Enhanced Geothermal Systems pilot projects, accelerating engineered reservoir creation in previously inaccessible geological formations.
- Indonesia's feed-in tariff structures:The Ministry of Energy and Mineral Resources guarantees long-term electricity pricing, attracting private capital to high-enthalpy development in the Ring of Fire corridor.
- Binary cycle technology maturation:Moderate-temperature fluid utilization is expanding economically viable resource bases beyond traditional volcanic zones into sedimentary basins.
Market Restraints
- Drilling cost volatility:Steel alloy prices and specialized rig availability fluctuate with oilfield service cycles, exposing geothermal projects to input cost spikes unrelated to electricity markets.
- Induced seismicity protocols:Subsurface injection regulations in seismically active zones impose operational pauses and monitoring burdens that extend commissioning schedules.
- Working fluid constraints:The EU F-Gas Regulation restricts hydrofluorocarbon use in binary plants, forcing retrofits or alternative refrigerant adoption with lower thermodynamic efficiency.
Strategic Opportunities
- Kenya's drilling cost guarantees:The Energy and Petroleum Regulatory Authority absorbs exploration risk, opening the East African Rift to accelerated private development.
- Direct thermal applications:Greenhouse agriculture and district heating networks in Turkey's Aegean region present offtake diversification beyond electricity-only revenue models.
- Closed-loop systems convergence:Integration with advanced materials and horizontal drilling techniques from shale extraction is unlocking hot dry rock resources without hydraulic stimulation.
Industry Challenges
- Reservoir engineering talent scarcity:Geoscientists capable of integrating geophysics, thermodynamics, and drilling operations command premium compensation, constraining project staffing velocity.
- Legacy grid interconnection queues:Transmission access timelines in Indonesia's Java-Bali system delay commercial operation dates by 18-36 months beyond plant completion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Geothermal Energy Market |
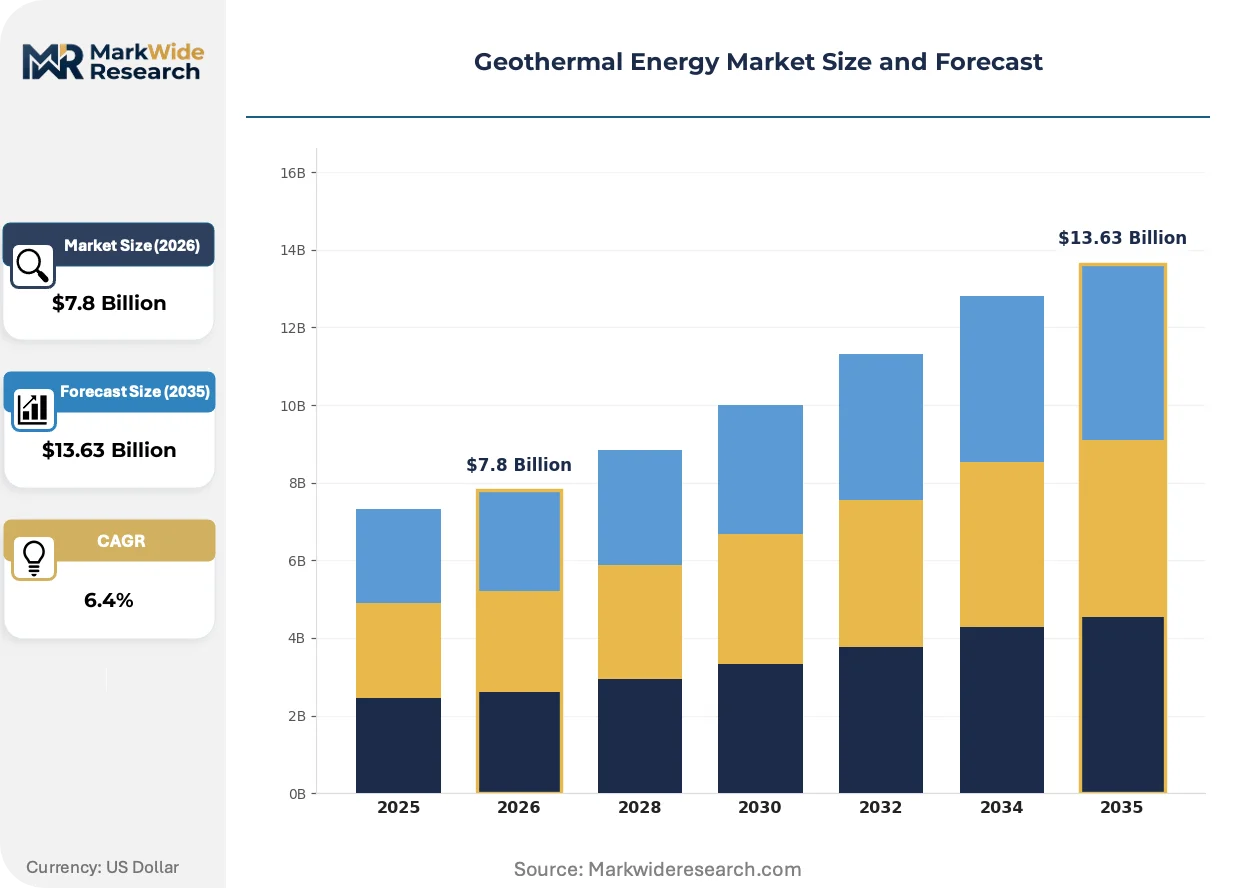
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Binary Cycle, Flash Steam, Dry Steam, Enhanced Geothermal Systems Application: Power Generation, Direct Use, Heat Pumps, Industrial Heating End User: Electric Utilities, Residential, Commercial, Industrial Installation: Onshore, Offshore, District Heating, Standalone Systems |
| Companies Covered | Ormat Technologies, Mitsubishi Heavy Industries, Calpine Corporation, Enel Green Power, Turboden S.p.A., Toshiba Energy Systems & Solutions Corporation, Atlas Copco Group, Exergy, General Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Geothermal Energy Market Emerging Trajectories
Technology trajectories in geothermal development are converging on engineered solutions that bypass traditional hydrothermal dependency, while regulatory frameworks increasingly embed climate performance into equipment standards and project finance structures.
Closed-loop geothermal systems are decentralizing project siting by eliminating the need for natural hydrothermal reservoirs. These systems circulate working fluid through sealed boreholes, enabling development in geologically stable regions previously dismissed as non-viable. Rural electric cooperatives in the US Midwest are piloting deployments near agricultural load centers, compressing transmission buildout requirements and accelerating permitting timelines relative to conventional flash plants.
The EU F-Gas Regulation is tightening working fluid specifications for binary cycle installations, mandating transition to lower-global-warming-potential alternatives by specified phase-out deadlines. Equipment manufacturers are redesigning heat exchanger configurations and turbine specifications to accommodate propane and ammonia blends with altered thermodynamic properties. European binary plant operators face retrofit decisions or new-build technology selection that prioritizes refrigerant compliance over legacy efficiency metrics.
Utility procurement departments are unbundling after-sales service contracts from equipment supply agreements, forcing technology providers to compete on operational performance guarantees rather than upfront capital cost. This behavioral shift is most pronounced in Turkey's competitive tender environment, where state-backed generators now require 15-year availability warranties and predictive maintenance integration as standard bid components, displacing traditional EPC lump-sum contracting.
Geothermal Energy Market Segmentation
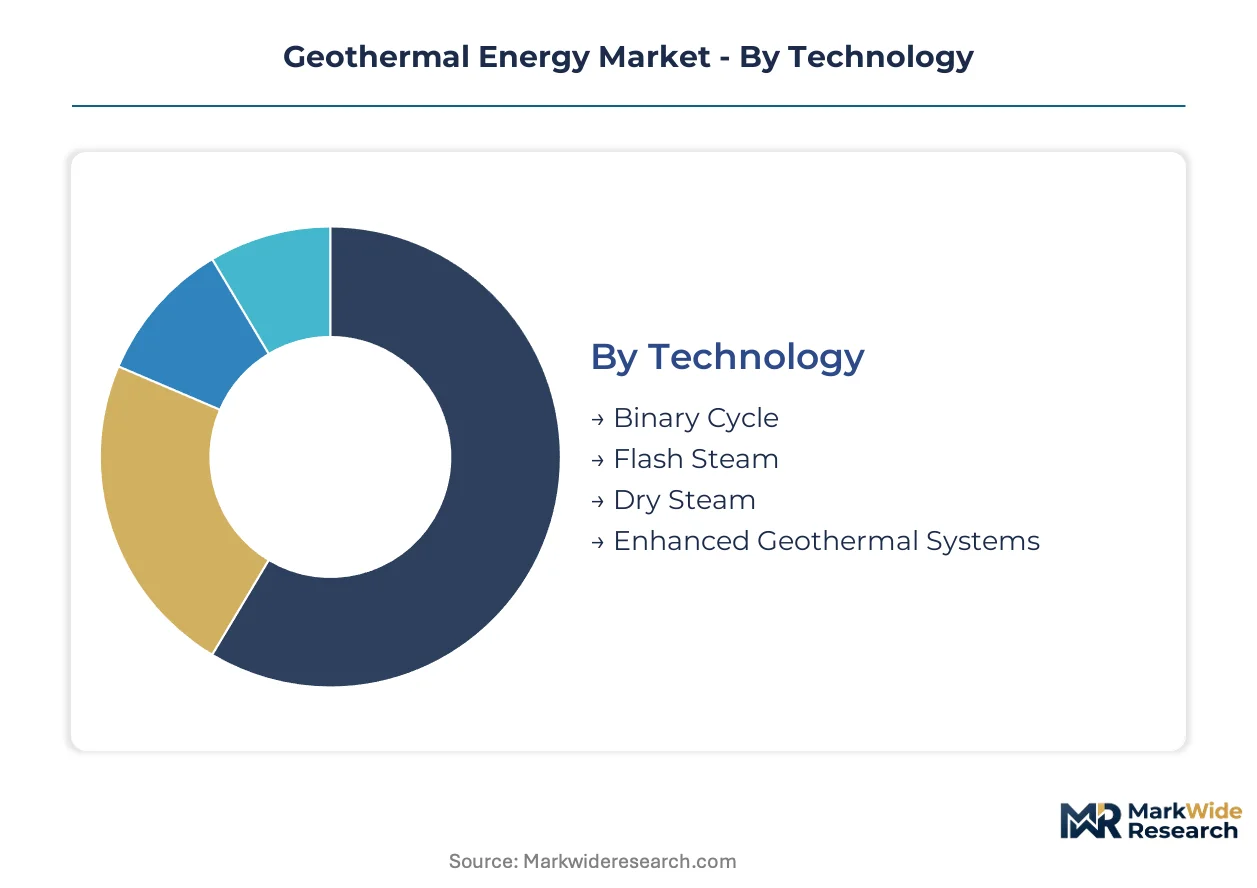
Technology selection dictates project economics across temperature gradients and geological formations. Application mix determines revenue stability through electricity sales versus thermal offtake contracts. End-user concentration shapes financing structures and risk allocation between developers and offtakers.
Technology:
Binary cycle configurations extract energy from moderate-temperature reservoirs through secondary working fluid loops, expanding addressable resource bases beyond volcanic zones.
- Binary Cycle:Closed-loop systems circulate organic working fluids through heat exchangers to drive turbines at temperatures as low as 74°C. Sedimentary basins in Turkey's Aegean region and Germany's Upper Rhine Valley deploy these units where hydrothermal fluids lack flash conditions. The EU F-Gas Regulation is forcing refrigerant transitions to propane and ammonia blends with altered thermodynamic efficiency profiles.
- Enhanced Geothermal Systems:Engineered reservoirs created through hydraulic stimulation or directional drilling unlock hot dry rock formations without natural permeability. The U.S. Department of Energy's FORGE program and European Green Deal innovation grants are de-risking pilot projects in Utah and the Upper Rhine Graben. These installations carry higher capital intensity but eliminate surface manifestation requirements that constrain conventional siting.
- Flash Steam:High-enthalpy reservoirs above 180°C flash pressurized brine into steam for direct turbine drive. Indonesia's Wayang Windu and Kenya's Olkaria fields anchor the global installed base.
- Dry Steam:Rare natural steam reservoirs at The Geysers in California and Larderello in Italy supply the oldest operating plants with minimal surface equipment.
Mature deployment sits with Flash Steam. Newer deployment is concentrated in Enhanced Geothermal Systems.
Application:
Revenue models diverge between electricity markets with merchant price exposure and thermal contracts with indexed heat pricing.
- Power Generation:Baseload electricity sales through long-term power purchase agreements dominate project finance structures. Grid operators in Indonesia and the Philippines prioritize dispatchable renewable capacity over intermittent solar-wind portfolios, rewriting procurement protocols to require firm output guarantees.
- Direct Use:Greenhouse agriculture, aquaculture, and mineral drying applications consume thermal energy without electricity conversion losses. Iceland's Reykjanes Peninsula and Turkey's Afyonkarahisar district demonstrate district-scale thermal distribution networks.
- Heat Pumps:Ground-source systems exploit shallow geothermal gradients for building climate control, with residential installations concentrated in suburban developments across the US Midwest.
- Industrial Heating:Process heat for food processing, pulp drying, and chemical manufacturing commands premium pricing in markets with carbon border adjustments.
Power Generation commands the largest capital deployment. Heat Pumps are expanding most quickly in building sector decarbonization programs.
End User:
Counterparty credit quality and contract duration vary sharply across customer categories, with utilities offering 20-30 year tenors against 5-10 year commercial terms.
- Electric Utilities:State-owned generators in Indonesia and Kenya absorb resource risk through drilling cost guarantees and feed-in tariff structures. Procurement departments now unbundle after-sales service from equipment supply, demanding 15-year availability warranties as standard.
- Industrial:Mining operations, data centers, and manufacturing facilities seek behind-the-meter generation to hedge volatile grid pricing.
- Commercial:Hotels, hospitals, and agricultural processors favor direct thermal applications with lower capital requirements than electricity generation.
- Residential:Distributed heat pump installations scale through utility rebate programs and building code mandates in California and New York.
Electric Utilities anchor project finance capacity. Industrial offtake is climbing fastest as energy-intensive sectors pursue Scope 2 emissions reductions.
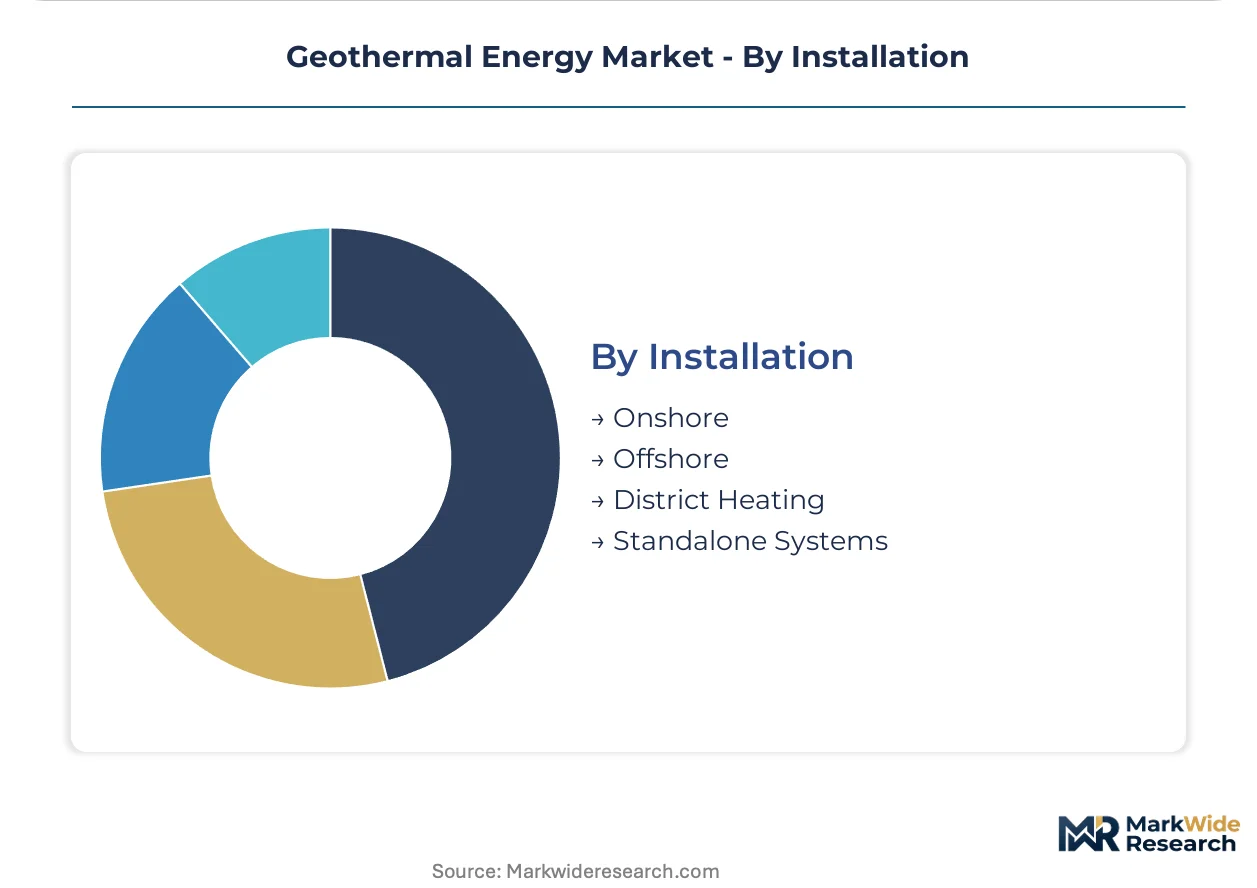
Installation:
Siting constraints and interconnection timelines create divergent development risk profiles across deployment configurations.
- Onshore:Conventional hydrothermal development concentrates along volcanic belts and tectonic rift zones. Indonesia's Java-Bali grid faces 18-36 month transmission queue delays beyond plant completion.
- District Heating:Centralized thermal distribution networks in Reykjavik and Paris leverage existing pipeline infrastructure to aggregate building-level demand.
- Standalone Systems:Modular binary units and closed-loop installations serve isolated loads without grid interconnection, compressing permitting timelines.
- Offshore:Submarine hydrothermal vent exploitation remains experimental, with no commercial installations operating.
Onshore deployment holds the operational base. District Heating networks are gaining share fastest in European building retrofit programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's geothermal acceleration zones along the Ring of Fire corridor concentrate development capital through Ministry of Energy and Mineral Resources feed-in tariff guarantees, drawing private developers to Java and Sumatra.
Indonesia
State utility PLN rewrites procurement protocols to prioritize firm baseload capacity over intermittent renewables, mandating dispatchability guarantees in power purchase agreements. The Ministry of Energy and Mineral Resources underwrites exploration risk through drilling cost guarantees and standardized feed-in tariffs. The Wayang Windu field in West Java anchors high-enthalpy flash steam deployment, while binary cycle projects expand into sedimentary basins in Sumatra's southern provinces.
United States
Electric utilities in California and Nevada seek carbon-free baseload alternatives to retiring coal units, expanding renewable portfolio standard compliance pathways. The Department of Energy's FORGE program in Utah de-risks Enhanced Geothermal Systems through directed research funding and testbed infrastructure. The Geysers field in northern California remains the world's largest dry steam installation, while closed-loop pilots emerge in the Great Basin region.
Kenya
Kenya Power and Lighting Company absorbs transmission interconnection risk for new geothermal capacity, accelerating grid integration timelines. The Energy and Petroleum Regulatory Authority guarantees drilling cost coverage for exploration phases, reducing developer capital exposure. The Olkaria complex in the Great Rift Valley hosts Africa's largest geothermal fleet, with expansion drilling targeting the Menengai caldera for binary cycle additions.
Turkey
Industrial processors in the Aegean region seek process heat contracts to hedge natural gas price volatility, diversifying revenue beyond electricity sales. The Renewable Energy Law establishes purchase guarantees and license simplifications for geothermal developers. The Afyonkarahisar district hosts concentrated binary cycle deployment, while district heating networks expand across Izmir's metropolitan area.
Philippines
Manila Electric Company and provincial cooperatives prioritize indigenous renewable resources to reduce liquefied natural gas import dependence. The Department of Energy streamlines permitting timelines for renewable energy service contracts in volcanic zones. The Tiwi-MakBan corridor in southern Luzon concentrates flash steam capacity, while Palawan island pilots modular binary units for isolated grid segments.
Geothermal Energy Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated technology providers commanding premium positioning in high-enthalpy flash installations while modular binary suppliers penetrate sedimentary basin opportunities. Equipment fabrication concentrates among turbine specialists, drilling contractors, and heat exchanger fabricators with complementary rather than overlapping capabilities. Three archetypes dominate: vertically integrated EPC firms, component-focused technology licensors, and regional project developers with captive equipment sourcing. Consolidation pressure operates through strategic partnerships between turbine manufacturers and drilling service providers, plus technology licensing agreements that transfer binary cycle know-how to local fabrication facilities.
Among established technology providers, Ormat Technologies exemplifies the integrated EPC archetype through captive manufacturing of binary cycle equipment and direct project ownership. Mitsubishi Heavy Industries anchors Asian supply chains through specialized turbine fabrication capabilities for high-temperature resource conditions. General Electric occupies a position bridging industrial equipment breadth with power generation system integration, representing the diversified conglomerate model in geothermal infrastructure deployment.
| Leading Market Players |
|---|
| Ormat Technologies |
| Mitsubishi Heavy Industries |
| Calpine Corporation |
| Enel Green Power |
| Turboden S.p.A. |
| Toshiba Energy Systems & Solutions Corporation |
| Atlas Copco Group |
| Exergy |
| General Electric |
| Others |
Supply Flow & Price Mechanics
Utility procurement departments unbundling after-sales service contracts from equipment supply agreements are forcing technology providers to compete on operational performance guarantees rather than upfront capital cost, compressing margins for manufacturers unable to demonstrate long-term availability warranties. This behavioral shift is redirecting supply chain investment toward predictive maintenance capabilities and captive service networks.
Pricing Analysis
Lead-time premiums for specialized drilling rigs and turbine components command substantial markups over standard delivery schedules, while spot-market steel alloy purchases expose developers to commodity volatility. Project-based long-term offtake contracts dominate financing structures, with price differentiation driven by resource temperature grade and grid interconnection proximity. Cost compression in binary cycle equipment is intensifying as modular suppliers penetrate sedimentary basins. Industrial offtakers exhibit highest price sensitivity due to behind-the-meter generation alternatives, while state-backed utilities absorb premium pricing for dispatchability guarantees.
Supply Chain Analysis
Specialized turbine fabrication rests on Japanese and German precision manufacturing capabilities, while drilling rig supply draws from U.S. and Chinese oilfield service sectors. Critical inputs include nickel-based superalloys for high-temperature turbine blades, precision-forged steel for wellhead equipment, and organic working fluids constrained by EU F-Gas Regulation phase-out schedules. Single-source vulnerability concentrates in advanced geothermal turbine engineering expertise. Distribution runs through EPC contractors with captive equipment sourcing relationships to project developers in Indonesia, Kenya, and Turkey.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The geothermal sector sits in a technology-transition phase as Enhanced Geothermal Systems displace traditional hydrothermal dependency through engineered reservoir creation, while binary cycle maturation unlocks moderate-temperature resources previously dismissed as uneconomic.
For Market Incumbents: Cement market position by deepening backward integration into precision turbine casting and expanding captive drilling service capacity in the East African Rift. Resource engineering talent scarcity threatens execution velocity; secure long-term employment contracts with geoscientists capable of integrating geophysics, thermodynamics, and drilling operations. For New Entrants and Emerging Players: Kenya's Energy and Petroleum Regulatory Authority drilling cost guarantees open a window for private developers to enter exploration phases with attenuated capital exposure. Target sedimentary basin binary cycle deployments in Turkey's Aegean region where moderate-temperature fluids lack flash conditions. Pursue direct thermal application contracts with greenhouse agriculture operators as a go-to-market angle bypassing electricity market merchant price exposure. For Investors and Strategic Acquirers: The window for entry favors vertically integrated EPC firms with captive equipment manufacturing and established utility relationships. Long-term viability hinges on technology providers capable of navigating refrigerant transition requirements under EU F-Gas Regulation mandates. Watch induced seismicity protocol developments in seismically active basins as the inflection indicator for project timeline risk.| Strategic Initiative | Industry Significance |
|---|---|
| Enhanced Geothermal Systems Pilot Deployment | U.S. Department of Energy FORGE program de-risks engineered reservoir creation in Utah's hot dry rock formations. |
| Binary Cycle Technology Licensing | Modular unit know-how transfer to Turkish fabrication facilities accelerates sedimentary basin penetration. |
| Power Purchase Agreement Restructuring | Indonesia's PLN procurement protocols now mandate 15-year availability warranties as standard bid components. |
| Backward Integration into Turbine Manufacturing | Captive precision casting capacity insulates margins from Japanese and German supplier lead-time volatility. |
| Direct Thermal Application Expansion | Greenhouse agriculture contracts in Turkey's Afyonkarahisar district diversify revenue beyond electricity-only models. |
Methodological Framework
Multi-period observation of drilling cost indices, feed-in tariff revisions, and grid interconnection queue lengths anchored the trend analysis, supplemented by interviews with utility planning officers, IPP project developers, EPC contractors, and geothermal reservoir engineers. Secondary validation drew from U.S. Department of Energy funding disclosures, Indonesia Ministry of Energy and Mineral Resources regulatory filings, Kenya Energy and Petroleum Regulatory Authority drilling guarantee records, and European Green Deal innovation grant databases. Bottom-up project pipeline aggregation triangulated against top-down macroeconomic energy demand modeling.
Segment-weighting across technology configurations, application types, and end-user categories structured the analytical framework throughout the projection horizon. Modeled dimensions included generation capacity tier, project development stage, resource temperature classification, and regulatory framework cluster. CAGRs were derived from installed capacity build-out trajectories and capital cost learning curve assumptions. Forecast inputs incorporated steel alloy price volatility cycles and specialized rig availability constraints from oilfield service sector capacity allocation.
The model assumes a particular technology adoption path for Enhanced Geothermal Systems; alternative pathways for closed-loop systems without hydraulic stimulation would alter the outlook for induced seismicity risk profiles and permitting timelines. Forecasts reflect underlying assumptions about continued feed-in tariff stability and drilling cost guarantee program continuity. Regulatory shifts around subsurface mineral rights and refrigerant phase-out schedules warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Geothermal Energy
Geothermal Power Infrastructure and Components Market
Geothermal Energy
United Kingdom Geothermal Energy Market
Geothermal Energy
Geothermal Power Market
Geothermal Energy
Geothermal Power Generation Market
Geothermal Energy
Sweden Geothermal Energy Market
Geothermal Energy
Enhanced Geothermal System Market
Geothermal Energy
Hungary Geothermal Energy Market
Geothermal Energy
Indonesia Geothermal Energy Market
Geothermal Energy
US Geothermal Heat Pump Market
Geothermal Energy
Geothermal Power Infrastructure Market
Geothermal Energy
Global Geothermal Heat Pumps Market
Geothermal Energy
Denmark Geothermal Energy Market
Geothermal Energy
Asia-Pacific Geothermal Energy Market
Geothermal Energy
Netherlands Geothermal Energy Market
Geothermal Energy
Philippines Geothermal Energy Market