
 Peru Renewable Energy Market | 2026-2036
Peru Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Peru Renewable Energy Market Analytics
Utility-scale power purchase agreement channels are rewriting how renewable electrons reach corporate buyers in Peru. Engie Energía Perú leverages its long-term contracts with mining conglomerates to anchor project finance for new solar installations. Statkraft Perú sustains a dominant position in run-of-river hydroelectric generation across the central Andes. Grenergy Renovables competes aggressively on distributed generation portfolios for commercial off-takers seeking tariff stability.
Peru renewable energy encompasses electricity generation from solar irradiation, wind kinetic energy, flowing water, and organic biomass feedstocks, typically converted through photovoltaic panels, horizontal-axis turbines, Francis or Pelton hydro turbines, and combustion or anaerobic digestion systems rated from kilowatt residential scales to multi-hundred-megawatt utility facilities serving industrial load centers and national grid injection. Hydroelectric generation occupies the mature baseload position with established dam infrastructure, while photovoltaic technology leads capacity additions due to module cost declines and Peru's coastal desert irradiation profiles exceeding six kilowatt-hours per square meter daily. Utility-scale application segments capture the dominant share of capital deployment, though distributed generation and microgrid configurations are gaining traction among mining camps and rural communities distant from transmission backbone infrastructure.
Peru's Ministry of Energy and Mines enforces Law 28832 renewable quota obligations, while the Supervisory Agency for Investment in Energy and Mining regulates transmission access and tariff structures that determine project bankability. The Organismo Supervisor de la Inversión Privada en Telecomunicaciones coordinates rural electrification standards affecting off-grid system specifications. Stakeholders must monitor auction calendar timing, transmission bottleneck resolution in the southern corridor, and evolving carbon credit eligibility rules for export-oriented power contracts.
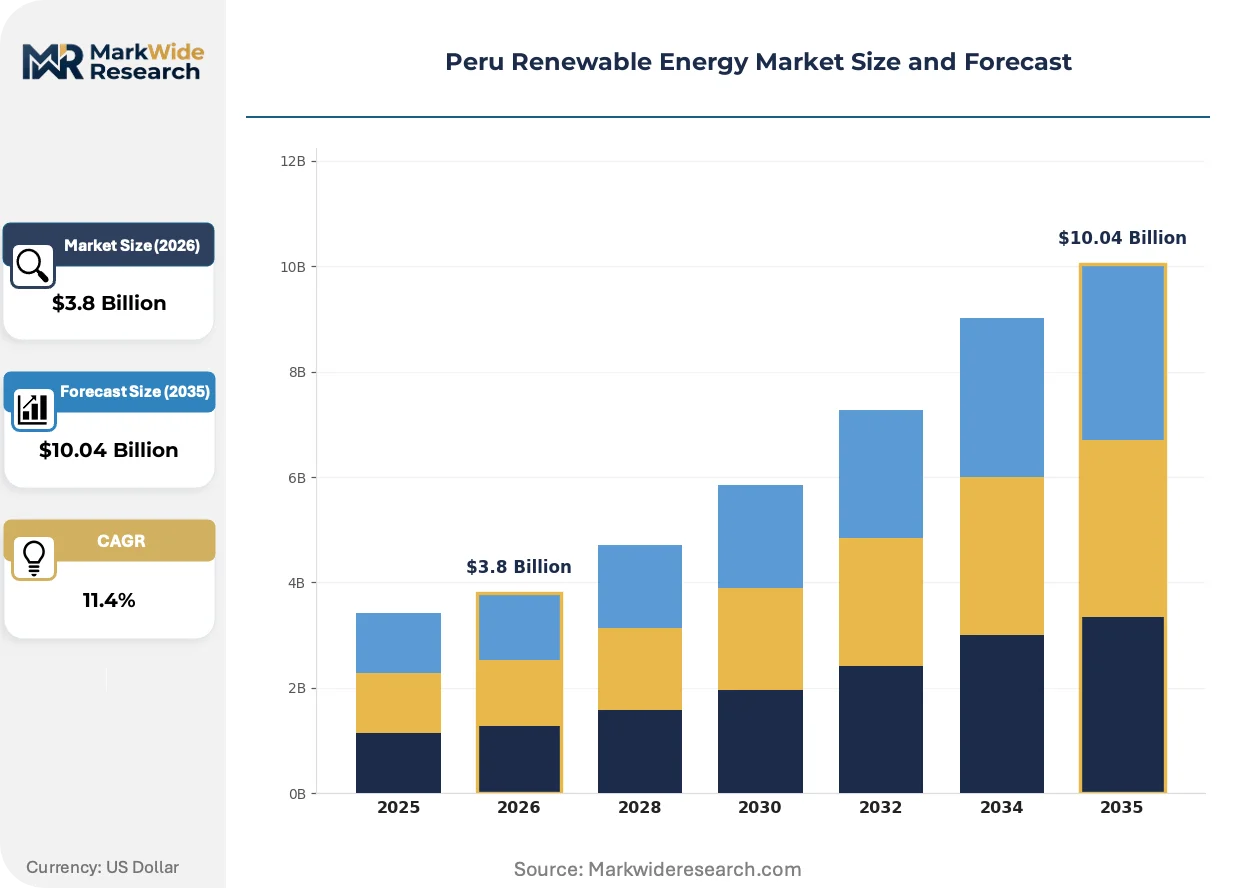
Market Dynamics
Mining corporations in Peru are accelerating power purchase agreement signings with solar and wind developers, creating a demand pull that is restructuring how renewable projects secure offtake and financing before construction begins.
Growth Catalysts
- Law 28832 quota mandates:Peru's Ministry of Energy and Mines enforces renewable energy quotas for regulated consumers, compelling distribution companies to contract clean generation and creating guaranteed demand pools for project developers.
- Arequipa solar irradiation concentration:Daily irradiation levels exceeding six kilowatt-hours per square meter in the southern desert support utility-scale photovoltaic parks with capacity factors unmatched elsewhere in the country.
- Mining sector electrification:Copper and gold producers face Scope 3 emissions scrutiny from export markets, driving direct contracting with renewable developers to secure carbon-neutral power certificates for metal shipments.
Market Restraints
- Transmission corridor saturation:The southern Peru backbone connecting Arequipa generation to Lima load centers operates near thermal limits, forcing curtailment or expensive network upgrades that erode project returns.
- Lithium-ion battery import dependency:Grid-scale storage systems rely on Chinese cell suppliers, exposing developers to shipping delays and currency fluctuations that destabilize hybrid solar-plus-storage economics.
- Hydroelectric reservoir variability:Run-of-river installations in the central Andes face El Niño-induced flow disruptions that undermine capacity factors and complicate forward contract pricing.
Strategic Opportunities
- Amazon basin microgrids:Rural communities beyond transmission reach present untapped demand for solar-diesel hybrid systems that displace expensive fuel barges and improve energy access metrics.
- Green hydrogen pilot zones:Peru's coastal desert renewables could feed electrolyzer installations serving ammonia export markets, leveraging existing port infrastructure at Matarani and Ilo.
- Carbon credit stacking:Verified Carbon Standard and Gold Standard registries offer supplemental revenue streams for projects serving mining offtakers seeking dual certification for Scope 3 reporting.
Industry Challenges
- Grid code compliance timelines:The Supervisory Agency for Investment in Energy and Mining mandates frequency response and voltage ride-through testing that delays commercial operation dates by four to eight months.
- Geotechnical assessment capacity:Qualified firms capable of Andean slope stability studies for hydroelectric intakes are concentrated in Lima, creating bottlenecks that extend pre-construction schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peru Renewable Energy Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Solar, Wind, Hydroelectric, Biomass Technology: Photovoltaic, Concentrated Solar Power, Onshore Wind, Hydro Turbines Application: Utility-Scale, Distributed Generation, Off-Grid, Microgrid End User: Residential, Commercial, Industrial, Government |
| Companies Covered | Engie Energía Perú, Statkraft Perú, Orygen Perú, Enel Green Power Perú, Grenergy Renovables, Kallpa Generación, Acciona, Fenix Power, Viridi Energías Renovables, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peru Renewable Energy Market Evolving Landscape
Peru's renewable energy sector is experiencing a technological pivot where digital infrastructure and policy refinement are compressing development cycles and reshaping how electrons reach corporate buyers.
Hybrid inverter architectures with integrated power plant controllers are virtualizing the traditional separation between generation assets and grid management functions. Mining offtakers in the Arequipa region are specifying these systems in new tenders to reduce balance-of-plant costs and accelerate commissioning timelines. This convergence is virtualizing the role of standalone SCADA providers and forcing equipment vendors to bundle software capabilities with hardware shipments.
Peru's Ministry of Energy and Mines is refining auction mechanisms under Law 28832 to incorporate hourly matching requirements rather than annual energy blocks. This policy evolution forces developers to pair solar installations with storage or firm hydro contracts to meet dispatchability criteria. Photovoltaic projects without co-located batteries are experiencing bid disqualification rates above prior auction rounds.
Corporate buyers in the mining sector are abandoning traditional utility intermediaries to negotiate sleeved power purchase agreements directly with project sponsors. Southern Peru Copper and Buenaventura have executed direct contracts that bypass distribution concessionaires entirely. This disintermediation concentrates in the southern mining corridor where load scale justifies dedicated transmission investments.
Peru Renewable Energy Market Segmentation
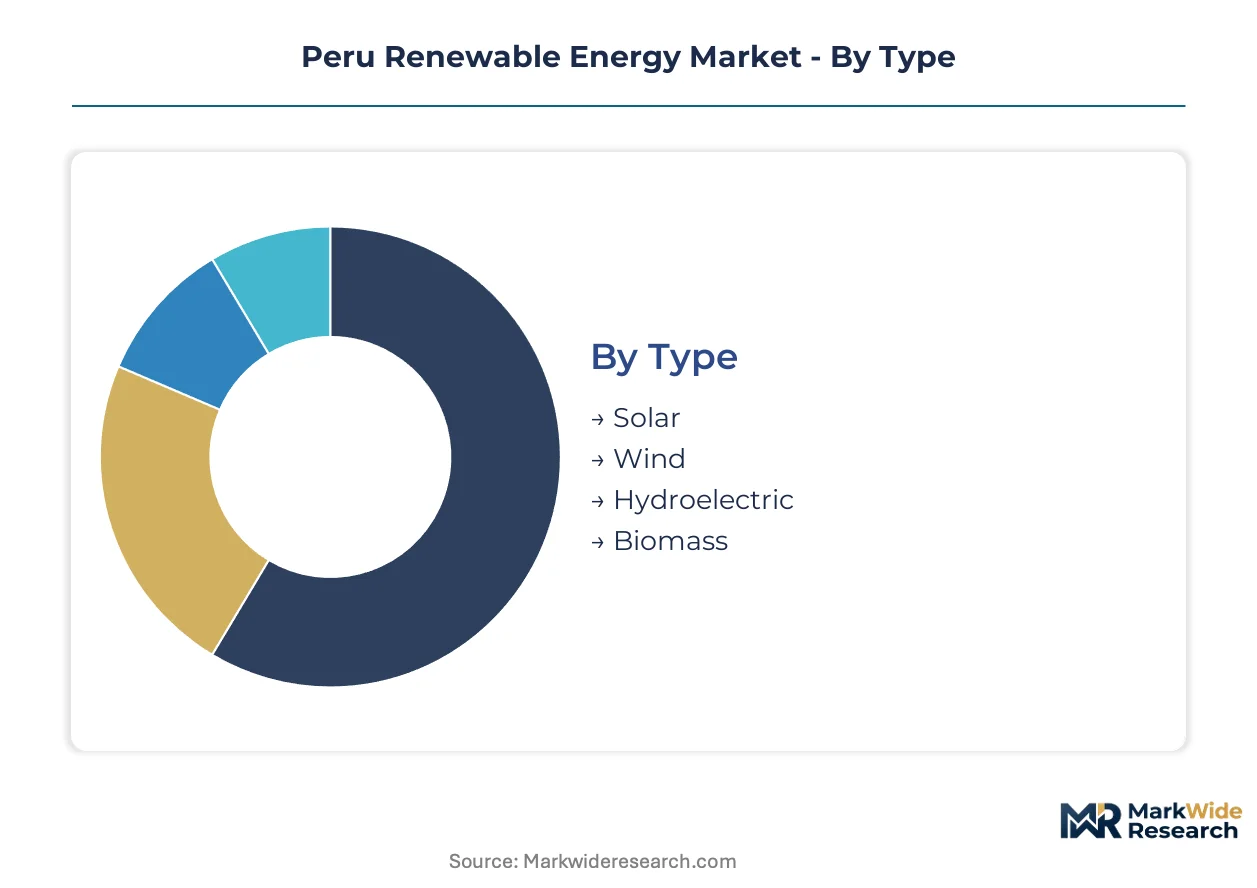
Peru's renewable energy market segments across generation technology, deployment scale, and customer archetype. Each dimension shapes capital intensity, regulatory exposure, and offtake contracting structures differently.
Type:
Mature baseload technologies coexist with emerging variable sources in Peru's generation mix.
- Solar:Photovoltaic installations dominate new capacity additions, leveraging coastal desert irradiation exceeding six kilowatt-hours per square meter daily. Arequipa's mining corridor concentrates utility-scale demand as copper producers seek carbon-neutral power certificates for export compliance.
- Hydroelectric:Run-of-river installations provide firm generation from central Andes watersheds, though El Niño-induced flow variability complicates forward contract pricing. Statkraft Perú maintains the largest operational portfolio across this mature segment.
- Wind:Onshore developments cluster in northern coastal zones where Pacific wind patterns sustain capacity factors above regional averages.
- Biomass:Agricultural residue combustion serves rural agro-industrial facilities with captive feedstock access in northern valley regions.
Hydroelectric retains volume leadership; solar holds the steepest expansion curve.
Technology:
Cost tier differentiation separates mass-deployable modules from specialized thermal or mechanical systems.
- Photovoltaic:Crystalline silicon modules from Chinese manufacturers anchor project economics through sub-dollar-per-watt landed costs. Distributed generation portfolios in Lima's commercial districts favor rooftop configurations with net metering.
- Onshore Wind:Horizontal-axis turbines rated two to three megawatts dominate northern sites, with gearbox reliability determining operational expenditure profiles.
- Concentrated Solar Power:Parabolic trough configurations with molten salt storage remain pre-commercial in Peru, limited by higher capital intensity against photovoltaic competition.
- Hydro Turbines:Francis and Pelton designs adapt to Andean head and flow conditions, with civil works representing sixty to seventy percent of project costs.
Photovoltaic commands deployment scale; onshore wind is climbing fastest in the north.
Application:
Volume concentration versus margin capture defines strategic positioning across deployment modes.
- Utility-Scale:Grid-connected installations exceeding ten megawatts secure long-term power purchase agreements with mining conglomerates and distribution concessionaires. Law 28832 quota obligations create guaranteed offtake pools for auction winners.
- Distributed Generation:Commercial and industrial rooftop systems below five megawatts exploit net metering regulations, with Grenergy Renovables competing aggressively for tariff-sensitive off-takers.
- Off-Grid:Diesel displacement systems serve Amazon basin communities beyond transmission reach, reducing fuel barge logistics costs.
- Microgrid:Solar-diesel hybrid configurations power remote mining camps and agricultural processing facilities with dedicated load management.
Utility-scale anchors capital deployment; microgrid configurations are expanding most quickly in extractive sectors.
End User:
Customer type dictates contract duration, creditworthiness, and sustainability reporting requirements.
- Industrial:Mining corporations execute sleeved power purchase agreements directly with developers, bypassing distribution intermediaries. Southern Peru Copper and Buenaventura have pioneered this disintermediation in the Arequipa corridor.
- Commercial:Retail and logistics operators seek tariff stability through distributed generation contracts, prioritizing budget predictability over lowest unit cost.
- Government:Ministry of Energy and Mines auction participation and rural electrification mandates drive public sector procurement.
- Residential:Net-metered rooftop systems remain nascent, constrained by financing availability and Lima's coastal cloud cover.
Industrial off-takers dominate contract value; commercial segment is gaining share fastest among urban deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Southern Peru Interconnection System anchors renewable energy distribution, transmitting Arequipa solar generation to Lima industrial load centers through high-voltage corridors.
Arequipa Region
Southern Peru Copper and Buenaventura anchor mining demand for carbon-neutral power certificates in the Arequipa corridor. Law 28832 quota mandates compel distribution companies to contract clean generation from local solar parks. The Majes-Siguas irrigation zone hosts utility-scale photovoltaic installations exploiting daily irradiation exceeding six kilowatt-hours per square meter.
Lima Metropolitan Area
Commercial and industrial off-takers in Lima's financial district seek distributed generation contracts for tariff stability. The Ministry of Energy and Mines regulates net metering standards for rooftop photovoltaic systems. San Isidro and Miraflores business districts concentrate Grenergy Renovables installations serving retail and logistics operators.
Central Andes
Run-of-river hydroelectric installations from Statkraft Perú supply firm baseload generation to central grid nodes. El Niño-induced flow variability complicates forward contract pricing for watershed-dependent projects. The Mantaro River valley clusters Francis and Pelton turbine installations feeding into the national interconnected system.
Northern Coast
Pacific wind patterns sustain onshore developments with capacity factors above regional averages in Piura and Lambayeque departments. Horizontal-axis turbine installations exploit consistent trade wind exposure along the Sechura Desert coastline. The Talara refining complex anchors industrial electricity demand for wind power offtake agreements.
Peru Renewable Energy Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated utilities with long-term mining offtake relationships and independent developers competing on distributed generation portfolios. Two strategic archetypes dominate: European-headquartered energy majors leveraging balance sheet capacity for utility-scale project finance, and Spanish-specialized renewable developers capturing commercial rooftop segments through tariff-sensitive contracting. Competitive positioning depends on securing auction allocations under Law 28832 and negotiating sleeved power purchase agreements that bypass distribution intermediaries.
Among European-headquartered operators, Engie Energía Perú and Statkraft Perú exemplify the utility-scale archetype through their established presence in regulated auctions and mining sector contracting. Grenergy Renovables occupies a specialized position within the distributed generation tier, competing for commercial off-takers seeking alternatives to utility intermediaries.
| Leading Market Players |
|---|
| Engie Energía Perú |
| Statkraft Perú |
| Orygen Perú |
| Enel Green Power Perú |
| Grenergy Renovables |
| Kallpa Generación |
| Acciona |
| Fenix Power |
| Viridi Energías Renovables |
| Others |
Value Network & Pricing Analysis
Transmission corridor saturation in southern Peru signals undercapacity that compresses developer margins while concentrating pricing power among grid-adjacent generators. Law 28832 auction winners with secured interconnection slots command premium contract terms from mining offtakers desperate for carbon-neutral power certificates.
Pricing Analysis
Long-term power purchase agreement pricing stratifies across auction-winning, sleeved-direct, and spot-market tiers. Price differentiation hinges on interconnection security and offtaker credit quality, with mining conglomerates paying scarcity premiums for firm delivery guarantees. Cost compression in utility-scale solar is intensifying because Chinese module oversupply feeds aggressive developer bidding. Commercial distributed generation buyers exhibit highest price sensitivity, while industrial miners prioritize supply certainty over unit cost.
Supply Chain Analysis
Tariff exposure between China and Peru dominates supply chain risk for lithium-ion battery imports feeding hybrid solar-plus-storage projects. Crystalline silicon modules draw from Chinese manufacturing concentration, while Francis and Pelton hydro turbines source from European and Asian precision foundries. Single-source vulnerability in grid-scale inverter components threatens commissioning timelines. Distribution runs through Lima-based EPC contractors with Andean logistics specialization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Peru's renewable energy sector rewards developers who control scarce transmission access and geotechnical assessment capacity. Qualified slope stability firms concentrated in Lima create bottlenecks that extend project schedules and inflate development costs.
For Market Incumbents: Insulate auction positions by securing preemptive grid interconnection agreements before Law 28832 allocation rounds intensify. Backward integration into geotechnical assessment capacity reduces reliance on Lima-based engineering bottlenecks. Prioritize sleeved power purchase agreement templates that bypass distribution intermediaries entirely.
For New Entrants and Emerging Players: Amazon basin communities beyond transmission reach offer white-space expansion for solar-diesel hybrid microgrids displacing expensive fuel barge logistics. Green hydrogen pilot zones at Matarani and Ilo ports present early-mover electrolyzer installation opportunities. Lead with outcome-based energy service contracts rather than equipment sales to de-risk rural offtaker credit profiles.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among developers with locked-in mining sector power purchase agreements spanning the analysis window. Acquisition targets should demonstrate secured interconnection rights and established relationships with the Supervisory Agency for Investment in Energy and Mining. Watch auction bid disqualification rates for storage-mandated solar projects as inflection signals for technology transition timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement | Long-term mining sector contracts anchor project finance for utility-scale solar installations in Arequipa. |
| Backward Integration | In-house geotechnical assessment capacity reduces Lima engineering bottlenecks for Andean hydroelectric projects. |
| Technology Licensing | Hybrid inverter architectures with integrated plant controllers accelerate commissioning timelines for mining offtakers. |
| Vertical Integration into Storage | Co-located battery systems qualify developers for hourly matching auction requirements under refined Law 28832 mechanisms. |
| Green Certification Program | Verified Carbon Standard and Gold Standard registries unlock supplemental revenue streams for Scope 3 reporting compliance. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, project development databases, and customs trade records. Interviews with IPP project developers, EPC contractors, utility planning officers, and grid operators informed demand-side assumptions. Secondary validation drew from Ministry of Energy and Mines auction disclosures, Supervisory Agency for Investment in Energy and Mining transmission data, and IEA renewable energy reports. Bottom-up capacity installation tracking triangulates against top-down national generation statistics.
Forecast inputs span generation technology, project scale tier, regulatory framework cluster, and regional grid type across the projection horizon. Analytical framework models capacity additions, capacity factor assumptions, and tariff evolution without year-specific anchoring. CAGRs derive from regression analysis of historical auction outcomes and mining sector electrification trajectories. El Niño-induced hydroelectric variability and lithium-ion import cost volatility feed sensitivity scenarios.
Macroeconomic conditions sit as an overlay; deviation in copper export demand, Chinese module pricing, or sol currency stability would shift the trajectory. Forecasts reflect documented assumptions regarding transmission corridor expansion timelines and mining sector decarbonization commitments. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Global Renewable Energy Market
Renewable Energy
Solar Lighting System Market
Renewable Energy
Solar District Heating Market
Renewable Energy
Netherlands Renewable Energy Market
Renewable Energy
Hybrid Solar Wind Diesel Market
Renewable Energy
Argentina Renewable Energy Market
Renewable Energy
Solar Tracker Market
Renewable Energy
Green Renewable Energy Market
Renewable Energy
Variable Renewable Energy Market
Renewable Energy
Solar Panel Mounting Structure Market
Renewable Energy
Wind Turbine Inspection Drones Market
Renewable Energy
Switzerland Renewable Energy Market
Renewable Energy
Austria Renewable Energy Market
Renewable Energy
Blockchain in Renewable Energy Market
Renewable Energy
Hybrid Power System Market
Renewable Energy
Uzbekistan Renewable Energy Market