
 North America Solar Tracker Market | 2026-2036
North America Solar Tracker Market Size, Share, and Industry Trends Forecast 2026-2036
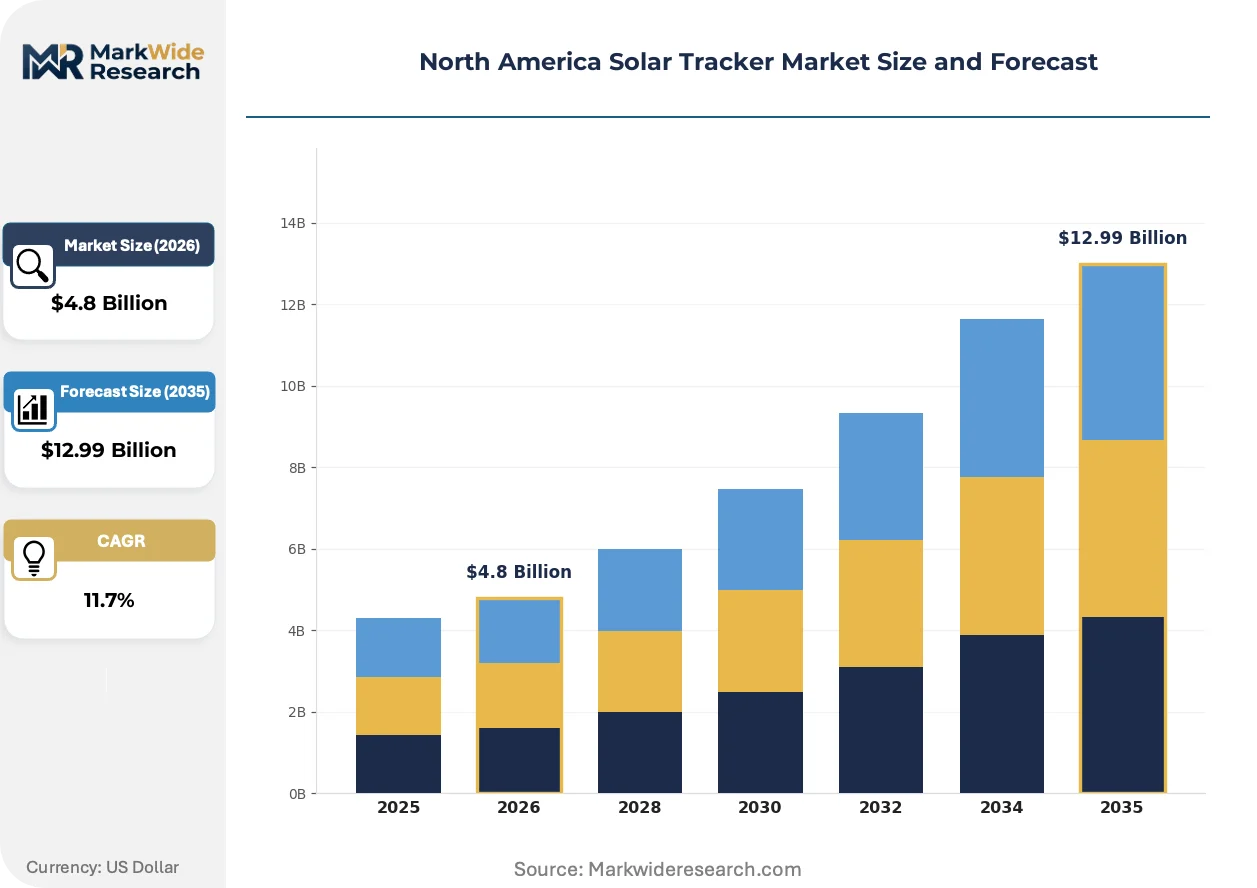
North America Solar Tracker Market Outlook
Utility-scale solar procurement is expanding across North America as independent power producers and regulated utilities replace fixed-tilt arrays with tracking systems to boost capacity factors. Nextracker Inc. leverages its software-driven tracker architecture to dominate large-scale project deployments in the southwestern United States. Array Technologies sustains manufacturing scale through its centralized torque-tube design, while GameChange Solar competes aggressively on installation speed and steel content reduction.
A solar tracker is a mechanical racking system that orients photovoltaic modules toward the sun using electromechanical actuators, typically achieving 20-35% additional energy yield versus fixed-tilt configurations depending on latitude and weather patterns. Single-axis trackers anchor the installed base due to favorable levelized cost of energy economics on flat terrain, while dual-axis systems occupy niche applications where land constraints justify premium capture rates. Electromechanical drive systems lead technology adoption because servo motor precision enables row-to-row synchronization without hydraulic fluid maintenance burdens.
The US Inflation Reduction Act shapes demand through production and investment tax credits that improve tracker project returns, while state-level renewable portfolio standards in California and Texas mandate specific clean electricity procurement timelines that accelerate deployment schedules. Canada's federal carbon pricing framework and provincial programs in Alberta and Ontario create parallel incentive structures for tracking infrastructure. Stakeholders must monitor interconnection queue backlogs and steel tariff volatility as these variables determine project economics more directly than module cost declines.
Market Dynamics
The IRA's domestic content bonus credit is compressing project development timelines and forcing tracker manufacturers to reconfigure supply chains toward US steel sourcing and assembly operations.
Growth Catalysts
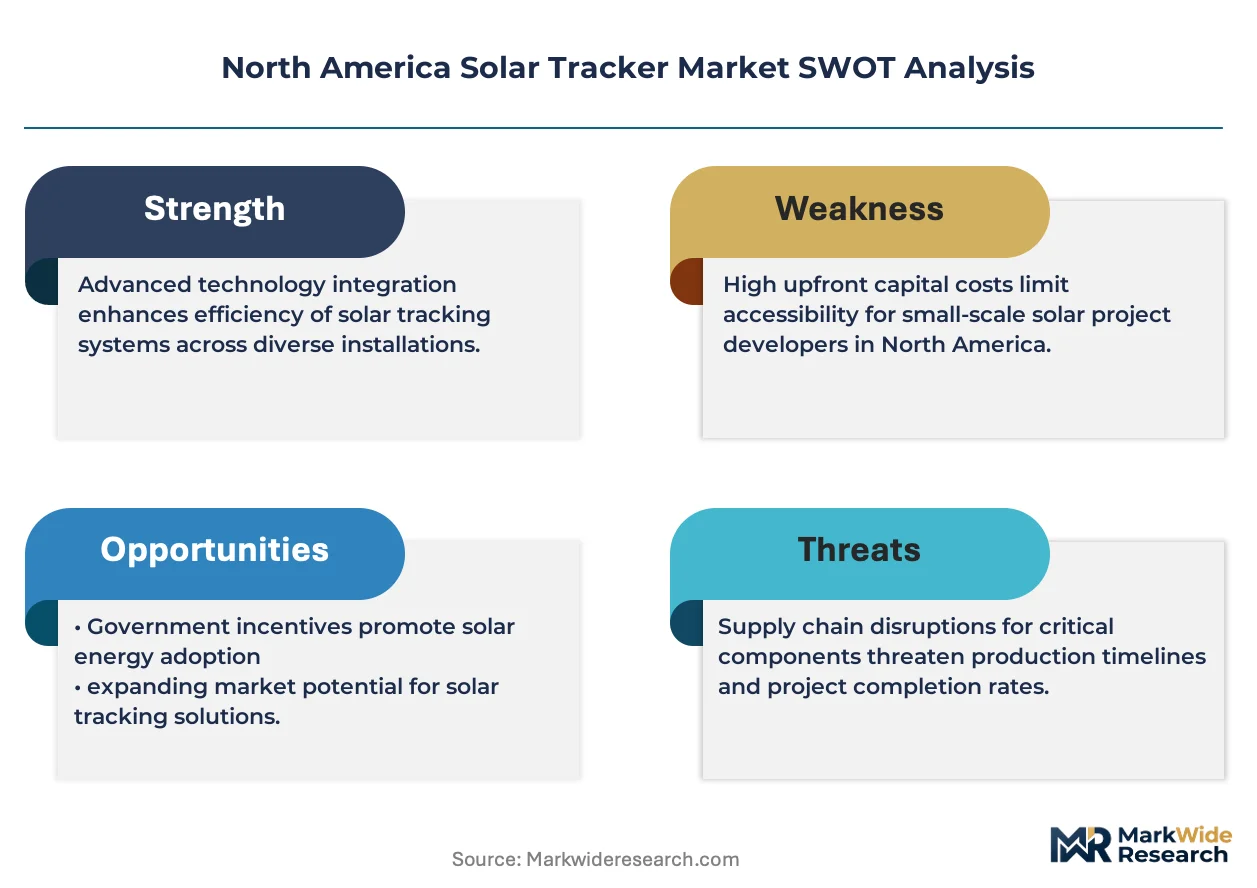
- Investment Tax Credit Stacking:The US Inflation Reduction Act allows project developers to layer production tax credits with domestic content adders, improving tracker project returns by 10 percentage points in eligible configurations.
- Texas Interconnection Reform:ERCOT's generator interconnection process revisions are clearing queue backlogs for utility-scale solar, accelerating tracker deployment schedules in the state's western renewable zones.
- Electromechanical Precision:Servo motor architectures with row-to-row synchronization capabilities are displacing hydraulic systems across single-axis installations, reducing O&M burdens and fluid contamination risks.
Market Restraints
- Steel Tariff Volatility:Section 232 and Section 301 duties on imported structural steel create input cost uncertainty for torque-tube fabricators, compressing margin visibility on multi-year EPC contracts.
- Interconnection Queue Congestion:ISO-New England and CAISO backlogs extending 3-5 years are freezing project commercial operation dates and stranding committed tracker manufacturing capacity.
- Fixed-Tilt Residual Economics:Steep module price declines are partially eroding the energy yield premium of tracking systems on certain high-irradiance sites with complex terrain constraints.
Strategic Opportunities
- Alberta Solar Deployment:Canada's provincial renewable procurement programs in Alberta are creating first-mover positioning for tracker suppliers as the province scales from 2 GW to projected 10 GW solar capacity.
- Agrivoltaics Convergence:Dual-use installations combining tracking infrastructure with shade-tolerant crop cultivation are opening acreage-constrained markets in California's Central Valley and Texas High Plains.
- Software-Defined O&M:Predictive analytics platforms integrated with tracker control systems are enabling performance guarantee structures and recurring revenue streams independent of hardware shipments.
Industry Challenges
- Electromechanical Technician Scarcity:Field commissioning of servo drive networks requires specialized control systems expertise that EPCs struggle to source in rural deployment regions.
- Geotechnical Variability:Soil bearing capacity heterogeneity across southwestern US project sites is forcing custom foundation designs that erode the standardization benefits of centralized tracker architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Solar Tracker Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Axis, Dual-Axis, Horizontal, Vertical End User: Utility, Commercial, Residential, Government Technology: Electromechanical, Hydraulic, Servo Motors, Gearbox Installation: Ground Mount, Rooftop, Floating, Track Mounted |
| Companies Covered | Nextracker Inc., Array Technologies, GameChange Solar, PV Hardware, Solar FlexRack, Valmont Industries Inc., Deger Canada Inc., All Earth Renewables, Soltec, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Solar Tracker Market Strategic Shifts
Tracker system architecture is bifurcating between centralized torque-tube designs optimized for manufacturing scale and distributed drive configurations that reduce steel intensity and installation labor.
Distributed drive architectures with independent row motors are modularizing project execution by eliminating the heavy torque tubes that constrain shipping logistics and foundation standardization. EPCs in Texas and California are adopting these systems for sites with irregular topography or restricted access roads. The shift is modularizing the traditional tracker value chain, separating mechanical fabrication from electrical integration and enabling regional assembly partnerships.
The US Treasury's domestic content guidance under the Inflation Reduction Act is tightening eligibility requirements for steel and manufactured product classifications. Tracker manufacturers are responding by qualifying US-milled steel sources and relocating final assembly to domestic facilities. The policy is reshaping procurement patterns, with independent power producers now requiring supply chain documentation that was unnecessary prior to 2023.
Utility procurement committees are unbundling tracker supply from EPC wrap contracts, creating direct manufacturer relationships that bypass traditional channel intermediaries. This disintermediation is most pronounced in California and Texas, where repeat project developers have accumulated sufficient technical capacity to specify and manage tracker performance guarantees independently. The pattern is compressing distributor margins and forcing manufacturers to build direct service organizations.
North America Solar Tracker Market Segmentation
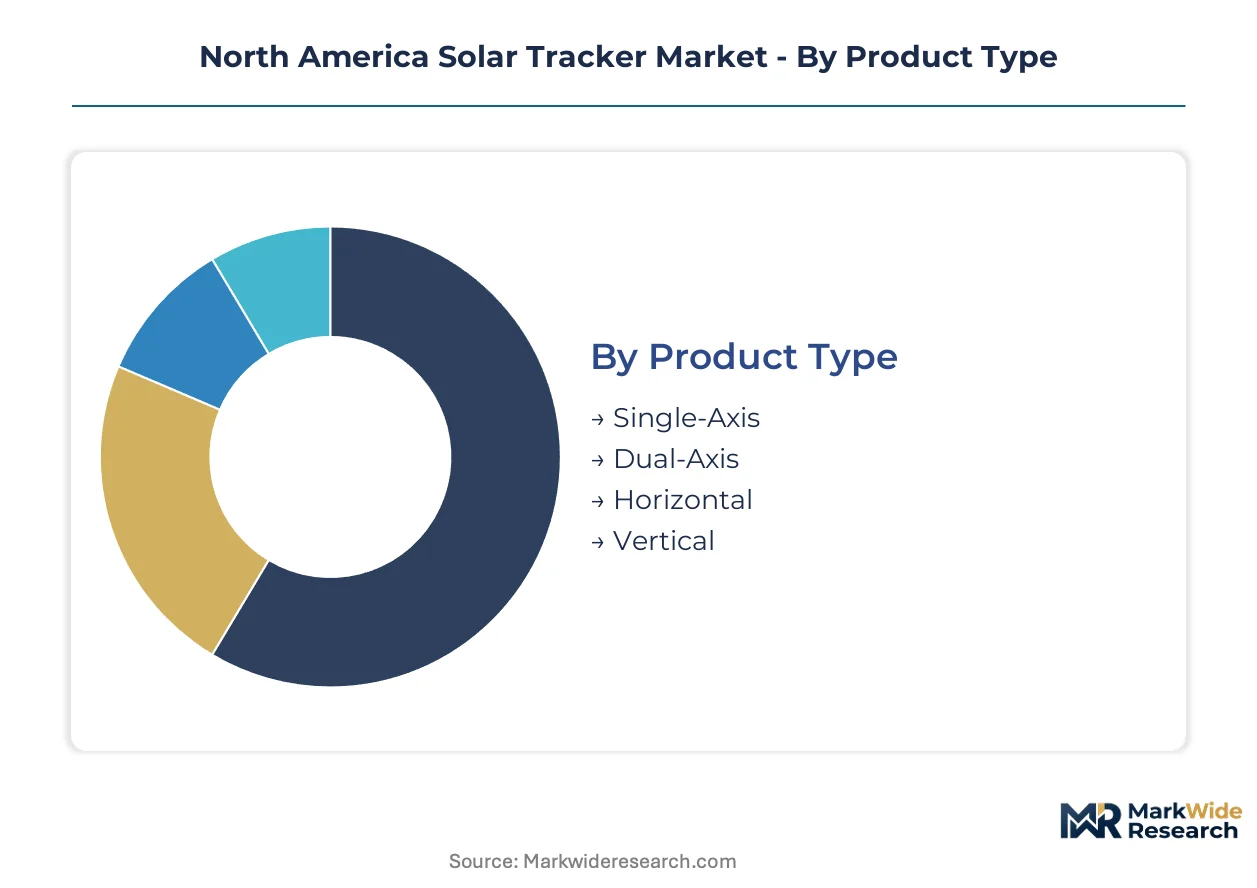
Tracker deployment economics vary sharply across product architectures, end-user scale thresholds, and installation constraints. Procurement committees weight these segment trade-offs against interconnection timelines, steel tariff exposure, and domestic content bonus eligibility under the IRA.
Product Type:
Supply concentration in single-axis manufacturing dominates procurement volumes across southwestern US utility zones.
- Single-Axis:Horizontal rotation about one pivot point captures 20-35% additional yield versus fixed-tilt with favorable LCOE economics on flat terrain. Demand concentrates in Texas and California utility-scale deployments where ERCOT queue reforms and state RPS mandates compress project schedules.
- Dual-Axis:Azimuth and elevation tracking maximizes energy capture per module but carries premium steel and foundation costs. Niche demand clusters in acreage-constrained sites and agrivoltaic pilots across California's Central Valley where land productivity justifies capital intensity.
- Horizontal:East-west tracking orientation suits high-latitude sites with asymmetric solar paths. Canadian Alberta procurement programs favor this configuration for winter performance optimization.
- Vertical:North-south axis rotation addresses specific terrain constraints and bifacial module pairing. Limited deployment in irregular topography sites where grading costs exceed tracker premium.
Today's leader: Single-Axis. Tomorrow's challenger: Dual-Axis.
End User:
Cost tier differentiation separates utility procurement scale from commercial and residential margin structures.
- Utility:Independent power producers and regulated utilities deploy multi-hundred-megawatt arrays with direct manufacturer relationships bypassing EPC intermediaries. Procurement concentrates in Texas renewable zones and California desert regions where interconnection queue positions determine commercial operation dates.
- Commercial:Behind-the-meter installations for industrial facilities and data centers face rooftop constraints and net metering policy variability. Demand clusters in states with favorable avoided-cost rate structures.
- Residential:Single-family and small multi-family deployments rarely justify tracker economics given fixed-tilt cost floors and permitting complexity. Negligible addressable market within segment.
- Government:Federal and state agency procurement prioritizes domestic content compliance for IRA bonus credit eligibility. Military installations in the southwestern US specify hardened tracker architectures for grid resilience.
Utility procurement commands volume leadership. Commercial segment climbs fastest on corporate renewable targets.
Technology:
Volume concentration in electromechanical architectures is displacing legacy hydraulic systems across new installations.
- Electromechanical:Servo motor precision enables row-to-row synchronization without fluid maintenance burdens. Standard for utility-scale deployments in Arizona and Nevada where O&M access costs favor reliability.
- Hydraulic:Fluid-driven actuation persists in legacy installations but faces replacement parts scarcity. Declining share in new procurement as electromechanical capital costs converge.
- Servo Motors:Closed-loop position control with encoder feedback delivers sub-degree tracking accuracy. Specified for high-DNI sites where capture rate optimization justifies premium.
- Gearbox:Mechanical reduction systems for torque multiplication in centralized drive architectures. Array Technologies and competitors optimize tooth profiles for 25-year service life.
Electromechanical systems anchor current procurement. Servo motor configurations gain fastest on precision requirements.
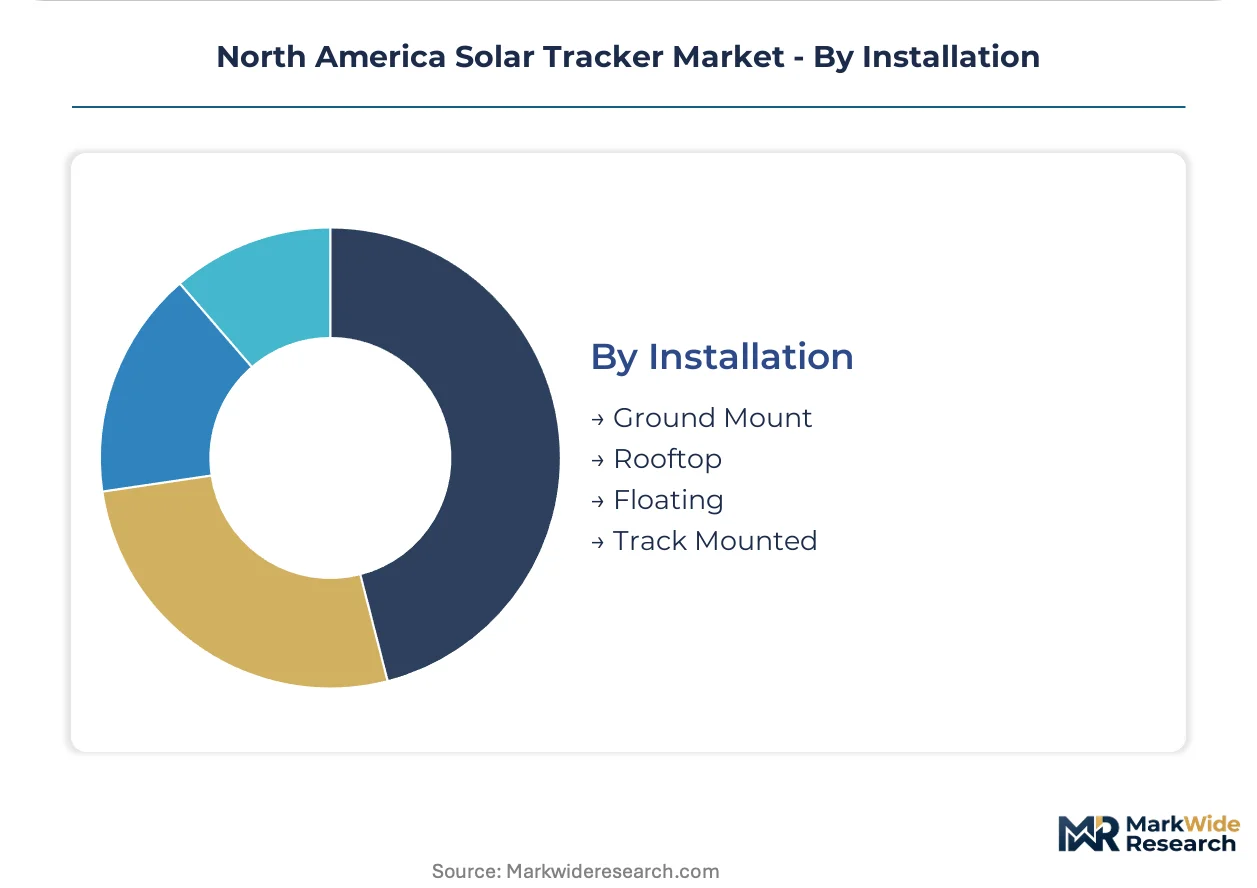
Installation:
Application context determines foundation standardization and labor productivity across deployment modes.
- Ground Mount:Standard piling or ballasted foundations for utility-scale and commercial arrays on graded terrain. Dominates Texas and California deployment volumes with geotechnical customization for soil variability.
- Rooftop:Structural load constraints and wind uplift engineering limit tracker applicability. Rare deployment except for large flat commercial roofs with reinforced structural capacity.
- Floating:Pontoon or mooring systems for reservoir and quarry installations. Emerging pilot projects in California water districts addressing evaporation reduction co-benefits.
- Track Mounted:Pre-assembled foundation and drive units for accelerated installation in remote access sites. GameChange Solar and competitors optimize for labor productivity in restricted logistics corridors.
Ground mount installations lead by volume. Track mounted systems expand most quickly on labor cost escalation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic content bonus credits under the US Inflation Reduction Act are reshaping manufacturing location decisions, with tracker fabricators relocating final assembly to capture compliance arbitrage against Canadian and Mexican import alternatives.
United States
ERCOT interconnection queue reforms and California's renewable portfolio standards are accelerating utility-scale deployments. The IRA's domestic content guidance from the US Treasury tightens steel sourcing requirements. Tracker manufacturing concentrates in Texas industrial corridors and Arizona assembly facilities serving southwestern solar zones.
Canada
Alberta's provincial renewable procurement programs are scaling solar capacity targets from 2 GW toward 10 GW. Federal carbon pricing frameworks and provincial incentives in Ontario create parallel demand structures. Calgary and Edmonton industrial clusters host tracker distribution hubs serving prairie utility installations.
Mexico
Nearshoring advantages for US-bound steel components are attracting tracker subassembly operations. CFE procurement modernization and private power purchase agreement growth in northern border states expand addressable demand. Monterrey manufacturing corridors leverage logistics access to Texas renewable zones.
North America Solar Tracker Market Competitive Environment
Supply chain reconfiguration dominates the current landscape as manufacturers relocate assembly operations to qualify for IRA domestic content credits. The vendor base stratifies between integrated hardware-software platforms and fabrication-focused suppliers. Three archetypes define competitive positioning: torque-tube specialists optimizing manufacturing scale, distributed drive innovators reducing steel intensity, and control system integrators monetizing software-defined O&M. Capacity expansion and strategic localization represent the dominant competitive moves, with firms qualifying US-milled steel sources and establishing domestic final assembly.
Within the integrated platform tier, Nextracker Inc. and Array Technologies exemplify contrasting architectural philosophies—software-driven distributed configurations versus centralized torque-tube designs. GameChange Solar occupies a position emphasizing installation velocity and material efficiency. These three anchors illustrate how tracker suppliers are differentiating through mechanical design choices rather than module efficiency gains, with each representing a distinct bet on labor productivity, shipping logistics, and foundation standardization trade-offs.
| Leading Market Players |
|---|
| Nextracker Inc. |
| Array Technologies |
| GameChange Solar |
| PV Hardware |
| Solar FlexRack |
| Valmont Industries Inc. |
| Deger Canada Inc. |
| All Earth Renewables |
| Soltec |
| Others |
Value Chain & Pricing Dynamics
IRA domestic content bonus credit eligibility is compressing procurement timelines and forcing tracker manufacturers toward US-milled steel sourcing, which elevates input costs and compresses margin visibility on multi-year EPC contracts.
Pricing Analysis
Distributor margin compression is accelerating as utility procurement committees unbundle tracker supply from EPC wrap contracts and establish direct manufacturer relationships. Pricing stratifies across premium servo-motor precision tiers, standard electromechanical configurations, and economy hydraulic legacy systems, with differentiation driven by steel tariff exposure and domestic content certification. Cost pressure runs through standard tiers as module price declines partially erode tracking yield premiums. Commercial behind-the-meter buyers exhibit highest price sensitivity due to net metering policy variability, while utility-scale IPPs prioritize performance guarantees over unit economics.
Supply Chain Analysis
Regional distribution centers in Texas industrial corridors and Arizona assembly facilities anchor hub-and-spoke patterns serving southwestern solar zones. Manufacturing concentrates in the United States, Mexico, and Canada as firms relocate final assembly to capture IRA compliance arbitrage. Steel torque tubes, servo motor drives, and geotechnical foundation hardware constitute critical input dependencies. Single-source vulnerability in US-milled structural steel creates exposure to Section 232 duty volatility. Distribution runs through direct manufacturer relationships that displace traditional channel intermediaries in California and Texas markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America solar tracker market functions as a stable compounder underpinned by state-level renewable portfolio standards that mandate clean electricity procurement timelines regardless of macroeconomic cycles.
For Market Incumbents: Deepen backward integration into US steel sourcing and captive servo motor assembly to defend against tariff volatility and domestic content compliance requirements. Expand technical service organizations in Texas and California to support direct procurement relationships and performance guarantee structures. Prioritize software-defined O&M platform development to capture recurring revenue independent of hardware shipment cycles. For New Entrants and Emerging Players: Alberta utility-scale developers represent an underserved buyer archetype as provincial procurement scales solar capacity targets. Agrivoltaic pilots across California's Central Valley offer penetrable white-space for dual-axis configurations where land productivity justifies capital intensity. Pursue partnership-based go-to-market positioning with regional EPCs lacking in-house tracker specification expertise. For Investors and Strategic Acquirers: Asymmetric upside sits with distributed drive architecture specialists whose modular designs reduce steel intensity and enable regional assembly partnerships. The five-to-ten year viability window favors platforms combining hardware manufacturing scale with software control system integration. Acquisition targets should demonstrate qualified US steel supply relationships and established direct utility procurement channels. Monitor ERCOT interconnection queue clearance rates as the critical inflection signal for deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Content Supply Chain Reconfiguration | Qualifying US-milled steel sources captures IRA bonus credit arbitrage against Mexican import alternatives. |
| Software-Defined O&M Platform Development | Predictive analytics integration enables performance guarantee structures and recurring revenue streams. |
| Direct Utility Procurement Relationship Buildout | Bypassing EPC intermediaries compresses distributor margins and secures volume commitments. |
| Agrivoltaic Dual-Use Installation Piloting | Shade-tolerant crop cultivation opens acreage-constrained markets in California and Texas. |
| Regional Assembly Partnership Structuring | Modular distributed drive architectures separate mechanical fabrication from electrical integration. |
Study Parameters
Bottom-up utility-scale deployment modeling reconciled against top-down tracker manufacturing capacity tracking forms the analytical core of this study. Primary interviews with IPP project developers, EPC procurement leads, tracker manufacturer sales directors, and utility planning officers were cross-validated against secondary sources including EIA generation data, FERC interconnection filings, IEA renewable deployment reports, and state RPS compliance databases. This dual-layer approach ensures demand-side consumption patterns align with supply-side production and inventory movements.
Input-output matrices map tracker system shipments across product architecture, end-user scale, and installation mode dimensions over the projection horizon. CAGRs derive from segmented volume trajectories adjusted for interconnection queue clearance assumptions, steel tariff exposure scenarios, and domestic content bonus uptake rates. Forecast inputs incorporate ERCOT generator interconnection process reform timelines and Alberta provincial procurement auction schedules as demand-side drivers.
Inputs from EIA, FERC, and state utility commission filings were available through the study window; gaps in real-time interconnection queue position data introduce uncertainty bands around commercial operation date assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Romania Renewable Energy Market
Renewable Energy
Egypt Renewable Energy Market
Renewable Energy
Wind Turbine Inspection Services Market
Renewable Energy
Hungary Renewable Energy Market
Renewable Energy
Venezuela Renewable Energy Market
Renewable Energy
Singapore Renewable Energy Market
Renewable Energy
In-Pipe Hydroelectric System Market
Renewable Energy
Solar Balloon Market
Renewable Energy
Romania Wind Energy Market
Renewable Energy
Variable Renewable Energy Market
Renewable Energy
Solar PV and Wind Energy Market
Renewable Energy
South Asia Renewable Energy Market
Renewable Energy
Renewable Energy MRO Market
Renewable Energy
Solar Chimney Market
Renewable Energy
Marine Energy Market
Renewable Energy
Europe Ocean Power Market