
 United Kingdom Corrugated Packaging Market | 2026-2036
United Kingdom Corrugated Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Corrugated Packaging Market Analytics
Asset-light leasing models for converting equipment are reshaping competitive entry in UK corrugated packaging. Smurfit WestRock leverages its integrated containerboard-to-box network across British manufacturing sites. DS Smith PLC anchors its position through specialized e-commerce protective designs for major retail fulfillment operations. Mondi Group differentiates via high-performance kraft liner innovations that reduce grammage without sacrificing stack strength.
Corrugated packaging comprises fluted paperboard sheets laminated between flat linerboards, typically manufactured through steam-heated corrugators operating at 100–300 meters per minute to produce protective, stackable transit containers. Single-wall and double-wall configurations dominate UK volume, with double-wall formats commanding premium positioning in heavy-goods logistics due to superior burst and edge crush resistance. Die-cut designs represent the fastest-expanding product type as automated packing lines in food and beverage processing plants demand precision-fit inserts that minimize void fill and dimensional weight charges.
The UK's Environment Agency enforces Packaging Waste Regulations that mandate minimum recycled content thresholds, while the Competition and Markets Authority scrutinizes green claims under emerging anti-greenwashing guidance. Extended Producer Responsibility reforms scheduled for full implementation will shift cost burdens upstream to producers and reshape material sourcing economics across the value chain. Stakeholders must monitor whether virgin fiber price volatility or recycled pulp quality variability becomes the binding constraint on margin recovery.
Market Dynamics
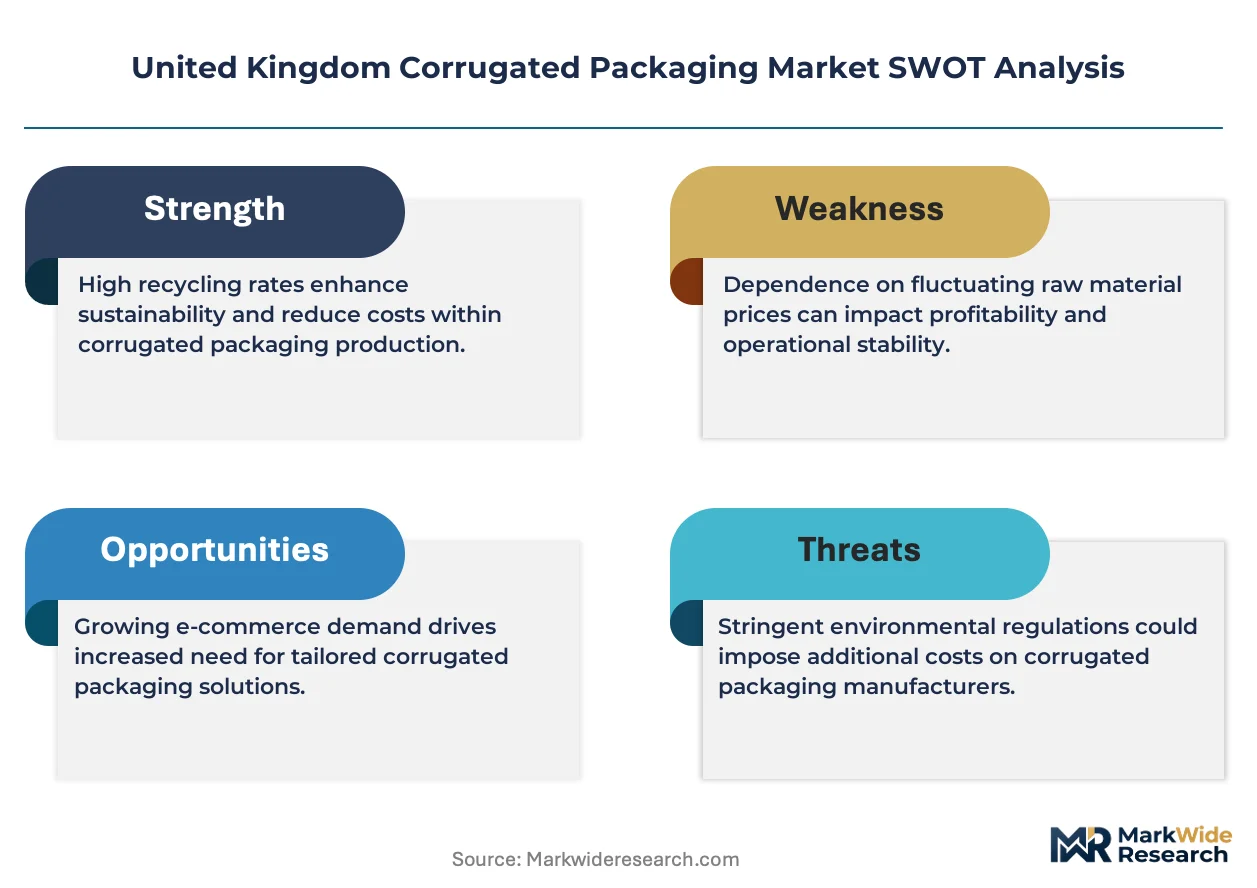
Extended Producer Responsibility reforms are redistributing cost burdens across the United Kingdom corrugated packaging value chain, forcing converters to renegotiate material sourcing contracts and accelerate closed-loop fiber recovery investments.
Growth Catalysts
- E-commerce fulfillment expansion:Automated packing lines in England's Midlands manufacturing corridor are absorbing precision-fit die-cut formats to minimize void fill and dimensional weight charges.
- Packaging Waste Regulations:The UK's Environment Agency mandates minimum recycled content thresholds, creating captive demand for domestically recovered linerboard.
- Lightweighting innovations:High-performance kraft liner developments enable grammage reduction without stack strength compromise, cutting raw material exposure.
Market Restraints
- Recycled pulp quality variability:Inconsistent fiber strength from municipal recovery streams constrains high-grade linerboard output and raises rejection rates.
- Energy cost volatility:Steam-heated corrugators face margin compression from natural gas price swings, particularly at 100–300 meters per minute operating speeds.
- Substitute material encroachment:Reusable plastic totes and flexible film pouches are capturing share in closed-loop retail distribution between fixed nodes.
Strategic Opportunities
- Greater London distribution hub densification:Last-mile consolidation centers are demanding rapid-turn protective formats with print-on-demand branding capabilities.
- Food contact barrier coatings:Water-based and bio-based treatments are opening chilled and greasy food segments previously blocked by waxed alternatives.
- Asset-light equipment leasing:Converting machinery rental models are lowering entry barriers for regional specialists serving niche protective applications.
Industry Challenges
- Corrugator technician scarcity:Specialized knowledge of steam-heated web tension control and flute profile calibration is retiring faster than apprenticeship pipelines replenish.
- Legacy ERP integration:Automated packing line interfaces require real-time dimensional data exchange that older mill systems cannot support without middleware overhauls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Corrugated Packaging Market |
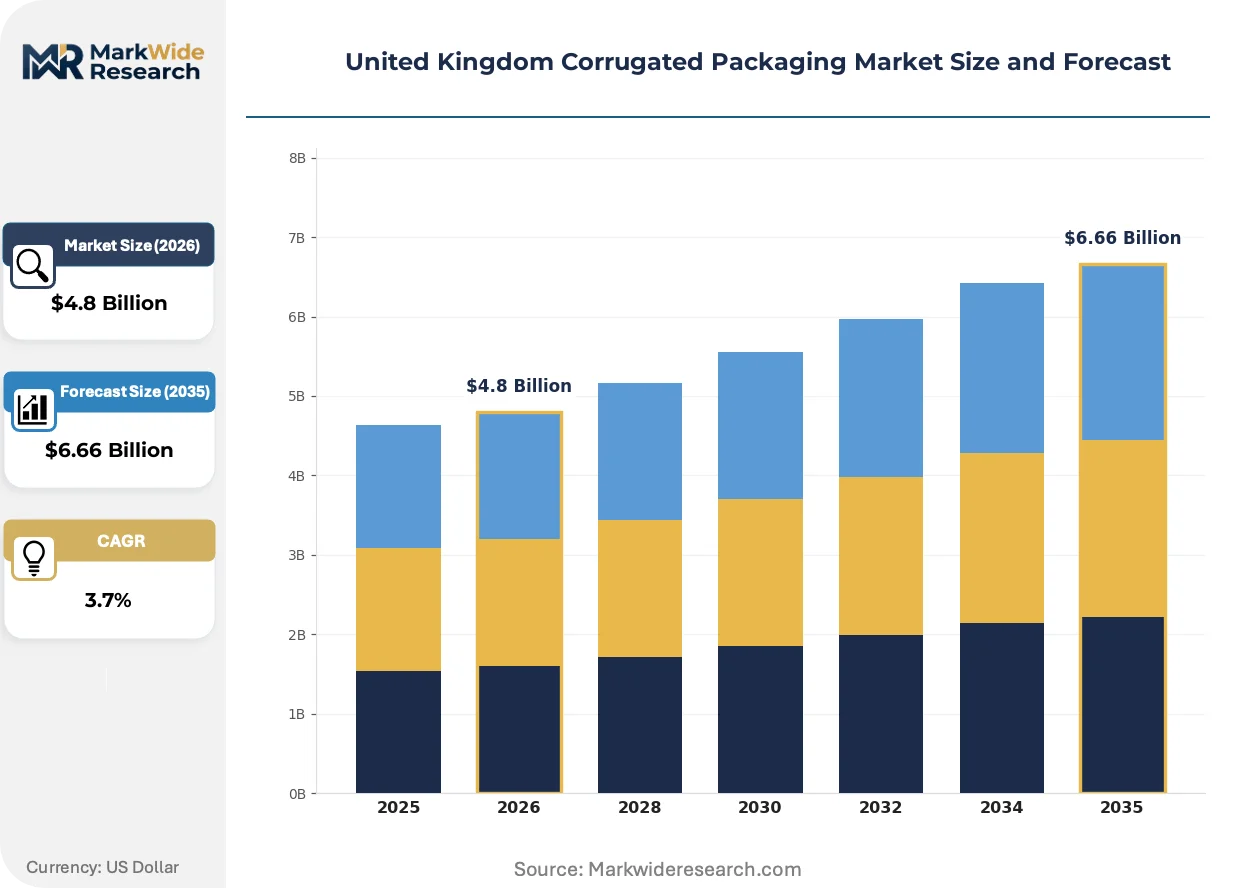
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-wall, Double-wall, Triple-wall, Die-cut End Use Industry: Food & Beverage, Electronics, Personal Care, E-commerce Material: Recycled Paper, Virgin Fiber, Coated Paperboard, Kraft Paper Design Type: Flat, Foldable, Rigid, Custom-shaped |
| Companies Covered | GWP Group Limited, Saica Group, Smurfit WestRock, Atlas Packaging Limited, DS Smith PLC, Mondi Group, Belmont Packaging, Nuttall Packaging, International Paper Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Corrugated Packaging Market Evolving Landscape
Digital print integration and smart packaging interfaces are compressing design-to-delivery cycles while enabling batch-size-one economics previously unattainable at corrugated scale.
Digital inkjet printheads are hybridizing with conventional flexo stations on corrugator outfeeds, enabling variable-data graphics and regional promotional versioning without plate changeover downtime. Major grocery retailers in Greater London are piloting this configuration for seasonal campaigns. The technology is hybridizing make-to-order economics with mass-production throughput, collapsing minimum order quantities from truckload to pallet scale.
The UK's Extended Producer Responsibility framework is tightening material traceability obligations, compelling converters to deploy blockchain-linked chain-of-custody documentation. The Competition and Markets Authority's emerging anti-greenwashing guidance is accelerating third-party certification adoption. Food and beverage processors are responding fastest, demanding Forest Stewardship Council and Programme for the Endorsement of Forest Certification dual accreditation.
Consolidated procurement desks at major e-commerce fulfillment operators are compressing supplier rosters and mandating vendor-managed inventory programs. Third-party logistics providers are displacing direct mill relationships as the primary contracting interface. This concentration is most visible in England's Midlands, where Amazon and Ocado fulfillment networks are consolidating corrugated spend through tier-one integrators with national coverage.
United Kingdom Corrugated Packaging Market Segmentation
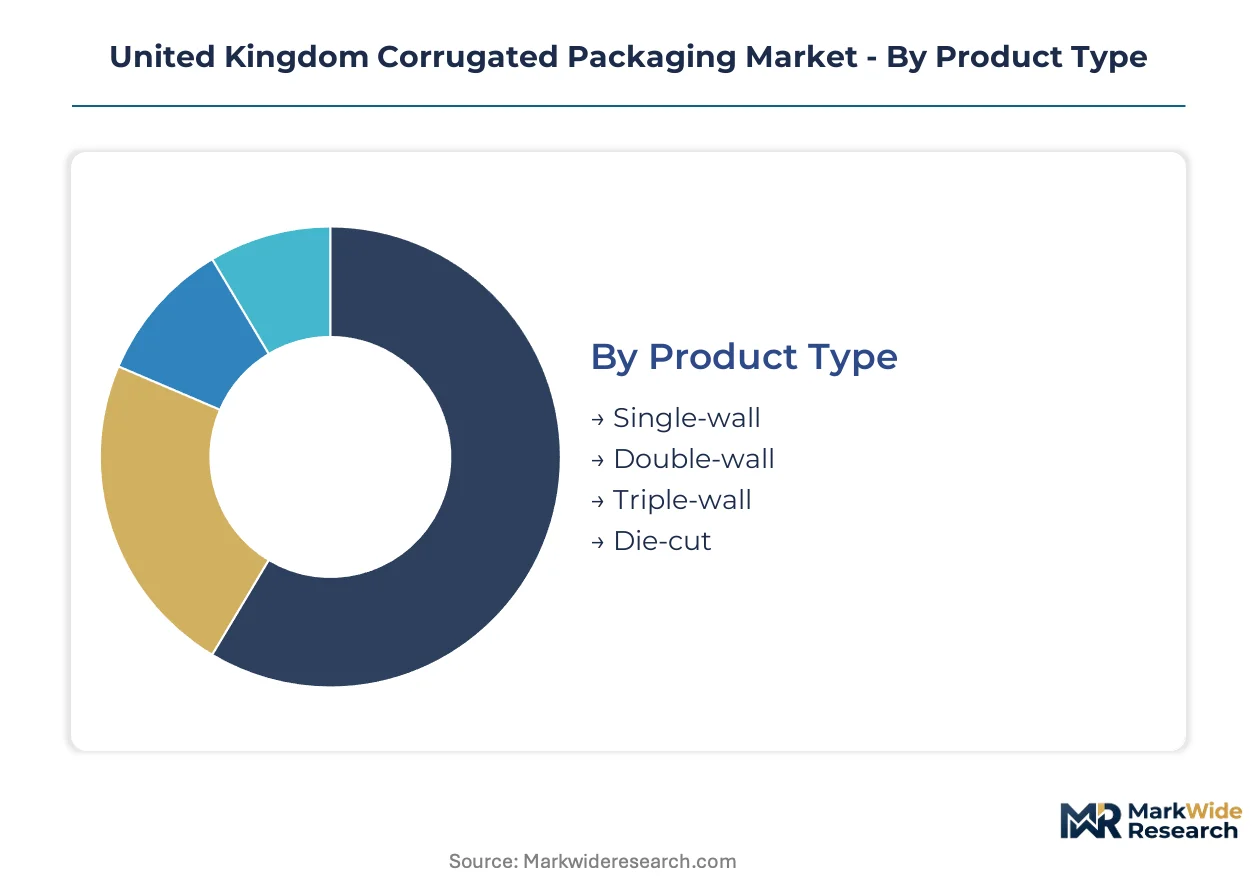
Segmentation in UK corrugated packaging reveals how converter investments align with divergent cycle economics. Product type and end-use splits determine corrugator scheduling priority, while material and design choices govern margin recovery under Extended Producer Responsibility compliance.
Product Type:
Cycle times compress from multi-day runs of commodity formats to same-day turnaround for precision-cut specifications.
- Single-wall:Comprises one fluted medium between two linerboards, typically 125–150 gsm combined grammage. England's Midlands food processors absorb this format for lightweight dry goods where burst strength requirements stay below 12 kg/cm².
- Double-wall:Stacks two fluted layers with three linerboard facings, delivering superior edge crush resistance above 7 kN/m. Greater London distribution hubs specify this construction for heavy-goods e-commerce fulfillment where stack height exceeds 1.5 meters.
- Triple-wall:Heavy-duty industrial specification with three flute profiles laminated for export machinery crating.
- Die-cut:Precision-scored formats produced on flatbed or rotary die cutters for automated packing line integration.
Single-wall anchors the volume base while die-cut gains share at the steepest rate.
End Use Industry:
Customer concentration shapes converter capacity allocation, with fulfillment networks demanding shortest lead times.
- Food & Beverage:Chilled supply chain specifications dominate, requiring moisture-resistant liners and food-contact barrier coatings. Ocado and Tesco consolidation centers in England's Midlands specify rapid-turn formats with print-on-demand branding windows.
- E-commerce:Protective designs with void-fill minimization absorb premium positioning. Amazon fulfillment networks mandate vendor-managed inventory programs with 24-hour replenishment cycles from tier-one integrators.
- Electronics:Anti-static and shock-absorbing inserts for high-value device distribution.
- Personal Care:Shelf-ready packaging with high-graphic print requirements for retail display compliance.
Food & Beverage commands the installed corrugator base while E-commerce climbs the fastest.
Material:
Fiber sourcing economics split between price-volatile virgin kraft and quality-variable recycled streams.
- Recycled Paper:Post-consumer recovered fiber processed through deinking and pulping stages. The UK's Environment Agency mandates minimum thresholds under Packaging Waste Regulations, creating captive demand for domestically sourced linerboard with 80–100% recycled content.
- Virgin Fiber:Unbleached or semi-bleached softwood kraft pulp delivering superior tear index and ring crush values. Mondi Group's high-performance kraft liner innovations enable grammage reduction without stack strength compromise.
- Coated Paperboard:Clay or polymer surface treatments for high-definition print reproduction in retail-ready applications.
- Kraft Paper:Unbleached natural brown grades for industrial wrapping and protective interleaving.
Recycled Paper underpins compliance-driven procurement while Virgin Fiber retains premium positioning for performance-critical specifications.
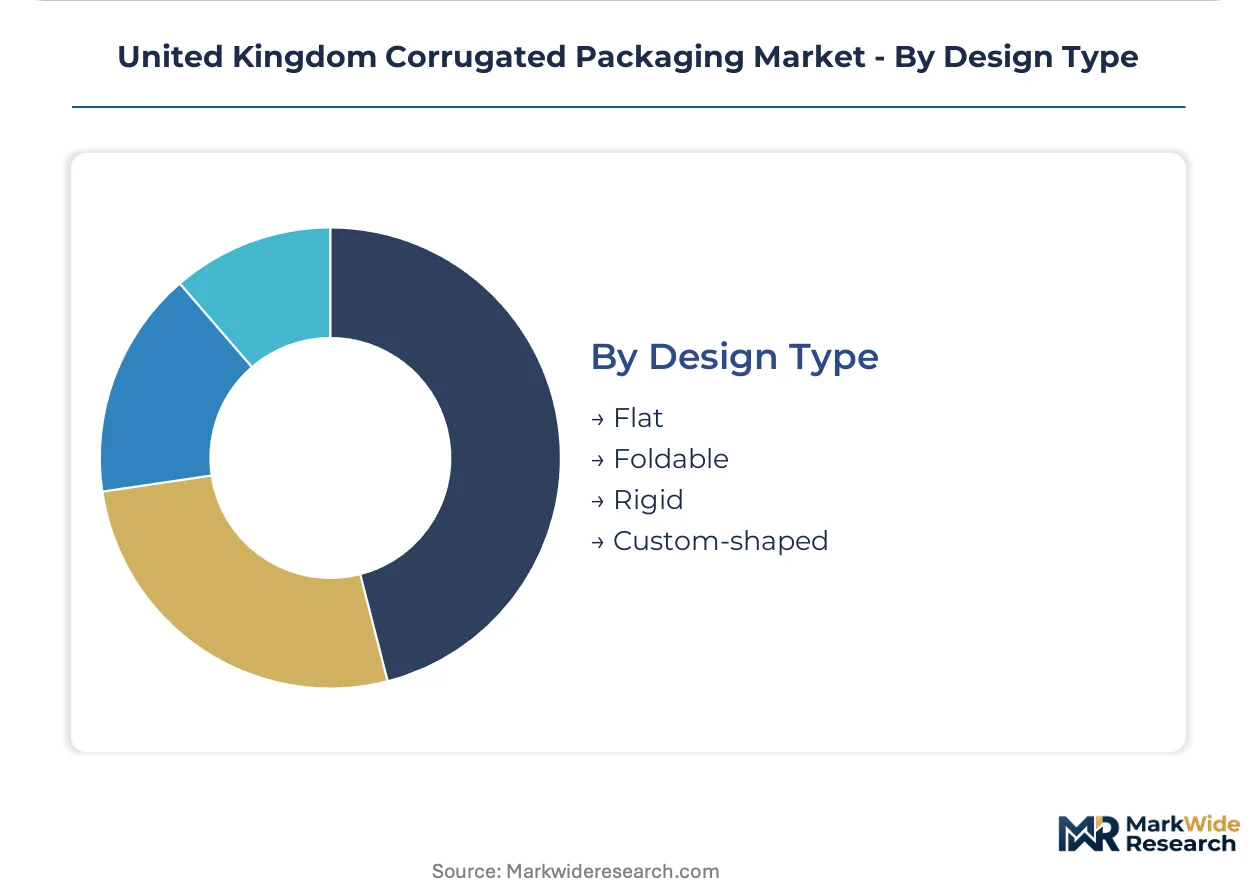
Design Type:
Structural complexity correlates with automation compatibility and dimensional weight optimization.
- Flat:Basic unassembled sheet formats for manual erection at point of use, dominating commodity produce distribution.
- Foldable:Pre-glued or self-locking constructions that collapse for return logistics in closed-loop retail systems.
- Rigid:Heavy-duty fixed formats for industrial machinery and automotive component shipping.
- Custom-shaped:Product-specific contours produced through CAD-driven die engineering for dimensional weight charge minimization.
Flat formats sustain the highest throughput volumes while Custom-shaped designs capture the steepest expansion trajectory among automated packing line adopters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United Kingdom corrugated packaging sector maintains a modest export surplus in specialty grades while importing commodity linerboard from Nordic mills. Regional demand splits between England's manufacturing heartland and Scottish industrial zones, with regulatory divergence between UK-wide Packaging Waste Regulations and Scotland's stricter circular economy targets.
England's Midlands
Food processing plants and automotive component suppliers absorb precision-cut die formats for automated packing integration. The UK's Environment Agency enforces minimum recycled content thresholds through Packaging Waste Regulations. Birmingham and Leicester host dense clusters of tier-two converters serving Ocado and Tesco consolidation centers with rapid-turn protective designs.
Greater London
Last-mile fulfillment networks demand print-on-demand branding capabilities and vendor-managed inventory programs. Extended Producer Responsibility reforms redistribute cost burdens upstream to producers and importers. Amazon and DHL distribution hubs in Dartford and Enfield are consolidating supplier rosters through national integrators.
Scotland
Whisky and seafood exporters require moisture-resistant barrier coatings for chilled supply chains. Scotland's Circular Economy Bill mandates higher recycling targets than UK baseline regulations. Grangemouth and Dundee harbor industrial zones where converters specialize in export-grade triple-wall crating for machinery.
North England
Legacy paper mills and corrugated plants anchor employment in Yorkshire and Lancashire manufacturing corridors. The Competition and Markets Authority scrutinizes green claims under emerging anti-greenwashing guidance. Leeds and Manchester distribution zones are absorbing lightweight single-wall formats for e-commerce parcel consolidation.
Wales
Steel and automotive component manufacturers specify heavy-duty double-wall constructions for export logistics. Welsh Government procurement guidelines favor suppliers with Forest Stewardship Council dual accreditation. Newport and Cardiff industrial parks host mid-scale converters serving Bristol Channel shipping routes.
United Kingdom Corrugated Packaging Market Competitive Landscape
On the supply side, the industry is consolidating around integrated containerboard-to-box networks and specialized protective design houses. Tier-one players command national coverage through multi-site manufacturing footprints, while regional specialists exploit asset-light leasing models for converting equipment. Two strategic archetypes dominate: integrated pulp-to-box operators with captive linerboard supply, and design-led converters focused on e-commerce protective solutions. Competitive intensity centers on M&A-driven scale expansion and vendor-managed inventory program penetration.
Within the integrated operator tier, Smurfit WestRock and DS Smith PLC exemplify scale-driven positioning through British manufacturing site networks. Mondi Group occupies a differentiated position via high-performance kraft liner specialization. Among mid-scale regional fabricators, GWP Group Limited, Saica Group, and Belmont Packaging represent the design-responsive archetype serving niche protective applications with shorter lead times.
| Leading Market Players |
|---|
| GWP Group Limited |
| Saica Group |
| Smurfit WestRock |
| Atlas Packaging Limited |
| DS Smith PLC |
| Mondi Group |
| Belmont Packaging |
| Nuttall Packaging |
| International Paper Company |
| Others |
Value Network & Pricing Analysis
England's Midlands manufacturing corridor concentrates converting capacity for food processors and automotive suppliers, translating upstream linerboard volatility into asymmetric pricing power for tier-one integrators serving Ocado and Tesco consolidation centers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures with volume-scale and certification-grade differentiation. Pricing stratifies across Forest Stewardship Council-accredited premium tiers, standard recycled-content compliance grades, and economy virgin-fiber specifications. Cost compression in standard grades is intensifying because recycled pulp quality variability raises rejection rates. Small regional fabricators exhibit highest price sensitivity, while national e-commerce fulfillment networks tolerate premium positioning for vendor-managed inventory guarantees.
Supply Chain Analysis
Extended payment terms from Nordic linerboard mills and supply-chain finance facilities at British clearing banks lubricate working capital for Midlands converters. Geographic supply concentration draws from Sweden, Finland, and Germany for virgin kraft pulp, with domestic recovered fiber feeding compliance-mandated recycled content. Raw material dependencies rest on softwood pulp, post-consumer recovered paper, and starch-based adhesives. Single-source vulnerability concentrates in high-performance kraft liner imports. Distribution runs through third-party logistics providers displacing direct mill relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reusable plastic totes and flexible film pouches threaten corrugated share in closed-loop retail distribution, forcing incumbents to defend through protective design specialization and barrier coating innovation.
For Market Incumbents: Harden vendor-managed inventory program penetration at Amazon and DHL distribution hubs to lock in replenishment cycles. Deepen backward integration into captive linerboard supply or secure long-term offtake agreements with Nordic mills to insulate against virgin fiber volatility. Prioritize food-contact barrier coating R&D to capture chilled and greasy food segments previously blocked by waxed alternatives.
For New Entrants and Emerging Players: Wales and North England offer geographic underpenetration for mid-scale converters serving steel and automotive component manufacturers with heavy-duty double-wall specifications. Target Forest Stewardship Council dual accreditation gaps among regional specialists. Exploit asset-light equipment leasing models to serve niche protective applications with shorter lead times than national integrators.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because Extended Producer Responsibility reforms will redistribute cost burdens upstream, favoring scaled operators with closed-loop fiber recovery infrastructure. Acquisition targets include design-led converters with e-commerce protective specialization and blockchain-linked chain-of-custody capabilities. Monitor recycled pulp quality variability as the signal for margin compression inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Linerboard Supply | Captive pulp sourcing insulates Smurfit WestRock and DS Smith PLC from Nordic mill price volatility. |
| Food-Contact Barrier Coating Development | Water-based treatments open Ocado and Tesco chilled supply chains previously blocked by waxed alternatives. |
| Blockchain-Linked Chain-of-Custody Deployment | Third-party certification adoption accelerates under Competition and Markets Authority anti-greenwashing guidance. |
| Vendor-Managed Inventory Program Expansion | Amazon fulfillment networks consolidate supplier rosters through tier-one integrators with national coverage. |
| Asset-Light Equipment Leasing Model | Regional specialists lower entry barriers for niche protective applications in England's Midlands corridor. |
Research Methodology
Operator-level perspectives from corrugator technicians, procurement leads at food and beverage processors, third-party logistics contract managers, and linerboard mill sales directors anchored the qualitative base. Secondary validation drew from UK Environment Agency Packaging Waste Regulations filings, Competition and Markets Authority guidance documents, SEC 10-K disclosures of listed packaging groups, and customs trade data on linerboard imports. Bottom-up capacity assessments and top-down demand modeling triangulated volume estimates.
Scenario-bracketing around Extended Producer Responsibility implementation pace and recycled pulp quality variability shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type construction, end-use industry concentration, material sourcing tier, and design automation compatibility. CAGRs derived from historical corrugator throughput trends, e-commerce fulfillment network expansion trajectories, and regulatory compliance cost pass-through assumptions. Industry-specific forecast inputs encompassed steam-heated corrugator energy cost exposure and die-cut precision adoption curves.
Practitioners should monitor virgin fiber price volatility, recycled pulp rejection rate spikes, and natural gas cost swings for early signals of margin compression. Forecasts reflect documented assumptions on regulatory implementation timelines and substitution elasticity. Macroeconomic deviation, regulatory delay, or breakthrough barrier coating technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Letterpress Card Market
Paper & Paperboard Packaging
Cardboard Tubs Market
Paper & Paperboard Packaging
Desiccant Paper Market
Paper & Paperboard Packaging
Wax Paper Medicine Pots Market
Paper & Paperboard Packaging
Plywood Box Market
Paper & Paperboard Packaging
Paper Cups Market
Paper & Paperboard Packaging
Global Multi Depth Corrugated Boxes Market
Paper & Paperboard Packaging
UAE Corrugated Board Packaging Market
Paper & Paperboard Packaging
Paperboard Mailer Market
Paper & Paperboard Packaging
Paper Pleated Cups Market
Paper & Paperboard Packaging
Mottled Test Liner Market
Paper & Paperboard Packaging
Coated Paper Market
Paper & Paperboard Packaging
Medical Packaging Paper Market
Paper & Paperboard Packaging
Foam Cups Market
Paper & Paperboard Packaging
Middle East and Africa Corrugated Box Market
Paper & Paperboard Packaging
Russia Paper Packaging Market