
 Middle East and Africa Paper Cone Market | 2026-2036
Middle East and Africa Paper Cone Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Paper Cone Market Foresight
Market Context
Food service is restructuring demand patterns across the Middle East and Africa Paper Cone Market as quick-service restaurants and cloud kitchens multiply from Lagos to Dubai. Sonoco Products Company leverages its regional manufacturing footprint to supply coated and printed cone formats for beverage and food packaging clients. Smurfit Kappa Group anchors supply through integrated containerboard-to-converting operations that sustain cost competitiveness in price-sensitive North African markets.
Technical Definition and Segment Structure
A paper cone is a tapered cylindrical container formed from kraft paperboard or recycled fiber pulp, typically ranging from 40 to 200 grams per square meter in basis weight, engineered to hold liquids, dry foods, or textile yarns without structural failure. Double-wall constructions command premium positioning in hot-beverage applications across Saudi Arabia and the UAE, where thermal insulation requirements exceed single-wall capabilities. The textile end-user segment in Egypt and Morocco sustains demand for large-format custom cones engineered to precise taper angles for high-speed yarn winding, while food service drives fastest growth in small and medium printed variants.
Regulatory Framework
South Africa's national standards body enforces migration limits on food-contact paperboard, compelling converters to certify coating chemistries and virgin fiber ratios. Egypt's food safety authority and Saudi Arabia's SFDA both mandate labeling disclosures and substance restrictions that shape import qualification timelines for foreign suppliers. Stakeholders must monitor evolving extended producer responsibility frameworks across Gulf states, as packaging waste regulations will soon dictate minimum recycled content thresholds and end-of-life collection infrastructure investments.
Market Dynamics
Food service chains across the Gulf Cooperation Council states are restructuring procurement specifications toward coated and printed formats, while textile spinners in Egypt's Alexandria corridor sustain demand for precision-engineered yarn carriers.
Growth Catalysts
- SFDA food-contact mandates:Saudi Arabia's labeling and substance disclosure requirements are accelerating converter investments in certified coating chemistries for beverage applications.
- Cloud kitchen proliferation:Quick-service restaurant and ghost kitchen expansion from Lagos to Dubai is pulling small-format printed cone procurement.
- Spinning mill clustering:Egypt's Alexandria industrial corridor concentrates textile end-users demanding custom taper angles for high-speed winding operations.
Market Restraints
- Kraft pulp price volatility:Basis weight specifications from 40 to 200 GSM expose converters to fluctuating virgin fiber input costs.
- Single-wall thermal limitations:Hot-beverage applications in Saudi Arabia and the UAE require double-wall constructions that compress margin structures.
- South African compliance friction:Migration limits enforced by the national standards body extend import qualification timelines for foreign suppliers.
Strategic Opportunities
- Morocco textile automation:Underpenetrated spinning mill modernization programs create demand for large-format precision cones.
- Gulf extended producer responsibility:Emerging packaging waste regulations across Gulf states will mandate minimum recycled content thresholds and collection infrastructure.
- Digital print convergence:Combination of flexographic and inkjet technologies enables short-run customization for regional food brands.
Industry Challenges
- Coating chemistry certification:SFDA and Egypt's food safety authority both require substance testing that extends product development cycles.
- Skilled converter labor:Taper angle engineering for textile applications demands specialized die-cutting expertise scarce in North African markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Paper Cone Market |
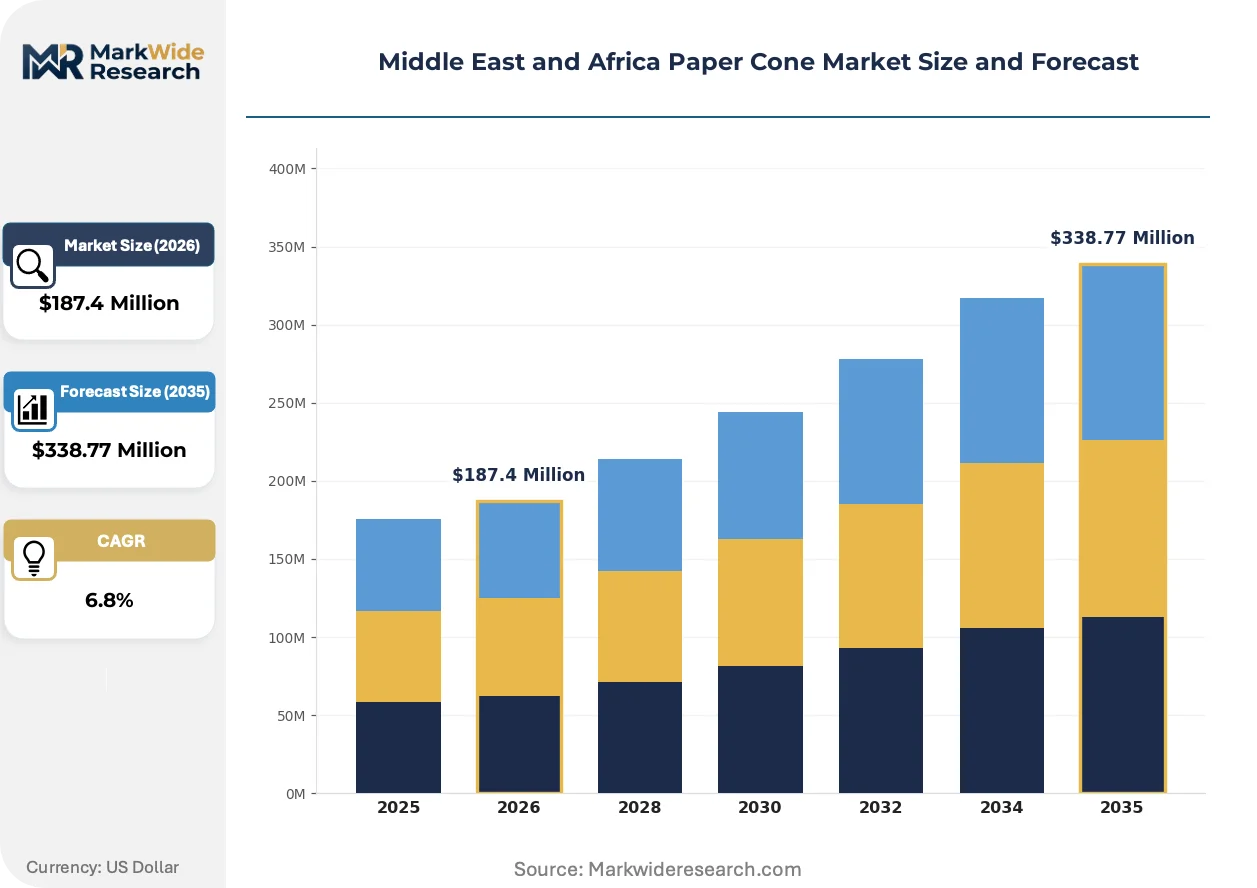
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-wall, Double-wall, Printed, Coated End User: Food Service, Packaging, Beverage, Textile Size: Small, Medium, Large, Custom Distribution Channel: Online, Offline, Direct Sales, Wholesalers |
| Companies Covered | Sonoco Products Company, Conitex Sonoco, SKS Paper Products, Huhtamaki Oyj, Smurfit Kappa Group, Ahlstrom-Munksjo, Paper Machinery Corporation, PTM Packaging Pvt. Ltd., Shree Umiya Paper Cone, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Paper Cone Market Shifts & Advancements
Material science advances and regulatory tightening are reshaping specification standards across food-contact and industrial applications.
Water-based barrier coatings are decentralizing the dominance of polyethylene-lined constructions in hot-beverage service. Quick-service chains in Dubai and Riyadh are piloting these formats for compostability claims. The shift is compressing demand for conventional plastic-laminated stock among mid-tier Gulf distributors.
South Africa's national standards body has tightened migration limits on cellulose-based food-contact materials. Converters must now certify virgin fiber ratios and coating chemistries before market entry. Double-wall hot-beverage formats face the steepest compliance burden given their direct liquid contact surfaces.
Direct mill-to-kitchen procurement is fragmenting traditional distributor channels. Cloud kitchen operators in Lagos and Nairobi are negotiating volume contracts bypassing wholesale intermediaries. This pattern is most visible in mid-size urban clusters where aggregator platforms concentrate order flow.
Middle East and Africa Paper Cone Market Segmentation
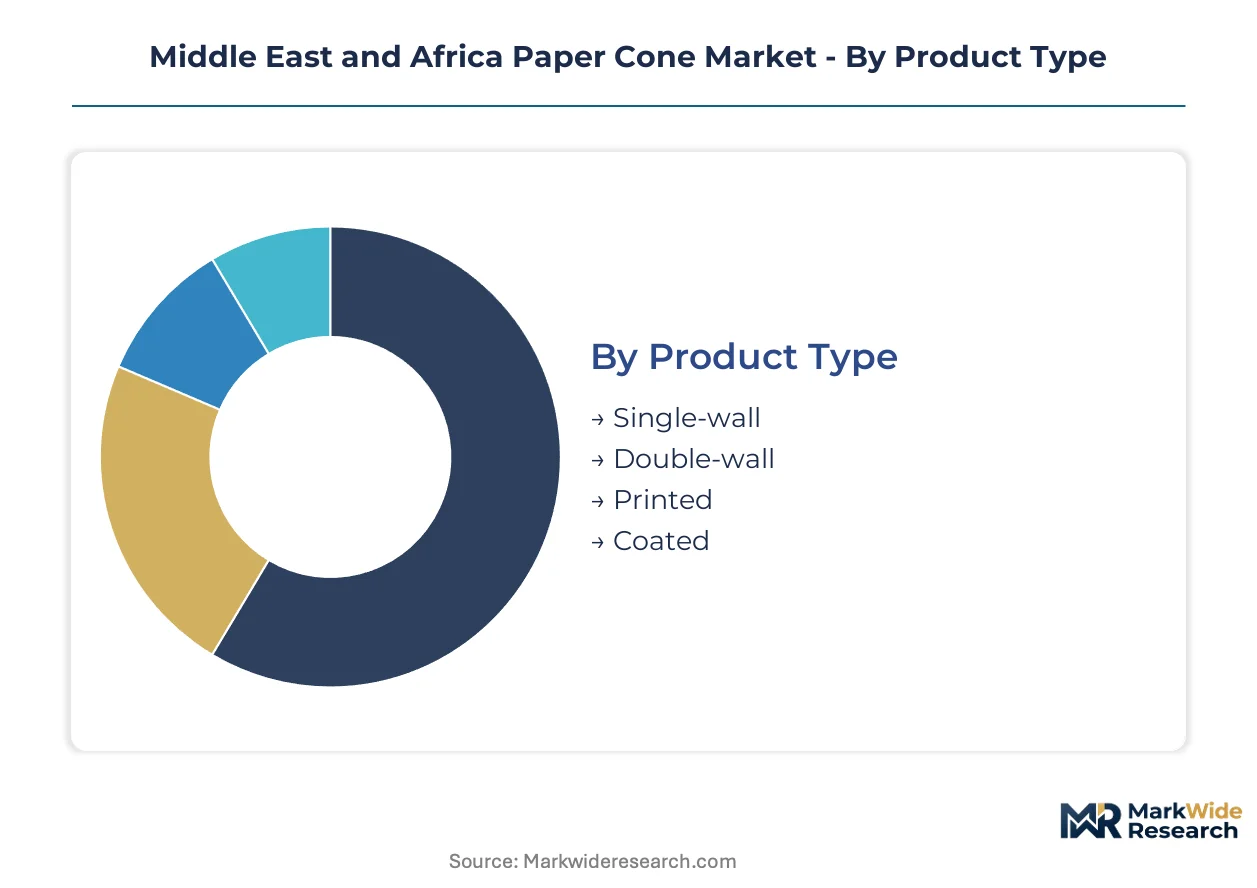
Paper cone specification choices in the Middle East and Africa hinge on thermal performance mandates and food-contact compliance timelines. Procurement patterns diverge sharply between Gulf food-service chains demanding coated formats and Egyptian textile spinners requiring precision-engineered custom geometries.
Product Type:
Upgrade cycles in beverage and food packaging are compressing as Saudi Arabia's SFDA tightens migration limits and hot-service chains seek thermal performance improvements.
- Double-wall:Two-layer kraft construction with inter-wall air gap delivers thermal resistance above 60°C liquid contact. Saudi Arabia and UAE quick-service chains specify this format for coffee and tea service despite 40-60% cost premium over single-wall alternatives.
- Coated:Polyethylene or water-based barrier layers applied to kraft substrate prevent liquid penetration and fiber migration. SFDA certification requirements for coating chemistries are extending product development cycles for Gulf market entry.
- Single-wall:Basic 40-120 GSM kraft construction serves cold-beverage and dry-food applications where thermal insulation is unnecessary.
- Printed:Flexographic or inkjet decoration enables brand differentiation for regional food chains; short-run digital capabilities are displacing traditional plate-based methods for trial volumes.
Double-wall sits at the top of the volume ranking, with Coated climbing the fastest as water-based alternatives displace polyethylene constructions.
End User:
Cost tier segmentation separates premium-certified food-contact applications from industrial specifications where compliance burden is lighter.
- Food Service:Quick-service restaurants and cloud kitchens from Lagos to Dubai drive procurement of small-format printed cones for takeaway packaging. Direct mill-to-kitchen contracting is fragmenting traditional wholesale channels in urban aggregator clusters.
- Textile:Egypt's Alexandria industrial corridor concentrates spinning mill demand for large-format custom cones with precise taper angles engineered for high-speed winding automation.
- Beverage:Hot-drink service specifications mandate double-wall or coated constructions; cold applications tolerate single-wall economics.
- Packaging:Dry-goods and industrial applications utilize uncoated kraft formats with minimal regulatory friction.
Food Service dominates current volume, with Textile expanding most quickly as Moroccan spinning mill modernization accelerates.
Size:
Application requirements and automation compatibility determine dimensional selection across customer types.
- Custom:Textile spinners in Egypt and Morocco specify taper angles and wall thicknesses matched to winding machinery; die-cutting precision requirements limit qualified supplier base.
- Small:100-200ml capacity serves single-serve beverage and condiment portions for Gulf food-service chains.
- Medium:250-400ml range captures standard takeaway coffee and soft-drink applications across urban African markets.
- Large:500ml+ formats address shared portions and industrial yarn winding; limited penetration outside textile segment.
Custom formats lead in value per unit, with Small gaining share fastest through cloud kitchen proliferation.
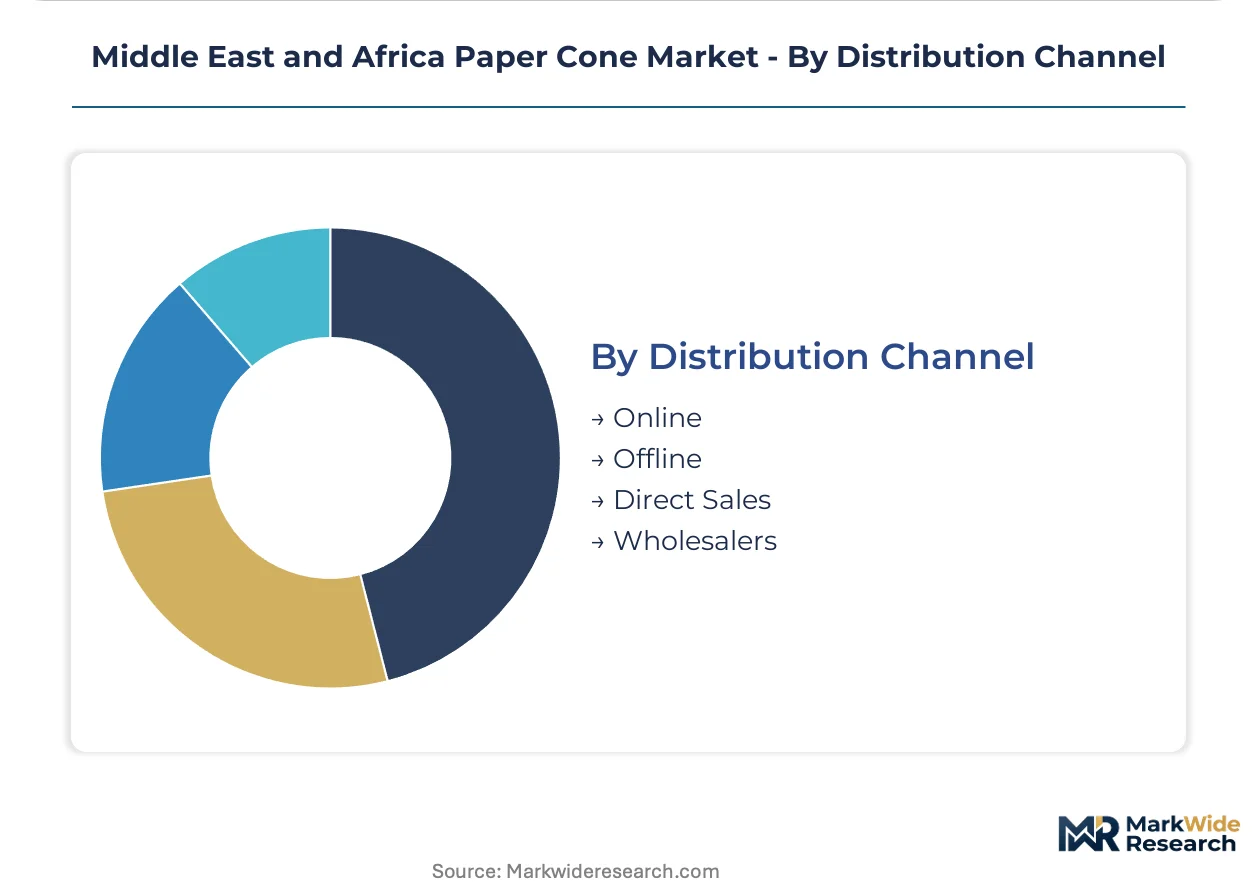
Distribution Channel:
Customer scale and geographic concentration determine channel economics for converter-direct versus intermediary relationships.
- Direct Sales:Cloud kitchen operators and textile mills in Lagos, Nairobi, and Alexandria negotiate volume contracts bypassing wholesale markup.
- Offline:Traditional distributor networks sustain reach into fragmented food-service and packaging accounts across North African secondary cities.
- Wholesalers:Inventory aggregation serves mid-tier Gulf distributors lacking converter-direct qualification for SFDA-compliant stock.
- Online:Digital procurement platforms capture trial volumes and standardized specifications; limited penetration for custom textile formats requiring technical consultation.
Direct Sales commands the highest volume throughput, with Online expanding most rapidly among standardized food-service specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting converter investment toward jurisdictions with streamlined food-contact certification timelines. Egypt and Morocco absorb capacity expansion as Gulf compliance costs escalate.
Saudi Arabia
SFDA migration limits on coating chemistries are accelerating domestic converter certification investments. Hot-beverage chains in Riyadh and Jeddah specify double-wall formats despite 40-60% cost premiums. The Eastern Province industrial corridor hosts expanding integrated containerboard-to-converting operations serving Gulf distribution networks.
UAE
Dubai's cloud kitchen aggregator platforms are fragmenting traditional wholesale procurement channels through direct mill contracting. MOHAP food-contact material disclosures align with Saudi standards, simplifying cross-border qualification. The Jebel Ali free zone concentrates import consolidation for re-export across East Africa and South Asia.
Egypt
Alexandria's spinning mill cluster sustains demand for custom taper-angle cones engineered to high-speed winding specifications. The national food safety authority enforces labeling and substance restrictions that shape import timelines for coated stock. Cairo-based converters are expanding water-based barrier coating capacity for regional food-service export.
South Africa
The national standards body's tightened migration limits on cellulose-based packaging extend foreign supplier qualification cycles. Domestic quick-service chains are consolidating procurement around certified coating chemistries. The Gauteng industrial corridor hosts specialized die-cutting operations serving textile and food-contact segments.
Morocco
Underpenetrated spinning mill modernization programs are generating demand for large-format precision cones. Casablanca-based distributors aggregate North African volume for European converter supply agreements. The Tangier-Med port logistics zone facilitates re-export positioning toward West African markets.
Middle East and Africa Paper Cone Market Competitive Landscape
Capacity expansion dominates the current landscape as regional converters add water-based coating lines to capture SFDA-compliant demand. The vendor base separates into three tiers: integrated multinational packaging groups with captive pulp supply, regional specialists focused on textile precision engineering, and emerging local converters serving fragmented food-service accounts. Strategic differentiation concentrates on coating chemistry certification speed and taper-angle engineering capability for high-speed winding automation.
Among integrated packaging groups, Sonoco Products Company and Smurfit Kappa Group exemplify the scale-driven archetype with regional manufacturing footprints. Conitex Sonoco occupies a position within the precision-engineering tier serving textile automation requirements. These anchors illustrate how competitive positioning splits between Gulf food-service certification speed and North African textile engineering specialization.
| Leading Market Players |
|---|
| Sonoco Products Company |
| Conitex Sonoco |
| SKS Paper Products |
| Huhtamaki Oyj |
| Smurfit Kappa Group |
| Ahlstrom-Munksjo |
| Paper Machinery Corporation |
| PTM Packaging Pvt. Ltd. |
| Shree Umiya Paper Cone |
| Others |
Supply & Pricing Matrix
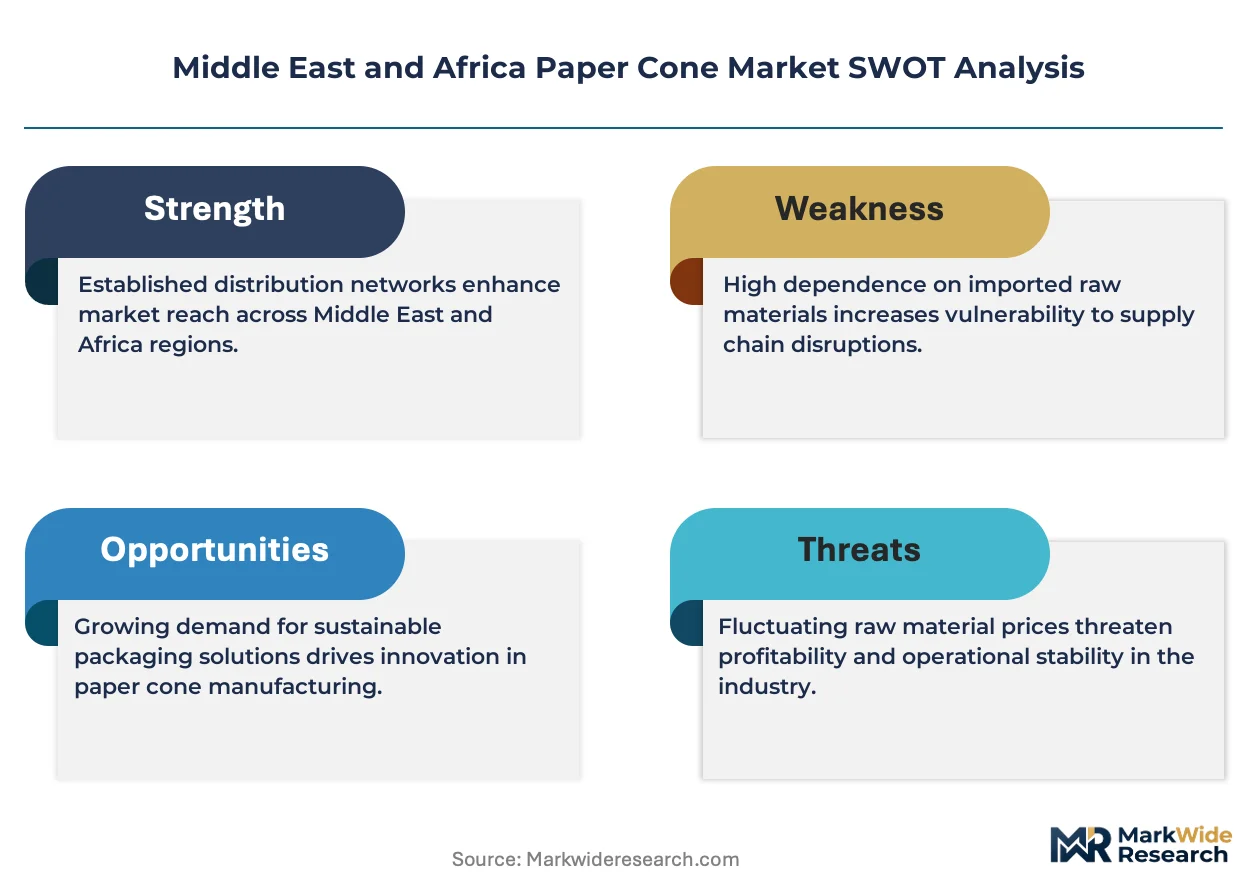
SFDA food-contact compliance mandates gate qualified supply and premium-tier pricing access across Gulf markets, compressing margin structures for converters unable to certify water-based barrier coatings while rewarding integrated players with captive certification capabilities.
Pricing Analysis
Distributor margin layers in traditional wholesale channels absorb 15-25% markup before reaching mid-tier food-service accounts, while direct-to-kitchen contracting eliminates this intermediary layer for cloud kitchen aggregators in Lagos and Nairobi. Three-tier pricing structure across SFDA-certified premium, standard polyethylene-lined, and economy single-wall levels separates buyers by compliance burden and thermal performance requirements. Cost compression in standard polyethylene formats is intensifying because water-based alternatives displace conventional laminated stock among sustainability-positioned Gulf chains. Cloud kitchen operators exhibit highest price sensitivity due to volume procurement and platform-negotiated rates, while Egyptian textile spinners tolerate premium custom engineering costs for precision taper-angle specifications.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale textile mill demand from Alexandria and Casablanca, bypassing distributor aggregation for custom-engineered yarn carriers. Geographic supply concentrates in Egypt for precision textile cones, Saudi Arabia and UAE for Gulf food-service certification, and South Africa for domestic compliance-bound production. Raw material dependencies draw from Scandinavian kraft pulp suppliers, regional containerboard integrators, and water-based coating chemistry specialists. Single-source vulnerability around SFDA-certified coating inputs creates qualification bottlenecks for foreign converters seeking Gulf market entry. Distribution runs through integrated multinational packaging groups with captive pulp supply, regional textile engineering specialists, and emerging local converters serving fragmented accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through water-based coating substitution, as premium-tier SFDA-compliant formats capture 40-60% price premiums over conventional polyethylene constructions while input cost differentials compress.
For Market Incumbents: Extend certification speed advantages by adding dedicated water-based coating lines in Jeddah and Cairo production corridors, defending against emerging local converters in secondary North African cities. Backward integration into regional containerboard supply secures cost competitiveness when virgin fiber volatility spikes. Channel control through direct mill-to-kitchen contracting locks in cloud kitchen volume before wholesale intermediaries adapt. For New Entrants and Emerging Players: The 35-50% price-point gap between SFDA-certified premium and economy single-wall tiers creates entry space for mid-tier water-based formats targeting Moroccan spinning mill modernization and Kenyan cloud kitchen clusters. Underpenetrated textile automation in Casablanca and Tangier offers the most penetrable geography for precision cone engineering. A technical sales-led go-to-market angle emphasizing taper-angle customization and die-cutting consultation differentiates against commodity food-service suppliers. For Investors and Strategic Acquirers: Roll-up economics work for regional textile cone specialists because customer tooling lock-in and custom engineering capabilities create sticky revenue streams resistant to price competition. The five-to-ten year viability window favors acquisitions of Egyptian and Moroccan precision-engineering shops with established spinning mill relationships. Watch SFDA enforcement intensity across Saudi Arabia's Eastern Province industrial corridor as the signal for premium-tier demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Coating Line Expansion | Captures SFDA-compliant demand from Riyadh and Dubai hot-beverage chains seeking compostability claims. |
| Direct Mill-to-Kitchen Contracting | Bypasses wholesale markup for Lagos and Nairobi cloud kitchen aggregators consolidating order flow. |
| Precision Taper-Angle Engineering Investment | Serves Alexandria and Casablanca textile automation with custom die-cutting capabilities scarce in North Africa. |
| Regional Containerboard Integration | Secures virgin fiber cost stability for price-sensitive North African food-service and packaging accounts. |
| Digital Print Capability Addition | Enables short-run brand customization for trial volumes displacing traditional plate-based flexographic methods. |
Research Methodology
Multiple input streams — converter production data, distributor inventory flows, and regulatory filing analysis — were reconciled through structured primary interviews with coating chemistry specialists, textile mill procurement directors, and food-service chain supply managers, validated against secondary sources including SFDA substance disclosure registries, Egyptian food safety authority labeling directives, South African national standards body migration limit publications, and trade flow records from Jebel Ali and Tangier-Med port authorities. Bottom-up volume estimates from individual converter capacity and top-down demand segmentation from end-user procurement patterns were cross-referenced for consistency.
Data-stream reconciliation across the modeling period applied product-type segmentation by wall construction and coating chemistry, end-user segmentation by food-service, textile, beverage, and packaging applications, and geographic segmentation by national regulatory cluster. CAGRs were derived from trend extrapolation of procurement volume patterns and substitution dynamics between polyethylene and water-based barrier formats. Forecast inputs incorporated SFDA enforcement trajectory, spinning mill automation adoption curves in Morocco and Egypt, and cloud kitchen platform expansion rates across urban African markets.
Caveats apply where kraft pulp price volatility, regulatory enforcement delays, or water-based coating performance failures in high-temperature applications could materially shift the outlook. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Paper Bag Box Market
Paper & Paperboard Packaging
Release Paper Market
Paper & Paperboard Packaging
Tissue and Hygiene Paper Packaging Market
Paper & Paperboard Packaging
Fast Food Wrapping Paper Market
Paper & Paperboard Packaging
Cold Waxed Paper Cups Market
Paper & Paperboard Packaging
Protective Paperboard Market
Paper & Paperboard Packaging
Waxing Base Paper Market
Paper & Paperboard Packaging
Corrugated Boxes Market
Paper & Paperboard Packaging
MMA Film & Sheet Market
Paper & Paperboard Packaging
Envelope Market
Paper & Paperboard Packaging
Coated Paper Market
Paper & Paperboard Packaging
Ovenable Paperboard Trays Market
Paper & Paperboard Packaging
Global Paper Bags Market
Paper & Paperboard Packaging
Paperboard Packaging Market
Paper & Paperboard Packaging
Global Sack Kraft Paper Market
Paper & Paperboard Packaging
Malaysia Corrugated Boxes Market