
 Paperboard Protectors Market | 2026-2036
Paperboard Protectors Market Size, Share, and Industry Trends Forecast 2026-2036
Paperboard Protectors Market Analytics
Food-grade virgin kraft liner specifications is reorganizing procurement priorities among premium converters. Smurfit Kappa Group leverages its integrated European pulp network to secure consistent linerboard supply. Sonoco Products Company anchors its North American position through dedicated structural packaging R&D facilities. Cascades Inc. differentiates via closed-loop recycled fiber systems that reduce virgin pulp dependence.
Paperboard protectors are engineered paper-based structural elements, typically fabricated from multi-ply linerboard or fluted medium with calipers ranging from 0.4 to 3.0 millimeters, designed to absorb impact loads and distribute compression forces across palletized or unitized cargo. Edge protectors reinforce vertical load-bearing corners during stacked warehousing, while corner protectors shield high-value finished goods from strapping damage and forklift impact. Recycled paperboard commands volume leadership in cost-sensitive logistics applications, though kraft paperboard retains margin concentration in moisture-resistant and food-contact specifications where fiber purity standards apply.
FDA food-contact substance regulations govern paperboard compositions for direct and indirect food packaging applications in the United States, while the EU Packaging and Packaging Waste Regulation mandates minimum recycled content thresholds and extended producer responsibility schemes across member states. The Chinese GB standards for packaging materials impose heavy metal limits and recyclability labeling requirements that exporters must satisfy for market access. Stakeholders must evaluate how diverging national recycling infrastructure capabilities will reshape material qualification protocols and regional sourcing footprints.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is forcing converters to requalify fiber sourcing and recalibrate recycled content ratios across product lines, compressing lead times for specification changes.
Growth Catalysts
- EU recycled content mandates:Minimum thresholds under the EU Packaging and Packaging Waste Regulation are accelerating demand for closed-loop paperboard systems in automotive parts logistics.
- E-commerce fulfillment center expansion:Edge and corner protector orders from automated distribution hubs are concentrating in Germany and the Netherlands.
- Heavy-duty pallet protection:German automotive exports require multi-ply caliper specifications that absorb forklift impact loads during stacked warehousing.
Market Restraints
- Recycled fiber cost volatility:OCC (old corrugated containers) price swings in European spot markets destabilize converter margin structures.
- Supply concentration in Nordic pulp:Bleached kraft liner availability depends on a narrow supplier base in Sweden and Finland.
- Moisture resistance limitations:Standard recycled paperboard fails food-contact specifications where FDA or EFSA fiber purity standards apply.
Strategic Opportunities
- Poland and Czech Republic logistics hubs:Underpenetrated Central European markets offer white space for pallet protection systems serving east-west freight corridors.
- Food-grade barrier coatings:Water-based treatments that maintain recyclability streams are capturing premium slots in direct-contact applications.
- Extended producer responsibility schemes:EU fee structures reward converters with verified closed-loop fiber recovery rates.
Industry Challenges
- GB standards compliance timelines:Chinese heavy metal limits and recyclability labeling requirements extend qualification cycles for export-bound production.
- Legacy equipment retrofit costs:Caliper range expansion from 0.4 to 3.0 millimeters demands press modifications that strain mid-cap converter balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paperboard Protectors Market |
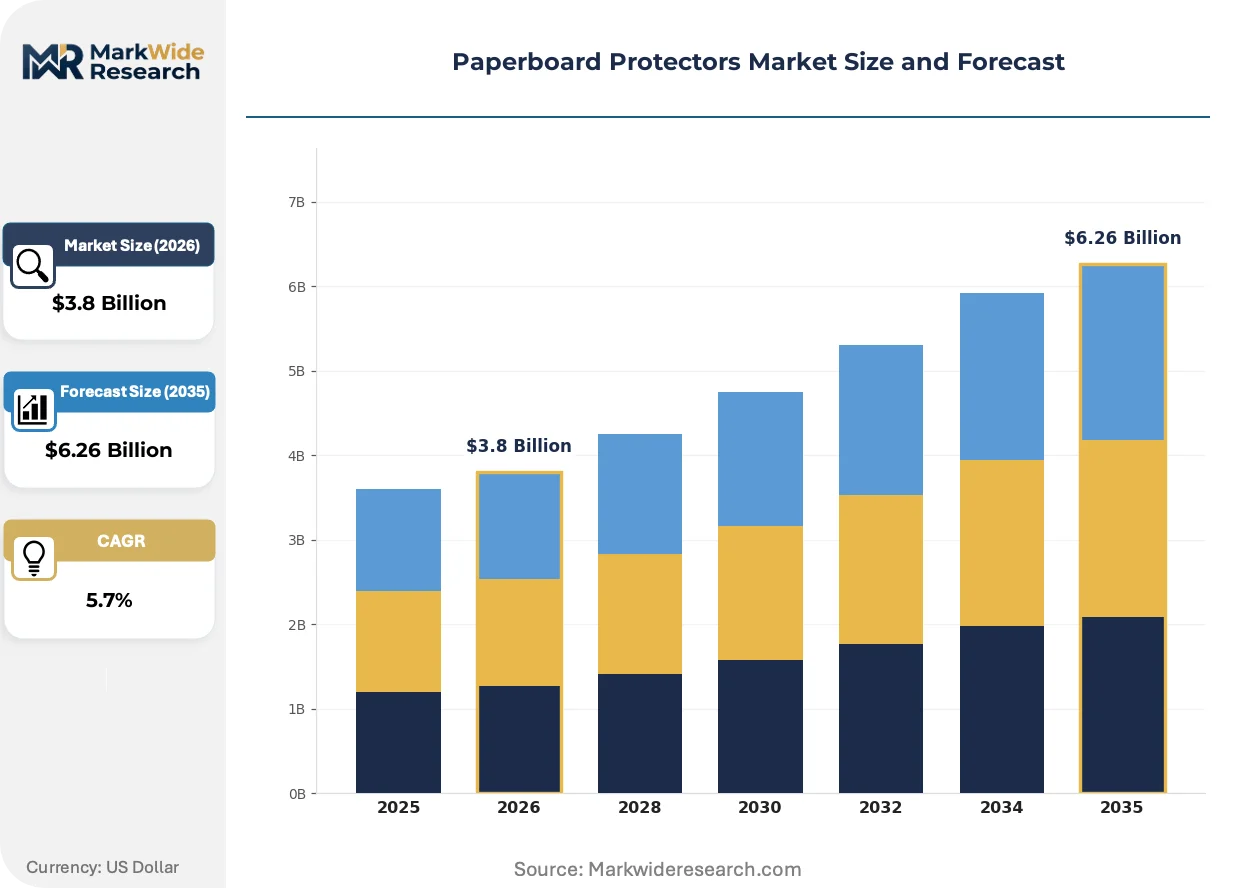
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corrugated Protectors, Edge Protectors, Corner Protectors, Pallet Wraps Application: Packaging, Transportation, Storage, Display End User: Retail, E-Commerce, Manufacturing, Logistics Material: Recycled Paperboard, Kraft Paperboard, Coated Paperboard, Others |
| Companies Covered | Smurfit Kappa Group, Sonoco Products Company, Packaging Corporation of America, VPK Packaging Group, Cascades Inc., Rengo Co., Ltd., Pratt Industries, Pactiv LLC, Napco National, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paperboard Protectors Market Evolving Landscape
Material science advances and regulatory stringency are compressing specification cycles while opening premium tiers for certified sustainable alternatives.
High-performance molded fiber corner protectors are displacing expanded polystyrene in electronics and appliance packaging. German white goods manufacturers are specifying these formats for export shipments to meet retailer sustainability scorecards. The shift is displacing virgin plastic foam demand in European appliance supply chains while compressing unit economics for traditional paperboard converters.
The EU Packaging and Packaging Waste Regulation mandates minimum recycled content thresholds and modulated extended producer responsibility fees. Converters must document fiber provenance through mass-balance certification to access reduced fee tiers. Premium food-contact specifications face the steepest compliance burden, as kraft liner purity requirements conflict with recycled content targets.
Automotive tier-one suppliers are consolidating packaging specifications across continental production networks. Single-source qualification for edge protectors now spans plants in Germany, Spain, and Romania, replacing country-specific procurement. This concentration is visible most acutely in German automotive export corridors, where pallet protection systems must satisfy divergent retailer requirements across destination markets.
Paperboard Protectors Market Segmentation
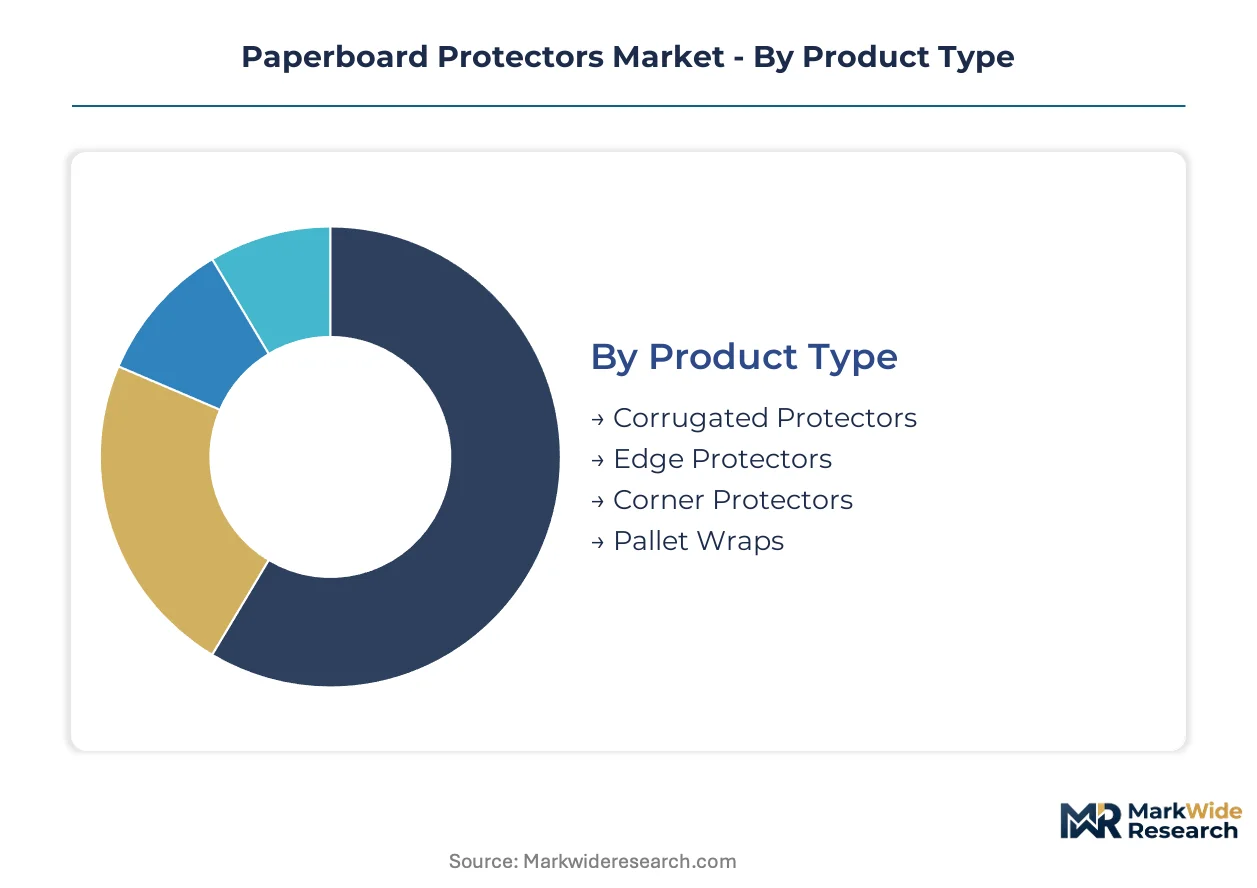
Paperboard protectors serve divergent functional requirements across logistics chains, from impact absorption in heavy pallet loads to cosmetic protection for retail-ready goods. Specification tiers separate commodity logistics applications from food-contact and moisture-resistant segments where fiber purity commands premium positioning.
Product Type:
Margin pools concentrate in multi-ply caliper specifications serving German automotive export corridors, where forklift impact resistance justifies unit price premiums over standard logistics grades.
- Edge Protectors:Fabricated from laminated linerboard with calipers ranging from 1.5 to 3.0 millimeters, these vertical load-bearing elements reinforce pallet corners during stacked warehousing. Demand concentrates in automated German distribution hubs serving east-west freight corridors, driven by EU recycled content mandates that favor closed-loop fiber systems in automotive parts logistics.
- Corner Protectors:Molded or folded structural elements shield high-value finished goods from strapping damage and forklift impact during unitized transport. E-commerce fulfillment centers in the Netherlands and Germany are expanding orders for automated-compatible formats that integrate with robotic palletizing systems.
- Corrugated Protectors:Fluted medium constructions absorb distributed compression loads across pallet surfaces.
- Pallet Wraps:Sheet-form paperboard layers provide base protection for unitized cargo.
Edge protectors hold installed capacity. Corner protectors are rotating up the share rankings.
Application:
Application mix tracks directly to supply chain node requirements, with transportation and storage commanding volume leadership while display applications capture margin concentration through retail-ready specifications.
- Transportation:Heavy-duty specifications for palletized cargo moving through international freight corridors absorb dynamic compression and impact loads during multimodal handoffs. German automotive tier-one suppliers are consolidating packaging specifications across continental production networks in Germany, Spain, and Romania.
- Packaging:Direct-contact and indirect food packaging applications face the steepest compliance burden under FDA food-contact substance regulations and EU Packaging and Packaging Waste Regulation recycled content targets.
- Storage:Static load-bearing requirements in stacked warehousing favor cost-optimized recycled fiber constructions.
- Display:Retail-ready formats with printed graphics and structural integrity for shelf presentation.
Transportation holds installed capacity. Packaging is rotating up the share rankings.
End User:
End user segmentation reflects procurement concentration patterns, with e-commerce and logistics sectors driving specification standardization while manufacturing retains fragmented legacy sourcing.
- Logistics:Third-party fulfillment operators and freight consolidators specify standardized edge and corner protection systems across multi-client operations. Central European logistics hubs in Poland and the Czech Republic offer white space for pallet protection systems serving east-west freight corridors.
- E-Commerce:Automated distribution centers demand dimensionally consistent protectors compatible with robotic palletizing and depalletizing equipment. Order concentration in Germany and the Netherlands is compressing lead times for specification changes.
- Manufacturing:Automotive and appliance producers qualify single-source specifications across continental production networks.
- Retail:Sustainability scorecards from European retailers are displacing virgin plastic foam demand in favor of molded fiber alternatives.
Logistics holds installed capacity. E-commerce is rotating up the share rankings.
Material:
Material tiering separates cost-sensitive logistics applications from premium segments where fiber purity standards govern food-contact and moisture-resistant specifications.
- Kraft Paperboard:Virgin fiber constructions with controlled moisture resistance and food-contact compliance under FDA and EFSA fiber purity standards. Premium food-contact specifications face the steepest compliance burden as kraft liner purity requirements conflict with EU recycled content targets.
- Recycled Paperboard:Closed-loop fiber systems from OCC streams dominate cost-sensitive logistics applications. EU Packaging and Packaging Waste Regulation mandates are accelerating demand for verified closed-loop fiber recovery rates that access reduced extended producer responsibility fee tiers.
- Coated Paperboard:Water-based barrier treatments that maintain recyclability streams are capturing premium slots in direct-contact applications.
- Others:Hybrid and specialty fiber blends for niche performance requirements.
Recycled paperboard holds installed capacity. Kraft paperboard is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Swedish and Finnish bleached kraft liner capacity anchors premium fiber supply for moisture-resistant specifications. German automotive export corridors concentrate heavy-duty pallet protection demand. Chinese GB standards compliance timelines reshape qualification cycles for converters serving Asia-Pacific freight networks.
Germany
Automotive tier-one suppliers consolidate packaging specifications across plants in Bavaria, Baden-Württemberg, and Lower Saxony. The EU Packaging and Packaging Waste Regulation mandates minimum recycled content thresholds that compress lead times for specification changes. Stuttgart and Wolfsburg production clusters drive multi-ply caliper demand for forklift impact resistance in stacked warehousing.
United States
FDA food-contact substance regulations govern paperboard compositions for direct and indirect food packaging applications across Midwest and Southeast distribution hubs. Extended producer responsibility schemes remain state-level rather than federal, creating patchwork compliance obligations. Chicago and Atlanta logistics corridors anchor edge protector demand from automated e-commerce fulfillment centers.
China
GB standards for packaging materials impose heavy metal limits and recyclability labeling requirements that exporters must satisfy for market access. NMPA and MIIT oversight extends to fiber purity documentation for food-contact shipments. Yangtze River Delta manufacturing clusters in Shanghai and Jiangsu province concentrate converter capacity serving export-bound production.
Netherlands
Rotterdam port logistics and automated distribution hubs in Randstad expand orders for robotic palletizing-compatible corner protector formats. ECHA chemical compliance frameworks intersect with EU Packaging and Packaging Waste Regulation recycled content mandates. Eindhoven's high-tech manufacturing corridor generates precision packaging specifications for electronics exports.
Poland
Central European logistics hubs in Warsaw and Łódź offer white space for pallet protection systems serving east-west freight corridors. EU cohesion funds accelerate warehouse automation adoption that standardizes protector specifications. Silesian manufacturing zones attract automotive supplier investments that replicate German packaging qualification protocols.
Paperboard Protectors Market Competitive Landscape
Concentration sits with integrated European pulp networks and North American structural packaging specialists. Tier-one converters maintain captive linerboard supply through backward integration into Nordic pulp assets. Mid-cap regional fabricators compete on specification flexibility and lead time compression. Dominant competitive moves include capacity expansion in Central European logistics corridors and portfolio diversification into food-grade barrier coatings.
Among Irish-registered integrated packaging groups, Smurfit Kappa Group exemplifies the pulp-captive archetype through European fiber network control. US-based Sonoco Products Company anchors the structural packaging specialist position with dedicated R&D facilities. Canadian converter Cascades Inc. occupies the closed-loop recycled fiber tier, reducing virgin pulp dependence through verified recovery systems.
| Leading Market Players |
|---|
| Smurfit Kappa Group |
| Sonoco Products Company |
| Packaging Corporation of America |
| VPK Packaging Group |
| Cascades Inc. |
| Rengo Co., Ltd. |
| Pratt Industries |
| Pactiv LLC |
| Napco National |
| Others |
Value Network & Pricing Analysis
Sixty-day linerboard inventory cycles in European converter networks concentrate pricing power with Nordic pulp suppliers while compressing margin buffers for mid-cap fabricators serving automotive logistics corridors.
Pricing Analysis
The EU Packaging and Packaging Waste Regulation dictates the pricing tier structure across paperboard protector categories, enforcing three-tier pricing stratification across premium food-contact kraft specifications, standard recycled fiber logistics grades, and economy uncalibrated edge protectors. Price differentiation rests on mass-balance certification status and moisture-resistant barrier coating inclusion, with certified closed-loop systems commanding fifteen to twenty percent premiums over uncertified alternatives. Pricing pressure stems from OCC spot market volatility destabilizing converter input costs, particularly for German automotive tier-one suppliers consolidating specifications. Logistics sector buyers exhibit highest price sensitivity due to standardized multi-client operations, while food-contact applications show lowest sensitivity given FDA and EFSA compliance requirements.
Supply Chain Analysis
Strategic stockpile preferences dominate Nordic bleached kraft liner procurement, contrasting with just-in-time OCC sourcing for recycled fiber systems. Supply concentrates in Sweden, Finland, and Germany, with Swedish and Finnish pulp assets anchoring premium fiber availability and German converter capacity serving automotive export demand. Raw material dependencies center on OCC streams, virgin kraft linerboard, and water-based barrier coating chemistries. Single-source vulnerability sits with Nordic bleached kraft liner supply, where mill maintenance cycles or energy cost spikes transmit rapidly through specification tiers. Distribution runs through automated fulfillment hubs in Germany and the Netherlands, with secondary channels serving Central European logistics corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The paperboard protectors market is reshaping around EU regulatory stringency, with recycled content mandates and extended producer responsibility schemes compressing specification cycles while opening premium tiers for certified sustainable alternatives.
For Market Incumbents: Secure captive linerboard supply through backward integration into Nordic pulp networks or long-term offtake agreements with Swedish and Finnish suppliers. Invest in mass-balance certification infrastructure to access reduced EPR fee tiers and defend margin position against emerging molded fiber substitutes displacing traditional edge protectors in electronics packaging. For New Entrants and Emerging Players: Lead with food-grade barrier coating capabilities targeting premium direct-contact applications where kraft liner purity requirements conflict with recycled content targets. Poland and Czech Republic logistics hubs offer penetrable white space for pallet protection systems serving east-west freight corridors, with EU cohesion funds accelerating warehouse automation adoption that standardizes protector specifications. For Investors and Strategic Acquirers: Carve-out targets emerge from integrated packaging groups divesting non-core structural packaging divisions amid portfolio consolidation toward fiber-light solutions. Five-to-ten year viability favors converters with verified closed-loop recovery rates and automotive qualification protocols spanning multiple continental production networks. Monitor ECHA chemical compliance framework expansions as inflection indicators for barrier coating technology acquisition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nordic Pulp Assets | Secures bleached kraft liner supply for moisture-resistant specifications serving German automotive exports. |
| Mass-Balance Certification Investment | Unlocks reduced EU extended producer responsibility fee tiers for closed-loop fiber systems. |
| Food-Grade Barrier Coating Development | Captures premium positioning in direct-contact applications facing FDA and EFSA compliance burdens. |
| Central European Logistics Hub Expansion | Addresses underpenetrated Poland and Czech Republic markets serving east-west freight corridors. |
| Molded Fiber Corner Protector Scale-Up | Displaces expanded polystyrene in electronics and appliance packaging per retailer sustainability scorecards. |
Research Methodology
Cross-validation between primary interviews with converter operations directors, automotive packaging engineers, and logistics procurement leads and secondary validation through EU regulatory filings, trade association statistics, and customs data anchors the qualitative findings. The approach combines bottom-up capacity surveys at German, Dutch, and Polish converter facilities with top-down demand modeling from automotive production databases and e-commerce fulfillment center expansion trackers.
Sensitivity analysis across recycled content mandate implementation timelines and OCC price volatility bands informs the projection framework. Segmentation dimensions modeled include product type tier, material grade, end-use sector, and regional regulatory cluster. CAGRs derive from unit volume trajectories in transportation and packaging applications, with specific inputs including German automotive export volumes and automated warehouse capital expenditure disclosures.
The analysis sits within stated boundaries; outcomes outside EU Packaging and Packaging Waste Regulation enforcement intensity or Nordic pulp supply continuity would require recalibration. Forecasts reflect documented assumptions about specification consolidation rates and barrier coating adoption curves. Practitioners should keep alternative scenarios live as ECHA chemical compliance expansions and Chinese GB standards enforcement timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Self-Sealing Paper Bands Market
Paper & Paperboard Packaging
Cardboard Tubs Market
Paper & Paperboard Packaging
Binder's Board Market
Paper & Paperboard Packaging
Paper Band Market
Paper & Paperboard Packaging
Middle East and Africa Paper Packaging Market
Paper & Paperboard Packaging
Foam Cups Market
Paper & Paperboard Packaging
Disposable Paper Cups Market
Paper & Paperboard Packaging
Paper Cones Market
Paper & Paperboard Packaging
Kraft Paper Shopping Bag Market
Paper & Paperboard Packaging
Asia-Pacific Paper Cone Market
Paper & Paperboard Packaging
France Paper Packaging Market
Paper & Paperboard Packaging
Japan Paper Packaging Market
Paper & Paperboard Packaging
Paper Waste Strippers Market
Paper & Paperboard Packaging
Plastic Toilet Paper Dispenser Market
Paper & Paperboard Packaging
Paper and Paperboard Trays Market
Paper & Paperboard Packaging
Die Cut Box Market