
 Paper Wrap Market | 2026-2036
Paper Wrap Market Size, Share, and Industry Trends Forecast 2026-2036
Paper Wrap Market Analytics
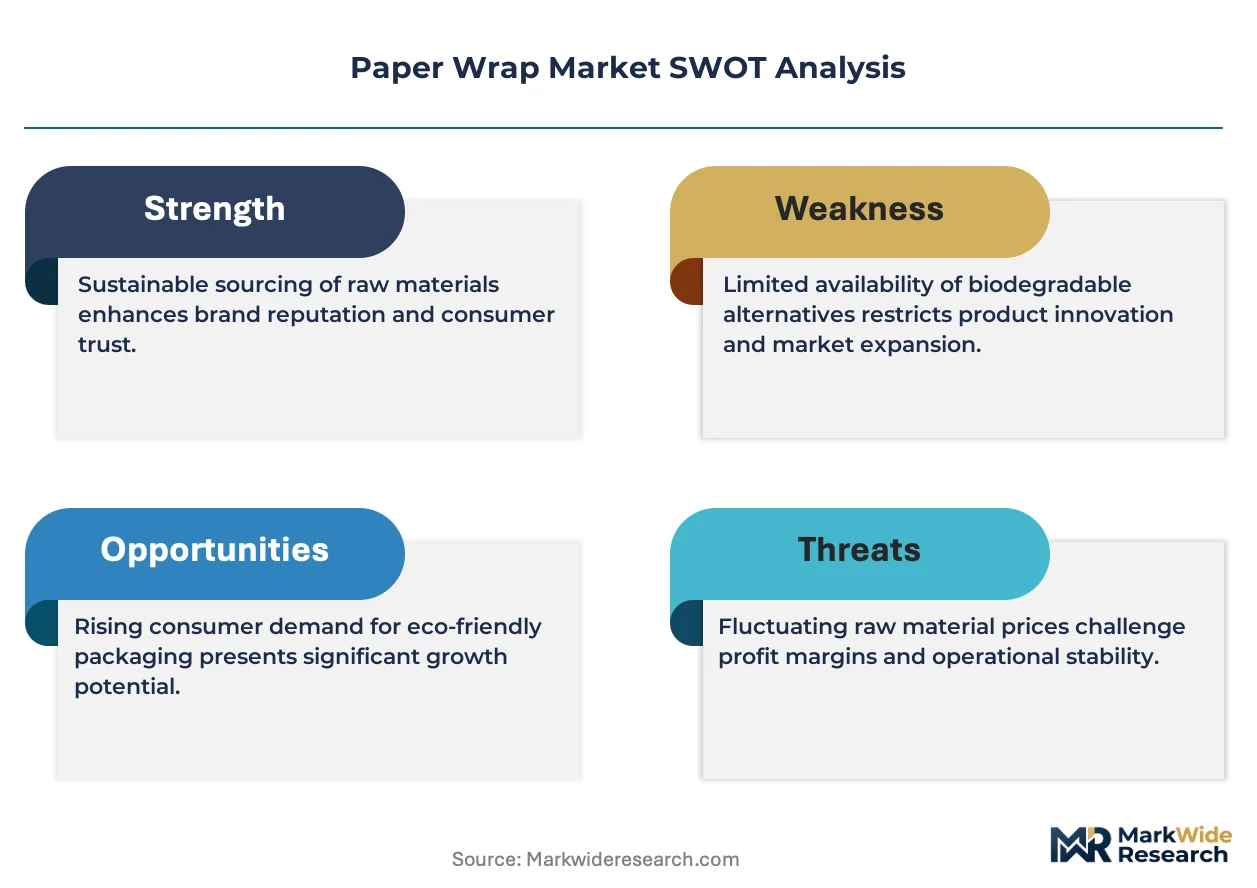
The EU Packaging and Packaging Waste Regulation is consolidating demand around fiber-based alternatives as brand owners face binding recycled-content targets. Mondi leverages its integrated pulp-to-paper operations across European mills to secure kraft paper supply chains. DS Smith anchors its position through corrugated and paper wrap synergies in the UK and continental Europe. Smurfit Kappa competes via specialization in renewable packaging formats for food service and retail.
Paper wrap denotes flexible sheet or roll stock manufactured from bleached or unbleached wood pulp, typically ranging from 30 to 80 grams per square meter, engineered for moisture resistance, grease barrier, or print receptivity to encase food items, industrial components, or consumer goods. Kraft paper dominates volume due to its tensile strength and compatibility with high-speed wrapping equipment across food packaging lines. Greaseproof paper captures premium margin pools in bakery and quick-service applications where fat resistance determines performance. Specialty paper extends into gift wrapping and retail presentation where surface finish and print fidelity command price differentiation.
The European Chemicals Agency oversees substance restrictions affecting coating chemistries applied to food-contact paper wraps. The US Food and Drug Administration sets migration limits for adjuvants in paper-based food packaging through its food-contact notification system. China's Ministry of Ecology and Environment enforces emission standards that shape bleaching and coating process investments by suppliers serving export markets. Stakeholders must monitor how diverging national packaging waste frameworks reshape material certification requirements and cross-border product acceptance criteria.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing substitution timelines as quick-service chains and bakery operators face binding recycled-content mandates and single-use plastic prohibitions. This regulatory pressure is restructuring procurement specifications across European food service networks.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Binding recycled-content targets for fiber-based food-contact packaging are accelerating material substitution in quick-service restaurant supply chains across Germany, France, and Italy.
- Kraft paper tensile performance:Unbleached kraft grades compatible with high-speed wrapping equipment are capturing volume from polyethylene-coated alternatives in bakery and sandwich applications.
- Greaseproof barrier chemistry:Fluorochemical-free fat-resistant coatings are opening premium positioning in quick-service fried food segments where performance specifications previously favored plastic laminates.
Market Restraints
- Pulp cost volatility:Softwood kraft pulp pricing swings are compressing margin predictability for converters lacking long-term fiber supply agreements with Scandinavian or Iberian mill networks.
- Barrier coating chemistry restrictions:ECHA substance restrictions on per- and polyfluoroalkyl substances are eliminating legacy greaseproof performance standards and forcing reformulation investments.
- Molded fiber substitution:Rigid molded pulp clamshells and trays are displacing flexible paper wrap in select prepared-food segments where structural protection outweighs wrapping efficiency.
Strategic Opportunities
- Central and Eastern Europe food service expansion:Quick-service restaurant penetration in Poland, Czech Republic, and Romania is outpacing local paper packaging supply infrastructure.
- Digital print integration:Water-based inkjet and flexographic systems are enabling short-run customization for regional bakery chains and private-label retail programs.
- Compostability certification alignment:Industrial composting infrastructure expansion in the Netherlands and Belgium is creating pull for TÜV Austria OK Compost INDUSTRIAL-certified wrap specifications.
Industry Challenges
- Food-contact notification timelines:FDA food-contact notification system review periods for novel barrier coatings are extending go-to-market schedules for reformulated products targeting US export markets.
- High-speed line integration:Heat-seal temperature windows for bio-based coatings diverge from legacy polyethylene specifications, requiring retrofit investments on existing wrapping equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paper Wrap Market |
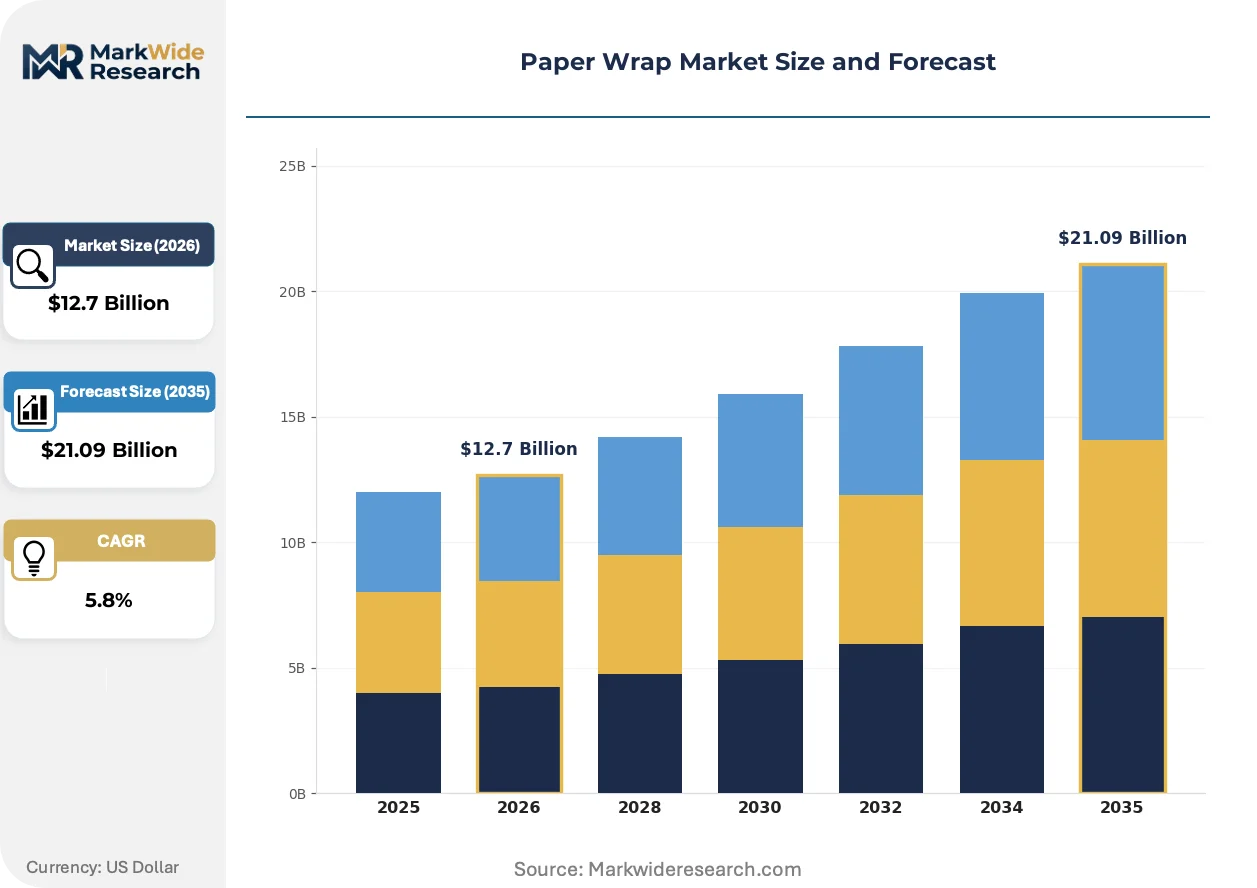
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $21.09 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wax Paper, Greaseproof Paper, Kraft Paper, Specialty Paper Application: Food Packaging, Industrial Packaging, Retail Packaging, Gift Wrapping End User: Food Service, Retailers, Manufacturers, Distributors Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Mondi, DS Smith, Smurfit Kappa, International Paper, WestRock, Huhtamaki, Packaging Corporation of America, Georgia-Pacific, Nordic Paper, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paper Wrap Market Evolving Landscape
Barrier coating chemistry and converting automation are converging to redefine performance specifications across food service and retail wrap segments. Material suppliers and equipment manufacturers are co-developing solutions that align regulatory compliance with line-speed economics.
Water-based barrier coatings incorporating polysaccharide or protein matrices are automating the transition from fluorochemical-dependent greaseproof grades in European quick-service applications. Bakery chains in Germany and the Netherlands are piloting these formulations at commercial volumes. The technology is automating compliance with ECHA PFAS restrictions while maintaining fat-resistance performance on high-speed sandwich wrapping lines.
REACH substance restrictions on intentionally added microplastics are eliminating conventional polyethylene extrusion coatings for food-contact paper in the European Union. Converters are redirecting capital toward aqueous dispersion and bio-based polymer alternatives. The regulation is reshaping supplier qualification criteria for retail private-label programs across France, Italy, and Spain.
Consolidated procurement by pan-European quick-service restaurant operators is compressing supplier qualification cycles and favoring multi-site certification coverage. Regional converters with single-facility footprints are losing access to chain-level contracts. This concentration is most visible in Germany, where centralized technical buying functions at headquarters locations in Munich and Hamburg are standardizing specifications across national store networks.
Paper Wrap Market Segmentation
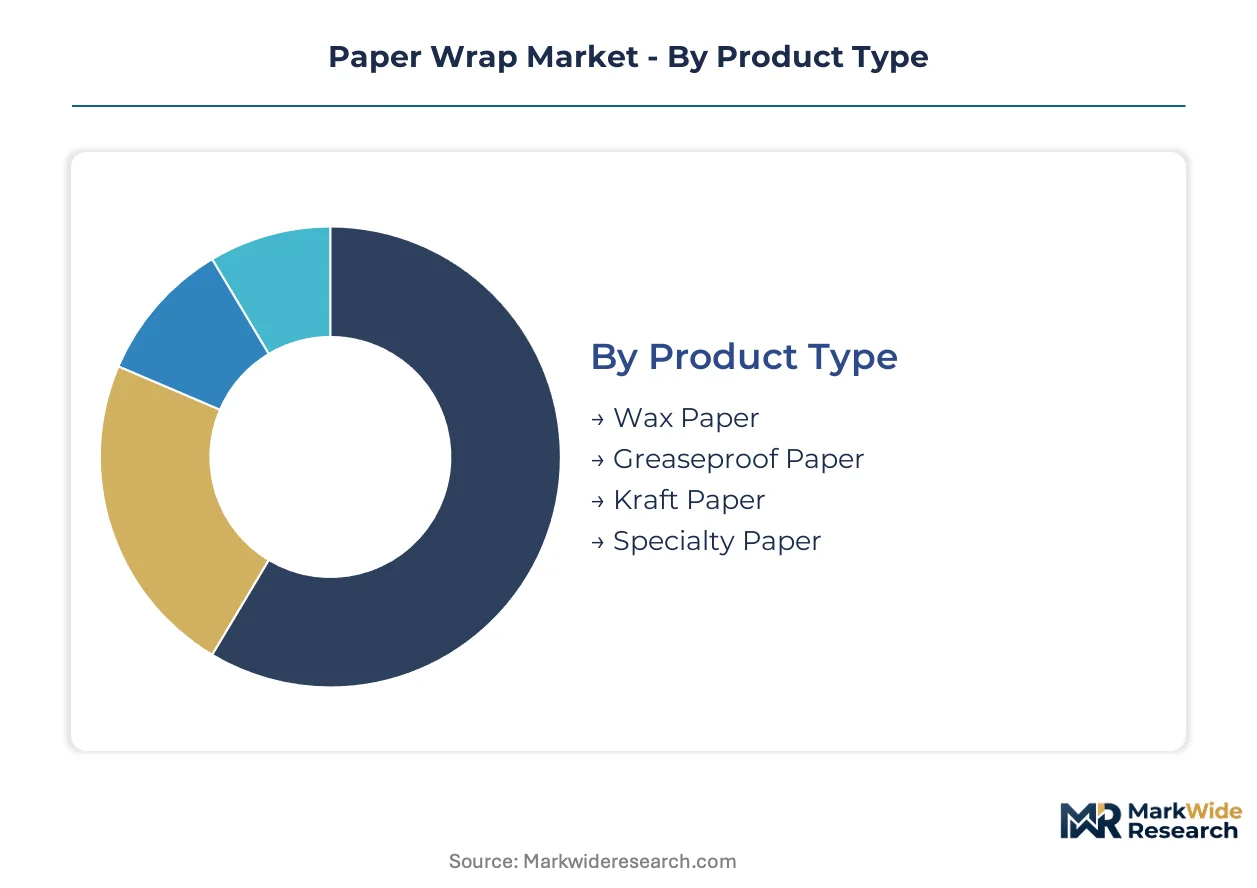
Paper wrap segmentation reflects divergent performance requirements across food safety, industrial protection, and retail presentation applications. Material specifications and barrier chemistries determine upgrade cycles as converters migrate from legacy plastic laminates toward fiber-based alternatives.
Product Type:
Upgrade cycles vary sharply by base fiber and coating chemistry, with unbleached kraft grades replacing polyethylene-coated alternatives fastest in high-speed food service lines.
- Kraft Paper:Unbleached sulfate pulp delivers tensile strength of 6-10 kN/m, compatible with automated wrapping equipment at 300+ units per minute. Quick-service restaurant chains in Germany and France are standardizing on 40-60 gsm kraft specifications for sandwich and bakery applications under EU single-use plastic prohibitions.
- Greaseproof Paper:Dense-sheeted cellulose with fluorochemical-free barrier coatings resists fat penetration above 70°C. Fried food segments in quick-service channels are adopting these reformulated grades as ECHA PFAS restrictions eliminate legacy performance standards.
- Wax Paper:Paraffin or vegetable-based coatings provide moisture barriers for chilled deli and cheese applications.
- Specialty Paper:Bleached grades with clay coatings serve gift wrapping and luxury retail where print fidelity commands premium positioning.
Volume placements concentrate in kraft paper; the faster expansion belongs to greaseproof as fat-resistant coating reformulations unlock quick-service substitution.
Application:
Cost tier stratification separates commodity food-contact volumes from premium retail presentation segments, with certification requirements widening the gap.
- Food Packaging:Direct-contact wraps for bakery, deli, and prepared meals require FDA or EFSA compliance plus industrial composting certification for Netherlands and Belgium market access. Centralized procurement by pan-European quick-service operators is consolidating supplier qualifications around multi-site certified facilities.
- Retail Packaging:Private-label programs demand short-run digital print compatibility and TÜV Austria OK Compost INDUSTRIAL certification. French and Italian supermarket chains are tightening specifications as REACH microplastic restrictions reshape coating chemistries.
- Industrial Packaging:VCI-treated kraft wraps protect metal components during shipment and storage.
- Gift Wrapping:Surface-finished papers with foil stamping and embossing serve seasonal and luxury gifting occasions.
Food packaging commands the largest volume base; retail packaging is climbing the fastest as private-label sustainability mandates accelerate material substitution.
End User:
Customer type determines specification complexity, with food service operators driving standardization while manufacturers retain bespoke requirements.
- Food Service:Quick-service restaurants and bakery chains specify heat-seal temperature windows, fat resistance, and compostability certification in unified procurement frameworks. Technical buying functions in Munich and Hamburg headquarters are eliminating regional specification variation across German store networks.
- Retailers:Supermarket and department store private-label programs require water-based inkjet compatibility and short-run flexibility for seasonal campaigns.
- Manufacturers:Industrial goods producers specify VCI corrosion protection and electrostatic discharge properties for component wrapping.
- Distributors:Packaging resellers aggregate demand across small-format food service and retail accounts with limited technical specification resources.
Food service generates the densest volume concentration; retailer sustainability mandates are gaining share fastest as ESG procurement criteria harden.
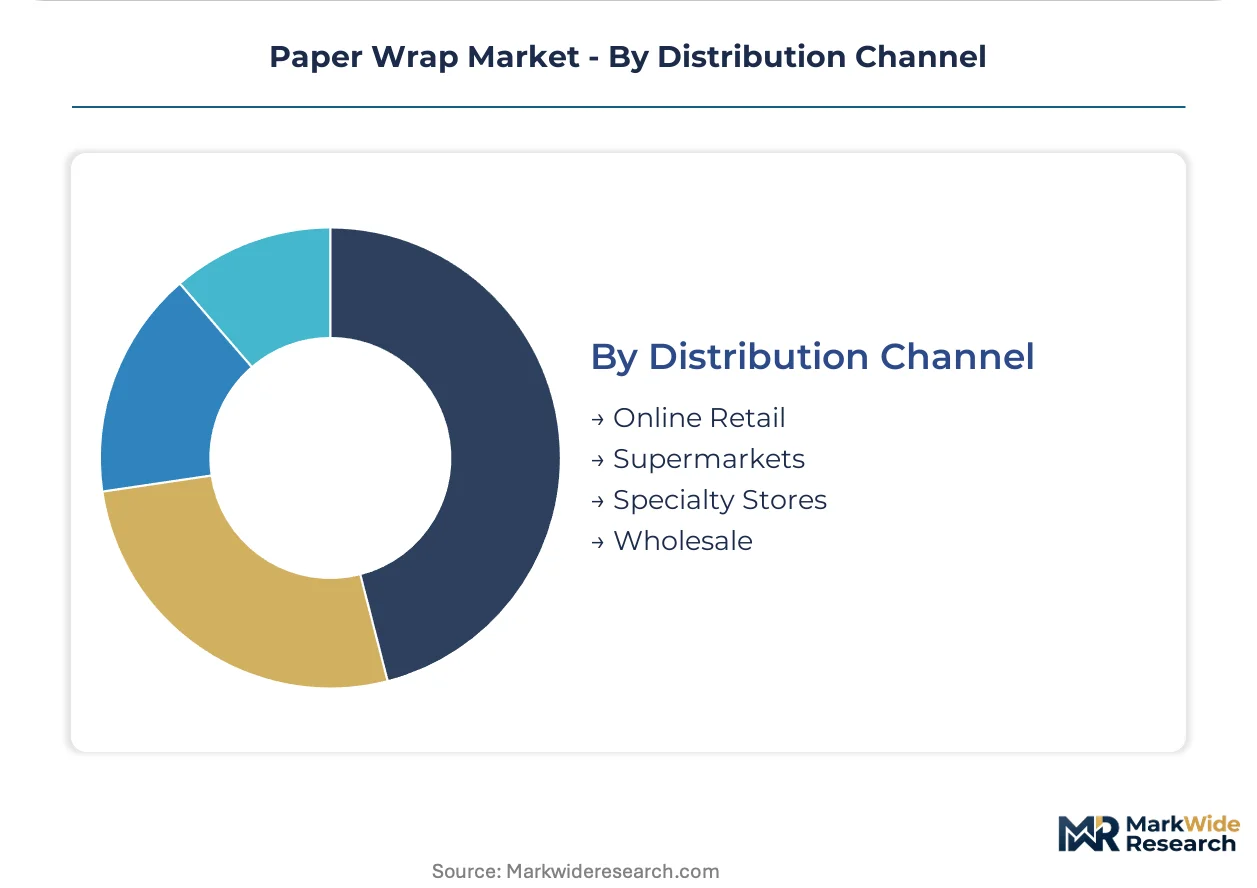
Distribution Channel:
Supply concentration favors wholesale and supermarket procurement for commodity grades, while specialty and online channels serve fragmented customization demand.
- Wholesale:Pan-European distributors aggregate volume from Scandinavian and Iberian mill networks, offering kraft and greaseproof grades in pallet quantities to converter and food service accounts. Long-term fiber supply agreements provide margin stability against softwood pulp price swings.
- Supermarkets:Mass retail chains stock consumer-format wax and parchment papers for home baking and food storage applications.
- Specialty Stores:Stationery and craft retailers carry premium gift wrapping papers with seasonal design rotations.
- Online Retail:E-commerce platforms enable short-run customization for regional bakery chains and event-based gifting demand.
Wholesale channels dominate volume flows; online retail is expanding most quickly as digital print integration enables micro-batch customization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Munich and Hamburg anchor European paper wrap procurement centralization, where technical buying functions at quick-service restaurant headquarters standardize specifications across national store networks and drive fiber-based substitution timelines.
Germany
Quick-service restaurant chains and bakery operators are consolidating procurement through centralized technical buying functions in Munich and Hamburg. The EU Packaging and Packaging Waste Regulation mandates binding recycled-content targets for fiber-based food-contact packaging. The Rhine-Ruhr industrial corridor hosts converting facilities supplying certified kraft wrap grades to pan-European food service networks.
France
Supermarket private-label programs are tightening sustainability specifications as ESG procurement criteria harden across retail chains. REACH substance restrictions on intentionally added microplastics are eliminating conventional polyethylene extrusion coatings for food-contact paper. The Île-de-France region concentrates converter operations serving quick-service and retail accounts with aqueous dispersion alternatives.
Italy
Bakery chains and prepared-food operators are piloting fluorochemical-free greaseproof formulations at commercial volumes. ECHA restrictions on per- and polyfluoroalkyl substances are forcing coating reformulation investments. The Emilia-Romagna packaging cluster is retooling lines for bio-based barrier chemistries compatible with high-speed sandwich wrapping equipment.
Netherlands
Industrial composting infrastructure expansion is creating pull for TÜV Austria OK Compost INDUSTRIAL-certified wrap specifications. The Dutch government accelerates circular economy procurement mandates for food service packaging. The Rotterdam-Antwerp port corridor facilitates kraft pulp import flows from Scandinavian mill networks to regional converting operations.
United States
Quick-service chains are navigating extended FDA food-contact notification timelines for novel barrier coatings targeting reformulated products. The EPA oversees emission standards affecting bleaching and coating process investments by suppliers. The Southeast packaging corridor—spanning Georgia and the Carolinas—hosts integrated pulp-to-paper operations supplying kraft wrap grades to domestic food service networks.
Paper Wrap Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification and barrier chemistry capabilities, with integrated pulp-to-paper operations commanding supply security premiums. The vendor base stratifies between Scandinavian and Iberian mill networks with captive fiber supply, regional converters with single-facility footprints, and multinational packaging groups with multi-site certification coverage. Three archetypes dominate: integrated forest products groups with kraft pulp backward integration, specialty converters focused on greaseproof and barrier-coated grades, and diversified packaging conglomerates leveraging corrugated synergies. Capacity expansion and M&A consolidation represent the dominant competitive moves, as pan-European procurement concentration favors suppliers with multi-site technical qualification.
Within the integrated mill network tier, Mondi and DS Smith exemplify archetypes leveraging European pulp-to-paper infrastructure. Mondi occupies a position representing kraft paper supply chain security through integrated operations, while DS Smith anchors corrugated and paper wrap synergies across UK and continental European markets. Smurfit Kappa sits within the specialty renewable packaging segment, exemplifying focus on food service and retail format specialization. These three companies represent the competitive core as centralized procurement compresses supplier qualification cycles.
| Leading Market Players |
|---|
| Mondi |
| DS Smith |
| Smurfit Kappa |
| International Paper |
| WestRock |
| Huhtamaki |
| Packaging Corporation of America |
| Georgia-Pacific |
| Nordic Paper |
| Others |
Value Network & Pricing Analysis
Softwood kraft pulp futures traded on European exchanges cascade through converter margins into three distinct pricing tiers for paper wrap, with Scandinavian mill networks commanding premiums over Iberian competitors and spot-market converters absorbing volatility through shorter contract terms.
Pricing Analysis
Throughput-based pricing anchors value capture for quick-service restaurant chains running high-speed wrapping lines above 300 units per minute, with certification premiums for TÜV Austria OK Compost INDUSTRIAL grades separating premium kraft specifications from standard unbleached grades and economy wax-coated alternatives. Price differentiation rests on barrier chemistry performance and fiber provenance, with fluorochemical-free greaseproof formulations commanding spreads over legacy grades. Cost compression in standard kraft tiers is intensifying because pan-European procurement consolidation eliminates regional price arbitrage. Food service operators with centralized technical buying functions exhibit lowest price sensitivity; single-facility regional converters face highest margin pressure.
Supply Chain Analysis
Direct-to-food-service channels handle hyperscale demand from pan-European quick-service restaurant networks, while wholesale distributors aggregate fragmented bakery and retail accounts. Geographic supply concentrates in Sweden, Finland, and Portugal, where integrated pulp-to-paper operations draw from captive softwood fiber basins. Raw material dependencies center on sulfate pulp, aqueous barrier coatings, and bio-based heat-seal polymers. Single-source vulnerability runs through Scandinavian kraft pulp networks exposed to energy cost volatility and fiber supply disruptions. Distribution runs through Rotterdam-Antwerp port corridors for continental European converting operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Centralized procurement by pan-European quick-service operators is compressing supplier qualification cycles and forcing regional converters without multi-site certification coverage toward exit or acquisition.
For Market Incumbents: Extend backward integration into kraft pulp supply through long-term offtake agreements with Scandinavian mill networks to defend margin stability against softwood price swings. Deepen certification coverage across multiple European production sites to retain access to chain-level contracts as technical buying functions in Munich and Hamburg standardize specifications. Prioritize fluorochemical-free greaseproof R&D to capture premium positioning as ECHA PFAS restrictions eliminate legacy performance standards. For New Entrants and Emerging Players: The 40-60 gsm standard kraft gap between premium certified grades and economy wax-coated alternatives offers entry points for regional converters with digital print integration capabilities. Target Central and Eastern European food service expansion in Poland, Czech Republic, and Romania where quick-service penetration outpaces local paper packaging supply infrastructure. Lead with short-run customization for private-label retail programs requiring water-based inkjet compatibility and seasonal design flexibility. For Investors and Strategic Acquirers: Distressed-cycle entries favor single-facility regional converters with established food service relationships but lacking multi-site certification coverage in Germany and the Netherlands. Long-term viability hinges on fiber supply security and barrier chemistry reformulation capabilities across a 5-10 year regulatory tightening window. Monitor ECHA substance restriction enforcement timelines as the inflection indicator for coating chemistry investment requirements and stranded asset risk in legacy fluorochemical-dependent production lines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kraft Pulp Supply | Captive fiber access from Scandinavian mill networks insulates margin stability against commodity price volatility. |
| Multi-Site Certification Coverage | TÜV Austria OK Compost INDUSTRIAL qualification across multiple facilities unlocks pan-European chain-level procurement contracts. |
| Fluorochemical-Free Barrier Coating Development | ECHA PFAS restrictions are eliminating legacy greaseproof standards and creating premium positioning for reformulated grades. |
| Digital Print Integration | Water-based inkjet systems enable short-run customization for regional bakery chains and private-label retail programs. |
| Central and Eastern European Capacity Expansion | Quick-service restaurant penetration in Poland, Czech Republic, and Romania outpaces local paper packaging supply infrastructure. |
Research Methodology
Independent corroboration across converter production data, pan-European quick-service restaurant procurement disclosures, and ECHA regulatory filings underwrites the qualitative findings in this study. Primary interviews with paper mill technical directors, food service packaging procurement leads, barrier coating R&D specialists, and wholesale distribution channel managers were combined with secondary validation from customs trade records, SEC filings of listed packaging groups, and EU Packaging and Packaging Waste Regulation impact assessments. Bottom-up volume estimates from converting capacity utilization and top-down demand projections from food service operator expansion plans were triangulated to establish market sizing.
Rate-of-change decomposition across the analysis window segments volume trajectories by product type, application, end user, and distribution channel dimensions. Modeled categories include kraft paper, greaseproof paper, wax paper, and specialty paper grades; food packaging, retail packaging, industrial packaging, and gift wrapping applications; food service, retailer, manufacturer, and distributor end users; wholesale, supermarket, specialty store, and online retail channels. CAGRs were derived from regression analysis of historical substitution patterns and regulatory mandate implementation schedules, with inputs from pulp price elasticity models and high-speed line integration adoption curves.
Inputs from converter production databases and food service operator procurement disclosures were available through the study window; gaps in real-time barrier coating formulation cost structures introduce uncertainty bands around margin projections. Forecasts reflect assumptions regarding ECHA enforcement timelines, FDA food-contact notification review periods, and industrial composting infrastructure buildout rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Natural Sack Kraft Papers Market
Paper & Paperboard Packaging
Food Contact Paper and Board Market
Paper & Paperboard Packaging
GCC Paper Cup Market
Paper & Paperboard Packaging
C1S Packaging Paper Market
Paper & Paperboard Packaging
Cold Waxed Paper Cups Market
Paper & Paperboard Packaging
Clay Coated Recycled Boxboard Market
Paper & Paperboard Packaging
Non-Tacky Transfer Paper Market
Paper & Paperboard Packaging
Paper Honeycomb Market
Paper & Paperboard Packaging
Macerated Paper Padded Mailers Market
Paper & Paperboard Packaging
Paper Canisters Market
Paper & Paperboard Packaging
Europe Paper Cone Market
Paper & Paperboard Packaging
Super Calendered Kraft Papers Market
Paper & Paperboard Packaging
Clear Envelopes and Mailing Supplies Market
Paper & Paperboard Packaging
Global Sack Kraft Paper Market
Paper & Paperboard Packaging
Paper Release Liners Market
Paper & Paperboard Packaging
South Korea Paper Packaging Market