
 Asia-Pacific Paper Cone Market | 2026-2036
Asia-Pacific Paper Cone Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Paper Cone Market Outlook
Aftermarket customization services for textile cone specifications is tilting margin pools away from commodity production. Oji Holdings Corporation anchors its position through captive pulp sourcing across Japanese mill networks. Conitex Sonoco competes by leveraging vertical integration into recycled fiber recovery systems. SKS Paper Products dominates South Asian distribution through direct mill relationships rather than distributor networks.
Asia-Pacific paper cones are cylindrical carriers formed from kraft or recycled paperboard, typically ranging from 3 to 7 degrees taper angle, designed to wind and transport yarn, thread, or filament during textile processing. The structural form must maintain dimensional stability under rotational speeds exceeding 15,000 RPM in modern ring spinning frames. Coated paper cones command premium positioning among high-speed textile operations where surface friction coefficients determine breakage rates. Recycled paper cones are gaining fastest in sustainability-driven supply chains, though raw paper variants still occupy volume leadership across cost-sensitive South Asian markets. Small and medium size categories concentrate demand from home textile and specialty yarn segments where batch flexibility outweighs unit economics.
India's BIS standards for paper-based packaging materials and China's GB/T standards for recycled paperboard quality collectively shape product certification requirements across the region. Japan's METI circular economy guidelines and Australia's ACCC consumer product safety rules further constrain material composition and labeling protocols for export-oriented manufacturers. Stakeholders must monitor evolving Extended Producer Responsibility frameworks across Southeast Asian markets where importer liability for end-of-life cone recovery is tightening without uniform implementation timelines.
Market Dynamics
India's BIS certification mandates for sustainable packaging materials are compressing adoption timelines for raw paper cones across South Asian textile clusters, forcing mills to requalify suppliers ahead of enforcement windows.
Growth Catalysts
- Regulatory Mandates:India's BIS standards for paper-based packaging materials compel integrated spinning mills to convert yarn carrier specifications from plastic to paper-based alternatives.
- High-Speed Textile Operations:Coated paper cones with optimized surface friction coefficients reduce yarn breakage rates in ring spinning frames operating above 15,000 RPM.
- Recycled Fiber Recovery:Captive pulp sourcing and in-house production of recycled fiber streams lower input cost volatility for Japanese mill networks.
Market Restraints
- Kraft Pulp Price Volatility:Raw material costs for virgin kraft paperboard fluctuate with global pulp futures, squeezing margin pools for commodity-grade cone manufacturers.
- Supply Concentration Risk:Tamil Nadu's integrated spinning clusters source from localized cone production, creating geographic dependency for 60% of India's textile belt demand.
- Dimensional Stability Limits:Recycled paperboard variants exhibit higher moisture absorption rates, restricting deployment in high-humidity Southeast Asian mill environments.
Strategic Opportunities
- Vietnam Textile Expansion:Home textile exporters in Ho Chi Minh City industrial zones seek batch-flexible small and medium cone specifications for specialty yarn runs.
- Extended Producer Responsibility:Australia's ACCC consumer product safety rules and tightening importer liability frameworks create first-mover advantage for cone recovery service providers.
- Digital Specification Platforms:Direct mill relationships via online technical specification portals bypass traditional distributor markups in Bangladesh's emerging textile corridors.
Industry Challenges
- Certification Timeline Compression:BIS laboratory testing queues for sustainable packaging validation extend supplier qualification cycles beyond typical procurement windows.
- Legacy Equipment Retrofit Costs:Ring spinning frame cone adapters require capital expenditure for taper angle compatibility with newer 5-degree standard designs.
- Cross-Border Labeling Complexity:Divergent GB/T standards for recycled paperboard quality between China and India force dual-sku inventory strategies for regional exporters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Paper Cone Market |
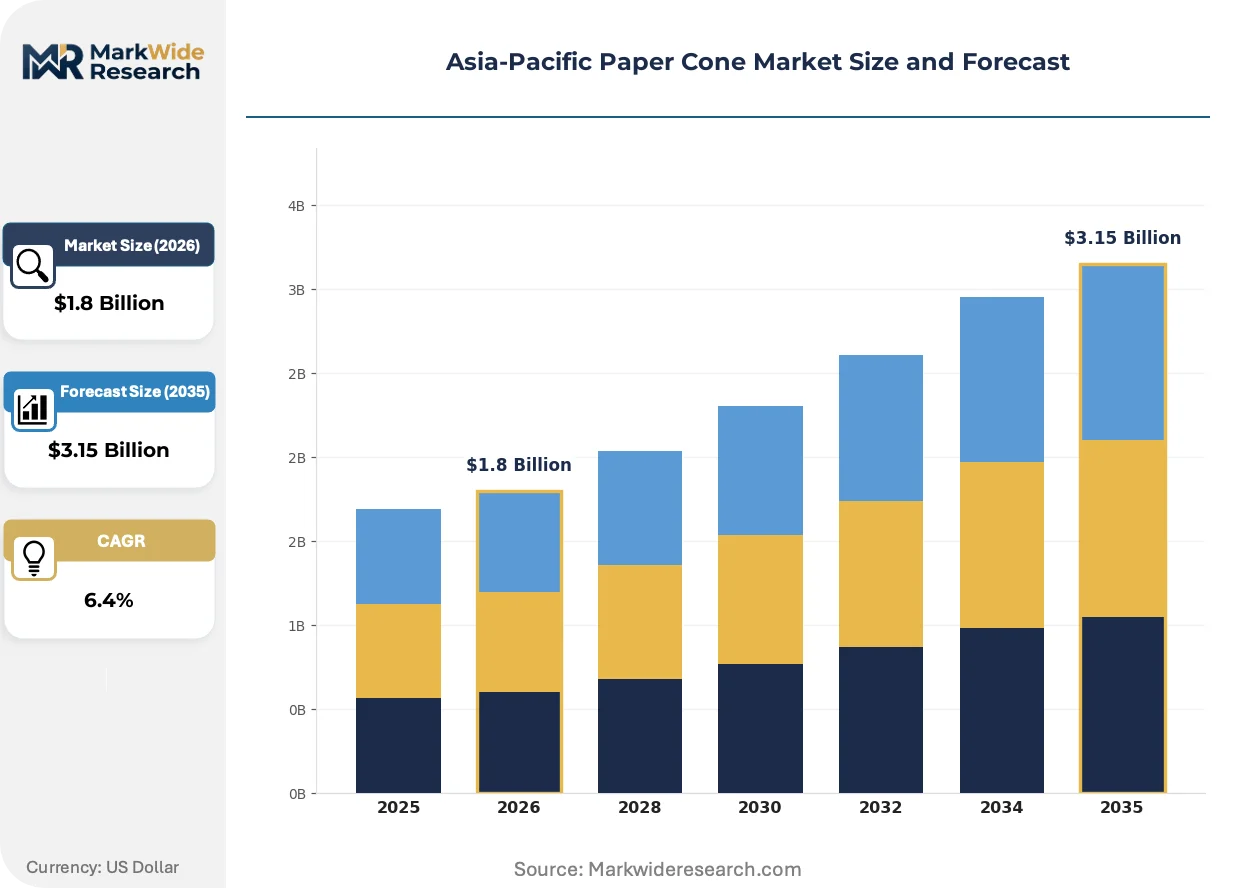
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Paper Cone, Coated Paper Cone, Printed Paper Cone, Recycled Paper Cone End User: Textile Industry, Food Industry, Packaging Industry, Craft Industry Distribution Channel: Online Retail, Wholesale, Direct Sales, Supermarkets Size: Small, Medium, Large, Custom |
| Companies Covered | Hilmarton, SCG Packaging PCL, Conitex Sonoco, Sarnti Packaging Co Ltd, Oji Holdings Corporation, SKS Paper Products, Shree Umiya Paper Cone, International Paper Company, Pacific Paper Products, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Paper Cone Market Strategic Shifts
Digital specification platforms and predictive maintenance integration are compressing traditional procurement cycles while elevating technical service expectations from cone suppliers across Asia-Pacific textile clusters.
Surface coating technologies using nano-scale friction modifiers are virtualizing the performance gap between virgin kraft and recycled paperboard variants. High-speed spinning mills in Tamil Nadu and Bangladesh are adopting these treated cones for polyester filament applications. The technology is virtualizing commodity-grade supply chains into performance-tiered segments previously reserved for coated premium products.
China's GB/T standards for recycled paperboard quality and India's BIS certification mandates are creating divergent compliance pathways for regional exporters. Manufacturers serving both markets must maintain dual testing protocols and separate inventory streams. Vietnam-based suppliers face the steepest compliance burden as they pivot exports between Chinese and Indian buyer specifications.
Direct technical collaboration between cone manufacturers and spinning mill engineering teams is displacing traditional distributor-mediated procurement in South Asia. SKS Paper Products and comparable suppliers now embed specification engineers within Tamil Nadu textile clusters. Bangladesh's emerging home textile sector shows the fastest behavioral transition, with mills demanding real-time dimensional tolerance adjustments rather than standard catalog offerings.
Asia-Pacific Paper Cone Market Segmentation
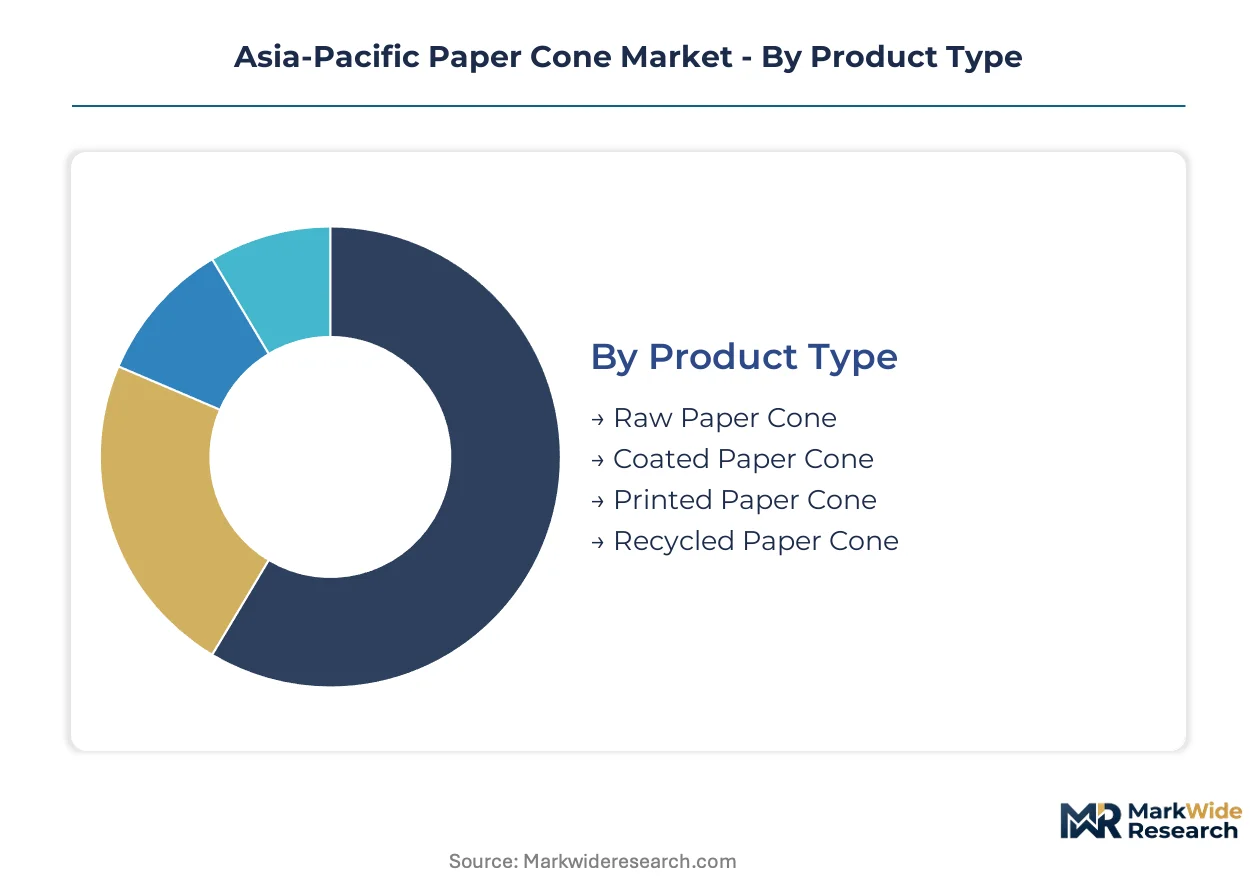
Paper cone specifications diverge sharply across Asia-Pacific textile clusters, with coating technologies and taper angles determining compatibility with high-speed ring spinning frames. Procurement patterns in Tamil Nadu and Bangladesh industrial zones favor direct technical collaboration over distributor channels.
Product Type:
Mature virgin kraft formulations coexist with emerging recycled fiber variants as sustainability mandates reshape material specifications across Japanese and Indian mill networks.
- Raw Paper Cone:Virgin kraft paperboard construction delivers dimensional stability under rotational stress exceeding 15,000 RPM in Tamil Nadu ring spinning operations. South Asian integrated spinning clusters source these cones for cost-sensitive polyester filament winding where surface friction tolerance permits uncoated finishes.
- Coated Paper Cone:Nano-scale surface modifiers optimize friction coefficients for high-speed textile operations demanding minimal yarn breakage. Bangladesh's emerging home textile exporters specify these cones for specialty yarn runs requiring batch-to-batch consistency in humid mill environments.
- Printed Paper Cone:Brand identification and lot tracking codes support traceability requirements in Vietnam's export-oriented textile corridors.
- Recycled Paper Cone:Post-consumer fiber streams face moisture absorption constraints limiting deployment in Southeast Asian high-humidity conditions.
Raw paper cones handle the majority of throughput; recycled variants are expanding most quickly on share as BIS certification timelines compress.
End User:
Application intensity varies by sector margin structure, with textile operations commanding technical specification priority over commodity packaging buyers.
- Textile Industry:Cylindrical carriers wound from 3-7 degree taper angle paperboard support yarn transport through ring spinning and winding processes. Ho Chi Minh City industrial zones and Tamil Nadu clusters drive specification innovation through direct engineering collaboration with cone manufacturers.
- Food Industry:Grease-resistant coatings and FDA-compliant barrier layers position cones for dry food dispensing applications in Australian retail channels.
- Packaging Industry:Structural rigidity requirements for protective inner supports favor heavy-gauge kraft constructions.
- Craft Industry:Decorative printed finishes and custom color matching serve hobbyist supply chains through online retail channels.
Textile applications dominate volume absorption; food sector specifications are climbing the fastest as barrier coating technologies mature.
Distribution Channel:
Channel economics reflect buyer technical sophistication, with specification complexity determining whether direct mill relationships or intermediary networks prevail.
- Online Retail:Digital specification portals enable real-time dimensional tolerance adjustments for Bangladesh mills bypassing traditional distributor markups. Platform-based procurement is displacing catalog-based ordering in emerging textile corridors where batch flexibility outweighs volume discounts.
- Wholesale:Regional inventory pooling serves fragmented craft industry buyers lacking technical specification capabilities.
- Direct Sales:Embedded specification engineers from SKS Paper Products and comparable suppliers maintain presence within Tamil Nadu textile clusters.
- Supermarkets:Standardized small-format cones for consumer craft applications rotate through mass retail shelf sets.
Direct sales channels capture the highest-margin technical specifications; online retail is gaining share fastest among new mill entrants.
Size:
Volume scale determines production economics, with custom specifications commanding premium positioning against standardized small-batch formats.
- Small:3-4 inch base diameter cones serve home textile and specialty yarn segments where frequent changeovers favor batch flexibility over unit cost optimization.
- Medium:Mid-range specifications balance throughput efficiency with handling ergonomics in Vietnam's export-oriented spinning operations.
- Large:Maximum yarn capacity cones reduce changeover frequency in high-volume polyester filament production.
- Custom:Non-standard taper angles and proprietary surface coatings address legacy equipment retrofit requirements in mixed-age mill installations.
Medium sizes handle standard textile throughput; custom specifications are expanding most quickly as equipment heterogeneity persists across South Asian mill bases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity diverges sharply across Asia-Pacific textile clusters. South Asian spinning mills prioritize unit economics and raw material cost minimization. Japanese and Australian buyers absorb premium pricing for certified sustainable specifications.
India
Tamil Nadu's integrated spinning clusters generate sixty percent of national textile belt cone demand through localized supplier relationships. BIS certification mandates for sustainable packaging materials compress supplier qualification timelines ahead of enforcement windows. Coimbatore and Tiruppur industrial zones drive specification innovation through direct engineering collaboration with cone manufacturers.
China
GB/T standards for recycled paperboard quality shape export-oriented manufacturer compliance requirements across Yangtze River Delta production bases. Dual carbon goals accelerate fiber recovery system investments among mill networks serving domestic ring spinning operations. Zhejiang and Jiangsu province textile corridors concentrate demand for high-speed compatible cone specifications.
Japan
METI circular economy guidelines constrain material composition and end-of-life recovery protocols for domestic and export production. Captive pulp sourcing across mill networks insulates Oji Holdings and comparable suppliers from global kraft futures volatility. Nagoya and Osaka industrial zones maintain premium positioning through technical specification leadership.
Vietnam
Ho Chi Minh City industrial zone home textile exporters seek batch-flexible small and medium cone specifications for specialty yarn runs. Importer liability frameworks for packaging waste recovery tighten without uniform implementation timelines across ASEAN markets. Binh Duong and Dong Nai province spinning clusters source increasingly from regional rather than Chinese suppliers.
Australia
ACCC consumer product safety rules govern labeling protocols and barrier coating compliance for food-contact cone applications in retail channels. Extended Producer Responsibility frameworks create first-mover positioning for recovery service providers serving import-dependent manufacturing bases. Melbourne and Sydney distribution hubs channel specification requirements to Asia-Pacific production networks.
Asia-Pacific Paper Cone Market Competitive Environment
Capability concentration sits with integrated pulp-to-cone specialists; scale advantage sits with regional distribution-anchored fabricators. The vendor base separates into three strategic archetypes: captive pulp networks, recycled fiber recovery specialists, and direct-mill relationship operators. Consolidation pressure favors backward integration into fiber sourcing and specification engineering embedment within textile clusters.
Among Asia-Pacific headquartered suppliers, Oji Holdings Corporation exemplifies the captive pulp network archetype through Japanese mill network integration. SKS Paper Products occupies a position within the direct-mill relationship tier, embedding specification engineers within South Asian textile clusters. Conitex Sonoco represents recycled fiber recovery specialization, anchoring positioning through upstream control over post-consumer material streams.
| Leading Market Players |
|---|
| Hilmarton |
| SCG Packaging PCL |
| Conitex Sonoco |
| Sarnti Packaging Co Ltd |
| Oji Holdings Corporation |
| SKS Paper Products |
| Shree Umiya Paper Cone |
| International Paper Company |
| Pacific Paper Products |
| Others |
Value Chain & Pricing Dynamics
Tamil Nadu's integrated spinning clusters concentrate sixty percent of India's paper cone procurement, granting localized suppliers substantial leverage over regional pricing benchmarks. BIS certification timelines compress supplier qualification windows, forcing mills to absorb premium positioning for certified sustainable alternatives or risk operational disruption.
Pricing Analysis
Aftermarket specification services and technical customization drive lifetime value beyond commodity cone sales. Three-tier pricing structure across premium, standard, and economy levels separates coated high-speed variants from raw kraft constructions and recycled fiber alternatives. Cost compression in standard-grade segments intensifies as Vietnamese and Bangladeshi mills expand capacity. Home textile exporters in Ho Chi Minh City industrial zones exhibit highest price sensitivity, while Japanese ring spinning operations absorb premium positioning for dimensional stability.
Supply Chain Analysis
Virgin kraft pulp from Indonesian and Malaysian mill networks feeds South Asian cone production, with recycled fiber streams drawing from Japanese post-consumer recovery systems. Raw material dependencies center on kraft paperboard quality grades, nano-scale surface modifiers, and proprietary coating chemistries. Single-source vulnerability concentrates around Tamil Nadu's geographic supplier concentration for India's textile belt. Distribution runs through direct mill relationships anchored by embedded specification engineers, bypassing traditional wholesale markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks textile capital expenditure cycles, with recovery momentum tied to Vietnam's home textile export expansion and South Asian spinning capacity additions.
For Market Incumbents: Build captive pulp sourcing moats through backward integration into Indonesian and Malaysian fiber networks. Defend against emerging recycled fiber specialists by accelerating BIS certification coverage ahead of enforcement windows. Anchor positioning through embedded specification engineers within Tamil Nadu and Bangladesh textile clusters. For New Entrants and Emerging Players: Pursue white-space capture in Vietnam's batch-flexible small and medium cone specifications, where equipment heterogeneity creates specification fragmentation. Target Australia's Extended Producer Responsibility recovery services gap before uniform ASEAN implementation timelines solidify. Lead with digital specification portals offering real-time dimensional tolerance adjustments. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors recycled fiber recovery specialists with upstream post-consumer material control. Long-term viability hinges on sustainability mandate acceleration across BIS and GB/T regulatory frameworks. Acquisition targets should demonstrate dual-certification capability serving both Indian and Chinese export specifications. Watch for kraft pulp futures volatility as inflection signal for margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Sourcing | Captive fiber supply insulates Oji Holdings from global kraft volatility. |
| BIS Certification Pre-Qualification | Accelerated laboratory testing queues compress supplier switching costs. |
| Embedded Specification Engineering | SKS Paper Products displaces distributor channels through direct mill presence. |
| Recycled Fiber Recovery System Investment | Conitex Sonoco anchors positioning through post-consumer stream control. |
| Digital Specification Platform Launch | Real-time tolerance adjustments capture Bangladesh mill procurement shifts. |
Study Parameters
Two parallel data streams informed the analysis: primary field engagement with textile mill procurement directors, cone manufacturer specification engineers, and BIS certification laboratory managers; and secondary validation through customs trade records, BIS notification filings, and GB/T standard documentation. Bottom-up volume triangulation across Tamil Nadu, Ho Chi Minh City, and Zhejiang province clusters converged with top-down macro textile production forecasts.
Forecast inputs considered coating technology adoption curves, taper angle standardization trends, and regulatory enforcement probability across the projection horizon. Segmentation dimensions modeled include product type, end-use industry, distribution channel, and geographic production cluster. CAGRs derived from weighted average of historical textile capital expenditure patterns and sustainability mandate diffusion rates.
Sensitivities concentrate around BIS enforcement timeline acceleration, kraft pulp futures volatility, and recycled fiber moisture absorption technical limits. Cross-checking against textile machinery import data and spinning frame installation records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Ovenable Paperboard Trays Market
Paper & Paperboard Packaging
Vegetable Parchment Paper Market
Paper & Paperboard Packaging
Hanging Box Market
Paper & Paperboard Packaging
UAE Corrugated Board Packaging Market
Paper & Paperboard Packaging
Wax-Coated Paper Market
Paper & Paperboard Packaging
Saudi Arabia Paper and Paperboard Packaging Market
Paper & Paperboard Packaging
Corrugated Packaging Market
Paper & Paperboard Packaging
Air Fryer Paper Liners Market
Paper & Paperboard Packaging
Waxing Base Paper Market
Paper & Paperboard Packaging
Europe Paper Cone Market
Paper & Paperboard Packaging
Coffee Filter Paper Market
Paper & Paperboard Packaging
Disposable Paper Plates Market
Paper & Paperboard Packaging
EMEA Corrugated Board Packaging Market
Paper & Paperboard Packaging
Ultraflute Paper Market
Paper & Paperboard Packaging
Australia Paper and Paperboard Packaging Market
Paper & Paperboard Packaging
Push-Pull Slip Sheets Market