
 Kitchen Oil Absorbing Paper Market | 2026-2036
Kitchen Oil Absorbing Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Kitchen Oil Absorbing Paper Market Insights
Food-grade cellulose certification is redrawing competitive boundaries in kitchen oil absorbing paper. Kimberly-Clark Corporation leverages its North American tissue infrastructure to dominate institutional supply chains. Procter & Gamble anchors its position through retail channel control and consumer brand recognition. Georgia-Pacific competes on manufacturing scale, operating integrated pulp-to-sheet facilities that sustain margin pressure on smaller converters.
Kitchen oil absorbing paper denotes engineered cellulose or synthetic fiber sheets designed with controlled porosity, typically ranging from 40 to 120 grams per square meter, to trap lipids from fried foods and cooking surfaces without fiber shedding. The product serves commercial kitchens and households seeking to reduce oil content in prepared foods and maintain surface hygiene. Roll format leads in commercial end users where volume throughput demands continuous feed, while pouch packs represent the fastest-growing structural segment as urban households in Asia prioritize convenience and storage efficiency. Biodegradable materials command premium positioning as regulatory frameworks in the European Union and select Asian markets restrict conventional synthetic fiber disposal, concentrating margin pools with certified compostable grades.
The FDA regulates kitchen oil absorbing paper under food-contact substance notifications, requiring manufacturers to demonstrate no migration of harmful substances under intended use conditions. The EU EFSA framework enforces stricter migration limits through the Plastics Regulation and emerging single-use packaging directives that extend to disposable absorbent articles. China's NMPA and national food-contact GB standards impose additional testing protocols for imported cellulose products. Stakeholders must monitor evolving compostability certification requirements across jurisdictions and assess whether backward integration into pulp sourcing or captive supply of food-grade cellulose offers defensible cost positioning against tightening raw material traceability rules.
Market Dynamics
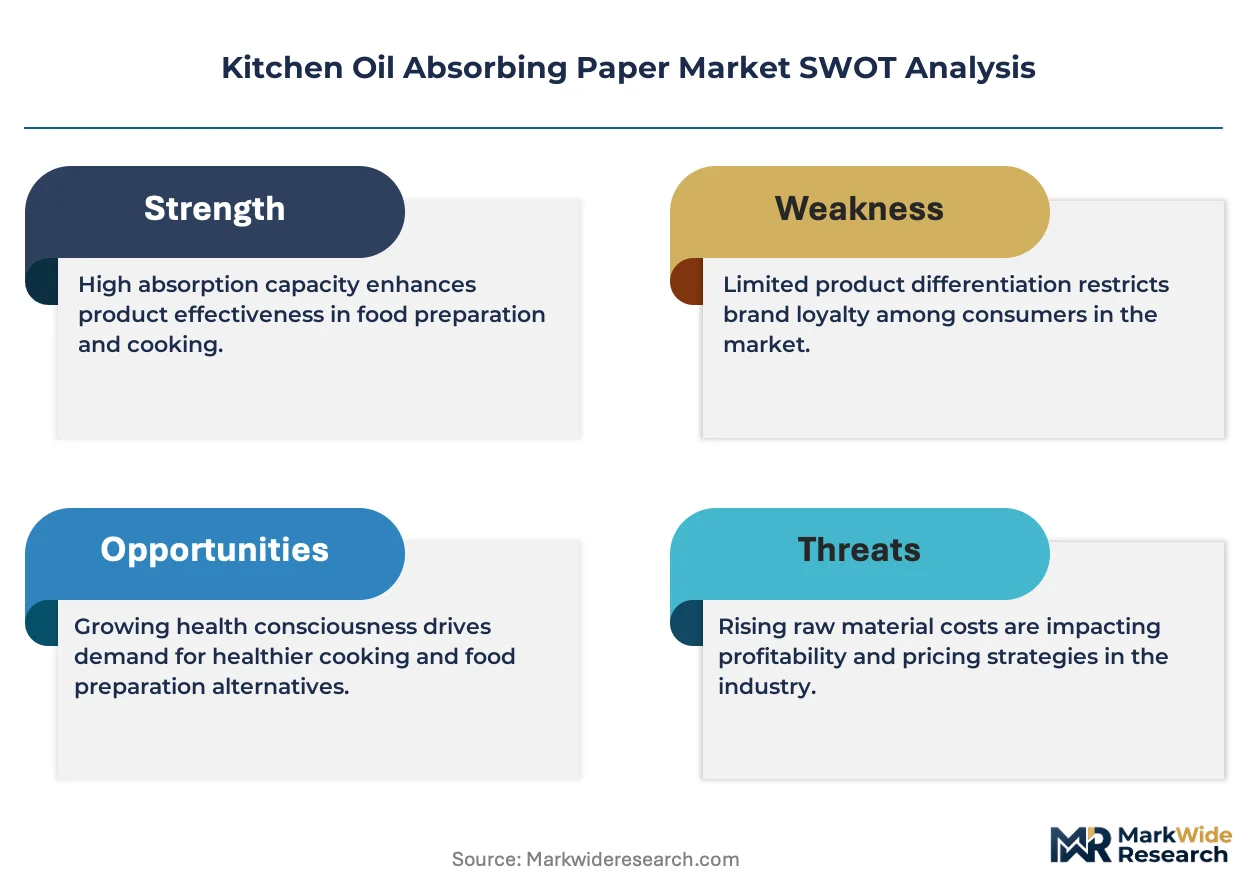
Cellulose pulp cost volatility and tightening food-contact purity mandates are compressing converter margins while favoring integrated pulp-to-sheet producers with captive fiber supply and in-house bleaching capacity.
Growth Catalysts
- EU Single-Use Packaging Directive:The EU Green Deal's extension to disposable absorbent articles creates mandatory demand pull for certified compostable grades, redirecting procurement budgets toward biodegradable cellulose suppliers.
- Japan's compact kitchen formats:Urban household density in Tokyo and Osaka accelerates pouch-pack adoption for residential oil absorption, with convenience-store distribution channels expanding SKU availability.
- Fried food health positioning:Restaurant chains in the United States deploy oil-absorbing sheets as visible food safety compliance tools, marketing reduced lipid content to health-conscious consumers.
Market Restraints
- Bleached softwood pulp price volatility:Northern European and Canadian pulp mill supply disruptions transmit directly to converter cost structures, eroding margin stability for non-integrated producers.
- China NMPA import testing protocols:Extended GB standard compliance timelines for foreign cellulose products delay market entry and tie up working capital in certification inventory.
- Synthetic fiber substitution in commercial kitchens:Polypropylene-based oil pads offer superior wet strength and lower unit cost, capturing price-sensitive institutional buyers despite disposal restrictions.
Strategic Opportunities
- South Korea's premium household segment:Seoul's single-person household growth and convenience culture create white space for branded, design-forward pouch formats at shelf-price premiums.
- India FSSAI food-grade material expansion:The regulator's evolving standards for food-contact articles open import pathways for certified cellulose producers as domestic quick-service restaurant chains scale.
- Digital direct-to-consumer channels:Subscription box models and e-commerce platforms bypass traditional retail gatekeepers, enabling specialty converters to build brand equity and capture margin.
Industry Challenges
- Food-grade cellulose certification timelines:FDA food-contact substance notifications and EU EFSA migration limit compliance require 18-24 month validation cycles, constraining product launch velocity.
- Compostability standard fragmentation:Divergent certification requirements across BPI, TÜV Austria, and home-composting schemes force redundant testing and SKU proliferation.
- Legacy wet-laid equipment retrofit costs:Conventional tissue machines require capital-intensive modifications to achieve food-grade purity and eliminate fiber shedding in oil-contact applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kitchen Oil Absorbing Paper Market |
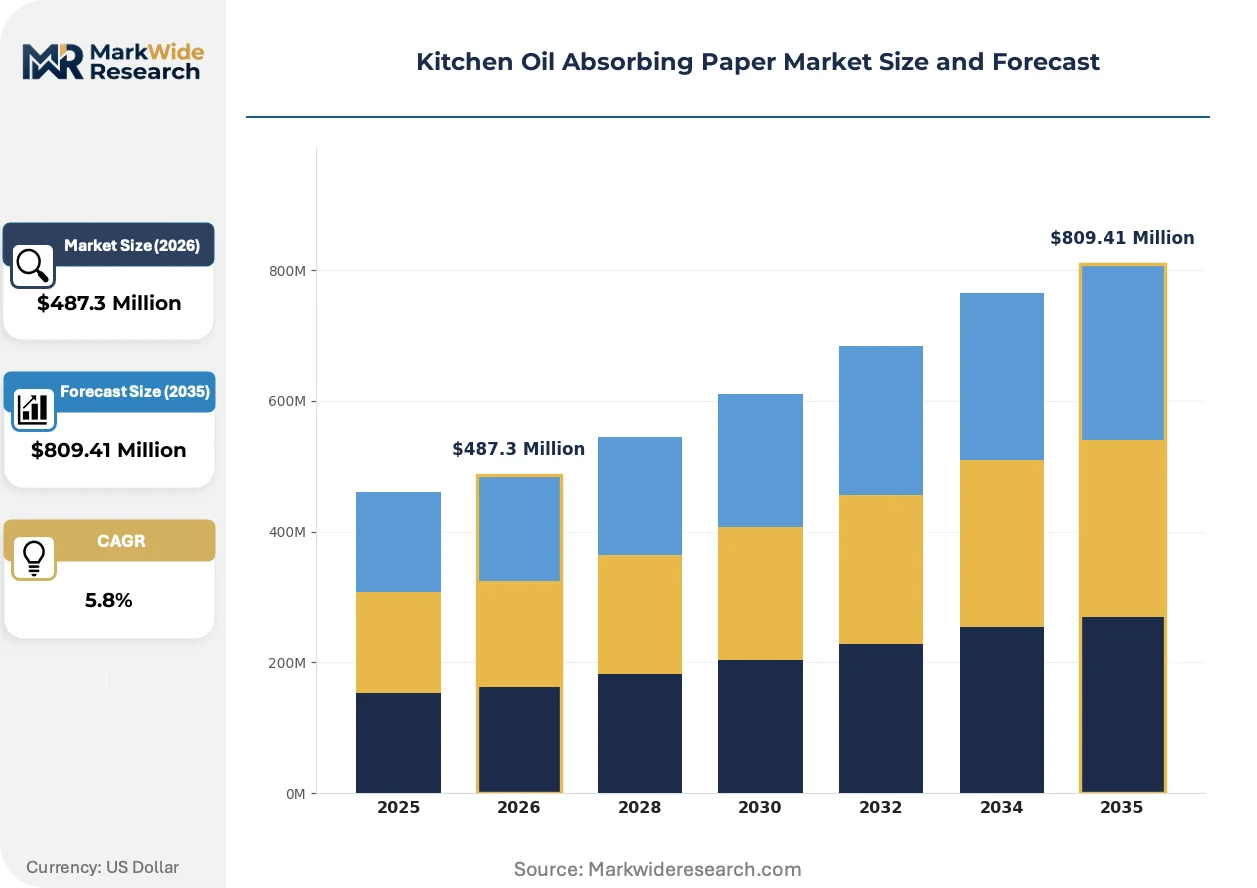
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Sheets, Roll Format, Pouch Packs, Bulk Packs Material: Cellulose, Synthetic Fiber, Recycled Paper, Biodegradable Materials End User: Households, Restaurants, Food Trucks, Catering Services Size: Small Sheets, Large Sheets, Mini Rolls, Jumbo Rolls |
| Companies Covered | Kimberly-Clark Corporation, Procter & Gamble, Georgia-Pacific, Fulton, Supreminox, International Paper, Essity, Life-do.Plus Co., Ltd., Shanghai XiSi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kitchen Oil Absorbing Paper Market Trends and Innovations
Material science advances and regulatory boundary-setting are reconfiguring competitive advantage around biodegradability certification, precision fiber engineering, and channel-specific format optimization.
Unbleached bamboo pulp formulations are fragmenting the raw material base for kitchen oil absorbing paper. Asian converters in Vietnam and Indonesia source bamboo fiber to bypass softwood pulp price cycles and market FSC-certified sustainability credentials. Foodservice distributors in Singapore and Hong Kong now specify bamboo-based absorbents for corporate catering contracts, compressing market share for conventional bleached cellulose grades.
REACH candidate list expansion to include certain fluorinated treatments is forcing reformulation of grease-resistant coatings. European converters face 12-18 month substitution timelines as ECHA evaluates PFAS restrictions, redirecting R&D spend toward polysaccharide-based barrier technologies. Pouch-pack producers targeting German and French retail channels are accelerating PFAS-free certification to preempt 2025 regulatory deadlines.
Quick-commerce platforms are compressing traditional retail replenishment cycles for household oil absorbing paper. Urban consumers in Shanghai and Beijing now expect same-day delivery of convenience-format pouch packs, forcing brand owners to integrate with Meituan and Ele.me logistics networks. This channel shift concentrates volume with converters capable of small-batch production and direct-to-warehouse fulfillment.
Kitchen Oil Absorbing Paper Market Segmentation
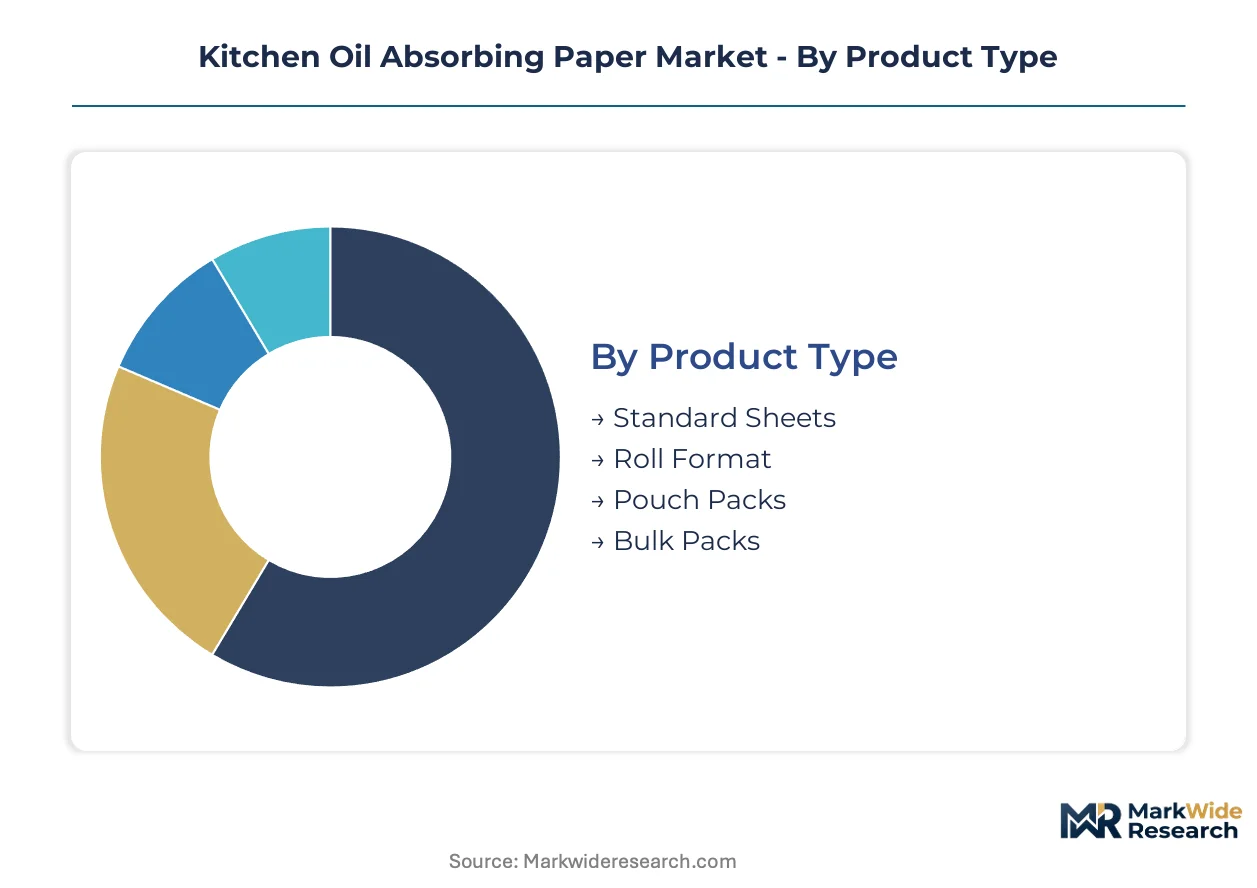
Kitchen oil absorbing paper segments fracture along format preferences, material certification tiers, and channel throughput requirements. Each dimension carries distinct margin profiles and regulatory exposure that shape supplier positioning.
Product Type:
Roll format dominates foodservice distribution and institutional procurement channels. Pouch packs and bulk configurations flow through retail and e-commerce, with convenience-store networks driving SKU proliferation in dense urban markets.
- Standard Sheets:Individual sheets measuring 20x20cm to 30x30cm serve household frying applications and small commercial kitchens. Demand clusters in Japan and South Korea where apartment-scale cooking limits batch sizes. FDA food-contact compliance requirements elevate sourcing costs for imported grades.
- Roll Format:Continuous perforated rolls of 50-100 meters enable high-throughput deployment in restaurant chains and central kitchens. North American QSR procurement specifications favor roll formats for line-speed efficiency. Kimberly-Clarl and Georgia-Pacific anchor supply contracts through integrated pulp-to-roll manufacturing.
- Pouch Packs:Pre-counted sheet quantities in resealable packaging target convenience-oriented households. Tokyo and Osaka convenience-store channels stock 10-30 sheet pouches for impulse purchase. Miniaturization adds per-unit cost but commands shelf-price premiums.
- Bulk Packs:Institutional cases of 500-2000 sheets serve catering operations and food manufacturing facilities. Procurement concentrates through broadline distributors with pallet-scale logistics requirements.
Roll format dominates installed base. Pouch packs are where expansion concentrates.
Material:
Raw material selection determines regulatory pathway and disposal compliance cost. Cellulose grades face food-contact purity mandates while biodegradable alternatives capture procurement preference in EU member states with extended producer responsibility schemes.
- Cellulose:Bleached softwood pulp with controlled porosity of 40-120 gsm remains the volume standard. EFSA migration limit compliance and FDA food-contact substance notification requirements extend certification timelines to 18-24 months. Northern European and Canadian pulp mill disruptions transmit directly to converter cost structures.
- Biodegradable Materials:Unbleached bamboo pulp and agricultural fiber formulations bypass conventional pulp price cycles. Vietnam and Indonesia converters source FSC-certified bamboo to supply Singapore and Hong Kong corporate catering contracts. EU Green Deal packaging directives accelerate procurement preference.
- Synthetic Fiber:Polypropylene-based oil pads deliver superior wet strength at lower unit cost. Commercial kitchens in price-sensitive segments substitute synthetic grades despite landfill disposal restrictions in regulated jurisdictions.
- Recycled Paper:Post-consumer fiber content faces food-contact regulatory barriers that limit deployment to non-direct-contact surface wiping applications. Certification scarcity constrains volume growth.
Cellulose commands volume share. Biodegradable materials are climbing the fastest.
End User:
User type dictates performance specification, order frequency, and price elasticity. Restaurant chains prioritize supply security and compliance documentation while households respond to convenience and packaging aesthetics.
- Restaurants:Full-service and limited-service chains deploy oil-absorbing sheets as visible food safety compliance tools. Procurement runs through broadline distributors with quarterly contract structures. Health-positioning marketing drives specification of reduced-lipid grades.
- Households:Residential demand fragments across single-person urban units and multi-generational households. Seoul's single-person household growth creates white space for design-forward pouch formats at premium shelf pricing.
- Catering Services:Event and corporate catering operations require case-scale procurement with flexible delivery scheduling. Sustainability credentials influence contract awards in EU and Asia-Pacific corporate accounts.
- Food Trucks:Mobile foodservice operations prioritize compact storage formats and rapid deployment. Limited cold-chain infrastructure constrains bulk inventory holding.
Restaurants anchor procurement volume. Households are gaining share fastest.
Size:
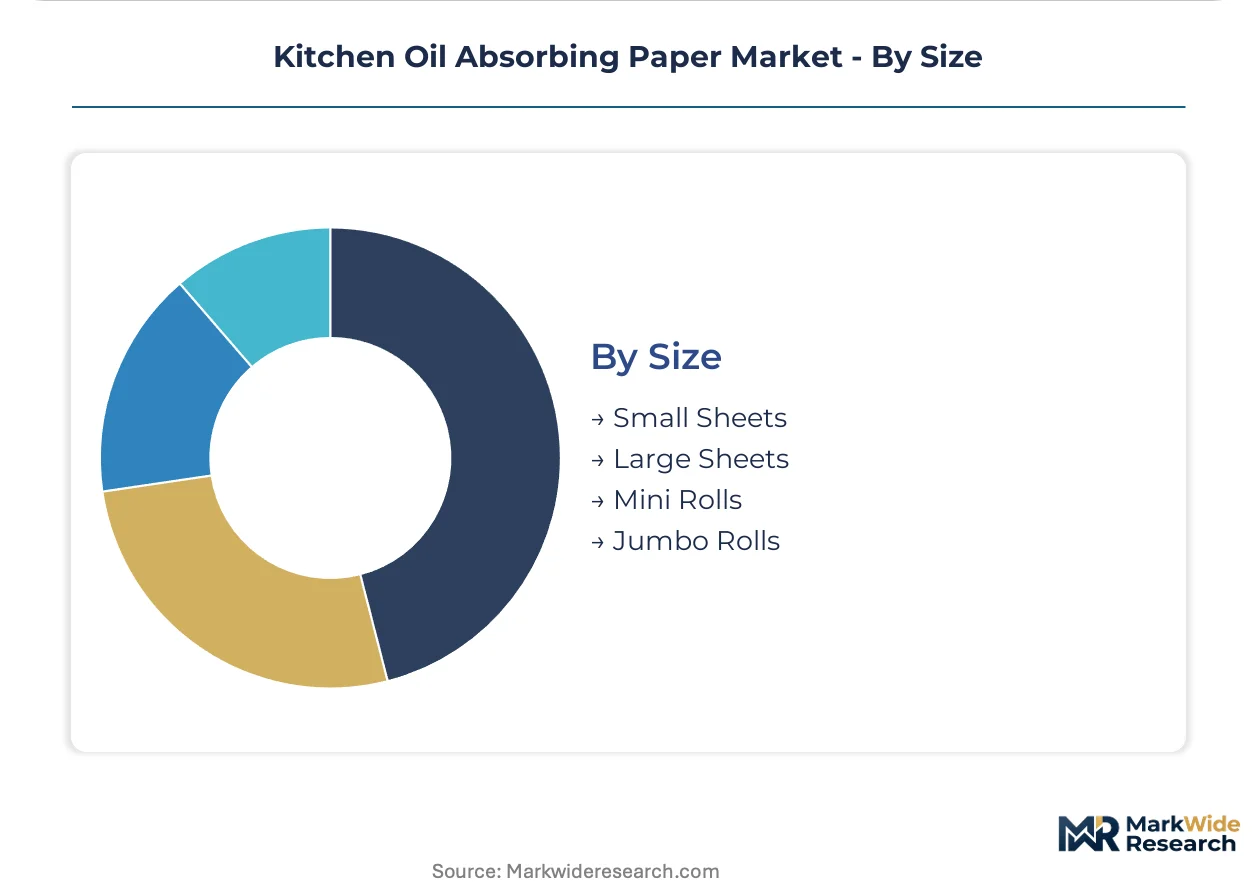
Dimension selection correlates with end-use batch scale and storage constraints. Commercial throughput demands continuous feed configurations while residential formats optimize for drawer and cabinet storage efficiency.
- Jumbo Rolls:Industrial-scale rolls exceeding 500 meters serve central kitchens and food manufacturing. Capital equipment integration requires specialized dispensing hardware that locks in supplier relationships.
- Large Sheets:30x40cm and larger formats handle commercial frying equipment and grill surfaces. Restaurant chain specification standards consolidate demand around 2-3 dimension standards.
- Small Sheets:Compact 15x15cm to 20x20cm dimensions match residential cookware scales. Japan's compact kitchen formats accelerate specification of space-efficient sheet sizes.
- Mini Rolls:Reduced-length rolls of 10-20 meters balance continuous feed convenience with residential storage constraints. Emerging format with limited standardization across brands.
Jumbo rolls dominate commercial installed base. Small sheets are where residential expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances in cellulose pulp are redirecting kitchen oil absorbing paper supply chains. Japan and South Korea rely on imported northern European softwood pulp, while Vietnam and Indonesia leverage domestic bamboo fiber to capture regional catering contracts. Regulatory divergence across FDA, EFSA, and NMPA frameworks fragments certification requirements and extends compliance timelines for cross-border suppliers.
United States
Restaurant chains deploy oil-absorbing sheets as visible food safety compliance tools to health-conscious consumers. FDA food-contact substance notifications require 18-24 month validation cycles for new cellulose grades. Georgia-Pacific operates integrated pulp-to-sheet facilities in the Southeast that supply institutional procurement channels.
Germany
Corporate catering contracts in Berlin and Hamburg now specify bamboo-based absorbents with FSC-certified sustainability credentials. ECHA's PFAS restrictions under REACH candidate list expansion force 12-18 month reformulation timelines for grease-resistant coatings. Bavarian converters accelerate PFAS-free certification to preempt regulatory deadlines.
Japan
Compact kitchen formats in Tokyo and Osaka accelerate pouch-pack adoption for residential oil absorption. METI standards align with food-contact purity mandates that elevate sourcing costs for imported grades. Convenience-store distribution channels in Kanto region expand SKU availability for 10-30 sheet pouches.
China
Quick-commerce platforms in Shanghai and Beijing compress retail replenishment cycles with same-day delivery expectations. NMPA GB standard compliance timelines for foreign cellulose products delay market entry and tie up working capital. Yangtze River Delta converters integrate with Meituan and Ele.me logistics networks for direct-to-warehouse fulfillment.
South Korea
Seoul's single-person household growth creates white space for branded, design-forward pouch formats at shelf-price premiums. MFDS food-contact regulations enforce migration limit testing that extends certification timelines. Busan-Ulsan industrial corridor hosts converters targeting premium household segments with convenience-oriented packaging.
Kitchen Oil Absorbing Paper Market Competitive Landscape
Listed leaders compete with private specialists across pulp-to-sheet integration levels. The vendor base concentrates around three tiers: integrated pulp producers with captive fiber supply, mid-scale converters with regional distribution lock-in, and specialty fabricators serving quick-commerce channels. Strategic moves center on backward integration into pulp sourcing and format-specific capacity expansion for pouch-pack production.
Among North American integrated producers, Kimberly-Clark Corporation and Georgia-Pacific exemplify the pulp-captive archetype with in-house bleaching capacity. Procter & Gamble occupies a position anchored through retail channel control and consumer brand recognition. Life-do.Plus Co., Ltd. represents the Asia-Pacific specialist tier focused on compact-format residential demand.
| Leading Market Players |
|---|
| Kimberly-Clark Corporation |
| Procter & Gamble |
| Georgia-Pacific |
| Fulton |
| Supreminox |
| International Paper |
| Essity |
| Life-do.Plus Co., Ltd. |
| Shanghai XiSi |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between northern European pulp mills and integrated sheet producers lock in fiber supply visibility while insulating converters from spot-market volatility in bleached softwood pulp. These arrangements concentrate pricing power with pulp-captive manufacturers as FDA and EFSA compliance costs elevate barriers for non-integrated competitors.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing across the institutional segment, with three-tier pricing structure across premium, standard, and economy levels separating certified compostable grades from conventional cellulose and synthetic fiber alternatives. Price differentiation rests on food-contact certification tier and volume scale, with FDA notification-grade products commanding sustained premiums. Cost compression in the standard tier is intensifying because Vietnamese bamboo pulp converters are undercutting northern European fiber on landed cost. Quick-service restaurant chains show least price sensitivity due to compliance documentation requirements, while independent food trucks exhibit highest elasticity.
Supply Chain Analysis
Canada and Sweden anchor softwood pulp production for food-grade cellulose, while Vietnam and Indonesia feed regional bamboo fiber supply chains. Raw material sourcing draws from northern European bleached kraft pulp, FSC-certified bamboo plantations, and polypropylene resin for synthetic alternatives. Single-source vulnerability concentrates in northern European pulp mill capacity, where energy cost spikes and labor disruptions transmit directly to converter margins. Distribution runs through broadline foodservice distributors for institutional volume, with quick-commerce platforms capturing household pouch-pack replenishment in Chinese and Japanese urban markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certification-as-a-service offerings are expanding faster than base sheet production, as converters bundle FDA notification support and compostability documentation with volume contracts to capture recurring revenue from compliance-challenged buyers.
For Market Incumbents: Compound pulp-to-sheet integration advantages by expanding captive bleaching capacity in the Southeast United States to offset European energy cost volatility. Lock in broadline distributor exclusivity through multi-year compliance documentation bundles that raise switching costs for restaurant chain procurement. Synthetic fiber substitution in price-sensitive commercial kitchens threatens volume share; counter with certified compostable grade price-matching in EU jurisdictions where disposal regulations bite hardest. For New Entrants and Emerging Players: Lead with quick-commerce channel integration for pouch-pack formats in Seoul and Shanghai, where same-day delivery expectations have outpaced incumbent logistics adaptation. South Korea's single-person household segment offers the most penetrable white space, with design-forward packaging commanding shelf-price premiums above functional equivalence. Pursue digital-native brand building through subscription box models that bypass retail slotting fee barriers. For Investors and Strategic Acquirers: Regional converters with captive bamboo pulp sourcing and existing FSC certification infrastructure present acquisition targets with defensible cost positioning against softwood price cycles. Long-term viability hinges on backward integration depth and multi-jurisdiction compliance capability rather than scale alone. Watch EU EFSA migration limit enforcement intensity as the inflection indicator for premium grade margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Sourcing | Captive fiber supply insulates margin from northern European mill disruption and EFSA purity mandates. |
| Compostability Certification Acceleration | BPI and TÜV Austria pre-certification captures EU Green Deal procurement preference ahead of 2025 deadlines. |
| Quick-Commerce Platform Integration | Meituan and Ele.me logistics network access enables same-day pouch-pack delivery in Shanghai and Beijing. |
| PFAS-Free Coating Reformulation | Polysaccharide barrier technology substitution preempts ECHA REACH candidate list restrictions on fluorinated treatments. |
| Design-Forward Pouch Format Launch | Seoul convenience-store channel placement captures single-person household premium pricing in Asia-Pacific's fastest-expanding segment. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with pulp procurement directors, foodservice distributor category managers, converter operations heads, and regulatory compliance officers; and secondary validation against FDA food-contact substance notification databases, EU EFSA migration limit guidance, NMPA GB standard filings, and customs trade records for cellulose pulp imports. Bottom-up volume triangulation across format-specific production estimates was cross-checked against top-down market sizing derived from broadline distributor procurement data and retail SKU velocity indicators.
Across the analysis window, the forecasting framework modeled demand evolution across product format, material certification tier, end-user segment, and regional regulatory cluster dimensions. CAGRs were derived from segment-level volume build-ups incorporating pulp cost pass-through elasticity, compliance timeline lag effects, and channel shift velocity parameters. Industry-specific forecast inputs included convenience-store SKU proliferation rates in Japanese urban markets and quick-commerce platform penetration in Chinese metropolitan areas.
The analysis sits within stated boundaries; outcomes outside sustained EU packaging directive enforcement, stable northern European pulp mill operating rates, or continued quick-commerce platform growth would require recalibration. Forecasts reflect documented assumptions regarding certification timeline durations and fiber substitution elasticity. Recalibration cycles align with material shifts in EFSA migration limit enforcement, NMPA import protocol revisions, and bamboo pulp capacity expansion in Southeast Asia.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
GCC Paper Bags Market
Paper & Paperboard Packaging
Converting Paper Market
Paper & Paperboard Packaging
Greyboard Market
Paper & Paperboard Packaging
Coated Sack Kraft Paper Market
Paper & Paperboard Packaging
Parchment Paper Market
Paper & Paperboard Packaging
Paper Canisters Market
Paper & Paperboard Packaging
MMA Film & Sheet Market
Paper & Paperboard Packaging
Decal Paper Market
Paper & Paperboard Packaging
Paperboard Protectors Market
Paper & Paperboard Packaging
Tea Filter Paper Market
Paper & Paperboard Packaging
Cold Seal Paper Market
Paper & Paperboard Packaging
Box Liners Market
Paper & Paperboard Packaging
Eco-Friendly Paper Plates Market
Paper & Paperboard Packaging
Bamboo Packaging Market
Paper & Paperboard Packaging
North America Paper Bags Market
Paper & Paperboard Packaging
Paper Cup Lids Market