
 Indonesia and Malaysia Lead Acid Battery Market | 2026-2036
Indonesia and Malaysia Lead Acid Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia and Malaysia Lead Acid Battery Market Analysis
Fleet consolidation among Indonesian logistics operators is realigning procurement volumes toward long-term supply contracts. Exide Industries Ltd. leverages its Indian manufacturing base to serve Southeast Asian aftermarket channels. PT. Trimitra Baterai Prakasa anchors domestic production capacity for Indonesia's commercial vehicle segment. Clarios competes through its regional distribution network covering both archipelago and peninsular markets.
Indonesia and Malaysia lead acid batteries store electrical energy through reversible electrochemical reactions between lead dioxide and sponge lead electrodes immersed in sulfuric acid electrolyte, typically operating at nominal voltages of 2V per cell with energy densities of 30-50 Wh/kg. Flooded batteries dominate the automotive starting-lighting-ignition segment due to lower unit costs and established service infrastructure. AGM variants capture share in telecommunications and UPS installations where maintenance-free operation and vibration resistance justify premium positioning. VRLA technology extends into renewable energy storage as solar deployment accelerates across both countries.
Indonesia's Ministry of Environment and Forestry enforces hazardous waste regulations governing spent battery collection, while Malaysia's Department of Environment administers similar Extended Producer Responsibility frameworks under the Environmental Quality Act. BIS-aligned standards from India's Bureau of Indian Standards influence regional product certification expectations for imported cells. Stakeholders must track evolving recycler licensing requirements and cross-border waste shipment protocols between the two jurisdictions.
Market Dynamics
Fleet consolidation among Indonesian logistics operators is compressing procurement cycles and locking in multi-year supply agreements with domestic manufacturers. This structural shift toward centralized purchasing is redistributing margin capture from distributors to producers with certified recycling capabilities.
Growth Catalysts
- Extended Producer Responsibility mandates:Indonesia's Ministry of Environment and Forestry hazardous waste regulations now require manufacturers to finance end-of-life battery collection, creating licensed recycler networks that secure feedstock for domestic smelters.
- Telecommunications infrastructure rollout:5G base station deployments across Java and the Klang Valley are absorbing VRLA battery volumes for backup power systems, with tower operators specifying AGM variants for reduced maintenance access.
- Commercial vehicle fleet expansion:E-commerce logistics growth is accelerating truck and van registrations, stretching replacement demand for heavy-duty starting batteries through Java's manufacturing corridor.
Market Restraints
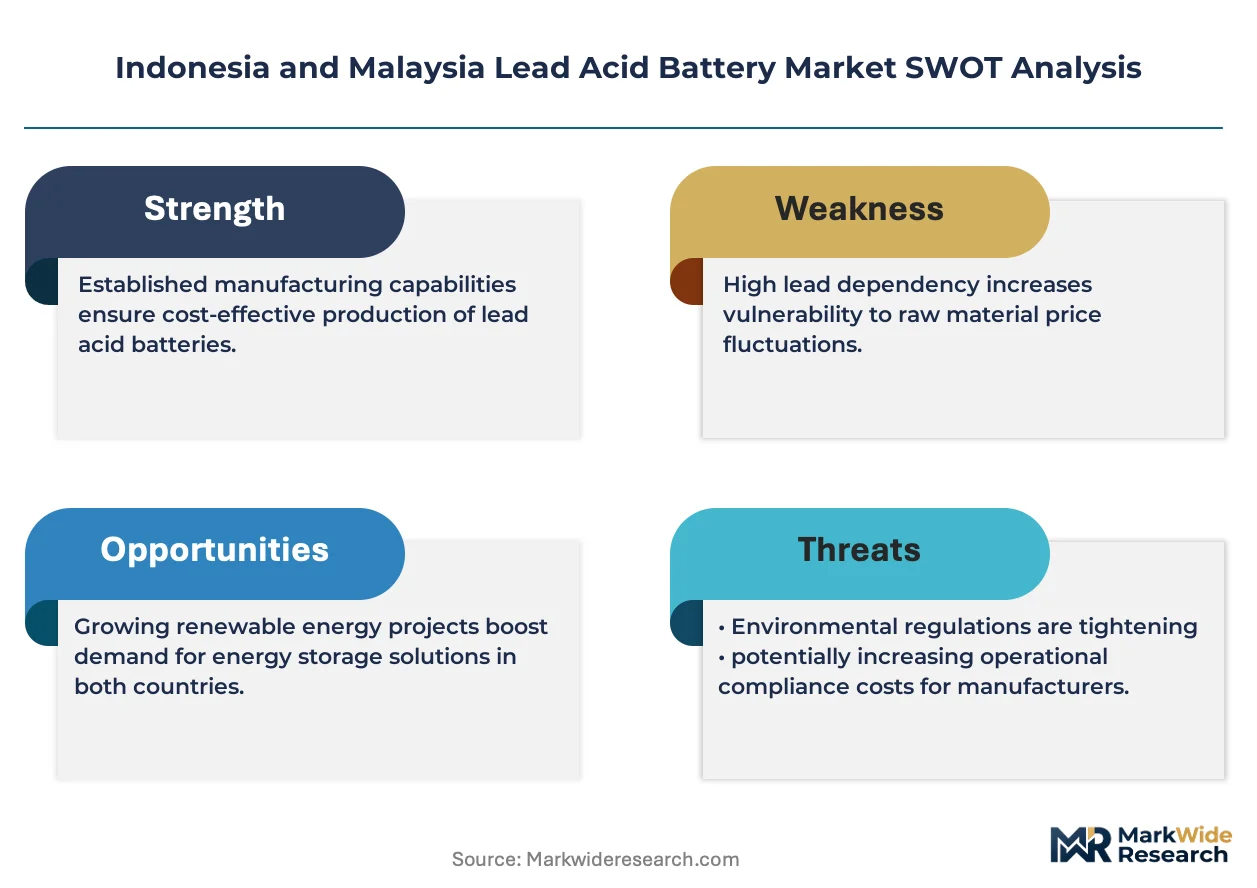
- Lead price volatility:Raw material cost swings from London Metal Exchange pricing compress margins for flooded battery assemblers lacking long-term concentrate supply contracts.
- Lithium-ion substitution:Forklift electrification and two-wheeler segments are migrating to lithium phosphate chemistry, constraining lead acid addressable market in motive power applications.
- Smelter concentration risk:Spent battery processing capacity clusters in Indonesia's Banten province, creating geographic single-point vulnerability for recycling compliance.
Strategic Opportunities
- Solar-storage hybrid installations:Off-grid renewable deployments in Sumatra and Sarawak are specifying deep-cycle lead acid for cost-sensitive rural electrification projects.
- Direct-to-fleet distribution:Bypassing traditional aftermarket channels through telematics-integrated battery monitoring contracts captures lifetime value from logistics operators.
- BIS-aligned certification:India's Bureau of Indian Standards testing protocols are becoming de facto regional benchmarks, enabling Indonesian exporters to access Bangladesh and Sri Lankan markets.
Industry Challenges
- Recycler licensing delays:Indonesia's Ministry of Environment and Forestry permit backlogs are extending compliance timelines for new collection hub rollouts.
- Cross-border waste protocol friction:Malaysia's Department of Environment and Indonesian regulators maintain incompatible spent battery shipment documentation, complicating regional reverse logistics.
- Technical workforce scarcity:Electrochemical engineering talent pools in both countries remain thin for advanced AGM and gel battery manufacturing scale-up.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia and Malaysia Lead Acid Battery Market |
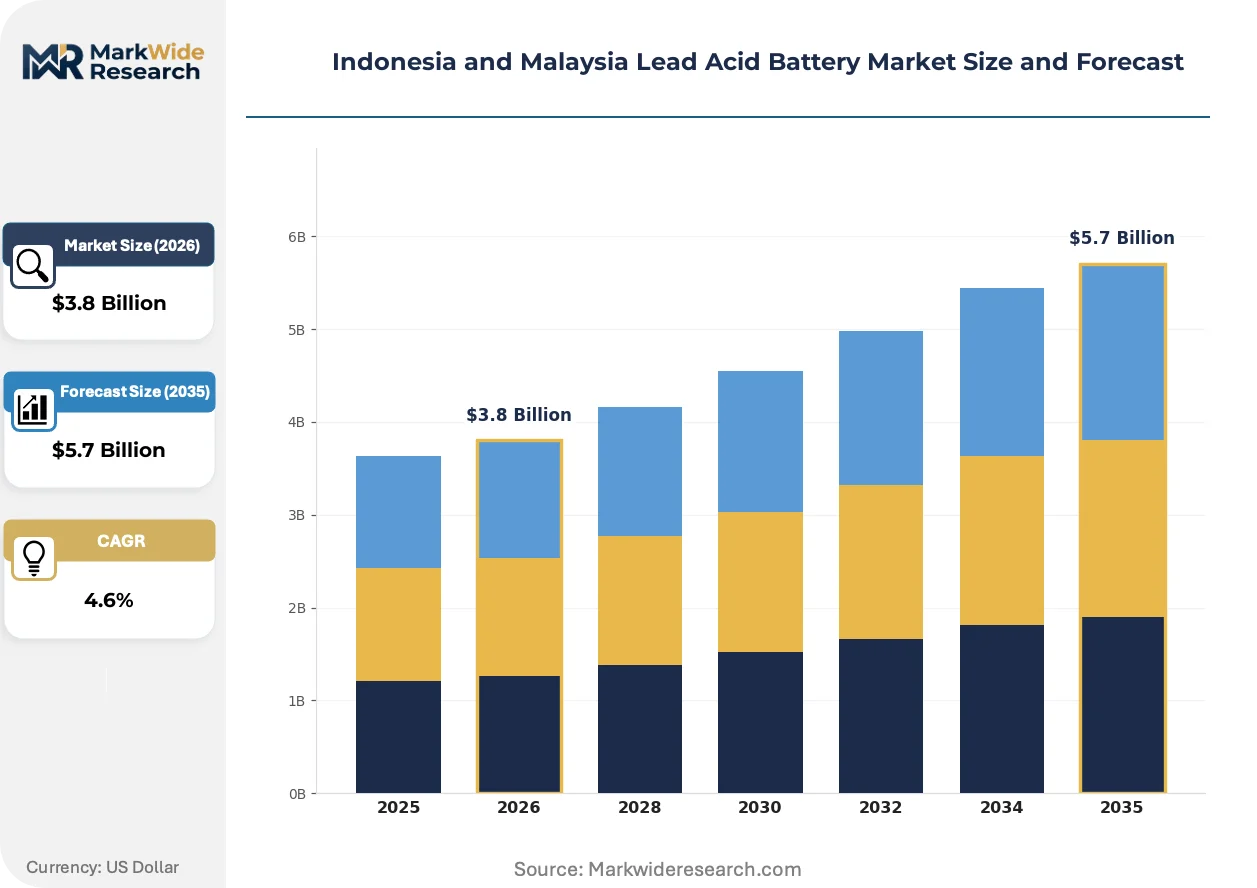
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flooded, AGM, Gel, VRLA End User: Automotive, Telecommunications, UPS, Renewable Energy Technology: Lead-Acid, Hybrid, Advanced Lead-Acid, Recycled Lead-Acid Application: Starting Lighting Ignition, Energy Storage, Backup Power, Forklift |
| Companies Covered | Exide Industries Ltd., PT. Trimitra Baterai Prakasa, Clarios, PT. Yuasa Industrial Battery Indonesia, Century Batteries Indonesia, GS Yuasa Corporation, Amara Raja Energy & Mobility, Panasonic Corporation, EnerSys, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia and Malaysia Lead Acid Battery Market Emerging Trajectories
Carbon additive formulations and automated assembly lines are compressing cost structures while regulatory pressure on recycling compliance is reshaping competitive requirements. These forces are converging to differentiate producers with integrated smelter operations from pure assemblers.
Silicon-enhanced negative plates are absorbing higher charge acceptance rates in micro-hybrid vehicle applications. Malaysian passenger car assemblers are specifying these enhanced flooded batteries for start-stop systems, displacing standard flooded units in the OEM channel. The technology is absorbing incremental market share as fuel economy regulations tighten.
Malaysia's Department of Environment Extended Producer Responsibility framework under the Environmental Quality Act now mandates annual recycling rate disclosures from battery importers. Industrial users in the Klang Valley are demanding chain-of-custody documentation for spent battery disposal. Telecommunications operators are responding by pre-qualifying suppliers with licensed recycler partnerships.
Consolidated fleet procurement is compressing distributor margins and favoring direct manufacturer relationships. Large logistics operators in Java are unbundling battery supply from vehicle maintenance contracts, negotiating standalone multi-year agreements with volume guarantees. This pattern is most visible among cold-chain transporters operating refrigerated trucks between Jakarta and Surabaya.
Indonesia and Malaysia Lead Acid Battery Market Segmentation
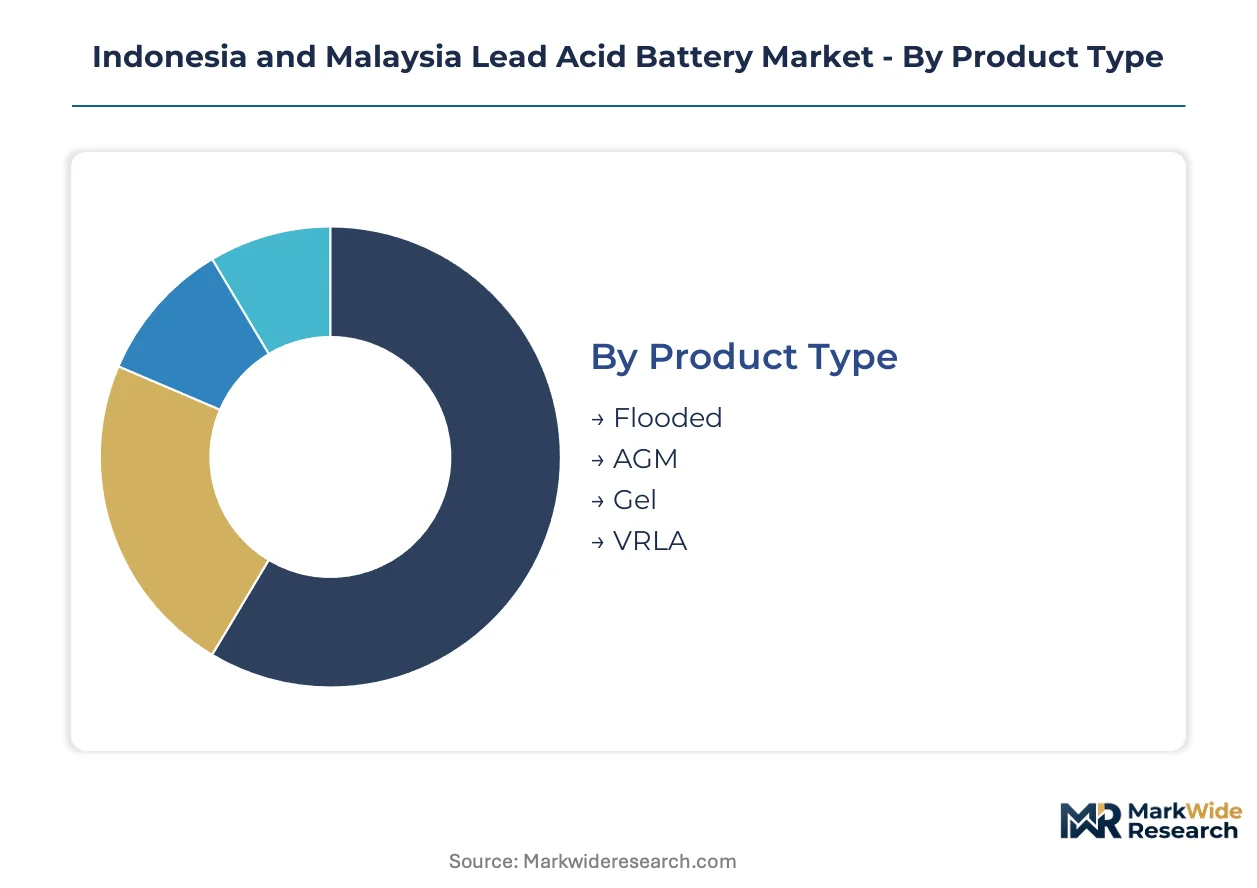
Segmentation in the Indonesia and Malaysia lead acid battery market reveals how regulatory frameworks and application requirements fragment procurement patterns. Each dimension carries distinct certification burdens and margin structures that shape competitive positioning.
Product Type:
BIS-aligned standards from India's Bureau of Indian Standards create tiered compliance obligations across product categories, with flooded batteries facing lighter documentation than sealed variants intended for critical infrastructure.
- Flooded:Standard flooded cells use liquid sulfuric acid electrolyte with removable caps for maintenance access. Demand concentrates in Java's commercial vehicle aftermarket where fleet operators prioritize unit economics over maintenance-free operation. Indonesia's Ministry of Environment and Forestry hazardous waste regulations now require collection documentation for these high-volume, shorter-lifecycle products.
- AGM:Absorbed glass mat construction immobilizes electrolyte in fiberglass separators, enabling vibration resistance and sealed operation. Telecommunications operators across the Klang Valley specify AGM for 5G base station backup power where maintenance access is costly. Malaysia's Department of Environment Extended Producer Responsibility framework mandates recycler partnerships for these premium deployments.
- Gel:Silica-thickened electrolyte prevents stratification and extends cycle life in deep-discharge applications. Solar installers in Sumatra and Sarawak favor gel for off-grid rural electrification.
- VRLA:Valve-regulated lead acid technology combines recombinant gas chemistry with pressure-relief safety mechanisms. UPS installations in Kuala Lumpur's financial district require VRLA for fire-code compliance in enclosed spaces.
Leading the category by volume: Flooded. Growing fastest: AGM.
End User:
Cost tier differentiation separates price-sensitive automotive replacement demand from premium infrastructure applications where total cost of ownership calculations dominate procurement.
- Automotive:Starting-lighting-ignition batteries serve passenger cars, trucks, and buses across both archipelago and peninsular markets. E-commerce logistics expansion in Java's manufacturing corridor is stretching replacement schedules for heavy-duty commercial fleets.
- Telecommunications:Tower operators in Indonesia and Malaysia specify VRLA and AGM variants for grid-backup reliability. 5G rollout timelines are absorbing incremental volume as base station density increases.
- UPS:Uninterruptible power supply installations protect data centers and manufacturing lines in the Klang Valley industrial zone. Financial institutions and semiconductor fabs demand chain-of-custody documentation for spent battery disposal.
- Renewable Energy:Solar-storage hybrid projects in rural Sumatra and Sarawak specify deep-cycle lead acid for cost-sensitive deployments where lithium-ion premiums are prohibitive.
Automotive commands absolute volume. Renewable energy climbs fastest as rural electrification accelerates.
Technology:
Supply concentration in Indonesia's Banten province smelters creates geographic dependency that shapes technology selection for recycling compliance.
- Lead-Acid:Conventional flooded and VRLA chemistries using virgin or recycled lead feedstock. Dominates current installed base across both markets.
- Hybrid:Carbon-enhanced negative plates improve charge acceptance for micro-hybrid start-stop applications. Malaysian passenger car assemblers are specifying these for fuel economy compliance.
- Advanced Lead-Acid:Silicon-doped electrodes and optimized grid alloys extend cycle life and reduce sulfation. Targets premium UPS and telecommunications segments.
- Recycled Lead-Acid:Batteries manufactured with secondary lead from licensed smelters. Indonesia's hazardous waste regulations are mandating minimum recycled content disclosures for fleet supply contracts.
Conventional lead-acid holds volume dominance. Hybrid technology expands most quickly as start-stop penetration rises.
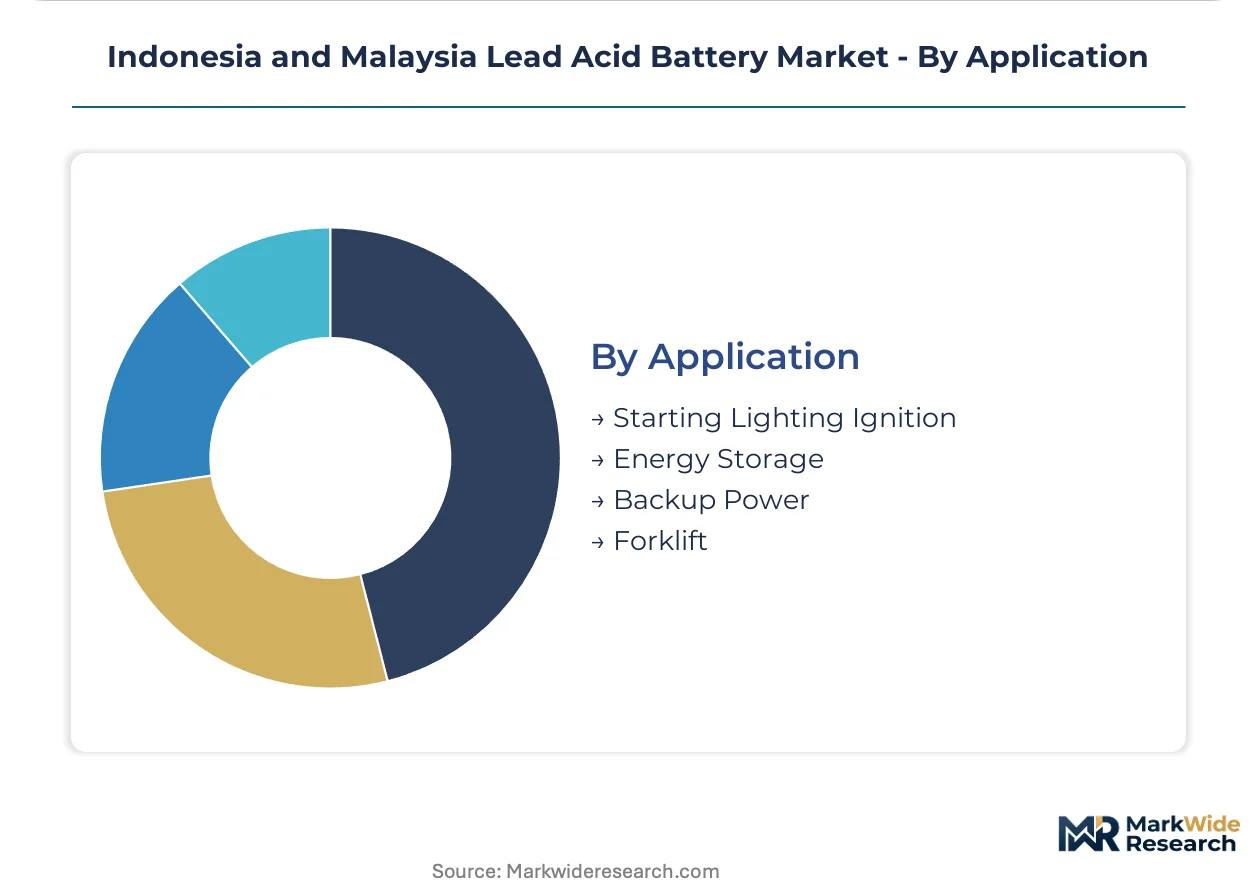
Application:
Customer type fragmentation separates OEM channel specifications from aftermarket replacement cycles with divergent margin structures.
- Starting Lighting Ignition:Cranking power for internal combustion engines across passenger and commercial vehicles. Java's logistics consolidation is compressing procurement into multi-year fleet agreements.
- Energy Storage:Deep-cycle operation for solar and wind integration. Rural electrification projects in Sumatra favor lead acid over lithium for capital cost containment.
- Backup Power:Standby operation for critical infrastructure during grid interruptions. Telecommunications and data center operators in the Klang Valley prioritize maintenance-free AGM and VRLA.
- Forklift:Motive power for material handling in warehouses and manufacturing. Lithium-ion substitution is constraining lead acid addressable market in this segment.
Starting-lighting-ignition generates largest volume. Energy storage gains share fastest on renewable deployment momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Java's manufacturing corridor and the Klang Valley industrial zone around Kuala Lumpur. Fleet consolidation among Indonesian logistics operators is realigning procurement volumes toward long-term supply contracts. Malaysia's Department of Environment Extended Producer Responsibility framework is tightening compliance requirements for cross-border battery movements.
Indonesia
E-commerce logistics expansion is accelerating truck and van registrations across Java's manufacturing corridor. Indonesia's Ministry of Environment and Forestry enforces hazardous waste regulations governing spent battery collection and recycling. Smelter processing capacity clusters in Banten province, creating geographic concentration for recycling compliance that shapes domestic supply chain configurations.
Malaysia
5G base station deployments across the Klang Valley are absorbing VRLA battery volumes for backup power systems. The Department of Environment administers Extended Producer Responsibility frameworks under the Environmental Quality Act. Tower operators in Kuala Lumpur's financial district are demanding chain-of-custody documentation for spent battery disposal from their suppliers.
Thailand
Automotive assembly plants serving Southeast Asian export markets generate aftermarket replacement demand for starting-lighting-ignition batteries. The country's national environmental regulator maintains hazardous waste handling protocols for industrial battery users. Manufacturing corridors around Bangkok and the Eastern Economic Corridor host fleet operators consolidating procurement into centralized purchasing agreements.
Vietnam
Rapid manufacturing sector expansion is driving forklift and material handling equipment electrification, creating motive power battery demand. National technical standards for battery safety and recycling are evolving under industrial environmental regulations. Industrial zones in northern provinces around Hanoi and southern hubs near Ho Chi Minh City concentrate logistics fleet operations.
Philippines
Telecommunications infrastructure buildout for island connectivity requires reliable backup power systems across dispersed base stations. The national environmental management authority oversees hazardous waste protocols for battery disposal. Metro Manila's logistics operators and Cebu-based manufacturing facilities represent primary demand concentrations for commercial vehicle batteries.
Indonesia and Malaysia Lead Acid Battery Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue certified recycling capabilities and direct-to-fleet distribution channels. The vendor base organizes around three archetypes: integrated manufacturers with licensed smelter operations, regional distributors leveraging import networks, and domestic assemblers serving fleet replacement cycles. Consolidation pressures favor producers with hazardous waste compliance infrastructure over pure trading operations. Competitive moves center on backward integration into recycling assets and multi-year supply contract capture from logistics operators.
Among India-based producers, Exide Industries Ltd. and Amara Raja Energy & Mobility exemplify the integrated manufacturing archetype with cross-border supply capabilities. PT. Trimitra Baterai Prakasa represents domestic production capacity anchored in Indonesia's commercial vehicle segment. Clarios occupies a position within the multinational distribution tier, competing through regional network coverage spanning archipelago and peninsular markets. These three entities illustrate the competitive spectrum from import-dependent distribution to fully integrated domestic manufacturing with recycling compliance.
| Leading Market Players |
|---|
| Exide Industries Ltd. |
| PT. Trimitra Baterai Prakasa |
| Clarios |
| PT. Yuasa Industrial Battery Indonesia |
| Century Batteries Indonesia |
| GS Yuasa Corporation |
| Amara Raja Energy & Mobility |
| Panasonic Corporation |
| EnerSys |
| Others |
Supply Flow & Price Mechanics
Carbon additive formulations and automated assembly lines are compressing production economics while concentrating margin capture among integrated manufacturers. This dual transformation is redistributing pricing power from distributors toward producers with captive smelter operations and licensed recycling capabilities across Indonesia and Malaysia.
Pricing Analysis
Volume-mass flooded batteries trade on razor-thin unit economics while premium AGM and gel variants command maintenance-free premiums. Three-tier pricing structure across premium, standard, and economy levels separates telecommunications-grade AGM from commercial fleet flooded cells from generic aftermarket imports. Cost compression in the flooded tier is intensifying because fleet consolidation forces multi-year contract bidding wars. Cold-chain logistics operators in Java exhibit highest price sensitivity, while Klang Valley data centers prioritize total cost of ownership over upfront battery expenditure.
Supply Chain Analysis
Regional distribution centers in Jakarta and Kuala Lumpur operate hub-and-spoke patterns reaching Surabaya and Penang satellite warehouses. Lead concentrate feeds from Australia, Peru, and domestic Indonesian mines; sulfuric acid is sourced from local chemical processors; polyethylene separators are imported from China and Thailand. Single-source vulnerability clusters in Banten province smelters, where spent battery processing capacity concentrates. Distribution runs through manufacturer-direct fleet contracts and traditional aftermarket channels serving smaller commercial operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market has become a vertical-integration race where backward integration into licensed recycling assets determines compliance viability and feedstock security for domestic manufacturers.
For Market Incumbents: Anticipate lithium-ion encroachment in forklift motive power by deepening AGM capacity for telecommunications backup and start-stop hybrid applications. Secure BIS-aligned certification for Indonesian exporters targeting Bangladesh and Sri Lankan markets. Lock multi-year fleet agreements with Java cold-chain operators before distributor relationships fragment further.
For New Entrants and Emerging Players: Begin with solar-storage hybrid installations in rural Sumatra and Sarawak where lithium-ion premiums exclude cost-sensitive electrification projects. Pursue direct-to-fleet telematics-integrated monitoring contracts bypassing traditional aftermarket channels. Target telecommunications tower operators demanding chain-of-custody documentation as entry wedge.
For Investors and Strategic Acquirers: Re-rating potential sits with integrated manufacturers possessing licensed smelter operations given Indonesia's Ministry of Environment and Forestry tightening hazardous waste handling enforcement. Long-term viability favors producers with captive recycling feedstock and direct fleet relationships over pure assemblers. Watch recycler licensing permit velocity as inflection indicator for compliance cost escalation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycling | Captures spent battery feedstock for Banten smelters under tightening Ministry of Environment and Forestry regulations. |
| Direct-to-Fleet Distribution | Bypasses distributor margin compression through telematics-integrated lifetime value contracts with Java logistics operators. |
| BIS-Aligned Certification Investment | Enables Indonesian exporters to access Bangladesh and Sri Lankan aftermarket channels with recognized standards. |
| AGM Capacity Expansion | Serves 5G base station backup power demand across Klang Valley telecommunications infrastructure rollout. |
| Licensed Recycler Partnership | Satisfies Malaysia's Department of Environment Extended Producer Responsibility disclosure mandates for tower operators. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with fleet procurement managers, telecommunications infrastructure planners, battery manufacturing plant engineers, and licensed recycler operations directors were cross-referenced against Indonesia's Ministry of Environment and Forestry hazardous waste documentation, Malaysia's Department of Environment Extended Producer Responsibility disclosures, BIS certification registries, and London Metal Exchange lead price archives. Bottom-up volume estimates from end-use segmentations were reconciled with top-down market value assessments.
Granularity-level modeling distinguished product type, end user, technology tier, and application dimensions across the analysis window. Conventional lead-acid, hybrid, and advanced lead-acid technology categories were projected separately; automotive, telecommunications, UPS, and renewable energy end-use segments carried distinct growth assumptions. CAGRs were derived from segment-level volume trajectories weighted by average selling price evolution. Solar deployment pipelines in Sumatra and Sarawak, 5G base station rollout schedules in the Klang Valley, and commercial vehicle fleet expansion in Java's manufacturing corridor provided industry-specific forecast inputs.
Underlying measurement precision varies by segment; flooded automotive replacement volumes carry tighter precision than emerging solar-storage applications. Forecasts reflect documented assumptions regarding regulatory enforcement timelines, lead price volatility bands, and lithium-ion substitution rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
United Kingdom SLI Battery Market
Batteries
Advanced Batteries Market
Batteries
Europe Consumer Battery Market
Batteries
Stretchable Battery Market
Batteries
Asia-Pacific Dual Carbon Battery Market
Batteries
Wireless Power Bank Market
Batteries
Sodium-Air Battery Market
Batteries
Bangladesh Lead Acid Battery Market
Batteries
Middle East Rechargeable Battery Market
Batteries
India SLI Battery Market
Batteries
High Voltage Battery Market
Batteries
Electric Battery Market
Batteries
Secondary Battery Market
Batteries
Southeast Asia Battery Market
Batteries
South America Battery Cell Market
Batteries
Europe Rechargeable Battery Market