
 18650 And 21700 Battery Market | 2026-2036
18650 And 21700 Battery Market Size, Share, and Industry Trends Forecast 2026-2036
18650 And 21700 Battery Market Insights
Silicon-dominant anode blends is consolidating around 21700 formats as cell makers push energy density past 300 Wh/kg thresholds. Panasonic leverages its Nevada-Tesla joint production footprint to anchor North American cylindrical cell supply. Samsung SDI competes through specialized high-nickel cathode formulations for premium power tool packs. LG Energy Solution differentiates with automated winding equipment that cuts electrode defect rates below two parts per million.
18650 and 21700 batteries are standardized cylindrical lithium-ion cells measuring 18mm by 65mm and 21mm by 70mm respectively, constructed with layered electrode assemblies wound around a central mandrel and housed in nickel-plated steel cans with pressure-relief vent mechanisms. These formats serve as modular building blocks for battery packs requiring high discharge rates, thermal stability, and manufacturing consistency across electric vehicles, power tools, and portable electronics. The application dimension shows electric vehicles commanding the dominant value share as OEMs specify 21700 cells for skateboard-platform packs, while energy storage systems represent the fastest-expanding outlet behind declining cell costs per kilowatt-hour. Product type segmentation reveals lithium-ion chemistry holding mature volume leadership as nickel-cobalt variants retain premium positioning in high-rate tool applications.
The EU Battery Regulation mandates carbon footprint declarations and recycled content thresholds that reshape cell import compliance costs for non-European producers. China's NMPA enforces GB 38031 thermal runaway propagation standards that force design changes to venting pathways and separator materials. The US IRA domestic content bonus credits steer pack assembly location decisions independent of cell origin. Stakeholders must monitor how regional certification divergence affects platform standardization strategies across multinational customer portfolios.
Market Dynamics
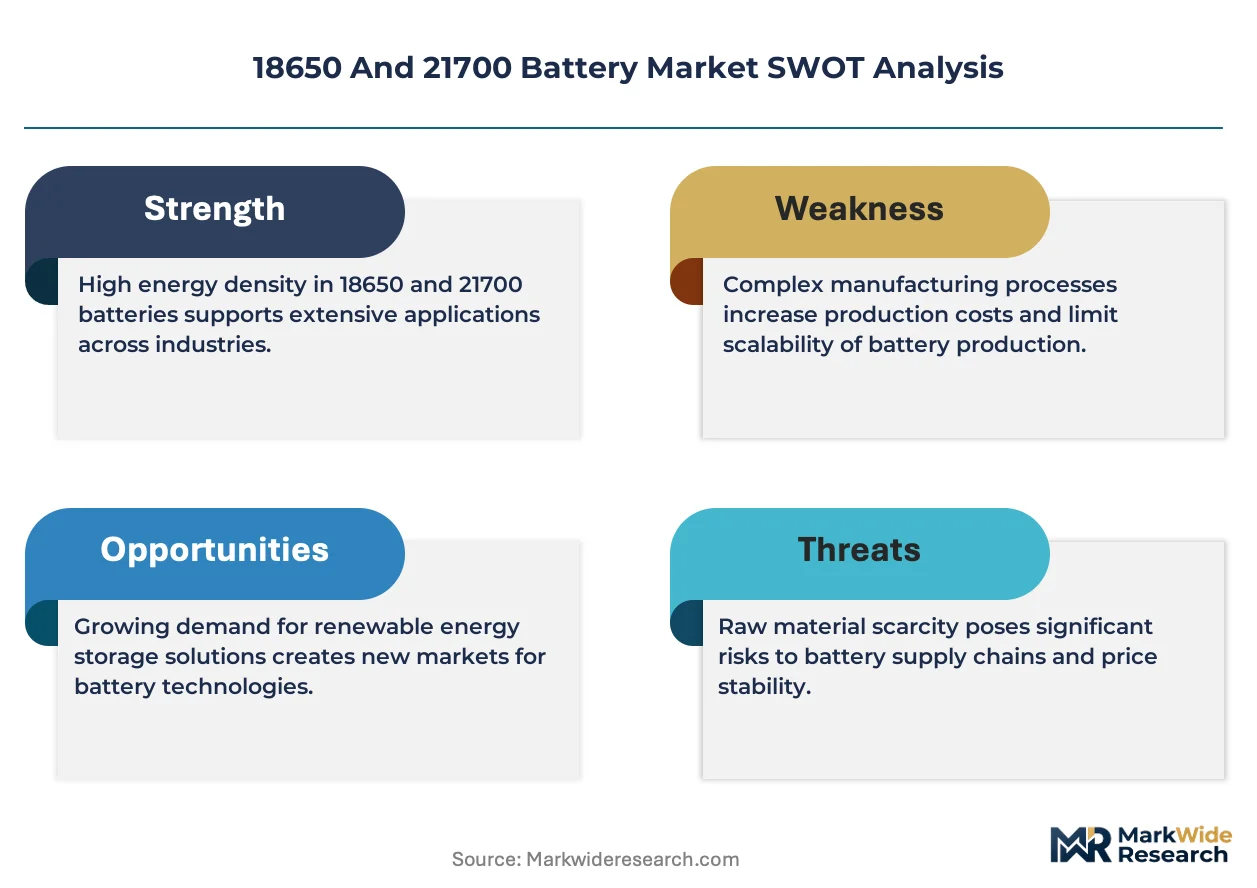
Silicon-dominant anode chemistry is compressing traditional graphite anode supply chains as cell manufacturers chase energy density thresholds above 300 Wh/kg, forcing cathode material suppliers in China's Jiangsu province to recalibrate procurement specifications.
Growth Catalysts
- GB 38031 Thermal Runaway Standards:China's NMPA certification mandates are accelerating separator material upgrades and venting pathway redesigns across cylindrical cell architectures, pulling demand for advanced ceramic-coated separators.
- Power Tool OEM Pack Refresh Cycles:Professional-grade cordless equipment manufacturers are specifying high-nickel 21700 formulations to replace legacy nickel-metal hydride packs, creating sustained cathode material demand.
- Lithium Iron Phosphate Chemistry Expansion:Electric vehicle pack designers are absorbing LFP cylindrical cells for entry-level skateboard platforms, diversifying cathode procurement away from cobalt-dependent supply chains.
Market Restraints
- Refined Cobalt Price Volatility:Artisanal mining concentration in the Democratic Republic of Congo exposes cathode precursor costs to geopolitical disruption and ethical sourcing audit failures.
- Separator Film Supply Concentration:Wet-process polyethylene separator production clusters in South Korea and Japan, creating single-source vulnerability for cell manufacturers outside Northeast Asia.
- Prismatic Cell Format Substitution:Automotive OEMs designing blade-style battery architectures are bypassing cylindrical winding equipment entirely, compressing addressable demand for 18650 and 21700 tooling.
Strategic Opportunities
- Stationary Energy Storage Underpenetration:Grid-scale battery installations in India remain below 5 GWh cumulative deployment, presenting first-mover positioning for cylindrical cell suppliers meeting BIS certification requirements.
- US IRA Domestic Content Bonus:The Inflation Reduction Act's tax credit stacking for North American pack assembly is redirecting cell qualification programs toward Nevada and Michigan manufacturing footprints.
- Solid-State Electrolyte Convergence:Sulfide-based ceramic electrolyte research programs at Japanese automotive OEMs are creating partnership opportunities for cylindrical cell makers with dry-electrode coating capabilities.
Industry Challenges
- Electrolyte Formulation Talent Scarcity:Cell manufacturers report 18-month lead times to hire experienced lithium salt and additive chemists capable of optimizing high-voltage cycling stability.
- Multi-Standard Certification Parallelism:Simultaneous pursuit of UN 38.3 transport certification, UL 9540A thermal runaway propagation testing, and regional NMPA or EU Battery Regulation compliance extends product launch timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 18650 And 21700 Battery Market |
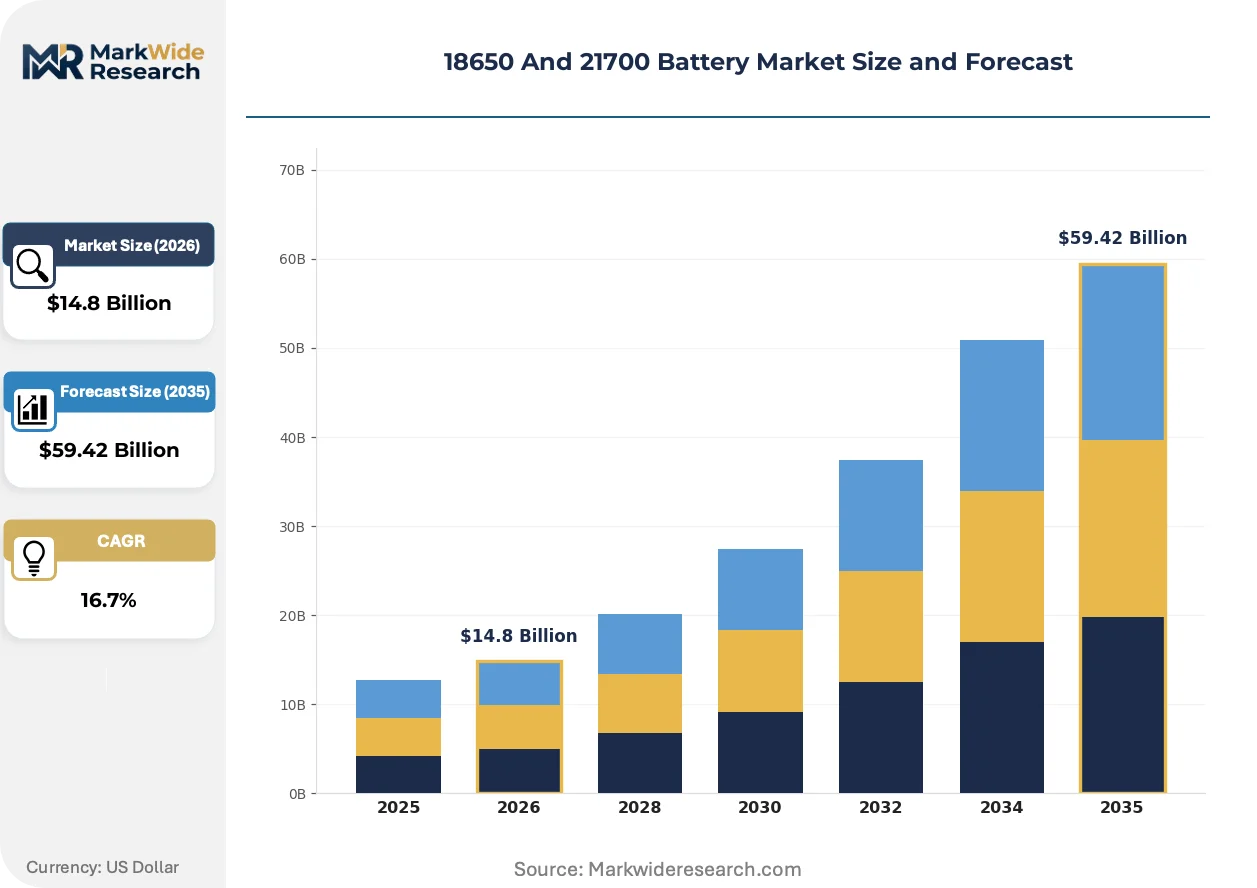
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $59.42 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rechargeable, Lithium-ion, Nickel-cobalt, Lithium-polymer Application: Electric Vehicles, Power Tools, Consumer Electronics, Energy Storage Systems Configuration: Single Cell, Pack, Module, Custom Design Distribution Channel: Online Retail, Direct Sales, Distributors, Specialty Stores |
| Companies Covered | Panasonic, Samsung SDI, LG Energy Solution, Murata Manufacturing, EVE Energy, BAK Power, Tianjin Lishen, SVOLT, Sunpower, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
18650 And 21700 Battery Market Trends and Innovations
Electrode manufacturing equipment and cell formation protocols are undergoing parallel transformation as energy density targets collide with compressed cycle time requirements and tightening safety margins.
Silicon-dominant anode blends are absorbing incremental graphite capacity as cell makers validate 10-15% silicon oxide loadings in 21700 formats. Electric vehicle battery engineers at OEMs specifying skateboard platforms are adopting these cells for premium range variants. The technology is absorbing capital allocation previously directed toward incremental nickel content increases in cathode formulations.
EU Battery Regulation carbon footprint declarations and recycled content thresholds are forcing non-European cell manufacturers to deploy mass-balance accounting systems and secure black mass processing partnerships. Industrial consequence includes 12-18 month compliance preparation timelines for suppliers without existing European recycling infrastructure. High-nickel cylindrical cells for premium power tool applications face the steepest documentation burden due to complex cobalt supply chain provenance requirements.
Direct-to-pack procurement contracts are consolidating previously fragmented spot-market purchasing for cylindrical cells. Automotive OEMs are displacing tier-one battery integrators with cell qualification programs managed in-house, compressing margin capture for traditional pack assemblers. This pattern is most visible in Germany where KBA type-approval processes now require cell-level traceability documentation that only direct manufacturer relationships can satisfy.
18650 And 21700 Battery Market Segmentation
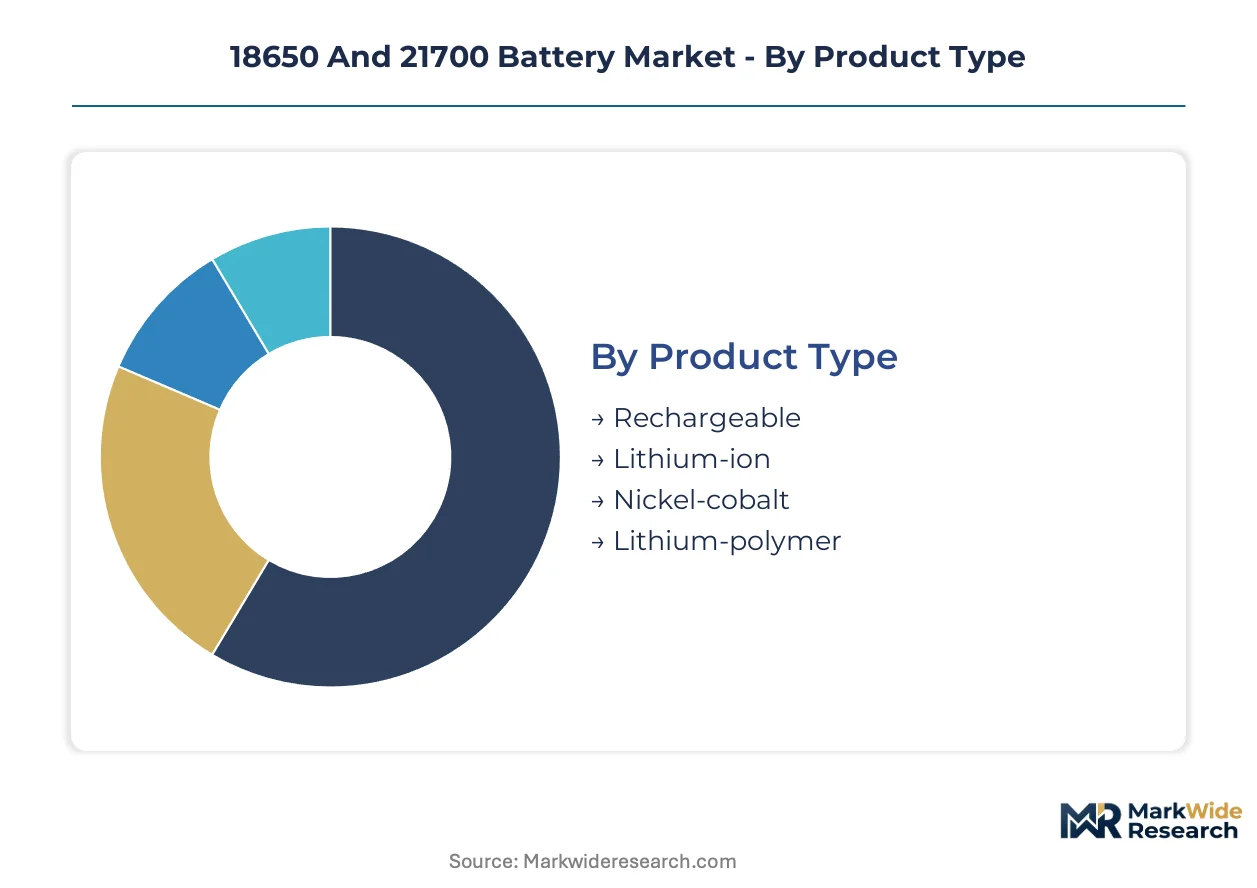
Cylindrical cell procurement decisions cascade through chemistry selection, pack architecture, and channel configuration, each tier carrying distinct margin profiles and certification burdens. OEMs weight thermal runaway compliance against energy density targets when mapping segment priorities.
Product Type:
Cost tier structures procurement with premium formulations commanding qualification premiums for high-rate applications.
- Lithium-ion:Graphite-anode cylindrical cells dominate volume manufacturing with standardized 3.6V nominal outputs and mature winding equipment ecosystems. Demand concentrates in China's Jiangsu province gigafactories serving electric vehicle skateboard platforms, pulled by GB 38031 thermal propagation mandates forcing separator upgrades.
- Nickel-cobalt:High-nickel cathode formulations deliver 4.2V ceiling voltages for power tool packs requiring 30A continuous discharge. Procurement clusters with professional-grade cordless equipment OEMs refreshing legacy nickel-metal hydride inventories, constrained by DRC cobalt provenance documentation for EU Battery Regulation compliance.
- Rechargeable:Consumer-grade cells with cycle life specifications above 500 charge cycles.
- Lithium-polymer:Pouch-format alternatives with flexible form factors for compact electronics.
Volume sits with lithium-ion; growth tilts toward nickel-cobalt.
Application:
Application dictates cell format selection with 21700 dimensions displacing 18650 where pack space efficiency outweighs legacy tooling investment.
- Electric Vehicles:Automotive OEMs specify 21700 cells for skateboard-platform packs with silicon-dominant anode blends pushing energy density past 300 Wh/kg thresholds. Demand concentrates with Nevada-Tesla joint production anchoring North American supply, pulled by US IRA domestic content bonus credits steering pack assembly location decisions.
- Energy Storage Systems:Grid-scale cylindrical cell deployments absorb declining per-kilowatt-hour costs for stationary applications. Procurement is expanding most quickly in India below 5 GWh cumulative deployment, creating first-mover positioning for suppliers meeting BIS certification requirements.
- Power Tools:Professional cordless equipment requiring high-rate discharge capability.
- Consumer Electronics:Portable devices with standardized cell dimensions for manufacturing consistency.
Revenue concentrates with electric vehicles; steepest expansion trajectory belongs to energy storage systems.
Configuration:
Customer type separates spot-market purchasers from direct-to-pack contract holders consolidating previously fragmented procurement.
- Pack:Integrated cell assemblies with battery management systems and thermal interface materials. Demand concentrates with automotive OEMs displacing tier-one battery integrators through in-house qualification programs, pulled by KBA type-approval processes in Germany requiring cell-level traceability documentation.
- Module:Intermediate assemblies with standardized interconnects for scalable system architecture.
- Single Cell:Individual cylindrical units for replacement markets and custom integration.
- Custom Design:Application-specific geometries outside standard 18650/21700 dimensions.
Procurement volume favors pack configurations; module demand climbs fastest as energy storage standardizes.
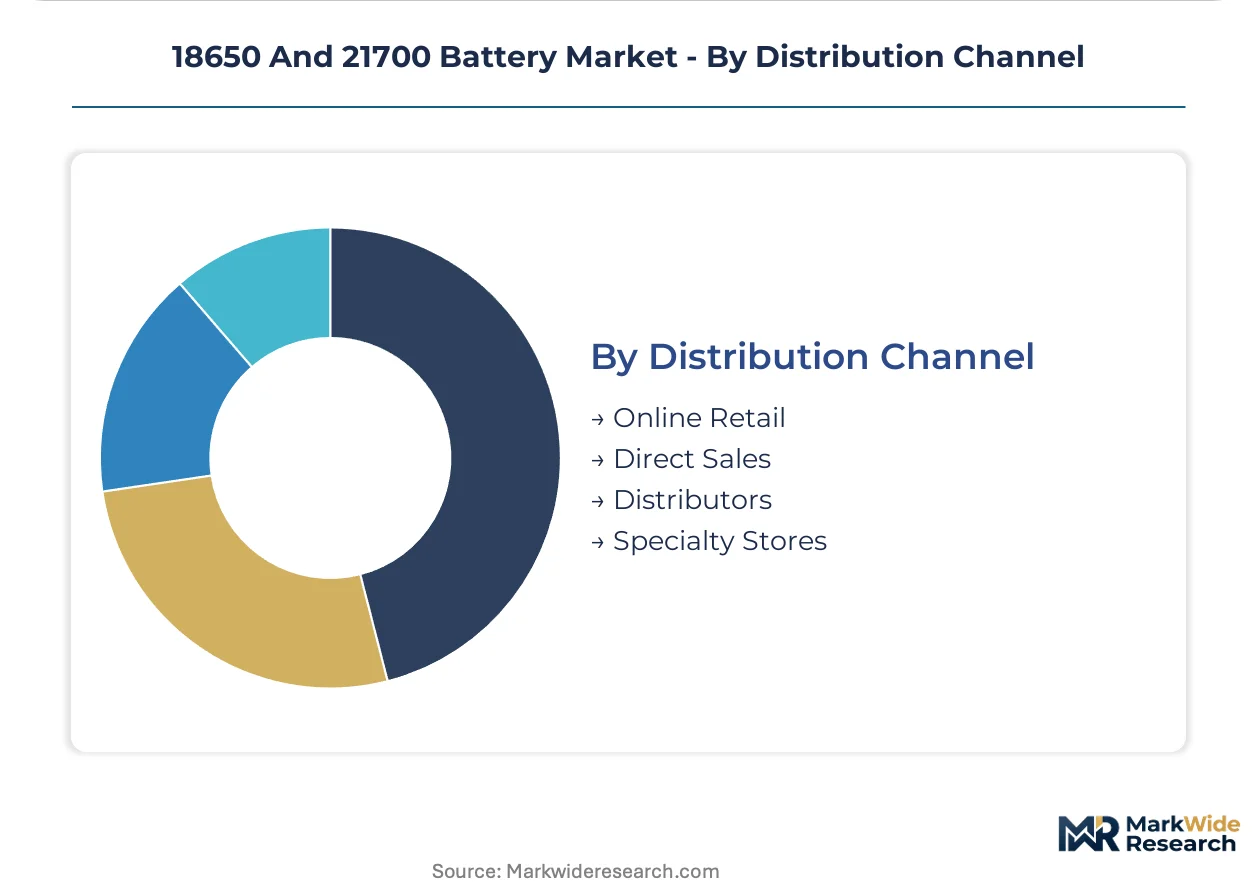
Distribution Channel:
Supply concentration shapes channel access with direct relationships capturing qualification-intensive automotive and industrial accounts.
- Direct Sales:Manufacturer-to-OEM contracts with multi-year volume commitments and joint development clauses. Demand concentrates with electric vehicle and power tool pack designers, pulled by carbon footprint declaration requirements under EU Battery Regulation forcing mass-balance accounting system deployment.
- Distributors:Regional inventory holders serving mid-volume industrial and replacement markets.
- Online Retail:E-commerce platforms for consumer electronics and hobbyist segments.
- Specialty Stores:Technical retailers with application engineering support for professional users.
Transaction volume flows through distributors; direct sales gain share fastest in automotive qualification programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in China's Jiangsu and Guangdong provinces where cell gigafactories cluster near cathode material suppliers, while regulatory divergence across major economies reshapes localization strategies.
China
GB 38031 thermal runaway propagation standards from NMPA are forcing design changes to venting pathways and separator materials across cylindrical cell architectures. The dual carbon goals policy framework accelerates domestic LFP chemistry expansion for entry-level electric vehicle platforms. Cell production gravity centers on Jiangsu province gigafactories serving skateboard-platform pack assemblers.
United States
IRA domestic content bonus credits steer pack assembly location decisions toward Nevada and Michigan manufacturing footprints independent of cell origin. Panasonic leverages its Nevada-Tesla joint production to anchor North American cylindrical cell supply for premium range variants. KBA type-approval processes in Germany indirectly pressure US-based automotive OEMs to adopt direct-to-pack procurement with cell-level traceability documentation.
Germany
EU Battery Regulation carbon footprint declarations and recycled content thresholds reshape cell import compliance costs for non-European producers. KBA type-approval processes now require cell-level traceability documentation that only direct manufacturer relationships can satisfy. Automotive OEMs in Bavaria and Baden-Württemberg are displacing tier-one battery integrators through in-house qualification programs.
South Korea
Wet-process polyethylene separator production clusters in South Korea and Japan, creating single-source vulnerability for cell manufacturers outside Northeast Asia. Samsung SDI competes through specialized high-nickel cathode formulations for premium power tool packs. LG Energy Solution differentiates with automated winding equipment that cuts electrode defect rates below two parts per million.
India
Grid-scale battery installations remain below 5 GWh cumulative deployment, presenting first-mover positioning for cylindrical cell suppliers meeting BIS certification requirements. The PLI scheme for advanced chemistry cell manufacturing redirects capital toward domestic gigafactory development. Maharashtra and Gujarat states are absorbing initial cell qualification programs as energy storage procurement expands fastest.
18650 And 21700 Battery Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with tier-one cell makers consolidating automotive direct procurement while mid-scale fabricators serve power tool and consumer electronics replacement markets. The structure tilts toward concentrated supply at the high-performance tier and fragmented competition in standardized lithium-ion formulations. Three archetypes dominate: integrated chemistry-innovation leaders, equipment-automation specialists, and regional cost-optimized producers. Capacity expansion and backward integration into cathode precursor processing represent the dominant competitive moves reshaping margin capture.
Among Northeast Asian integrated leaders, Panasonic, Samsung SDI, and LG Energy Solution occupy positions that exemplify the chemistry-innovation archetype. Panasonic represents the joint-venture production model with captive demand anchoring through Nevada-based output. Samsung SDI sits within the high-nickel specialization tier where cathode formulation expertise creates differentiation. LG Energy Solution exemplifies equipment-automation leadership through winding technology that compresses defect rates. These three entities anchor the premium tier where direct-to-pack contracts are consolidating previously fragmented procurement.
| Leading Market Players |
|---|
| Panasonic |
| Samsung SDI |
| LG Energy Solution |
| Murata Manufacturing |
| EVE Energy |
| BAK Power |
| Tianjin Lishen |
| SVOLT |
| Sunpower |
| Others |
Pricing and Supply Chain Analysis
Cathode precursor cobalt contracts cascade through three pricing tiers as Jiangsu province gigafactories convert DRC-mined ore into nickel-cobalt-manganese formulations for premium 21700 cells, while LFP cylindrical alternatives anchor economy positioning for entry-level electric vehicle platforms.
Pricing Analysis
Volume sits with standardized lithium-ion cells where graphite-anode formulations compete on scale; margin concentrates in high-nickel cathode tiers where Samsung SDI and LG Energy Solution extract qualification premiums for power tool OEMs demanding 30A continuous discharge. Price differentiation hinges on certification burden—EU Battery Regulation carbon footprint declarations and GB 38031 thermal runaway compliance add documentation costs that separate premium direct-to-pack contracts from spot-market transactions. Cost compression runs through nickel-cobalt tiers as artisanal mining audit failures in the DRC disrupt precursor supply. Energy storage system buyers exhibit highest price sensitivity due to project finance constraints, while automotive OEMs absorb premium positioning for silicon-dominant anode variants pushing past 300 Wh/kg thresholds.
Supply Chain Analysis
Single-source vulnerability sits with wet-process polyethylene separator production clustering in South Korea and Japan, exposing cell manufacturers outside Northeast Asia to supply interruption. Raw material procurement draws from DRC cobalt concentrates, Australian spodumene for lithium hydroxide, and Jiangsu province cathode precursor synthesis. Tariff exposure intensifies as EU Battery Regulation recycled content thresholds force non-European producers to secure black mass processing partnerships. Distribution runs through direct manufacturer-to-OEM contracts consolidating previously fragmented spot-market purchasing, with tier-one battery integrators losing share to in-house automotive qualification programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cylindrical cell sector sits in a chemistry-transition phase as silicon-dominant anode blends displace incremental graphite capacity and LFP formulations erode nickel-cobalt-manganese dominance in entry-level electric vehicle platforms.
For Market Incumbents: Deepen backward integration into cathode precursor processing to defend margin capture against prismatic cell format substitution threatening cylindrical winding equipment demand. Anchor capacity expansion in Nevada and Michigan manufacturing footprints to capture US IRA domestic content bonus credits steering pack assembly location decisions. Prioritize automated winding equipment investments that compress electrode defect rates below two parts per million, replicating LG Energy Solution's differentiation model. For New Entrants and Emerging Players: Enter via India's sub-5 GWh cumulative grid-scale deployment gap where BIS certification requirements create first-mover positioning for cylindrical cell suppliers meeting stationary energy storage procurement expansion. Target Maharashtra and Gujarat states absorbing initial cell qualification programs under the PLI scheme for advanced chemistry cell manufacturing. Lead with direct-to-pack contract structures that displace tier-one battery integrators, mirroring German automotive OEM procurement patterns. For Investors and Strategic Acquirers: Panasonic's Nevada-Tesla joint production consolidation is the leading indicator that captive demand anchoring through automotive partnerships determines long-term viability across the analysis window. Acquisition targets should screen for dry-electrode coating capabilities positioning for sulfide-based ceramic electrolyte convergence at Japanese automotive OEM research programs. Monitor solid-state electrolyte partnership announcements as the inflection signal separating equipment-automation specialists from stranded chemistry-only players.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Precursor Processing | Captures margin from DRC cobalt provenance through Jiangsu province synthesis capacity. |
| Silicon-Dominant Anode Capacity Buildout | Positions suppliers for 300 Wh/kg premium range variants at Nevada-Tesla joint production. |
| Direct-to-Pack Contract Structuring | Satisfies KBA type-approval traceability requirements displacing tier-one integrators. |
| EU Battery Regulation Compliance Infrastructure | Deploys mass-balance accounting systems securing black mass processing partnerships. |
| Automated Winding Equipment Investment | Replicates LG Energy Solution defect rate compression below two parts per million. |
Research Methodology
Document review covered SEC filings from Panasonic, Samsung SDI, and LG Energy Solution, complemented by interviews with cell manufacturing executives, cathode material procurement leads at Jiangsu province gigafactories, power tool OEM pack designers, and stationary energy storage project developers. Secondary validation drew from NMPA GB 38031 certification databases, EU Battery Regulation implementation guidance, US IRA domestic content bonus credit interpretations, and India BIS certification requirement documentation. Bottom-up cell production capacity modeling triangulated against top-down electric vehicle skateboard-platform pack demand forecasts.
Output projections span unit volume and value across chemistry type, application segment, and configuration tier throughout the forecast period. Segmentation dimensions modeled include lithium-ion versus nickel-cobalt versus LFP chemistry, electric vehicle versus energy storage versus power tool end-use, and pack versus module versus single cell configuration. CAGRs derive from installed base replacement cycles, OEM platform refresh timelines, and regional regulatory compliance phase-in schedules. Industry-specific inputs incorporate silicon-dominant anode loading validation curves and separator material upgrade cost trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under DRC supply disruption, prismatic format acceleration, or solid-state electrolyte commercialization breakthroughs. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
South and Central America Battery Market
Batteries
South Europe Battery Market
Batteries
US Motive Lead Acid Battery Market
Batteries
Zinc-Manganese Oxide Printed Battery Market
Batteries
East Europe Battery Market
Batteries
Battery Light Towers Market
Batteries
West Europe Battery Market
Batteries
Battery Voltage Recorder Market
Batteries
Forklift Battery Rental Market
Batteries
Sodium-Air Battery Market
Batteries
Marine Powerboat Battery Market
Batteries
Tubular GEL Battery Market
Batteries
India Alkaline Battery Market
Batteries
Europe Automotive Lead-Acid Battery Market
Batteries
High Temperature NiMH Battery Market
Batteries
Primary Lithium Battery Market