
 High Voltage Battery Market | 2026-2036
High Voltage Battery Market Size, Share, and Industry Trends Forecast 2026-2036
High Voltage Battery Market Intelligence
Aftermarket service revenue is fragmenting across diagnostic software, cell balancing, and thermal retrofitting as battery system complexity outpaces generic maintenance capabilities. CATL sustains manufacturing scale through integrated cathode production in Ningde. LG Energy Solution anchors premium automotive supply relationships with dedicated lines for 800-volt architectures. Tesla Energy differentiates through proprietary battery management software that locks service revenue internally.
High voltage batteries store and deliver electrical energy at potentials exceeding 60 volts DC, typically employing layered oxide cathodes, graphite or silicon-blend anodes, and non-aqueous electrolytes formulated for electrochemical stability across thousands of cycles. Their primary purpose centers on traction power for electric vehicles and grid-scale energy buffering where energy density and discharge rate determine system economics. Lithium-ion cells occupy the dominant position in installed capacity while solid-state formats attract development capital for their potential to eliminate thermal runaway pathways. Energy Storage Systems applications show the steepest demand trajectory as utility procurement shifts from pilot programs to multi-gigawhour tenders. Battery Management Systems technology commands disproportionate margin share relative to cell production, reflecting software complexity and safety certification barriers.
China's MIIT enforces GB standards for battery safety testing that constrain cell suppliers without certified thermal propagation resistance. The EU Battery Regulation mandates recycled content thresholds and digital passport traceability that reshape supply chain accountability across European-bound exports. In the United States, NHTSA defect investigation protocols and EPA lifecycle emissions scrutiny add compliance layers distinct from Asian manufacturing baselines. Stakeholders must weigh regional certification divergence against platform standardization economics when committing to cell chemistry and pack architecture roadmaps.
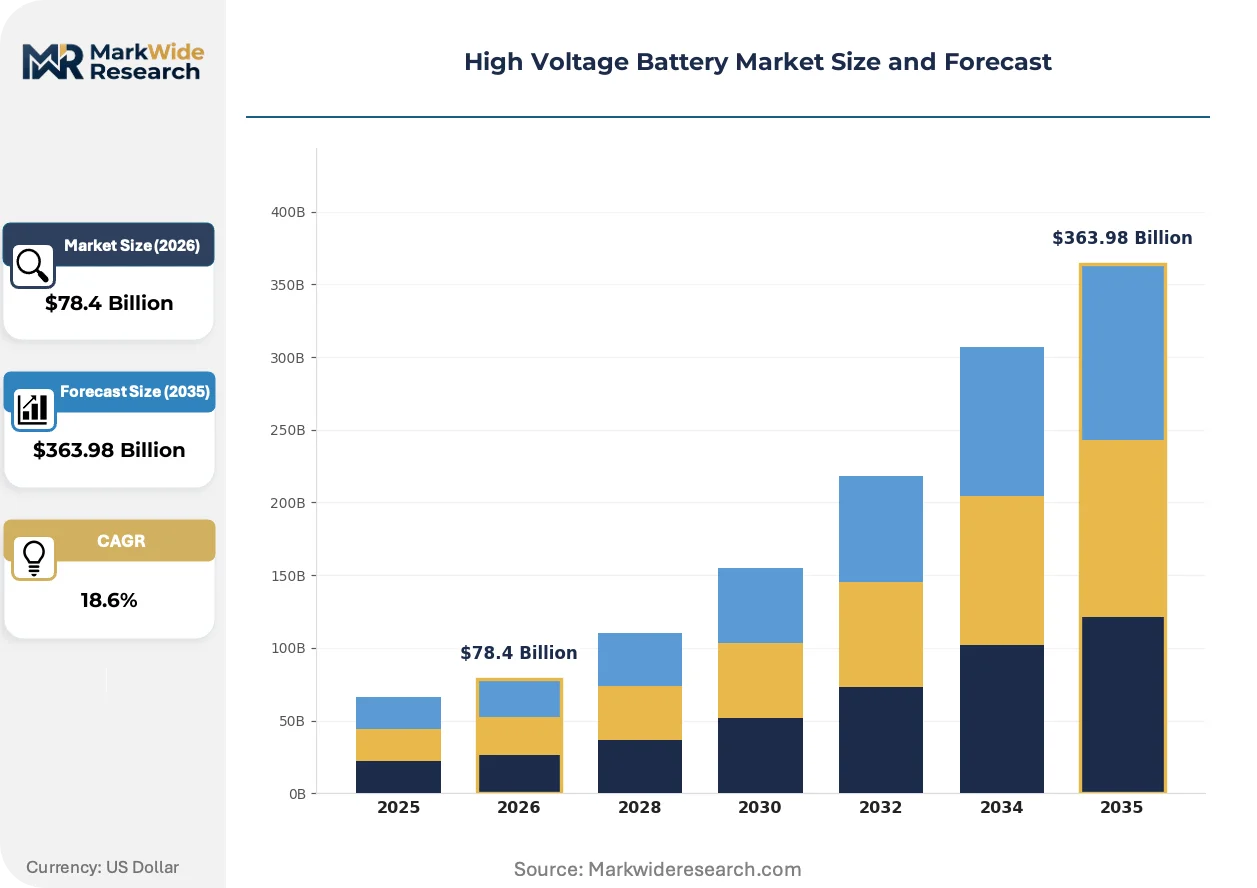
Market Dynamics
Cell-to-pack architecture is collapsing traditional module assembly steps, compressing manufacturing footprints and redirecting capital toward integrated cathode-anode production lines in Ningde and Jiangsu.
Growth Catalysts
- EU Battery Regulation recycled content mandates:Digital passport traceability requirements are accelerating supply chain reconfiguration across European-bound exports, forcing upstream integration into certified refining operations.
- 800-volt traction architectures:Premium automotive OEMs are specifying high-voltage platforms above 400 volts DC, pulling demand for silicon carbide inverters and matched cell chemistries.
- Jiangsu-Fujian production clusters:Integrated cell-to-pack facilities in these provinces are capturing procurement volume from domestic OEMs and energy storage integrators simultaneously.
Market Restraints
- Nickel-cobalt price volatility:Cathode raw material swings above 30% quarterly are compressing margin predictability for nickel-rich NMC formulations.
- MIIT GB thermal propagation standards:Uncertified cell suppliers face exclusion from Chinese automotive qualification, creating a two-tier supply structure.
- Solid-state electrolyte manufacturing yield:Ceramic processing defects above 15% are delaying commercial scale-up of sulfide and oxide solid-state formats.
Strategic Opportunities
- Grid-scale energy storage tenders:Utility procurement shifting from pilot programs to multi-gigawhour contracts is opening dedicated production lines outside automotive qualification cycles.
- Battery Management Systems software licensing:Functional safety certification to ISO 26262 ASIL-D is creating captive revenue streams independent of cell supply relationships.
- US Inflation Reduction Act domestic content credits:$35 per kWh production incentives are attracting cathode active material investments into North American chemical processing.
Industry Challenges
- Electrochemical modeling talent scarcity:Cell degradation algorithm development requires PhD-level expertise in solid-electrolyte interphase mechanics that outpaces university pipeline output.
- Pack-to-vehicle integration timelines:OEM platform cycles spanning 48 months are misaligned with 18-month cell chemistry iteration rates, forcing bridge inventory commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Voltage Battery Market |
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $363.98 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Nickel Metal Hydride, Lead-acid, Solid State End User: Automotive, Consumer Electronics, Renewable Energy, Industrial Equipment Application: Energy Storage Systems, Electric Vehicles, Uninterruptible Power Supplies, Hybrid Systems Technology: Fast Charging, Wireless Charging, Battery Management Systems, Thermal Management |
| Companies Covered | LG Energy Solution, Sungrow, CATL, EVE Energy, Pylontech, BYD Energy Storage, Siemens Battery Storage, Gotion High-tech, Tesla Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Voltage Battery Market Strategic Shifts & Innovations
Silicon-anode blending and dry electrode coating are compressing legacy wet-process equipment valuations while redirecting R&D toward solid-state interface engineering.
Dry electrode coating is collapsing capital intensity requirements for electrode manufacturing by eliminating solvent recovery systems and reducing drying oven footprints by 70%. Korean and Chinese equipment suppliers are retrofitting existing lines while Greenfield facilities in Hungary and Arizona specify dry-process native architectures. This transition is collapsing the competitive position of solvent-based coating incumbents who lack thermal bonding expertise.
The EU Battery Regulation's digital passport mandate is forcing cell-level traceability from mine to module, with ECHA compliance systems now required for all European-bound automotive and stationary storage products. Suppliers without blockchain-verified chain-of-custody documentation face automatic disqualification from public procurement tenders. German automotive OEMs are responding by mandating supplier ERP integration with their passport generation platforms before 2027 qualification gates.
Utility procurement departments are consolidating vendor relationships around integrated cell-pack-system suppliers capable of warranting 20-year cycle life, displacing the previous multi-vendor assembly model. This concentration is compressing margins for pure-play cell producers lacking in-house power conversion or thermal management capabilities. The shift is most visible in Texas and California ISO markets where merchant storage developers face offtake bankability requirements that favor vertically integrated suppliers.
High Voltage Battery Market Segmentation
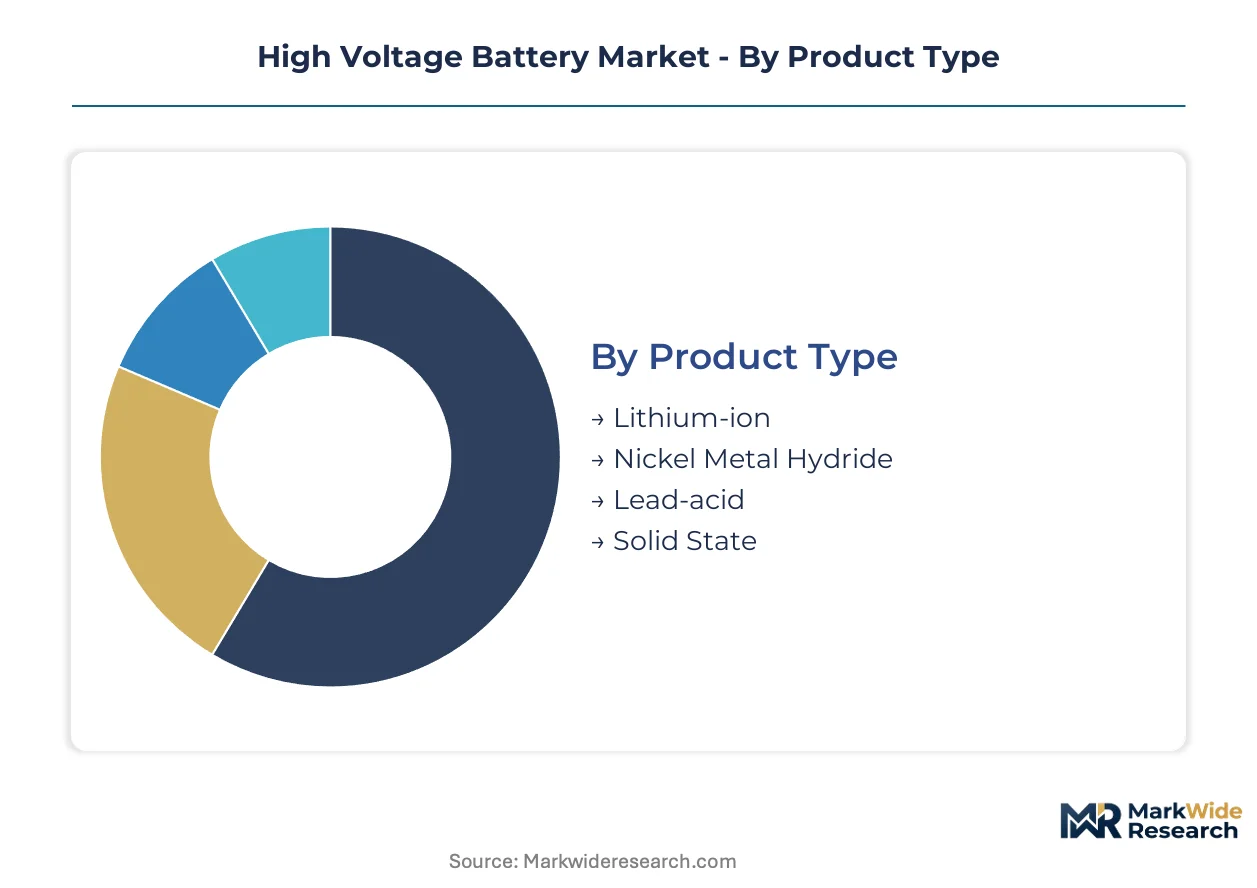
High voltage battery procurement patterns diverge sharply across chemistry platforms, end-use specifications, and integration architectures. Manufacturers configure production lines around distinct thermal envelopes, cycle life requirements, and safety certification tiers that resist cross-segment standardization.
Product Type:
Chemistry selection determines energy density ceilings, raw material exposure, and manufacturing capital intensity across the value chain.
- Lithium-ion:Layered oxide cathodes paired with graphite or silicon-blend anodes dominate installed capacity through mature electrode coating and formation protocols. Demand concentrates in Jiangsu and Fujian province facilities supplying both domestic Chinese OEMs and European energy storage integrators as national emissions standards tighten.
- Solid State:Ceramic electrolyte architectures eliminate thermal runaway pathways but face 15% plus manufacturing defect rates in sulfide and oxide formats. Japanese and Korean development programs anchor premium automotive qualification timelines while commercial scale-up awaits yield breakthroughs.
- Nickel Metal Hydride:Mature chemistry retains position in hybrid electric vehicle applications where moderate energy density tolerates established supply chains.
- Lead-acid:Flooded and absorbed glass mat formats persist in industrial uninterruptible power supply and starter applications where cost sensitivity outweighs energy density requirements.
Lithium-ion commands the established base. The steepest expansion runs through solid state formats as ceramic processing yields improve.
End User:
Customer procurement specifications create divergent performance envelopes and warranty structures that shape cell chemistry roadmaps.
- Automotive:Traction battery packs rated above 400 volts DC require silicon carbide inverter matching and 800-volt architecture compatibility. German, Chinese, and United States manufacturers scale procurement as fleet emissions regulations tighten and platform electrification accelerates.
- Renewable Energy:Grid-scale storage tenders demand 20-year cycle life warranties and integrated power conversion capabilities. Utility procurement in Texas and California ISO markets favors vertically integrated cell-pack-system suppliers over pure-play cell producers.
- Consumer Electronics:Cylindrical and prismatic formats prioritize volumetric energy density and fast charge acceptance for portable power tool and personal mobility applications.
- Industrial Equipment:Forklift, mining vehicle, and material handling systems specify ruggedized thermal management and opportunity charging protocols.
Automotive anchors current revenue concentration. Renewable energy is climbing the fastest as multi-gigawhour utility tenders displace pilot program volumes.
Application:
Use-case duty cycles determine depth of discharge profiles, thermal management intensity, and safety system redundancy requirements.
- Electric Vehicles:Battery electric and plug-in hybrid platforms specify cell-to-pack architectures that compress module assembly steps and redirect capital toward integrated cathode-anode production. Ningde and Jiangsu facilities capture procurement from both domestic OEMs and European export programs.
- Energy Storage Systems:Stationary applications prioritize calendar life over power density, pulling demand for lithium iron phosphate and emerging sodium-ion chemistries. Merchant storage developers face offtake bankability requirements that favor integrated suppliers with in-house power conversion.
- Uninterruptible Power Supplies:Data center and critical infrastructure applications demand instantaneous fault tolerance and redundant battery management system architectures.
- Hybrid Systems:Combined renewable-plus-storage and diesel-battery hybrid configurations require flexible charge-discharge scheduling software.
Electric vehicles retains the volume base. Energy storage systems shows the steepest trajectory as procurement shifts from pilot to utility-scale tenders.
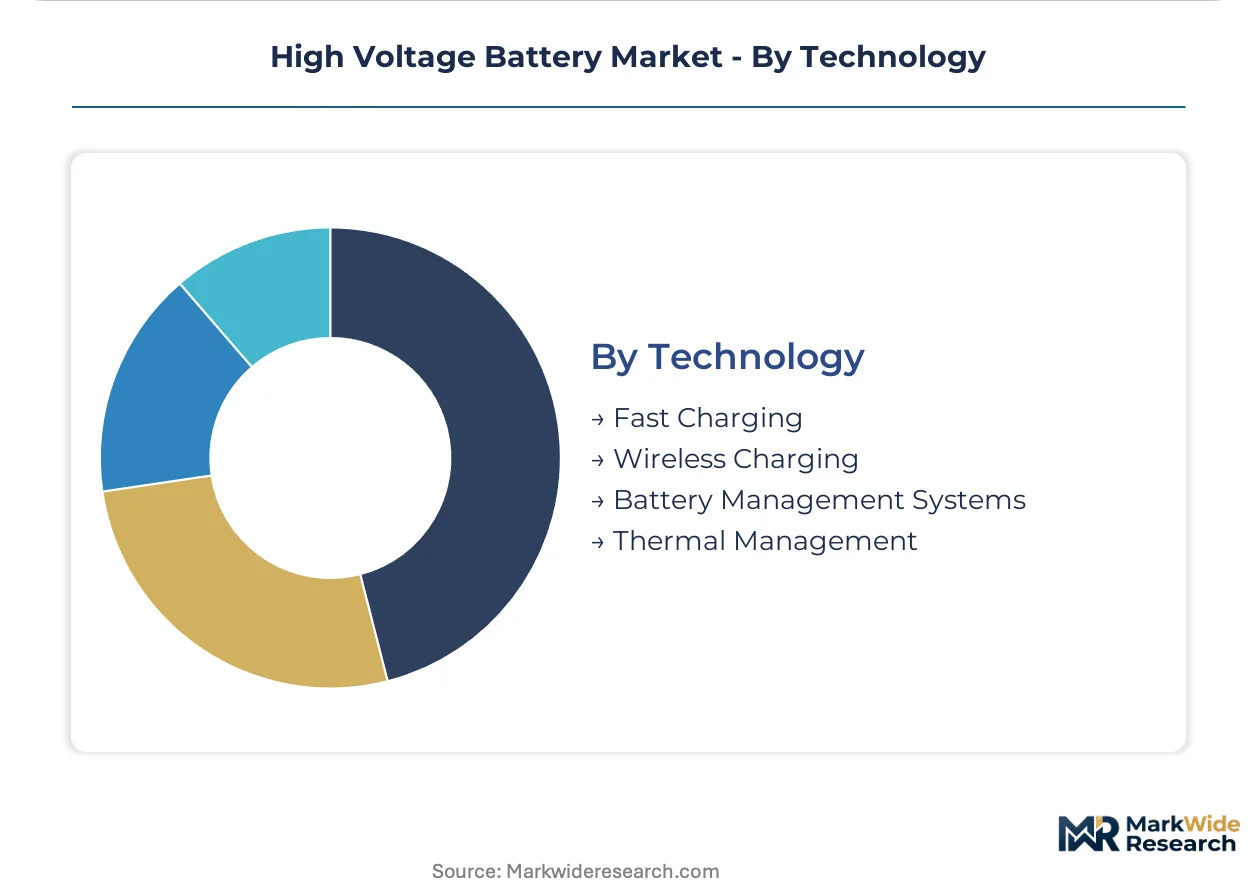
Technology:
Performance differentiation increasingly concentrates in software, thermal architecture, and charging infrastructure rather than cell chemistry alone.
- Battery Management Systems:Functional safety certification to ISO 26262 ASIL-D creates captive revenue streams through cell balancing algorithms, state-of-charge estimation, and thermal runaway detection. Tesla Energy locks service revenue internally through proprietary software stacks.
- Thermal Management:Liquid cooling plates, immersion dielectrics, and phase change materials determine fast charge capability and cycle life in high-C-rate applications. CATL sustains manufacturing scale through integrated thermal design in Ningde facilities.
- Fast Charging:350-kilowatt plus infrastructure compatibility requires silicon carbide power electronics and matched cell chemistries with reduced lithium plating susceptibility.
- Wireless Charging:Inductive and resonant coupling architectures address fleet automation and consumer convenience segments with alignment-tolerant power transfer.
Battery management systems commands margin concentration. Thermal management is expanding most quickly as 800-volt architectures proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility buyers in Texas and California show the lowest price elasticity, absorbing 800-volt system premiums for bankable offtake contracts. Fleet operators in India and Southeast Asia remain acutely price-sensitive, driving procurement toward lithium iron phosphate chemistries despite lower energy density.
United States
Merchant storage developers in Texas and California ISO markets favor vertically integrated suppliers with 20-year cycle life warranties. The Inflation Reduction Act's $35 per kWh domestic content credits are attracting cathode active material investments into North American chemical processing. Arizona and Nevada host greenfield dry-electrode facilities serving both automotive OEMs and grid-scale integrators.
China
Domestic OEMs and European energy storage integrators simultaneously source from Jiangsu and Fujian province cell-to-pack facilities. MIIT enforces GB standards for thermal propagation resistance that exclude uncertified cell suppliers from automotive qualification. Ningde anchors integrated cathode-anode production lines that sustain manufacturing scale for CATL and downstream pack assemblers.
Germany
Premium automotive OEMs specify 800-volt traction architectures requiring silicon carbide inverter matching and matched cell chemistries. The EU Battery Regulation mandates recycled content thresholds and digital passport traceability that reshape supply chain accountability for European-bound exports. Bavaria hosts dedicated production lines for high-voltage platforms as national fleet emissions regulations tighten.
South Korea
Korean equipment suppliers retrofit existing electrode coating lines while domestic development programs anchor premium automotive qualification timelines for solid-state formats. The country's national industrial regulator enforces functional safety certification aligned with ISO 26262 ASIL-D standards for battery management systems. Seoul-based conglomerates maintain dedicated lines for 800-volt architectures serving German and US automotive supply relationships.
Japan
Japanese development programs focus on ceramic electrolyte architectures for premium automotive applications awaiting yield breakthroughs in sulfide and oxide solid-state formats. METI coordinates national research consortia addressing manufacturing defect rates above 15% that delay commercial scale-up. Nagoya-area engineering clusters specialize in solid-state interface engineering and thermal bonding expertise for next-generation cell formats.
High Voltage Battery Market Key Industry Players
Integrated cell-pack-system suppliers and pure-play cell producers split the market along warranty capability and vertical scope lines. The vendor base concentrates around three strategic archetypes: conglomerate-backed energy divisions with captive cathode supply, independent cell specialists lacking in-house power conversion, and automotive-captive battery operations locking service revenue through proprietary software. Dominant competitive moves include backward integration into certified refining operations and strategic partnerships with silicon carbide inverter manufacturers.
Within the conglomerate-backed tier, CATL and LG Energy Solution exemplify scale-driven positions anchored in integrated production geographies. Tesla Energy occupies a distinct software-captive archetype, internalizing battery management system revenue through proprietary stacks rather than licensing. BYD Energy Storage represents the automotive-captive model, leveraging vehicle platform integration to secure stationary storage offtake.
| Leading Market Players |
|---|
| LG Energy Solution |
| Sungrow |
| CATL |
| EVE Energy |
| Pylontech |
| BYD Energy Storage |
| Siemens Battery Storage |
| Gotion High-tech |
| Tesla Energy |
| Others |
Cost & Logistics Intelligence
Ningde's integrated cathode-anode production lines concentrate manufacturing scale for CATL and downstream pack assemblers, compressing cost structures and amplifying pricing power for certified suppliers against uncertified competitors excluded by MIIT GB thermal propagation standards. This geographic clustering enables three-tier pricing stratification across premium automotive, standard energy storage, and economy industrial segments, with downstream buyers in Texas and California ISO markets absorbing 800-volt system premiums while fleet operators in India and Southeast Asia drive procurement toward lower-cost lithium iron phosphate chemistries.
Pricing Analysis
After-sales service revenue from diagnostic software, cell balancing, and thermal retrofitting drives lifetime value capture, with battery management system licensing creating captive revenue streams independent of cell supply relationships. Price differentiation rests on ISO 26262 ASIL-D functional safety certification and 20-year cycle life warranty capabilities, with premium tiers commanding substantial premiums over uncertified alternatives. Cost compression in nickel-rich NMC formulations is intensifying because cathode raw material swings above 30% quarterly are eroding margin predictability. Utility procurement departments in Texas and California show the lowest price sensitivity, absorbing system premiums for bankable offtake contracts, while fleet operators in India and Southeast Asia remain acutely price-sensitive.
Supply Chain Analysis
Export-control regimes limiting semiconductor and advanced manufacturing equipment flows are reshaping cathode active material investment patterns, with the US Inflation Reduction Act's domestic content credits attracting chemical processing capacity into North America. Supply concentration centers on China, South Korea, and Japan, with Jiangsu-Fujian production clusters and Korean equipment suppliers anchoring electrode coating and cell-to-pack assembly. The chain draws from nickel-cobalt cathode precursors, silicon carbide power electronics, and ceramic electrolyte materials, with single-source vulnerability in sulfide solid-state electrolyte processing creating structural risk. Distribution runs through vertically integrated cell-pack-system suppliers capable of warranting 20-year cycle life, displacing previous multi-vendor assembly models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating around utility procurement departments consolidating vendor relationships for multi-gigawhour tenders, fragmenting competitive positioning for pure-play cell producers lacking integrated power conversion or thermal management capabilities. This consolidation shifts margin capture toward suppliers with captive software stacks and certified thermal architectures.
For Market Incumbents: Build certification moats through ISO 26262 ASIL-D functional safety investment and integrated cathode production capacity in Ningde or Jiangsu. Defensive moves center on backward integration into certified refining operations to satisfy EU Battery Regulation recycled content mandates, and strategic partnerships with silicon carbide inverter manufacturers to lock 800-volt architecture supply relationships against emerging Korean and Chinese equipment suppliers.
For New Entrants and Emerging Players: Build out grid-scale energy storage tender capabilities outside automotive qualification cycles, targeting merchant storage developers in Texas and California ISO markets facing offtake bankability requirements. The most penetrable white space sits in sodium-ion chemistries for stationary applications prioritizing calendar life over power density, with go-to-market angles anchored on 20-year cycle life warranties and integrated power conversion systems.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated suppliers with in-house battery management software and thermal management capabilities over pure-play cell producers. Long-term viability across the projection horizon rests on capturing margin concentration in software licensing and functional safety certification rather than commodity cell production. The acquisition target archetype combines dry electrode coating expertise with solid-state interface engineering capabilities. The signal to watch is ceramic processing yield breakthroughs in sulfide and oxide formats falling below commercialization thresholds.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Refining | Secures certified supply chains for EU Battery Regulation recycled content compliance and digital passport traceability. |
| Dry Electrode Coating Capacity Buildout | Eliminates solvent recovery systems and reduces drying oven footprints by 70% versus legacy wet-process equipment. |
| Battery Management System Software Licensing | Captures ISO 26262 ASIL-D certified revenue streams independent of cell supply relationships and price cycles. |
| Silicon Carbide Inverter Partnership | Locks 800-volt architecture compatibility for premium automotive OEMs specifying high-voltage traction platforms. |
| Grid-Scale Storage System Integration | Addresses utility procurement consolidation around single-vendor warranties for 20-year cycle life bankability. |
Research Approach
The analysis maps lithium-ion, solid-state, nickel metal hydride, and lead-acid chemistry platforms, each validated through cell engineering directors, utility procurement officers, automotive platform engineers, and energy storage integrators. Primary interviews with these stakeholders combined with secondary validation from MIIT GB standard filings, EU Battery Regulation compliance databases, EIA utility storage project disclosures, and SEC cathode producer filings. Bottom-up cell production capacity estimates triangulated against top-down OEM procurement forecasts across the segmentation dimensions.
Assumptions held fixed include MIIT GB thermal propagation certification requirements, EU Battery Regulation digital passport mandates, and IRA domestic content credit structures, while nickel-cobalt price volatility, solid-state electrolyte manufacturing yields, and 800-volt platform adoption rates were varied across sensitivity bands. The analytical framework modeled chemistry platform, end-use specification, integration architecture, and regional regulatory cluster across the projection horizon. CAGRs were derived from installed capacity buildout trajectories and OEM platform electrification timelines, with cell-to-pack adoption rates and silicon-anode blending penetration serving as industry-specific forecast inputs.
Stress conditions across nickel-cobalt price swings, ceramic processing defect rates, and thermal propagation certification timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these assumptions and risk factors including regulatory divergence between Chinese, European, and North American certification regimes, commodity price volatility in cathode raw materials, and yield breakthroughs in solid-state formats that could accelerate chemistry transitions. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Coin Cell Lithium Batteries Market
Batteries
Asia-Pacific Rechargeable Battery Market
Batteries
Battery Plate Market
Batteries
India Rechargeable Battery Market
Batteries
Middle East Rechargeable Battery Market
Batteries
South and Central America Battery Market
Batteries
18650 And 21700 Battery Market
Batteries
Water-Based Zinc-Ion Battery Market
Batteries
East Asia Battery Market
Batteries
Japan Battery Market
Batteries
UAV Battery Pack Market
Batteries
Asia Pacific Electric Vehicle Battery Electrolyte Market
Batteries
Stretchable Battery Market
Batteries
Solid-State Battery Mechanical and Safety Test Equipment Market
Batteries
Battery Simulator Market
Batteries
Custom Battery Pack Market