
 Stretchable Battery Market | 2026-2036
Stretchable Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Stretchable Battery Market Analytics
Market Context
Multi-source procurement of stretchable cell materials is expanding as wearable OEMs reduce dependence on single polymer electrolyte suppliers. Samsung SDI leverages its display-sector expertise to dominate flexible substrate integration. LG Energy Solution anchors South Korea's stretchable battery ecosystem through dedicated solid-state research lines.
Technical Foundation and Segment Structure
Stretchable batteries are electrochemical energy storage devices engineered to maintain conductive pathways under mechanical deformation exceeding 20% strain, typically employing serpentine interconnects or intrinsically stretchable ionogel electrolytes to power conformal electronics. Thin-film batteries occupy the mature revenue tier due to established roll-to-roll manufacturing, while bio-inspired architectures represent the fastest-growing segment as researchers emulate cutaneous energy storage geometries. Among end users, medical devices command premium positioning because FDA Class III validation requirements create margin-protecting barriers, whereas IoT devices compete on unit cost at scale.
Regulatory Environment and Outlook
FDA clearance timelines govern medical device integration pathways for stretchable power sources in the United States, while REACH compliance in Europe restricts certain solvent-based electrolyte formulations and the EU Green Deal mandates recycled content thresholds for battery materials. South Korea's MIIT-aligned standards through KATS shape domestic testing protocols for deformable cells. Stakeholders must monitor how divergent electrochemical safety standards across jurisdictions affect cross-border product qualification timelines.
Market Dynamics
Wearable device OEMs are consolidating supplier relationships around polymer electrolyte vendors capable of certifying under divergent electrochemical safety regimes, compressing qualification timelines and reshaping procurement power dynamics.
Growth Catalysts
- EU Green Deal battery mandates:Recycled content thresholds for energy storage materials are accelerating domestic European R&D into solvent-free electrolyte formulations, creating captive demand for sustainable stretchable cell architectures.
- Medical device integration:FDA Class III validation pathways for implantable cardiac monitors are expanding addressable volume for biocompatible stretchable power sources with extended cycle life.
- Solid-state ionogel advances:Intrinsically stretchable electrolytes achieving 500%+ strain tolerance without conductivity degradation are unlocking conformal applications previously constrained by mechanical failure modes.
Market Restraints
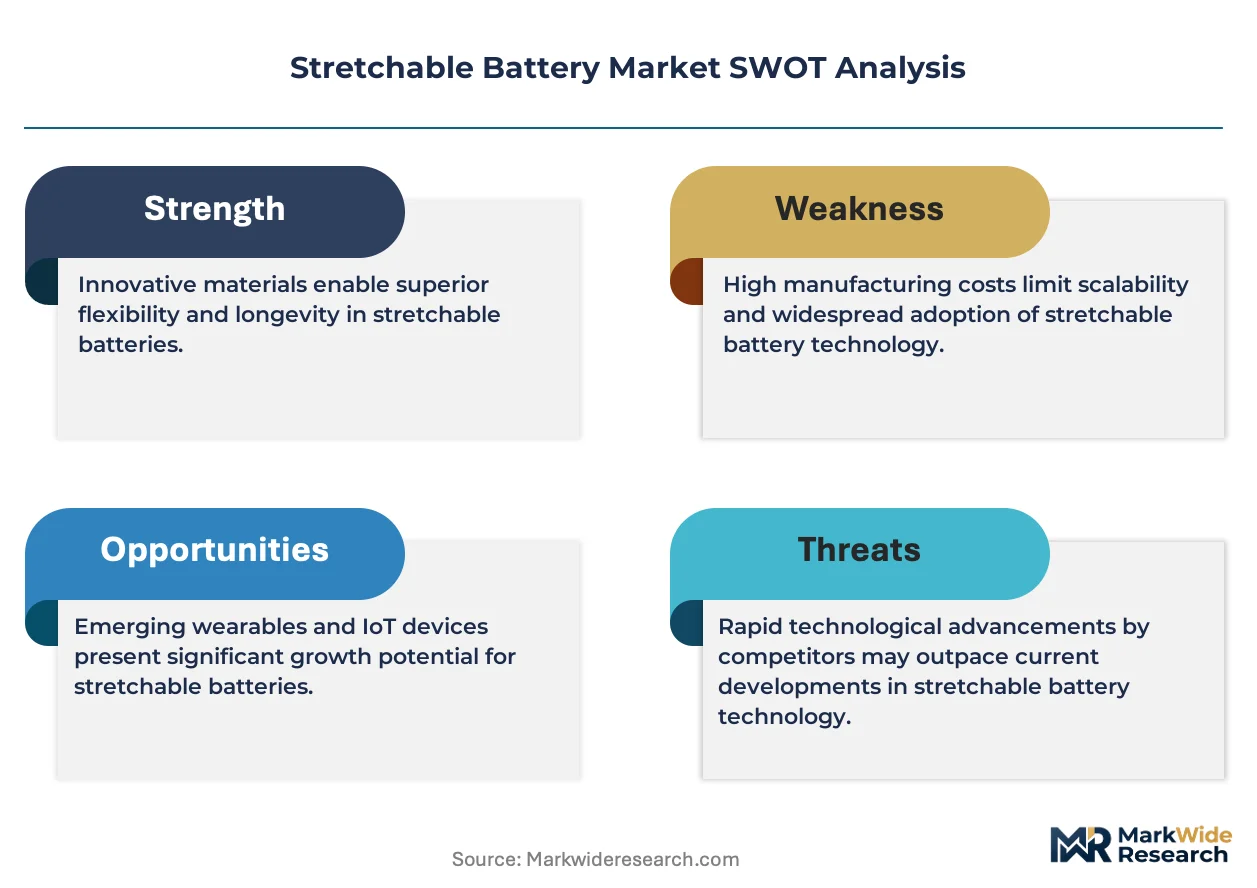
- Fluoropolymer substrate concentration:Roll-to-roll manufacturing capacity for stretchable encapsulants clusters in East Asian chemical conglomerates, exposing buyers to single-source risk during geopolitical trade friction.
- Silver nanowire cost volatility:Precious metal interconnects represent 35-45% of bill-of-materials for high-conductivity serpentine designs, amplifying margin pressure when commodity markets fluctuate.
- REACH solvent restrictions:ECHA classification of certain polar aprotic solvents as substances of very high concern is forcing reformulation of established gel electrolyte recipes, extending development cycles.
Strategic Opportunities
- India PLI scheme alignment:Domestic cell manufacturing incentives are attracting stretchable battery assembly investments targeting wearable exports to Middle Eastern healthcare systems.
- Soft robotics convergence:Integration of stretchable power with pneumatic artificial muscles is creating demand for distributed energy storage in industrial automation end-effectors.
- Direct-to-clinic distribution:Bypassing traditional medical device distributors for FDA-cleared stretchable patches is capturing margin previously allocated to channel intermediaries in North American wound care markets.
Industry Challenges
- Multiphysics simulation talent scarcity:Coupled electrochemical-mechanical modeling expertise required for predictive failure analysis remains concentrated in academic laboratories, constraining industrial design throughput.
- Cross-jurisdiction certification fragmentation:Divergent testing protocols between KATS in South Korea, MFDS alignment requirements, and FDA electrical safety standards force redundant validation spending for global product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stretchable Battery Market |
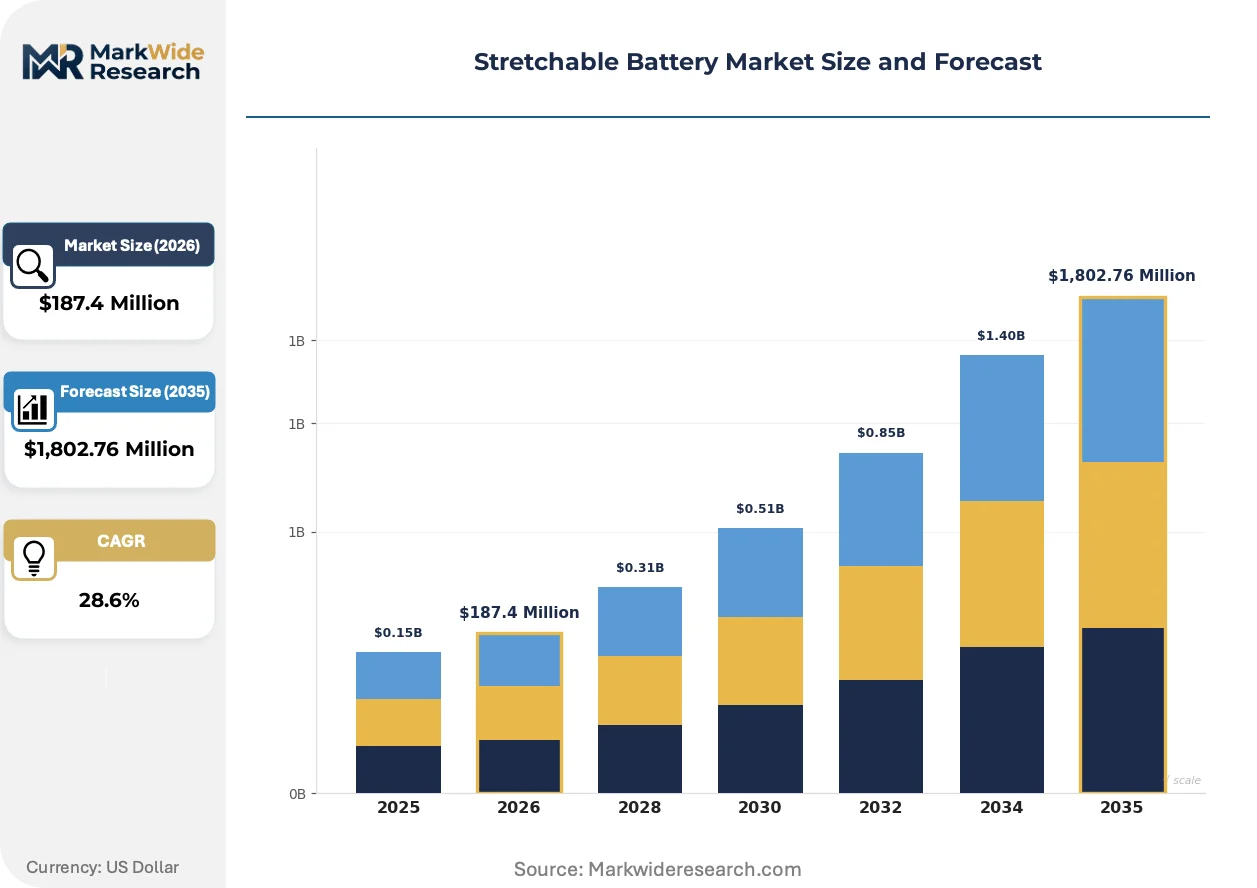
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,802.76 Million |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thin-film Batteries, Flexible Batteries, Bio-inspired Batteries, Solid-state Batteries End User: Wearable Devices, Medical Devices, Consumer Electronics, IoT Devices Technology: Nanotechnology, Organic Electronics, Printed Electronics, Lithium-ion Technology Application: Energy Harvesting, Smart Textiles, Flexible Electronics, Environmental Sensors |
| Companies Covered | Samsung SDI, LG Energy Solution, Panasonic Corporation, STMicroelectronics, Blue Spark Technologies, Enfucell Oy, Ultralife Corporation, BrightVolt, Cymbet Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stretchable Battery Market Evolving Landscape
Stretchable battery development is pivoting from materials-science demonstrations toward manufacturable platforms that satisfy electrochemical safety certification across multiple jurisdictions simultaneously.
Self-healing polymer networks with dynamic covalent bonds are integrating into stretchable cell architectures to recover conductive pathways after mechanical damage. Medical device manufacturers in Germany and Switzerland are piloting these materials for long-term implantable applications. The structural consequence is compressing warranty liability exposure and extending serviceable device lifecycles beyond current 3-5 year replacement cycles.
REACH compliance deadlines for solvent-based electrolyte restrictions are forcing European formulators toward aqueous and ionic liquid alternatives. Industrial consequence includes 18-24 month reformulation timelines and restaged toxicology dossiers. South Korean exporters to the EU are responding by accelerating KATS certification of water-based gel platforms to maintain market access.
Hospital procurement departments are consolidating stretchable power source vendors under outcome-based contracts tied to device uptime metrics rather than unit pricing. Group purchasing organizations in the United States are displacing traditional distributor relationships with direct manufacturer agreements. This pattern is most visible in cardiac monitoring and continuous glucose sensing verticals where total cost of ownership dominates capital allocation decisions.
Stretchable Battery Market Segmentation
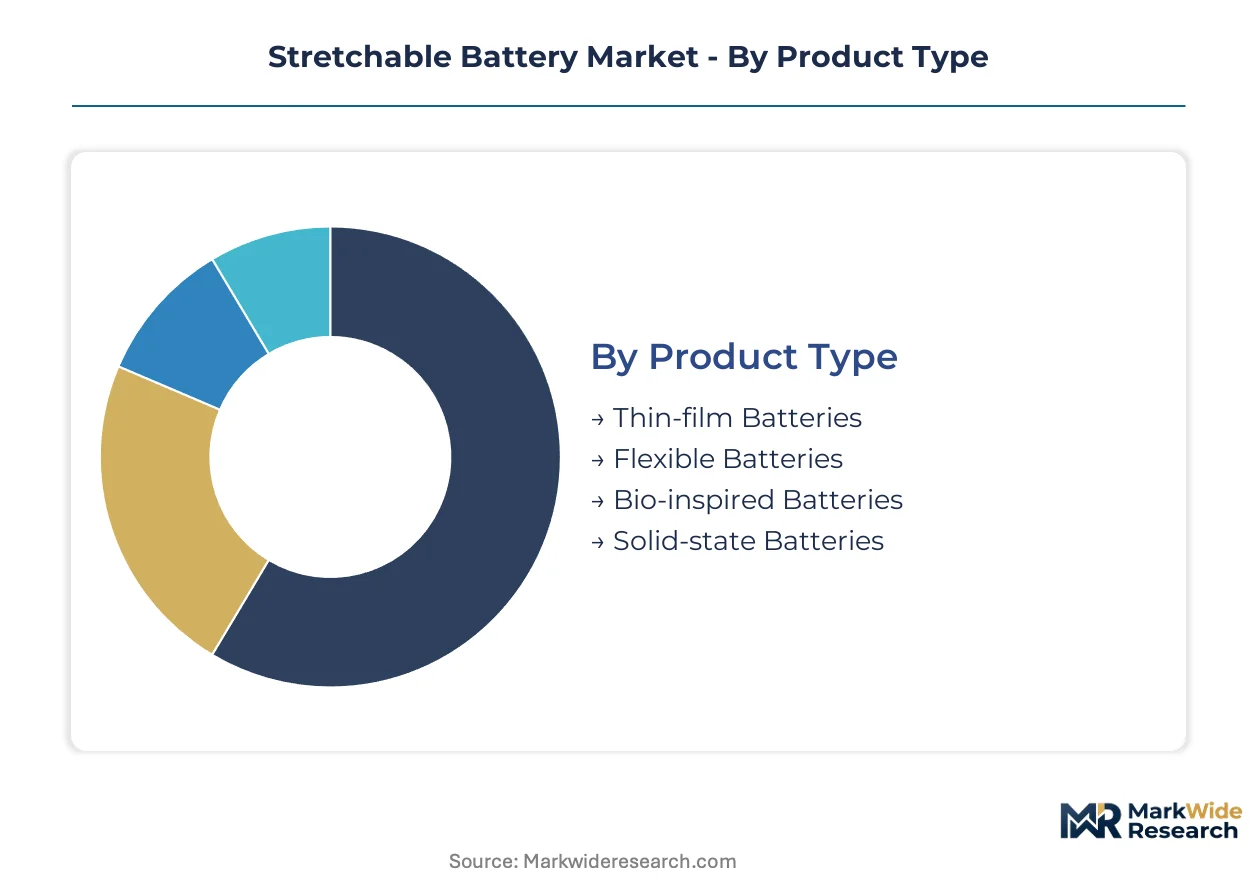
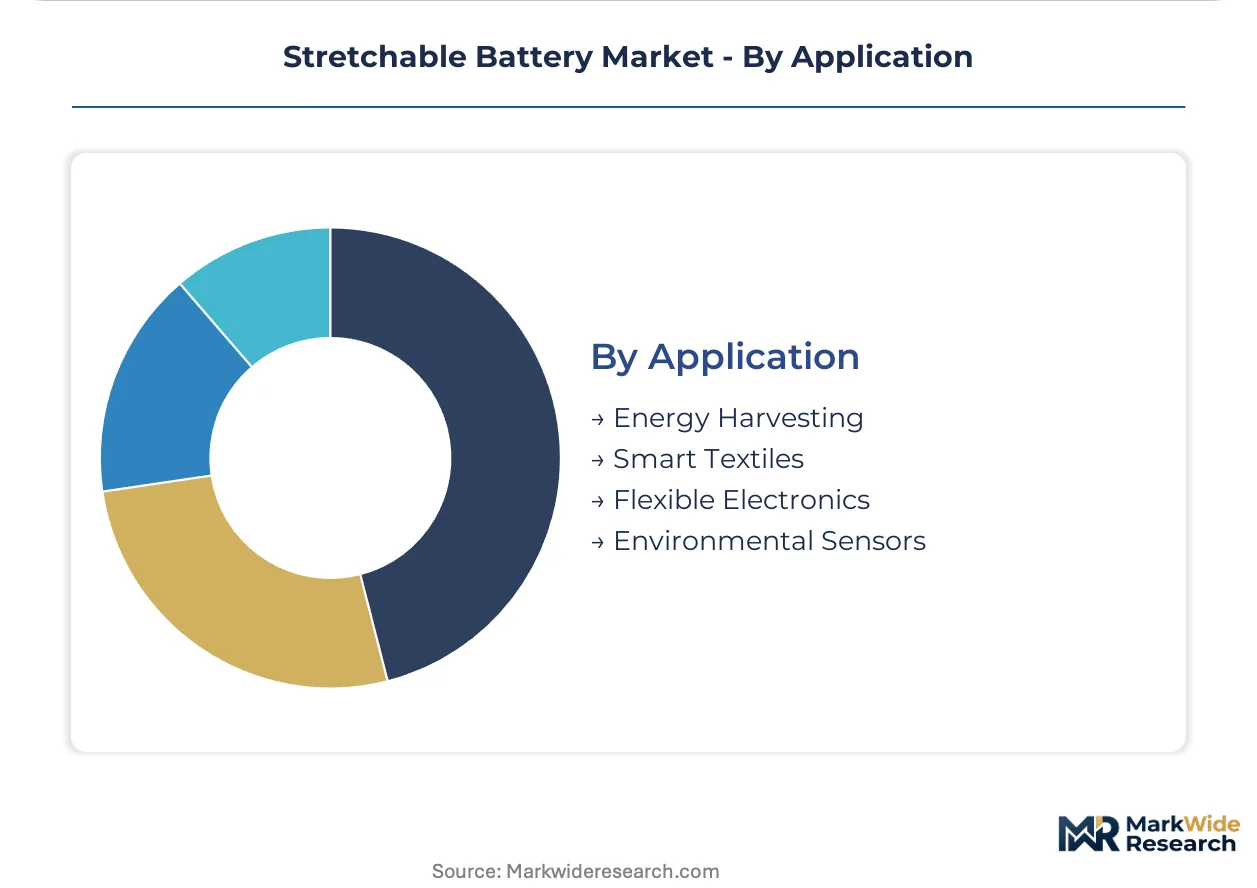
Stretchable battery procurement patterns diverge sharply between medical-grade validation requirements and consumer electronics cost optimization. OEMs configure supply chains around specific deformation tolerances, electrochemical safety certifications, and manufacturing scalability thresholds unique to each segment cluster.
Product Type:
Customization intensity spans from commodity roll-to-roll formats to architecturally complex bio-mimetic designs requiring co-development partnerships.
- Thin-film Batteries:Roll-to-roll vapor deposition onto polyimide substrates enables 50-micron form factors with established IEC 62133 safety certification pathways. Samsung SDI and LG Energy Solution anchor production clusters in South Korea, serving wearable OEMs demanding sub-2mm thickness for wrist-worn health monitors.
- Bio-inspired Batteries:Cutaneous-mimetic architectures with fractal interconnect geometries achieve 300%+ areal expansion while maintaining conductive pathways. German and Swiss medical device manufacturers pilot these formats for long-term implantable cardiac monitors where mechanical compliance with tissue deformation prevents fibrotic encapsulation.
- Flexible Batteries:Bending-tolerant designs with radius-of-curvature specifications below 10mm serve foldable smartphone and e-reader applications.
- Solid-state Batteries:Solvent-free ceramic-polymer composite electrolytes eliminate thermal runaway risks for aerospace and defense conformal power requirements.
Most installed capacity flows through thin-film architectures. Expansion is steepest in bio-inspired formats.
End User:
Margin structures stratify across FDA Class III validation barriers versus unit-cost competition at consumer electronics scale.
- Medical Devices:Implantable cardiac monitors and continuous glucose sensors demand biocompatible encapsulants with ISO 10993 cytotoxicity clearance and 10-year calendar life specifications. FDA PMA pathways create 18-36 month qualification timelines that protect pricing power for validated suppliers.
- IoT Devices:Distributed environmental sensors and asset trackers prioritize unit economics over mechanical resilience, accepting 20% strain tolerance in exchange for sub-dollar bill-of-materials targets.
- Wearable Devices:Smartwatch and fitness band manufacturers specify 500+ cycle life with sweat-resistant encapsulation.
- Consumer Electronics:Foldable display power requirements drive demand for bending-tolerant formats with rapid charge capability.
Revenue concentration sits with medical applications. Volume scaling accelerates fastest in IoT deployments.
Technology:
Intellectual property density varies from mature lithium-ion process knowledge to frontier organic semiconductor formulations.
- Nanotechnology:Silver nanowire percolation networks and carbon nanotube current collectors enable transparent conductor integration for stretchable display-battery laminates. South Korean R&D clusters dominate patent filings in mechanically robust nanowire ink formulations.
- Printed Electronics:Aerosol-jet and screen-printed electrode patterns reduce capital intensity versus vacuum deposition, attracting Indian PLI scheme beneficiaries targeting Middle Eastern healthcare export markets.
- Organic Electronics:Conjugated polymer redox active materials enable intrinsically stretchable electrodes without metallic interconnects.
- Lithium-ion Technology:Conventional intercalation chemistry adapted with compliant binders and wavy current collector geometries.
Patent thickets concentrate around nanomaterial interconnects. Manufacturing adoption is broadest in printed electronics.
Application:
Use-case thermal and mechanical loading profiles dictate electrolyte selection between aqueous gel and ionic liquid formulations.
- Smart Textiles:Garment-integrated power requires wash-cycle durability and skin-contact safety certification under REACH restricted substance protocols. European textile manufacturers specify water-based electrolytes to preempt ECHA SVHC classification risks.
- Environmental Sensors:Distributed agricultural and industrial monitoring nodes prioritize decade-scale calendar life with minimal maintenance access, favoring solid-state architectures with low self-discharge.
- Energy Harvesting:Thermoelectric and piezoelectric coupling demands matched impedance with micro-watt source output.
- Flexible Electronics:Display and logic power integration requires optical transparency and bending tolerance.
Deployment density is highest in smart textile pilots. Technical complexity is greatest in energy harvesting system integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's Gyeonggi-do corridor anchors stretchable battery manufacturing capacity through integrated display-electronics clusters. Domestic R&D spending from Samsung SDI and LG Energy Solution concentrates talent and patent filings in deformable cell architectures. Regulatory divergence across FDA, ECHA, and KATS jurisdictions fragments certification pathways for exporters.
United States
FDA Class III PMA pathways for implantable cardiac monitors drive biocompatibility validation demand in Massachusetts and Minnesota medical device clusters. The IRA domestic manufacturing incentives attract solid-state electrolyte pilot lines to Arizona and Texas. Boston-area research hospitals pilot self-healing polymer networks for long-term implantable applications.
Germany
REACH solvent restrictions force Baden-Württemberg chemical formulators toward aqueous gel electrolyte platforms. ECHA SVHC classifications disrupt established supply relationships for polar aprotic solvents. Stuttgart and Karlsruhe host Fraunhofer institutes coupling printed electronics expertise with medical-grade stretchable power development.
South Korea
KATS electrochemical safety standards align with MIIT protocols to streamline export certification for Seoul Capital Area manufacturers. Samsung SDI leverages display-sector vapor deposition expertise for polyimide substrate integration. Busan-Ulsan chemical complexes supply fluoropolymer encapsulants to domestic stretchable cell assemblers.
Switzerland
Swissmedic device regulations and ISO 10993 cytotoxicity requirements protect margin structures for Zurich and Basel implantable power specialists. Private-public research partnerships in the Swiss Nano Institute advance fractal interconnect geometries for cardiac tissue compliance. Roche and Novartis procurement standards shape supplier qualification timelines.
India
PLI scheme cell manufacturing incentives attract stretchable battery assembly investments to Gujarat and Tamil Nadu for Middle Eastern healthcare exports. CDSCO medical device rules harmonize with ISO 13485 to reduce redundant validation for export-oriented producers. Bangalore printed electronics startups target aerosol-jet electrode patterning for cost-sensitive IoT deployments.
Stretchable Battery Market Competitive Landscape
Global majors compete with regional champions across substrate integration and electrolyte formulation capabilities. The vendor base stratifies into three tiers: integrated conglomerates with display-sector crossover expertise, dedicated solid-state research houses, and printed electronics specialists serving cost-optimized segments. Consolidation pressure concentrates around polymer electrolyte suppliers capable of multi-jurisdiction certification. Dominant competitive moves include backward integration into ionogel material production and strategic partnerships with wearable OEMs to compress qualification timelines.
Within the integrated conglomerate tier, Samsung SDI and LG Energy Solution occupy positions shaped by display manufacturing heritage and captive R&D infrastructure. Panasonic Corporation exemplifies the diversified electronics archetype with cross-divisional materials science capabilities. STMicroelectronics sits within the semiconductor-integrated segment, leveraging microfabrication expertise for serpentine interconnect geometries. Blue Spark Technologies represents the dedicated flexible power specialist archetype with focused thin-film battery development. Enfucell Oy anchors the Nordic printed electronics cluster with disposable battery platforms.
| Leading Market Players |
|---|
| Samsung SDI |
| LG Energy Solution |
| Panasonic Corporation |
| STMicroelectronics |
| Blue Spark Technologies |
| Enfucell Oy |
| Ultralife Corporation |
| BrightVolt |
| Cymbet Corporation |
| Others |
Value Network & Pricing Analysis
Roll-to-roll manufacturing migration from batch vapor deposition compresses unit economics while concentrating polymer electrolyte procurement power among East Asian chemical conglomerates. Samsung SDI and LG Energy Solution leverage captive substrate integration to extract margin premiums from wearable OEMs facing FDA and REACH compliance timelines.
Pricing Analysis
Silver nanowire and fluoropolymer substrate costs pass through directly to tiered pricing structures separating medical-grade from consumer electronics volumes. Price differentiation rests on FDA Class III certification status and ISO 10993 biocompatibility clearance, with medical device buyers absorbing premiums for validated supply chains. Cost compression in IoT-facing tiers intensifies as Indian PLI scheme beneficiaries enter printed electronics assembly. Hospital procurement committees exhibit lowest price sensitivity due to outcome-based contracting tied to device uptime metrics.
Supply Chain Analysis
Air freight premiums for solvent-free electrolyte formulations from South Korea to European REACH-compliant markets amplify landed costs for German and Swiss medical device manufacturers. Fluoropolymer encapsulant production draws from Busan-Ulsan chemical complexes, while silver nanowire inks source from domestic South Korean nanomaterial specialists. Single-source vulnerability concentrates in stretchable substrate roll-to-roll capacity. Distribution runs through direct manufacturer agreements with hospital group purchasing organizations displacing traditional medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The stretchable battery market compounds steadily as wearable OEM procurement consolidates around multi-jurisdiction certification capabilities, embedding recurring revenue streams for validated suppliers.
For Market Incumbents: Cement polymer electrolyte backward integration to secure margin against precious metal interconnect volatility and REACH solvent reformulation cycles. Expand KATS-certified water-based gel production lines to defend South Korean export positioning into EU Green Deal markets. Prioritize direct-to-clinic distribution partnerships with North American hospital systems to capture distributor margin displacement. For New Entrants and Emerging Players: Solid-state ionogel platforms achieving 500%+ strain tolerance offer entry wedges into soft robotics and industrial automation end-effector applications underserved by incumbent medical-device-focused suppliers. Target Indian PLI scheme assembly incentives for cost-optimized IoT sensor exports to Middle Eastern healthcare systems. Lead with aerosol-jet printed electrode patterning to bypass capital-intensive vapor deposition barriers. For Investors and Strategic Acquirers: Valuations sit cheapest among printed electronics specialists with CDSCO-ISO 13485 dual certification pathways and established Middle Eastern healthcare export relationships. Five-to-ten year viability favors acquisition targets with aqueous electrolyte formulation capabilities aligned to ECHA SVHC restriction timelines. Monitor KATS-MIIT harmonization progress as signal for South Korean export volume inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ionogel Production | Samsung SDI and LG Energy Solution secure captive electrolyte supply against REACH reformulation cycles. |
| KATS Certification of Water-Based Gel Platforms | South Korean exporters maintain EU market access under ECHA SVHC classification deadlines. |
| Direct-to-Clinic Distribution Partnerships | Manufacturers capture margin from displaced medical device distributors in North American wound care markets. |
| Printed Electronics Assembly Investment | Indian PLI scheme beneficiaries target cost-sensitive IoT deployments for Middle Eastern healthcare exports. |
| Self-Healing Polymer Network Integration | German and Swiss medical device manufacturers extend implantable device lifecycles beyond current replacement cycles. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with polymer electrolyte formulators, wearable OEM procurement directors, FDA regulatory consultants, and hospital GPO contract managers with secondary validation against KATS certification databases, ECHA SVHC substance listings, and SEC filings from integrated battery manufacturers. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Segment-weighting approaches distributed value and volume across product type, end user, technology, and application dimensions, with medical device and IoT deployment patterns receiving distinct elasticity parameters. CAGRs derived from fitted growth curves incorporating EU Green Deal recycled content mandate timelines, FDA PMA pathway duration benchmarks, and solid-state ionogel strain tolerance improvement trajectories. Regional forecasts integrated MIIT-aligned KATS standard adoption rates and PLI scheme disbursement schedules.
The model holds under stable regulatory harmonization trajectories; deviation in REACH enforcement intensity or KATS-MFDS alignment delays would shift South Korean export volume assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Rear Rack Battery Market
Batteries
Industrial Backup Battery Market
Batteries
Italy SLI Battery Market
Batteries
India Electric Vehicle Battery Electrolyte Market
Batteries
Sodium-Ion Battery Electrolyte Market
Batteries
Forklift Battery Market
Batteries
Myanmar Battery Market
Batteries
Portable Battery Pack Market
Batteries
Disposable Batteries Market
Batteries
Asia-Pacific Rechargeable Battery Market
Batteries
USA Forklift Battery Market
Batteries
48 Volt Battery System Market
Batteries
Advanced Batteries Market
Batteries
United Kingdom Electric Vehicle Battery Electrolyte Market
Batteries
South and Central America Battery Market
Batteries
Portable Battery Powered Products Market