
 Middle East Rechargeable Battery Market | 2026-2036
Middle East Rechargeable Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Rechargeable Battery Market Insights
Saudi gigafactory development is broadening regional cell manufacturing capacity. CATL leverages its lithium iron phosphate expertise to anchor supply agreements with Middle Eastern energy developers. Panasonic Corporation sustains its technology leadership through advanced cylindrical cell architectures suited for desert climate applications. BYD Company Ltd. competes aggressively on integrated battery-electric vehicle and stationary storage platforms across Gulf markets.
Rechargeable batteries in the Middle East context are electrochemical energy storage devices engineered with nickel-cobalt-manganese or lithium iron phosphate cathode formulations, designed to operate across ambient temperature ranges exceeding 50 degrees Celsius while delivering cycle lives of 3,000 to 8,000 charge-discharge events. Their primary purpose centers on buffering intermittent renewable generation, powering electric mobility fleets, and providing uninterruptible power for industrial and medical infrastructure. Lithium-ion chemistry dominates current procurement volumes due to its superior energy density and declining cost curve, while sodium-ion variants represent an emerging structural category positioned for grid-scale deployments where weight constraints are minimal. Among end user segments, renewable energy applications exhibit the steepest demand trajectory, driven by utility-scale solar pairing mandates in the UAE and Saudi Arabia, whereas consumer electronics maintains mature, replacement-driven consumption patterns with compressed margin pools.
Saudi Arabia's Saudi Standards, Metrology and Quality Organization and the UAE's Emirates Authority for Standardization and Metrology enforce thermal runaway testing protocols and import certification requirements that filter market access to technically qualified suppliers. The Gulf Cooperation Council's harmonized technical regulation for secondary cells and batteries creates a unified compliance pathway across Bahrain, Kuwait, Oman, Qatar, Saudi Arabia, and the UAE, reducing fragmentation but raising barriers for uncertified entrants. Stakeholders must monitor evolving domestic content requirements and local assembly incentives that could restructure competitive positioning between imported cells and regionally manufactured packs.
Market Dynamics
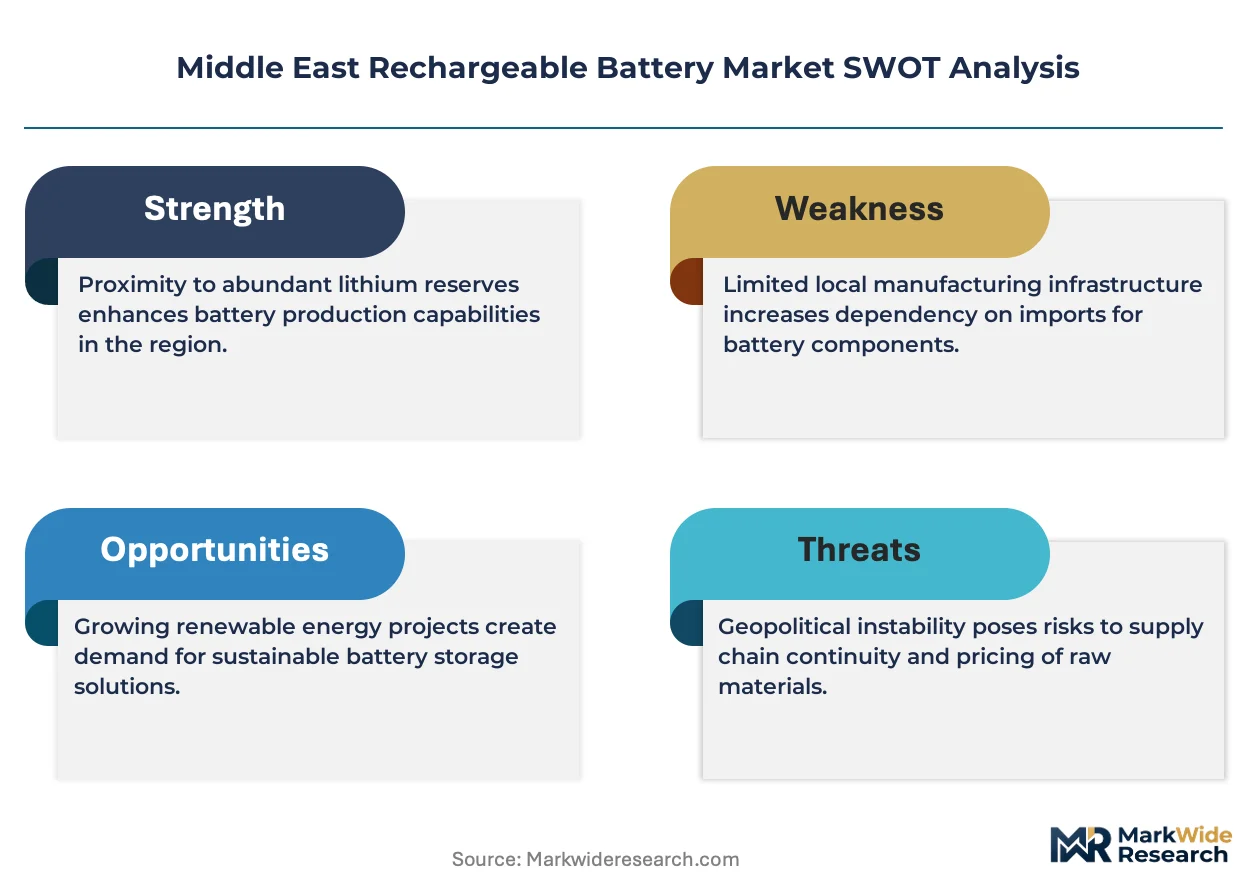
The Saudi Standards, Metrology and Quality Organization's thermal runaway testing mandates and the UAE's grid modernization directives are forcing suppliers to reengineer cell architectures for ambient temperatures exceeding 50 degrees Celsius, compressing margins for uncertified entrants while advantaging technically qualified manufacturers.
Growth Catalysts
- Utility-scale solar pairing mandates:Saudi Arabia and the UAE now require battery co-location with new renewable installations, creating guaranteed procurement pipelines for lithium iron phosphate systems.
- Gulf Cooperation Council harmonized technical regulation:Unified certification across six member states reduces compliance fragmentation and accelerates cross-border deployment for qualified suppliers.
- Electric mobility fleet electrification:Riyadh and Dubai's public transport authorities are procuring integrated battery-electric bus platforms, pulling demand for high-cycle-life cell chemistries.
Market Restraints
- Lithium carbonate price volatility:Cathode material cost swings from South American and Australian concentrate suppliers compress pack margins and deter long-term procurement commitments.
- Cell manufacturing concentration in East Asia:Dependence on imported cylindrical and prismatic cells from concentrated overseas suppliers exposes Gulf developers to shipping disruptions and currency risk.
- Sodium-ion energy density limitations:Emerging chemistry variants struggle to match lithium-ion volumetric performance for mobility applications, constraining their addressable market to stationary grid buffers.
Strategic Opportunities
- Oman and Kuwait underpenetration:These Gulf Cooperation Council members lag Saudi Arabia and the UAE in storage deployment, offering first-mover advantages for suppliers with established regional certification.
- Integrated solar-plus-storage EPC convergence:Engineering-procurement-construction contractors are bundling photovoltaic and battery assets, creating channel control points for vertically capable suppliers.
- Saudi domestic content incentives:The Kingdom's local assembly requirements and gigafactory development subsidies are restructuring competitive positioning toward regionally manufactured packs.
Industry Challenges
- Thermal management engineering talent scarcity:Cell and pack design for desert climate operation requires specialized electrochemical and materials expertise that Gulf labor markets currently undersupply.
- Extended Emirates Authority for Standardization and Metrology certification timelines:Import approval processes for new cell formulations create 6-12 month launch delays, compressing product refresh cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Rechargeable Battery Market |
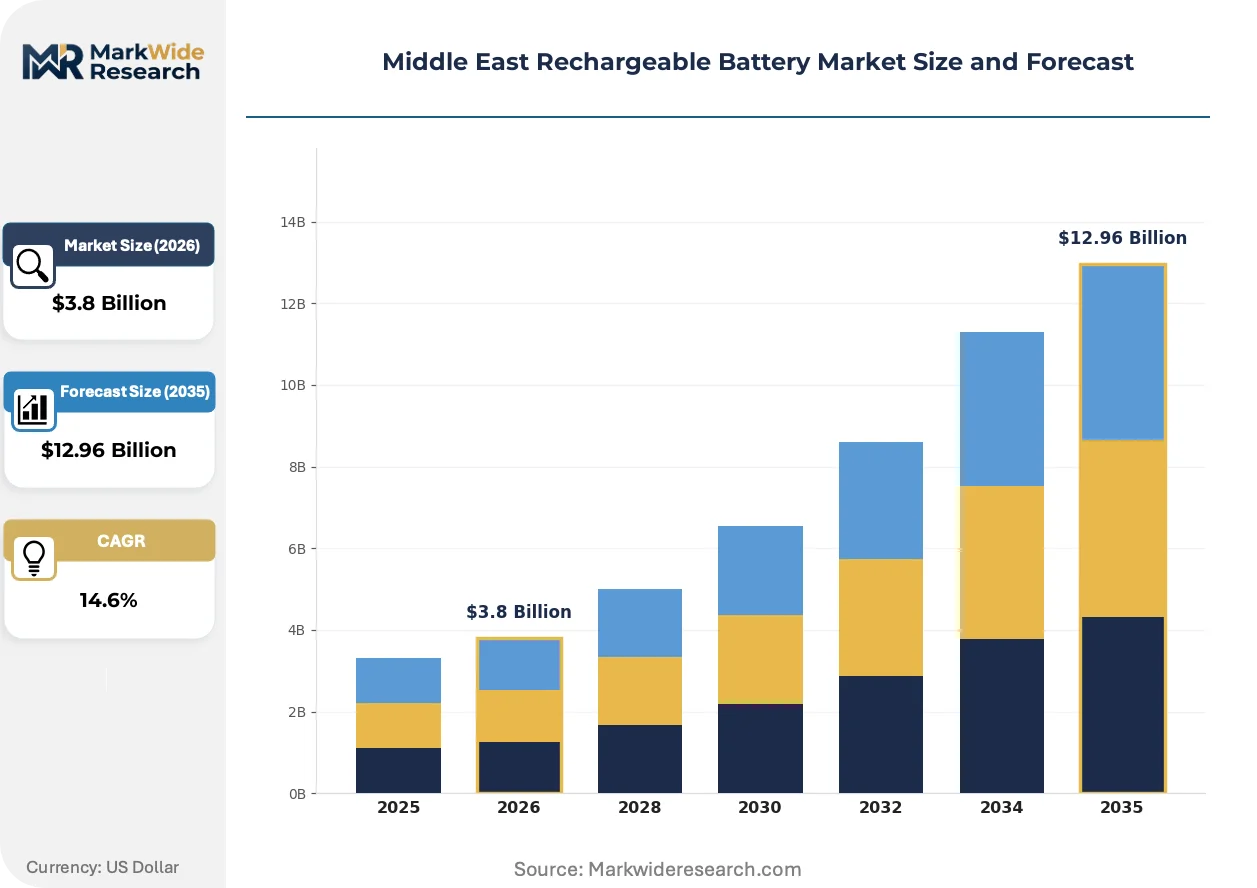
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Nickel-Metal Hydride, Lead Acid, Sodium-ion End User: Consumer Electronics, Automotive, Renewable Energy, Industrial Devices Charging Technology: Fast Charging, Wireless Charging, Solar Charging, Standard Charging Application: Power Tools, Electric Vehicles, Energy Storage Systems, Medical Devices |
| Companies Covered | Panasonic Corporation, Exide Industries Ltd., Middle East Battery Company (MEBCO), Tesla Inc., EnerSys, BYD Company Ltd., CATL (Contemporary Amperex Technology Co., Limited), LG Energy Solution, Samsung SDI, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Rechargeable Battery Market Trends and Innovations
Desert climate engineering requirements and utility-scale procurement consolidation are compressing product differentiation toward thermal resilience and bankability metrics rather than energy density alone.
Lithium iron phosphate chemistry is consolidating its position as the dominant cathode formulation for Middle East stationary storage deployments. Saudi and Emirati utility-scale developers specify this chemistry for its superior thermal stability and extended cycle life under ambient temperatures exceeding 50 degrees Celsius. The technology is consolidating procurement decisions around safety certification and warranty terms rather than volumetric energy density.
Saudi Standards, Metrology and Quality Organization thermal runaway testing protocols are tightening import filters for uncertified cell suppliers. The regulation mandates propagation resistance verification and abuse tolerance documentation that many overseas manufacturers cannot satisfy. Pack assemblers serving Saudi utility projects are responding by pre-qualifying fewer cell sources and deepening technical partnerships with certified chemistry providers.
Long-term power purchase agreements with storage co-location clauses are displacing merchant battery merchant deployments across Gulf Cooperation Council markets. Independent power producers now structure 20-25 year contracts that bundle solar generation with guaranteed storage dispatch, shifting developer risk profiles and financing structures. This pattern is most visible in Abu Dhabi and Riyadh procurement corridors where sovereign wealth-backed energy entities anchor offtake commitments.
Middle East Rechargeable Battery Market Segmentation
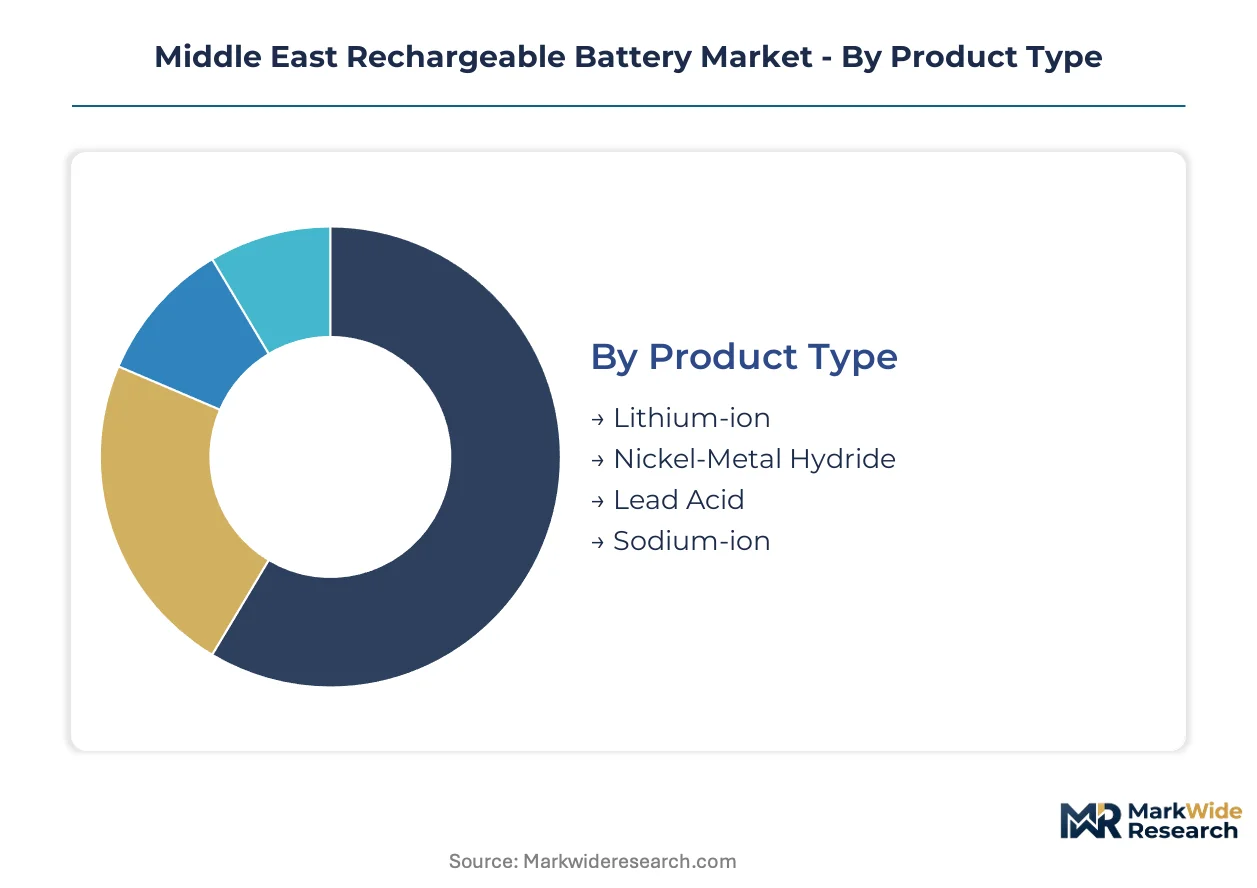
Segmentation in the Middle East rechargeable battery market reveals how certification requirements, thermal resilience specifications, and procurement channel structures vary sharply across chemistry types and end-use applications. Understanding these divides enables suppliers to prioritize qualification investments and align product portfolios with the fastest-expanding demand corridors.
Product Type:
Saudi Standards, Metrology and Quality Organization thermal runaway testing and UAE Emirates Authority for Standardization and Metrology import certification create divergent compliance burdens across chemistries, with lithium iron phosphate systems facing streamlined pathways while sodium-ion entrants encounter extended validation timelines.
- Lithium-ion:Dominant electrochemical architecture utilizing nickel-cobalt-manganese or lithium iron phosphate cathodes, engineered for 3,000-8,000 cycle lives under ambient temperatures exceeding 50 degrees Celsius. Procurement concentrates in Saudi utility-scale solar-plus-storage mandates and UAE grid modernization programs where thermal stability certification accelerates deployment. Leading the category by volume: Lithium-ion. Growing fastest: Lithium iron phosphate variants specified for stationary storage.
- Sodium-ion:Emerging chemistry employing abundant sodium-based intercalation compounds, positioned for grid-scale buffers where energy density constraints are acceptable. Abu Dhabi and Riyadh procurement corridors are piloting deployments for non-mobile applications, though Emirates Authority for Standardization and Metrology certification timelines lag established lithium pathways by 6-12 months.
- Nickel-Metal Hydride:Mature chemistry retaining niche presence in hybrid electric vehicle auxiliary systems and industrial backup power where proven supply chains outweigh energy density limitations.
- Lead Acid:Legacy technology constrained to price-sensitive uninterruptible power supply and starter battery applications, losing procurement share to lithium-ion in all premium segments.
Margin compression concentrates in lead acid replacement cycles while lithium iron phosphate commands premium positioning through warranty terms and bankability metrics.
End User:
Cost tier stratification separates consumer replacement markets with compressed margins from utility-scale procurement pipelines anchored by sovereign wealth-backed offtake guarantees.
- Renewable Energy:Utility-scale solar pairing mandates in Saudi Arabia and the UAE create guaranteed procurement volumes for lithium iron phosphate systems with 20-25 year power purchase agreement structures. Saudi gigafactory development and domestic content incentives are restructuring supplier qualification toward regionally assembled packs.
- Automotive:Electric mobility fleet electrification across Riyadh and Dubai public transport authorities pulls demand for high-cycle-life cell chemistries with integrated battery-electric vehicle platforms. Procurement concentrates on bus and commercial vehicle segments where total cost of ownership calculations favor extended warranty coverage.
- Consumer Electronics:Mature replacement-driven consumption patterns with saturated smartphone and laptop penetration, offering limited growth trajectory and margin compression from commoditized supply chains.
- Industrial Devices:Uninterruptible power supply and medical infrastructure applications requiring thermal resilience certification, with procurement filtering toward suppliers with established Gulf Cooperation Council technical regulation compliance.
Procurement volume leaders: Renewable energy and automotive segments. Steepest expansion trajectory: Renewable energy co-location mandates.
Charging Technology:
Application context dictates charging infrastructure investment priorities, with fast charging networks concentrating in urban mobility corridors while solar charging integrates with desert climate generation assets.
- Fast Charging:High-power DC infrastructure for electric vehicle fleet operations, with Dubai and Riyadh transit authorities specifying 350kW+ capability for commercial bus depots. Thermal management engineering requirements for desert climate operation create capability scarcity premiums.
- Solar Charging:Direct photovoltaic-to-battery coupling mandated in Saudi and Emirati utility-scale procurement, with integrated solar-plus-storage EPC convergence creating channel control points for vertically capable suppliers.
- Wireless Charging:Emerging inductive systems for premium consumer electronics and specialized industrial automation, limited by efficiency losses in high-temperature ambient conditions.
- Standard Charging:AC residential and commercial infrastructure, dominant in installed base but losing procurement share to fast charging in mobility segments.
Deployment scale ranking: Standard charging maintains widest installed base. Infrastructure investment acceleration: Fast charging networks.
Application:
Customer type differentiation separates merchant battery developers from long-term contracted asset owners, with power purchase agreement structures reshaping financing and supplier selection criteria.
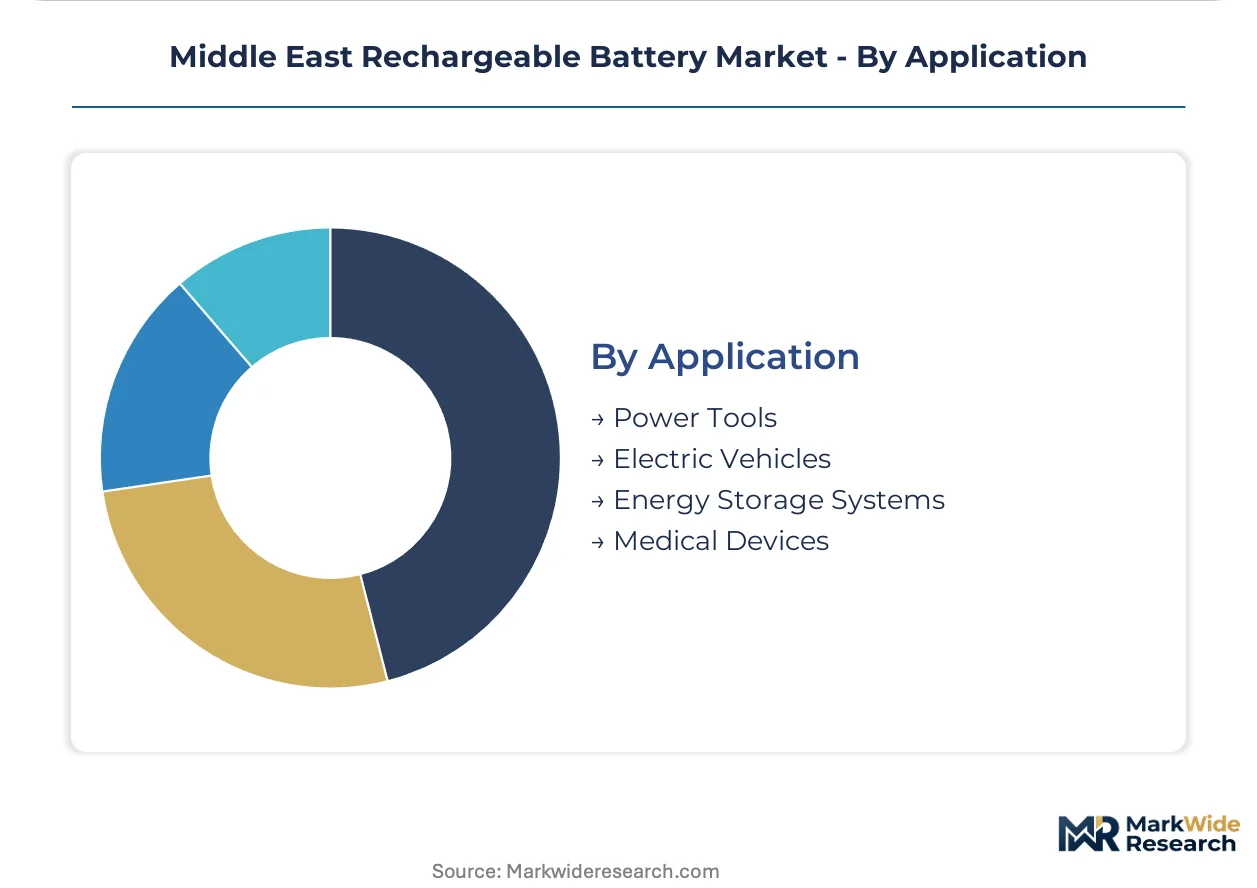
- Energy Storage Systems:Grid-scale and behind-the-meter installations buffering intermittent renewable generation, with Saudi and UAE mandates requiring battery co-location. Procurement decisions center on safety certification, warranty terms, and bankability metrics rather than volumetric energy density alone.
- Electric Vehicles:Battery-electric bus platforms and commercial fleets procured through Riyadh and Dubai public transport authorities, pulling integrated cell and pack supply agreements from certified manufacturers.
- Power Tools:Professional and consumer cordless equipment with established lithium-ion penetration, offering replacement-cycle stability but limited expansion trajectory.
- Medical Devices:Critical uninterruptible power applications requiring thermal runaway propagation resistance and abuse tolerance documentation under Saudi Standards, Metrology and Quality Organization protocols.
Revenue concentration: Energy storage systems anchor procurement volume. Fastest-climbing segment: Electric vehicle fleet electrification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium carbonate feedstock from Chilean and Australian concentrate suppliers anchors the Middle East rechargeable battery value chain, with Gulf Cooperation Council states converting imported cathode materials into utility-scale storage systems and electric mobility platforms.
Saudi Arabia
Solar-plus-storage procurement mandates and gigafactory development are accelerating domestic cell assembly capacity. The Saudi Standards, Metrology and Quality Organization enforces thermal runaway testing protocols that filter market access to qualified suppliers. Riyadh anchors deployment concentration as sovereign wealth-backed developers execute 20-25 year power purchase agreements bundling generation with guaranteed storage dispatch.
United Arab Emirates
Dual carbon goals and grid modernization directives are reshaping product certification requirements for battery imports. The Emirates Authority for Standardization and Metrology mandates propagation resistance verification and abuse tolerance documentation. Abu Dhabi concentrates procurement activity where independent power producers structure long-term contracted asset ownership displacing merchant battery deployments.
Qatar
Industrial diversification beyond hydrocarbon exports is pulling investment into renewable energy infrastructure and backup power systems. The country's national standards body aligns with Gulf Cooperation Council harmonized technical regulation for secondary cells. Doha represents an emerging procurement corridor where thermal resilience specifications for medical and industrial uninterruptible power applications filter supplier selection.
Oman
Underpenetration relative to Saudi Arabia and the UAE creates first-mover advantages for suppliers with established regional certification. Domestic content requirements remain less stringent than neighboring markets, lowering barriers for imported pack assembly. Muscat and surrounding industrial zones are piloting grid-scale sodium-ion deployments where energy density constraints are acceptable for stationary buffers.
Middle East Rechargeable Battery Market Competitive Landscape
Global majors compete with regional champions across certification pathways and thermal engineering capabilities. The supplier base stratifies into three tiers: East Asian cell manufacturers with established Gulf Cooperation Council compliance, European and American system integrators leveraging warranty terms, and emerging regional pack assemblers capturing domestic content incentives. Strategic moves concentrate on pre-qualifying fewer cell sources under tightening Saudi and Emirati protocols, and deepening technical partnerships with certified chemistry providers to compress 6-12 month import approval timelines.
Within the East Asian manufacturing tier, CATL and BYD Company Ltd. exemplify scale-driven positions anchored by lithium iron phosphate expertise and integrated platform capabilities. Panasonic Corporation occupies a technology leadership archetype through advanced cylindrical cell architectures. These three companies represent the dominant competitive anchors as Gulf utility-scale developers consolidate procurement decisions around safety certification and bankability metrics rather than volumetric energy density alone.
| Leading Market Players |
|---|
| Panasonic Corporation |
| Exide Industries Ltd. |
| Middle East Battery Company (MEBCO) |
| Tesla Inc. |
| EnerSys |
| BYD Company Ltd. |
| CATL (Contemporary Amperex Technology Co., Limited) |
| LG Energy Solution |
| Samsung SDI |
| Others |
Pricing and Supply Chain Analysis
Thermal management engineering talent scarcity in South Korea and Japan feeds directly into pricing-tier spreads across the Middle East rechargeable battery market, with certified pack assemblers commanding substantial premiums over commodity importers unable to satisfy Saudi Standards, Metrology and Quality Organization protocols.
Pricing Analysis
Warranty and service bundling separates premium-tier suppliers from unbundled commodity traders, with extended cycle-life guarantees and propagation resistance documentation now standard in Saudi utility procurement but optional for Kuwaiti industrial buyers. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales thermal engineering support. Cost compression in economy tiers intensifies because East Asian cell manufacturers compete on volume for uninterruptified power supply replacement cycles. Consumer electronics buyers exhibit highest price sensitivity while sovereign wealth-backed renewable developers prioritize bankability metrics over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Saudi and Emirati utility-scale developers, while distributor networks serve fragmented industrial and medical device segments. Cathode active material production concentrates in China, South Korea, and Japan, with lithium carbonate feedstock drawing from Chilean and Australian concentrate suppliers. Cell manufacturing rests on nickel-cobalt-manganese precursor availability and specialized separator membrane supply. Single-source vulnerability around East Asian cylindrical cell output exposes Gulf developers to shipping disruptions. Distribution runs through certified pack assemblers in Riyadh and Dubai free zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermal runaway testing capacity bottlenecks at Saudi Standards, Metrology and Quality Organization laboratories prop pricing for pre-certified suppliers, creating a supply-constrained market structure favoring technical qualification over scale.
For Market Incumbents: Anticipate sodium-ion chemistry encroachment on stationary grid buffers by deepening lithium iron phosphate cost advantages through backward integration into cathode precursor production. Pre-empt domestic content requirements by accelerating Riyadh gigafactory qualification timelines ahead of competitor pack assembly investments.
For New Entrants and Emerging Players: Omani utility developers represent the most penetrable buyer archetype given underdeveloped local certification infrastructure and less stringent domestic content thresholds. Target sodium-ion pilot deployments in Muscat industrial zones where energy density constraints are acceptable. Pursue integrated solar-plus-storage EPC partnerships as the primary go-to-market channel.
For Investors and Strategic Acquirers: The window for entry favors certified pack assemblers with established Emirates Authority for Standardization and Metrology compliance. Long-term viability hinges on securing 20-25 year contracted asset positions rather than merchant battery exposure. Watch Saudi gigafactory subsidy allocation announcements as the critical inflection signal for competitive positioning shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Thermal Runway Certification Investment | Saudi Standards, Metrology and Quality Organization pre-qualification accelerates deployment timelines for qualified cell suppliers. |
| Backward Integration into Cathode Precursors | In-house nickel-cobalt-manganese production hedges South American lithium carbonate volatility for Gulf pack assemblers. |
| Integrated Solar-Plus-Storage EPC Convergence | Engineering-procurement-construction bundling creates channel control points for vertically capable battery suppliers. |
| Sodium-Ion Pilot Deployment | Abu Dhabi and Riyadh procurement corridors test grid-scale buffers where energy density constraints are minimal. |
| Domestic Content Compliance Buildout | Saudi gigafactory subsidies restructure competitive positioning toward regionally manufactured pack assembly. |
Research Methodology
Independent corroboration across utility planning officers, EPC contractors, IPP project developers, and cell manufacturing technical directors underwrites the qualitative findings. Primary interviews with Saudi Standards, Metrology and Quality Organization certification specialists and Emirates Authority for Standardization and Metrology import approval staff combined with secondary validation from customs trade data, Gulf Cooperation Council harmonized technical regulation filings, and project development databases. Bottom-up cell shipment aggregation and top-down renewable energy capacity modeling provide triangulation.
Comparable-period anchoring to historical utility-scale procurement cycles established baseline deployment velocities across the projection horizon. Segmentation dimensions modeled include chemistry type, end-use application, charging technology, and regional regulatory cluster. CAGRs derive from installed base expansion rates and replacement cycle frequencies. Forecast inputs incorporate Saudi solar pairing mandate enforcement schedules and UAE grid modernization capex disclosures.
Revisions become necessary when lithium carbonate concentrate supply disruptions, thermal runaway testing protocol amendments, or domestic content incentive threshold adjustments materialize. Forecasts reflect documented assumptions regarding certification timeline stability and cathode material cost trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
East Asia Battery Market
Batteries
Europe Consumer Battery Market
Batteries
Battery Coolant-Antifreeze Refractometer Market
Batteries
Cylindrical Lithium Battery Winding Machine Market
Batteries
Forklift Battery Market
Batteries
Japan Mobile Battery Market
Batteries
Wireless Power Bank Market
Batteries
18650 And 21700 Battery Market
Batteries
Battery Maintainer Market
Batteries
Europe Battery Cell Market
Batteries
Global Coke Oven Batteries Market
Batteries
Vietnam Battery Market
Batteries
Southeast Asia Battery Market
Batteries
North America Lead Acid Battery Market
Batteries
Solid-State Car Battery Market
Batteries
Smart Diagnostic Battery Charger Market