
 Europe Consumer Battery Market | 2026-2036
Europe Consumer Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Consumer Battery Market Foresight
Aftermarket battery replacement revenue is reconfiguring margin pools away from original equipment bundling toward standalone retail and certified refurbishment channels. Samsung SDI leverages its integrated cell-to-pack architecture to dominate premium lithium-ion segments for consumer electronics. VARTA Consumer Batteries anchors its position through specialized hearing aid and household battery portfolios with deep German manufacturing roots. Northvolt AB competes on sustainable supply chain credentials, building European-sourced cathode capacity to differentiate against Asian imports.
Europe consumer batteries encompass electrochemical energy storage cells rated typically from 1.5V to 48V, engineered through roll-to-roll electrode coating and precision winding processes to power portable devices, cordless appliances, and personal mobility equipment. Alkaline cells retain volume leadership in household primary battery sales across European retail, though lithium-ion chemistry captures the expanding margin pool in rechargeable segments for power tools and portable electronics. The rechargeable technology segment outpaces primary battery growth as cordless device proliferation and EU right-to-repair directives extend replacement cycles and elevate cell quality requirements.
The EU Battery Regulation, REACH, and CE marking frameworks collectively mandate recycled content thresholds, carbon footprint labeling, and restricted substance controls that reshape product design and market access across European member states. ECHA substance evaluations and national WEEE transpositions further tighten end-of-life accountability, forcing producers to redesign collection infrastructure. Stakeholders must monitor evolving delegated acts under the Battery Regulation that will define performance classes and due diligence obligations before compliance deadlines crystallize into competitive barriers.
Market Dynamics
The EU Battery Regulation's carbon footprint declarations and recycled content mandates are forcing producers to reengineer supply chains and collection infrastructure ahead of binding compliance deadlines.
Growth Catalysts
- Right-to-repair mandates:EU directives extending device lifespans elevate demand for higher-cycle rechargeable cells in power tools and portable electronics.
- Germany's electrification lead:Cordless appliance adoption in German households outpaces neighboring markets, concentrating premium lithium-ion procurement.
- Roll-to-roll coating advances:Precision electrode manufacturing cuts cell production costs while improving energy density for consumer applications.
Market Restraints
- Cathode material concentration:European cell makers remain dependent on Asian-processed lithium cobalt oxide and nickel manganese cobalt supply.
- REACH substance evaluations:ECHA's expanding restricted substance list forces costly reformulation of electrolyte solvents and separator materials.
- Alkaline primary cell substitution:Single-use zinc-carbon and alkaline formats face displacement by USB-rechargeable lithium-ion alternatives in low-drain devices.
Strategic Opportunities
- Netherlands circular hubs:Rotterdam-Amsterdam logistics corridors offer integrated collection-sorting-recycling infrastructure for WEEE-compliant battery recovery.
- Hearing aid cell specialization:Zinc-air and silver oxide formats for audiology devices command premium pricing with limited Asian competition.
- Carbon footprint labeling:Early compliance with EU Battery Regulation performance classes creates differentiation against imported cells lacking European-sourced materials.
Industry Challenges
- Electrochemistry talent scarcity:Cell engineering and solid-state research expertise concentrates in Asian universities and corporate labs, constraining European R&D expansion.
- Collection infrastructure capex:Producer-funded WEEE transposition schemes require heavy investment in reverse logistics networks across fragmented national implementations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Consumer Battery Market |
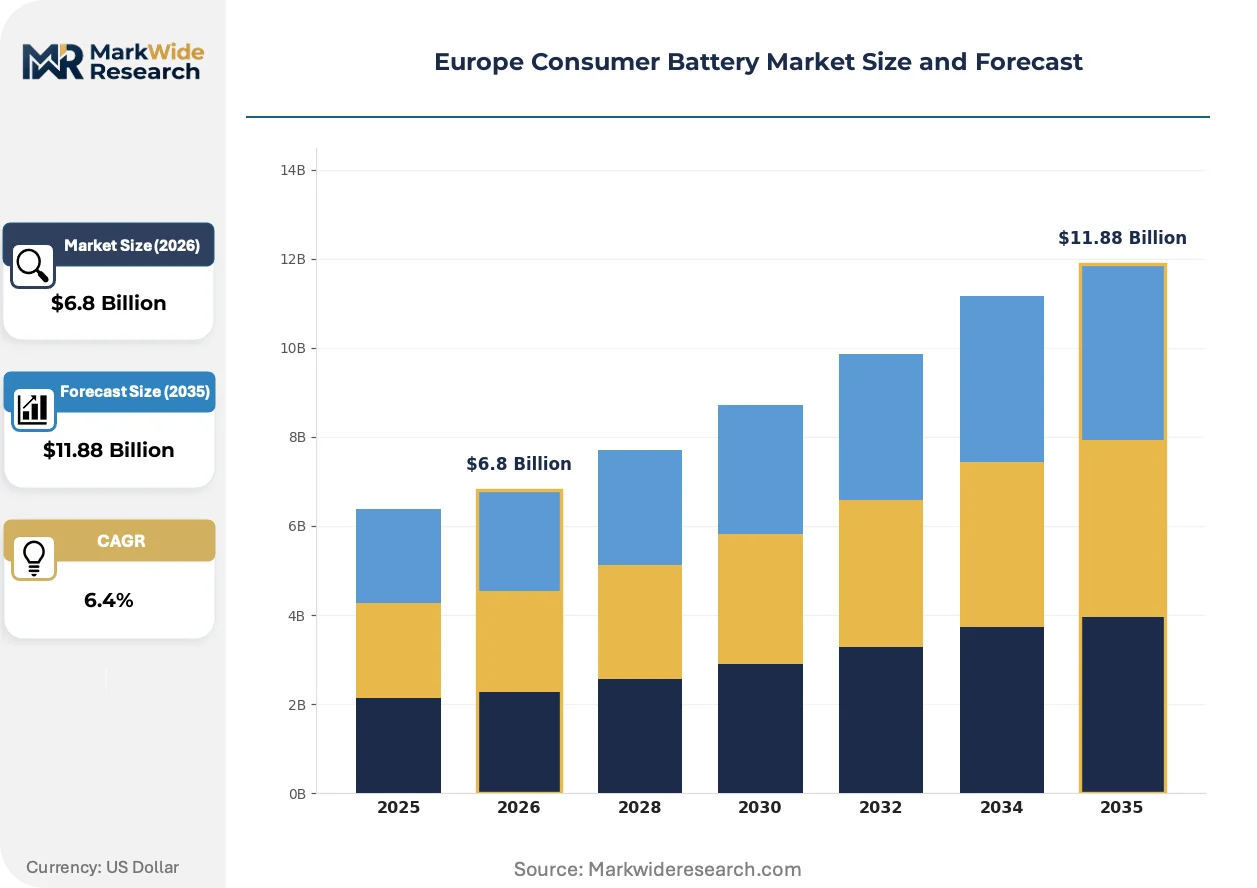
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alkaline, Lithium-ion, Nickel-Cadmium, Zinc-Carbon End User: Electronics, Automotive, Power Tools, Renewable Energy Technology: Rechargeable, Primary, Fuel Cell, Nano Battery Application: Consumer Electronics, Electric Vehicles, Portable Devices, Energy Storage |
| Companies Covered | Samsung SDI, Northvolt AB, VARTA Consumer Batteries, Maxell Holdings, GS Yuasa Corporation, Duracell, Saft, PolyPlus Battery Company, LG Chem, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Consumer Battery Market Shifts & Advancements
Solid-state and silicon-anode chemistries are compressing conventional lithium-ion development timelines, while regulatory transparency mandates reshape how battery performance is communicated to buyers.
Silicon nanowire anode technology is rendering obsolete graphite-dominated energy density limits in premium consumer cells. High-end laptop and smartphone manufacturers are integrating silicon-blend anodes ahead of mass-market adoption. This chemistry is rendering obsolete the gram-per-watt-hour tradeoffs that previously constrained portable device form factors.
REACH substance restrictions and the EU Battery Regulation's due diligence obligations are tightening material provenance requirements. Producers must now document supply chain audits for cobalt, lithium, and nickel sourcing. Premium consumer electronics brands in France and Germany are responding by qualifying European-sourced cathode active materials ahead of delegated act deadlines.
Aftermarket channel unbundling is separating battery sales from original equipment bundling. Certified refurbishment networks and standalone retail are capturing replacement demand previously locked into manufacturer-controlled supply chains. This shift is most visible in German and Dutch markets where right-to-repair enforcement has accelerated independent repair shop qualification programs.
Europe Consumer Battery Market Segmentation
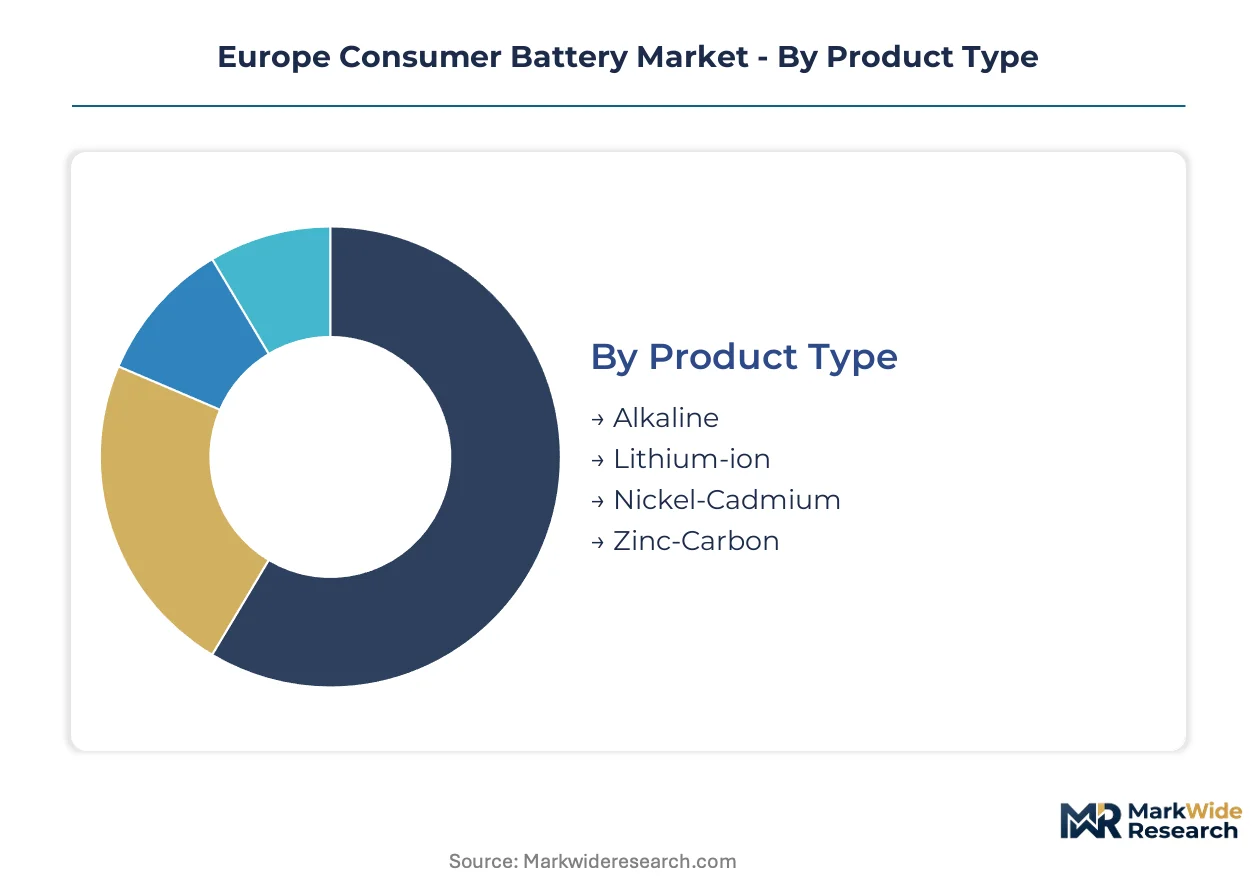
Segmentation in the Europe Consumer Battery Market reveals how chemistry choices, end-use requirements, and regulatory pressures fragment procurement patterns across member states. Distinct performance thresholds and compliance obligations in Germany, France, and the Netherlands concentrate demand in specific product configurations.
Product Type:
Mature alkaline formats coexist with emerging lithium-ion architectures as European households transition from disposable to rechargeable power sources.
- Lithium-ion:Roll-to-roll electrode coating enables energy densities above 250 Wh/kg for premium consumer electronics. German cordless appliance manufacturers and Dutch portable device assemblers drive procurement of high-cycle cells that satisfy EU Battery Regulation carbon footprint thresholds.
- Alkaline:Zinc-manganese dioxide chemistry with potassium hydroxide electrolyte dominates household primary battery retail across European supermarkets. French and German mass-market retailers maintain volume leadership in single-use cell distribution despite rechargeable substitution pressures.
- Nickel-Cadmium:Obsolete in consumer applications due to REACH cadmium restrictions; limited to legacy power tool battery packs in Eastern European markets with delayed WEEE compliance enforcement.
- Zinc-Carbon:Lowest-cost primary chemistry retains niche presence in price-sensitive Southern European retail for low-drain remote controls and clocks.
Alkaline retains volume leadership across European retail channels; lithium-ion holds the steepest expansion curve as right-to-repair directives extend replacement demand.
End User:
Cost-tier stratification separates premium OEM procurement from aftermarket replacement channels across distinct equipment categories.
- Electronics:Smartphone, laptop, and wearable manufacturers specify pouch and cylindrical cells with silicon-anode enhancements. French premium electronics brands qualify European-sourced cathode materials ahead of delegated act deadlines.
- Power Tools:Cordless drill and garden equipment producers demand 18650 and 21700 cylindrical formats with 500+ cycle life. German professional tool manufacturers anchor European lithium-ion procurement volume through integrated pack design.
- Automotive:Limited to auxiliary 12V systems and micro-hybrid applications; consumer-grade cells excluded from traction battery regulations under EU Battery Regulation scope distinctions.
- Renewable Energy:Residential solar storage and portable power stations absorb surplus consumer-format cells; Dutch household energy management adoption concentrates demand in the Netherlands.
Electronics commands premium pricing tiers; power tools exhibits the most rapid capacity expansion as cordless equipment displaces corded alternatives.
Technology:
Application-specific requirements differentiate single-use primary cells from cycle-intensive rechargeable architectures.
- Rechargeable:Lithium-ion and nickel-metal hydride chemistries power devices with daily cycling requirements. EU right-to-repair mandates elevate cell quality specifications for power tools and portable electronics across German and French markets.
- Primary:Single-use alkaline and zinc-air formats serve hearing aids, smoke detectors, and emergency equipment with multi-year shelf life requirements. Silver oxide variants command premium pricing in audiology applications with limited Asian competition.
- Fuel Cell:Proton exchange membrane micro-cells for portable charging applications remain pre-commercial; German research consortia pilot methanol reformer systems for outdoor equipment.
- Nano Battery:Solid-state thin-film architectures for medical implants and smart cards; Swiss and German precision manufacturing clusters advance pilot production lines.
Primary technology retains installed base dominance; rechargeable technology expands most quickly as device electrification accelerates replacement cycles.
Application:
Geographic concentration patterns align application demand with specific European manufacturing and consumption clusters.
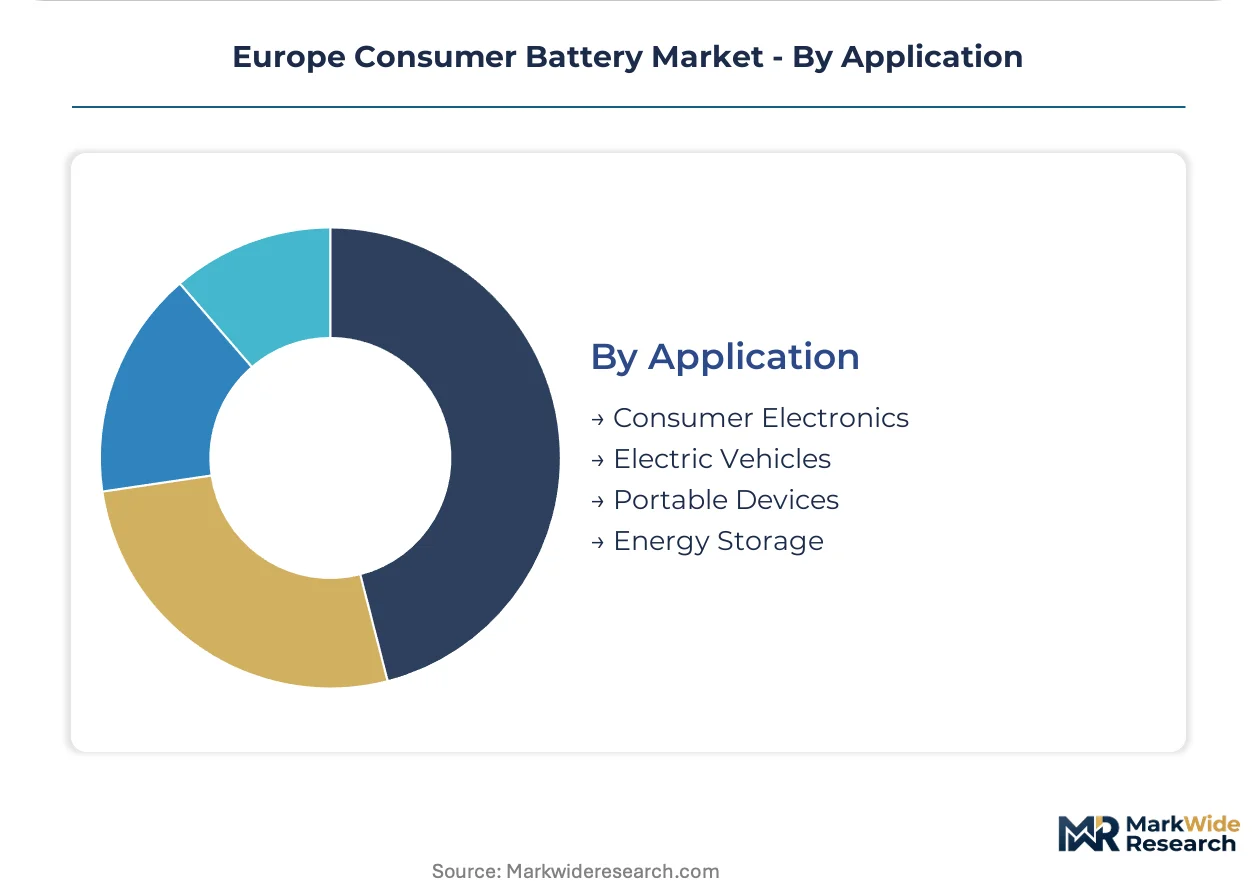
- Consumer Electronics:Smartphones, tablets, laptops, and wearables require compact high-energy cells. German and Dutch consumer electronics retail channels concentrate premium lithium-ion procurement for replacement and upgrade cycles.
- Portable Devices:Cordless vacuums, personal mobility equipment, and outdoor power tools demand robust cylindrical formats. French household appliance electrification drives mid-tier rechargeable adoption ahead of neighboring markets.
- Electric Vehicles:Excluded from consumer battery scope; light electric vehicles and e-bikes represent boundary applications with hybrid regulatory treatment under EU Battery Regulation.
- Energy Storage:Residential and portable power systems absorb consumer-format cells for backup and off-grid applications; Netherlands circular hub infrastructure supports second-life cell redeployment.
Consumer Electronics maintains revenue concentration; Portable Devices gains share fastest as cordless proliferation extends beyond professional into household segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German households favor premium cordless appliances requiring high-cycle lithium-ion cells, while French consumers prioritize compact formats for portable electronics, and Dutch buyers lead second-life redeployment for residential energy storage.
Germany
Professional power tool manufacturers and household appliance brands drive procurement of cylindrical 18650 and 21700 formats with extended cycle life. The EU Battery Regulation's carbon footprint declarations force producers to document supply chain audits for cobalt and nickel sourcing. Stuttgart and Munich manufacturing clusters concentrate pack assembly operations for cordless garden equipment and vacuum systems.
France
Premium smartphone and laptop brands specify pouch cells with silicon-anode enhancements for energy density above 250 Wh/kg. ANSM and DGCCRF enforcement of CE marking and REACH substance restrictions tightens material provenance requirements for electrolyte solvents. Paris-Saclay research corridors advance solid-state thin-film pilot lines for medical implant applications.
Netherlands
Household energy management adoption concentrates demand for portable power stations and residential solar storage using surplus consumer-format cells. WEEE transposition schemes mandate producer-funded collection infrastructure with Rotterdam-Amsterdam logistics hubs integrating sorting and recycling operations. Eindhoven's circular manufacturing clusters pilot second-life cell redeployment for backup power systems.
United Kingdom
Aftermarket replacement channels capture demand from right-to-repair enforcement in consumer electronics and power tools. The UK's post-Brexit alignment with REACH restrictions maintains substance controls on cadmium and mercury while diverging on delegated act timelines. London-Oxford-Cambridge innovation corridors advance nano-battery architectures for smart card and implantable device applications.
Italy
Price-sensitive Southern European retail sustains alkaline and zinc-carbon volume for low-drain remote controls and emergency lighting. CE marking enforcement through the Ministry of Economic Development tightens compliance for imported cells lacking European-sourced materials. Milan-Turin industrial districts concentrate hearing aid battery packaging and distribution for audiology device manufacturers.
Europe Consumer Battery Market Competitive Landscape
Capability concentration sits with integrated cell-to-pack specialists; scale advantage sits with diversified chemical conglomerates. The vendor base separates into three tiers: premium lithium-ion architects, specialized primary cell producers, and mass-market alkaline distributors. Dominant competitive moves include backward integration into cathode active material production and strategic partnerships with European recycling operators to satisfy recycled content mandates.
Within the integrated architecture tier, Samsung SDI and Northvolt AB exemplify divergent sourcing strategies for European market positioning. VARTA Consumer Batteries anchors the specialized primary segment through German manufacturing roots in hearing aid and household formats. Among Asian-headquartered suppliers, LG Chem and GS Yuasa Corporation occupy positions serving premium electronics OEMs with established cylindrical and prismatic cell platforms.
| Leading Market Players |
|---|
| Samsung SDI |
| Northvolt AB |
| VARTA Consumer Batteries |
| Maxell Holdings |
| GS Yuasa Corporation |
| Duracell |
| Saft |
| PolyPlus Battery Company |
| LG Chem |
| Others |
Supply & Pricing Matrix
Stuttgart-Munich manufacturing clusters concentrate cylindrical cell assembly capacity for German cordless appliance brands, translating electrode coating scale into procurement leverage over smaller pack integrators across neighboring markets. REACH substance restrictions and EU Battery Regulation carbon footprint thresholds force electrolyte and separator reformulation costs downstream, compressing margins for distributors lacking backward integration into cathode active material production.
Pricing Analysis
Long-term offtake contracts between German power tool OEMs and Korean-Japanese cell suppliers dominate premium lithium-ion procurement, locking in volume commitments that insulate against cobalt and nickel spot volatility. Price differentiation separates CE-marked cells with documented supply chain audits from gray-market imports lacking ECHA-compliant material provenance. Cost compression in alkaline primary cells intensifies as USB-rechargeable lithium-ion alternatives displace zinc-carbon formats in French and Dutch retail channels. Mass-market supermarket buyers in Southern Europe exhibit highest price sensitivity, while professional tool manufacturers in Germany absorb premiums for 500+ cycle life specifications.
Supply Chain Analysis
Tariff exposure between European Union member states and third-country cathode processors dominates supply chain risk planning for cell assemblers dependent on Asian-sourced lithium cobalt oxide. China, South Korea, and Japan concentrate precursor chemical production and roll-to-roll electrode coating equipment manufacturing. European cell makers draw from Chilean lithium brine, Indonesian nickel, and DRC cobalt concentrates processed through East Asian refineries. Single-source vulnerability in separator membrane supply constrains production scheduling for Dutch and German pack integrators. Distribution runs through Rotterdam-Amsterdam logistics corridors integrating WEEE-compliant collection with certified refurbishment channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among German cordless appliance manufacturers and French premium electronics OEMs, consolidating procurement volume across fewer cell qualification programs and squeezing margin pools for undifferentiated distributors.
For Market Incumbents: Insulate core lithium-ion cell supply relationships through captive cathode active material partnerships with European recycling operators, countering Northvolt AB's sustainable sourcing differentiation. Secure CE marking and EU Battery Regulation performance class compliance ahead of delegated act deadlines to lock out Asian imports lacking carbon footprint documentation. Prioritize hearing aid and audiology cell specialization where zinc-air formats command premium pricing with limited Korean competition. For New Entrants and Emerging Players: Southern European price-sensitive retail for alkaline and zinc-carbon primary cells offers the most penetrable white-space, with Italian and Spanish supermarket channels underserved by dedicated battery specialists. Target certified refurbishment networks in the Netherlands where WEEE transposition schemes mandate producer-funded collection infrastructure. Lead with carbon footprint labeling compliance as a go-to-market wedge against established distributors lacking European-sourced material documentation. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because EU Battery Regulation recycled content mandates and REACH substance restrictions will crystallize into competitive moats for compliant European producers. Acquisition targets should cluster around integrated cell-to-pack specialists with qualified European cathode supply and established WEEE collection infrastructure. Watch for ECHA delegated act finalization on performance classes as the signal indicating when compliance investments convert to pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Active Materials | European recycling partnerships satisfy EU Battery Regulation recycled content thresholds ahead of binding deadlines. |
| CE Marking and Carbon Footprint Labeling Investment | ANSM and DGCCRF enforcement in France and KBA oversight in Germany tighten market access for non-compliant imports. |
| Certified Refurbishment Network Expansion | Right-to-repair directives in Germany and the Netherlands accelerate independent repair shop qualification programs. |
| Hearing Aid Cell Specialization | Zinc-air and silver oxide formats for audiology devices command premium pricing with limited Asian manufacturer competition. |
| Rotterdam-Amsterdam Logistics Hub Integration | WEEE transposition schemes mandate producer-funded collection-sorting-recycling infrastructure for battery recovery compliance. |
Research Methodology
Cross-validation between primary interviews with cell engineering directors, procurement leads at German power tool OEMs, ECHA regulatory affairs specialists, and Dutch circular economy cluster managers anchors the qualitative findings. Secondary validation draws from EU Battery Regulation delegated act drafts, ECHA substance evaluation reports, WEEE transposition scheme filings, and customs trade data on lithium carbonate and cobalt chemical imports. Bottom-up cell production capacity estimates triangulate against top-down replacement demand modeling across consumer electronics, power tools, and portable device categories.
Calibration against historical lithium-ion price curves and alkaline volume trends across European retail channels informs the projection framework. Segmentation dimensions span chemistry type, end-use equipment category, technology class, and national regulatory implementation intensity. CAGRs derive from installed base growth, replacement cycle compression, and cordless device electrification rates. Industry-specific inputs include silicon-anode adoption timelines in premium electronics and right-to-repair enforcement patterns across member states.
Macroeconomic conditions sit as an overlay; deviation in eurozone manufacturing PMI, lithium spot price volatility, or Chinese export license restrictions would shift the trajectory. Forecasts reflect assumptions on regulatory timeline adherence and cathode material supply diversification that continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Thin Film and Printed Battery Market
Batteries
Global Zinc Air Batteries Market
Batteries
South America Rechargeable Battery Market
Batteries
Elastic Battery Binders Market
Batteries
Modular Battery Pack Platforms for Skateboard EVs Market
Batteries
Lithium-Fluorinated Graphite Batteries Market
Batteries
North America Consumer Battery Market
Batteries
Battery Simulator Market
Batteries
Nimh Battery Market
Batteries
Floor Scrubber Battery Market
Batteries
India Lead-Acid Battery Market
Batteries
Proton Battery Market
Batteries
Deep Cycle Battery Market
Batteries
High Temperature NiMH Battery Market
Batteries
Nas Battery Market
Batteries
US Solar Battery Market