
 Electric Battery Market | 2026-2036
Electric Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Battery Market Analysis
Modular battery pack architecture is rebalancing procurement patterns across automotive OEMs. Contemporary Amperex Technology Co. Limited leverages vertical integration from cathode materials to finished cells, sustaining cost advantages in volume production. LG Energy Solution Ltd. anchors its position through specialized cylindrical and prismatic formats for premium EV platforms. BYD Company Ltd. dominates in-house blade-cell deployment across its vehicle lineup, reducing external supplier dependency.
An electric battery is an electrochemical device storing and releasing energy through reversible redox reactions, typically achieving energy densities of 150–300 Wh/kg in lithium-ion configurations and serving as the core power source for mobility and grid-scale storage systems. Lithium-ion chemistry leads across product types due to manufacturing scale and declining cost curves, while solid-state designs attract R&D capital for their potential to eliminate thermal runaway risks. Energy density and fast charging parameters within technology segmentation command premium positioning as automakers specify longer-range EV platforms.
The US Inflation Reduction Act and EU Battery Regulation impose escalating domestic content thresholds and recycling mandates, forcing manufacturers to reconfigure supply geography or face market access barriers. China's MIIT enforces GB standards for cell safety and performance, creating parallel compliance tracks for exporters. Japan's METI coordinates national solid-state roadmaps with Panasonic Energy and Toyota-aligned suppliers. Stakeholders must monitor how divergent carbon-footprint accounting rules reshape cell sourcing decisions across major demand centers.
Market Dynamics
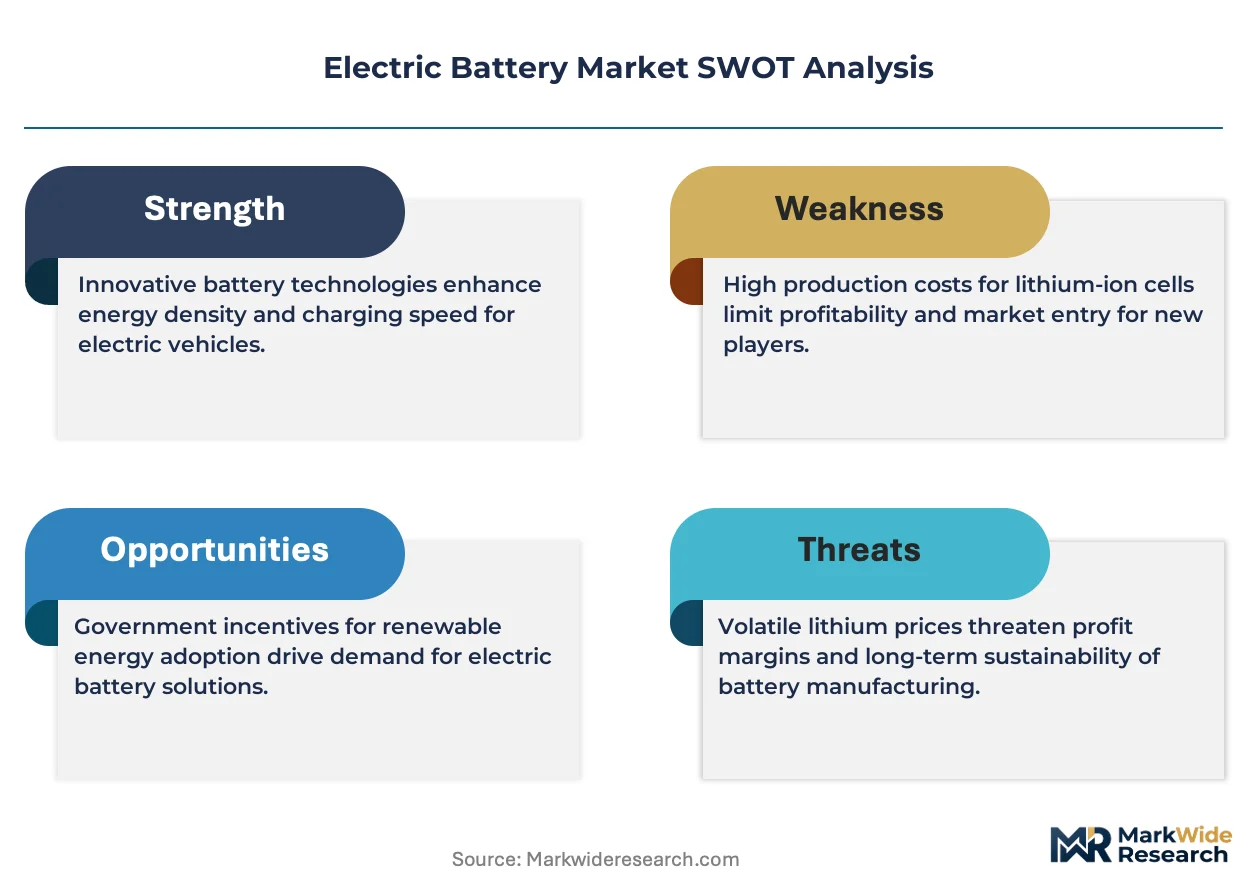
Domestic content mandates under the US Inflation Reduction Act and EU Battery Regulation are forcing manufacturers to rewire supply geography, redirecting capital toward regional cell plants and upstream material refining to preserve market access.
Growth Catalysts
- EV Platform Electrification:Automotive OEMs are committing to dedicated battery-electric architectures, locking in multi-year cell procurement contracts that de-risk manufacturing investments for suppliers.
- Stationary Storage Deployment:Grid operators in Germany, Australia, and California are procuring utility-scale lithium-ion systems to balance renewable intermittency, creating parallel demand outside mobility.
- Recycling Mandates:The EU Battery Regulation establishes minimum recovered content thresholds, incentivizing closed-loop material flows and secondary supply development.
Market Restraints
- Lithium Supply Concentration:Hard rock and brine extraction concentrates in Chile, Australia, and Argentina, exposing cell makers to export policy shifts and offtake competition.
- Cathode Material Cost Volatility:Nickel and cobalt price swings compress margin predictability for high-nickel chemistries, pushing some buyers toward lithium iron phosphate alternatives.
- Thermal Runaway Limitations:Liquid electrolyte architectures require extensive thermal management hardware, adding mass and complexity that solid-state designs promise to eliminate.
Strategic Opportunities
- Second-Life Applications:Retired EV packs retain 70-80% capacity, enabling repurposing into stationary storage for commercial and industrial backup power in India and Southeast Asia.
- Solid-State Convergence:Sulfide and oxide electrolyte research combined with silicon anode development targets 400+ Wh/kg densities for premium aviation and luxury automotive segments.
- Direct Recycling Methods:Hydrometallurgical and direct cathode regeneration processes recover materials without full smelting, aligning with EU carbon-footprint accounting rules for green batteries.
Industry Challenges
- Electrolyte Formulation Expertise Gap:Solid-state manufacturing requires dry-room environments and thin-film deposition skills scarce in incumbent cell plants, slowing technology transfer.
- Gigafactory Capital Intensity:Cell production facilities demand $3-5 billion per 50 GWh of capacity, stretching balance sheets and requiring offtake guarantees before groundbreaking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Battery Market |
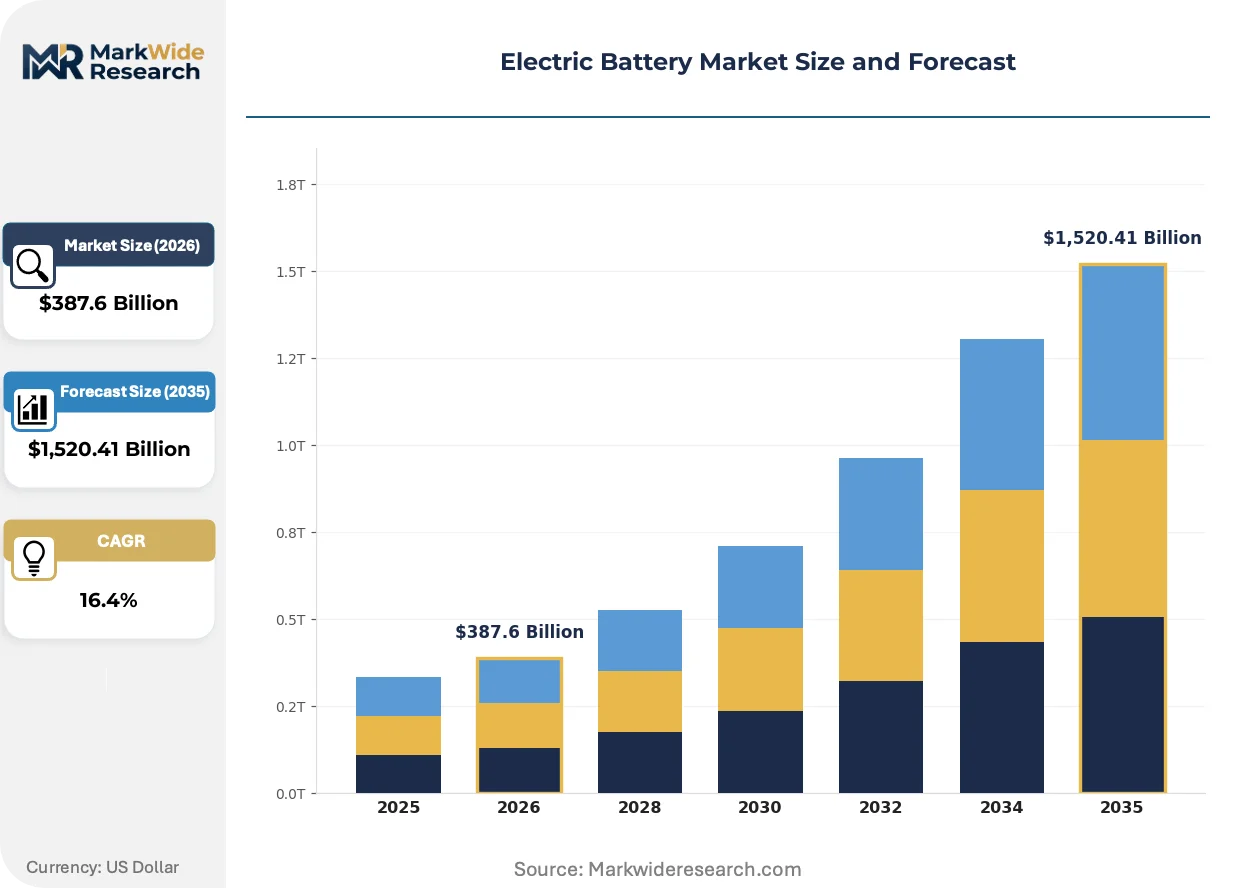
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $1,520.41 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-Ion, Nickel-Metal Hydride, Lead-Acid, Solid State Technology: Energy Density, Cycle Life, Fast Charging, Safety Features End User: Electric Vehicles, Consumer Electronics, Renewable Energy Storage, Industrial Applications Application: Grid Storage, Mobile Devices, Automotive, Uninterruptible Power Supply |
| Companies Covered | Contemporary Amperex Technology Co. Limited, LG Energy Solution Ltd., BYD Company Ltd., Panasonic Energy, Samsung SDI Co., Ltd., SK On, CALB, Sunwoda, EVE Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Battery Market Emerging Trajectories
Cell-to-pack architectures and solid-state electrolyte research are compressing traditional module-tier supply relationships, while regulatory carbon-accounting rules reshape material sourcing decisions.
Silicon-dominant anodes are replacing graphite in premium cell designs, boosting energy density by 20-40% in prototype configurations. Korean and Japanese suppliers are qualifying these chemistries for next-generation EV platforms launching in 2026-2027. This transition is modularizing pack design, allowing OEMs to standardize thermal management hardware across multiple vehicle classes.
The EU Battery Regulation mandates digital battery passports tracing carbon intensity, material origin, and recycled content across the value chain. Cell importers face market exclusion without third-verified documentation starting in 2027. High-volume producers are deploying blockchain-anchored supply chain tracking to automate compliance and accelerate customs clearance.
Long-term offtake contracting is displacing spot market purchasing for critical minerals, with automakers directly investing in mining and refining projects to secure lithium and nickel supply. This verticalization concentrates negotiation leverage among OEMs with balance sheet capacity, squeezing mid-tier cell suppliers in Europe and North America. German and US automakers have pioneered this model, with similar structures emerging in Japanese keiretsu supply networks.
Electric Battery Market Segmentation
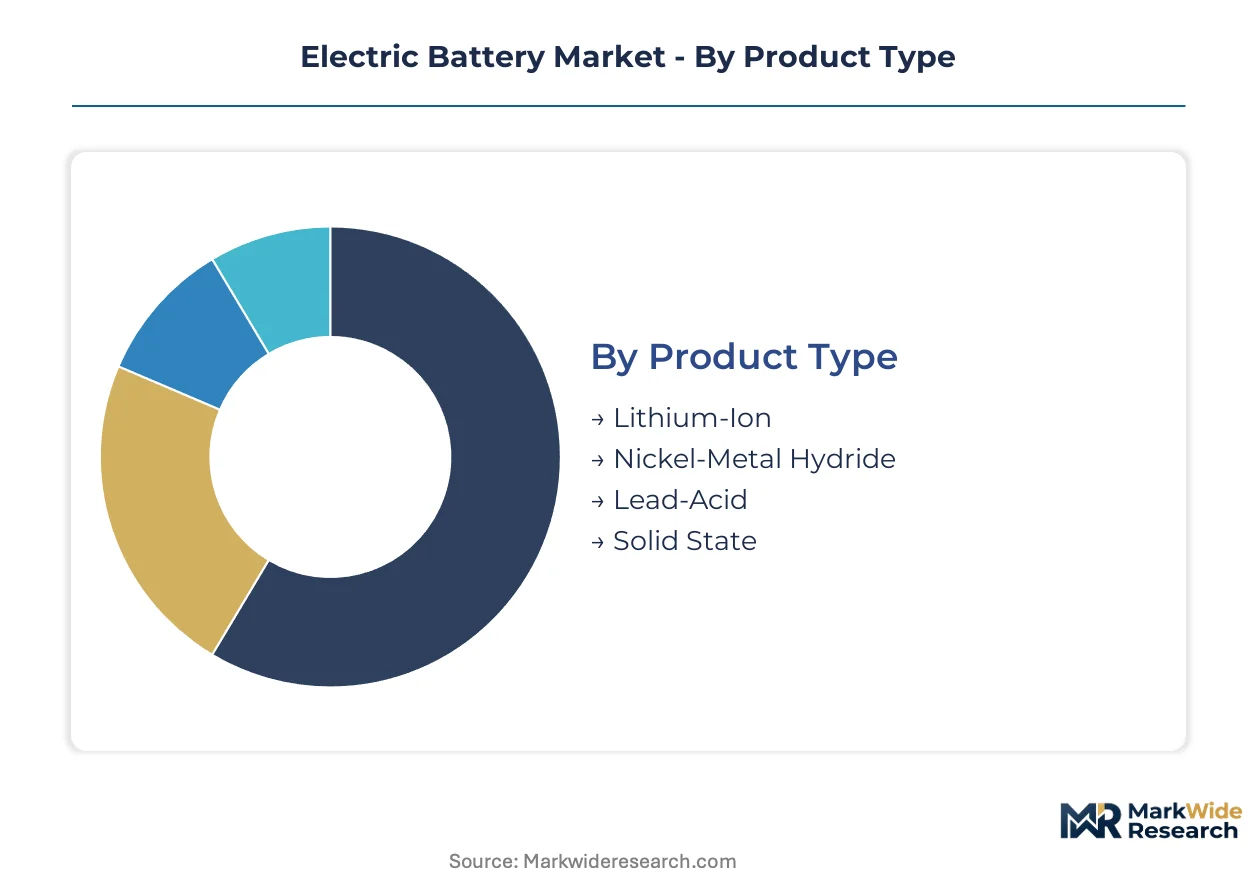
Electric battery procurement patterns diverge sharply across chemistry types and application requirements, with certification burdens and performance specifications dictating supplier selection. Understanding how segments interlock reveals where margin concentrates and which technology transitions will reshape competitive positioning.
Product Type:
Lithium-ion cells carry UN 38.3 transport certification and IEC 62619 safety approvals for stationary storage, while solid-state architectures await updated GB standards from China's MIIT and UL listings for commercial deployment.
- Lithium-Ion:Dominant chemistry employing layered oxide cathodes and graphite or silicon-blend anodes, achieving 250-300 Wh/kg in NMC configurations. Demand concentrates in automotive platforms from Tesla, BYD, and European OEMs, driven by IRA domestic content credits forcing North American cell sourcing.
- Solid State:Emerging architecture replacing liquid electrolytes with sulfide or oxide ceramic conductors, targeting elimination of thermal runaway risks. Prototype cells from Toyota-Panasonic partnerships and QuantumScape target aviation and luxury automotive segments where safety premiums justify unit costs.
- Nickel-Metal Hydride:Mature chemistry retaining position in hybrid electric vehicles where moderate energy density suffices and thermal stability reduces cooling hardware mass.
- Lead-Acid:Lowest-cost chemistry constrained to starter-lighting-ignition functions and backup power where cycle depth requirements remain shallow.
Leading the category by volume: Lithium-Ion. Expanding most quickly: Solid State.
Technology:
Performance parameters segment procurement tiers, with energy density specifications commanding premium pricing in aviation and long-range automotive applications while cycle life requirements dominate utility storage tenders.
- Energy Density:Gravimetric and volumetric capacity metrics determining pack mass and vehicle range. Silicon-anode prototypes from Korean suppliers target 400 Wh/kg for next-generation EV platforms.
- Fast Charging:C-rate capability enabling 10-80% state-of-charge in under 20 minutes, now standard for premium automotive segments and critical for commercial fleet uptime.
- Cycle Life:Degradation resistance measured in charge-discharge cycles, with LFP chemistries exceeding 6,000 cycles and winning stationary storage tenders in California and Germany.
- Safety Features:Thermal propagation prevention and venting systems mandated by ECE R100 for automotive and UL 9540 for stationary installations.
Fastest share gain: Fast Charging. Highest margin concentration: Energy Density.
End User:
Customer scale and integration depth fragment the demand landscape, with automotive OEMs demanding cell-to-pack architectures while grid operators prioritize containerized system availability.
- Electric Vehicles:Largest demand pool spanning passenger cars, commercial vans, and heavy trucks, with platform-specific form factors locking in supplier relationships.
- Renewable Energy Storage:Utility-scale and behind-the-meter installations balancing solar and wind intermittency, procuring on dollar-per-kWh lifetime cost rather than upfront capital.
- Consumer Electronics:Cylindrical and pouch formats for smartphones, laptops, and power tools, with energy density prioritized over cycle depth.
- Industrial Applications:Forklifts, mining equipment, and marine propulsion requiring ruggedized thermal management and extended operational temperature ranges.
Volume leadership: Electric Vehicles. Steepest expansion trajectory: Renewable Energy Storage.
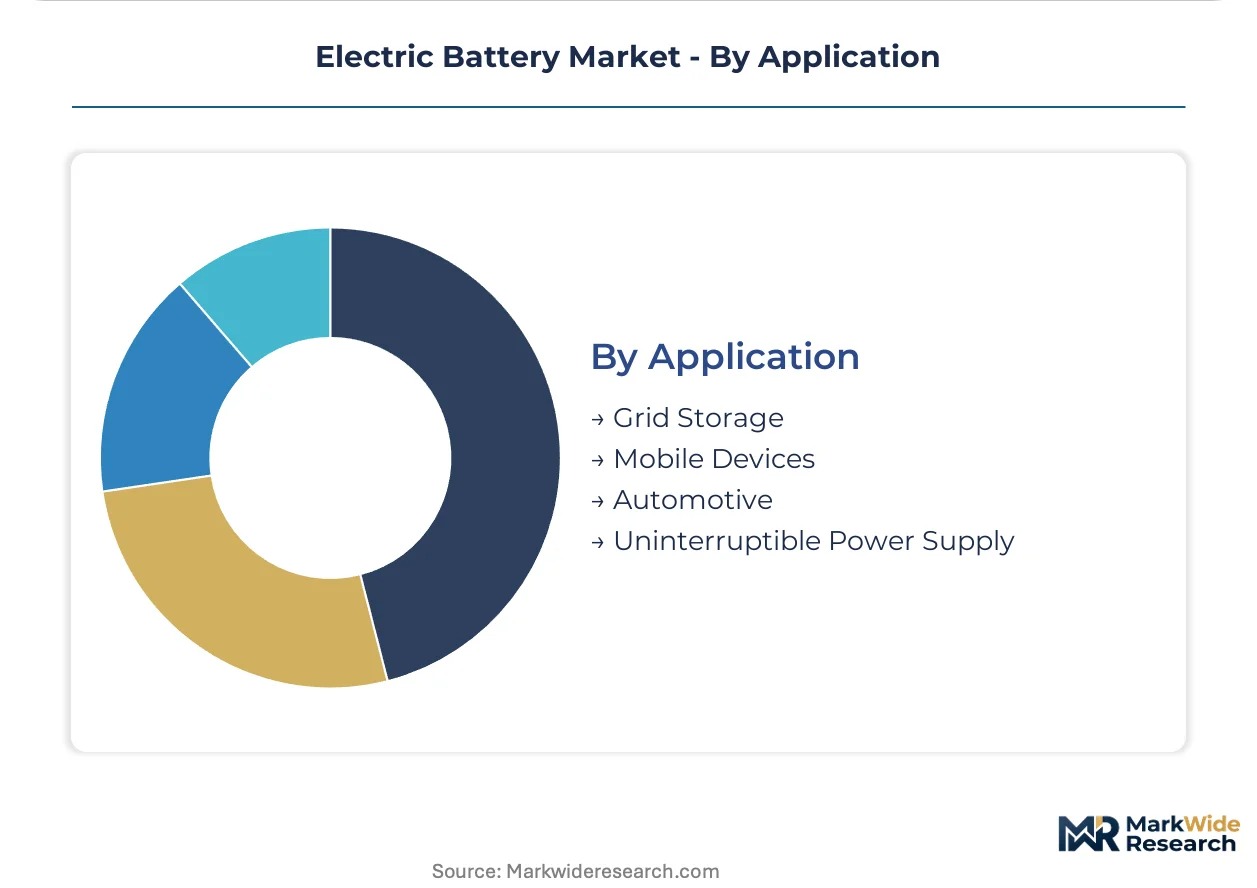
Application:
Deployment environment dictates pack architecture, with automotive integration requiring crash-resistant enclosures and grid storage emphasizing modular scalability for phased commissioning.
- Automotive:Floor-integrated packs with structural load-bearing functions, liquid cooling circuits, and battery management systems meeting ASIL-D functional safety grades.
- Grid Storage:Containerized megawatt-hour systems with power conversion and grid-forming inverters, procured through 15-20 year service agreements by utilities.
- Mobile Devices:Compact pouch and cylindrical cells with protection circuits, prioritizing volumetric energy density for slim industrial designs.
- Uninterruptible Power Supply:Rack-mounted systems for data centers and healthcare facilities requiring instantaneous switchover and 15-30 minute runtime.
Dominant by installed capacity: Automotive. Fastest-growing application: Grid Storage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of global cells while Western markets consume them under tightening domestic content rules. Cell makers in Asia-Pacific anchor production capacity as North American and European automakers scramble to localize supply chains. Regulatory fragmentation is forcing parallel plant investments across three continents.
United States
Automakers in Michigan and Tennessee are locking in decade-long offtake agreements with Korean cell suppliers building plants in Georgia and Ohio. The Inflation Reduction Act's domestic content thresholds exclude vehicles using Chinese-sourced cells from tax credits. The Southeast manufacturing corridor spanning South Carolina to Kentucky is attracting cathode precursor facilities from Korean conglomerates seeking to qualify for IRA benefits.
Germany
Premium automakers in Stuttgart and Munich are specifying high-nickel cells for next-generation EV platforms launching through 2027. The EU Battery Regulation mandates carbon footprint declarations and recycled content minimums from 2027, pressuring importers. The Upper Rhine region hosts pilot solid-state production lines from established suppliers seeking to leapfrog Asian liquid-electrolyte dominance.
China
CATL and BYD anchor gigafactory clusters in Fujian and Shenzhen serving both domestic automakers and export markets. MIIT enforces GB standards for cell safety and performance that create parallel compliance tracks for foreign entrants. The Yangtze River Delta concentration spans cathode material refining through finished pack assembly, sustaining cost advantages in volume production.
Japan
Automotive keiretsu networks coordinate solid-state roadmaps targeting aviation and luxury segments where safety premiums justify unit costs. METI channels national R&D funding toward sulfide electrolyte manufacturing processes. The Kansai industrial belt around Osaka hosts pilot lines from established electronics suppliers seeking to reclaim technology leadership.
South Korea
Cell makers in Seoul and Ulsan are expanding cylindrical and prismatic capacity for premium EV platforms from German and US automakers. The government's K-Battery strategy subsidizes domestic material refining to reduce Chinese import dependency. The Gyeonggi-do province cluster concentrates R&D investment in silicon-anode chemistries for next-generation energy density targets.
Electric Battery Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across multiple technology vectors. The market structure consolidates around Asian cell makers with manufacturing scale advantages while Western entrants struggle to match capital intensity. Three archetypes dominate: vertically integrated material-to-cell producers, specialized format suppliers, and automaker-captive operations. Capacity expansion and strategic partnerships constitute the primary competitive moves as firms race to secure offtake agreements before plant commissioning.
Among Chinese producers, Contemporary Amperex Technology Co. Limited anchors the vertically integrated archetype through upstream control over cathode materials. LG Energy Solution Ltd. exemplifies the specialized format supplier position with dedicated cylindrical and prismatic lines. BYD Company Ltd. occupies the automaker-captive tier, reducing external supplier dependency through in-house blade-cell deployment. Panasonic Energy represents Japanese solid-state development efforts targeting premium segments.
| Leading Market Players |
|---|
| Contemporary Amperex Technology Co. Limited |
| LG Energy Solution Ltd. |
| BYD Company Ltd. |
| Panasonic Energy |
| Samsung SDI Co., Ltd. |
| SK On |
| CALB |
| Sunwoda |
| EVE Energy |
| Others |
Supply Flow & Price Mechanics
Lithium carbonate spot benchmarks cascading through cathode precursor contracts stratify cell pricing across automotive procurement tiers. IRA domestic content thresholds and EU carbon-footprint declarations compel buyers to absorb regional sourcing premiums or forfeit market access, compressing margin pools for non-integrated suppliers.
Pricing Analysis
Cost-down pressure on standard-format cylindrical cells accelerates because automakers are consolidating volume awards among qualified suppliers. Three-tier pricing structure across premium silicon-anode, standard high-nickel, and economy LFP configurations reflects energy density performance and certification grade. Price differentiation hinges on UL/IEC safety tier and volume scale, with fleet buyers commanding steepest discounts. Commercial vehicle operators exhibit highest price sensitivity; aviation and luxury automotive segments show lowest.
Supply Chain Analysis
Dual-sourcing mandates from German and US automakers require cell suppliers to qualify parallel cathode material streams from distinct geographies. Manufacturing gravity centers on China, South Korea, and Japan for finished cells, with Australia, Chile, and Argentina anchoring lithium extraction. Raw material dependencies span spodumene concentrate, nickel sulfate, and cobalt hydroxide. Single-source vulnerability concentrates in Chinese graphite anode supply. Distribution runs through long-term offtake contracts directly to OEM gigafactory gates, bypassing spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive positioning in this market is concentrating around captive control of upstream refining capacity and downstream pack integration. Players securing lithium offtake and regional cell plant commitments are capturing margin that modular suppliers forfeit.
For Market Incumbents: Hedge against solid-state disruption by maintaining parallel liquid-electrolyte capacity commitments while funding sulfide electrolyte pilot lines. Lock in decade-long cathode material offtake from Australian and Chilean projects before supply competition intensifies. Defensive consolidation through regional joint ventures with Korean suppliers preserves IRA qualification pathways. For New Entrants and Emerging Players: Begin with second-life battery repurposing for Indian and Southeast Asian commercial storage, where certification barriers remain lower than automotive. Target grid-scale containerized systems procured on dollar-per-kWh lifetime cost rather than upfront capital. Go-to-market through direct utility contracting bypasses entrenched automotive supplier relationships. For Investors and Strategic Acquirers: The window for entry favors direct recycling technology specialists with hydrometallurgical process patents aligned to EU Battery Regulation compliance. Long-term viability rests on positioning for closed-loop material recovery as recovered content mandates escalate. Watch for inflection in solid-state manufacturing yield rates as the signal for technology transition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Vertical Integration into Cathode Refining | Captures margin pools threatened by nickel and cobalt price volatility under IRA sourcing rules. |
| Solid-State Pilot Line Commissioning | Positions suppliers for aviation and luxury automotive segments where safety premiums justify unit costs. |
| Long-Term Lithium Offtake Contracting | Secures supply certainty as hard rock and brine extraction concentrates in Chile, Australia, and Argentina. |
| Direct Recycling Process Development | Aligns with EU Battery Regulation carbon-footprint accounting for green battery certification. |
| Regional Gigafactory Expansion | Qualifies for IRA domestic content credits and EU Battery Regulation market access requirements. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with cell procurement directors at automotive OEMs, cathode material plant managers, and utility storage planners combined with bottom-up capacity modeling and top-down demand validation. Secondary sources spanned MIIT GB standard documentation, EU Battery Regulation implementing acts, US IRA Treasury guidance, and UN Comtrade lithium carbonate flow records.
Reconciliation of production capacity databases, cell shipment manifests, and vehicle registration data streams underpinned forecast construction. Segmentation dimensions modeled include chemistry type, cell format, end-use application, and regional regulatory cluster. CAGRs derived from installed capacity buildout schedules and automaker platform electrification timelines across the projection horizon. Forecast inputs incorporated silicon-anode adoption curves and solid-state manufacturing yield assumptions.
Underlying measurement precision varies by segment; lithium-ion automotive applications carry tighter precision than emerging solid-state categories. Forecasts reflect assumptions regarding IRA domestic content phase-in schedules and EU carbon-border adjustment implementation. Deviation in lithium extraction export policy or solid-state electrolyte manufacturing yield breakthroughs would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Sodium-Air Battery Market
Batteries
Non-Rechargeable Battery Market
Batteries
Global Battery Market
Batteries
India Electric Vehicle Battery Manufacturing Equipment Market
Batteries
Tubular GEL Battery Market
Batteries
Printable Battery Market
Batteries
Electrolyte Solutions for Li-Ion Batteries Market
Batteries
Global Coke Oven Batteries Market
Batteries
Myanmar Battery Market
Batteries
Battery Binders Market
Batteries
Battery Anode Materials Market
Batteries
West Africa Battery Market
Batteries
America SLI Battery Market
Batteries
Asia-Pacific Industrial Battery Market
Batteries
Norway Rechargeable Battery Market
Batteries
Breathing Battery Market