
 Medical Batteries Market | 2026-2036
Medical Batteries Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Batteries Market Analysis
Buyer concentration among hospital procurement groups is expanding as integrated delivery networks consolidate purchasing power across multi-state systems. Panasonic Corporation leverages its cylindrical cell expertise to anchor contracts with original equipment manufacturers of patient monitors. EnerSys competes through its thin-cell lithium platform designed for wearable diagnostic patches. Ultralife Corporation specializes in military-grade reliability standards that translate into extended-cycle implants for cardiac rhythm management.
Medical batteries are electrochemical energy storage devices engineered to deliver stable voltage output under sterilization temperatures and biological exposure, typically incorporating hermetic sealing and biocompatible electrolyte formulations to prevent leakage within tissue-contacting applications. Lithium-ion configurations dominate the implantable segment due to superior energy density, while nickel-metal hydride retains share in portable diagnostic instruments where cost sensitivity outweighs miniaturization requirements. The surgical instruments category is shifting toward rechargeable architectures as operating rooms phase out disposable alkaline cells to reduce per-procedure waste.
The FDA enforces 21 CFR Part 820 quality system regulations that mandate validation of battery failure modes across device lifecycles, directly elevating R&D expenditure for market entrants. ISO 14708-1 standards for active implantable medical devices specify voltage stability thresholds that lithium-primary cells routinely satisfy but that challenge emerging solid-state alternatives. Stakeholders must monitor how the EU Medical Device Regulation's tightened post-market surveillance requirements will reshape supplier qualification timelines for European distribution channels.
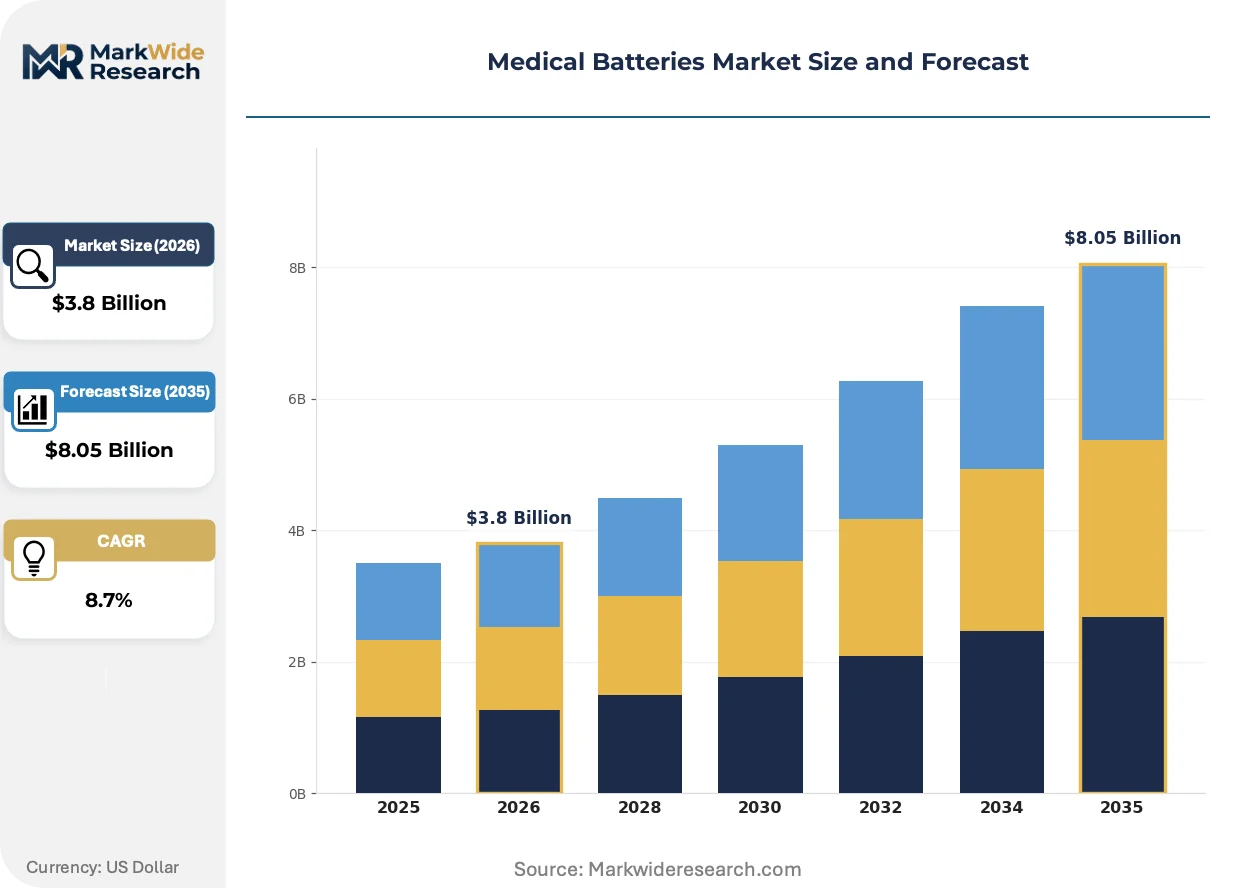
Market Dynamics
Solid-state battery architectures are compressing replacement cycles for implantable devices while FDA validation protocols force manufacturers to front-load quality assurance expenditure before market entry.
Growth Catalysts
- EU Medical Device Regulation:Post-market surveillance mandates are elevating supplier qualification standards, favoring battery manufacturers with established ISO 14708-1 certification pathways and accelerating consolidation among compliant vendors.
- Continuous glucose monitors:Expanding adoption of wearable metabolic sensors is generating sustained demand for thin-cell lithium platforms capable of multi-year operation under skin-contact conditions.
- German regulatory leadership:BfArM quality benchmarks are concentrating procurement decisions around lithium-ion suppliers with proven hermetic sealing capabilities, reinforcing established supply relationships.
Market Restraints
- Lithium supply concentration:Raw material processing gravity centers on limited jurisdictions, exposing battery manufacturers to geopolitical disruption risk and input cost volatility.
- Biocompatibility validation costs:ISO 10993 testing requirements for electrolyte formulations impose fixed R&D burdens that disproportionately constrain mid-tier entrants.
- Nickel-metal hydride persistence:Cost-sensitive portable diagnostic instruments continue specifying legacy chemistries, delaying full lithium-ion penetration in non-implantable segments.
Strategic Opportunities
- Rechargeable surgical instruments:Operating room waste reduction mandates are creating replacement demand for alkaline cells with lithium-ion rechargeable architectures.
- Japan METI circular economy frameworks:Battery recycling incentives are opening service-revenue streams for manufacturers willing to establish reverse logistics networks.
- Solid-state electrolyte convergence:Ceramic-polymer hybrid formulations promise simultaneous gains in energy density and thermal stability for next-generation cardiac implants.
Industry Challenges
- Electrochemical engineering talent scarcity:Specialized expertise in sterilization-compatible cell design remains concentrated among legacy medical device suppliers, constraining new entrant scale-up velocity.
- 21 CFR Part 820 compliance timelines:FDA quality system validation protocols extend product development cycles, compressing window for technology refresh before patent expiration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Batteries Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lithium-Ion, Nickel-Metal Hydride, Lead Acid, Alkaline Application: Portable Devices, Implants, Surgical Instruments, Emergency Equipment End User: Hospitals, Clinics, Home Care, Laboratories Distribution Channel: Online Retail, Direct Sales, Distributors, Medical Supply Stores |
| Companies Covered | Panasonic Corporation, EnerSys, Ultralife Corporation, EaglePicher Technologies, Tadiran Batteries, VARTA Microbattery, Duracell, Integer Holdings Corporation, Saft Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Batteries Market Emerging Trajectories
Battery chemistry evolution is intersecting with sterilization protocol advancement and procurement consolidation to redefine competitive positioning across implantable and portable segments.
Solid-state lithium-metal architectures are overtaking liquid-electrolyte designs in next-generation implantable cardioverter-defibrillators. Cardiac rhythm management OEMs are accelerating qualification timelines for ceramic-polymer cells that eliminate thermal runaway risk. This chemistry shift is overtaking conventional lithium-ion dominance in premium implant tiers and compressing supplier qualification pools to vendors with thin-film deposition expertise.
REACH substance restrictions are tightening permissible electrolyte additive profiles for batteries distributed within European Economic Area markets. Manufacturers are reformulating biocompatible electrolyte systems to eliminate restricted phthalate plasticizers and heavy metal stabilizers. The portable diagnostic instrument segment is responding fastest, with German and French procurement groups now requiring full material disclosure documentation.
Integrated delivery networks are consolidating multi-state purchasing authority and unbundling battery procurement from device OEM service contracts. Hospital procurement groups are establishing direct supplier relationships for replacement cells, bypassing traditional equipment vendor markups. This channel disintermediation is most advanced in US Midwest health systems where group purchasing organizations have centralized cardiac implant battery logistics.
Medical Batteries Market Segmentation
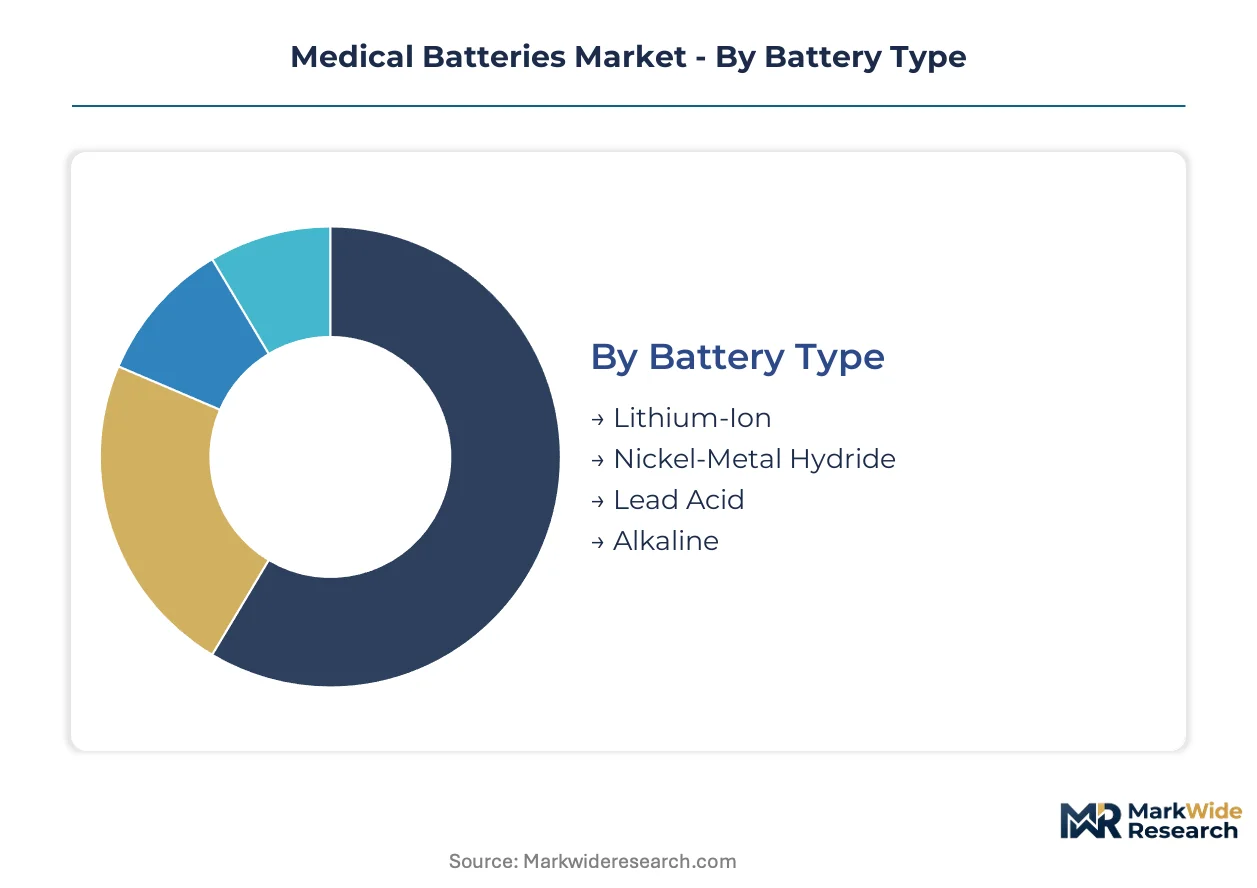
Medical battery procurement decisions split across chemistry performance, device integration requirements, and channel economics. Each segmentation dimension carries distinct regulatory burdens and margin structures that reshape supplier positioning.
Battery Type:
Lithium-ion platforms demand the heaviest upfront capital for cleanroom manufacturing and hermetic sealing infrastructure.
- Lithium-Ion:Solid-state and liquid-electrolyte architectures deliver superior energy density for implantable cardioverter-defibrillators and continuous glucose monitors. FDA validation protocols for these cells compress supplier pools to vendors with thin-film deposition expertise. German hospital procurement groups concentrate orders around established lithium-ion manufacturers with proven ISO 14708-1 certification pathways.
- Nickel-Metal Hydride:Lower energy density suits portable diagnostic instruments where cost sensitivity outweighs miniaturization needs. REACH substance restrictions are forcing electrolyte reformulations to eliminate restricted phthalate plasticizers. French and German procurement groups now require full material disclosure documentation for these cells.
- Lead Acid:Emergency backup power for hospital-grade uninterruptible power supplies retains share despite weight penalties.
- Alkaline:Disposable cells face displacement as operating rooms phase out single-use batteries to reduce per-procedure waste.
Most installed capacity flows through lithium-ion platforms. Expansion is steepest in solid-state lithium-metal architectures.
Application:
Implantable devices command premium pricing tiers tied to biocompatibility validation depth.
- Implants:Cardiac rhythm management and neurostimulation devices require hermetic sealing and biocompatible electrolyte formulations to prevent tissue leakage. Solid-state battery architectures are compressing replacement cycles while elevating thermal stability. BfArM quality benchmarks in Germany concentrate procurement around suppliers with proven multi-year implant track records.
- Portable Devices:Wearable diagnostic patches and patient monitors favor thin-cell lithium platforms capable of multi-year skin-contact operation. Integrated delivery networks in the US Midwest are consolidating purchasing authority and establishing direct supplier relationships to bypass equipment vendor markups.
- Surgical Instruments:Rechargeable lithium-ion architectures are displacing disposable alkaline cells as waste reduction mandates tighten.
- Emergency Equipment:Defibrillators and ventilator backup systems prioritize instantaneous power delivery over energy density optimization.
Revenue concentrates in implantable tiers. Portable diagnostic applications are climbing the fastest.
End User:
Hospital procurement groups wield consolidated purchasing power across multi-state systems.
- Hospitals:Integrated delivery networks unbundle battery procurement from device OEM service contracts and centralize logistics for cardiac implant replacements. Group purchasing organizations in the US Midwest have established direct supplier relationships for replacement cells.
- Clinics:Outpatient diagnostic centers specify nickel-metal hydride for cost-sensitive portable instruments.
- Home Care:Continuous glucose monitor users generate sustained demand for thin-cell lithium platforms with multi-year operational lifespans.
- Laboratories:Analytical instruments require stable voltage output under varying sterilization temperature exposure.
Procurement volume aggregates in hospital systems. Home care applications are expanding most quickly.
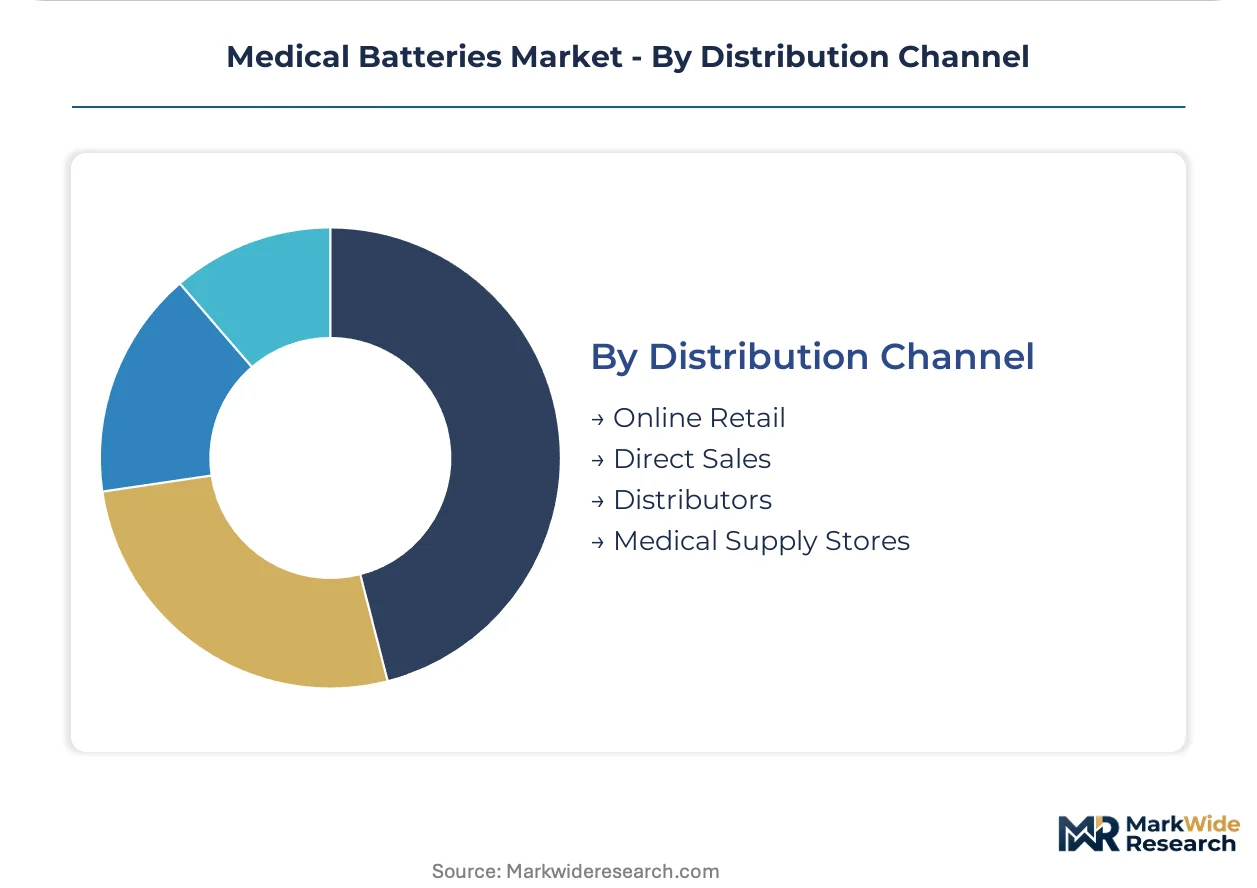
Distribution Channel:
Channel selection determines margin capture and regulatory documentation burden.
- Direct Sales:OEM anchor contracts with Panasonic and EnerSys bypass distributor markups and secure volume commitments for cylindrical and thin-cell lithium platforms. These relationships dominate implantable and patient monitor segments.
- Distributors:Regional medical supply distributors handle fragmented clinic and laboratory demand with lower minimum order quantities.
- Online Retail:E-commerce penetration remains limited to replacement batteries for consumer-facing portable devices.
- Medical Supply Stores:Brick-and-mortar channels serve emergency equipment procurement with immediate availability requirements.
Direct sales channels capture the majority of implantable battery value. Online retail is gaining share fastest in portable device replacement segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates procurement authority around BfArM-certified suppliers while the United States fragments purchasing across competing integrated delivery networks. Japan's METI circular economy frameworks are reshaping end-of-life battery logistics. China's NMPA is accelerating domestic qualification timelines for implantable power systems.
United States
Hospital procurement groups across the Midwest and Southeast are consolidating multi-state purchasing authority for cardiac implant batteries. FDA enforcement of 21 CFR Part 820 quality system regulations extends product development cycles and elevates R&D expenditure requirements. The Boston-Cambridge medical device cluster anchors solid-state battery qualification programs for next-generation neurostimulation devices.
Germany
BfArM quality benchmarks concentrate hospital procurement decisions around established lithium-ion suppliers with proven hermetic sealing capabilities. REACH substance restrictions are forcing electrolyte reformulations to eliminate restricted phthalate plasticizers from nickel-metal hydride cells. The Baden-Württemberg industrial corridor hosts thin-film deposition facilities serving cardiac rhythm management OEMs.
Japan
METI circular economy frameworks are opening service-revenue streams for manufacturers establishing reverse logistics networks for end-of-life medical batteries. PMDA post-market surveillance requirements align with EU MDR timelines, accelerating supplier qualification standardization. The Kanto region around Tokyo anchors cylindrical cell production for patient monitor OEM contracts.
China
NMPA is tightening validation protocols for implantable battery architectures while domestic demand for continuous glucose monitors expands. GB standards for active implantable medical devices are converging toward ISO 14708-1 voltage stability thresholds. The Yangtze River Delta manufacturing belt is scaling cleanroom infrastructure for solid-state lithium-metal cell production.
Switzerland
Swissmedic certification requirements for cardiac rhythm management devices favor suppliers with multi-year implant track records and biocompatible electrolyte formulations. The country's precision manufacturing heritage supports hermetic sealing expertise for premium implant tiers. Basel-Zurich corridor facilities specialize in ceramic-polymer hybrid electrolyte development for next-generation defibrillator applications.
Medical Batteries Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across chemistry, application, and channel dimensions. Panasonic Corporation leverages cylindrical cell expertise to anchor OEM contracts, while EnerSys competes through thin-cell lithium platforms for wearable diagnostics. The vendor base stratifies into three archetypes: diversified electronics conglomerates, dedicated battery manufacturers, and medical-device-integrated suppliers. Competitive moves concentrate on strategic partnerships with cardiac rhythm management OEMs and capacity expansion in solid-state thin-film deposition.
Among diversified conglomerates, Panasonic Corporation occupies a position exemplifying cylindrical cell dominance in patient monitor applications. EnerSys and Ultralife Corporation represent contrasting specialization vectors within the dedicated battery manufacturer tier—EnerSys anchors thin-cell lithium platforms for wearable diagnostic patches, while Ultralife exemplifies military-grade reliability standards translated into extended-cycle cardiac implants. These three companies collectively illustrate the competitive spectrum from scale-driven electronics integration to niche reliability engineering.
| Leading Market Players |
|---|
| Panasonic Corporation |
| EnerSys |
| Ultralife Corporation |
| EaglePicher Technologies |
| Tadiran Batteries |
| VARTA Microbattery |
| Duracell |
| Integer Holdings Corporation |
| Saft Group |
| Others |
Supply Flow & Price Mechanics
Integrated delivery networks and hospital procurement groups concentrate purchasing authority across multi-state systems, anchoring contract-based long-term offtake pricing that favors lithium-ion suppliers with proven FDA validation pathways. This buyer concentration compresses margin capture for mid-tier entrants while rewarding established vendors with hermetic sealing expertise and ISO 14708-1 certification depth.
Pricing Analysis
Capacity additions in China's Yangtze River Delta manufacturing belt are reshaping price floors for solid-state lithium-metal cells used in cardiac rhythm management devices. Three-tier pricing structure across premium, standard, and economy levels separates vendors by FDA validation tier and hermetic sealing capability. Price differentiation hinges on certification grade and volume scale, with German hospital procurement groups commanding the steepest discounts through consolidated purchasing. Cost compression in nickel-metal hydride portable diagnostic tiers is intensifying because REACH substance restrictions force electrolyte reformulations. Clinics and outpatient diagnostic centers exhibit the highest price sensitivity, while implantable device OEMs prioritize reliability over unit cost.
Supply Chain Analysis
Electrochemical engineering talent scarcity in thin-film deposition disciplines constrains cleanroom manufacturing scale-up across Germany, Japan, and South Korea. Lithium carbonate and cobalt sulfate feedstock sourcing draws from Chilean and Indonesian processing hubs, while ceramic-polymer electrolyte precursors rest on Japanese specialty chemical suppliers. Single-source vulnerability in solid-state electrolyte precursor supply exposes manufacturers to geopolitical disruption risk. Distribution runs through direct OEM anchor contracts for implantable tiers, with regional medical supply distributors handling fragmented clinic demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Manufacturers can exploit geographic arbitrage between Germany's stringent BfArM quality benchmarks and China's accelerating NMPA qualification timelines, capturing margin differential through dual-registered production facilities. This regulatory spread rewards battery suppliers with parallel certification pathways across both jurisdictions.
For Market Incumbents: Hedge against solid-state electrolyte convergence by securing thin-film deposition talent pools in Japan's Kanto region and Germany's Baden-Württemberg corridor. Backward integration into ceramic-polymer precursor supply buffers raw material volatility. Capacity expansion in China aligns with NMPA domestic qualification acceleration while maintaining BfArM-certified European production for premium implant tiers.
For New Entrants and Emerging Players: Launch via direct sales to integrated delivery networks in the US Midwest that have unbundled battery procurement from device OEM service contracts. Portable diagnostic instruments specify nickel-metal hydride for cost-sensitive applications, presenting the most penetrable segment. Target home care continuous glucose monitor replacement demand with thin-cell lithium platforms capable of multi-year skin-contact operation.
For Investors and Strategic Acquirers: Cardiac rhythm management OEMs represent the most active acquirer in this space, seeking captive battery supply for next-generation implantable cardioverter-defibrillator programs. Acquisition targets with proven FDA 21 CFR Part 820 compliance and ISO 14708-1 certification pathways offer viable long-term positioning. Watch for inflection in METI circular economy framework adoption rates, which signal service-revenue stream viability through reverse logistics networks.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission Pathway | 21 CFR Part 820 quality system validation compresses supplier pools to compliant vendors. |
| CE Marking Pathway | EU MDR post-market surveillance mandates elevate ISO 14708-1 certification requirements. |
| Hospital System Partnership | Integrated delivery network consolidation creates direct supplier relationship opportunities. |
| Backward Integration | Ceramic-polymer precursor supply control buffers lithium carbonate price volatility. |
| Reimbursement Strategy | German Diagnosis-Related Group coding alignment secures BfArM procurement preference. |
Methodological Framework
Multiple input streams — primary interviews with biomedical engineers, hospital purchasing committees, and GPO contracts managers; secondary validation against FDA 510(k) filings, BfArM device registrations, and hospital procurement databases — were reconciled through bottom-up and top-down triangulation. Clinical stakeholders provided implantable device performance benchmarks, while supply chain contacts detailed thin-film deposition capacity constraints. Trade data from German and Japanese customs authorities supplemented secondary source validation.
Historical shipment volumes were cross-referenced against expert panel inputs to construct the analytical framework across the analysis window. Segmentation dimensions modeled include battery chemistry tier, device application class, end-user procurement authority, and regional regulatory cluster. CAGRs were derived through iterative convergence of supply-side capacity buildout assumptions and demand-side adoption curves for continuous glucose monitors and rechargeable surgical instruments. Solid-state electrolyte technology readiness levels and REACH substance restriction timelines informed chemistry-transition assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under lithium supply disruption or accelerated EU MDR enforcement scenarios. Material deviation in FDA validation protocol stringency or METI circular economy incentive structures warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Asia-Pacific Rechargeable Battery Market
Batteries
Modular Battery Pack Market
Batteries
PVT Battery Panel Market
Batteries
Cobalt-Free Battery Market
Batteries
United States SLI Battery Market
Batteries
Mobile Battery Market
Batteries
Australia Battery Market
Batteries
Vanadium Redox Batteries Market
Batteries
Smart Battery Market
Batteries
North America Lead Acid Battery Market
Batteries
Industrial Battery Charger Market
Batteries
South and Central America Battery Market
Batteries
Silicon Battery Market
Batteries
India Rechargeable Battery Market
Batteries
Middle-East Battery Market
Batteries
Carbon Foam Battery Market