
 Lead Acid Battery Market | 2026-2036
Lead Acid Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Lead Acid Battery Market Analysis
Modular rack configurations for data-center UPS installations is restructuring procurement patterns among enterprise buyers. EnerSys leverages its North American manufacturing footprint to supply pre-assembled cabinet systems with embedded monitoring. Clarios sustains its position through captive lead recycling and closed-loop material recovery. GS Yuasa anchors Asian utility-scale deployments with region-specific cell geometries.
A lead acid battery stores electrical energy through reversible electrochemical reactions between lead dioxide positive plates, sponge lead negative plates, and sulfuric acid electrolyte, typically operating at nominal voltages of 2V per cell with energy densities of 30–50 Wh/kg. The device serves as a cost-effective source of high surge currents for engine starting and provides backup power for critical infrastructure. Flooded cells still occupy the largest share of automotive starter applications due to established recycling infrastructure and low unit cost. VRLA designs are gaining share in UPS and renewable energy storage where maintenance-free operation and sealed construction reduce total cost of ownership. Gel electrolyte variants compete in marine and remote telecom installations where vibration resistance and deep-cycle durability justify price premiums.
EPA hazardous waste rules under RCRA govern spent battery collection and smelter emissions in the United States, while REACH restrictions in Europe limit lead compound exposure across the manufacturing chain. India's BIS certification requirements and China's GB/T standards enforce dimensional and performance consistency for domestic supply. Stakeholders must track regulatory tightening on lead smelter permits and recycling quotas as these determine regional cost structures and supply availability.
Market Dynamics
Lead smelter permit restrictions across India, China, and the United States are compressing primary lead availability and forcing battery manufacturers toward captive recycling infrastructure. This regulatory chokepoint is restructuring cost curves and geographic production decisions.
Growth Catalysts
- Automotive OEM starter-lighting-ignition specifications:Passenger and commercial vehicle platforms continue to specify flooded lead acid units for engine cranking duty cycles due to cold-cranking amperage reliability and established service networks.
- India's BIS certification mandates:Dimensional and heavy-metal content standards are formalizing domestic supply chains and disqualifying informal imports, consolidating demand around certified foundries in Pune and Gujarat.
- Data-center UPS rack standardization:Modular cabinet configurations with embedded monitoring are expanding addressable demand among enterprise buyers seeking maintenance-free backup power with predictable replacement cycles.
Market Restraints
- Primary lead smelter concentration:Foundry capacity clusters in China's Henan province and India's Rajasthan create geographic supply vulnerability to environmental shutdowns.
- Lithium iron phosphate substitution:Declining cell costs and energy density advantages are capturing two-wheeler electrification and residential solar storage applications.
- REACH lead compound exposure limits:European manufacturing chain restrictions raise compliance costs for export-oriented producers serving EU automotive customers.
Strategic Opportunities
- Telecom tower rural electrification:Off-grid and unreliable-grid installations across India's northeastern states present demand for deep-cycle gel batteries with 8-10 year service life.
- Renewable energy storage coupling:Solar-wind hybrid microgrids in sub-Saharan Africa and Southeast Asia are specifying VRLA banks for frequency regulation and ride-through capacity.
- Closed-loop recycling mandates:China's dual carbon goals and extended producer responsibility frameworks reward manufacturers with in-house smelting and paste recovery capabilities.
Industry Challenges
- Foundry environmental compliance capex:Baghouse filtration and acid recovery system upgrades require capital deployment that strains mid-tier assemblers without captive lead supply.
- BIS certification timeline compression:Testing laboratory bottlenecks and documentation requirements delay product launches for new entrants targeting India's replacement market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lead Acid Battery Market |
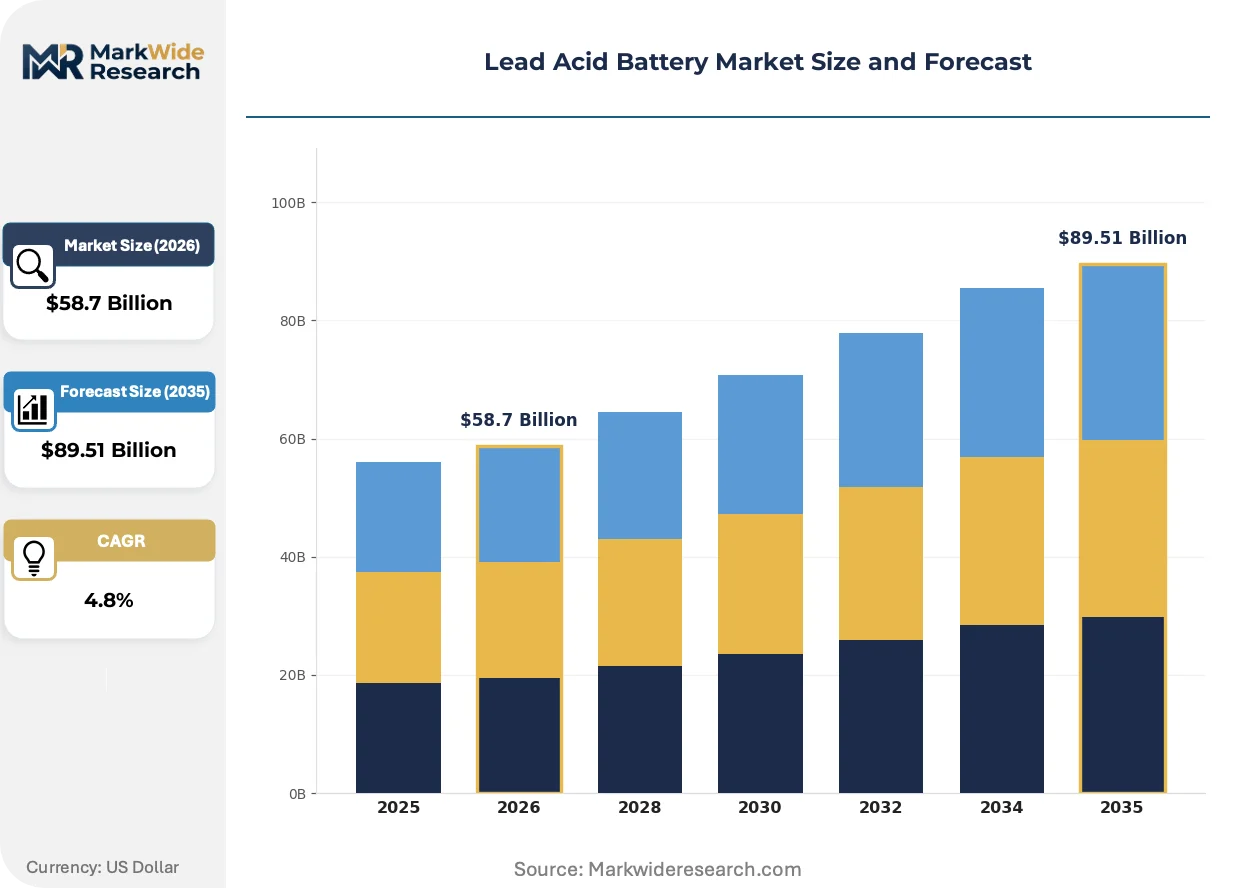
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $89.51 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SLA, Flooded, VRLA, Gel End User: Automotive, UPS, Renewable Energy, Marine Capacity: Low Capacity, Medium Capacity, High Capacity, Extra High Capacity Installation: Portable, Stationary, OEM, Aftermarket |
| Companies Covered | EnerSys, East Penn Manufacturing Company, Exide Technologies, CSB Energy Technology, Leoch International Technology, GS Yuasa, Amara Raja Energy & Mobility, NPP Power Group, Clarios, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lead Acid Battery Market Emerging Trajectories
Carbon additive formulations and automated plate stacking are compressing manufacturing variance and extending cycle life in deep-cycle applications. These process refinements are reshaping competitive differentiation beyond unit cost.
Lead-carbon hybrid chemistry is consolidating in stationary energy storage installations where partial state-of-charge operation and rapid recharge capability outweigh pure lead acid economics. Microgrid developers and telecom infrastructure operators are specifying these cells for cyclic duty in solar-diesel hybrid configurations. The technology is consolidating market share in applications previously served by premium gel or absorbed glass mat designs.
China's GB/T performance and dimensional standards are tightening interoperability requirements for domestic supply chains, forcing export-oriented manufacturers to maintain parallel SKU portfolios. The regulations are accelerating consolidation among smaller foundries unable to absorb compliance testing costs. Domestic battery assemblers serving the automotive aftermarket are the most affected, with many outsourcing plate production to certified tier-one suppliers.
Enterprise buyers in data-center and critical infrastructure verticals are unbundling battery procurement from turnkey UPS contracts, creating direct relationships with cell manufacturers for replacement cycle planning. This disintermediation compresses distributor margins and rewards suppliers with predictive monitoring platforms and regional service depots. The pattern is most visible in North American and Western European markets where total cost of ownership modeling dominates capital allocation decisions.
Lead Acid Battery Market Segmentation
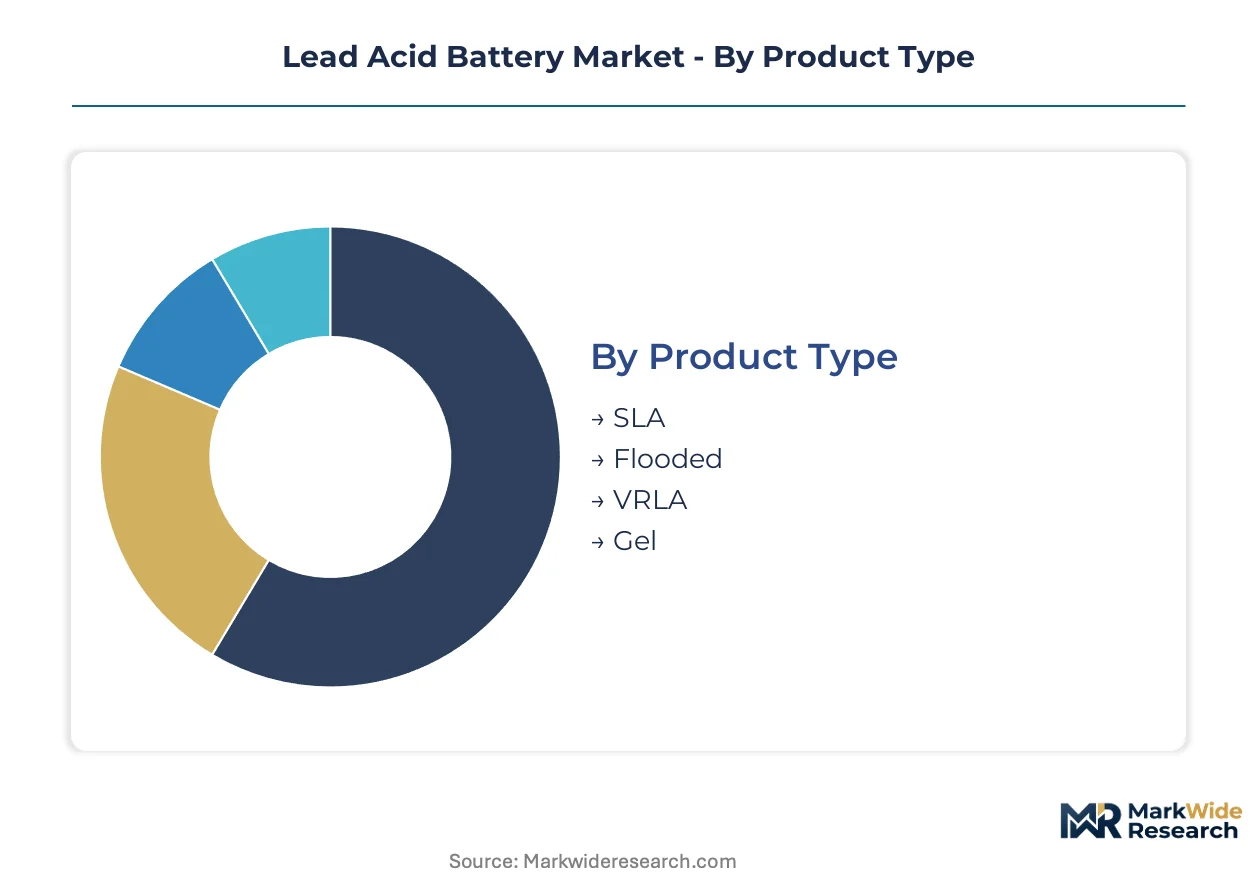
Segmentation in lead acid batteries reveals how chemistry choices, capacity thresholds, and channel configurations map to divergent margin structures and replacement cycle economics. Understanding these splits enables suppliers to align foundry output with specific duty-cycle requirements and regulatory compliance burdens.
Product Type:
Flooded cells dominate unit volume through automotive starter applications, while sealed variants command premium positioning in maintenance-sensitive installations.
- Flooded:Open-vented construction with liquid electrolyte enables high surge current delivery for engine cranking. Demand clusters in passenger vehicle OEM specifications across India and China, where established recycling infrastructure sustains total cost advantages.
- VRLA:Valve-regulated recombinant chemistry eliminates watering requirements through oxygen recombination at the negative plate. UPS and data-center buyers in North America specify these for rack-mounted installations where accessibility constraints favor sealed construction.
- SLA:Sealed lead acid variants serve price-sensitive backup power applications with simplified handling protocols. Small-format SLA units power emergency lighting and security systems where installation density favors compact footprints.
- Gel:Silica-thickened electrolyte resists stratification and thermal runaway in deep-cycle duty. Marine and off-grid solar installers in sub-Saharan Africa specify gel cells for vibration tolerance and extended cycle life in partial state-of-charge operation.
Mature deployment sits with Flooded. Newer deployment is concentrated in VRLA.
End User:
Application-driven segmentation separates high-frequency replacement cycles from decade-long service intervals, reshaping how manufacturers configure distribution and service networks.
- Automotive:Starter-lighting-ignition duty cycles demand cold-cranking amperage reliability and tolerance for temperature extremes. OEM specifications in India, China, and the United States continue to specify flooded lead acid for passenger and commercial platforms due to service network density and established reverse logistics.
- UPS:Uninterruptible power supply installations require float service compatibility and predictable end-of-life signaling. Enterprise data-center operators in North America and Western Europe are unbundling battery procurement from turnkey contracts, creating direct supplier relationships for replacement planning.
- Renewable Energy:Solar-wind hybrid microgrids specify deep-cycle tolerance and daily cycling capability. Rural electrification projects across India's northeastern states and Southeast Asian archipelagos drive demand for gel and lead-carbon hybrid configurations.
- Marine:Vibration resistance and spill-proof certification dominate specification criteria. Leisure craft and commercial fishing fleets in Mediterranean and Southeast Asian waters favor sealed gel constructions for safety compliance in enclosed hull compartments.
Replacement frequency peaks in Automotive. Steepest expansion trajectory appears in Renewable Energy.
Capacity:
Energy content thresholds determine manufacturing equipment scale, with high-capacity cells requiring specialized plate curing and formation infrastructure.
- Low Capacity:Sub-20 Ah units serve motorcycle starting, portable power tools, and small-scale backup applications. Two-wheeler electrification in India and Southeast Asia is compressing demand for these formats as lithium alternatives capture new vehicle sales.
- Medium Capacity:20-100 Ah range covers passenger vehicle starting, residential solar storage, and small UPS installations. This band represents the highest production volume globally, with foundries in China's Henan province and India's Rajasthan optimizing lines for standardized plate dimensions.
- High Capacity:100-200 Ah cells anchor commercial vehicle starting, telecom tower backup, and industrial UPS banks. Telecom infrastructure operators in India specify these for 8-10 year service life in off-grid and unreliable-grid installations.
- Extra High Capacity:Above 200 Ah units serve motive power for forklifts, golf carts, and renewable energy storage at utility scale. Regional logistics hubs and solar-diesel microgrids in sub-Saharan Africa specify these for deep-cycle durability in cyclic duty applications.
Volume concentration rests in Medium Capacity. Margin expansion concentrates in Extra High Capacity.
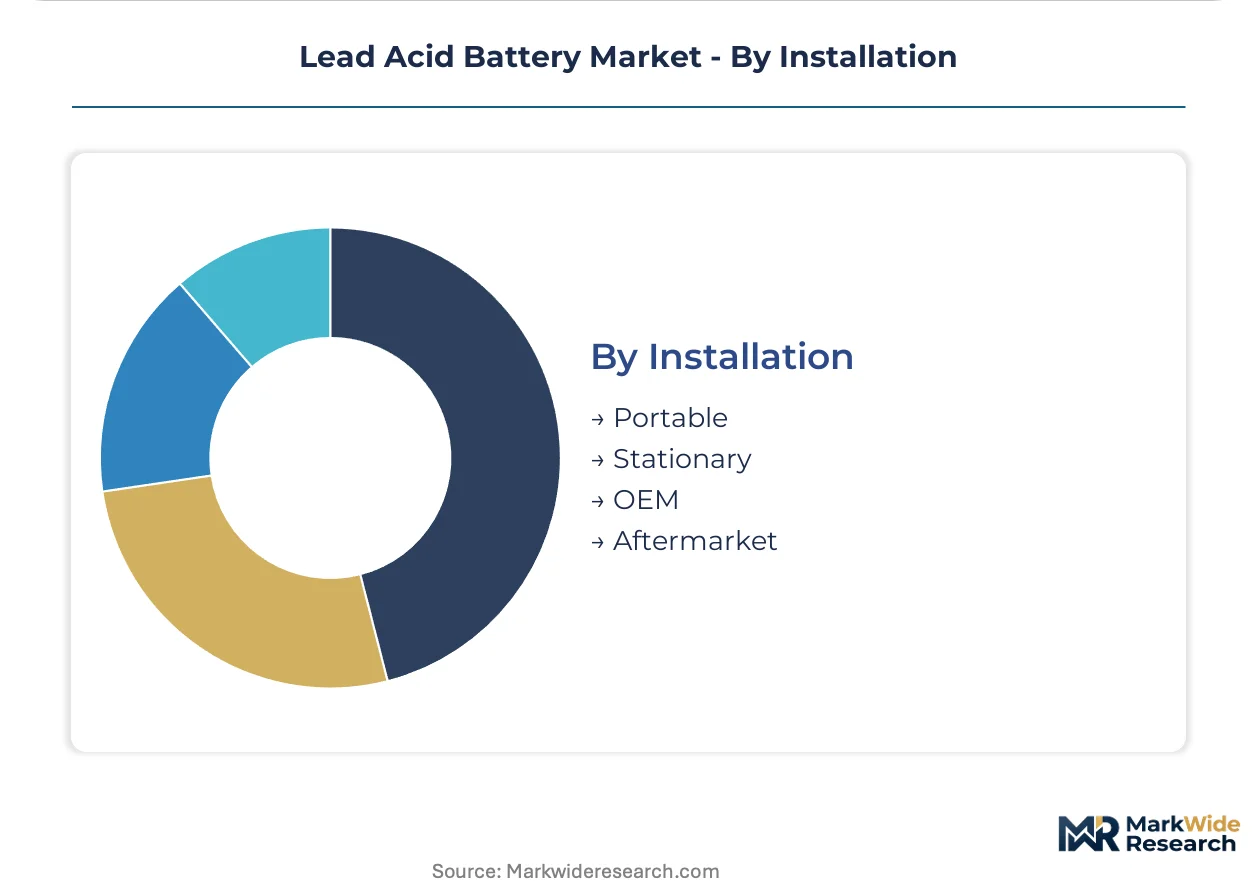
Installation:
Channel configuration determines warranty liability, technical support requirements, and the feasibility of closed-loop recycling arrangements.
- OEM:Original equipment supply demands traceability, batch consistency, and collaborative design integration with vehicle electrical systems. Automotive OEMs in India, China, and the United States specify flooded cells through long-term supply agreements with foundries holding BIS, GB/T, or equivalent certifications.
- Aftermarket:Replacement sales flow through distributor networks, retail auto parts chains, and independent service garages. India's western industrial corridor around Pune and Gujarat anchors domestic aftermarket consolidation as BIS certification mandates disqualify informal imports.
- Stationary:Fixed installations in data centers, telecom shelters, and utility substations require rack integration and remote monitoring compatibility. Modular cabinet configurations with embedded sensors are restructuring procurement patterns among enterprise buyers.
- Portable:Mobile applications encompass recreational vehicles, marine craft, and field-deployed equipment where handling weight and spill containment matter. Leisure market distributors in North America and Europe stock sealed AGM and gel variants for consumer safety preferences.
Revenue stability characterizes OEM. Channel margin compression affects Aftermarket.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China produces the majority of global lead acid capacity while India and the United States absorb the largest consumption volumes. This production-consumption divide shapes freight economics and regional compliance strategies across the value chain.
China
Foundry capacity clusters in Henan province supply domestic automotive OEMs and export markets with standardized plate dimensions. GB/T standards enforce dimensional and performance consistency, disqualifying smaller foundries from automotive supply chains. Manufacturers in the Yangtze River Delta maintain parallel SKU portfolios to serve both domestic and export specifications.
India
Automotive OEM specifications and telecom tower rural electrification drive demand across western and northeastern corridors. BIS certification mandates formalize domestic supply chains and disqualify informal imports. Foundries in Pune and Gujarat consolidate certified production capacity as replacement market demand concentrates in the western industrial corridor.
United States
Data-center UPS installations and automotive starter applications anchor consumption across enterprise and OEM channels. EPA hazardous waste rules under RCRA govern spent battery collection and smelter emissions. Pre-assembled cabinet systems with embedded monitoring ship from North American manufacturing footprints serving enterprise buyers.
Germany
Industrial UPS and motive power applications for forklifts sustain demand among manufacturing and logistics operators. REACH restrictions limit lead compound exposure across the manufacturing chain, raising compliance costs for export-oriented producers. Battery assemblers serving EU automotive customers maintain documentation protocols for cross-border material traceability.
Japan
Stationary energy storage and industrial backup power applications specify region-specific cell geometries for utility-scale deployments. METI guidelines shape extended producer responsibility frameworks and recycling quota enforcement. Manufacturers anchor Asian utility-scale deployments with chemistry variants optimized for local grid stabilization requirements.
Lead Acid Battery Market Vendor Landscape
The competitive structure tilts toward vertically integrated specialists with captive recycling infrastructure and foundry control. Tier-one suppliers with in-house smelting and paste recovery capabilities command cost advantages as primary lead availability tightens. Three archetypes dominate: integrated battery-smelter operators, pure-play assemblers sourcing certified plates, and regional specialists serving aftermarket replacement cycles. Consolidation accelerates through foundry acquisitions and strategic partnerships for closed-loop material recovery.
Among integrated operators, EnerSys and Clarios exemplify the captive recycling archetype with North American manufacturing footprints and pre-assembled system capabilities. GS Yuasa anchors Asian utility-scale deployments with region-specific cell geometries. These three occupy positions defined by geographic manufacturing concentration and direct relationships with enterprise buyers unbundling battery procurement from turnkey contracts.
| Leading Market Players |
|---|
| EnerSys |
| East Penn Manufacturing Company |
| Exide Technologies |
| CSB Energy Technology |
| Leoch International Technology |
| GS Yuasa |
| Amara Raja Energy & Mobility |
| NPP Power Group |
| Clarios |
| Others |
Supply Flow & Price Mechanics
Foundry labor pools in India's Rajasthan and China's Henan province anchor cost structures across pricing tiers, with wage differentials between these clusters translating into 15-20 point spreads between economy-grade flooded cells and premium VRLA configurations for data-center buyers.
Pricing Analysis
Margin tightening in economy flooded cells reflects lithium iron phosphate substitution in two-wheeler starting applications and compressed replacement cycles. Three-tier pricing structure across premium, standard, and economy levels separates BIS-certified OEM supply from aftermarket imports and grey-channel units. Price differentiation hinges on certification grade and captive recycling integration. Automotive OEM buyers in India exhibit lowest price sensitivity due to specification lock-in, while telecom tower operators in sub-Saharan Africa prioritize unit cost over cycle life.
Supply Chain Analysis
Reverse logistics for spent battery collection and smelter feedstock recovery determines regional cost competitiveness. Primary supply concentrates in China, India, and the United States, with foundry output drawing from lead concentrate imports, secondary scrap recovery, and captive paste reclamation. Single-source vulnerability sits with China's Henan province smelter cluster. Distribution runs through OEM direct contracts, aftermarket distributor networks, and enterprise procurement platforms for data-center rack systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive smelting and closed-loop material recovery determine margin survival. Players securing upstream foundry control or downstream recycling infrastructure capture structural cost advantages as primary lead availability tightens.
For Market Incumbents: Anticipate lithium substitution in automotive starting applications by accelerating lead-carbon hybrid chemistry development and securing BIS certification for Indian aftermarket consolidation. Prioritize captive recycling infrastructure in Rajasthan and Henan to offset primary lead smelter permit restrictions. Defend OEM relationships through collaborative design integration for next-generation vehicle electrical architectures. For New Entrants and Emerging Players: Launch via direct enterprise procurement relationships for data-center UPS replacement cycles, bypassing traditional distributor channels. Target telecom tower rural electrification across India's northeastern states with gel battery offerings optimized for 8-10 year service life. Pursue white-label manufacturing partnerships with certified foundries in Pune and Gujarat to circumvent BIS testing laboratory bottlenecks. For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier assemblers possessing in-house smelting and paste recovery capabilities given China's dual carbon goals and extended producer responsibility enforcement. Long-term viability favors operators with backward integration into lead recycling rather than pure-play assembly. Monitor BIS certification timeline compression and foundry environmental compliance capex requirements as inflection indicators for consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Recycling Infrastructure | Closed-loop material recovery secures feedstock supply as primary lead smelter permits tighten under EPA RCRA and MEE enforcement. |
| BIS Certification Acceleration | Formal compliance with India's dimensional and heavy-metal standards disqualifies informal imports and consolidates replacement market share. |
| Lead-Carbon Hybrid Chemistry | Partial state-of-charge operation and rapid recharge capability defend stationary storage applications against lithium substitution. |
| Modular Rack System Integration | Pre-assembled cabinet configurations with embedded monitoring capture enterprise UPS procurement unbundling from turnkey contracts. |
| Regional Foundry Consolidation | Acquisition of certified plate production capacity in Henan and Rajasthan secures supply chain control amid environmental permit restrictions. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with foundry operations managers, automotive OEM procurement leads, telecom infrastructure operators, and aftermarket distributor principals. Secondary sources encompassed BIS certification databases, EPA RCRA enforcement records, GB/T standards documentation, and lead concentrate import manifests. Bottom-up cell-level production estimates triangulated against top-down regional consumption models.
Data-stream reconciliation across shipment volumes, smelter output, and replacement cycle frequencies informed the analytical framework. Segmentation dimensions spanned product chemistry, end-use application, capacity tier, and installation channel. CAGRs derived from regression analysis of historical foundry capacity expansion, OEM specification persistence, and lithium substitution elasticities across two-wheeler and residential storage segments.
Environmental permit revocation, lithium cell cost trajectories, and BIS certification timeline delays are the dominant revision risks to forecast assumptions. Practitioners should monitor MEE enforcement intensity, LFP pricing in Indian two-wheeler markets, and testing laboratory queue lengths for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Global Electric Scooter Batteries Market
Batteries
Liquid Metal Battery Market
Batteries
Carbon Black in Lead-Acid Battery Market
Batteries
Consumer Battery Market
Batteries
Battery Pack Balancer Market
Batteries
Iron-Chromium Flow Battery Market
Batteries
Middle-East and North Africa Rechargeable Battery Market
Batteries
Marine Powerboat Battery Market
Batteries
Asia Pacific Electric Vehicle VRLA Batteries Market
Batteries
Automotive AGM Battery Market
Batteries
Asia-Pacific NMC Battery Pack Market
Batteries
Europe Rechargeable Battery Market
Batteries
Modular Battery Pack Platforms for Skateboard EVs Market
Batteries
Coin Cell Lithium Batteries Market
Batteries
Drone Lithium Battery Charger Market
Batteries
Zinc-Manganese Oxide Batteries Market