
 Secondary Battery Market | 2026-2036
Secondary Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Secondary Battery Market Intelligence
Solid-state electrolyte development is reconfiguring how cell manufacturers design thermal management and packaging architectures. CATL leverages its position in lithium-iron-phosphate chemistry to anchor utility-scale energy storage contracts across multiple continents. Samsung SDI Co. Ltd. competes through differentiated cylindrical cell formats optimized for premium electric vehicle platforms.
Secondary batteries are electrochemical storage devices designed for repeated charge-discharge cycling, typically employing lithium-ion, nickel-metal hydride, or lead-acid chemistries with energy densities ranging from 30 Wh/kg to over 250 Wh/kg depending on cathode composition. These systems store electrical energy through reversible redox reactions and discharge it on demand for motive power, grid stabilization, or portable electronics. Lithium-ion technology dominates the automotive application segment due to its superior gravimetric energy density and declining cell cost curves. Lead-acid technology retains structural share in uninterruptible power supply systems where capital cost sensitivity outweighs cycle life requirements. Solid-state technology within the broader technology taxonomy represents the fastest-expanding research priority as manufacturers pursue higher voltage stability and reduced flammability profiles.
The US EPA tailpipe emission standards and the EU Green Deal carbon neutrality framework are tightening compliance thresholds for automotive OEMs, directly accelerating electrification procurement timelines. China's MIIT dual carbon goals and GB standards for new energy vehicle safety mandate specific cell testing protocols that shape export qualification requirements. South Korea's MFDS battery safety certification and Japan's METI subsidy structures for solid-state R&D create divergent but equally consequential market access conditions. Stakeholders must monitor which regulatory jurisdiction sets the most stringent thermal runaway testing standard, as that benchmark will cascade into global supply chain qualification requirements.
Market Dynamics
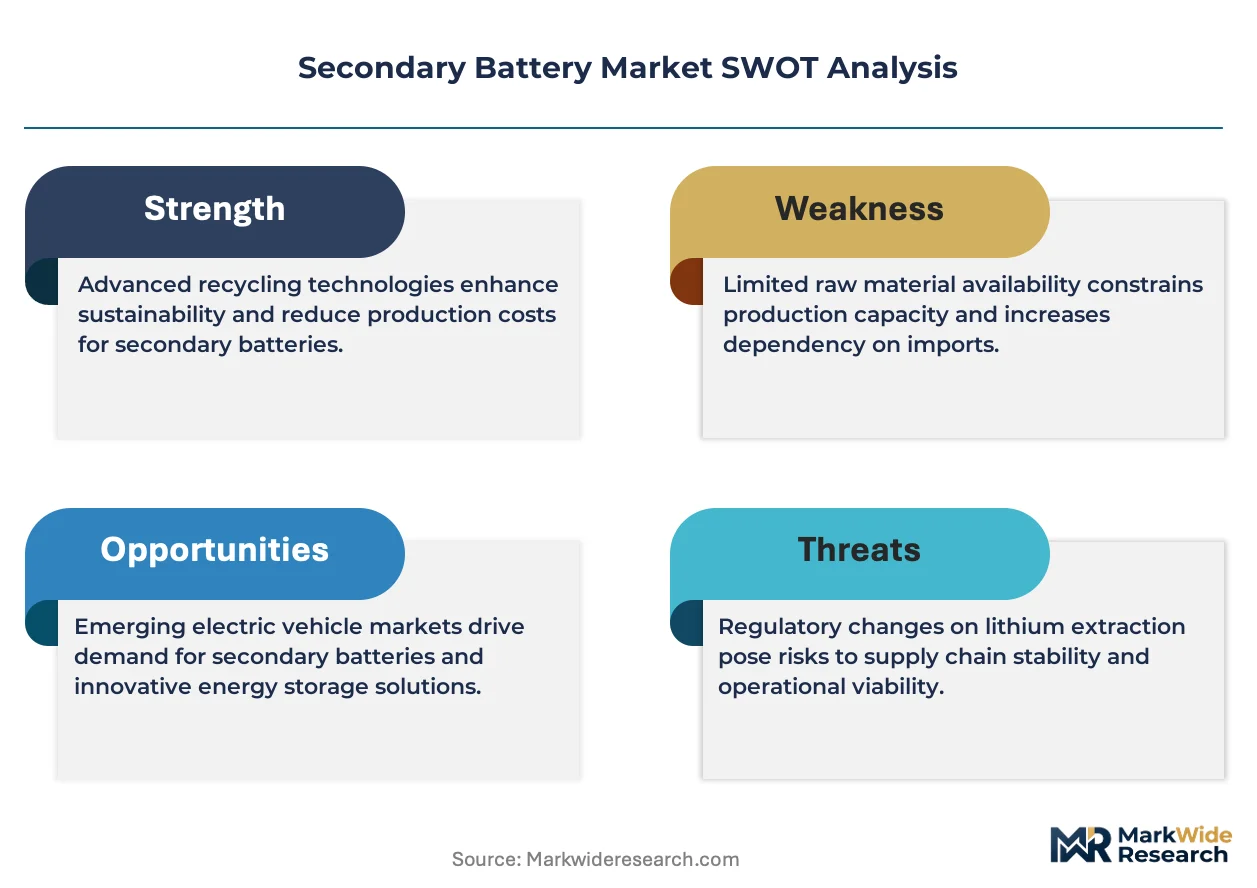
Solid-state electrolyte chemistry is forcing wholesale redesign of cell manufacturing lines, thermal management systems, and pack integration protocols across automotive and stationary storage supply chains.
Growth Catalysts
- US EPA tailpipe standards:Tightening emission thresholds are compressing electrification timelines for passenger vehicle OEMs and accelerating lithium-ion procurement volumes.
- Stationary energy storage:Grid operators across multiple continents are mandating battery-backed frequency regulation to accommodate renewable intermittency.
- Lithium-iron-phosphate cathodes:Improved cycle stability and reduced thermal runaway risk are opening utility-scale contracts previously reserved for alternative chemistries.
Market Restraints
- Lithium carbonate volatility:Concentrated South American brine extraction creates input cost instability that compresses cell manufacturer margins.
- Electrolyte supply concentration:Liquid electrolyte production clusters in China and South Korea generate single-source vulnerability for non-integrated pack assemblers.
- Solid-state manufacturing yield:Ceramic electrolyte sintering defects currently constrain batch consistency below commercial scale requirements.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for advanced chemistry cell manufacturing are attracting gigafactory investment outside established East Asian production zones.
- Marine electrification:Harbor craft and short-route ferries represent an underpenetrated application segment with distinct thermal and vibration specifications.
- Second-life stationary reuse:Retired automotive packs are converging with grid storage applications through standardized state-of-health testing protocols.
Industry Challenges
- Electrochemist talent scarcity:Solid-state R&D programs compete for limited pools of specialists with semiconductor and materials science backgrounds.
- Multi-jurisdiction certification:Divergent thermal runaway testing protocols across China's MIIT, South Korea's MFDS, and Japan's METI extend product qualification timelines.
- Dry electrode coating scale-up:Solvent-free manufacturing equipment requires capital deployment at scales unproven outside pilot facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Secondary Battery Market |
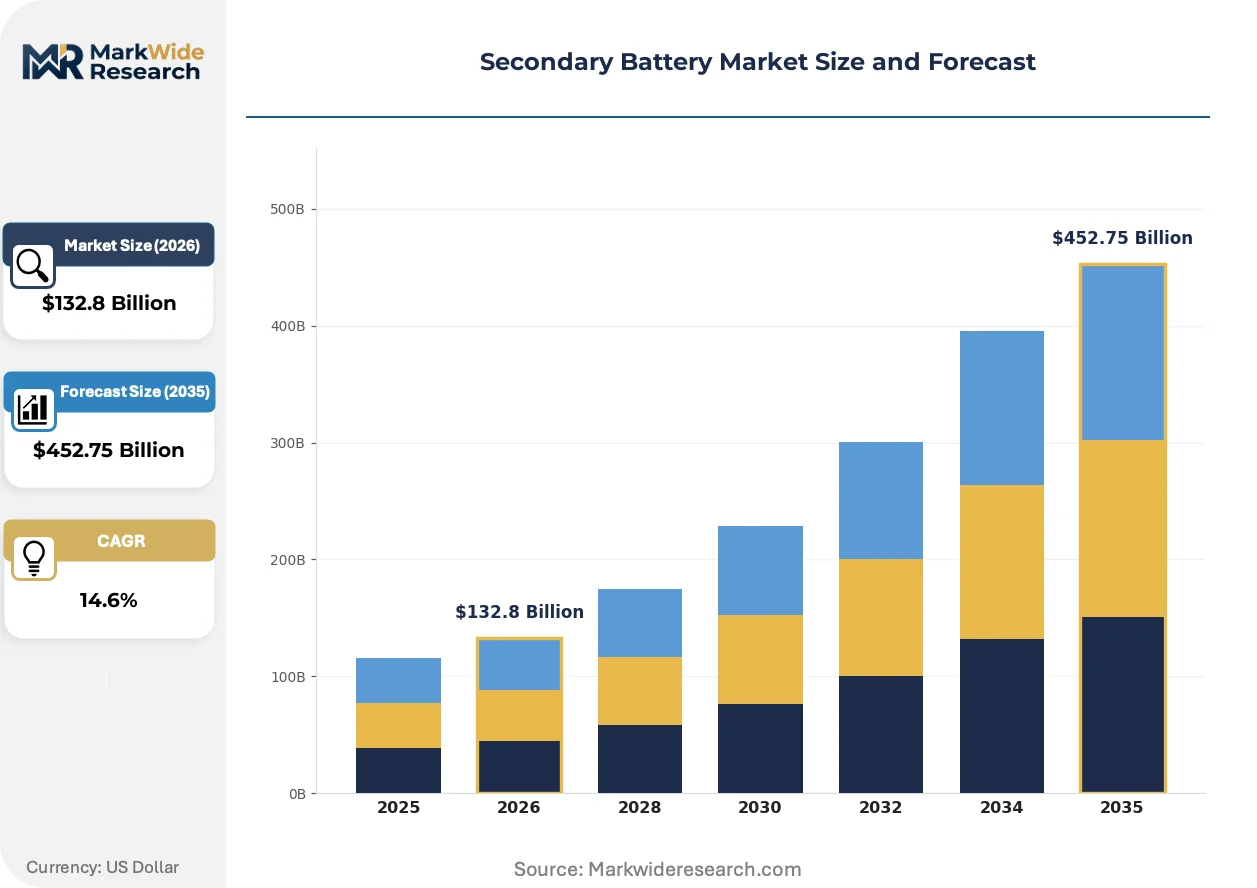
| Market Size in 2026 | $132.8 Billion |
| Market Size in 2035 | $452.75 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lithium-Ion, Nickel-Metal Hydride, Lead-Acid, Sodium-Sulfur End User: Automotive, Consumer Electronics, Industrial, Renewable Energy Technology: Solid-State, Flow, Graphene, Hybrid Application: Electric Vehicles, Energy Storage Systems, Power Tools, UPS |
| Companies Covered | BYD Company Ltd., TDK Corporation, Contemporary Amperex Technology Co., Limited (CATL), SK Innovation Co., Ltd., Toshiba Corporation, LG Chem Co. Ltd., Panasonic Corporation, EnerSys, Samsung SDI Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Secondary Battery Market Strategic Shifts & Innovations
Cell architecture and manufacturing process innovation are compressing cost curves while simultaneously elevating safety and energy density specifications beyond what liquid electrolyte platforms can deliver.
Sulfide-based solid-state electrolytes eliminate flammable organic solvents while enabling lithium-metal anode compatibility. Automotive OEMs with premium vehicle programs are locking in supply agreements for pilot-scale production. Conventional liquid electrolyte gigafactory designs are rendering obsolete before achieving full depreciation.
China's MIIT dual carbon mandates and updated GB standards for new energy vehicle safety are mandating cell-level thermal runaway propagation resistance. Export-oriented manufacturers must qualify against these protocols to access domestic Chinese OEM supply chains. European pack assemblers are restructuring procurement specifications to preemptively align with the most stringent testing regime.
Fleet operators and utility buyers are consolidating procurement through long-term offtake contracts rather than spot market purchases. Direct OEM-to-cell-manufacturer agreements are disintermediating traditional trading houses and distributors. This concentration is most visible in North American electric bus and grid storage deployments where project finance requirements favor supplier creditworthiness over transactional flexibility.
Secondary Battery Market Segmentation
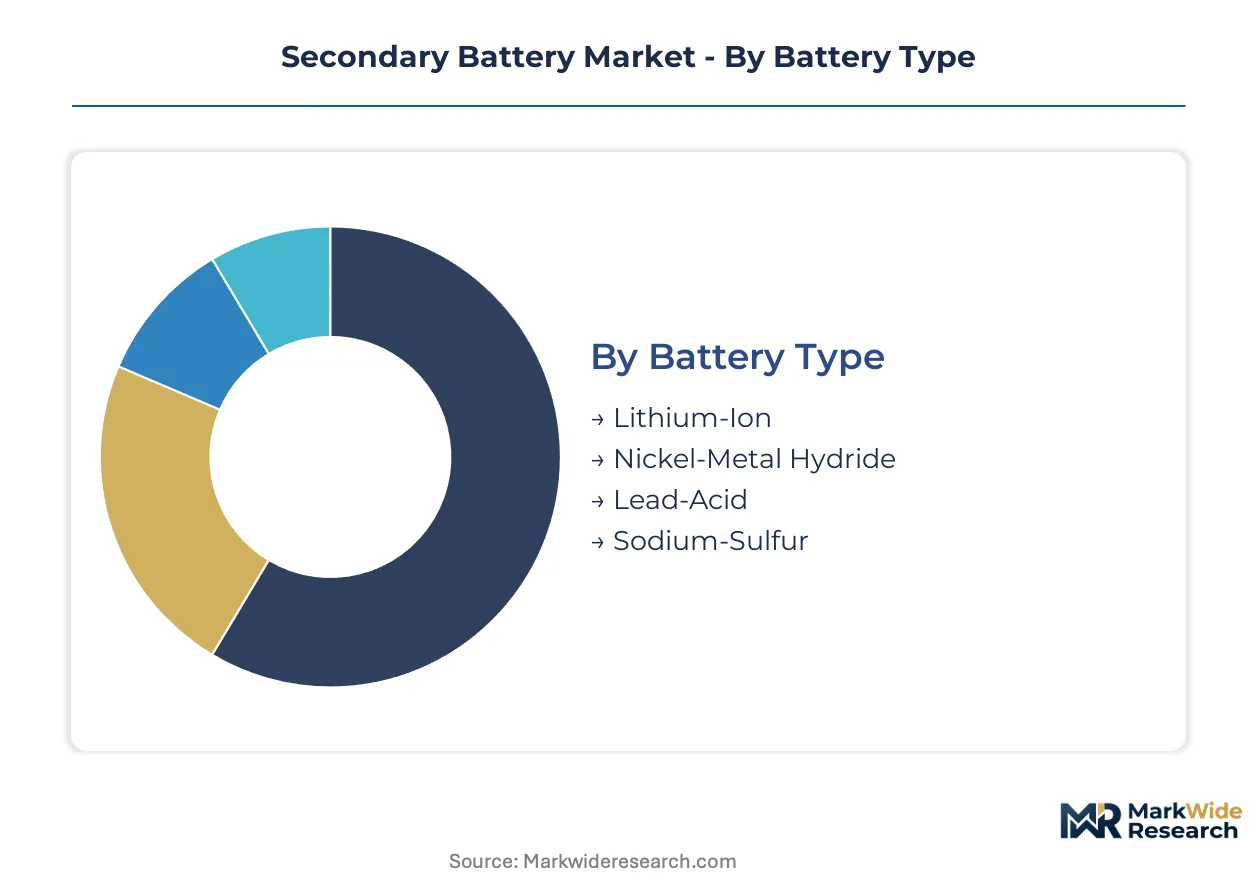
Secondary battery procurement patterns diverge sharply across application contexts, with warranty obligations and service network density varying by an order of magnitude between automotive and industrial installations. Cell manufacturers configure pricing and support architectures around these aftermarket intensity differentials.
Battery Type:
Aftermarket service exposure concentrates heavily in lithium-ion and lead-acid chemistries, where degradation monitoring and replacement scheduling drive recurring revenue streams for pack integrators.
- Lithium-Ion:Dominates motive power and grid storage with energy densities exceeding 250 Wh/kg. Automotive OEMs in Germany and China are locking in multi-year cathode supply agreements to secure qualification against MIIT and KBA thermal runaway protocols.
- Lead-Acid:Retains structural position in uninterruptible power supply systems where capital cost sensitivity outweighs cycle life requirements. Data center operators across Virginia and Frankfurt specify valve-regulated designs with 5-year replacement cycles.
- Nickel-Metal Hydride:Hybrid electric vehicle applications in Japan leverage established Toyota-Panasonic supply relationships with lower flammability profiles than lithium-ion alternatives.
- Sodium-Sulfur:High-temperature operation at 300°C limits deployment to utility-scale stationary installations with dedicated thermal management infrastructure.
By volume, lithium-ion leads. By growth pace, sodium-sulfur is climbing the fastest in grid-scale deployments.
End User:
Customer procurement sophistication spans from price-tendered utility auctions to collaborative R&D partnerships between cell makers and automotive platforms.
- Automotive:OEMs specify cell-to-pack architectures with 8-year warranty obligations. EPA tailpipe standards and EU Green Deal compliance timelines compress supplier qualification windows to 18 months.
- Renewable Energy:Grid operators in Texas, California, and South Australia mandate 4-hour duration lithium-iron-phosphate systems for frequency regulation contracts.
- Industrial:Forklift and material handling fleets in Ohio and Bavaria favor opportunity-charging lithium-ion over lead-acid for multi-shift operations.
- Consumer Electronics:Smartphone and laptop manufacturers prioritize volumetric energy density with 2-year replacement cycles and minimal service infrastructure.
Automotive commands the largest revenue pool. Renewable energy is gaining share fastest as offtake contracting displaces spot procurement.
Technology:
Manufacturing yield differentials separate pilot-scale solid-state lines from mature liquid electrolyte gigafactories with depreciated capital bases.
- Solid-State:Sulfide electrolyte designs eliminate flammable solvents while enabling lithium-metal anodes. METI subsidy structures in Japan and Samsung SDI pilot programs in South Korea target 2026-2027 commercialization.
- Flow:Vanadium redox systems decouple power and energy scaling for 8-12 hour utility storage durations. Australian and Chinese project developers specify containerized deployments with 20-year electrolyte lifetimes.
- Graphene:Enhanced conductivity additives in lithium-ion cathodes reduce internal resistance for high-rate discharge applications.
- Hybrid:Combined ultracapacitor-battery architectures address pulse power requirements in hybrid vehicle regenerative braking.
Solid-state attracts the steepest R&D investment trajectory. Flow batteries hold the longest demonstrated operational life in field deployments.
Application:
Pack integration complexity escalates from modular power tool battery packs to vehicle-integrated structural cell assemblies.
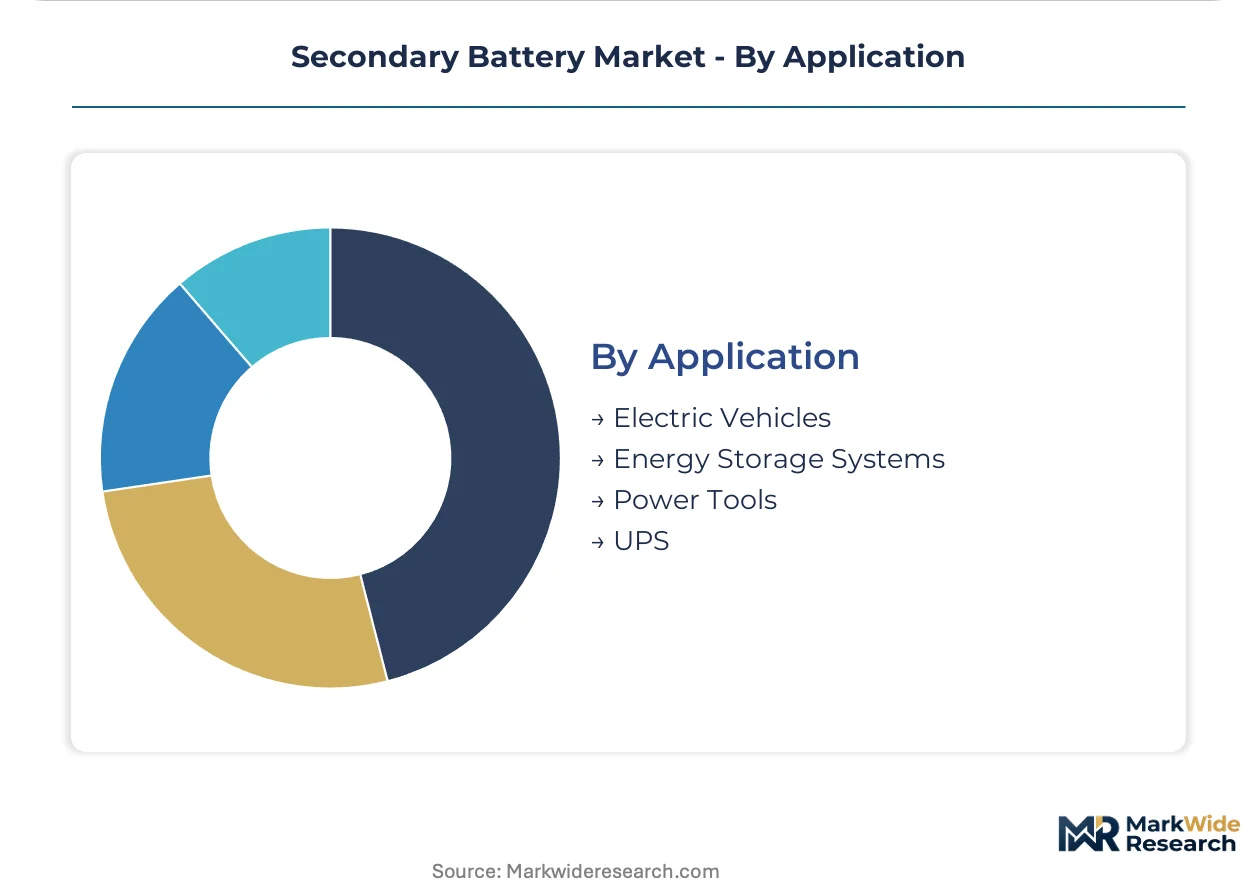
- Electric Vehicles:Cell-to-chassis designs in premium European and Chinese platforms reduce pack mass by 15-20% while complicating crash repair procedures. MFDS certification in South Korea mandates nail penetration testing at module level.
- Energy Storage Systems:Utility-scale deployments in Arizona, Chile, and Saudi Arabia specify lithium-iron-phosphate for fire safety compliance with local civil defense authorities.
- UPS:Data center operators prioritize lead-acid for capital cost containment in 15-minute backup applications.
- Power Tools:Cordless construction equipment in North America and Europe drives cylindrical cell demand with 2C discharge rate requirements.
Electric vehicles dominate absolute cell consumption. Energy storage systems are expanding most quickly as renewable penetration rises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports lithium-ion cells to automotive OEMs in Germany and the United States, establishing the dominant trade corridor in electrochemical storage. South Korea and Japan supply specialized cylindrical formats to premium electric vehicle platforms across North America and Europe. This tripartite export structure shapes regional competitive dynamics.
China
Domestic electric vehicle sales and utility-scale energy storage procurement drive cathode demand. MIIT dual carbon mandates and updated GB standards for new energy vehicle safety mandate cell-level thermal runaway propagation resistance. Shenzhen and Ningbo anchor gigafactory clusters where lithium-iron-phosphate output scales for export qualification.
South Korea
Premium automotive platform supply agreements and energy storage system exports propel cylindrical cell volumes. MFDS battery safety certification protocols extend product qualification timelines for international market access. Ulsan and Gwangju house integrated cathode-to-pack facilities serving European and North American OEM qualification programs.
Japan
Hybrid electric vehicle production and solid-state R&D commercialization sustain domestic cell demand. METI subsidy structures for solid-state battery development target 2026-2027 production timelines. Kyoto and Nagoya concentrate materials science research facilities advancing sulfide electrolyte sintering yields.
United States
Electric bus fleet electrification and grid storage procurement accelerate lithium-iron-phosphate offtake. EPA tailpipe emission standards compress OEM electrification timelines and supplier qualification windows. Michigan and Nevada host pack assembly operations qualifying against KBA and MIIT thermal runaway benchmarks.
Germany
Automotive OEM cell-to-pack integration and stationary storage deployment drive module demand. EU Green Deal carbon neutrality frameworks tighten compliance thresholds for electrification procurement. Stuttgart and Lower Saxony concentrate vehicle-integrated battery design centers aligning with MFDS nail penetration protocols.
Secondary Battery Market Key Industry Players
On the supply side, the industry is consolidating around integrated cathode-to-pack manufacturers with depreciated liquid electrolyte capacity and emerging solid-state pilot lines. Three archetypes dominate: diversified chemical conglomerates with automotive supply relationships, pure-play cell specialists with cylindrical format expertise, and state-linked champions with utility-scale contracting scale. Capacity expansion and strategic partnerships constitute the dominant competitive moves as firms secure cathode supply and offtake agreements.
Within the diversified conglomerate tier, BYD Company Ltd. and LG Chem Co. Ltd. exemplify vertical integration from raw material refining through vehicle platform supply. Contemporary Amperex Technology Co., Limited anchors the pure-play specialist archetype with lithium-iron-phosphate chemistry dominance across multiple continents. These three entities occupy positions that straddle automotive qualification requirements and grid storage procurement specifications, representing the structural concentration visible in contract awards and cathode supply allocations.
| Leading Market Players |
|---|
| BYD Company Ltd. |
| TDK Corporation |
| Contemporary Amperex Technology Co., Limited (CATL) |
| SK Innovation Co., Ltd. |
| Toshiba Corporation |
| LG Chem Co. Ltd. |
| Panasonic Corporation |
| EnerSys |
| Samsung SDI Co. Ltd. |
| Others |
Cost & Logistics Intelligence
Ningbo's lithium-iron-phosphate gigafactory cluster commands downstream pricing leverage through cathode supply scarcity, compressing margins for European pack assemblers who lack backward integration into lithium carbonate refining. Automotive OEMs in Germany and the United States absorb cell cost volatility through long-term offtake structures that transfer input risk to battery manufacturers.
Pricing Analysis
Liquid electrolyte cell pricing diverges sharply from emerging solid-state quotes, with the technology-generation gap exceeding 40 percent for equivalent energy capacity. Three-tier pricing structure across premium cylindrical formats, standard prismatic designs, and economy pouch cells reflects certification tier differentiation—MFDS and MIIT thermal runaway compliance commands measurable premiums. Pricing pressure stems from lithium carbonate spot volatility originating in Chilean and Argentine brine operations. Utility-scale energy storage buyers exhibit highest price sensitivity, while premium automotive platforms prioritize qualification reliability over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for North American pack assemblers sourcing cathode active materials. Manufacturing gravity centers on China, South Korea, and Japan for cell production, with Australia, Chile, and Indonesia feeding lithium, cobalt, and nickel inputs. Ceramic electrolyte precursor supply rests on Japanese and German specialty chemical producers with limited alternative sourcing. Single-source vulnerability concentrates in sulfide electrolyte sintering equipment. Distribution runs through direct OEM-to-manufacturer contracts that displace traditional trading house intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Secondary battery procurement is consolidating around platform-standardized cell-to-pack architectures, with interoperability between automotive and stationary storage systems emerging as the decisive ecosystem battleground.
For Market Incumbents: Build captive cathode supply moats through equity stakes in Australian spodumene and Chilean brine operations. Samsung SDI and CATL demonstrate this through direct offtake agreements that insulate against lithium carbonate volatility. Defensive consolidation should prioritize solid-state R&D talent acquisition from semiconductor materials programs, as electrochemist scarcity threatens pilot-scale yield targets. Capacity addition in Hungary and Mexico addresses tariff exposure while maintaining proximity to European and North American OEM qualification centers. For New Entrants and Emerging Players: Establish a beachhead in marine electrification harbor craft, where vibration specifications and thermal profiles differ sufficiently from automotive norms to delay incumbent specialization. India's PLI scheme offers capital subsidy coverage for advanced chemistry cell manufacturing outside established East Asian supply zones. Second-life stationary reuse protocols represent the most penetrable application segment, with standardized state-of-health testing creating service-revenue entry points without gigafactory capital requirements. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated cathode-to-pack manufacturers with utility-scale energy storage contracting scale and automotive qualification credentials. Long-term viability over the next decade hinges on solid-state commercialization timelines and thermal runaway certification positioning. Acquisition targets should display demonstrated MIIT, MFDS, or KBA protocol qualification against the most stringent jurisdiction. The signal to watch is ceramic electrolyte sintering yield breakthrough announcements from Japanese METI-subsidized programs.| Strategic Initiative | Industry Significance |
|---|---|
| Solid-State Pilot Line Scale-Up | Sulfide electrolyte manufacturing yield improvements unlock lithium-metal anode compatibility for premium automotive platforms. |
| Cathode Active Material Backward Integration | Equity stakes in Australian and Chilean lithium operations reduce exposure to carbonate spot price volatility. |
| Multi-Jurisdiction Thermal Runway Certification | MIIT, MFDS, and KBA protocol alignment accelerates OEM supplier qualification across German and Chinese vehicle programs. |
| Second-Life Stationary Reuse Protocol Development | Standardized state-of-health testing extends pack economic life into grid storage frequency regulation contracts. |
| Marine Electrification Product Line Launch | Harbor craft and short-route ferry specifications create defensible segmentation away from automotive incumbent dominance. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with cell manufacturing executives, automotive platform engineers, utility procurement officers, and electrochemistry R&D directors; and secondary validation against MIIT regulatory filings, MFDS certification databases, EIA grid storage deployment records, and customs trade data for lithium carbonate and cathode precursor movements. Bottom-up cell shipment aggregation by chemistry format and application was cross-referenced against top-down OEM electrification procurement disclosures.
Forecast inputs incorporated vehicle production platform electrification timelines, utility-scale energy storage auction awards, and solid-state pilot line yield progression curves. Segmentation modeling spanned battery chemistry, end-user vertical, technology generation, and regional regulatory cluster. CAGRs were derived from slope-consistent trajectory fitting across volume and value dimensions, with explicit sensitivity to lithium carbonate price band assumptions and thermal runaway certification protocol adoption rates.
Sensitivities concentrate around solid-state manufacturing yield breakthrough timing, lithium brine extraction expansion rates, and the jurisdiction setting the most stringent thermal runaway propagation standard. Forecasts reflect documented assumptions regarding cathode chemistry mix shifts and OEM platform electrification commitments. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Southeast Asia Battery Market
Batteries
North Europe Battery Market
Batteries
South Asia Battery Market
Batteries
SLI Battery Market
Batteries
Home Inverter Battery Market
Batteries
Modular Battery Pack Market
Batteries
Second-Life Automotive Battery Module Systems Market
Batteries
Advanced Batteries Market
Batteries
US Motive Lead Acid Battery Market
Batteries
Atomic Battery Market
Batteries
Valve Regulated Lead-Acid (VRLA) Batteries Market
Batteries
Asia-Pacific Primary Battery Market
Batteries
Battery Voltage Recorder Market
Batteries
Absorbent Glass Mat (AGM) Battery Market
Batteries
Echelon Utilization of Power Battery Market
Batteries
Electrolyte Solutions for Li-Ion Batteries Market