
 India Wind Energy Market | 2026-2036
India Wind Energy Market Size, Share, and Industry Trends Forecast 2026-2036
India Wind Energy Market Foresight
BIS certification for wind turbine generators is redrawing supplier eligibility in the India Wind Energy Market. Suzlon Energy Limited leverages its domestic manufacturing footprint to meet localized content requirements. Siemens Gamesa Renewable Energy anchors its position through technology transfer partnerships with Indian component suppliers. Adani Green Energy Limited competes on project development scale across Gujarat and Rajasthan wind zones.
Wind energy denotes the mechanical extraction of kinetic energy from air currents via aerodynamic rotor blades, typically spanning 40-120 meters in diameter, driving synchronous or doubly-fed induction generators to produce grid-frequency electricity. Onshore deployment dominates installed capacity while offshore technology represents the fastest-growing segment as water-depth engineering advances. Independent Power Producers command the largest share of end-user revenue, though industrial captive consumers increasingly drive new order intake as open-access regulations evolve.
The Central Electricity Authority mandates grid code compliance for all wind farms above 10 MW, while MNRE enforces generation-based incentives that shape project finance structures. State nodal agencies in Tamil Nadu and Maharashtra impose additional evacuation and land-use clearances that extend development timelines. Stakeholders must monitor upcoming offshore leasing frameworks and green hydrogen integration mandates that will reconfigure offtake contracting.
Market Dynamics
India's wind-solar hybrid policy is compressing standalone project economics and redirecting developer capital toward integrated renewable complexes that optimize land use and transmission access.
Growth Catalysts
- Renewable Purchase Obligations:State-run utilities in Maharashtra and Tamil Nadu are expanding procurement mandates that legally require distribution companies to source fixed percentages of power from wind assets.
- CEA Grid Code Alignment:The Central Electricity Authority's technical standards for wind farms above 10 MW are standardizing interconnection protocols and reducing commissioning delays.
- Gujarat Wind Resource Corridors:Concentrated high-capacity-factor zones in Kutch and Saurashtra are attracting private capital through pre-approved land banks and evacuation infrastructure.
Market Restraints
- Land Acquisition Friction:State nodal agencies in Karnataka and Rajasthan impose extended clearances for agricultural land conversion that stretch development timelines by 18-24 months.
- Transmission Bottlenecks:Weak inter-state green energy corridors limit evacuation from high-resource western states to demand centers in the northern and eastern grid.
- Import Dependency for Rare Earth Magnets:Permanent magnet synchronous generators rely on neodymium supply chains concentrated in Chinese processing facilities.
Strategic Opportunities
- Offshore Leasing Frameworks:The Ministry of New and Renewable Energy's upcoming seabed allocation mechanism will unlock capacity along Tamil Nadu and Gujarat coastlines.
- Green Hydrogen Integration Mandates:National hydrogen mission requirements for renewable electrolysis offtake are creating anchor demand for round-the-clock wind-solar hybrids.
- Industrial Captive Open Access:Evolving regulations in Maharashtra and Gujarat allow large consumers to contract directly with wind IPPs, bypassing utility intermediaries.
Industry Challenges
- BIS Certification Timelines:Bureau of Indian Standards testing protocols for wind turbine generators create 8-12 month qualification windows that delay project commissioning.
- Specialized Technician Shortage:Blade repair and drivetrain maintenance require certified crews that training institutes in Tamil Nadu and Gujarat cannot supply at scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Wind Energy Market |
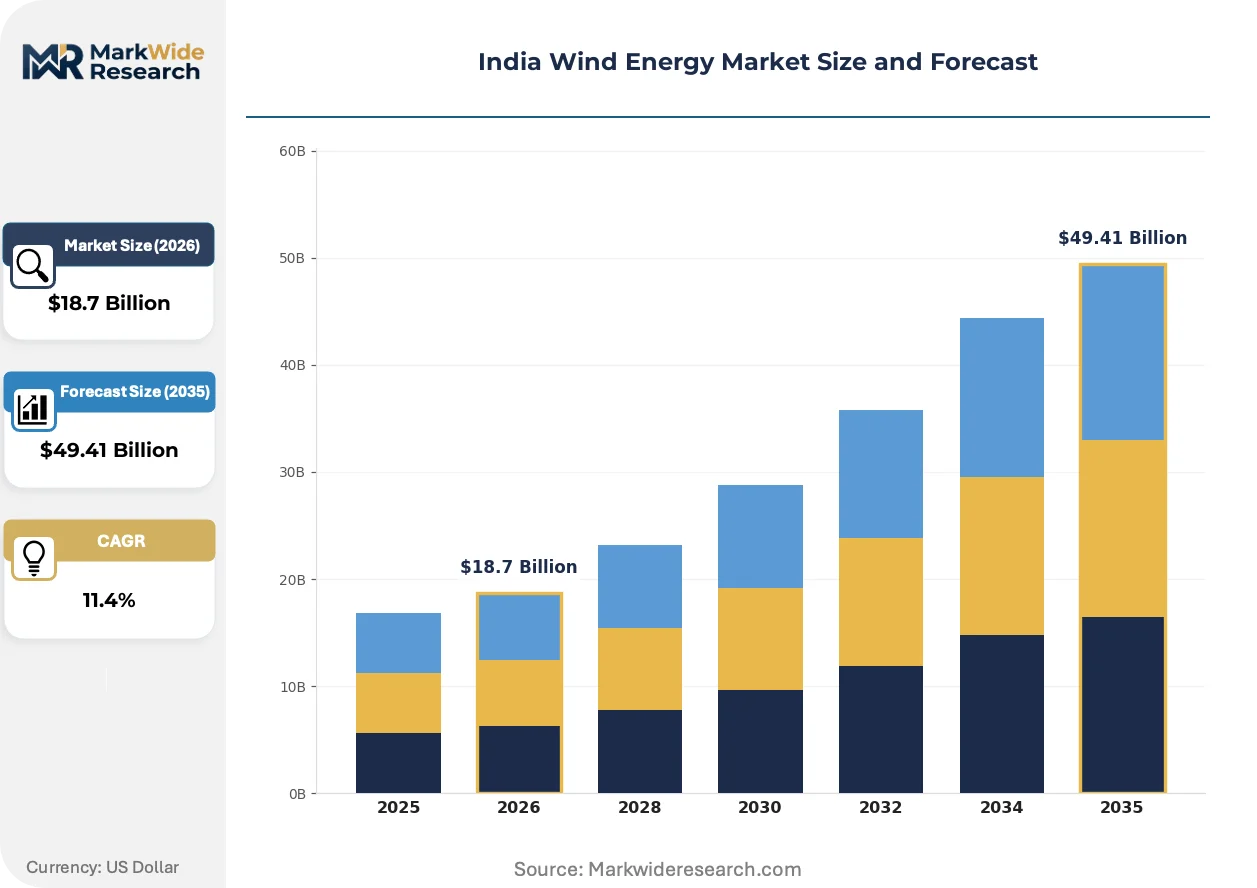
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Onshore, Offshore, Horizontal Axis, Vertical Axis End User: Utilities, Independent Power Producers, Industrial Users, Residential Users Deployment: Grid-Connected, Off-Grid, Hybrid, Microgrid Product Type: Turbines, Controllers, Inverters, Sensors |
| Companies Covered | Suzlon Energy Limited, Inox Wind Limited, Adani Green Energy Limited, Vestas Wind Systems A/S, Siemens Gamesa Renewable Energy, GE Renewable Energy, Orient Green Power Ltd., NTPC Ltd., Reliance Industries Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Wind Energy Market Shifts & Advancements
Technology convergence and procurement model evolution are restructuring competitive advantage away from equipment supply toward integrated energy solutions and long-term service contracts.
Doubly-fed induction generator architectures are fragmenting market share as developers prioritize grid-forming inverters that provide synthetic inertia and voltage support. Rajasthan and Gujarat utilities are mandating these capabilities for new interconnection agreements. The shift is compressing margins for conventional gearbox suppliers while opening service revenue streams for power electronics specialists.
The MNRE wind-solar hybrid policy is forcing standalone wind developers to redesign project layouts and control systems for co-located solar PV. Implementation rules issued by state nodal agencies in Karnataka and Maharashtra require shared transmission infrastructure and coordinated forecasting. Developers are responding by procuring hybrid inverters and unified SCADA platforms that manage mixed generation profiles.
Large industrial consumers in Gujarat and Tamil Nadu are negotiating direct power purchase agreements that displace traditional utility-mediated procurement. Textile clusters in Coimbatore and chemical processors in Vadodara are contracting 10-25 year tenors with wind IPPs to lock in renewable energy credits and hedge against grid tariff volatility. This channel shift is fragmenting offtake risk and requiring developers to maintain direct sales capabilities.
India Wind Energy Market Segmentation
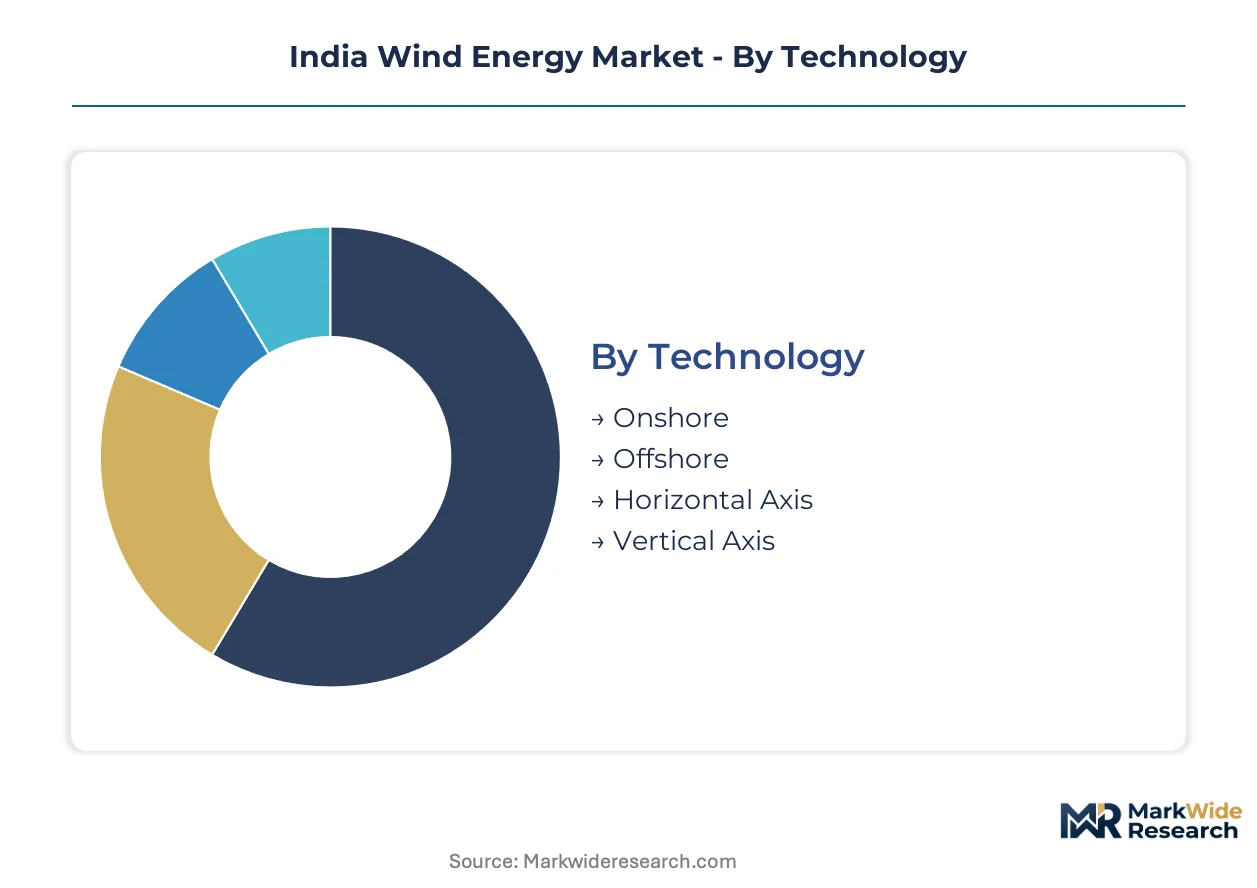
Technology and deployment configurations in the India Wind Energy Market determine project finance structures, grid integration requirements, and regulatory compliance pathways. End-user contracting patterns and product specifications further stratify competitive positioning across Gujarat's wind corridors and Tamil Nadu's manufacturing clusters.
Technology:
Horizontal axis designs face intensifying substitution pressure from emerging vertical axis architectures in distributed applications, while offshore platforms threaten to displace onshore dominance in coastal states.
- Onshore:Land-based installations utilizing steel tubular towers and doubly-fed induction generators dominate capacity additions across Kutch and Saurashtra. Gujarat and Rajasthan host the majority of new procurement under state renewable purchase obligations.
- Offshore:Fixed-bottom and floating platforms designed for water depths exceeding 30 meters are attracting feasibility studies along Tamil Nadu's coastline. The MNRE's anticipated seabed leasing mechanism will unlock project development once transmission evacuation schemes are finalized.
- Horizontal Axis:Three-blade upwind configurations with pitch control systems constitute the installed base. CEA grid code compliance mandates synthetic inertia capabilities for all new interconnections above 10 MW.
- Vertical Axis:Darrieus and Savonius designs suit low-wind-speed urban environments where horizontal footprint constraints apply. Maharashtra's industrial captive consumers pilot these systems for behind-the-meter generation.
Onshore retains volume leadership; offshore holds the steepest expansion curve once leasing frameworks activate.
End User:
Contracting economics diverge sharply across customer types, with industrial open-access arrangements compressing margins while utility-scale procurement preserves developer returns.
- Utilities:State distribution companies in Maharashtra and Tamil Nadu procure wind capacity through competitive bidding to meet renewable purchase obligations. Tariff discovery in these auctions sets reference pricing for private power purchase agreements.
- Independent Power Producers:Project development specialists aggregate land banks, secure evacuation approvals, and structure long-term offtake contracts. These entities dominate capacity commissioning in Gujarat's pre-approved wind zones.
- Industrial Users:Textile processors in Coimbatore and chemical manufacturers in Vadodara contract directly with wind farms under open-access regulations. These arrangements bypass utility intermediaries and lock in renewable energy credits.
- Residential Users:Small-scale rooftop and micro-turbine installations serve rural electrification programs and affluent urban consumers. Karnataka's net metering policies enable limited deployment in this channel.
Utilities anchor procurement volumes; industrial users are climbing the fastest as open-access regulations mature.
Deployment:
Grid synchronization requirements and storage integration costs create tiered investment thresholds that favor hybrid architectures over standalone configurations.
- Grid-Connected:Large-scale farms inject power through 33 kV and 132 kV substations into state transmission networks. CEA technical standards govern frequency response and voltage regulation for these installations.
- Off-Grid:Standalone systems with battery storage serve remote agricultural and industrial loads where grid extension is uneconomical. Rajasthan's desert regions host pilot diesel-wind hybrid mini-grids.
- Hybrid:Co-located wind-solar installations share transmission infrastructure and optimize capacity utilization factors. MNRE policy mandates unified control systems and coordinated forecasting for these projects.
- Microgrid:Islanded networks combining wind, solar, and storage serve industrial parks and rural clusters. Tamil Nadu's nodal agency permits limited commercial deployment with standardized interconnection protocols.
Grid-connected maintains the dominant share; hybrid configurations are gaining share fastest under integrated renewable mandates.
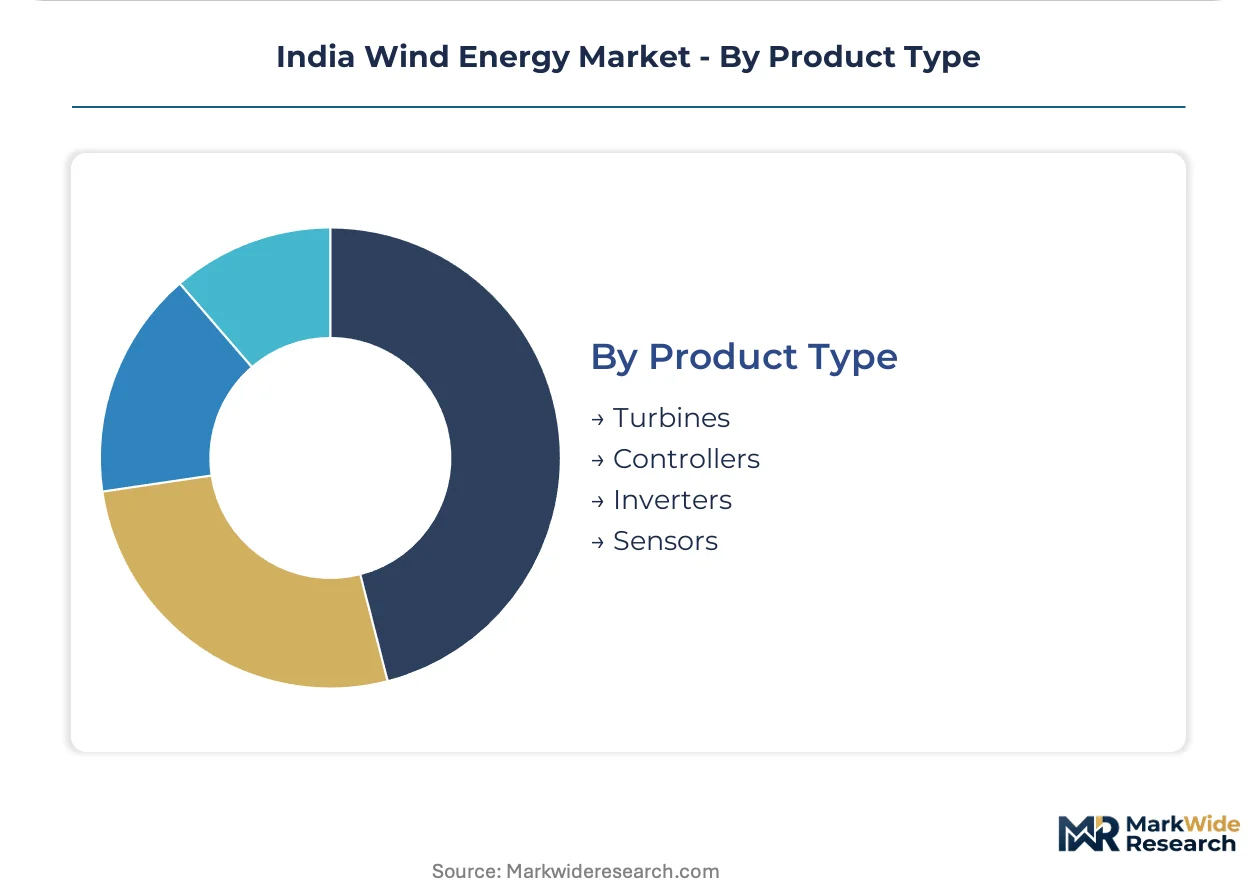
Product Type:
Component specifications stratify across turbine scale classes, with megawatt-class drivetrains demanding specialized manufacturing capabilities concentrated in Gujarat and Tamil Nadu.
- Turbines:Nacelle assemblies housing generators, gearboxes, and yaw systems range from 250 kW to 3 MW for Indian deployment. BIS certification requirements for wind turbine generators impose 8-12 month qualification timelines on new suppliers.
- Controllers:Pitch and yaw control systems manage aerodynamic loading and orientation optimization. These subsystems integrate with SCADA platforms for remote monitoring and predictive maintenance scheduling.
- Inverters:Grid-forming power electronics provide synthetic inertia and voltage support mandated by Rajasthan and Gujarat utilities. Full-converter architectures are displacing doubly-fed designs in new procurement.
- Sensors:Lidar wind measurement and vibration monitoring equipment enable condition-based maintenance programs. These systems reduce unplanned downtime and extend drivetrain service intervals.
Turbines command the largest revenue pool; inverters are expanding most quickly as grid-forming requirements proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial captive consumers in Gujarat and Tamil Nadu anchor procurement volumes, while state-run utilities in Maharashtra and Karnataka expand renewable purchase obligation compliance through competitive auctions.
Gujarat
Textile processors and chemical manufacturers in Vadodara and Surat drive open-access contracting with wind independent power producers. The Gujarat Electricity Regulatory Commission mandates renewable purchase obligations that require distribution companies to source fixed percentages from wind assets. Kutch and Saurashtra host concentrated high-capacity-factor zones where pre-approved land banks and evacuation infrastructure attract private capital.
Tamil Nadu
Wind turbine manufacturing clusters in Coimbatore and Chennai supply component ecosystems for domestic and export markets. The Tamil Nadu Generation and Distribution Corporation enforces additional evacuation clearances and land-use permits that extend development timelines. The state's nodal agency permits limited commercial microgrid deployment with standardized interconnection protocols for industrial parks.
Karnataka
State nodal agencies impose extended clearances for agricultural land conversion that stretch wind project timelines by 18-24 months. The Karnataka Renewable Energy Development Agency coordinates hybrid project implementation rules requiring shared transmission infrastructure and coordinated forecasting. Bangalore's technology corridor hosts training institutes for blade repair and drivetrain maintenance crews.
Maharashtra
Steel and cement manufacturers in Mumbai-Pune belt negotiate direct power purchase agreements bypassing utility intermediaries. The Maharashtra Electricity Regulatory Commission's evolving open-access regulations allow large consumers to contract directly with wind independent power producers. Nagpur and Aurangabad industrial zones pilot vertical axis turbine systems for behind-the-meter generation in low-wind-speed environments.
Rajasthan
Desert regions host pilot diesel-wind hybrid mini-grids serving remote agricultural and industrial loads where grid extension is uneconomical. The Rajasthan Electricity Regulatory Commission mandates grid-forming inverter capabilities with synthetic inertia and voltage support for new interconnection agreements. Jodhpur and Jaisalmer wind zones attract developers through competitive bidding for utility-scale procurement.
India Wind Energy Market Competitive Landscape
Player mix skews toward integrated project developers with captive manufacturing capabilities and technology licensors with localized component partnerships. Market structure concentrates around three strategic archetypes: domestic turbine manufacturers with BIS certification advantages, global technology providers with technology transfer arrangements, and conglomerate-backed independent power producers with land bank scale. Dominant competitive moves include backward integration into nacelle assembly and blade fabrication, plus strategic partnerships for grid-forming power electronics.
Within the domestic manufacturing tier, Suzlon Energy Limited exemplifies the vertically integrated archetype with localized content compliance capabilities. Siemens Gamesa Renewable Energy occupies a position among technology licensors leveraging component supplier partnerships. Adani Green Energy Limited anchors the conglomerate-backed developer segment with project concentration across Gujarat and Rajasthan wind zones.
| Leading Market Players |
|---|
| Suzlon Energy Limited |
| Inox Wind Limited |
| Adani Green Energy Limited |
| Vestas Wind Systems A/S |
| Siemens Gamesa Renewable Energy |
| GE Renewable Energy |
| Orient Green Power Ltd. |
| NTPC Ltd. |
| Reliance Industries Ltd. |
| Others |
Supply & Pricing Matrix
Capacity utilization at Tamil Nadu and Gujarat nacelle assembly plants shapes both component procurement concentration and turbine price floors for domestic developers. Scale advantages in these manufacturing clusters compress landed costs for local independent power producers while elevating entry barriers for unqualified foreign suppliers seeking BIS certification.
Pricing Analysis
Cost-plus contracts with steel and rare earth magnet indexation dominate utility-scale procurement between Maharashtra discoms and wind independent power producers. Price differentiation separates BIS-certified domestic turbines from pending-certification imports, with Gujarat textile clusters showing highest sensitivity to tariff volatility. Cost compression in the standard tier intensifies as Chinese neodymium supply constraints elevate permanent magnet generator pricing. Premium-tier buyers in Tamil Nadu's chemical corridor prioritize grid-forming inverter capabilities and absorb higher capital costs for synthetic inertia compliance.
Supply Chain Analysis
Port congestion at Mundra and Hazira elevates inbound logistics costs for gearbox and bearing shipments originating from Germany and Denmark. Component sourcing concentrates in China for rare earth magnets, in South Korea for power electronics, and domestically for steel towers and concrete foundations. Supply chain risk centers on single-source dependency for neodymium processing facilities. Distribution runs through state nodal agencies that coordinate land allocation and evacuation infrastructure approvals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India Wind Energy Market represents high-growth disruption as offshore leasing frameworks and green hydrogen integration mandates reconfigure offtake economics. The MNRE's seabed allocation mechanism constitutes the primary regulatory inflection reshaping developer capital allocation.
For Market Incumbents: Fortify domestic manufacturing scale through backward integration into blade fabrication and nacelle assembly. Suzlon Energy Limited's captive component supply demonstrates how localized content compliance neutralizes import-dependent competitors. Prioritize BIS certification pipeline acceleration to preempt foreign technology licensors. Defend against offshore entrants by anchoring Tamil Nadu coastal feasibility studies ahead of MNRE framework activation.
For New Entrants and Emerging Players: Predictive maintenance service gaps among incumbent turbine OEMs create white-space opportunities for specialized technical crews. Target Karnataka's agricultural land conversion bottlenecks where 18-24 month clearance delays strand projects requiring blade repair and drivetrain intervention. Penetrate through direct contracting with Maharashtra steel and cement manufacturers seeking open-access bypass of utility intermediaries. Anchor go-to-market around certified technician training partnerships with Bangalore institutes.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors conglomerate-backed independent power producers with pre-approved land banks in Gujarat and Rajasthan. Long-term viability hinges on hybrid project development capabilities integrating wind-solar coordination with green hydrogen offtake structuring. Acquisition targets should demonstrate grid-forming inverter deployment experience and MNRE policy navigation expertise. Monitor offshore leasing framework publication timing as inflection indicator for coastal state capacity expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | Gujarat's pre-approved land banks in Kutch accelerate project commissioning timelines for independent power producers. |
| Power Purchase Agreement | Maharashtra textile clusters lock in renewable energy credits through direct 10-25 year tenors with wind farms. |
| Technology Licensing | Siemens Gamesa Renewable Energy transfers doubly-fed induction generator expertise to Indian component suppliers. |
| Vertical Integration into Storage | Hybrid inverters with unified SCADA platforms manage co-located wind-solar generation profiles per MNRE mandates. |
| Green Certification Program | BIS testing protocols for wind turbine generators create 8-12 month qualification windows filtering supplier eligibility. |
Research Methodology
Desk research of MNRE policy circulars, CEA grid code amendments, and state electricity regulatory commission orders preceded structured interviews with utility planning officers, wind independent power producer development leads, EPC contractors, and grid operators. Secondary validation drew from Central Electricity Authority generation statistics, state nodal agency project databases, and Bureau of Indian Standards certification records. Bottom-up project pipeline aggregation triangulated against top-down renewable purchase obligation compliance targets across Maharashtra, Tamil Nadu, Gujarat, Karnataka, and Rajasthan.
Variance decomposition across technology segments, deployment configurations, and end-user contracting channels anchored the analytical framework over the projection horizon. Modeled dimensions span onshore versus offshore platforms, grid-connected versus hybrid architectures, and utility versus industrial captive offtake structures. CAGRs derived from capacity addition trajectories indexed to state renewable purchase obligation escalation schedules and green hydrogen mission electrolysis demand assumptions.
Material uncertainties — offshore leasing framework delays, rare earth magnet supply disruptions, and inter-state green energy corridor completion schedules — sit outside the modeled envelope. Forecasts reflect assumptions regarding MNRE policy continuity and state nodal agency clearance timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Germany Offshore Wind Energy Market
Wind Energy Systems
Brazil Wind Energy Market
Wind Energy Systems
Wind Turbine Pitch and Yaw Control System Market
Wind Energy Systems
Wind Power Converter Systems Market
Wind Energy Systems
Europe Wind Power Equipment Market
Wind Energy Systems
Wind Turbine Nacelle Market
Wind Energy Systems
Wind Tower Market
Wind Energy Systems
Global Wind Power Coatings Market
Wind Energy Systems
South Korea Wind Energy Market
Wind Energy Systems
Wind Power Couplings Market
Wind Energy Systems
Offshore Wind Tower Market
Wind Energy Systems
Wind Energy Rescue System Market
Wind Energy Systems
Sweden Wind Power Market
Wind Energy Systems
Taiwan Wind Energy Market
Wind Energy Systems
Japan Wind Energy Market
Wind Energy Systems
Bladeless Wind Turbines Market