
 South Korea Wind Energy Market | 2026-2036
South Korea Wind Energy Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Wind Energy Market Analytics
A capital-intensity divergence between domestic conglomerates and foreign OEMs is rotating competitive dynamics in South Korea's wind sector. Doosan Heavy Industries & Construction leverages its integrated foundry and fabrication complexes to captive-produce nacelle housings and tower sections. Siemens Gamesa anchors its position through technology leadership in direct-drive offshore platforms and local blade manufacturing partnerships.
South Korea wind energy encompasses turbine-based electricity generation systems rated from kilowatt-scale distributed units to 15-megawatt offshore machines, utilizing horizontal-axis rotors with carbon-fiber reinforced polymer blades and permanent-magnet generators to convert kinetic wind flux into grid-synchronous AC power. Offshore installations dominate capital deployment, with floating platform technology representing the fastest-expanding sub-category as deep-water sites beyond 50-meter depths open for lease. Onshore turbine procurement has matured into a replacement-driven segment where margin pools concentrate in O&M service contracts and blade retrofit kits rather than new unit sales.
MFDS enforces structural fatigue standards for offshore turbine towers under the Industrial Safety and Health Act, while KOSHA mandates worker certification for vessel-mounted installation crews. The Korea Energy Agency administers renewable energy certificate auctions that shape offtake economics for independent power producers. Stakeholders must monitor seabed lease auction timing and port infrastructure readiness to calibrate manufacturing capacity commitments against project pipeline visibility.
Market Dynamics
Floating offshore wind platforms are compressing project development timelines as Jeolla Province seabed auctions accelerate lease awards for deep-water sites beyond 50-meter depths.
Growth Catalysts
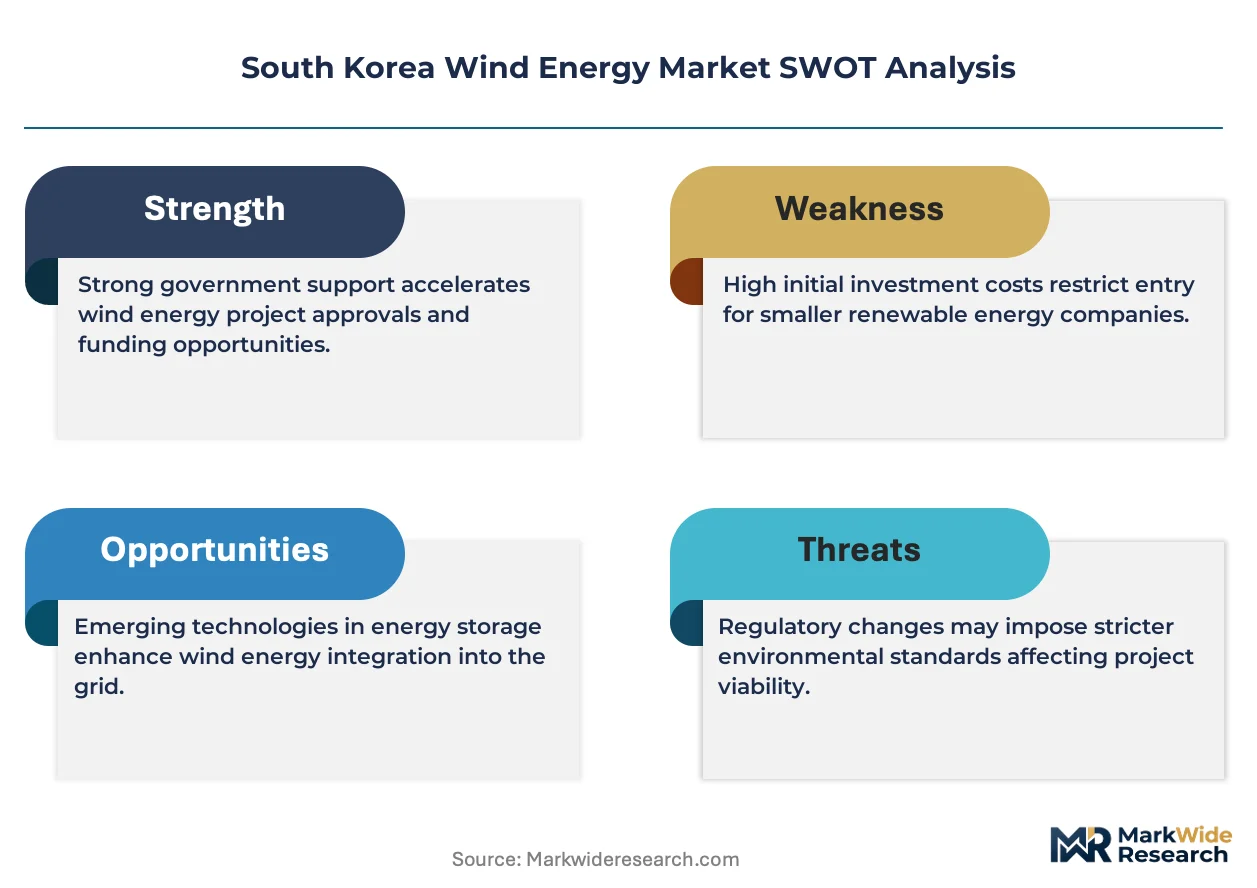
- MFDS Structural Fatigue Standards:Tightened certification requirements for offshore turbine towers under the Industrial Safety and Health Act are forcing component upgrades that extend asset lifespans and reduce long-term replacement cycles.
- Jeolla Province Lease Concentration:Coastal zone seabed auctions are creating dedicated development corridors with bundled grid connection rights, reducing permitting friction for utility-scale arrays.
- Carbon-Fiber Blade Adoption:Advanced composite manufacturing is enabling longer rotor diameters that capture higher wind flux at lower rotational speeds, improving capacity factors for offshore installations.
Market Restraints
- Specialized Vessel Bottleneck:Installation jack-up vessels capable of handling 15-megawatt turbine components remain concentrated among European and Chinese fleet operators, creating charter rate volatility.
- Permanent-Magnet Supply Concentration:Rare-earth processing for direct-drive generator magnets depends on upstream supply chains outside South Korea, exposing projects to input cost swings.
- KOSHA Certification Friction:Worker qualification mandates for vessel-mounted installation crews extend crew mobilization timelines and inflate labor cost structures.
Strategic Opportunities
- Ulsan Port Infrastructure Expansion:Dedicated offshore wind staging and assembly facilities under development will reduce turbine component logistics costs for projects in the East Sea.
- Replacement-Driven Onshore Segment:Aging turbine fleets installed during the 2010-2015 capacity build-out are creating demand for blade retrofit kits and generator upgrade packages.
- Korea Energy Agency REC Auctions:Renewable energy certificate price discovery mechanisms are stabilizing offtake revenue visibility for independent power producers.
Industry Challenges
- Installation Crew Skill Scarcity:KOSHA-certified technicians for floating platform mooring operations remain in short supply relative to projected project pipelines.
- Grid Synchronization Complexity:Variable renewable output from offshore arrays requires harmonic filtering equipment and reactive power compensation systems that inflate interconnection capex.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Wind Energy Market |
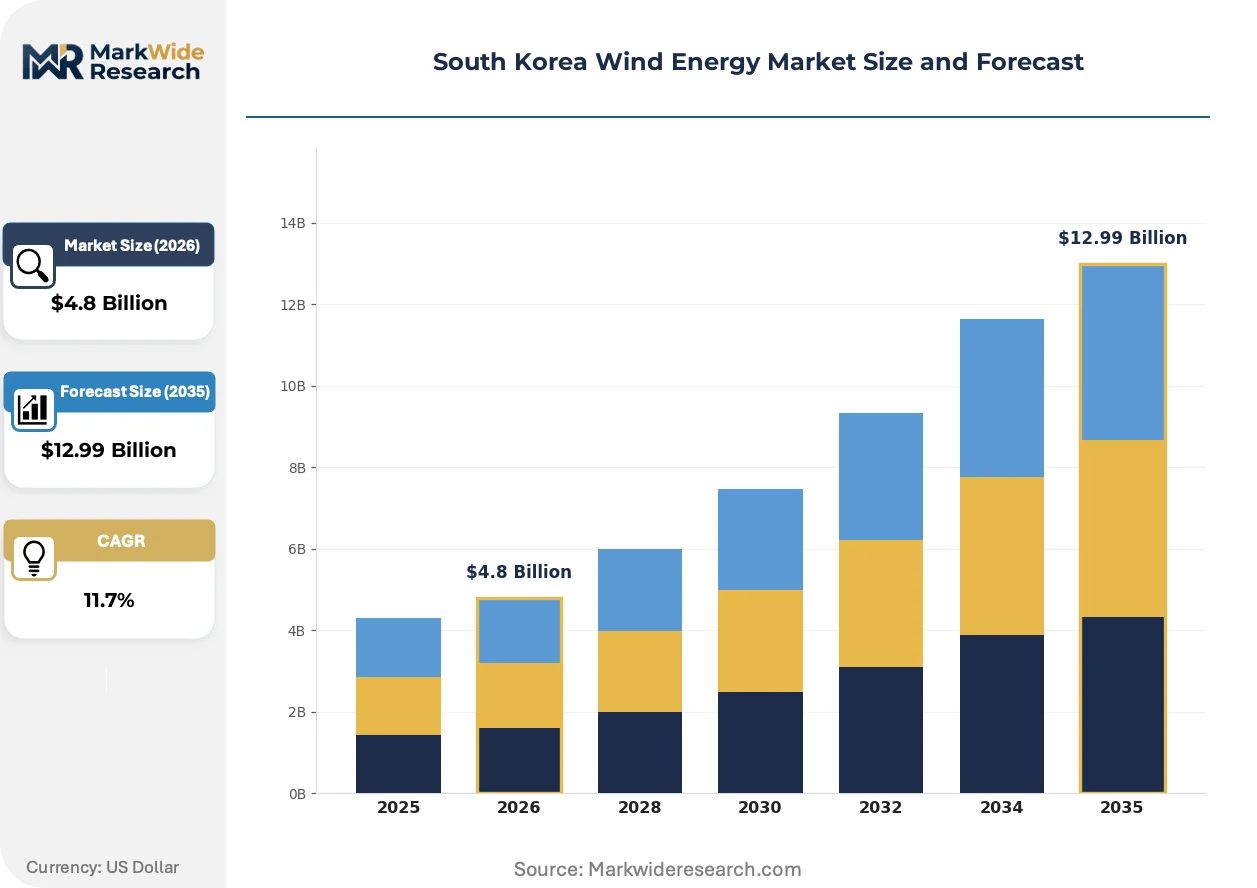
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
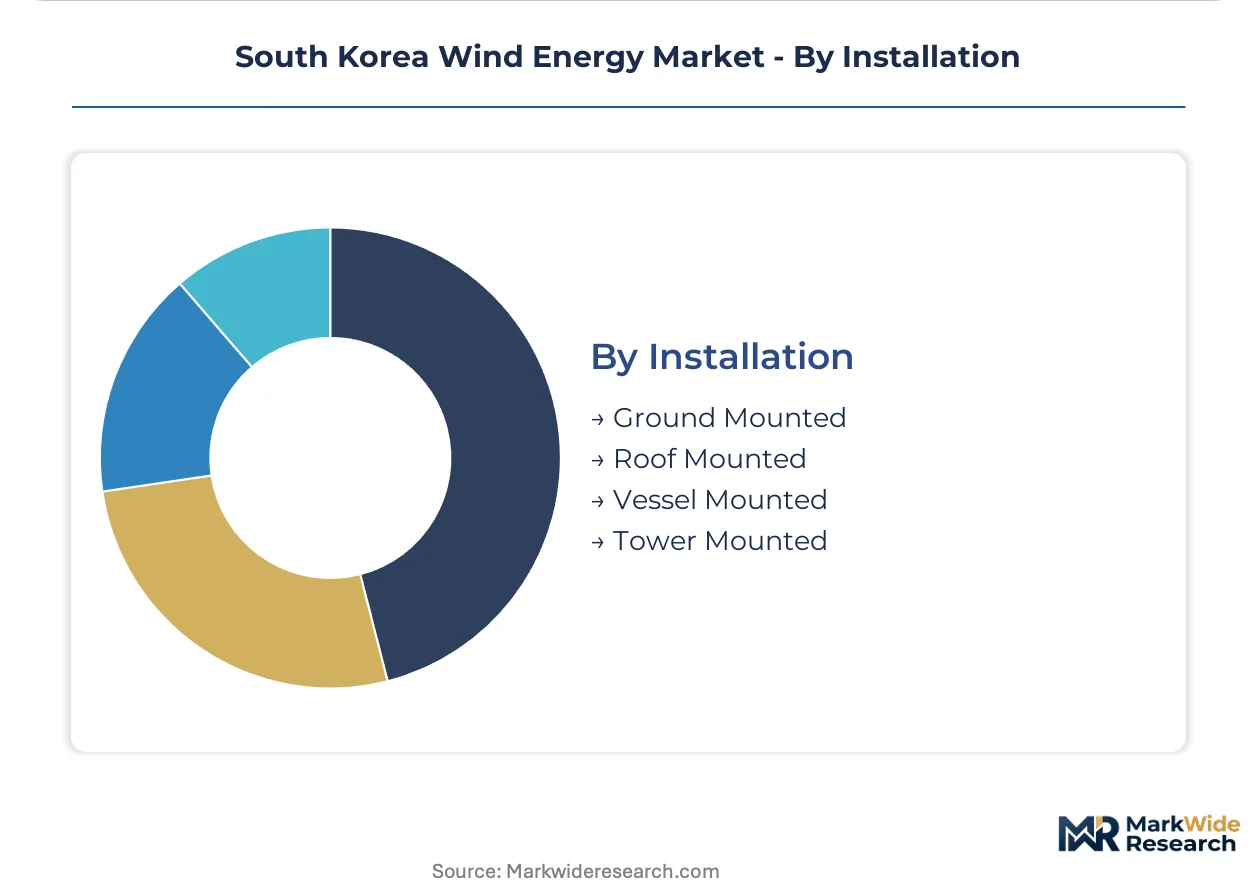
| Segmentation | Product Type: Onshore, Offshore, Hybrid, Small Wind Technology: Turbine, Gearless, Vertical Axis, Floating End User: Utilities, Independent Power Producers, Government, Commercial Installation: Ground Mounted, Roof Mounted, Vessel Mounted, Tower Mounted |
| Companies Covered | Vestas Wind Systems, Siemens Gamesa, Doosan Heavy Industries & Construction, Hyosung Heavy Industries, GE Renewable Energy, Nordex, Equinor, Hyundai Heavy Industries, Goldwind, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Wind Energy Market Evolving Landscape
Turbine scaling and platform design advances are compressing levelized cost trajectories while regulatory tightening around component safety is reshaping certification workflows.
Direct-drive permanent-magnet generators are eliminating gearbox maintenance burdens in offshore environments. Korean utilities deploying floating arrays in 50-meter-plus water depths are specifying these units for 25-year design lives. The technology is miniaturizing nacelle footprints relative to power output, reducing floating platform structural loads and mooring system costs.
MFDS enforcement of structural fatigue standards under the Industrial Safety and Health Act is mandating third-party tower inspection protocols. Component suppliers must now submit full-scale test data for welded joint classifications. Offshore turbine OEMs are responding by integrating digital twin monitoring systems that track tower stress cycles in real time.
Utility procurement teams are unbundling engineering-procurement-construction contracts into separate turbine supply and installation agreements. This fragmentation is displacing integrated EPC providers with specialized vessel operators and marine construction firms. The shift is most visible in Jeolla Province projects where port infrastructure constraints favor modular contracting approaches.
South Korea Wind Energy Market Segmentation
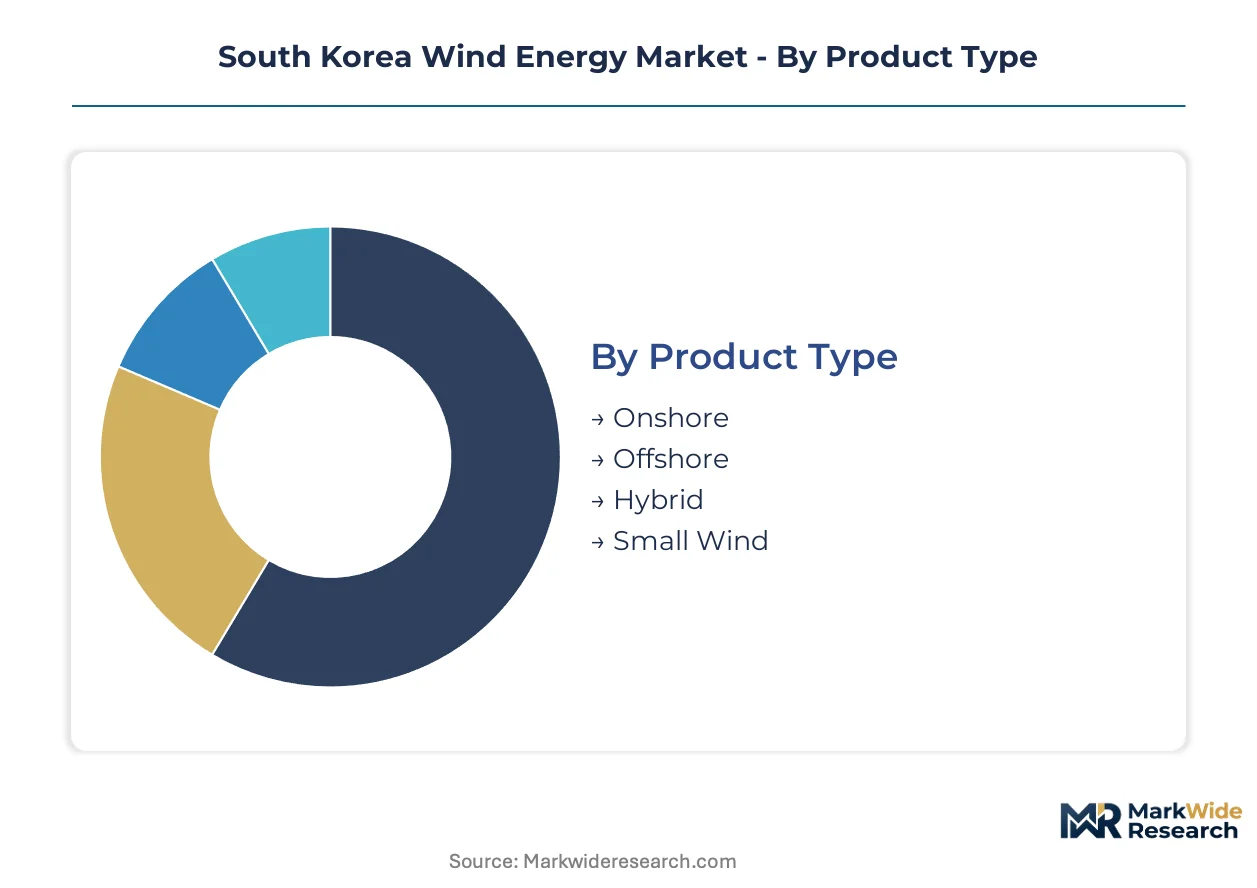
South Korea's wind energy segmentation reveals distinct procurement channels and capital deployment patterns. Channel mix varies sharply across product categories, with offshore arrays flowing through utility-led consortiums while distributed segments serve independent power producers and commercial offtakers.
Product Type:
Channel architecture diverges between centralized utility procurement and distributed commercial sales, with each product category commanding distinct contracting structures and stakeholder ecosystems.
- Offshore:Floating and fixed-bottom arrays rated above 5 megawatts dominate capital deployment in Jeolla Province lease zones. Procurement concentrates through Korea Electric Power Corporation-led joint ventures where bundled grid connection rights reduce development risk.
- Onshore:Utility-scale ground-mounted turbines in the 2-5 megawatt range anchor replacement demand from fleets installed during the 2010-2015 build-out. Revenue pools are shifting toward O&M service contracts and blade retrofit kits rather than new unit sales.
- Hybrid:Wind-solar co-location systems integrate storage buffers to smooth interconnection variability.
- Small Wind:Kilowatt-scale distributed units serve commercial rooftops and island microgrids through direct manufacturer sales.
Offshore dominates installed base. Onshore is where expansion concentrates for replacement-driven service revenue.
Technology:
Cost tier stratification separates premium direct-drive platforms from conventional geared architectures, with technology choice determining maintenance burden and design life economics.
- Gearless:Direct-drive permanent-magnet generators eliminate gearbox maintenance in salt-laden offshore environments. Korean utilities specify these units for 25-year design lives in floating arrays, with nacelle footprint miniaturization reducing platform structural loads.
- Floating:Semi-submersible and tension-leg platforms unlock deep-water sites beyond 50-meter depths where fixed foundations prove uneconomical. Jeolla Province lease auctions are accelerating deployment timelines for this sub-category.
- Turbine:Conventional geared drivetrains retain cost advantage in onshore replacement cycles.
- Vertical Axis:Darrieus and Savonius configurations serve niche urban applications with omnidirectional wind capture.
Gearless systems anchor premium offshore procurement. Floating platforms are climbing the fastest as deep-water leases open.
End User:
Customer type determines financing structure and offtake risk profile, with utilities leveraging balance-sheet capacity against independent power producers seeking project finance.
- Utilities:Korea Electric Power Corporation and regional generation subsidiaries deploy capital through integrated development models. These entities control interconnection queue priority and bundled seabed lease applications in Jeolla coastal zones.
- Independent Power Producers:Project developers rely on Korea Energy Agency renewable energy certificate auctions to stabilize revenue visibility. REC price discovery mechanisms are critical to debt financing for merchant exposure.
- Government:Public sector procurement supports island electrification and defense facility microgrids.
- Commercial:Corporate power purchase agreements drive distributed onshore installations for industrial load matching.
Utilities dominate project pipeline control. Independent power producers are where merchant risk innovation concentrates.
Installation:
Volume concentration maps to port infrastructure availability and vessel charter markets, with installation method determining logistics cost structure and crew certification requirements.
- Vessel Mounted:Jack-up and heavy-lift vessel operations handle offshore turbine component staging in Ulsan and Busan port zones. KOSHA-certified crews for floating platform mooring operations remain scarce relative to projected pipelines.
- Ground Mounted:Onshore foundation and tower erection services concentrate in Jeolla and Gyeongsang provinces where crane access and grid proximity align.
- Roof Mounted:Small wind distributed generation integrates with commercial building electrical systems.
- Tower Mounted:Retrofit and repowering services address aging onshore fleet upgrades.
Vessel mounted commands premium offshore logistics spend. Ground mounted anchors onshore replacement volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jeolla Province consumes wind energy infrastructure differently than Seoul Capital Area or Busan-Ulsan, with floating offshore arrays dominating capital deployment while onshore replacement cycles concentrate in southern coastal zones.
Jeolla Province
Seabed lease auctions for deep-water sites beyond 50-meter depths are accelerating floating platform procurement. MFDS structural fatigue standards under the Industrial Safety and Health Act mandate third-party tower inspections for all offshore installations. The Mokpo-Sinan coastal corridor anchors turbine component staging with dedicated marshalling ports under development.
Busan-Ulsan
Heavy-lift vessel charter markets and jack-up installation fleets concentrate in this southeastern maritime cluster. KOSHA certification requirements for vessel-mounted crews extend mobilization timelines for floating platform mooring operations. Ulsan Port Authority is expanding dedicated offshore wind assembly facilities to reduce logistics costs for East Sea projects.
Seoul Capital Area
Corporate power purchase agreement origination and Korea Energy Agency renewable energy certificate trading dominate transactional activity. The Korea Electric Power Corporation headquarters coordinates utility-led joint venture structures for bundled grid connection rights. Incheon metropolitan logistics zones handle nacelle component distribution to western coastal developments.
Gwangju-Honam
Onshore turbine replacement demand from 2010-2015 fleet installations is shifting revenue pools toward O&M service contracts. Regional independent power producers rely on REC auction price discovery to stabilize merchant exposure financing. The Naju innovation cluster hosts blade retrofit kit manufacturing for aging onshore generator upgrades.
Daegu-Gyeongbuk
Carbon-fiber reinforced polymer blade manufacturing partnerships with foreign OEMs anchor industrial investment. The country's national industrial safety regulator enforces worker qualification mandates for ground-mounted tower erection crews. Pohang steel complex supplies high-grade welded tower sections to Jeolla offshore developments.
South Korea Wind Energy Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with conglomerate-affiliated fabricators controlling captive component production while independent technology licensors compete on direct-drive platform efficiency. Domestic heavy industries leverage backward integration into foundry and fabrication complexes. Foreign OEMs anchor market presence through blade manufacturing partnerships and offshore technology licensing. Competitive moves concentrate on port infrastructure pre-commitments and KOSHA-certified crew training alliances.
Among Denmark-based turbine specialists, Vestas Wind Systems occupies a position exemplifying the scale-driven archetype through integrated nacelle supply chains. Siemens Gamesa, with Spanish-German corporate roots, represents the technology-licensing tier focused on direct-drive permanent-magnet platforms. Doosan Heavy Industries & Construction anchors the domestic integrated conglomerate segment with captive production of tower sections and structural components.
| Leading Market Players |
|---|
| Vestas Wind Systems |
| Siemens Gamesa |
| Doosan Heavy Industries & Construction |
| Hyosung Heavy Industries |
| GE Renewable Energy |
| Nordex |
| Equinor |
| Hyundai Heavy Industries |
| Goldwind |
| Others |
Value Network & Pricing Analysis
MFDS structural fatigue certification under the Industrial Safety and Health Act gates supplier qualification and price differentiation simultaneously, forcing component vendors to absorb third-party testing costs while tiering output between certified premium towers and uncertified standard alternatives.
Pricing Analysis
Long-term offtake contracts with Korea Electric Power Corporation anchor turbine procurement, with pricing stratifying across premium direct-drive platforms, standard geared architectures, and economy-tier onshore replacement units. Price differentiation rests on certification grade and volume scale, with floating platform bundles commanding premium positioning. Cost compression in standard onshore tiers intensifies because blade retrofit kit suppliers multiply. Independent power producers exhibit highest price sensitivity due to merchant exposure, while utility-led joint ventures prioritize design life over unit economics.
Supply Chain Analysis
Strait of Malacca transit for rare-earth concentrates from Myanmar and Australia underwrites permanent-magnet generator supply, with Chinese and Japanese processing facilities feeding Korean nacelle assembly. Carbon-fiber pre-preg draws from Toray's Japanese and French production bases, while high-grade steel plate sources from POSCO's domestic mills. Single-source vulnerability concentrates in heavy-lift vessel charter markets controlled by European and Chinese fleet operators. Distribution runs through Ulsan and Busan port zones with dedicated marshalling yards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Floating platform interoperability standards are consolidating Jeolla Province developments into a unified ecosystem, creating winner-take-most dynamics where early certification investments compound into locked-in supplier status.
For Market Incumbents: Shield installed base relationships by pre-committing to Ulsan Port Authority expansion slots before competitor vessel alliances form. Deepen backward integration into carbon-fiber blade manufacturing to offset foreign OEM technology licensing pressure. Lock in KOSHA-certified crew training pipelines to constrain rival mobilization capacity.
For New Entrants and Emerging Players: Anchor in Gwangju-Honam onshore O&M service contracts where aging 2010-2015 fleets create replacement-driven white space. Target blade retrofit kit manufacturing through Naju innovation cluster partnerships. Pursue direct sales to commercial offtakers with corporate power purchase agreement origination expertise.
For Investors and Strategic Acquirers: MFDS enforcement timeline reshapes the acquisition landscape toward certified component suppliers with full-scale test data libraries. Five-to-ten year viability favors tower section fabricators with integrated foundry capacity and Jeolla seabed lease adjacency. Monitor Korea Energy Agency REC auction price floors as inflection indicator for independent power producer debt capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| KOSHA-Certified Crew Training Alliance | Secures scarce installation labor for floating platform mooring operations ahead of pipeline ramp. |
| Ulsan Port Staging Facility Pre-Commitment | Locks in logistics cost advantage for East Sea project clusters against Busan competitor zones. |
| Direct-Drive Generator Technology License | Transfers permanent-magnet platform efficiency from Siemens Gamesa to domestic OEM balance sheets. |
| Carbon-Fiber Blade Manufacturing Joint Venture | Captures margin pool from foreign OEM partnerships while building domestic composite capability. |
| REC Auction Price Hedging Instrument | Stabilizes revenue visibility for merchant-exposed independent power producers seeking project finance. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with utility planning officers, independent power producer project developers, EPC contractors, and KOSHA certification auditors; and secondary validation through Korea Energy Agency auction records, MFDS inspection protocols, and port authority development filings. Bottom-up project pipeline aggregation triangulated against top-down capacity deployment models from grid operator interconnection queues.
Across the projection horizon, the analytical framework modeled segmentation by technology type, end-user financing structure, installation method, and regional grid cluster. CAGRs derived from capacity build-out schedules, equipment replacement cycles, and seabed lease award pacing. Forecast inputs incorporated vessel charter rate trajectories and rare-earth magnet price indices.
Underlying assumptions cover seabed lease auction timing, port infrastructure completion schedules, and KOSHA certification throughput capacity, with deviation risk concentrated in specialized vessel availability and REC auction price volatility. Practitioners should keep alternative scenarios live as floating platform technology cost curves and grid interconnection queue priorities evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Middle-East and Africa Wind Power Market
Wind Energy Systems
Wind Services Market
Wind Energy Systems
North America Wind Power Equipment Market
Wind Energy Systems
North America Wind Power Market
Wind Energy Systems
Asia-Pacific Wind Power Market
Wind Energy Systems
Europe Direct Drive Wind Turbine Market
Wind Energy Systems
Germany Wind Energy Market
Wind Energy Systems
Offshore Wind Power Market
Wind Energy Systems
Iran Wind Energy Market
Wind Energy Systems
Greece Wind Energy Market
Wind Energy Systems
South America Wind Power Market
Wind Energy Systems
India Wind Energy Market
Wind Energy Systems
Global Wind Turbine Operations Market
Wind Energy Systems
Denmark Wind Energy Market
Wind Energy Systems
Wind Turbine Blades Market
Wind Energy Systems
Wind Power Composite Market