
 Sweden Wind Power Market | 2026-2036
Sweden Wind Power Market Size, Share, and Industry Trends Forecast 2026-2036
Sweden Wind Power Market Insights
Aftermarket service revenue is tilting toward repowering and lifetime extension contracts as Sweden's installed base matures. Vattenfall AB leverages its vertically integrated fleet to capture recurring maintenance streams across northern Sweden. Vestas Wind Systems A/S dominates the turbine supply landscape through localized blade manufacturing and service hub density. Siemens Gamesa Renewable Energy SA differentiates via offshore platform specialization aligned with Baltic Sea lease rounds.
Sweden wind power encompasses electricity generation from kinetic wind energy conversion through horizontal or vertical axis turbines, typically sited onshore in forested terrain or offshore in Baltic Sea zones where mean wind speeds exceed seven meters per second at hub height. The primary commercial purpose is supplying baseload-compatible renewable electricity to Nordic grid interconnections and power-intensive industrial consumers. Horizontal axis turbines anchor the technology mix due to proven scalability in subarctic conditions, while offshore installations represent the fastest-expanding deployment category driven by deeper water lease allocations. Utility scale applications concentrate margin pools through long-term power purchase agreements with energy providers, whereas community projects and co-operative ownership models are gaining structural traction in rural municipalities.
The Swedish Energy Agency coordinates national permit frameworks, while the Swedish Environmental Protection Agency enforces Natura 2000 habitat assessments for onshore developments, together compressing project timelines where biodiversity compliance is pre-negotiated. EU Green Deal alignment through Sweden's integrated national energy and climate plan mandates capacity additions that tighten equipment certification standards under harmonized European norms. Stakeholders must monitor grid connection queue dynamics and municipal veto rights as decisive variables for project realization velocity.
Market Dynamics
Swedish heavy industry electrification is compressing power procurement timelines as steel, mining, and chemical producers seek baseload-compatible renewable supply. This demand surge is colliding with municipal veto rights and grid connection queues, creating a structural tension between project velocity and permitting reality.
Growth Catalysts
- EU Green Deal alignment:Sweden's integrated national energy and climate plan mandates capacity additions that tighten equipment certification standards under harmonized European norms.
- Heavy industry procurement:Steel producers and mining operators are accelerating long-term power purchase agreements with Swedish energy providers to secure renewable baseload.
- Norrland resource convergence:Wind speeds exceeding seven meters per second at hub height coincide with expanding grid transmission corridors in northern Sweden.
Market Restraints
- Grid connection queues:Swedish transmission system operator backlog extends project realization timelines beyond original development schedules.
- Municipal veto rights:Local government opposition under the Swedish Environmental Code blocks otherwise technically viable onshore sites.
- Baltic Sea lease scarcity:Offshore water depth allocations limit viable floating platform deployment zones.
Strategic Opportunities
- Repowering contracts:Lifetime extension and turbine replacement services address Sweden's maturing installed base from early 2000s deployments.
- Co-operative ownership models:Rural municipalities are structuring community equity participation to accelerate local acceptance.
- Forest turbine adaptation:Hub height optimization and wake steering algorithms unlock subarctic forested terrain previously deemed marginal.
Industry Challenges
- Subarctic maintenance specialization:Technician scarcity for cold-climate blade repair and gearbox servicing constrains fleet availability.
- Natura 2000 compliance timelines:Swedish Environmental Protection Agency habitat assessments compress development windows where biodiversity pre-negotiation fails.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sweden Wind Power Market |
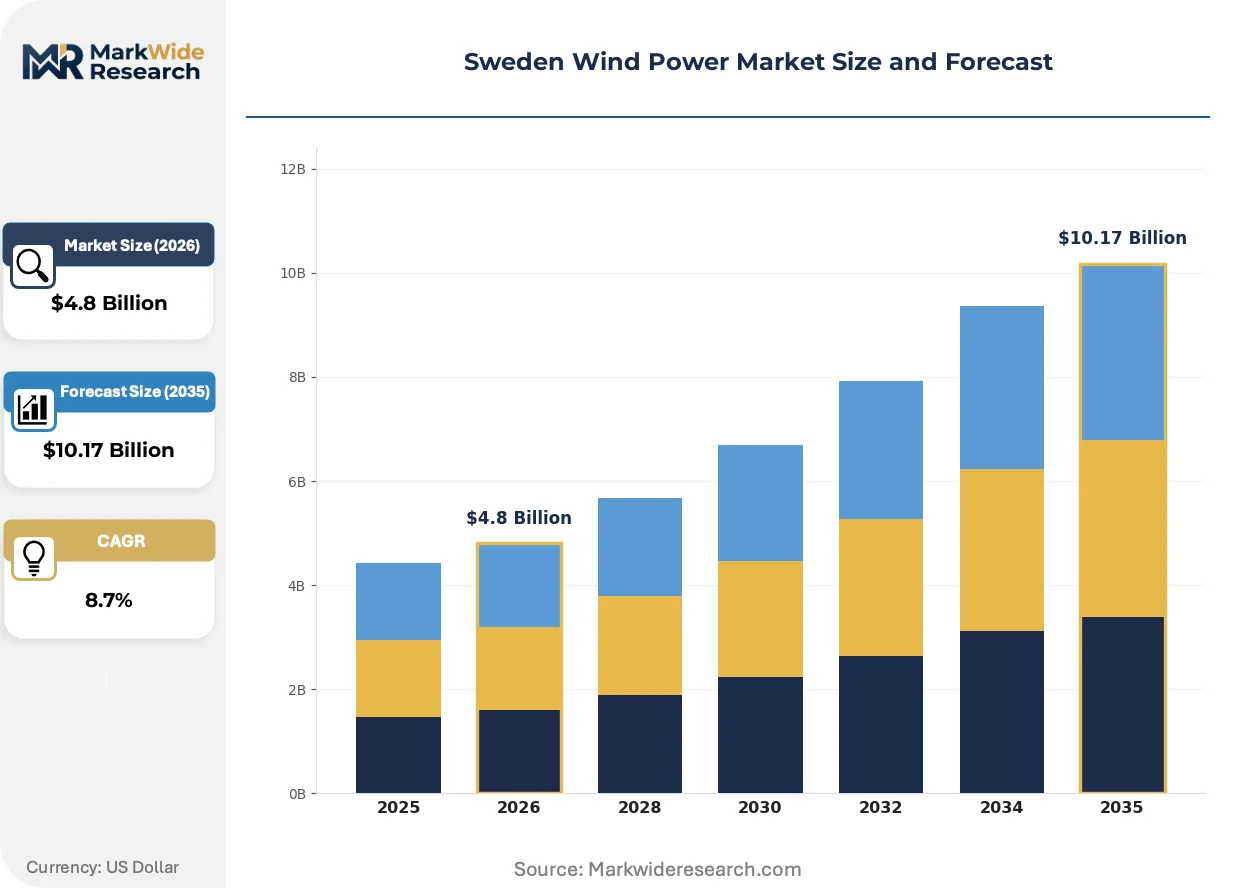
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Horizontal Axis Turbines, Vertical Axis Turbines, Offshore Installations, Onshore Installations Application: Utility Scale, Community Projects, Industrial Use, Residential Installations End User: Energy Providers, Government Agencies, Private Investors, Co-operatives Deployment: New Installations, Upgrades, Repowering, Maintenance Services |
| Companies Covered | Vattenfall AB, Fortum Oyj, Uniper SE, Statkraft AS, OX2 AB, Vestas Wind Systems A/S, Siemens Gamesa Renewable Energy SA, Arise AB, E.ON SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sweden Wind Power Market Trends and Innovations
Swedish wind development is pivoting from greenfield expansion toward asset optimization and hybrid system integration. Technology maturation is forcing service model reinvention while regulatory streamlining attempts to unlock stalled project pipelines.
Wake steering and lidar-based predictive control systems are hybridizing turbine output optimization with grid stability services. Swedish fleet operators are retrofitting existing assets to capture ancillary revenue streams. This convergence is compressing the traditional separation between generation-only and grid-balancing business models.
The Swedish Energy Agency's permit simplification reforms are compressing project approval timelines where pre-application biodiversity consultations are completed. Industrial developers are front-loading Natura 2000 assessments to avoid mid-process delays. Northern counties with established environmental baseline data are capturing disproportionate development velocity.
Steel and chemical producers are unbundling long-term supply contracts from traditional utility intermediaries. Direct corporate power purchase agreements with project developers are displacing bundled retail supply in Norrland industrial zones. This disintermediation is most visible among electrolyzer-linked hydrogen production facilities seeking price certainty.
Sweden Wind Power Market Segmentation
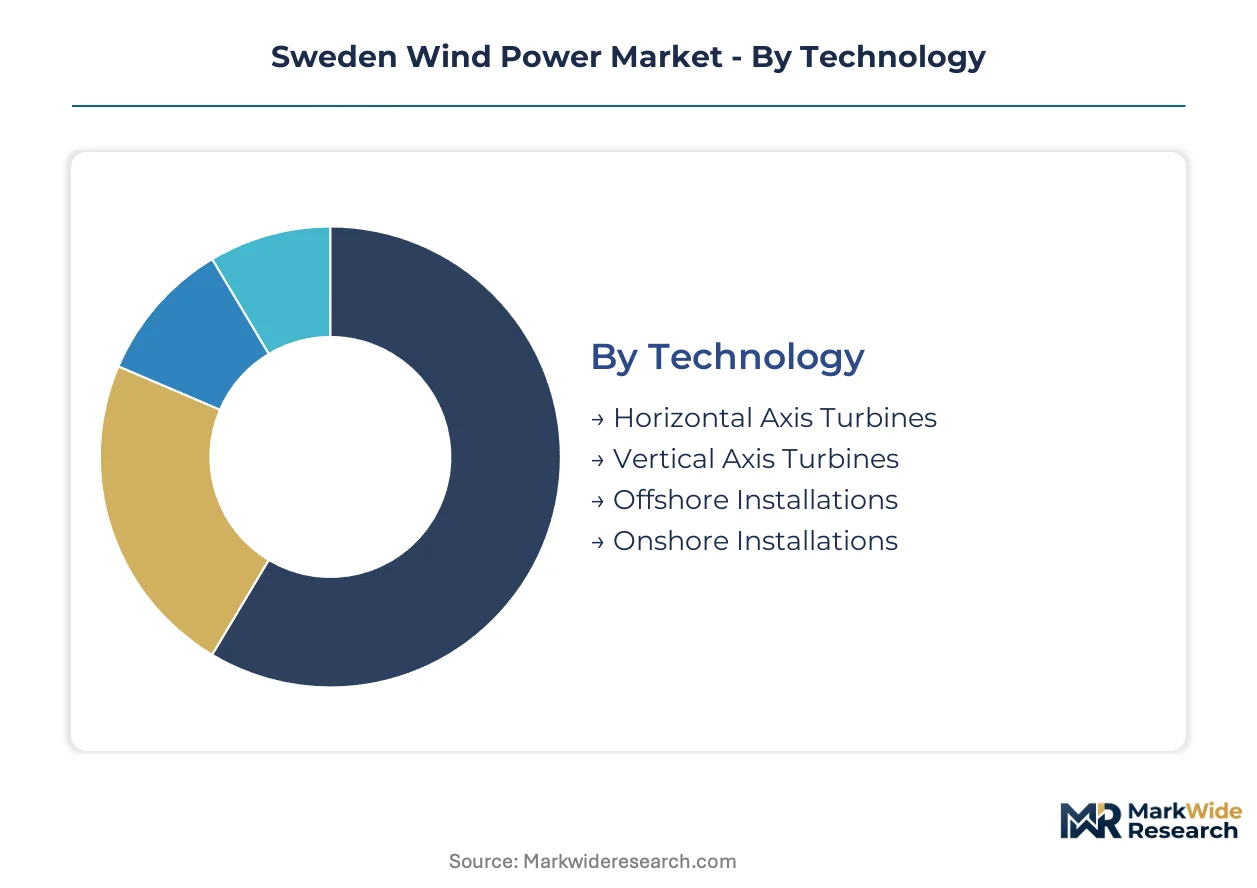
Sweden's wind power segmentation reveals divergent technology maturities and customer economics. Deployment categories reflect a market pivoting from greenfield expansion toward asset optimization. Each dimension carries distinct margin profiles and regulatory exposure.
Technology:
Horizontal axis configurations dominate utility procurement due to proven subarctic reliability, while emerging formats target specialized niches.
- Horizontal Axis Turbines:Three-blade upwind designs constitute the installed base majority, optimized for forested terrain through hub height extensions exceeding 150 meters. Norrland energy providers specify these units for baseload power purchase agreements with steel and mining operators.
- Offshore Installations:Fixed-bottom and floating platforms in Baltic Sea zones access mean wind speeds surpassing eight meters per second. Swedish Energy Agency lease allocations are compressing development timelines for these capital-intensive projects.
- Vertical Axis Turbines:Darrieus and Savonius variants serve distributed micro-generation in remote municipalities where grid connection costs prove prohibitive.
- Onshore Installations:Land-based deployments encompass forested ridge lines and coastal plains, subject to Swedish Environmental Protection Agency Natura 2000 assessments.
The dominant share belongs to Horizontal Axis Turbines, while Offshore Installations are gaining share fastest.
Application:
Customer scale determines financing structures and offtake contract duration, with industrial buyers driving procurement velocity.
- Utility Scale:Projects exceeding 100 megawatts secure long-term power purchase agreements with Nordic grid interconnections. These developments concentrate in Västerbotten and Norrbotten counties where transmission corridor expansion is underway.
- Industrial Use:Direct corporate procurement from steel, chemical, and mining operators bypasses traditional utility intermediaries. Electrolyzer-linked hydrogen production facilities in Norrland industrial zones anchor this segment's expansion.
- Community Projects:Municipal co-operative ownership models accelerate local acceptance through equity participation structures.
- Residential Installations:Small-scale distributed generation serves rural properties beyond centralized grid reach, limited by Swedish municipal planning permissions.
Utility Scale commands the largest revenue pool, though Industrial Use is climbing the fastest as heavy electrification accelerates.
End User:
Ownership structures shape project risk allocation and capital access, with institutional players dominating capacity additions.
- Energy Providers:Vattenfall AB and regional utilities deploy balance sheet capacity for fleet expansion and grid stabilization services. These entities capture recurring maintenance revenue through vertically integrated service operations.
- Private Investors:Infrastructure funds and pension capital target operational assets with contracted cash flows, favoring projects with completed environmental permitting.
- Co-operatives:Rural municipality equity participation models distribute ownership among local stakeholders to preempt veto rights under the Swedish Environmental Code.
- Government Agencies:Swedish Energy Agency direct procurement supports demonstration projects and research installations, particularly for floating offshore technology validation.
Energy Providers retain the dominant position, while Co-operatives are expanding most quickly as community ownership models proliferate.
Deployment:
Service intensity varies with asset age, redirecting vendor revenue from equipment supply toward lifecycle management.
- Repowering:Turbine replacement and lifetime extension contracts address Sweden's early 2000s installed base, retrofitting existing towers with modern drivetrains and larger rotors. Vestas Wind Systems A/S and Siemens Gamesa Renewable Energy SA compete for these high-margin service agreements.
- Maintenance Services:Cold-climate blade repair and gearbox servicing generate recurring revenue streams, constrained by technician scarcity for subarctic conditions. Vattenfall AB leverages fleet scale to maintain captive service capacity across northern Sweden.
- New Installations:Greenfield developments face Swedish transmission system operator grid connection queues extending project realization timelines.
- Upgrades:Control system retrofits and wake steering algorithm implementations optimize existing asset output for ancillary grid services.
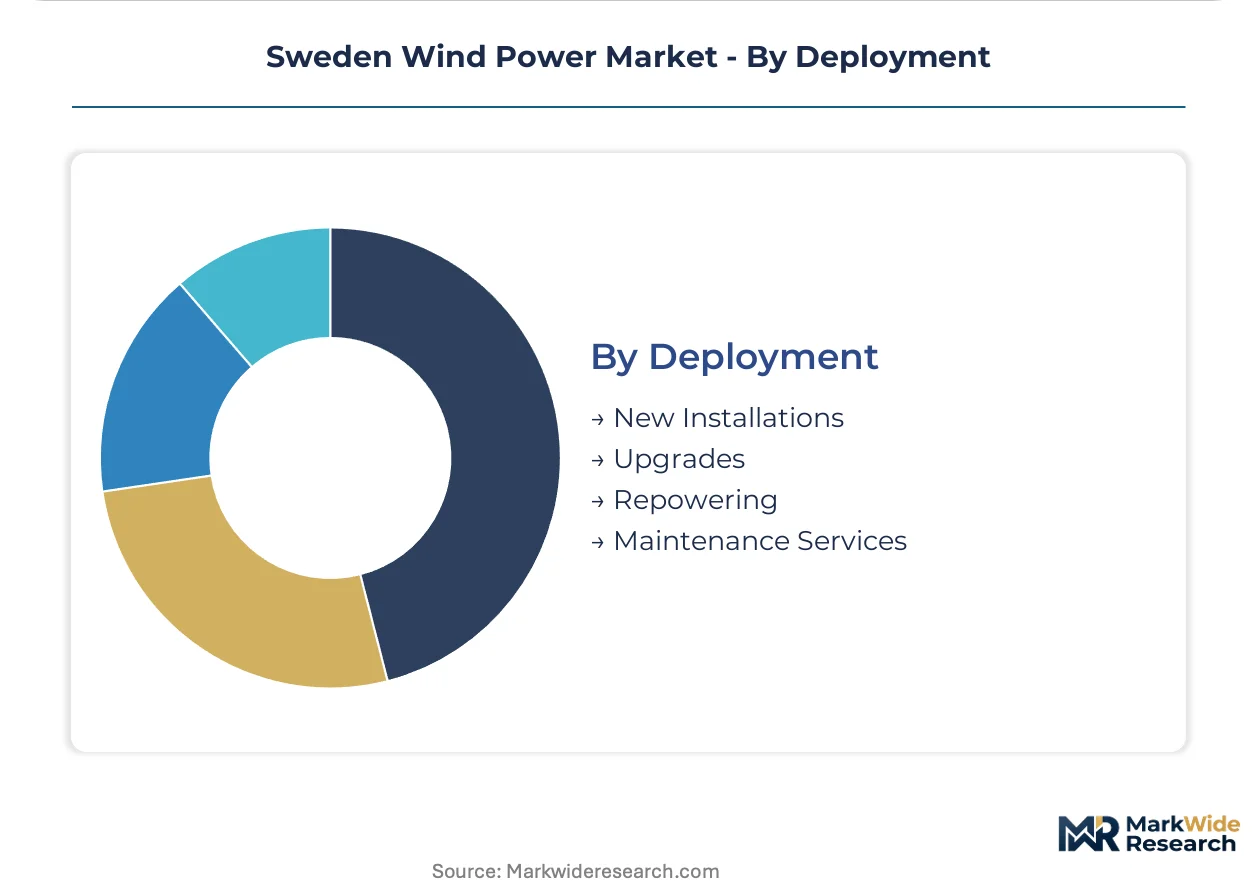
Maintenance Services generates the steadiest revenue flow, while Repowering shows the steepest expansion trajectory as the installed base matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial buyers in Norrland show the lowest price elasticity as electrification deadlines compress procurement timelines, while municipal co-operatives in central counties exhibit higher sensitivity to upfront capital requirements. Grid connection availability rather than generation cost increasingly determines project economics across Swedish sub-regions.
Norrland
Steel producers and mining operators in Västerbotten and Norrbotten counties are executing long-term power purchase agreements with energy providers to secure renewable baseload for electrolyzer-linked hydrogen production. The Swedish Energy Agency's permit simplification reforms are compressing approval timelines where pre-application biodiversity consultations are completed. The Luleå industrial cluster anchors this demand concentration as SSAB and H2 Green Steel advance fossil-free steel production timelines.
Svealand
Stockholm County data centers and manufacturing facilities are procuring wind power through direct corporate agreements bypassing traditional utility intermediaries. EU Green Deal alignment through Sweden's integrated national energy and climate plan mandates capacity additions that tighten equipment certification standards. The Mälardalen industrial corridor is capturing development velocity as transmission corridor expansion connects coastal wind resources to load centers.
Götaland
Chemical producers in Västra Götaland are accelerating renewable procurement to meet Scope 3 emission reduction targets under CSRD reporting requirements. The Swedish Environmental Protection Agency enforces Natura 2000 habitat assessments that compress development windows where biodiversity pre-negotiation fails. The Gothenburg industrial zone is experiencing project realization delays as municipal veto rights under the Swedish Environmental Code block otherwise technically viable onshore sites.
Gotland
Island municipalities are structuring co-operative ownership models to distribute equity among local stakeholders and preempt veto rights. Swedish transmission system operator grid connection queues extend project timelines beyond original development schedules for offshore cable connections. The Visby region is capturing disproportionate community project velocity as established environmental baseline data streamlines permitting.
Scania
Agricultural processors and food manufacturers in Skåne County are procuring smaller-scale wind generation through community equity participation structures. The Swedish Energy Agency coordinates national permit frameworks that municipal planning permissions complicate for distributed installations. The Öresund industrial corridor is experiencing slower deployment as Baltic Sea lease scarcity limits viable offshore platform zones.
Sweden Wind Power Market Competitive Landscape
Capability concentration sits with vertically integrated energy providers; scale advantage sits with specialized turbine manufacturers. The market structure divides between balance-sheet-backed fleet operators capturing recurring maintenance revenue and equipment suppliers competing on technology differentiation. Two strategic archetypes dominate: integrated utilities leveraging captive service capacity, and technology specialists competing on offshore platform expertise. Competitive moves center on repowering contract capture and direct corporate power purchase agreement origination.
Among Nordic integrated utilities, Vattenfall AB exemplifies the vertically integrated archetype through fleet-scale service operations across northern Sweden. Vestas Wind Systems A/S and Siemens Gamesa Renewable Energy SA occupy the technology-supplier tier, with the former representing localized manufacturing presence and the latter anchoring offshore specialization aligned with Baltic Sea development. These three entities illustrate the competitive bifurcation between asset ownership and equipment supply.
| Leading Market Players |
|---|
| Vattenfall AB |
| Fortum Oyj |
| Uniper SE |
| Statkraft AS |
| OX2 AB |
| Vestas Wind Systems A/S |
| Siemens Gamesa Renewable Energy SA |
| Arise AB |
| E.ON SE |
| Others |
Pricing and Supply Chain Analysis
Norrbotten County's turbine component manufacturing cluster anchors Sweden's wind supply capacity, translating localized blade production and nacelle assembly into procurement leverage for domestic developers negotiating long-term power purchase agreements with steel producers.
Pricing Analysis
Long-term offtake contracts dominate Swedish wind procurement, with twenty-year power purchase agreements securing price certainty for electrolyzer-linked hydrogen production facilities while spot market exposure concentrates among smaller municipal co-operatives. Price differentiation rests on certification grade under harmonized European norms and hub height specifications for subarctic forested terrain. Cost compression in utility-scale segments is intensifying as Vestas Wind Systems A/S and Siemens Gamesa Renewable Energy SA compete for turbine supply contracts. Industrial buyers in Norrland industrial zones exhibit the lowest price sensitivity, whereas rural co-operatives in central counties face acute capital constraint pressure.
Supply Chain Analysis
Steel feedstock for turbine towers draws from Swedish domestic production and German rolling mills, while rare earth magnet supply for direct-drive generators rests on Chinese processing concentration and limited alternative sourcing. Blade composite materials hinge on epoxy resin availability from South Korean and German chemical producers. Single-source vulnerability in permanent magnet supply creates exposure to export restriction risk. Distribution runs through vertically integrated energy providers with captive logistics networks, supplemented by specialized heavy-lift contractors for forested terrain access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Swedish wind power faces substitution pressure from Nordic nuclear restart initiatives and Baltic Sea offshore solar pilots, forcing incumbents to defend contracted offtake positions through operational reliability differentiation.
For Market Incumbents: Entrench repowering service capabilities to capture lifetime extension revenue from Sweden's early 2000s installed base, while securing backward integration into blade repair technician training programs to address cold-climate maintenance scarcity. Municipal veto rights under the Swedish Environmental Code threaten greenfield expansion velocity, making pre-application biodiversity consultation the priority engagement lever.
For New Entrants and Emerging Players: Build out floating offshore platform expertise aligned with Swedish Energy Agency lease allocations in deeper Baltic Sea zones, where water depth limits fixed-bottom deployment and incumbent concentration remains lowest. Forest turbine adaptation for subarctic ridge lines offers the most penetrable technology niche, with direct corporate power purchase agreement origination as the essential go-to-market angle bypassing utility intermediaries.
For Investors and Strategic Acquirers: Long-term, this sits as a contracted cash flow infrastructure play because Nordic grid interconnection expansion and heavy industry electrification create durable offtake demand. Target operational assets with completed Natura 2000 permitting in northern counties. Monitor Swedish transmission system operator grid connection queue clearance rates as the critical signal for project realization velocity inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Repowering Contract Capture | Lifetime extension services address Sweden's maturing turbine installed base from early 2000s deployments. |
| Direct Corporate PPA Origination | Steel and chemical producers in Norrland seek price certainty bypassing traditional utility intermediaries. |
| Floating Platform Technology Licensing | Baltic Sea lease allocations favor deeper water deployment zones beyond fixed-bottom viability. |
| Technician Training Program Investment | Cold-climate blade repair scarcity constrains fleet availability across northern Sweden service territories. |
| Pre-Application Biodiversity Consultation | Swedish Environmental Protection Agency Natura 2000 assessments compress timelines where front-loaded. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators; and secondary validation through Swedish Energy Agency permit databases, Svenska kraftnät transmission data, EU Green Deal implementation reports, and Nordic wind project development trackers. Bottom-up capacity addition modeling triangulated against top-down industrial electricity demand projections from steel and chemical sector associations.
Forecast inputs incorporated technology segmentation by turbine configuration and deployment category, application tier by customer scale and contract structure, and end-user ownership archetype across the projection horizon. CAGRs were derived from regression analysis of historical capacity deployment against industrial procurement timelines and permitting velocity indicators. Grid connection queue dynamics and municipal veto right invocation rates served as industry-specific forecast modifiers.
Practitioners should monitor Swedish transmission system operator backlog clearance, EU Green Deal subsidy allocation shifts, and Baltic Sea lease round timing for early signals of projection revision. Cross-checking against IEA renewable capacity deployment benchmarks and Nordic electricity spot price formation patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Wind Turbine Scrap Market
Wind Energy Systems
Italy Wind Energy Market
Wind Energy Systems
Wind Energy Rescue System Market
Wind Energy Systems
Wind Power SCADA Market
Wind Energy Systems
Wind Turbine Pitch and Yaw Drive Market
Wind Energy Systems
Europe Wind Power Equipment Market
Wind Energy Systems
Boat Wind Turbine Market
Wind Energy Systems
Small Scale Single and Multi-Rotor Wind Turbine Market
Wind Energy Systems
Onshore Wind Turbine (above 2.5MW) Market
Wind Energy Systems
Thailand Wind Energy Market
Wind Energy Systems
Wind Turbine Market
Wind Energy Systems
India Wind Industry Market
Wind Energy Systems
Wind Turbine Gearbox Market
Wind Energy Systems
United Kingdom Offshore Wind Energy Market
Wind Energy Systems
Offshore Wind Tower Market
Wind Energy Systems
Offshore Wind Power Market