
 Germany Offshore Wind Energy Market | 2026-2036
Germany Offshore Wind Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Offshore Wind Energy Market Foresight
Utility companies is collapsing merchant developers' share of new offtake agreements as Germany's auction regime mandates corporate or state-backed power purchase structures. RWE anchors the project pipeline through its concentrated North Sea development rights. Ørsted competes via specialized floating-platform expertise aimed at deeper Bavarian maritime zones. EnBW differentiates through integrated grid-balancing service offerings bundled with generation assets.
Germany offshore wind energy encompasses electricity generation from turbines sited in marine environments beyond the territorial baseline, typically utilizing monopile foundations in water depths under 40 meters and jacket structures for transitional zones to 60 meters. Fixed-bottom installations dominate current capacity due to proven installation logistics and lower levelized cost, though floating platforms represent the fastest-growing type as deeper sites enter the auction queue. Hydrogen production applications are attracting capital allocation ahead of grid-balancing services, reflecting industrial offtake agreements from steel and chemical buyers. Monopile methods sustain manufacturing scale advantages while suction-bucket alternatives gain share in sensitive seabed environments.
The Federal Network Agency (Bundesnetzagentur) administers offshore auction rounds under EEG amendments, while the Federal Maritime and Hydrographic Agency (BSH) governs site permitting and environmental standards. KBA certification requirements for specialized vessel operations add compliance layers to installation logistics. Stakeholders must monitor auction design changes and hydrogen corridor planning to align project timelines with offtake certainty.
Market Dynamics
Negative bidding auctions under EEG amendments are compressing developer margins while accelerating site allocation, forcing capital toward integrated hydrogen offtake structures that bypass traditional merchant power sales.
Growth Catalysts
- EEG Auction Regime:The negative bidding framework accelerates site allocation by requiring developers to pay for seabed rights, filtering out undercapitalized bidders and concentrating pipeline control among utility-backed consortia.
- Industrial Hydrogen Offtake:Steel and chemical buyers in Lower Saxony and North Rhine-Westphalia are signing long-term purchase agreements for offshore-derived green hydrogen, creating demand visibility that merchant power contracts cannot match.
- Monopile Manufacturing Scale:Domestic fabrication yards in Bremerhaven and Cuxhaven have achieved production volumes that reduce foundation costs for shallow-water projects below jacket structure alternatives.
Market Restraints
- Specialized Vessel Bottleneck:Installation jack-ups with KBA certification for heavy-lift turbine assembly number fewer than twelve units across European fleets, creating queue congestion during weather windows.
- Grid Connection Delays:TenneT's offshore converter platforms face construction backlogs that extend project commissioning timelines beyond original auction commitments, stranding capital in pre-revenue phases.
- Seabed Geology Variability:Glacial till and boulder fields in the Baltic Sea impose foundation cost premiums that erode project returns compared to homogeneous North Sea sand substrates.
Strategic Opportunities
- Floating Platform Deployment:Jacket and semi-submersible designs unlock water depths beyond sixty meters in the Exclusive Economic Zone, accessing wind resources with higher capacity factors than fixed-bottom sites.
- Integrated Grid Services:Battery co-location and synthetic inertia provision create secondary revenue streams that improve project economics under declining capture prices for raw generation.
- BSH Streamlined Permitting:The federal maritime regulator's consolidated environmental assessment procedures reduce approval timelines for projects in designated priority areas off Schleswig-Holstein.
Industry Challenges
- Installation Weather Windows:North Sea wave height restrictions limit heavy-lift operations to summer months, compressing construction schedules and inflating day-rate costs for chartered vessels.
- Supply Chain Reconfiguration:Transition from Asian-sourced turbine components to European manufacturing mandates requires qualification of new sub-suppliers for nacelle assembly and blade fabrication.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Offshore Wind Energy Market |
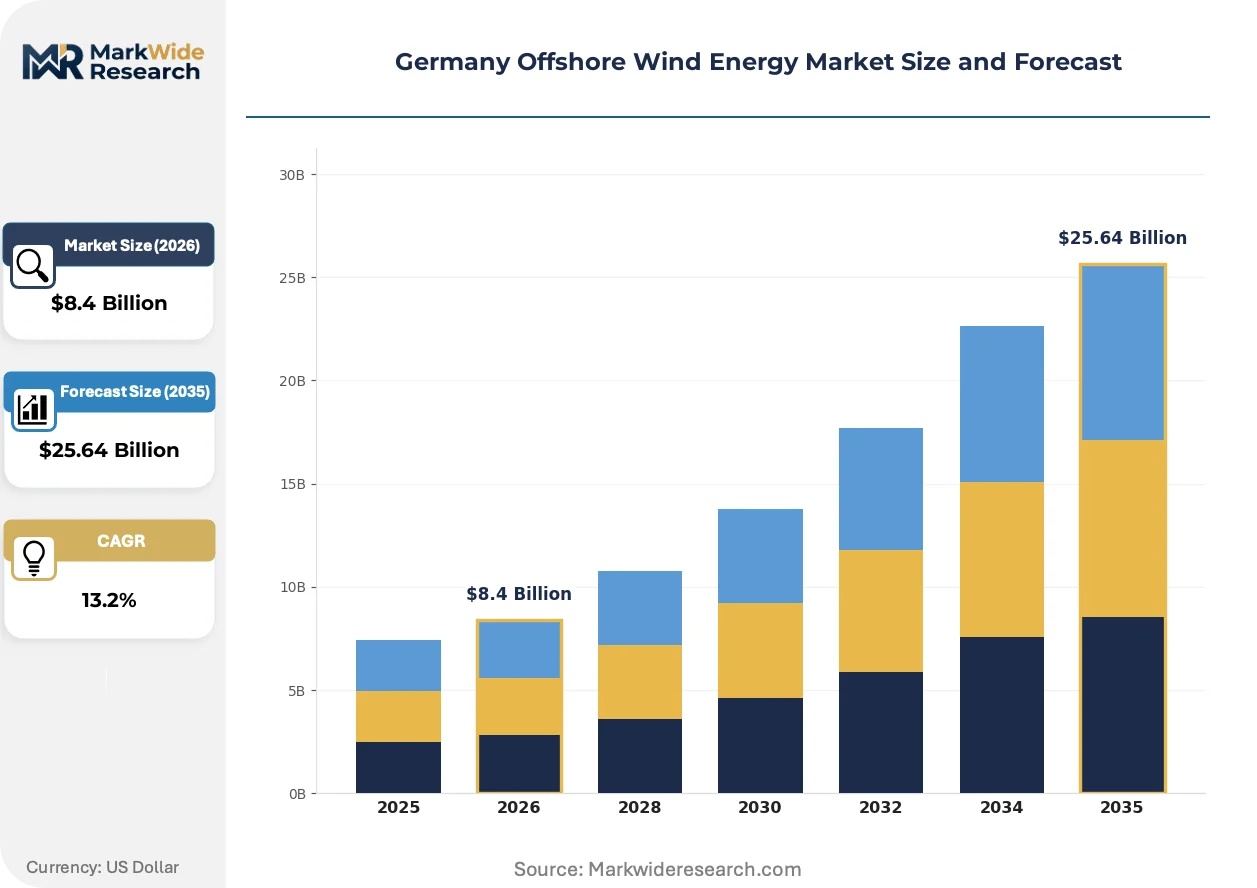
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $25.64 Billion |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Fixed-Bottom, Floating, Semi-Submersible, Tension Leg Platform Application: Electricity Generation, Grid Balancing, Hydrogen Production, Desalination Installation Method: Monopile, Jacket, Gravity-Based, Suction Bucket End User: Utility Companies, Energy Traders, Government Bodies, Independent Power Producers |
| Companies Covered | Ørsted, SSE, EnBW, Orlen, Equinor, Vattenfall, RWE, Northland Power, Iberdrola, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Offshore Wind Energy Market Shifts & Advancements
Modular construction methods and digital twin integration are compressing project development cycles while BSH regulatory updates accelerate deeper-water site releases beyond current fixed-bottom limits.
Monopile foundation design is decomposing into separate manufacturing stages—steel rolling, welding, and coating—enabling parallel processing across multiple European fabrication yards. RWE and EnBW are sourcing these components from distributed suppliers to reduce single-point failure risks. This decomposition is compressing foundation delivery timelines from eighteen months to eleven months for serial projects.
The EEG amendment framework mandates corporate or state-backed power purchase structures, eliminating merchant contracting as a viable offtake path. Project developers must secure fifteen-year purchase agreements before financial close, shifting development risk to procurement teams. Baltic Sea projects face particular pressure given lower wind resource consistency compared to North Sea clusters.
Steel producers in the Ruhr region are contracting directly with offshore wind developers for green hydrogen delivery, bypassing wholesale power markets entirely. This vertical offtake arrangement transfers price risk to industrial buyers seeking Scope 3 emissions reductions. The model is concentrating in North Sea developments with shortest pipeline distance to hydrogen corridor infrastructure.
Germany Offshore Wind Energy Market Segmentation
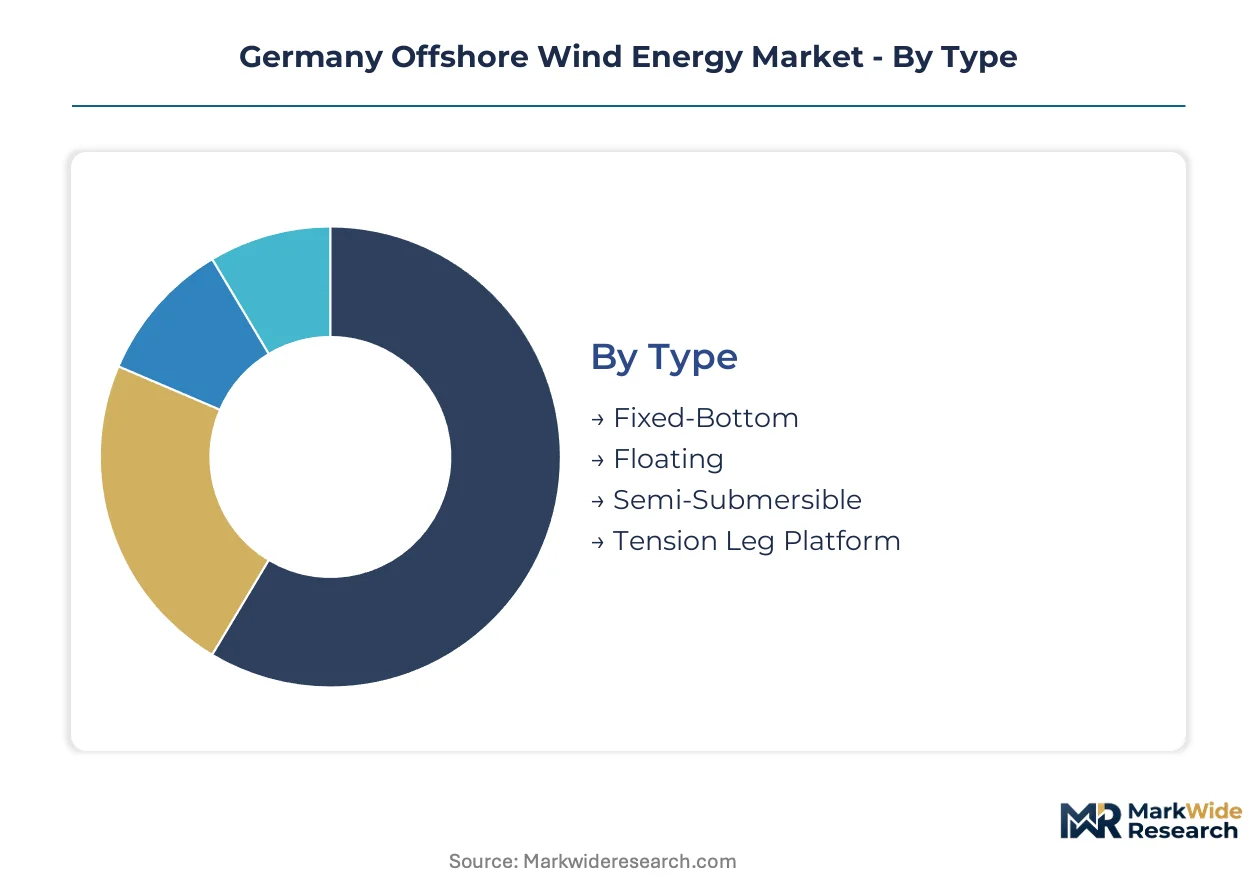
Germany's offshore wind segmentation reveals how technology choices, offtake structures, and installation methods interlock to determine project bankability. Each dimension carries distinct capital intensity profiles and regulatory compliance requirements that shape developer strategy.
Type:
Fixed-bottom platforms flow through utility-backed procurement channels with fifteen-year EEG-mandated power purchase agreements, while floating designs access specialized hydrogen offtake contracts from industrial buyers in Lower Saxony and North Rhine-Westphalia.
- Fixed-Bottom:Monopile and jacket structures dominate shallow-water developments under forty meters depth. Steel fabrication yards in Bremerhaven and Cuxhaven supply serial production for RWE and EnBW developments off Schleswig-Holstein, where homogeneous North Sea sand substrates minimize foundation cost variability.
- Floating:Semi-submersible and spar-buoy configurations unlock Bavarian maritime zones beyond sixty meters depth. Ørsted deploys specialized platforms here to capture higher capacity factors, though mooring system complexity elevates capital costs above fixed-bottom alternatives.
- Semi-Submersible:A floating sub-category with distributed buoyancy chambers providing platform stability. Steel producers in the Ruhr region contract directly for green hydrogen from these deeper-water sites.
- Tension Leg Platform:Tethered vertical mooring systems suited for extreme-depth zones. BSH permitting timelines for these experimental configurations remain untested in German waters.
Fixed-Bottom dominates installed base. Floating is where expansion concentrates.
Application:
Revenue models stratify by offtake certainty: hydrogen production commands premium pricing from steel and chemical buyers, while grid-balancing services face declining capture prices.
- Electricity Generation:Baseline power delivery to TenneT's offshore converter platforms. Grid connection backlogs at these facilities strand capital in pre-revenue phases for North Sea developments.
- Hydrogen Production:Electrolyzer co-location bypasses wholesale power markets entirely. Ruhr-region steelmakers sign long-term purchase agreements transferring price risk to industrial buyers seeking Scope 3 emissions reductions.
- Grid Balancing:Synthetic inertia and frequency response services create secondary revenue streams. Battery co-location improves project economics under EEG auction margin compression.
- Desalination:Reverse osmosis powered by surplus generation. Coastal municipalities in Lower Saxony evaluate pilot configurations for industrial water supply.
Hydrogen Production is climbing the fastest. Electricity Generation retains volume leadership.
Installation Method:
Foundation selection tracks water depth and seabed geology, with cost premiums in glacial till environments eroding returns relative to homogeneous sand substrates.
- Monopile:Single steel cylinders driven or drilled into seabed for water depths under thirty meters. Domestic manufacturing scale in Bremerhaven achieves eleven-month delivery timelines through decomposed production stages across distributed suppliers.
- Jacket:Lattice steel structures for transitional depths to sixty meters. KBA-certified jack-up vessels with heavy-lift capability number fewer than twelve across European fleets, creating installation queue congestion.
- Gravity-Based:Concrete caissons relying on mass for stability. Baltic Sea glacial till and boulder fields impose foundation cost premiums that favor this method in specific geologies.
- Suction Bucket:Skirted steel foundations using negative pressure for penetration. Sensitive seabed environments off Schleswig-Holstein drive adoption where pile-driving noise restrictions apply.
Monopile commands manufacturing scale. Suction Bucket is gaining share fastest.
End User:
Procurement authority concentrates among balance-sheet-backed entities capable of absorbing negative bidding auction costs and fifteen-year offtake commitments.
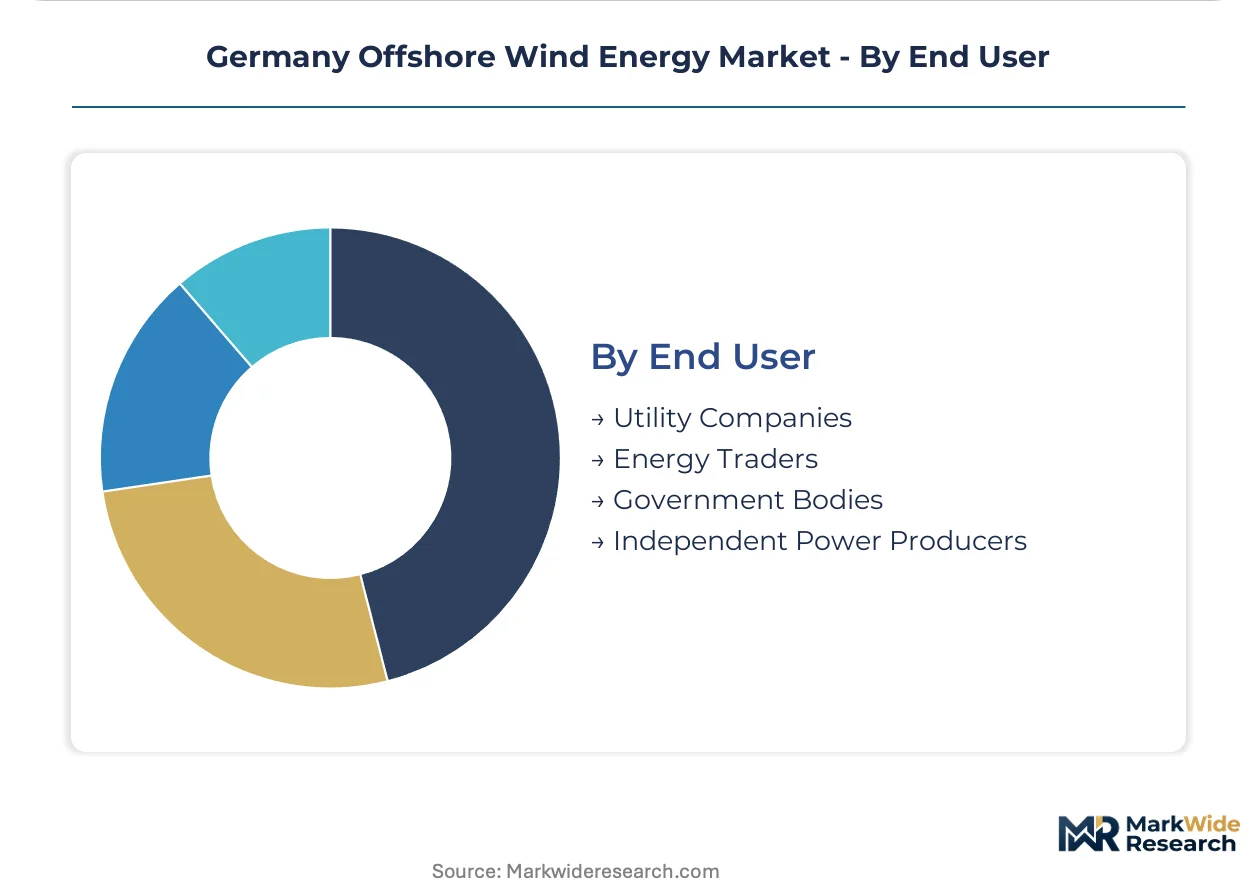
- Utility Companies:RWE and EnBW anchor project pipelines through concentrated North Sea development rights. EEG amendments mandate corporate power purchase structures that displace merchant contracting.
- Energy Traders:Diminished role under auction regime eliminating merchant developer participation. Remaining activity concentrates in secondary market hedging for utility portfolios.
- Government Bodies:Federal and state agencies direct hydrogen corridor planning. BSH streamlined permitting for priority areas accelerates approvals for publicly backed developments.
- Independent Power Producers:Marginalized by negative bidding requirements filtering undercapitalized bidders. Surviving players integrate into utility consortia or specialize in floating platform niches.
Utility Companies dominate pipeline control. Government Bodies drive hydrogen infrastructure expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic fabrication capacity clusters along the North Sea coast, with converter platform assembly yards in Emden and cable manufacturing in Nordenham anchoring supply-side investment. This geographic concentration shapes project economics and installation logistics across German maritime zones.
Schleswig-Holstein
North Sea lease areas here host the densest turbine concentrations, driven by homogeneous sand substrates that minimize foundation cost variability. BSH streamlined permitting procedures accelerate approvals for priority zone developments. RWE maintains concentrated development rights off Heligoland, with monopile fabrication contracted to Bremerhaven yards.
Lower Saxony
Industrial hydrogen demand from Ruhr-region steelmakers directs capital toward electrolyzer-ready offshore sites in this zone. The EEG auction regime mandates fifteen-year purchase agreements before financial close. Cuxhaven manufacturing facilities supply serial foundation production for utility-backed consortia.
Bavaria
Deeper maritime zones beyond sixty meters depth require floating platform configurations, accessing higher capacity factors than fixed-bottom alternatives. Ørsted deploys specialized semi-submersible designs here to capture wind resources unavailable to conventional installations. Mooring system complexity elevates capital costs above shallow-water projects.
Mecklenburg-Vorpommern
Baltic Sea developments face glacial till and boulder fields that impose foundation cost premiums compared to North Sea sand substrates. Gravity-based concrete caissons gain share in these geologies where pile-driving noise restrictions apply. Grid connection planning lags North Sea infrastructure timelines.
North Rhine-Westphalia
No direct offshore sites exist here, yet the state anchors hydrogen offtake demand through steel and chemical industrial clusters. Green hydrogen corridors from North Sea production zones terminate in Ruhr-region distribution hubs. This demand visibility transfers price risk from developers to industrial buyers seeking Scope 3 emissions reductions.
Germany Offshore Wind Energy Market Competitive Landscape
Concentration sits with utility-backed developers capable of absorbing negative bidding auction costs and fifteen-year offtake commitments. The pipeline consolidates around three to four integrated players with balance sheet capacity for seabed rights payments. Strategic archetypes include North Sea fixed-bottom specialists, floating platform technology leaders, and hydrogen-integrated developers. Competitive moves center on auction consortium formation and manufacturing partnerships with domestic fabrication yards.
Among European integrated utilities, RWE and EnBW anchor the German project pipeline through concentrated North Sea development rights and grid-balancing service bundling. Ørsted represents the floating platform specialization archetype with deeper-water expertise. These three exemplify the utility-backed consolidation displacing merchant developer participation under EEG-mandated procurement structures.
| Leading Market Players |
|---|
| Ørsted |
| SSE |
| EnBW |
| Orlen |
| Equinor |
| Vattenfall |
| RWE |
| Northland Power |
| Iberdrola |
| Others |
Supply & Pricing Matrix
Monopile manufacturing scale in Bremerhaven and Cuxhaven fabrication yards compresses foundation delivery timelines from eighteen months to eleven months, concentrating supply-side power among serial producers while establishing price floors that undercapitalized developers cannot match under EEG negative bidding requirements.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by foundation type and installation complexity. Premium tiers attach to floating platform configurations with specialized mooring systems, while standard tiers capture fixed-bottom monopile projects in shallow North Sea zones. Cost compression in economy tiers intensifies because domestic manufacturing scale advantages force merchant developers toward utility consortium structures. Steel producers in the Ruhr region exhibit lowest price sensitivity given long-term hydrogen offtake agreements that transfer commodity risk, while independent power producers face acute sensitivity under margin-compressed auction regimes.
Supply Chain Analysis
Germany and Denmark anchor turbine component fabrication and foundation steel rolling, with Poland emerging as a secondary hub for secondary steel processing and coating operations. Domestic supply draws from European-sourced rolled steel, specialized marine-grade epoxy coatings, and KBA-certified heavy-lift vessel chartering. Single-source vulnerability concentrates in installation jack-up availability, where fewer than twelve certified units serve European offshore demand. Distribution runs through Emden converter platform assembly yards and Nordenham cable manufacturing facilities before TenneT grid connection handover.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among utility-backed consortia capable of absorbing negative bidding auction costs, fragmenting merchant developer participation and shifting procurement leverage toward RWE, EnBW, and Ørsted archetypes with balance sheet depth for fifteen-year offtake commitments.
For Market Incumbents: Secure concentrated North Sea development rights through BSH priority zone applications before streamlined permitting windows narrow. Anchor manufacturing partnerships with Bremerhaven and Cuxhaven fabrication yards to lock in eleven-month foundation delivery timelines that undercut competitor cost structures. Defend against floating platform specialists by integrating electrolyzer co-location capabilities that capture Ruhr-region steelmaker hydrogen demand.
For New Entrants and Emerging Players: KBA certification fast-track for specialized vessel operations opens entry pathways in installation logistics segments where European fleet constraints create queue congestion. Target Baltic Sea gravity-based foundation niches in Mecklenburg-Vorpommern where glacial till geology favors concrete caisson methods underserved by monopile-focused incumbents. Lead with desalination application pilots for Lower Saxony coastal municipalities seeking industrial water supply alternatives.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors hydrogen-integrated developers with electrolyzer-ready site allocations and shortest pipeline distance to Ruhr-region distribution hubs. Long-term viability hinges on BSH permitting velocity and TenneT grid connection timeline execution rather than raw generation capture prices. Watch floating platform cost curves as the inflection signal for deeper-water Bavarian zone bankability.
| Strategic Initiative | Industry Significance |
|---|---|
| Electrolyzer Co-location | Bypasses wholesale power markets through direct Ruhr steelmaker hydrogen offtake contracts. |
| KBA Vessel Certification | Unlocks installation queue access where European heavy-lift fleet constraints strand competitor projects. |
| BSH Priority Zone Application | Accelerates permitting timelines for Schleswig-Holstein developments ahead of standard assessment tracks. |
| Monopile Manufacturing Partnership | Locks in eleven-month foundation delivery through distributed Bremerhaven and Cuxhaven supplier networks. |
| Floating Platform Technology Licensing | Captures Bavarian maritime zones beyond sixty-meter depth with higher capacity factor wind resources. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of BSH permitting databases, TenneT grid connection disclosures, and EEG auction outcome records. Primary interviews engaged utility planning officers at RWE and EnBW, offshore EPC contractors in Bremerhaven, and steel procurement leads at Ruhr-region industrial clusters. Secondary validation drew from Bundesnetzagentur auction documentation, KBA vessel certification registries, and Federal Maritime and Hydrographic Agency environmental assessment filings. Bottom-up project pipeline aggregation triangulates against top-down market sizing from regulatory capacity allocation announcements.
Segmentation dimensions modeled span foundation type across fixed-bottom and floating configurations, application across electricity generation and hydrogen production, installation method across monopile and gravity-based alternatives, and end user across utility companies and government bodies. CAGRs derive from project commissioning timelines mapped against auction award schedules and TenneT platform construction backlogs. Forecast inputs incorporate BSH streamlined permitting velocity for priority zones and electrolyzer co-location capital allocation trends from industrial offtake agreements.
The analysis sits within stated boundaries; outcomes outside sustained EEG amendment enforcement or TenneT grid delivery schedule adherence would require recalibration. Forecasts reflect assumptions on negative bidding auction participation thresholds and KBA-certified vessel availability across European fleets. Recalibration cycles align with material shifts in BSH regulatory updates and hydrogen corridor infrastructure commissioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Wind Turbine Scrap Market
Wind Energy Systems
Wind Turbine Operation and Maintenance Market
Wind Energy Systems
Vertical Axis Wind Turbine Market
Wind Energy Systems
Wind Turbine Forged Tower Flange Market
Wind Energy Systems
Iran Wind Energy Market
Wind Energy Systems
Quiet Wind Turbine Market
Wind Energy Systems
Wind Power Forgings Market
Wind Energy Systems
United Kingdom Wind Energy Market
Wind Energy Systems
Australia Wind Energy Market
Wind Energy Systems
Norway Wind Energy Market
Wind Energy Systems
Steel Wind Tower Market
Wind Energy Systems
Wind Energy Equipment Logistics Market
Wind Energy Systems
North America Wind Power Market
Wind Energy Systems
Offshore Wind Turbine Blade Leading-Edge Defect Inspection Equipment Market
Wind Energy Systems
Wind Speed Alarm Market
Wind Energy Systems
Boat Wind Turbine Market