
 Europe Wind Power Equipment Market | 2026-2036
Europe Wind Power Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Wind Power Equipment Market Foresight
Direct-drive generator technology is rewriting turbine architecture across Europe by eliminating gearbox maintenance burdens and enabling higher tip-speed ratios. Vestas Wind Systems A/S anchors its competitive stance through integrated blade-to-grid service contracts. Siemens Gamesa Renewable Energy specializes in offshore nacelle assemblies rated above 14 MW. Nordex SE extends its footprint in medium-wind onshore sites with modular turbine platforms.
Europe wind power equipment encompasses the engineered systems required to capture kinetic wind energy and convert it into grid-synchronous electricity, including rotor assemblies with carbon-fiber-reinforced polymer blades exceeding 100 meters in length, pitch and yaw control systems, and power electronics rated for variable frequency conversion. Turbine manufacturers supply the dominant value share of delivered project costs, while blade fabrication commands concentrated margin pools due to labor-intensive molding processes and strict lightning-protection standards. Offshore technology represents the fastest-expanding installation category as water-depth capabilities push beyond sixty meters, though onshore horizontal-axis systems still occupy the largest cumulative fleet base.
The EU Green Deal and F-Gas Regulation constrain refrigerant choices in turbine thermal management systems, while CE marking and the EU AI Act impose conformity requirements on predictive maintenance algorithms. Germany's KBA and Denmark's national energy agency enforce type-certification protocols for grid-code compliance that delay market entry for non-European suppliers. Stakeholders must monitor how the EU's Carbon Border Adjustment Mechanism reshapes sourcing economics for steel towers and rare-earth magnets.
Market Dynamics
Direct-drive generator architectures are compressing maintenance schedules across European wind fleets while the EU Green Deal's domestic content mandates force supply chain reconfiguration toward Baltic and North Sea manufacturing clusters.
Growth Catalysts
- EU Green Deal domestic content rules:Tightened local sourcing thresholds for nacelle assemblies and tower sections are pulling fabrication capacity back from Asian suppliers into Poland and Portugal.
- Floating foundation deployment:Water-depth capabilities beyond sixty meters unlock acreage off Scotland and Norway that fixed-bottom designs cannot reach.
- Carbon-fiber blade scaling:Rotor diameters exceeding 220 meters capture higher capacity factors at medium-wind sites across northern Germany and Denmark.
Market Restraints
- Rare-earth magnet concentration:Neodymium supply chains remain concentrated in Chinese processing facilities, exposing European turbine builders to export quota volatility.
- Grid-code certification delays:Germany's KBA type-approval protocols extend market entry timelines for non-European inverter suppliers by fourteen to eighteen months.
- Steel tower input costs:Carbon Border Adjustment Mechanism levies on imported rolled steel sections inflate capital intensity for projects sourcing from Turkish mills.
Strategic Opportunities
- Polish Baltic Sea corridor:Auction pipelines for 1.5 GW annual additions lack sufficient local blade molding capacity, creating greenfield manufacturing entry points.
- Predictive maintenance algorithms:EU AI Act conformity frameworks for autonomous fault detection systems favor first-movers certifying neural-network diagnostics.
- Port infrastructure retrofit:Heavy-lift quays at Esbjerg and Hull require reinforcement for 15 MW nacelle handling, opening construction and engineering contracts.
Industry Challenges
- Composite technician scarcity:Vacuum-infusion molding for lightning-protected blades requires specialized laminator certifications that training pipelines have not matched.
- Multi-vendor integration complexity:Projects mixing Vestas rotors with Siemens Gamesa power electronics face interoperability testing burdens that delay commissioning.
- F-Gas refrigerant phase-out:Thermal management system redesigns for nacelle cooling must eliminate hydrofluorocarbons before 2027 regulatory deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Wind Power Equipment Market |
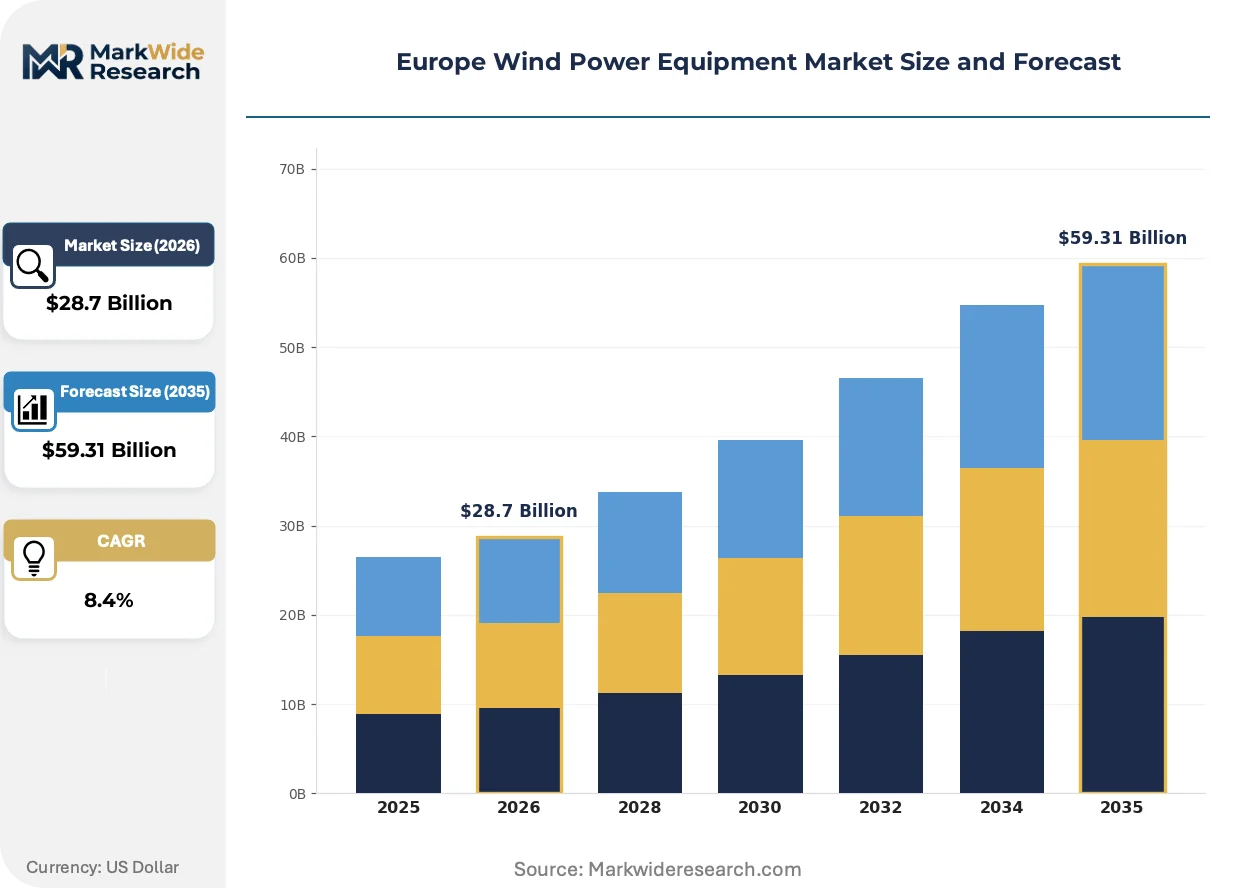
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $59.31 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Turbines, Gearboxes, Blades, Generators End User: Utilities, Project Developers, Industrial Users, Government Agencies Technology: Horizontal Axis, Vertical Axis, Offshore, Onshore Installation: New Build, Retrofit, Upgrade, Maintenance |
| Companies Covered | ENERCON GmbH, Enel Green Power, Vestas Wind Systems A/S, Orsted A/S, E.ON SE, Siemens Gamesa Renewable Energy, GE Vernova, RWE AG, Nordex SE, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Wind Power Equipment Market Shifts & Advancements
Digital twin architectures are compressing operational expenditure forecasts across European offshore fleets while regulatory pressure on embodied carbon reshapes material selection protocols.
Condition monitoring systems is digitizing turbine health management by embedding fiber-optic strain sensors into blade root structures. Offshore operators in the North Sea corridor are adopting these platforms at fleet-wide scale within twenty-four month procurement cycles. The technology is digitizing maintenance dispatch decisions, compressing unplanned downtime intervals from weeks to days.
EU F-Gas Regulation amendments constrain hydrofluorocarbon use in nacelle thermal management systems. Turbine OEMs must redesign cooling circuits using natural refrigerants or water-glycol loops before 2027 enforcement windows. Offshore platforms above 12 MW rating face the steepest redesign burden, with several Danish projects accelerating procurement to beat compliance deadlines.
Service contract unbundling is fragmenting the traditional blade-to-grid coverage model. German utility offtakers now separate predictive analytics subscriptions from corrective maintenance labor, pressuring Vestas and Siemens Gamesa to price software modules independently. The shift is most visible in repowering clusters across Schleswig-Holstein, where twenty-year-old fleets require component-level service flexibility.
Europe Wind Power Equipment Market Segmentation
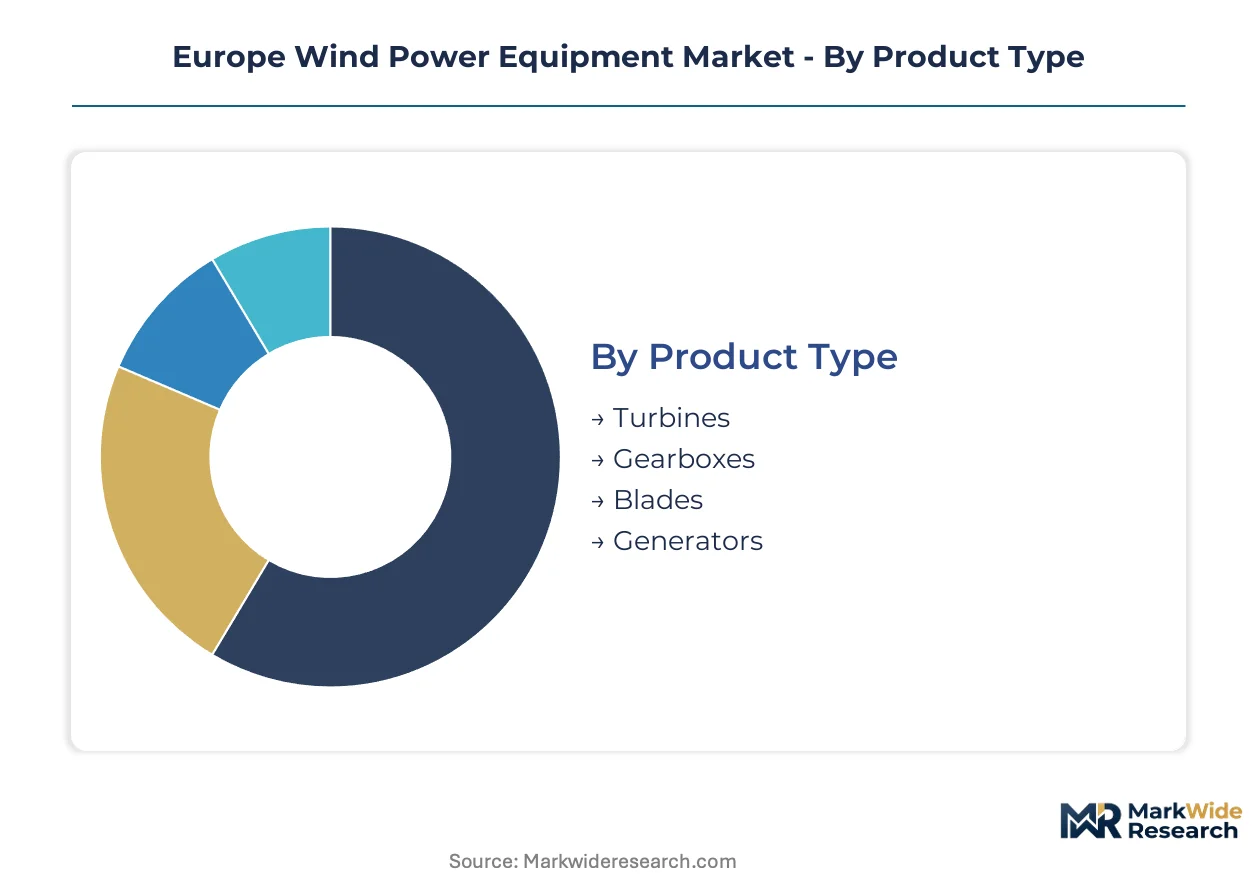
Equipment segmentation across the Europe wind power market reveals divergent margin structures and procurement patterns. Turbine OEMs capture dominant value share while blade fabricators and service providers operate in concentrated niche positions shaped by domestic content mandates and water-depth capabilities.
Product Type:
Component selection spans capital-intensive rotating machinery through precision-manufactured aerodynamic surfaces, each tier carrying distinct supply chain risks and localization requirements under EU Green Deal rules.
- Turbines:Integrated nacelle assemblies rated above 14 MW dominate offshore procurement pipelines across the North Sea corridor. German and Danish auction volumes for floating and fixed-bottom projects concentrate demand with Vestas and Siemens Gamesa, though gearbox-less direct-drive architectures are compressing maintenance schedules and reshaping competitive positioning.
- Blades:Carbon-fiber-reinforced polymer structures exceeding 100 meters in length require vacuum-infusion molding and integrated lightning-protection systems. Polish and Portuguese fabrication clusters lack sufficient laminator capacity to match Baltic Sea auction pipelines, creating greenfield entry points for specialized molders.
- Gearboxes:Precision-engineered planetary and helical stages persist in medium-wind onshore configurations where tip-speed ratios favor geared architectures. Nordex SE and other modular platform suppliers source these from dedicated drivetrain specialists.
- Generators:Permanent-magnet direct-drive units eliminate gearbox maintenance burdens but concentrate rare-earth magnet exposure in Chinese neodymium processing facilities. European OEMs face Carbon Border Adjustment Mechanism levies on imported rolled steel for stator housings.
Established volume favors Turbines; emerging adoption favors Blades as domestic content rules pull molding capacity back from Asian suppliers.
End User:
Procurement authority distributes across balance-sheet-backed utilities, development-stage project sponsors, and industrial offtakers with divergent risk appetites and contract structures.
- Utilities:RWE, Ørsted, and Iberdrola anchor offshore procurement with twenty-year power purchase agreements and integrated service contracts. These players unbundle predictive analytics from corrective maintenance in repowering clusters across Schleswig-Holstein.
- Project Developers:Specialized sponsors bid into German and UK auction rounds with merchant tail exposure, requiring equipment suppliers to assume construction risk through turbine availability guarantees.
- Industrial Users:Corporate renewable energy buyers in northern Germany and Denmark contract directly for onshore capacity behind-the-meter, favoring modular turbine platforms from Nordex SE for medium-wind sites.
- Government Agencies:State-backed entities in Norway and Scotland accelerate floating foundation deployment for water depths beyond sixty meters, unlocking acreage unreachable by fixed-bottom designs.
Contract scale concentrates with Utilities; margin expansion favors Project Developers as auction competition intensifies.
Technology:
Architectural choice between horizontal and vertical rotation axes, combined with siting environment, determines certification burden and grid-code compliance timelines.
- Horizontal Axis:Dominant configuration across European fleets with rotor diameters exceeding 220 meters capturing higher capacity factors. Germany's KBA enforces fourteen-to-eighteen-month type-approval protocols that delay market entry for non-European inverter suppliers.
- Offshore:Fastest-expanding installation category as water-depth capabilities push past sixty meters. Scottish and Norwegian floating projects require reinforced heavy-lift quays at Esbjerg and Hull for 15 MW nacelle handling.
- Onshore:Largest cumulative fleet base across northern Germany and Denmark, with repowering demand accelerating as twenty-year-old turbines reach end-of-design-life.
- Vertical Axis:Niche applications in distributed urban and industrial settings where omnidirectional wind capture offsets lower aerodynamic efficiency.
Horizontal Axis retains volume leadership; Offshore technology is climbing the fastest as auction pipelines deepen in the North Sea corridor.
Installation:
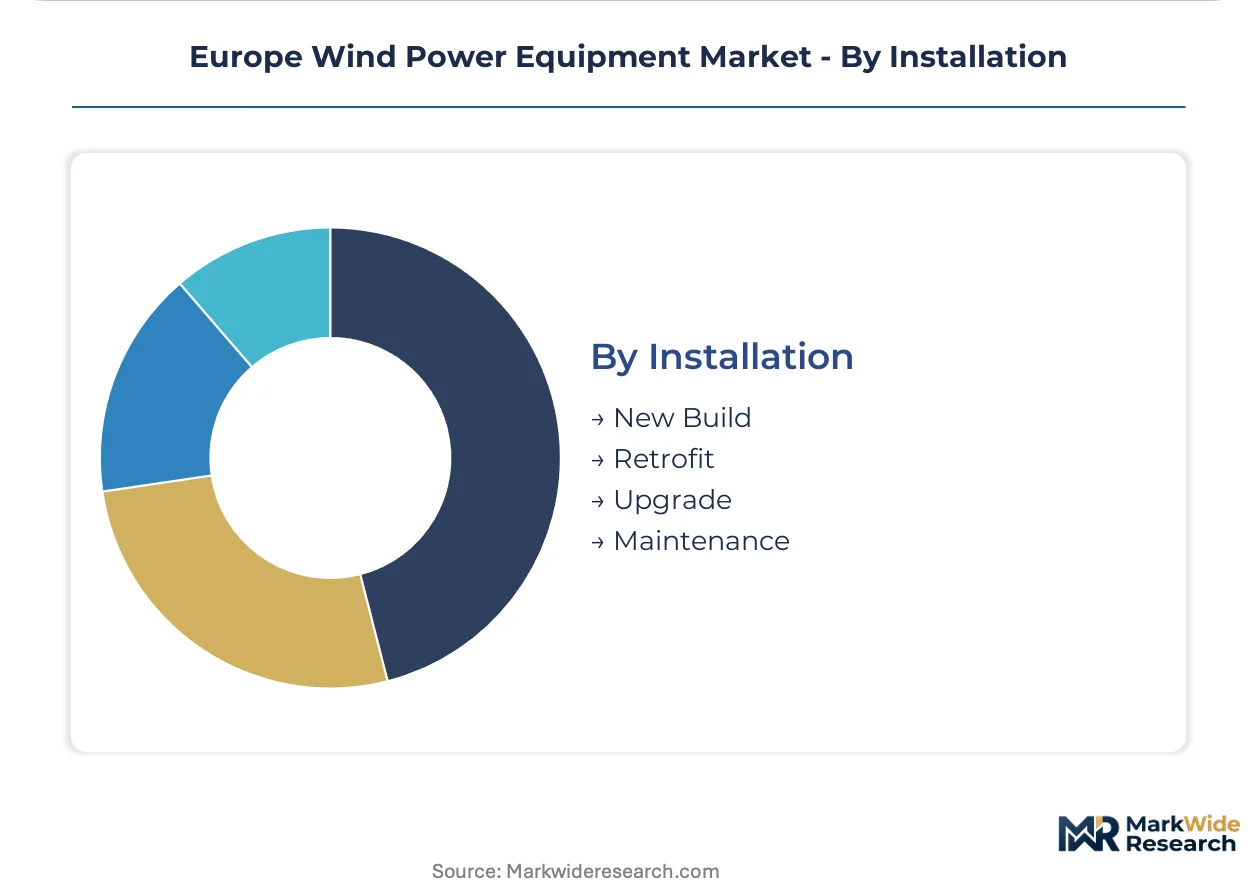
Lifecycle stage segmentation reflects divergent equipment intensity, with new build requiring full system delivery while retrofit and upgrade concentrate on component substitution.
- New Build:Full turbine delivery dominates capital deployment across Polish Baltic Sea corridor auctions and Scottish floating lease rounds. Procurement cycles compress as developers race to beat EU F-Gas Regulation deadlines for thermal management system compliance.
- Maintenance:Recurring revenue pools expand with fleet age, particularly for blade erosion repair and gearbox oil monitoring across German onshore clusters.
- Retrofit:Component-level replacement of generators and power electronics extends asset life in repowering-eligible sites where full turbine replacement faces permitting delays.
- Upgrade:Control system and sensor retrofits enable partial capacity factor improvements without rotor diameter expansion, favored where grid connection capacity is constrained.
Capital intensity peaks with New Build; margin stability favors Maintenance as European fleet age accumulates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European wind equipment trade flows reflect tightening domestic content rules under the EU Green Deal, with import dependency for rare-earth magnets and steel towers colliding with localization mandates for nacelle assemblies and blade fabrication.
Germany
Schleswig-Holstein repowering clusters and Baltic Sea auction pipelines drive turbine demand. Germany's KBA enforces fourteen-to-eighteen-month type-approval protocols for grid-code compliance that delay non-European inverter entry. Bremen and Hamburg harbor zones concentrate heavy-lift logistics capacity for 15 MW nacelle staging.
United Kingdom
Scottish floating lease rounds and Dogger Bank fixed-bottom phases anchor offshore procurement volumes. The UK's Contracts for Difference scheme mandates escalating domestic content thresholds through 2030. Port infrastructure at Hull requires reinforcement for next-generation component handling.
Denmark
National energy agency certification protocols and Esbjerg port expansion support North Sea corridor deployment. Danish auction design favors integrated service contracts spanning blade-to-grid coverage. Aarhus and Odense manufacturing zones specialize in direct-drive generator assembly.
Poland
Baltic Sea auction pipelines for 1.5 GW annual additions outpace local blade molding capacity. EU Green Deal domestic content rules pull fabrication investment toward Gdańsk and Szczecin corridor zones. Polish steel processing clusters face Carbon Border Adjustment Mechanism exposure on imported rolled sections.
Norway
Floating foundation deployment for water depths beyond sixty meters unlocks acreage unreachable by fixed-bottom designs. Norwegian state-backed entities accelerate procurement through Enova subsidy programs. Stavanger and Bergen subsea engineering clusters adapt oil-sector heavy-lift expertise to turbine installation.
Europe Wind Power Equipment Market Competitive Landscape
On the supply side, the industry is consolidating around integrated turbine OEMs with captive blade fabrication and service capabilities, while specialized component suppliers occupy tiered positions shaped by domestic content mandates and rare-earth supply exposure. Three archetypes dominate: full-stack OEMs controlling nacelle-to-blade integration, regional blade molders serving Baltic and North Sea corridors, and drivetrain specialists supplying planetary gearboxes for medium-wind onshore configurations. Competitive moves concentrate on backward integration into carbon-fiber preform manufacturing and strategic port partnerships for heavy-lift staging capacity.
Among Denmark-based integrated OEMs, Vestas Wind Systems A/S and Ørsted A/S exemplify the full-stack archetype with project development arms anchoring offshore auction participation. Siemens Gamesa Renewable Energy, headquartered in Spain, occupies a position within the premium-tier offshore nacelle segment. Germany-based Nordex SE represents the modular-platform approach for medium-wind onshore sites. These three entities illustrate how European turbine supply concentrates around integrated players with localized fabrication footprints.
| Leading Market Players |
|---|
| ENERCON GmbH |
| Enel Green Power |
| Vestas Wind Systems A/S |
| Orsted A/S |
| E.ON SE |
| Siemens Gamesa Renewable Energy |
| GE Vernova |
| RWE AG |
| Nordex SE |
| Others |
Supply & Pricing Matrix
Gdańsk and Szczecin corridor zones anchor blade molding capacity expansion as EU Green Deal domestic content rules pull fabrication investment from Asian suppliers, compressing margin pools for non-integrated molders while amplifying pricing power for European nacelle assemblers with captive blade production.
Pricing Analysis
Next-generation 15 MW offshore nacelles command substantial premiums over 12 MW fixed-bottom units and prior-generation 8 MW platforms. Three-tier pricing structure across premium offshore, standard onshore, and economy repowering configurations reflects certification grade and after-sales bundling intensity. Cost compression in economy-tier onshore turbines is intensifying because Turkish steel tower imports face Carbon Border Adjustment Mechanism levies. Project developers with merchant tail exposure exhibit highest price sensitivity; utilities with integrated service contracts show lowest.
Supply Chain Analysis
Neodymium feedstock draws from Chinese processing facilities, while carbon-fiber preforms feed from Japanese and German precursor plants, and rolled steel sections feed from Turkish and Polish mills. Rare-earth magnet concentration, carbon-fiber lightning-protection preform supply, and heavy-lift bearing castings constitute critical input dependencies. Single-source vulnerability in Chinese neodymium export quotas exposes European turbine builders to quota volatility. Distribution runs through port-centric heavy-lift staging at Esbjerg, Hull, and Bremen harbor zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
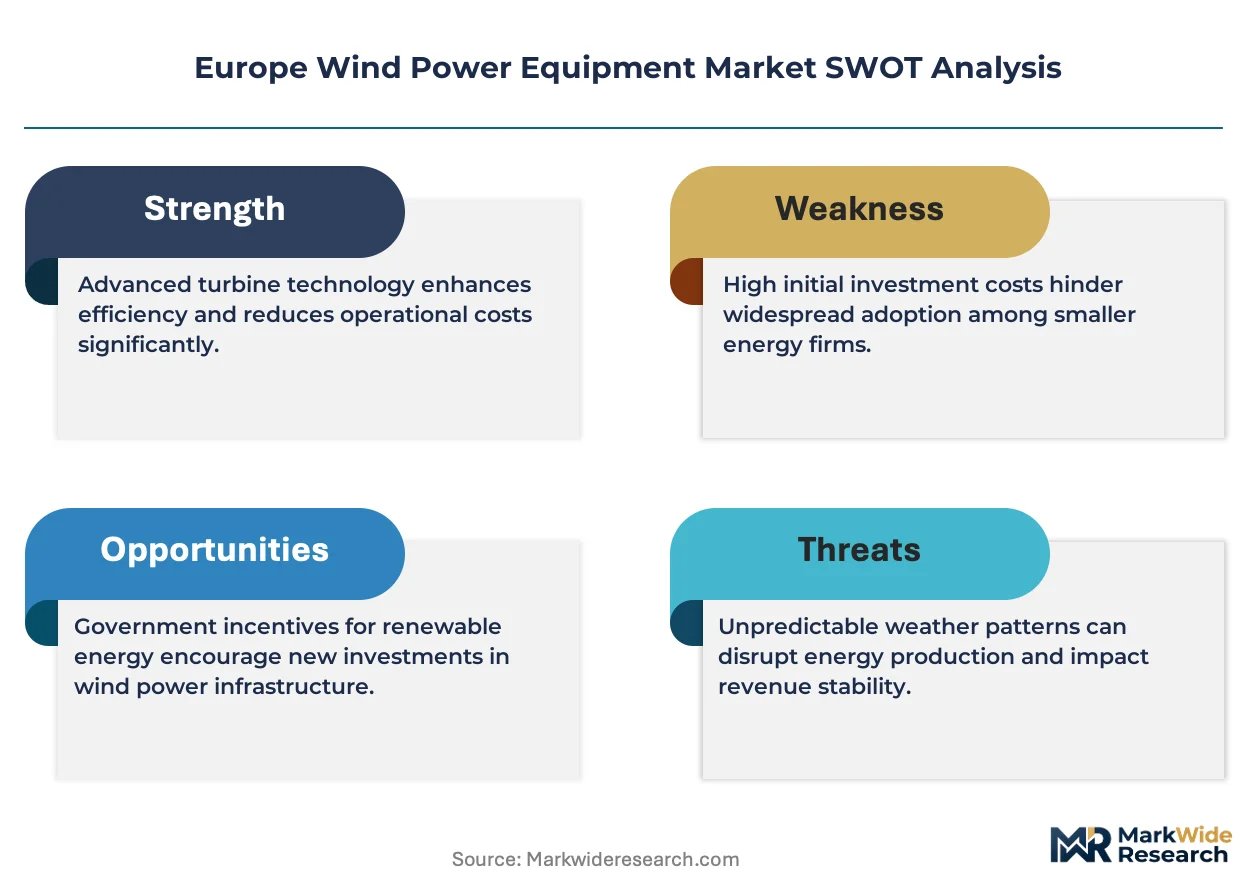
This market functions as a defensive-moat arena where regulatory entrenchment through Germany's KBA and Denmark's national energy agency certification protocols creates fourteen-to-eighteen-month entry barriers for non-European suppliers.
For Market Incumbents: Insulate market position through backward integration into carbon-fiber preform manufacturing and strategic port partnerships at Hull and Esbjerg for 15 MW nacelle handling capacity. Emerging Polish blade molders threaten margin pools in the Baltic Sea corridor; certification investment in EU AI Act conformity for predictive maintenance algorithms reinforces switching costs against modular service unbundling. For New Entrants and Emerging Players: Pursue greenfield blade molding entry in the Polish Baltic Sea corridor where 1.5 GW annual auction pipelines outpace local laminator capacity. Floating foundation deployment for Scottish and Norwegian water depths beyond sixty meters represents the most penetrable technology frontier. Direct-drive generator component supply to Aarhus and Odense assembly clusters offers a capital-light go-to-market angle. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among service providers with predictive analytics subscriptions unbundled from corrective maintenance labor. Long-term viability across the projection horizon favors specialized blade molders with vacuum-infusion certification and lightning-protection integration capabilities. Watch for EU F-Gas Regulation compliance acceleration as inflection indicator for thermal management system redesign demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon-Fiber Preforms | Captive supply of lightning-protection blade materials reduces exposure to Japanese precursor price volatility. |
| Port Infrastructure Reinforcement | Heavy-lift quay upgrades at Esbjerg enable 15 MW nacelle staging for Scottish floating lease rounds. |
| EU AI Act Conformity Certification | Neural-network predictive maintenance algorithms gain first-mover advantage in German utility unbundling. |
| Polish Blade Molding Greenfield Entry | Domestic content rules pull fabrication capacity toward Gdańsk corridor auction demand. |
| F-Gas Regulation Thermal Redesign | Nacelle cooling circuit replacement using natural refrigerants beats 2027 enforcement windows. |
Research Methodology
Initial hypotheses were tested against primary input from turbine OEM procurement directors, offshore project developers, blade fabrication plant managers, and utility offtake planning officers and refined through secondary validation against EIA project databases, IEA renewable energy reports, FERC interconnection filings, and EU auction pipeline registries. Bottom-up capacity build schedules triangulated against top-down policy target trajectories.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling equipment segmentation by turbine rating tier, blade length category, foundation type, and regional regulatory cluster. CAGRs derived from installed capacity forecasts cross-referenced with capital intensity benchmarks per megawatt. Grid-code certification timelines and domestic content threshold escalations served as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in steel commodity indices, rare-earth export quota volumes, or offshore wind auction clearing prices would shift the trajectory. Forecasts reflect documented assumptions on policy continuity and technology cost curves. Cross-checking against IEA World Energy Outlook benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Italy Wind Energy Market
Wind Energy Systems
Wind Turbine Market
Wind Energy Systems
Offshore Wind Anchoring Market
Wind Energy Systems
Global Small Wind Power Market
Wind Energy Systems
Taiwan Wind Energy Market
Wind Energy Systems
Asia-Pacific Wind Turbine Rotor Blade Market
Wind Energy Systems
Egypt Wind Energy Market
Wind Energy Systems
Wind Power Composite Market
Wind Energy Systems
Global Wind Automation Market
Wind Energy Systems
Europe Small Wind Turbine Market
Wind Energy Systems
Belgium Wind Energy Market
Wind Energy Systems
Global Small Wind Market
Wind Energy Systems
Wind Energy Rescue System Market
Wind Energy Systems
Brazil Wind Energy Market
Wind Energy Systems
Wind Energy Market
Wind Energy Systems
Offshore Wind Cable Market